
 Drone Analytics Software Market | 2026-2036
Drone Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Analytics Software Market Intelligence
Platform licensing revenue is reconfiguring margin pools away from perpetual sales toward recurring subscription streams. DroneDeploy leverages cloud-native architecture to capture recurring revenue from construction and agriculture clients. Pix4D anchors its position through photogrammetry specialization that commands premium pricing in surveying workflows. DJI extends its hardware dominance into software layers through integrated flight planning and data capture tools.
Drone analytics software processes aerial imagery, sensor data, and telemetry into actionable intelligence using photogrammetric reconstruction, multispectral indexing, and geospatial coordinate systems. These platforms transform raw drone outputs into orthomosaics, digital surface models, and vegetation indices for operational decision-making. Mapping software and inspection tools lead current revenue as mature use cases in construction progress tracking and infrastructure defect detection, while monitoring solutions tied to environmental compliance represent the fastest-expanding segment. Machine learning and computer vision capabilities are where margin pools concentrate, as automated feature extraction reduces manual analyst hours and differentiates vendor offerings.
FAA Part 107 mandates in the United States govern commercial flight operations and directly shape software demand for automated compliance logging and airspace authorization. EASA drone regulation frameworks in Europe enforce operational category classifications that determine which analytics features require enhanced data security and audit trails. ISO 21384-3 unmanned aircraft systems standards provide international baseline protocols for data quality and flight safety that vendors must embed to access cross-border contracts. Stakeholders must monitor how evolving beyond-visual-line-of-sight regulations will expand addressable use cases or fragment compliance requirements across jurisdictions.
Market Dynamics
Machine learning pipelines for automated defect detection are compressing analyst labor hours and redistributing margin pools toward vendors with proprietary training datasets. This capability gap separates cloud-native platforms from legacy desktop tools.
Growth Catalysts
- Beyond-visual-line-of-sight waivers:FAA Part 107 exemptions for automated pipeline inspection in Texas and North Dakota are expanding flight radius limits and driving demand for autonomous mission planning modules.
- Photogrammetry accuracy thresholds:Surveying firms in Germany now require sub-centimeter ground sampling distance for construction progress documentation, forcing software upgrades across Central European markets.
- Multispectral sensor fusion:Agronomists in Brazil are layering thermal and NDVI outputs for irrigation stress mapping, creating pull-through for analytics suites with integrated vegetation indexing.
Market Restraints
- Cloud compute cost volatility:GPU-intensive photogrammetric reconstruction exposes vendors to Amazon Web Services and Microsoft Azure pricing swings that erode SaaS gross margins.
- Sensor hardware concentration:DJI's dominance in RGB and multispectral camera modules creates dependency risk for software vendors optimizing around proprietary image formats.
- Data sovereignty fragmentation:EASA operational category classifications impose divergent audit trail requirements that complicate single-codebase deployment across EU member states.
Strategic Opportunities
- Environmental compliance monitoring:EPA wetland delineation mandates and EU Green Deal biodiversity tracking are opening new procurement channels for ecological restoration consultancies.
- Edge computing convergence:Onboard NVIDIA Jetson inference engines paired with 5G telemetry links enable real-time analytics without ground station dependency, unlocking emergency response applications.
- India infrastructure digitization:National highway authority drone surveying mandates for linear asset inventory are creating localized demand for Hindi-interface platforms with BIS-compliant data handling.
Industry Challenges
- Photogrammetrist talent scarcity:Certified operators capable of ground control point placement and coordinate system transformation command wage premiums that inflate project delivery costs.
- ISO 21384-3 certification timelines:Flight safety documentation and data quality audit processes stretch 8-14 months, delaying vendor access to cross-border industrial contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Analytics Software Market |
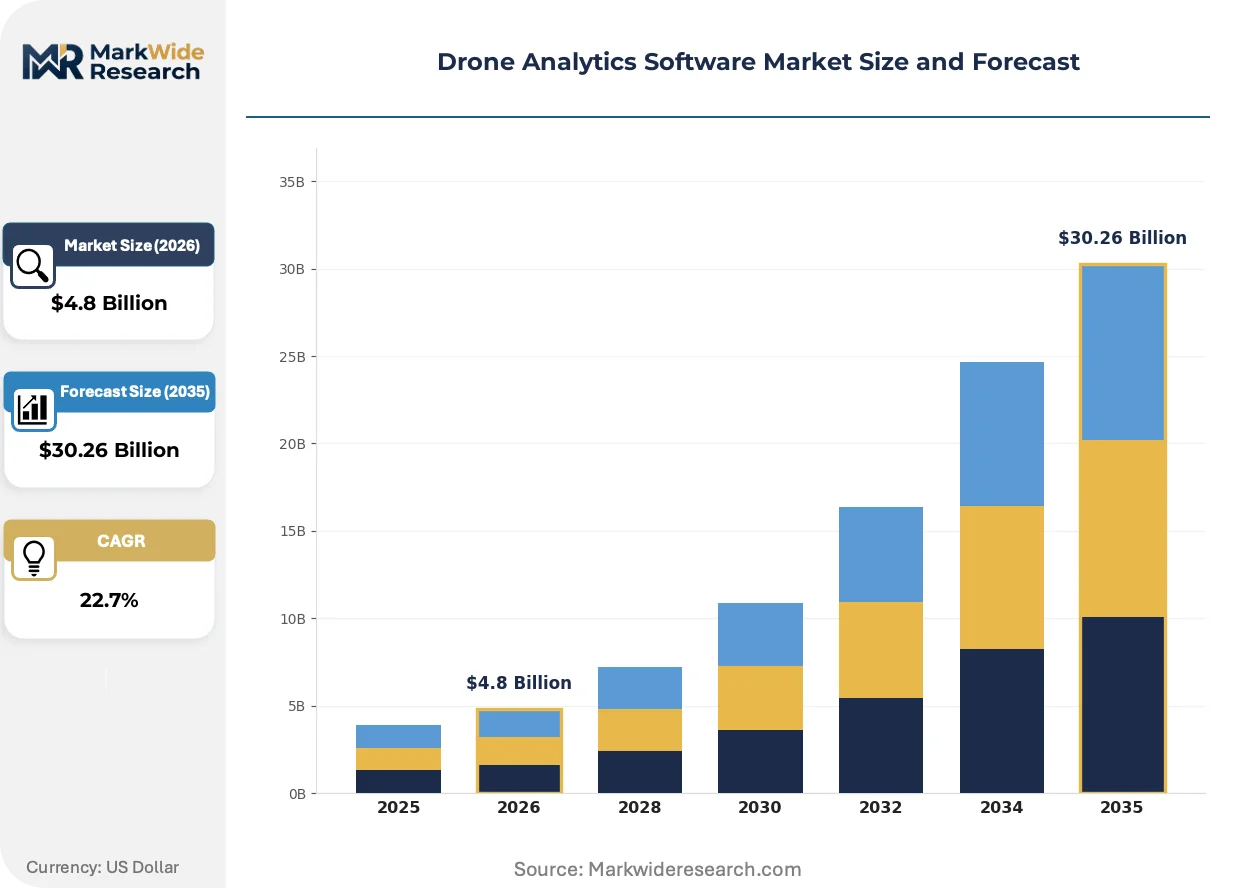
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mapping Software, Inspection Tools, Monitoring Solutions, Data Processing Platforms End User: Agriculture, Construction, Mining, Environmental Services Technology: Machine Learning, Computer Vision, Data Visualization, Analytics Engines Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | DJI, DroneDeploy, PrecisionHawk, Esri, Pix4D, AeroVironment, Skydio, AgEagle Aerial Systems, Kespry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Analytics Software Market Strategic Shifts & Innovations
Real-time analytics pipelines are displacing batch-processing workflows across inspection and emergency response verticals. This shift compresses decision cycles from days to hours and reconfigures vendor competitive moats around latency rather than accuracy alone.
Neural radiance fields (NeRF) for 3D scene reconstruction from sparse drone imagery are digitizing asset documentation workflows previously requiring LiDAR point clouds. Mining operators in Western Australia are piloting NeRF-based volumetric stockpile measurement, cutting survey equipment mobilization costs. The technology is digitizing how geotechnical teams capture pit wall stability data without ground access.
EASA's forthcoming drone regulation framework for certified category operations mandates encrypted data transmission and immutable flight logs. Wind turbine OEMs in Denmark and Spain are pre-emptively procuring analytics platforms with embedded audit trails to secure type-certification alignment. Offshore inspection service providers face the steepest compliance retrofit burden given satellite bandwidth constraints for real-time encryption.
Subscription fatigue among mid-market construction firms is fragmenting procurement toward modular, usage-billed feature tiers. Equipment rental channels in France and the United Kingdom now bundle drone analytics access with weekly aerial platform leases, bypassing traditional software vendor sales cycles. This unbundling is most pronounced among residential developers with project-based rather than fleet-based drone deployment.
Drone Analytics Software Market Segmentation
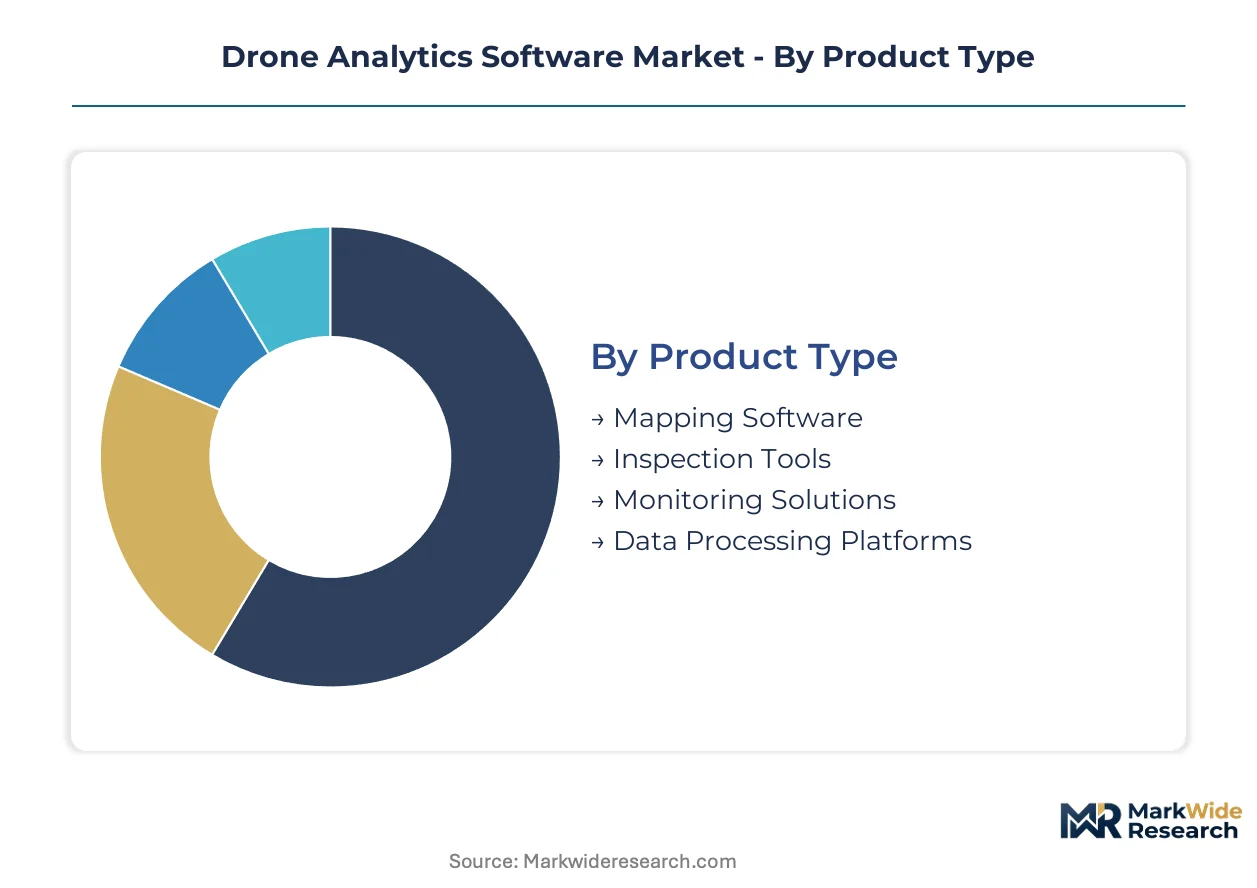
Drone analytics software segments reflect divergent after-sales service intensity, with photogrammetry-heavy mapping tools requiring ongoing calibration support while cloud-native monitoring solutions shift service burdens to automated update cycles. Vendors structure pricing and retention strategies around these support cost differentials.
Product Type:
After-sales service intensity varies sharply across product categories, with photogrammetry tools demanding sustained technical support while cloud platforms automate maintenance through continuous deployment pipelines.
- Mapping Software:Photogrammetric reconstruction engines process aerial imagery into orthomosaics and digital surface models with sub-centimeter accuracy specifications. German surveying firms drive procurement for construction progress documentation requiring ground control point validation and coordinate system transformation support.
- Inspection Tools:Automated defect detection pipelines compress analyst labor hours through machine learning models trained on proprietary damage classification datasets. Wind turbine OEMs in Denmark and Spain embed these tools within predictive maintenance workflows to satisfy EASA certified-category audit trail mandates.
- Monitoring Solutions:Real-time vegetation indexing and thermal stress mapping for Brazilian soybean operations.
- Data Processing Platforms:GPU-intensive batch reconstruction engines vulnerable to AWS and Azure pricing volatility.
Mapping Software holds the largest share; momentum sits with Monitoring Solutions.
End User:
Customer archetypes stratify by project scale and data maturity, with enterprise mining operators demanding bespoke integration while mid-market construction firms gravitate toward modular subscription tiers.
- Agriculture:Precision farming operations leverage multispectral sensor fusion for irrigation stress mapping and yield prediction. Brazilian agronomists layer thermal and NDVI outputs to optimize soy and corn management, pulling through integrated analytics suites with Portuguese-language interfaces.
- Construction:Progress tracking and earthwork volume calculations dominate current deployment, with equipment rental channels in France and the United Kingdom now bundling software access with aerial platform leases.
- Mining:Volumetric stockpile measurement and pit wall stability monitoring using NeRF reconstruction from sparse drone imagery.
- Environmental Services:EPA wetland delineation and EU Green Deal biodiversity compliance tracking.
Agriculture captures the largest installed base; Environmental Services is climbing the fastest.
Technology:
Capability differentiation concentrates where proprietary training datasets and inference optimization create defendable moats around automated feature extraction.
- Machine Learning:Automated defect classification and anomaly detection pipelines trained on vendor-curated damage libraries. These capabilities separate cloud-native platforms from legacy desktop tools and command pricing premiums in industrial inspection contracts.
- Computer Vision:Real-time object detection and tracking for emergency response and search-and-rescue missions.
- Data Visualization:Browser-based orthomosaic viewers and 3D mesh renderers for stakeholder presentation.
- Analytics Engines:Backend processing infrastructure for vegetation index calculation and change detection algorithms.
Machine Learning dominates current R&D investment; Computer Vision is gaining share fastest.
Deployment:
Infrastructure choices trade latency against control, with regulated industries accepting cloud dependency for scalability while sensitive operations retain on-premise sovereignty.
- Cloud-Based:SaaS delivery enables recurring subscription revenue and automatic feature updates without client IT overhead. DroneDeploy and comparable vendors target construction and agriculture clients with this architecture, though GPU-intensive reconstruction exposes margins to hyperscaler pricing swings.
- On-Premise:Air-gapped installations for defense, critical infrastructure, and data-sovereign jurisdictions with strict localization requirements.
- Hybrid:Split workflows with edge preprocessing and cloud-based model training and storage optimization.
- Edge Computing:NVIDIA Jetson onboard inference paired with 5G telemetry for real-time analytics without ground station dependency, unlocking emergency response and offshore inspection where satellite bandwidth constrains cloud connectivity.
Cloud-Based holds the largest share; Edge Computing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Brazilian agronomists prioritize Portuguese-language interfaces and localized crop models over premium pricing, while German wind turbine OEMs accept steep software premiums for EASA-certified audit trails and sub-centimeter accuracy guarantees.
United States
Beyond-visual-line-of-sight pipeline inspection waivers in Texas and North Dakota are expanding automated flight radius limits for energy infrastructure operators. FAA Part 107 mandates tighten operational standards and directly shape procurement for compliance logging modules. Houston and Bismarck clusters concentrate demand for autonomous mission planning tools among oilfield service providers.
Germany
Industrial inspection protocols for wind turbine maintenance are driving software procurement with mandatory encrypted data transmission requirements. EASA drone regulation frameworks enforce operational category classifications that determine audit trail specifications. Hamburg and Bremen harbor zones anchor maritime inspection demand where offshore service providers face satellite bandwidth constraints for real-time encryption.
Brazil
Precision agriculture operations in Mato Grosso and Goiás are expanding canopy health analytics for soy and corn management with thermal and NDVI sensor fusion. ANVISA-equivalent agricultural data protocols shape multispectral imagery handling standards. Ribeirão Preto and Sorriso farming cooperatives pull through integrated analytics suites with Portuguese-language vegetation indexing.
India
National highway authority drone surveying mandates for linear asset inventory are creating localized demand for Hindi-interface platforms. BIS-compliant data handling requirements govern procurement specifications for infrastructure digitization contractors. Mumbai-Pune Expressway and Delhi-Mumbai Industrial Corridor projects concentrate deployment of construction progress documentation tools.
Denmark
Wind turbine OEMs are pre-emptively procuring analytics platforms with embedded audit trails to secure EASA type-certification alignment for certified category operations. Offshore inspection service providers in the North Sea face the steepest compliance retrofit burden. Esbjerg port clusters anchor demand for real-time defect detection pipelines among marine logistics contractors.
Drone Analytics Software Market Key Industry Players
Capability concentration sits with photogrammetry specialists commanding premium pricing in surveying workflows; scale advantage sits with cloud-native platforms capturing recurring subscription revenue from construction and agriculture clients. The vendor base stratifies across three tiers: hardware-integrated incumbents extending flight planning tools, pure-play SaaS vendors leveraging GPU-intensive reconstruction, and specialized photogrammetry houses with proprietary accuracy benchmarks. Dominant competitive moves include strategic partnerships with sensor manufacturers and geographic expansion through localized language interfaces.
Within the cloud-native tier, DroneDeploy and Pix4D exemplify divergent positioning strategies. DroneDeploy occupies a position emphasizing recurring revenue capture from construction and agriculture verticals through browser-based delivery. Pix4D anchors the photogrammetry-specialist archetype with premium pricing power in surveying workflows requiring ground control point validation. DJI represents the hardware-integrated incumbent model, extending camera module dominance into adjacent software layers.
| Leading Market Players |
|---|
| DJI |
| DroneDeploy |
| PrecisionHawk |
| Esri |
| Pix4D |
| AeroVironment |
| Skydio |
| AgEagle Aerial Systems |
| Kespry |
| Others |
Cost & Logistics Intelligence
Single-source dependency on DJI's camera module ecosystem compresses margin pools for software vendors optimizing around proprietary image formats, forcing three-tier pricing stratification across premium certified, standard professional, and economy entry-level tiers while tethering supply chain resilience to Shenzhen manufacturing clusters.
Pricing Analysis
After-sales service revenue from calibration support and ground control point validation drives lifetime value for photogrammetry specialists. Subscription tiers separate enterprise clients with bespoke integration requirements from mid-market construction firms gravitating toward modular usage-billed access. Price differentiation centers on certification grade for EASA audit trail compliance and geographic delivery cost for Portuguese-language interfaces in Brazilian agriculture. Cost compression in cloud-native tiers is intensifying because GPU-intensive reconstruction exposes margins to Amazon Web Services and Microsoft Azure pricing swings. Mid-market construction firms show greatest price sensitivity, while German wind turbine OEMs accept steep premiums for sub-centimeter accuracy guarantees.
Supply Chain Analysis
Tariff exposure between the United States and China dominates vendor risk assessments for hardware-integrated software bundles. Component sourcing draws from Shenzhen for RGB and multispectral camera modules, Taiwan for NVIDIA Jetson inference engines, and Germany for precision surveying optics. Supply chain vulnerability rests on DJI's concentration in proprietary image formats that lock software optimization pathways. Distribution runs through equipment rental channels in France and the United Kingdom that bundle analytics access with aerial platform leases, bypassing traditional vendor sales cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
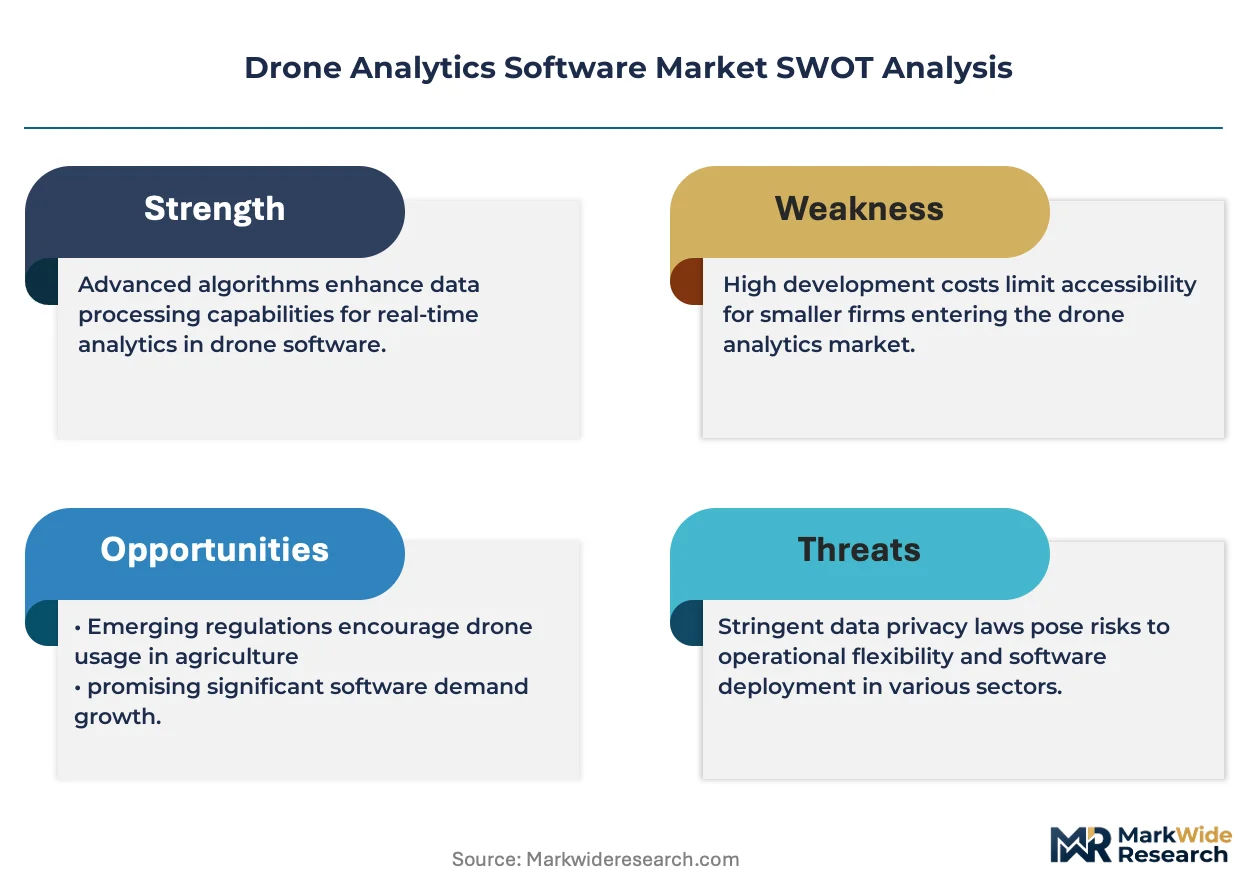
Proprietary training dataset scarcity separates cloud-native platforms from legacy desktop tools, concentrating margin capture among vendors with curated damage classification libraries for automated defect detection pipelines.
For Market Incumbents: Harden defensive moats by deepening proprietary photogrammetry accuracy benchmarks that command premium pricing in German surveying workflows. Invest in EASA-certified audit trail capabilities before certified-category mandates take effect, as wind turbine OEMs in Denmark and Spain are pre-emptively procuring compliant platforms. Control channel access through strategic partnerships with sensor manufacturers to limit substitute technology encroachment. For New Entrants and Emerging Players: Build out localized Hindi-interface platforms for India's national highway authority drone surveying mandates, where BIS-compliant data handling requirements create procurement friction for foreign incumbents. Target environmental compliance monitoring as the most penetrable segment, with EPA wetland delineation and EU Green Deal biodiversity tracking opening new procurement channels for ecological restoration consultancies. Pursue equipment rental channel partnerships as the primary go-to-market angle to bypass fragmented mid-market construction firm procurement cycles. For Investors and Strategic Acquirers: EASA's forthcoming certified-category framework reshapes the acquisition landscape toward platforms with embedded encrypted data transmission and immutable flight logs. Long-term viability over the projection horizon favors vendors with cloud-native architectures capturing recurring subscription revenue rather than perpetual license models. Monitor beyond-visual-line-of-sight waiver expansion in Texas and North Dakota as the signal indicating autonomous mission planning module demand inflection. Acquisition targets should display proprietary training dataset depth for automated feature extraction capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cloud-native vendors embed EASA-certified audit trails to secure wind turbine OEM procurement in Denmark. |
| Geographic Expansion | Portuguese-language interfaces unlock Brazilian soybean cooperative demand for thermal-NDVI sensor fusion. |
| Strategic Partnership | Equipment rental channels in France bundle analytics access with weekly aerial platform leases. |
| Acquisition of Specialist Firm | Photogrammetry houses with sub-centimeter accuracy benchmarks command premium positioning in German surveying. |
| Product Launch | Edge computing platforms with NVIDIA Jetson inference enable real-time analytics for offshore inspection. |
Research Approach
Operator-level perspectives from flight operations managers, photogrammetrists, precision agriculture agronomists, wind turbine maintenance engineers, and environmental compliance officers anchored the qualitative base. Primary interviews combined with secondary validation against FAA Part 107 regulatory filings, EASA operational category guidance documents, ISO 21384-3 unmanned aircraft systems standards, hyperscaler capex disclosures for GPU infrastructure, and customs records for multispectral sensor trade flows. Bottom-up segmentation triangulation across deployment models, vertical applications, and regional adoption patterns reinforced top-down market sizing.
Scenario-bracketing framed volume and value outputs across the projection horizon, with analytical models stress-testing sensitivity to beyond-visual-line-of-sight regulatory expansion timelines and cloud compute cost volatility. Segmentation dimensions included product type, end-user vertical, technology capability tier, and deployment architecture. CAGRs derived from fitted growth curves applied to installed base expansion and average revenue per account trajectories. Industry-specific inputs incorporated photogrammetry accuracy threshold evolution and EASA certification timeline assumptions.
Practitioners should monitor beyond-visual-line-of-sight waiver velocity, hyperscaler GPU pricing cycles, and EASA certified-category implementation timing for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Iraq ICT Market
Analytics
Global Analytics Market
Analytics
Global Graph Analytics Market
Analytics
Load (ETL) Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Data Analytics Market
Analytics
Scientific Text Analytics and Annotators Market
Analytics
Process Analytics Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Data Analytics in Telecom Market
Analytics
Global Marketing Attribution Software Market
Analytics
Greece ICT Market
Analytics
Global in-Memory Analytics Market
Analytics
Content Analytics Market
Analytics
Global Data Analysis Software Market
Analytics
Service Analytics Market