
 North America Speech Analytics Market | 2026-2036
North America Speech Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Speech Analytics Market Outlook
Subscription-based cloud deployment is narrowing the capital barrier for mid-market buyers in the North America speech analytics space. NICE Ltd. leverages its installed base in financial services compliance to sustain recurring revenue density. Verint Systems Inc. anchors its position through hybrid deployment architectures that bridge legacy on-premises investments with cloud scalability. CallMiner, Inc. specializes in real-time agent guidance, competing on outcome-based pricing rather than seat-based licenses.
Speech analytics encompasses the computational extraction of meaning, sentiment, and behavioral patterns from audio recordings and live voice streams, typically processing phonetic sequences at sampling rates of 8-16 kHz with latency thresholds under 500 milliseconds for real-time applications. Its primary commercial purpose centers on transforming unstructured conversational data into structured intelligence for regulatory compliance, operational quality, and revenue protection. Cloud-based deployment now captures the fastest expansion as enterprises shed data-center overhead, while on-premises installations retain dominance in BFSI segments where HIPAA and PCI-DSS audit trails demand physical infrastructure control. Natural language processing technology leads current investment flows, though machine learning subsystems are displacing rules-based classification engines in quality assurance workflows.
The FCC enforces Telephone Consumer Protection Act provisions that mandate recorded consent documentation, directly stimulating demand for automated compliance monitoring applications in telecom and retail outbound operations. HIPAA privacy rules administered by the Office for Civil Rights shape how healthcare providers architect voice data retention and de-identification pipelines, creating specification premiums for vendors with healthcare-specific certifications. State-level biometric privacy laws in Illinois and Texas impose additional consent layers on voice recognition deployments, fragmenting implementation standards across the region. Stakeholders must weigh jurisdictional compliance complexity against the operational efficiency gains of centralized cloud analytics platforms.
Market Dynamics
Natural language processing architectures are compressing latency thresholds below 300 milliseconds, forcing incumbent vendors to rebuild inference pipelines or cede real-time contracts to cloud-native competitors. This technical inflection redistributes competitive advantage toward providers with elastic GPU clusters and healthcare-specific compliance certifications.
Growth Catalysts
- Telephone Consumer Protection Act enforcement:FCC consent documentation mandates drive automated compliance monitoring adoption across retail and telecom outbound operations, with vendors bundling recording verification into core platform offerings.
- Healthcare voice data pipelines:HIPAA privacy rules administered by the Office for Civil Rights compel providers to architect de-identification workflows, creating specification premiums for certified analytics vendors.
- Real-time agent guidance:BFSI contact centers in New York and Chicago deploy sub-second coaching alerts to reduce regulatory exposure and compress average handle times.
Market Restraints
- Biometric consent fragmentation:Illinois and Texas state-level privacy laws impose additional voice recognition consent layers, complicating multi-jurisdictional deployment architectures.
- On-premises infrastructure lock-in:PCI-DSS audit trail requirements in financial services segments sustain capital-intensive physical data center commitments, slowing cloud migration velocity.
- Phonetic model training costs:Domain-specific acoustic model development demands labeled datasets exceeding 10,000 hours, concentrating advanced capabilities among well-capitalized platform providers.
Strategic Opportunities
- Mexican nearshore contact centers:Bilingual speech analytics penetration remains under 15 percent among Guadalajara and Monterrey operations serving US healthcare and financial services clients.
- Emotion detection convergence:Integration of acoustic prosody analysis with lexical sentiment scoring enables preemptive escalation protocols in high-stakes patient and collections interactions.
- Subscription pricing normalization:Seat-based license displacement by consumption-metered contracts lowers procurement friction for mid-market buyers previously excluded from enterprise-tier platforms.
Industry Challenges
- Conversational AI engineer scarcity:Cross-functional expertise spanning phonetics, transformer architectures, and healthcare compliance commands salary premiums exceeding 40 percent above standard data science roles.
- Legacy telephony integration:SIP trunk interoperability with 1990s-era private branch exchange systems consumes 6-12 month implementation timelines, delaying value realization and eroding customer lifetime value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Speech Analytics Market |
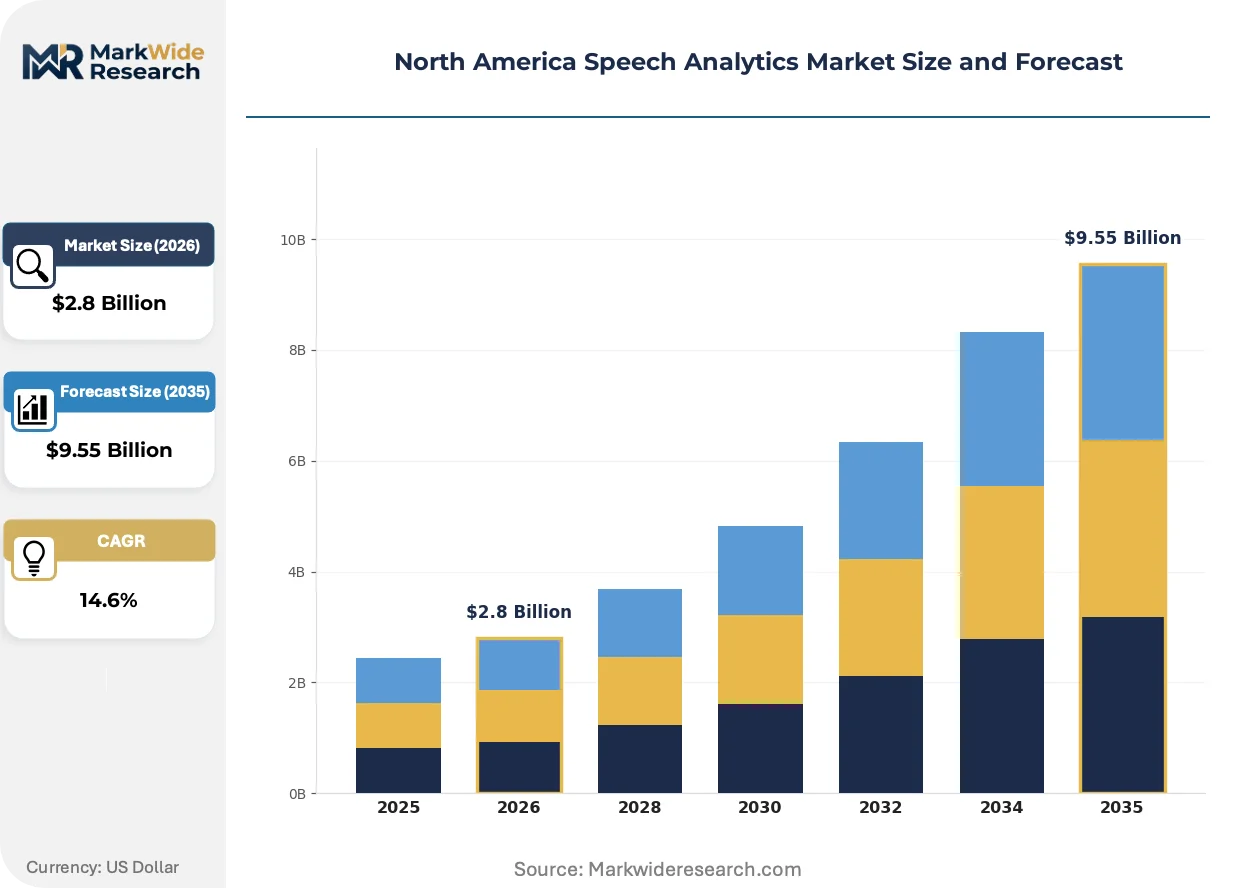
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: BFSI, Healthcare Providers, Retailers, Telecom Technology: NLP, Machine Learning, Voice Recognition, Analytics Application: Compliance Monitoring, Customer Engagement, Quality Assurance, Market Research |
| Companies Covered | NICE Ltd., Verint Systems Inc., CallMiner, Inc., Genesys Cloud Services, Inc., Avaya Inc., Calabrio, Inc., OpenText Corporation, Amazon Web Services, Inc., Hewlett Packard Enterprise Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Speech Analytics Market Strategic Shifts
Transformer-based architectures are compressing the accuracy gap between real-time and batch transcription, collapsing the historical trade-off between speed and precision that structured vendor segmentation. This technical convergence enables unified platforms to serve both compliance archiving and live coaching use cases.
Phonetic indexing technology is migrating from rules-based classification engines to neural embedding search, enabling semantic retrieval of conversational moments without predefined keyword libraries. Healthcare providers in Texas and Illinois deploy these systems to surface adverse event indicators across millions of recorded patient interactions. The structural consequence compresses quality assurance staffing ratios while elevating detection sensitivity for regulatory reporting obligations.
FCC enforcement patterns under the Telephone Consumer Protection Act are intensifying documentation requirements for recorded consent, with automated verification becoming standard in telecom and retail outbound operations. Enterprises now embed speech analytics directly into dialer workflows to flag non-compliant interactions before regulatory exposure materializes. This regulatory pressure concentrates demand among vendors with pre-built TCPA compliance modules and audit-ready reporting dashboards.
Mid-market procurement patterns favor outcome-based pricing structures that tie vendor compensation to measurable operational improvements rather than seat-based licensing. Canadian provincial health authorities and US regional banks negotiate contracts with tiered fees contingent on compliance violation reduction or customer satisfaction score movement. This behavioral shift compresses vendor margins during implementation phases while extending contract durations and switching costs post-deployment.
North America Speech Analytics Market Segmentation
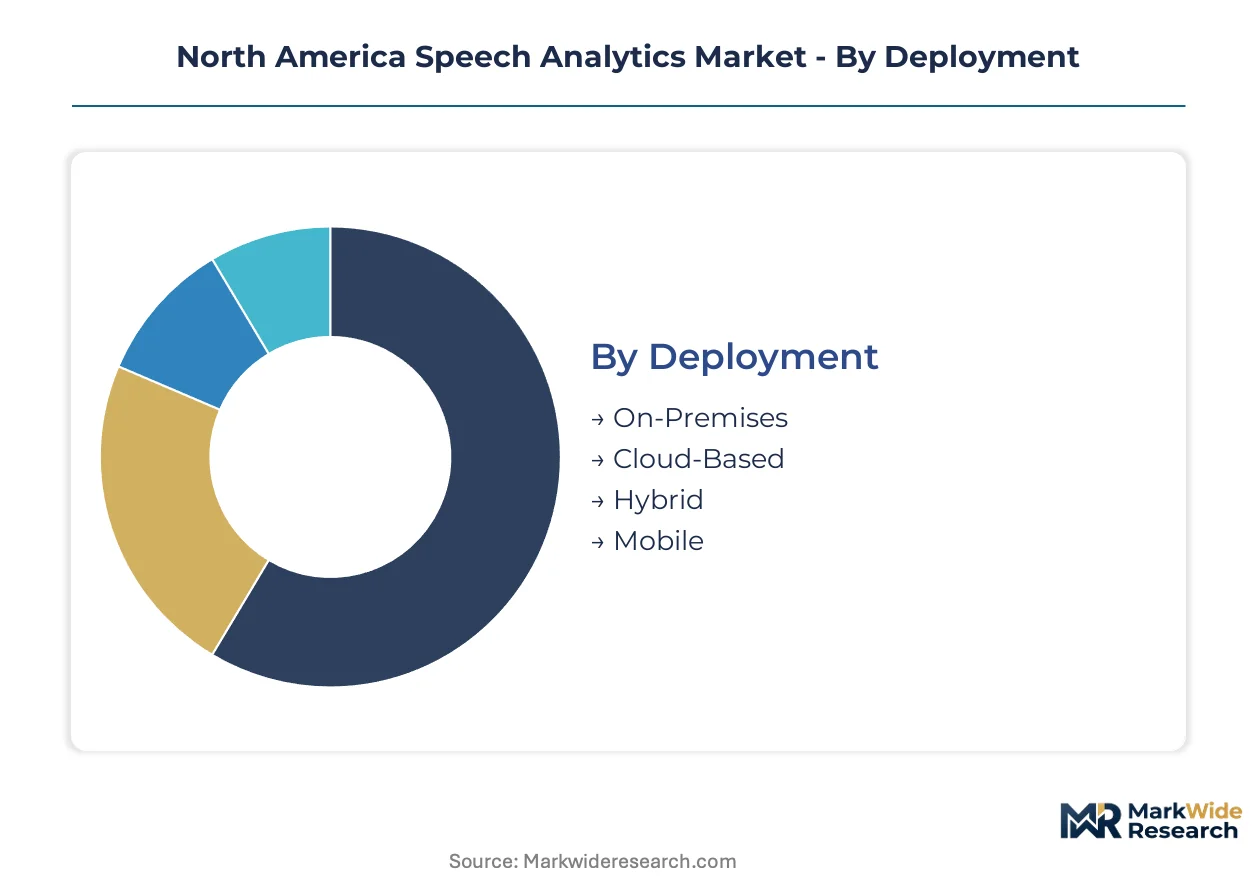
Speech analytics buyers in North America segment procurement decisions across infrastructure posture, regulatory exposure, and real-time latency requirements. Vendor positioning depends on matching deployment flexibility to HIPAA consent workflows in Texas hospitals or PCI-DSS audit trails in Chicago financial services.
Deployment:
Use-case spectrum spans legacy PBX integration in established BFSI contact centers to elastic GPU inference for healthcare startups.
- On-Premises:Physical infrastructure control satisfies HIPAA and PCI-DSS audit trail mandates. Chicago and New York BFSI operations sustain capital-intensive commitments to avoid cloud data residency exposure. The dominant share belongs to On-Premises, while Cloud-Based is closing the gap fastest.
- Cloud-Based:Elastic GPU clusters compress inference latency below 300 milliseconds for real-time agent guidance. Subscription pricing narrows capital barriers for mid-market buyers previously excluded from enterprise-tier platforms.
- Hybrid:Bridges legacy on-premises investments with cloud scalability, preserving compliance-sensitive workloads locally while offloading batch transcription.
- Mobile:Edge deployment for field-based healthcare workers and remote collections agents operating beyond reliable network coverage.
Cloud deployment contracts are expanding most quickly among Canadian provincial health authorities negotiating consumption-metered terms.
End User:
Cost tier stratification separates enterprise compliance budgets from mid-market outcome-based procurement.
- BFSI:Contact centers in New York and Chicago deploy sub-second coaching alerts to reduce TCPA regulatory exposure. PCI-DSS requirements sustain on-premises infrastructure lock-in despite cloud migration pressure.
- Healthcare Providers:HIPAA privacy rules compel de-identification workflow architecture. Texas and Illinois providers face additional state-level biometric consent layers that fragment implementation standards.
- Retailers:FCC consent documentation mandates drive automated compliance monitoring adoption across outbound telemarketing operations.
- Telecom:Dialer workflow integration flags non-compliant interactions before TCPA exposure materializes, with audit-ready reporting dashboards as standard procurement requirements.
BFSI captures the dominant procurement volume, though Healthcare Providers are gaining share fastest as voice recognition tools expand into patient interaction monitoring.
Technology:
Application maturity separates rules-based legacy systems from transformer architectures displacing classification engines.
- NLP:Leads current investment flows as transformer-based architectures compress the accuracy gap between real-time and batch transcription. Neural embedding search enables semantic retrieval without predefined keyword libraries.
- Machine Learning:Displaces rules-based classification engines in quality assurance workflows. Domain-specific acoustic model development demands labeled datasets exceeding 10,000 hours, concentrating capabilities among well-capitalized providers.
- Voice Recognition:Illinois and Texas biometric privacy laws impose additional consent layers, complicating multi-jurisdictional deployment architectures.
- Analytics:Structured intelligence output for regulatory compliance, operational quality, and revenue protection across archived and live voice streams.
NLP holds the dominant technology position, while Machine Learning is climbing the fastest as inference pipelines rebuild around elastic GPU clusters.
Application:
Customer type differentiation separates reactive compliance archiving from proactive operational intervention.
- Compliance Monitoring:FCC TCPA enforcement intensifies recorded consent documentation requirements. Automated verification bundles into core platform offerings for telecom and retail outbound operations.
- Customer Engagement:Real-time agent guidance reduces average handle times while elevating satisfaction scores. Outcome-based pricing ties vendor compensation to measurable operational improvements.
- Quality Assurance:Phonetic indexing migration to neural embedding search compresses staffing ratios while elevating detection sensitivity for regulatory reporting obligations.
- Market Research:Semantic retrieval surfaces adverse event indicators across millions of recorded patient interactions for healthcare providers in Texas and Illinois.
Compliance Monitoring commands the dominant application share, though Customer Engagement is expanding most quickly as real-time coaching protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America speech analytics market exhibits a pronounced trade surplus in software services, with United States-based platforms exporting cloud infrastructure and compliance modules to Canadian healthcare authorities and Mexican nearshore contact centers. Cross-border data flows concentrate licensing revenue in US technology hubs while operational deployment spreads across sub-regional clusters.
United States
FCC Telephone Consumer Protection Act enforcement drives automated consent documentation adoption across retail and telecom outbound operations. HIPAA privacy rules administered by the Office for Civil Rights compel healthcare providers in Texas and Illinois to architect de-identification workflows with state-level biometric consent overlays. BFSI contact centers in New York and Chicago deploy sub-second coaching alerts to compress average handle times and reduce regulatory exposure.
Canada
Provincial health authorities in Ontario and Quebec negotiate consumption-metered cloud contracts to narrow capital barriers for mid-market buyers. Health Canada oversight of medical device software classification creates specification premiums for vendors with healthcare-specific certifications. Toronto and Vancouver technology corridors anchor hybrid deployment architectures bridging legacy on-premises investments with elastic GPU inference.
Mexico
Guadalajara and Monterrey nearshore contact centers serving US healthcare and financial services clients drive bilingual speech analytics penetration currently under 15 percent. The national data protection authority imposes cross-border transfer requirements that complicate centralized cloud analytics platforms. Mexican operations leverage lower operational costs to justify extended implementation timelines for legacy telephony integration.
North America Speech Analytics Market Competitive Environment
On the supply side, the industry is consolidating around platform providers with elastic GPU clusters and healthcare-specific compliance certifications. Incumbent vendors face pressure to rebuild inference pipelines as transformer architectures compress latency thresholds below 300 milliseconds. Three strategic archetypes dominate: cloud-native specialists competing on outcome-based pricing, hybrid deployment architects bridging legacy and modern infrastructure, and compliance-focused platforms bundling regulatory modules. Dominant competitive moves include strategic partnerships with dialer workflow providers and geographic expansion into underpenetrated nearshore markets.
Within the established platform tier, NICE Ltd. and Verint Systems Inc. occupy positions defined by installed base density in financial services compliance. CallMiner, Inc. exemplifies the real-time specialist archetype, competing on outcome-based pricing structures rather than traditional seat-based licenses. These three companies anchor the competitive structure while cloud-native challengers erode margins through consumption-metered contracts.
| Leading Market Players |
|---|
| NICE Ltd. |
| Verint Systems Inc. |
| CallMiner, Inc. |
| Genesys Cloud Services, Inc. |
| Avaya Inc. |
| Calabrio, Inc. |
| OpenText Corporation |
| Amazon Web Services, Inc. |
| Hewlett Packard Enterprise Company |
| Others |
Value Chain & Pricing Dynamics
Single-source GPU cluster dependency concentrates pricing power among hyperscaler-backed platform providers while compressing margins for on-premises hardware vendors serving PCI-DSS-constrained BFSI buyers. This concentration forces tiered spreads between elastic cloud inference and capital-intensive physical infrastructure deployments.
Pricing Analysis
Enterprise compliance buyers anchor subscription pricing across three consumption tiers—premium real-time inference, standard batch transcription, and economy archival search—with differentiation driven by latency guarantees and HIPAA certification depth. Cost compression in the mid-market tier intensifies as consumption-metered contracts displace seat-based licenses. Healthcare providers in Texas and Illinois exhibit highest price sensitivity due to state-level biometric compliance overlays, while New York BFSI contact centers accept premium pricing for sub-300-millisecond agent guidance.
Supply Chain Analysis
Tariff exposure between the United States and China for advanced GPU accelerators dominates supply chain risk planning for inference pipeline vendors. Taiwan and South Korea anchor semiconductor fabrication for speech processing chips, while Mexico's nearshore contact centers draw from US-licensed cloud infrastructure to satisfy cross-border data transfer constraints. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams, with legacy telephony integration partners extending implementation timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America speech analytics market enters a cyclical recovery phase as FCC enforcement waves force compliance infrastructure refresh cycles across retail and telecom outbound operations.
For Market Incumbents: Insulate recurring revenue density by embedding TCPA compliance modules directly into dialer workflow partnerships, neutralizing cloud-native challengers competing on outcome-based pricing. Deepen healthcare-specific certification portfolios to capture specification premiums from Texas and Illinois providers facing biometric consent fragmentation. For New Entrants and Emerging Players: Pursue bilingual speech analytics penetration in Guadalajara and Monterrey contact centers, where current adoption sits below 15 percent among operations serving US healthcare and financial services clients. Lead with consumption-metered contracts that bypass capital barriers excluding mid-market buyers from incumbent platforms. For Investors and Strategic Acquirers: FCC consent documentation mandates reshape the acquisition landscape toward platforms with pre-built compliance modules and audit-ready reporting dashboards. Target hybrid deployment architects bridging legacy on-premises investments with elastic GPU inference, with signal concentration in healthcare-specific HIPAA certification depth as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding speech analytics into dialer workflows captures FCC compliance verification demand from telecom and retail outbound operations. |
| Geographic Expansion | Bilingual capability deployment in Mexican nearshore centers addresses underpenetrated demand from US healthcare and BFSI clients. |
| Acquisition of Specialist Firm | Neural embedding search specialists accelerate phonetic indexing migration from rules-based classification engines. |
| Strategic Partnership | Hyperscaler GPU cluster alliances compress inference latency below 300 milliseconds for real-time agent guidance contracts. |
| Product Launch | Healthcare-specific de-identification modules capture specification premiums from Texas and Illinois providers. |
Study Parameters
The analysis maps cloud-based deployment, on-premises infrastructure, hybrid architectures, and mobile edge computing, each validated through CTOs at BFSI contact centers, HIPAA compliance officers at Texas and Illinois health systems, procurement leads at Canadian provincial authorities, and integration specialists serving Mexican nearshore operations. Primary interview findings triangulate against secondary sources including FCC enforcement filings, HIPAA Office for Civil Rights guidance documents, hyperscaler capex disclosures, and state-level biometric privacy statutes. Bottom-up contract value aggregation cross-checks against top-down market sizing across deployment models and end-user verticals.
Forecast assumptions hold regulatory enforcement intensity and GPU cluster availability fixed while varying enterprise cloud migration velocity and mid-market subscription adoption rates. The analytical framework segments by deployment posture, end-user vertical, technology layer, and application use case across the projection horizon. CAGR derivation incorporates speech processing patent filing trajectories, healthcare voice data pipeline investment announcements, and contact center seat expansion patterns in target metropolitan clusters.
Sensitivities concentrate around FCC enforcement pattern shifts, state-level biometric law expansion beyond Illinois and Texas, and hyperscaler GPU allocation constraints affecting real-time inference pricing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
APAC Location Analytics Market
Analytics
FMCG Spending on Analytics Market
Analytics
Emotion Analytics Market
Analytics
Global in-Store Analytics Market
Analytics
Behavior Analytics Market
Analytics
Saudi Arabia Geospatial Analytics Market
Analytics
IT Operation Analytics (ITOA) Software Market
Analytics
Global AI Video Analytics Market
Analytics
Marketing Analytics Software Market
Analytics
Cloud Analytics Market
Analytics
Advanced Analytics Market
Analytics
Europe Speech Analytics Market
Analytics
Europe Edge Analytics Market
Analytics
Patent Analytics Services Market
Analytics
Complex Event Processing Market
Analytics
Global Data Visualization Tools Market