
 Greece ICT Market | 2026-2036
Greece ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Greece ICT Market Insights
Enterprise buyers is rotating toward cloud-native procurement models while legacy on-premise spending contracts. Microsoft Corporation leverages its Azure footprint to anchor public-sector modernization contracts across Greek ministries. Amazon Web Services competes through dedicated local zones that reduce latency for fintech and logistics clients. Intracom Telecom sustains its position in domestic networking infrastructure through specialized 5G equipment for island connectivity.
Information and communications technology encompasses software systems, hardware devices, networking infrastructure, and associated services that enable data processing, transmission, and storage across organizational boundaries. Cloud computing platforms utilize distributed server architectures with virtualization layers to deliver elastic compute resources without capital-intensive physical deployments. Software and services capture expanding margin pools as recurring revenue models displace perpetual licenses. Cybersecurity within the technology dimension leads growth as Greek financial institutions and healthcare providers harden defenses against escalating threat volumes.
The European Commission's Digital Decade targets and Greece's National Recovery and Resilience Plan shape procurement standards by mandating interoperability and green criteria for publicly funded ICT projects. BIS-aligned national standards and GDPR compliance requirements filter vendor eligibility for sensitive government and healthcare contracts. Stakeholders must monitor how EU AI Act implementation timelines affect algorithmic service deployments in Greek banking and public administration.
Market Dynamics
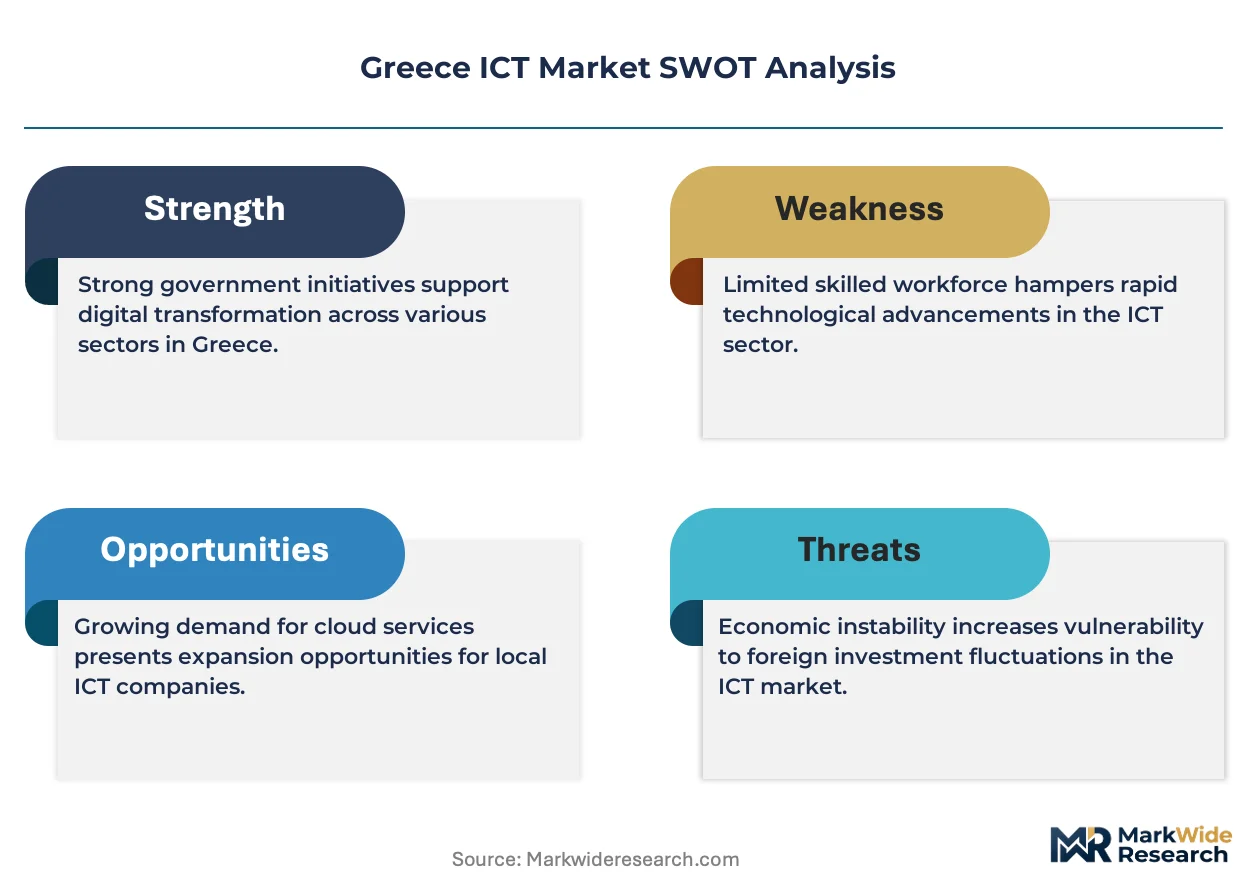
EU Recovery and Resilience Facility capital flows are restructuring Greece's public procurement landscape, with interoperability mandates and green criteria now gatekeeping vendor eligibility for ministry contracts.
Growth Catalysts
- Cloud infrastructure mandates:The National Recovery and Resilience Plan channels EU funds toward public-sector data center modernization, creating guaranteed demand pipelines for compliant vendors.
- Athens-Thessaloniki enterprise clustering:Concentrated banking and logistics headquarters in these metropolitan zones generate dense connectivity requirements that sustain networking equipment procurement cycles.
- Cybersecurity hardening in financial services:Greek banking regulators enforce stricter data protection protocols, expanding security software and services budgets across institutional IT departments.
Market Restraints
- Specialized engineering talent scarcity:Domestic universities produce insufficient cloud architecture and AI systems specialists, forcing enterprises to import skills at premium cost structures.
- Island geography fragmentation:Dispersed population centers across the Aegean and Ionian archipelagos multiply last-mile infrastructure deployment costs versus continental European benchmarks.
- Legacy system interdependency:Decades of accumulated on-premise government databases create technical debt that slows cloud migration timelines and inflates integration budgets.
Strategic Opportunities
- Crete and Peloponnese regional digitization:Secondary urban centers outside Athens-Thessaloniki remain underpenetrated for enterprise SaaS and managed services, offering first-mover expansion potential.
- EU AI Act compliance services:Algorithmic audit and governance tooling represents emerging white space as Greek financial institutions prepare for risk-based AI system classifications.
- 5G private network convergence:Manufacturing and port logistics operators in Thessaloniki and Piraeus are piloting dedicated wireless infrastructure, opening industrial IoT integration contracts.
Industry Challenges
- GDPR-BIS dual certification complexity:Vendors must satisfy overlapping national standards and European data governance frameworks, extending contract approval timelines by 40-60 percent.
- Multi-cloud orchestration skill gaps:Enterprise IT teams lack Kubernetes and container management expertise, forcing reliance on external systems integrators that fragment accountability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greece ICT Market |
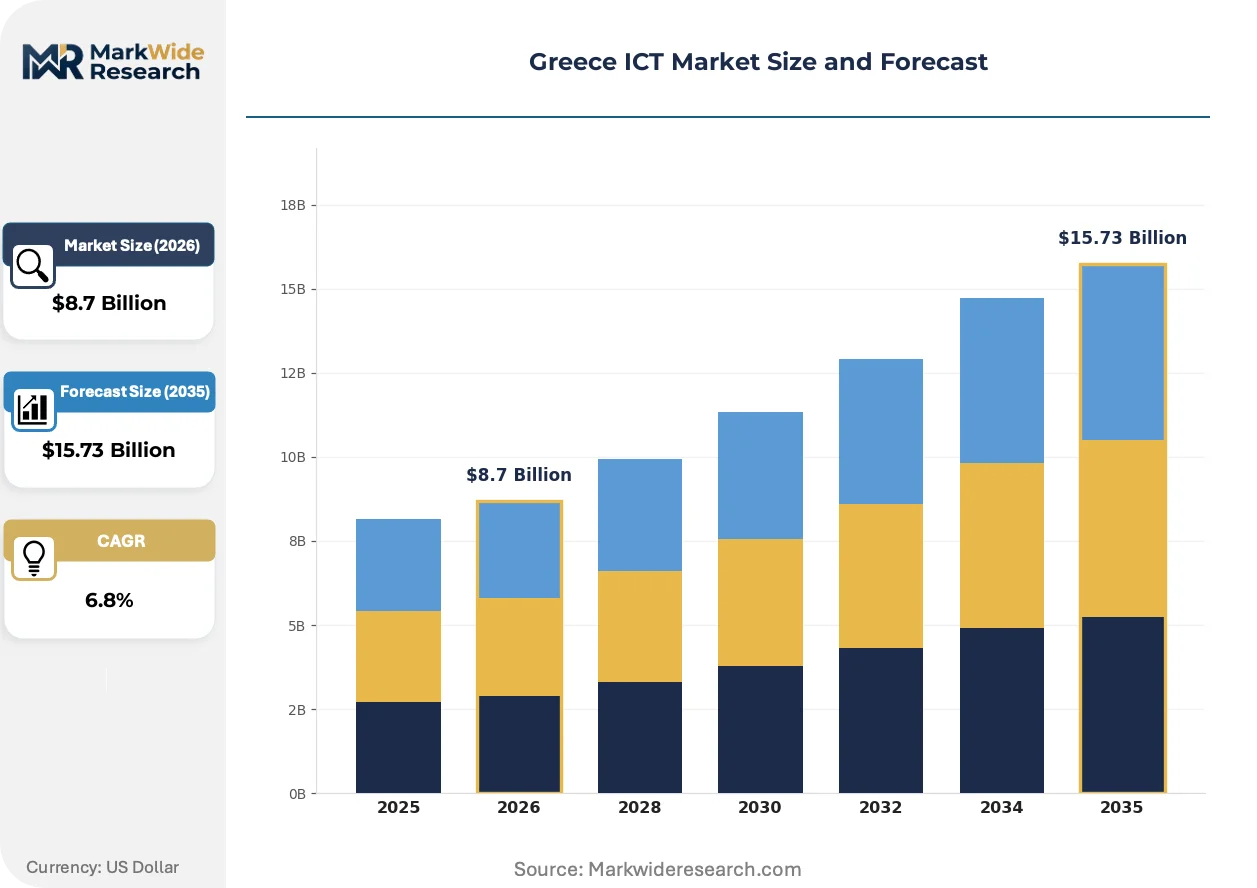
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Networking, Services Technology: Cloud Computing, Big Data, IoT, Cybersecurity End User: Government, Education, Healthcare, Retail Service Type: Consulting, Managed Services, Support, Training |
| Companies Covered | Microsoft Corporation, Google LLC, Amazon Web Services, IBM, Oracle Corporation, Cisco Systems Inc, SAP SE, Hellenic Telecommunications Organization, Intracom Telecom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greece ICT Market Trends and Innovations
Containerized application architectures and sovereign cloud requirements are reconfiguring how Greek enterprises evaluate vendor relationships and infrastructure deployment models.
Serverless computing platforms are displacing traditional virtual machine provisioning in Greek fintech and e-commerce operations. Development teams at Athens-based digital payment providers adopt function-as-a-service models to eliminate idle compute costs. This shift is displacing capital-intensive private data center expansion plans among mid-market enterprises.
The EU AI Act's risk-based classification system is reshaping algorithmic procurement standards for Greek banking and public administration. High-risk automated decision systems now require conformity assessments before deployment. Credit scoring and welfare eligibility platforms face the steepest compliance redesign timelines.
Subscription-based managed security services are supplanting perpetual-license antivirus and firewall purchases among regional healthcare providers. Hospital IT departments in Thessaloniki outsource threat detection to specialized operators rather than building internal security operations centers. This pattern concentrates most visibly in public hospital networks where budget predictability outweighs capital ownership preferences.
Greece ICT Market Segmentation
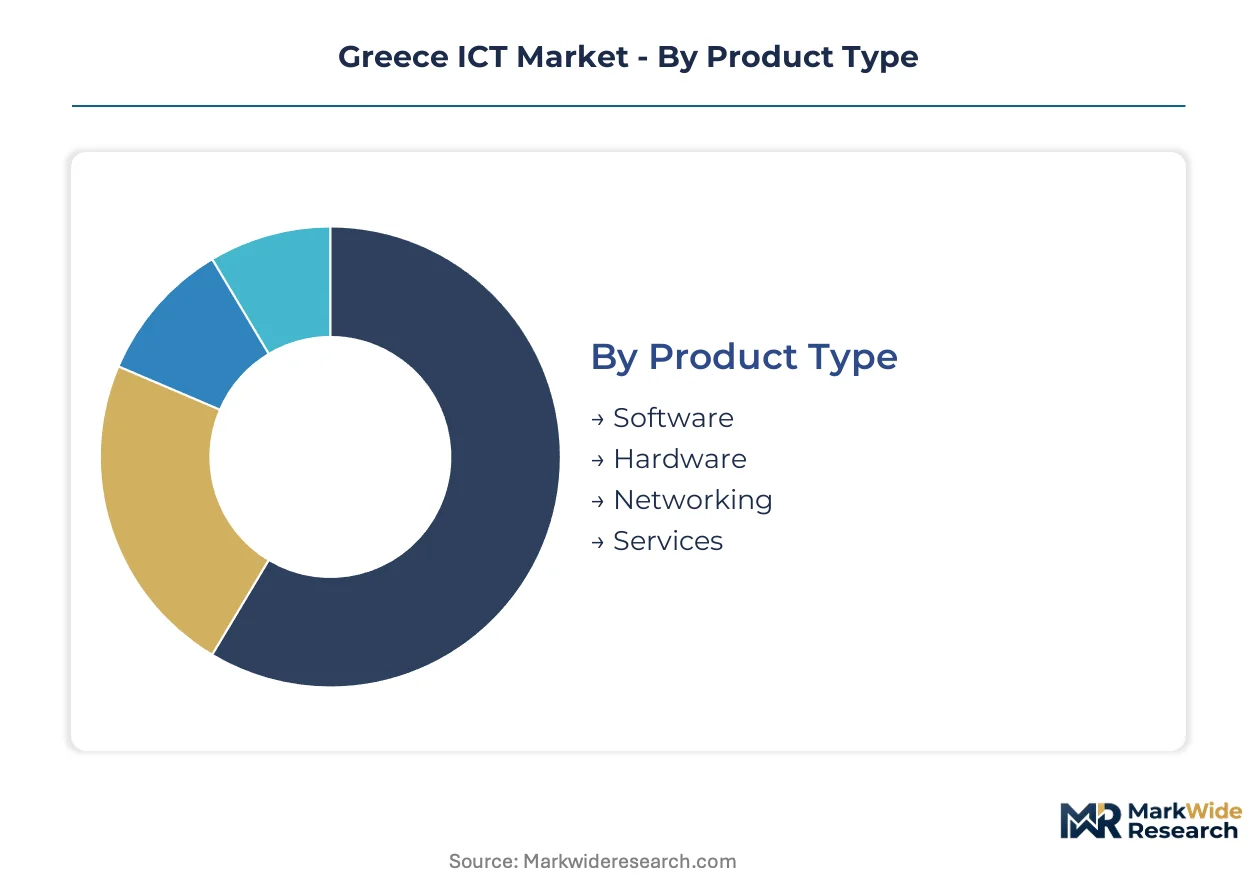
Segmentation reveals how EU Recovery and Resilience Facility capital is concentrating across procurement channels in Greece. Vendors must map their offerings against four intersecting dimensions to capture ministry and enterprise contracts.
Product Type:
GDPR and BIS certification requirements filter vendor eligibility differently across physical versus intangible product categories.
- Software:Cloud-native applications with containerized architectures dominate public-sector modernization tenders. Athens-based banking and logistics headquarters drive demand for enterprise resource planning and customer relationship management platforms that satisfy EU interoperability mandates.
- Services:Recurring-revenue managed services displace perpetual licenses as Greek healthcare providers and government agencies prioritize operational expenditure predictability. System integration and consulting contracts expand with National Recovery and Resilience Plan implementation.
- Hardware:Server and storage equipment procurement concentrates in enterprise data center clusters around Athens and Thessaloniki. Green criteria in public tenders favor energy-efficient infrastructure refresh cycles.
- Networking:Specialized 5G equipment addresses island connectivity gaps across the Aegean archipelago. Maritime and tourism operators in dispersed geographies sustain demand for robust last-mile infrastructure.
Software handles the majority of throughput; Services is expanding most quickly on share.
Technology:
Cost tier differentiation separates capital-intensive infrastructure deployments from subscription-based consumption models.
- Cloud Computing:Distributed server architectures with virtualization layers deliver elastic compute without capital-intensive physical deployments. Greek fintech and e-commerce operators in Athens adopt serverless function-as-a-service models to eliminate idle compute costs.
- Cybersecurity:Risk-based protection protocols mandated by banking regulators expand security software and services budgets. Greek financial institutions and healthcare providers harden defenses against escalating threat volumes through subscription-based managed security services.
- Big Data:Analytics platforms process transactional streams from retail and logistics operations. Thessaloniki port operators leverage predictive maintenance algorithms to optimize cargo handling efficiency.
- IoT:Industrial sensor networks pilot in manufacturing and port logistics across Thessaloniki and Piraeus. 5G private network convergence enables dedicated wireless infrastructure for real-time operational monitoring.
Cybersecurity commands premium pricing tiers; Cloud Computing is gaining share fastest.
End User:
Application maturity varies sharply between digitally advanced metropolitan centers and underpenetrated regional markets.
- Government:Ministry procurement pipelines guarantee demand for compliant vendors satisfying interoperability and green criteria. National Recovery and Resilience Plan directs EU funds toward data center modernization and citizen service digitization.
- Healthcare:Hospital IT departments outsource threat detection to specialized operators rather than building internal security operations centers. Public hospital networks prioritize budget predictability over capital ownership.
- Retail:E-commerce platforms drive cloud consumption with seasonal elasticity requirements. Digital payment providers adopt agile development frameworks to accelerate feature deployment.
- Education:University and research institutions generate demand for high-performance computing and collaborative platforms. Domestic universities produce insufficient cloud architecture specialists, forcing skills import at premium cost structures.
Government anchors procurement volume; Healthcare shows the steepest expansion trajectory.
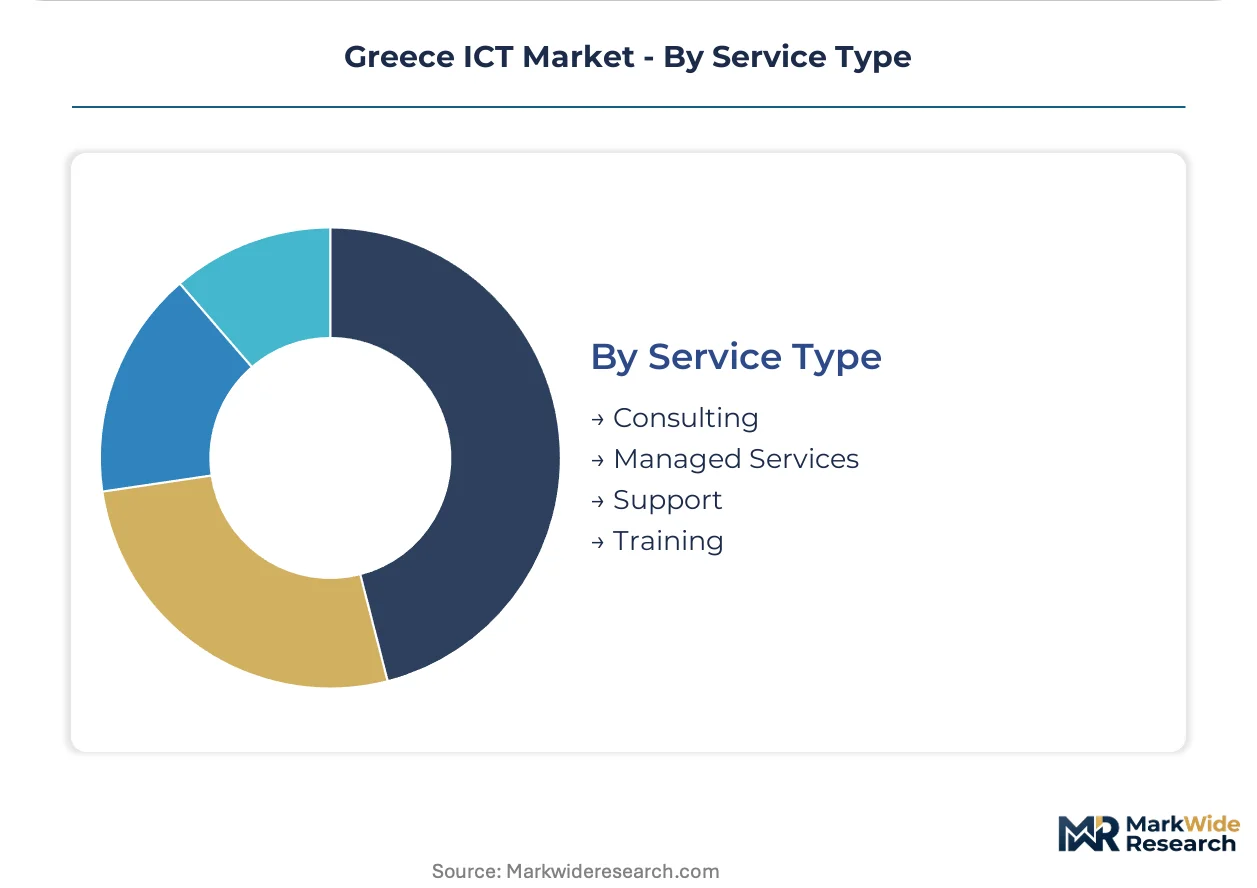
Service Type:
Customer type segmentation separates enterprise buyers with internal capabilities from organizations requiring full operational handoff.
- Managed Services:Outsourced infrastructure operations allow Greek mid-market enterprises to bypass Kubernetes and container management skill gaps. External systems integrators assume accountability for multi-cloud orchestration.
- Consulting:EU AI Act compliance services represent emerging demand as financial institutions prepare for risk-based algorithmic system classifications. Conformity assessments for high-risk automated decision systems require specialized advisory.
- Support:Technical maintenance contracts sustain legacy system interdependencies in government databases. Decades of accumulated on-premise infrastructure slow cloud migration timelines and inflate integration budgets.
- Training:Capability building addresses domestic engineering talent scarcity in cloud architecture and AI systems. Enterprises invest in upskilling programs to reduce premium costs of imported specialists.
Managed Services captures the largest contract values; Consulting is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greek ICT vendors export cloud and cybersecurity services to Southeast European buyers in Bulgaria, Romania, and Cyprus. The country's EU Recovery and Resilience Facility positioning channels digital infrastructure expertise toward Balkan markets seeking interoperability-compliant modernization.
Attica Region
Athens hosts dense banking and fintech headquarters demanding low-latency cloud connectivity. The National Recovery and Resilience Plan mandates interoperability standards for ministry data center contracts. Piraeus port operators pilot 5G private networks for cargo handling automation.
Central Macedonia
Thessaloniki anchors northern enterprise demand with logistics and manufacturing IT spending. GDPR compliance requirements filter vendor eligibility for public hospital network tenders. Industrial zones around the port city test IoT sensor networks for supply chain visibility.
Crete
Heraklion and Chania drive regional digitization outside the Athens-Thessaloniki axis. University research institutions generate high-performance computing demand for collaborative platforms. Maritime tourism operators sustain specialized networking equipment procurement for island connectivity.
Peloponnese
Patras and Kalamata represent underpenetrated territory for enterprise SaaS expansion. Green criteria in public tenders favor energy-efficient infrastructure refresh cycles. Manufacturing SMEs in Corinth industrial areas adopt managed services to bypass internal Kubernetes skill gaps.
Greece ICT Market Competitive Landscape
Listed leaders compete with private specialists across cloud infrastructure procurement channels, creating a tiered vendor structure in Greece. Microsoft Corporation and Amazon Web Services anchor the hyperscale cloud segment through Azure local zones and dedicated infrastructure investments. Oracle Corporation and IBM occupy positions in legacy system integration and database migration services. Strategic moves concentrate on public-sector contract capture through EU fund compliance certification and regional data center capacity expansion.
Within the hyperscale cloud tier, Microsoft Corporation and Amazon Web Services exemplify platform-first positioning anchored by local infrastructure presence. IBM represents the legacy integration archetype serving government database migration requirements. Among domestic specialists, Intracom Telecom occupies a networking equipment position addressing island geography fragmentation through 5G and microwave solutions.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Amazon Web Services |
| IBM |
| Oracle Corporation |
| Cisco Systems Inc |
| SAP SE |
| Hellenic Telecommunications Organization |
| Intracom Telecom |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with hyperscale cloud providers lock in multi-year compute access and price predictability for Greek enterprises navigating EU Recovery and Resilience Facility procurement timelines. These arrangements tie infrastructure costs to indexed service tiers while insulating buyers from spot-market volatility in semiconductor-dependent hardware procurement.
Pricing Analysis
Next-generation sovereign cloud deployments command 40-60 percent premiums over standard public cloud instances due to data residency certification and localized edge infrastructure. Subscription-based managed security services stratify across premium, standard, and economy tiers based on threat response SLAs and analyst coverage levels. Cost compression in legacy on-premise hardware intensifies as cloud-native procurement displaces capital-intensive refresh cycles. Mid-market enterprises in Thessaloniki exhibit highest price sensitivity, while Athens-based financial institutions prioritize compliance-grade service tiers over unit economics.
Supply Chain Analysis
Port congestion at Piraeus and container availability constraints on Asia-Europe trade lanes extend lead times for server and networking equipment inbound to Greek data center operators. Taiwan and South Korea anchor semiconductor supply for cloud infrastructure hardware, while Germany and the Netherlands feed enterprise software licensing and systems integration services. Single-source vulnerability concentrates in specialized 5G baseband processors and AI accelerator chips. Distribution runs through Athens-based systems integrators and Thessaloniki channel partners serving northern enterprise clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greek ICT procurement is reconfiguring around service-attach revenue models where managed security and compliance consulting expand faster than underlying hardware shipments. Recurring-revenue layers now capture margin pools previously locked in perpetual license and equipment sale transactions.
For Market Incumbents: Consolidate cloud infrastructure positions through EU fund certification investments that gate ministry contract eligibility against emerging regional competitors. Deepen vertical integration into sovereign cloud operations by establishing Attica-based data center capacity. Channel control over Kubernetes-certified systems integrators defends against hyperscaler direct-sales encroachment into mid-market accounts.
For New Entrants and Emerging Players: Differentiate on EU AI Act compliance tooling as algorithmic audit services face supply scarcity against accelerating financial sector demand. Target Crete and Peloponnese regional healthcare networks where managed security services penetration lags Athens-Thessaloniki benchmarks. Partner with domestic universities on cloud architecture training programs to reduce customer skills-import premiums and accelerate contract cycles.
For Investors and Strategic Acquirers: The market sits at a public-sector modernization phase that favors recurring-revenue service providers with established GDPR-BIS dual certification capabilities. Long-term viability hinges on exposure to EU Recovery and Resilience Facility contract pipelines extending through the analysis window. Acquisition target archetypes include specialized cybersecurity operators with Greek healthcare network references and regional systems integrators holding ministry cloud migration contracts. Monitor National Recovery and Resilience Plan disbursement velocity as the primary inflection signal for enterprise IT budget release.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU data residency mandates from GDPR and national BIS standards gate public-sector contract eligibility for infrastructure vendors. |
| Managed Security Service Launch | Greek banking regulators enforce stricter protocols that expand outsourced threat detection budgets across institutional IT departments. |
| 5G Private Network Deployment | Thessaloniki and Piraeus port operators pilot dedicated wireless infrastructure for cargo handling automation and industrial IoT integration. |
| EU AI Act Compliance Tooling | Algorithmic audit services address emerging white space as financial institutions prepare for risk-based automated decision system classifications. |
| Regional Data Center Expansion | Attica and Central Macedonia capacity additions reduce latency for Athens fintech and Thessaloniki logistics headquarters demanding low-latency connectivity. |
Research Methodology
Cross-validation between executive interviews with cloud platform providers and secondary analysis of EU Recovery and Resilience Facility procurement disclosures anchors the qualitative findings in documented contract flows. Primary fieldwork encompassed discussions with Greek ministry IT directors, cybersecurity vendor account executives, systems integration specialists, and healthcare network procurement officers. Secondary sources included National Recovery and Resilience Plan implementation reports, BIS certification registries, and hyperscaler regional capex disclosures. Bottom-up segment sizing triangulated against top-down EU fund allocation trajectories to validate market boundary definitions.
Sensitivity analysis tested forecast robustness across alternative disbursement scenarios for EU facility capital and varying cloud adoption velocity assumptions. The analytical framework modeled product type, technology, end user, and service type dimensions alongside deployment complexity tiers and regional adoption patterns. CAGRs derived from historical spending trajectories and projected EU fund absorption rates. Industry-specific inputs encompassed ministry digitalization timelines, banking regulator security mandate enforcement schedules, and 5G spectrum allocation progress.
Material uncertainties — EU fund disbursement delays, regulatory enforcement timeline shifts, and geopolitical semiconductor supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding interoperability mandate compliance and green procurement criteria adoption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
North America Operational Intelligence Market
Analytics
IT Operation Analytics (ITOA) Market
Analytics
Global Cognitive Analytics Market
Analytics
Global Visual Analytics Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Global Network Analytics Market
Analytics
Behavior Analytics Market
Analytics
Web Analytics Market
Analytics
Content Analytics Discovery and Cognitive Software Market
Analytics
Voice Analytics Market
Analytics
Mobile Business Intelligence Market
Analytics
Global Industrial Analytics Market
Analytics
Network Traffic Analytics Market
Analytics
Mobile Analytics Market
Analytics
Data Preparation Market
Analytics
Data Analytics Outsourcing Market