
 Content Analytics Software Market | 2026-2036
Content Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Content Analytics Software Market Outlook
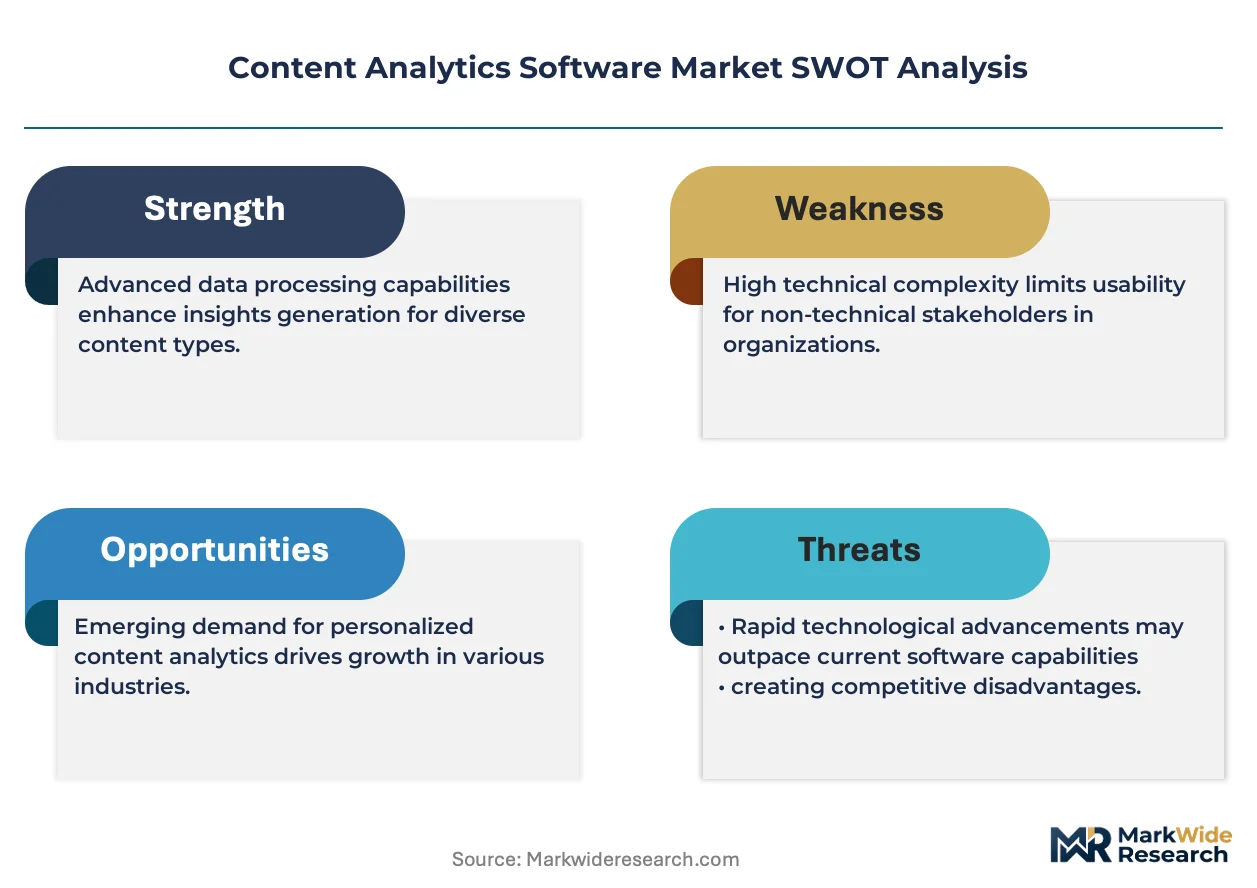
The EU AI Act is pivoting procurement priorities for automated content classification across European media houses and publishing conglomerates. Adobe Systems Inc. leverages its Creative Cloud integration to anchor enterprise content workflows, while IBM Corporation sustains R&D intensity in natural language processing engines for regulated industries. Microsoft competes through Azure AI services that embed compliance-ready analytics for multinational corporations navigating cross-border data governance.
Content analytics software encompasses platforms that apply computational linguistics, machine learning, and statistical pattern recognition to extract structured intelligence from unstructured text, audio, image, and video repositories, typically processing content at throughput rates exceeding thousands of documents per minute. These systems serve industrial and commercial purposes by enabling automated sentiment detection, entity extraction, topic clustering, and predictive content performance modeling across digital publishing, customer experience management, and regulatory surveillance workflows. Cloud-based and SaaS solution types capture expanding margin pools as enterprises prioritize elastic scaling over capital-intensive on-premises infrastructure, while hybrid deployment models retain traction among financial institutions subject to data residency constraints. The media and entertainment vertical leads in volume deployment, though healthcare and finance segments exhibit steeper trajectory curves as clinical documentation and transactional surveillance requirements intensify.
The EU AI Act and GDPR jointly shape demand by mandating explainability thresholds for automated content decisions and restricting cross-border training data transfers, compelling vendors to architect region-specific model instances. The US Federal Trade Commission and Securities and Exchange Commission enforce parallel transparency and market surveillance standards that elevate procurement scrutiny around algorithmic bias documentation. Stakeholders must monitor evolving interoperability mandates between national AI governance frameworks to anticipate certification burdens that will determine competitive access across the Atlantic corridor.
Market Dynamics
Multimodal AI architectures are compressing development cycles for content analytics platforms, forcing vendors to restructure engineering roadmaps around unified inference pipelines rather than discrete text, image, and audio processing modules.
Growth Catalysts
- EU AI Act explainability mandates:European publishers and broadcasters are procuring audit-ready sentiment analysis tools to satisfy algorithmic transparency requirements for automated content moderation systems.
- Real-time streaming analytics:Media conglomerates processing live audience feedback across OTT platforms demand sub-second latency in multilingual emotion detection engines.
- Silicon Valley cluster effects:Concentrated venture deployment in San Francisco and Seattle accelerates enterprise adoption of cloud-native text analytics infrastructure.
Market Restraints
- GPU compute cost volatility:Training and inference expenses for large language models fluctuate with semiconductor foundry capacity constraints in Taiwan and South Korea.
- Data residency fragmentation:Divergent national cloud sovereignty laws force redundant infrastructure deployment across Germany, France, and the United Kingdom.
- Annotation bottleneck:High-quality labeled datasets for low-resource languages remain concentrated among a narrow base of specialized linguistic service providers.
Strategic Opportunities
- Clinical documentation automation:Healthcare systems in India and Brazil present underpenetrated demand for voice-to-structure analytics in electronic health record workflows.
- Convergence of computer vision and NLP:Unified platforms analyzing video transcripts alongside visual sentiment cues unlock premium pricing in broadcast journalism.
- GDPR Article 22 enforcement:Automated decision-making restrictions create compliance-service revenue streams for vendors offering human-in-the-loop content classification.
Industry Challenges
- Multilingual model engineering scarcity:Talent capable of optimizing transformer architectures for morphologically complex languages commands premium compensation and extends hiring timelines.
- Legacy CMS integration friction:Decades-old publishing content management systems in established media houses resist API-native analytics embedding without expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Analytics Software Market |
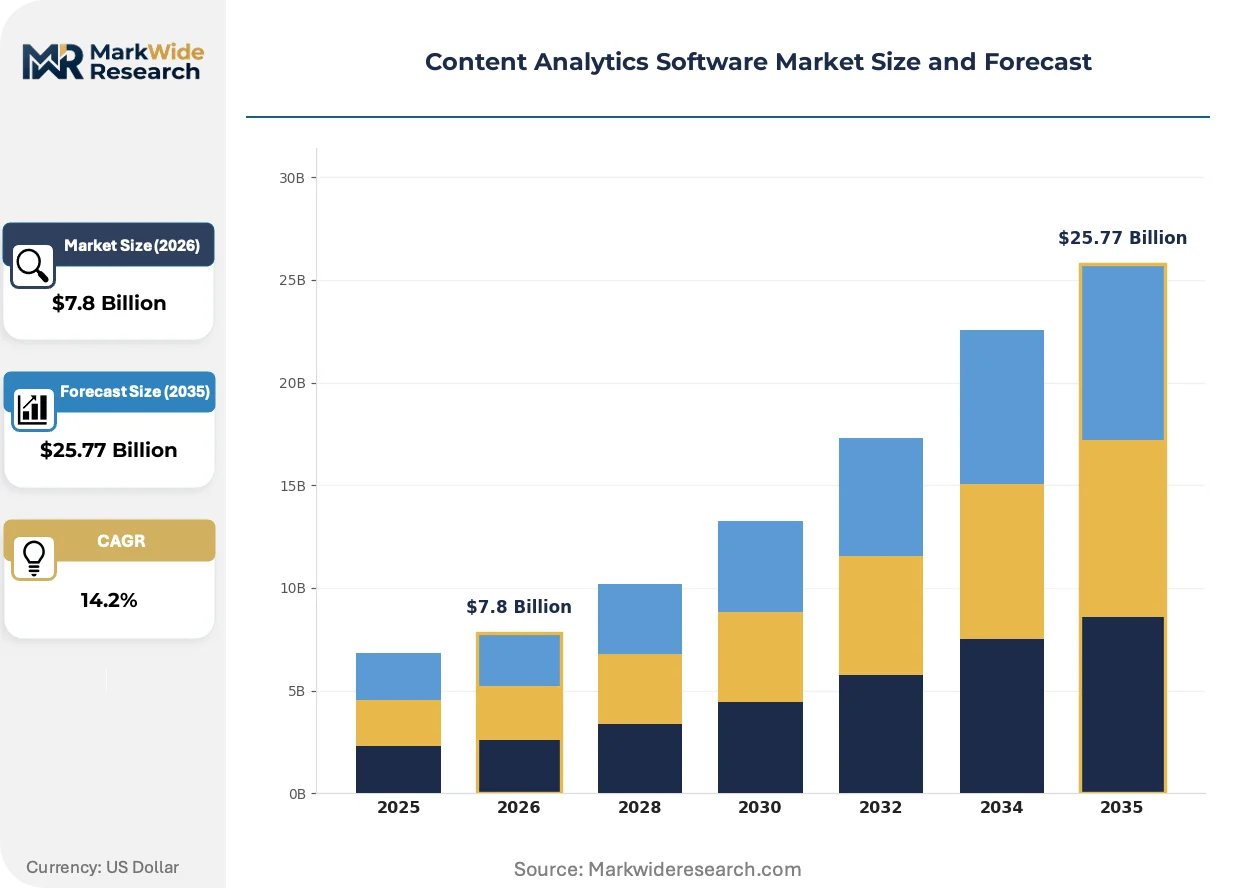
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $25.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: On-Premises, Cloud-Based, Hybrid, SaaS Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Hybrid Cloud End User: Enterprises, SMBs, Educational Institutions, Government Industry Vertical: Media & Entertainment, Retail, Healthcare, Finance |
| Companies Covered | Adobe Systems Inc., IBM Corporation, Microsoft, Google LLC, Oracle Corporation, Clarabridge Inc., OpenText Corporation, SAP SE, SAS Institute Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Analytics Software Market Strategic Shifts
Foundation model architectures are commoditizing baseline natural language capabilities, compelling vendors to differentiate through vertical-specific fine-tuning and proprietary data moats rather than raw parameter scale.
Retrieval-augmented generation is consolidating enterprise trust in content analytics outputs by grounding model responses in verifiable document corpora rather than parametric knowledge. Financial compliance departments at multinational banks are deploying these architectures for audit trail preservation in automated surveillance workflows. The structural consequence is compressing differentiation between generalist and specialist vendors as RAG infrastructure becomes table stakes.
The EU AI Act's risk-classification framework is forcing vendors to reengineer product roadmaps around prohibited-practice lists and high-risk system registration requirements. Automated content recommendation engines now require conformity assessments before deployment in European media markets. Publishers in France and Germany are prioritizing vendors with established notified body relationships to accelerate certification timelines.
Enterprise buyers are unbundling perpetual software licenses in favor of consumption-metered API access for document processing workloads. Media houses in the United States are shifting from seat-based pricing to per-page or per-minute transcription and analysis models. This reconfiguration is most visible among mid-market digital publishers optimizing variable cost structures against irregular content volumes.
Content Analytics Software Market Segmentation
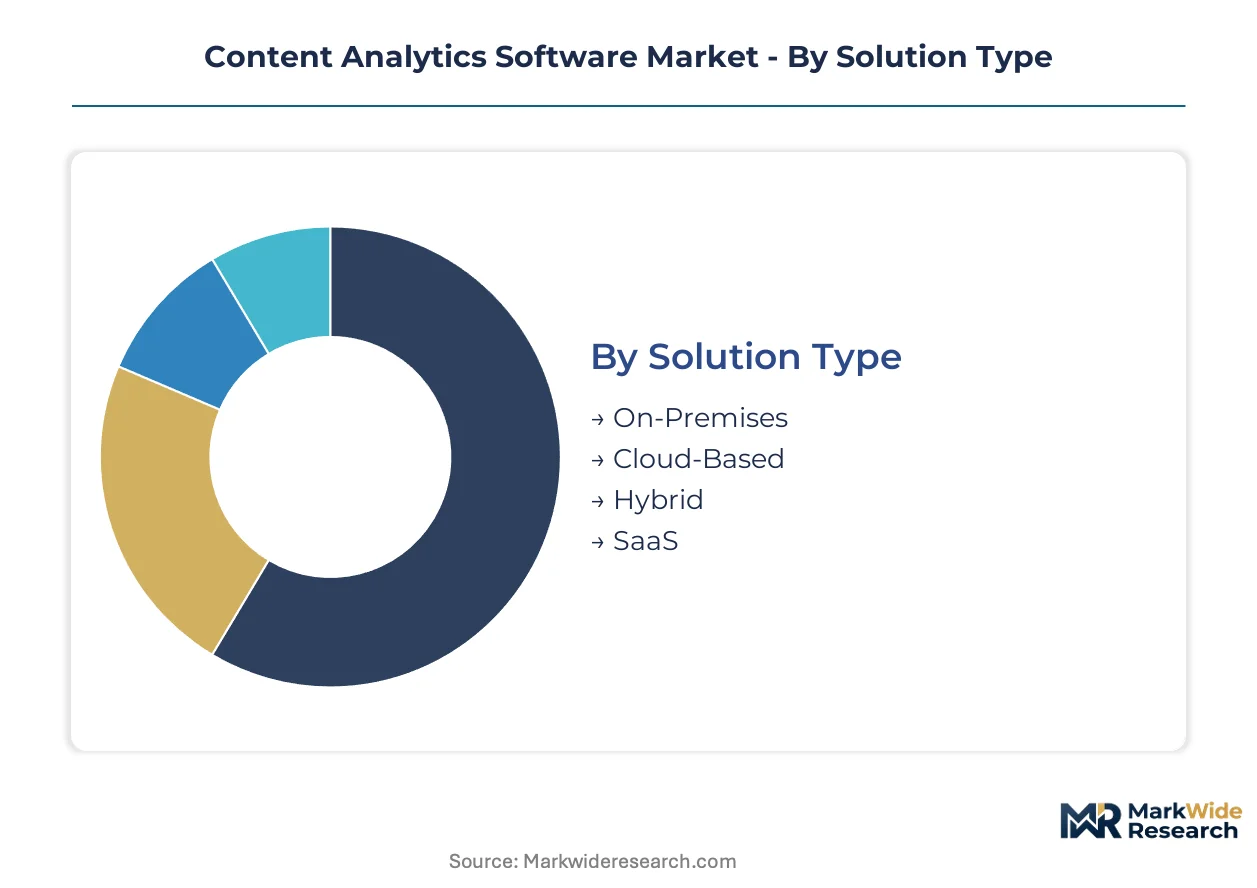
Segmentation in content analytics software reveals how procurement priorities diverge across infrastructure constraints, compliance burdens, and vertical-specific performance requirements. Vendors architect certification pathways and pricing architectures around these fault lines.
Solution Type:
EU AI Act high-risk system registration requirements and GDPR data residency mandates create divergent certification burdens across deployment modes, with cloud-native solutions facing multi-jurisdictional conformity assessments.
- Cloud-Based:Fully managed infrastructure with elastic compute scaling processes streaming content workloads without capital expenditure. Media conglomerates in France and Germany prioritize these deployments to satisfy GDPR Article 44 transfer mechanism requirements through region-specific model instances.
- SaaS:Subscription-metered access to pre-trained analytics engines eliminates infrastructure management overhead. Financial institutions in Singapore and the United States adopt these solutions for rapid deployment of sentiment monitoring across trading communications, though API rate limits constrain throughput for surveillance-scale workloads.
- On-Premises:Self-hosted infrastructure retains sensitive content within organizational network perimeters, satisfying national cloud sovereignty laws in Germany and China.
- Hybrid:Split architectures process non-sensitive workloads in cloud environments while retaining regulated data on local infrastructure, common among healthcare systems managing patient records.
Cloud-Based solutions sit at the top of the volume ranking, with SaaS climbing the fastest as procurement shifts from perpetual licenses to consumption-metered contracts.
Deployment Model:
Cost tier differentiation separates enterprise-grade private infrastructure from developer-accessible public alternatives, with multi-cloud strategies commanding premium pricing for redundancy guarantees.
- Public Cloud:Shared infrastructure pools deliver cost-efficient compute for batch processing of historical content archives. Digital publishers in India and Brazil leverage these deployments for seasonal traffic spikes without committed capacity reservations.
- Private Cloud:Dedicated single-tenant environments provide isolated processing for classified government communications and proprietary financial surveillance data. Defense contractors in the United States and intelligence agencies in the United Kingdom mandate these deployments for automated document classification workflows.
- Multi-Cloud:Distributed architectures across AWS, Azure, and Google Cloud mitigate vendor lock-in and regional outage risks. Multinational banks operating across London, Frankfurt, and New York deploy these models to satisfy divergent national data localization requirements without redundant platform engineering.
- Hybrid Cloud:Interconnected public-private environments balance burst capacity needs against baseline sovereignty constraints, prevalent among European broadcasters managing live event analytics.
Public Cloud captures the widest customer base by unit volume, while Multi-Cloud deployments gain share fastest among regulated enterprises seeking operational resilience.
End User:
Customer type determines feature complexity thresholds, with government procurement mandating explainability documentation that consumer-grade SMB solutions rarely provide.
- Enterprises:Global 2000 organizations deploy integrated content analytics suites across customer experience, risk management, and knowledge management functions. Technology conglomerates in Silicon Valley and Seattle clusters demand sub-second latency for real-time streaming analytics across multilingual social media feeds.
- Government:National security agencies and regulatory bodies require audit-ready algorithmic decision trails for automated content classification. The EU AI Act's high-risk system registry compels European public sector buyers to prioritize vendors with established notified body relationships in France and Germany.
- SMBs:Mid-market publishers and marketing agencies adopt stripped-down sentiment analysis tools through self-service onboarding portals.
- Educational Institutions:University research libraries and digital humanities departments leverage open-source analytics pipelines for archival text mining and citation network analysis.
Enterprises dominate current procurement volumes, though Government segment expansion accelerates most quickly under regulatory transparency mandates.
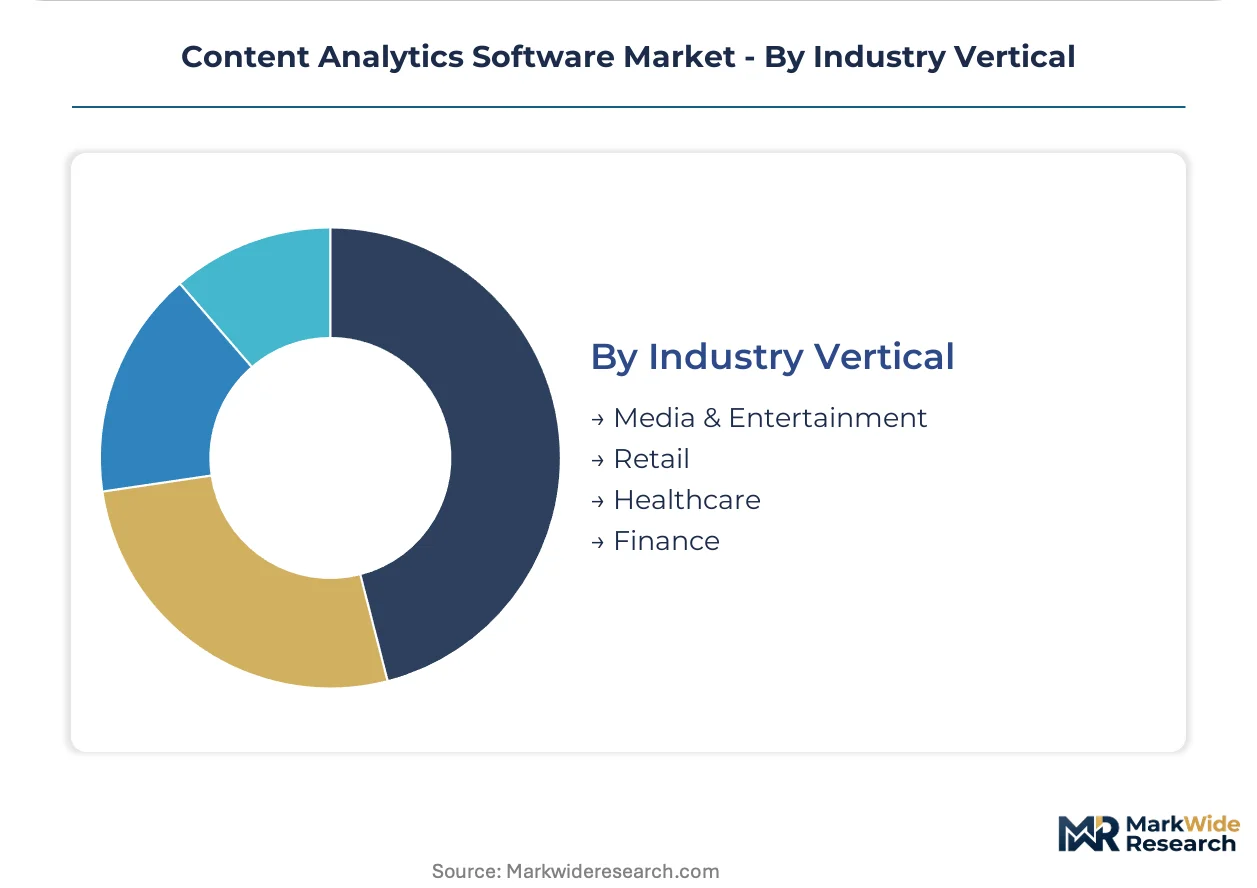
Industry Vertical:
Application-specific engineering requirements fragment vendor roadmaps, with healthcare clinical documentation and finance surveillance workflows demanding specialized compliance architectures.
- Media & Entertainment:Broadcasters and streaming platforms deploy real-time sentiment engines to optimize content recommendation algorithms and advertising insertion. OTT providers in the United States and South Korea process live audience feedback across millions of concurrent viewers, requiring multilingual emotion detection at sub-second latency.
- Finance:Investment banks and insurance carriers monitor transactional communications for market manipulation and conduct risk. The US SEC and UK FCA enforce surveillance standards that elevate procurement scrutiny around algorithmic bias documentation and audit trail preservation.
- Healthcare:Hospital systems and pharmaceutical companies extract structured data from unstructured clinical notes and regulatory submissions. Voice-to-structure analytics for electronic health record workflows concentrate demand in India and Brazil as these markets expand digitization initiatives.
- Retail:E-commerce platforms and consumer brands analyze product reviews and social conversations for brand health monitoring and competitive intelligence.
Media & Entertainment leads vertical deployment volumes, with Finance gaining momentum fastest under intensifying regulatory surveillance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Content analytics software traces its commercial origins to natural language processing research clusters at Stanford University and MIT during the 1990s, with venture deployment accelerating through Silicon Valley's enterprise software ecosystem before diffusing to European financial centers and Asian technology hubs.
United States
Enterprise procurement concentrates among media conglomerates and financial institutions demanding real-time sentiment analysis across streaming platforms and trading communications. The SEC and FTC enforce algorithmic transparency standards that elevate vendor scrutiny around bias documentation and audit trail preservation. Silicon Valley clusters in San Francisco and Seattle anchor cloud-native text analytics infrastructure deployment, while New York Metro financial institutions drive surveillance-scale workload requirements.
Germany
Industrial manufacturing and automotive conglomerates deploy content analytics for supply chain documentation and regulatory submission processing. The EU AI Act and GDPR Article 22 impose explainability mandates for automated decision systems, compelling vendors to establish notified body relationships for conformity assessments. Bavaria's Munich-Stuttgart corridor hosts enterprise software procurement headquarters for DAX-listed industrial groups.
United Kingdom
Investment banks and insurance carriers in the City of London procure surveillance analytics for market manipulation detection and conduct risk monitoring. The UK FCA enforces transparency standards parallel to EU AI Act requirements, creating certification continuity for vendors operating across the Channel. London's financial district concentrates procurement decision-making for multinational banking groups with pan-European operations.
India
Healthcare systems and pharmaceutical companies drive voice-to-structure analytics demand for electronic health record digitization and clinical documentation automation. The Digital India initiative and CDSCO regulatory frameworks accelerate procurement of multilingual text processing infrastructure for regional language clinical workflows. Karnataka's Bangalore cluster anchors software development operations serving domestic healthcare digitization and export-oriented analytics services.
Japan
Manufacturing conglomerates and financial institutions deploy content analytics for technical documentation processing and compliance surveillance across keiretsu supply networks. METI industrial digitization policies and PMDA regulatory submission requirements shape procurement priorities for structured data extraction from unstructured technical repositories. Tokyo's Marunouchi-Otemachi district concentrates enterprise procurement for financial services and industrial technology groups.
Content Analytics Software Market Competitive Environment
Premium-margin players sit above commodity-margin players across compliance certification depth and vertical-specific model fine-tuning capabilities. The vendor base stratifies into three tiers: hyperscale cloud platforms with integrated AI services, enterprise software incumbents with established regulatory relationships, and specialized analytics vendors with proprietary linguistic assets. Dominant competitive moves include strategic partnerships for notified body certification acceleration and geographic expansion through region-specific model deployment to satisfy data residency mandates.
Within the enterprise software incumbent tier, Adobe Systems Inc., IBM Corporation, and Microsoft occupy positions defined by creative workflow integration, regulated industry R&D intensity, and cloud-native compliance architecture respectively. Adobe's Creative Cloud ecosystem anchors publishing industry procurement, IBM's research heritage shapes natural language processing credibility for financial surveillance applications, and Microsoft's Azure AI services embed cross-border governance capabilities for multinational deployment. These three exemplify how vertical integration depth and regulatory relationship breadth determine competitive access across Atlantic corridor procurement processes.
| Leading Market Players |
|---|
| Adobe Systems Inc. |
| IBM Corporation |
| Microsoft |
| Google LLC |
| Oracle Corporation |
| Clarabridge Inc. |
| OpenText Corporation |
| SAP SE |
| SAS Institute Inc. |
| Others |
Value Chain & Pricing Dynamics
Transformer architecture specialists concentrated in the San Francisco Bay Area and Bangalore command compensation premiums that compress margins in the premium tier while widening spreads between economy-grade API services and enterprise-certified deployments. Labor-cost differentials between these talent clusters and Eastern European development centers directly shape three-tier pricing stratification across consumption-metered, subscription-bound, and perpetual-license contract structures.
Pricing Analysis
Consumption-metered API access dominates procurement among mid-market digital publishers, with pricing differentiation driven by certification grade for EU AI Act compliance and volume-scale thresholds for batch processing workloads. Cost compression in the economy tier intensifies as hyperscale cloud platforms commoditize baseline natural language capabilities through pre-trained model services. Government buyers exhibit lowest price sensitivity due to mandated audit-trail requirements, while SMB segments migrate aggressively toward per-page transcription models to align variable costs with irregular content volumes.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan Semiconductor Manufacturing capacity for GPU compute and South Korean memory fabrication for training infrastructure. NVIDIA accelerator hardware and high-bandwidth memory modules constitute critical input dependencies. Tariff exposure through US-China semiconductor trade restrictions threatens inference cost stability. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales channels, with regional model instances deployed to satisfy German and French data residency mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The content analytics software market functions as a stable compounder, with regulatory transparency mandates across the Atlantic corridor generating durable procurement demand from risk-averse institutional buyers.
For Market Incumbents: Anchor defensive positioning through notified body certification acceleration in France and Germany to preempt EU AI Act compliance windows. Deepen backward integration into proprietary training data pipelines to differentiate against foundation-model commoditization. Prioritize R&D allocation toward retrieval-augmented generation architectures that preserve audit trails for financial surveillance applications.
For New Entrants and Emerging Players: Multimodal video-to-text analytics for broadcast journalism represents the most penetrable white-space opportunity, with unified sentiment detection across visual and transcript cues commanding premium pricing. Target healthcare systems in India and Brazil through voice-to-structure clinical documentation workflows. Pursue partnership-led go-to-market strategies with regional system integrators possessing established electronic health record relationships.
For Investors and Strategic Acquirers: Hyperscale cloud platforms are the most active acquirer in this space, consolidating specialized analytics vendors to deepen vertical integration. Long-term viability rests on data moat durability and regulatory relationship breadth rather than raw model scale. Monitor EU AI Act enforcement intensity as the critical inflection signal for certification-service revenue expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Adobe's Creative Cloud ecosystem anchors publishing workflows through embedded sentiment analytics. |
| Strategic Partnership | IBM sustains financial surveillance credibility through Watson NLP engines for SEC-regulated banks. |
| Acquisition of Specialist Firm | Microsoft consolidates multilingual compliance capabilities through Azure AI regional model deployment. |
| Geographic Expansion | Google extends cloud-native infrastructure to satisfy German and French GDPR Article 44 transfer requirements. |
| Product Launch | Oracle embeds content classification into Fusion Cloud for healthcare clinical documentation automation. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with CTOs, IT procurement officers, platform engineers, and channel partners informed demand-side perspectives, while conversations with integration specialists captured deployment friction points. Secondary sources include SEC filings, hyperscaler capex disclosures, EU regulatory submissions, and clinical documentation databases. Bottom-up and top-down triangulation reconciled segment-level inputs with aggregate market sizing.
Granularity-level modeling deployed solution type, deployment model, organization size, and vertical-specific compliance architecture as core segmentation dimensions across the projection horizon. CAGRs derived from regression analysis against technology adoption curves and regulatory enforcement timelines. Industry-specific forecast inputs incorporated GPU compute cost trajectories and notified body certification pipeline capacity for EU AI Act high-risk system registration.
The model holds under stable semiconductor foundry capacity and gradual regulatory harmonization; deviation in export control expansion or abrupt GDPR enforcement shifts would revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Customer Analytics in E-Commerce Market
Analytics
Dark Analytics Market
Analytics
Geospatial Analytics Market
Analytics
BI and Analytics Market
Analytics
Global Mobile BI Market
Analytics
ASEAN Geospatial Analytics Market
Analytics
Human Resource Analytics Market
Analytics
Imagery Analytics Market
Analytics
Global Telco Data Monetization Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Italy Geospatial Analytics Market
Analytics
Latin America Big Data Analytics Market
Analytics
Global Subscription Analytics Software Market
Analytics
Audio and Video Analytics Software Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Operational Intelligence Market