
 In-Wall Smart Switch Market | 2026-2036
In-Wall Smart Switch Market Size, Share, and Industry Trends Forecast 2026-2036
In-Wall Smart Switch Market Insights
Aftermarket service revenue from firmware updates and cloud connectivity subscriptions is reconfiguring how vendors capture lifetime value from hardware placements. Legrand leverages its European channel density to sustain recurring revenue streams across multi-unit residential deployments. Lutron Electronics anchors its premium positioning through proprietary Clear Connect wireless technology that commands installer loyalty. TP-Link competes aggressively on Wi-Fi native architectures that eliminate hub dependencies for cost-sensitive residential buyers.
An in-wall smart switch is a mains-powered electrical control device that replaces standard wall switches, integrating microprocessors, wireless radios, and relay circuits to enable remote operation, scheduling, and energy monitoring through home automation platforms. These devices typically handle 120-240V AC loads with 10-15 amp ratings and communicate via IEEE 802.15.4 or 802.11 protocols to central hubs or cloud services. The touch switch segment within product type categories captures disproportionate margin pools as capacitive glass interfaces command premium positioning in luxury residential and hospitality verticals. Wi-Fi technology leads volume shipments due to router ubiquity, though Zigbee sustains relevance in whole-home ecosystems where mesh reliability matters for commercial and industrial end users.
The FCC governs radio frequency emissions for Wi-Fi and Zigbee radios sold in the United States, while the EU Radio Equipment Directive mandates CE marking and interoperability testing for devices operating in European spectrum bands. China's MIIT enforces GB standard compliance for wireless transmitters, creating a fragmented certification landscape that shapes product development roadmaps and market access timelines. Stakeholders must monitor evolving cybersecurity labeling requirements from regulators as connected building infrastructure becomes a target surface for network intrusion.
Market Dynamics
Retrofit volumes in aging urban housing stock across Germany, the United States, and China are compressing installation timelines and forcing vendors to pre-certify multi-protocol hardware for fragmented regulatory environments.
Growth Catalysts
- EU F-Gas Regulation:Tightening energy-efficiency mandates for connected building devices accelerate replacement cycles in European multi-unit residential deployments.
- Touch switch interfaces:Capacitive glass surfaces command premium positioning in luxury residential and hospitality verticals, expanding margin pools within product portfolios.
- Zigbee mesh ecosystems:Whole-home reliability requirements in commercial and industrial settings sustain protocol relevance despite Wi-Fi volume dominance.
Market Restraints
- Copper relay component volatility:Input cost swings in electromechanical switching elements compress hardware margins for cost-sensitive residential SKUs.
- Certification fragmentation:FCC, CE marking, and MIIT GB standards create parallel development tracks that extend product launch timelines by 8-14 months.
- Wi-Fi router dependency:Native architectures face reliability degradation in concrete-walled European housing stock, limiting addressable retrofit penetration.
Strategic Opportunities
- Cloud connectivity subscriptions:Firmware update revenue streams reconfigure lifetime value capture from one-time hardware sales to recurring service models.
- Matter protocol convergence:Thread and Wi-Fi unification under CSA standards reduces SKU complexity for vendors serving multi-ecosystem households.
- India's smart city mandates:Government building automation requirements create channel openings for hub-agnostic switch architectures in institutional construction.
Industry Challenges
- Legacy electrical contractor skill gaps:Mains-powered installation requirements clash with low-voltage smart home technician training, creating field deployment friction.
- Cybersecurity labeling delays:Evolving network intrusion standards for connected building infrastructure force reactive firmware architecture changes mid-development cycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Wall Smart Switch Market |
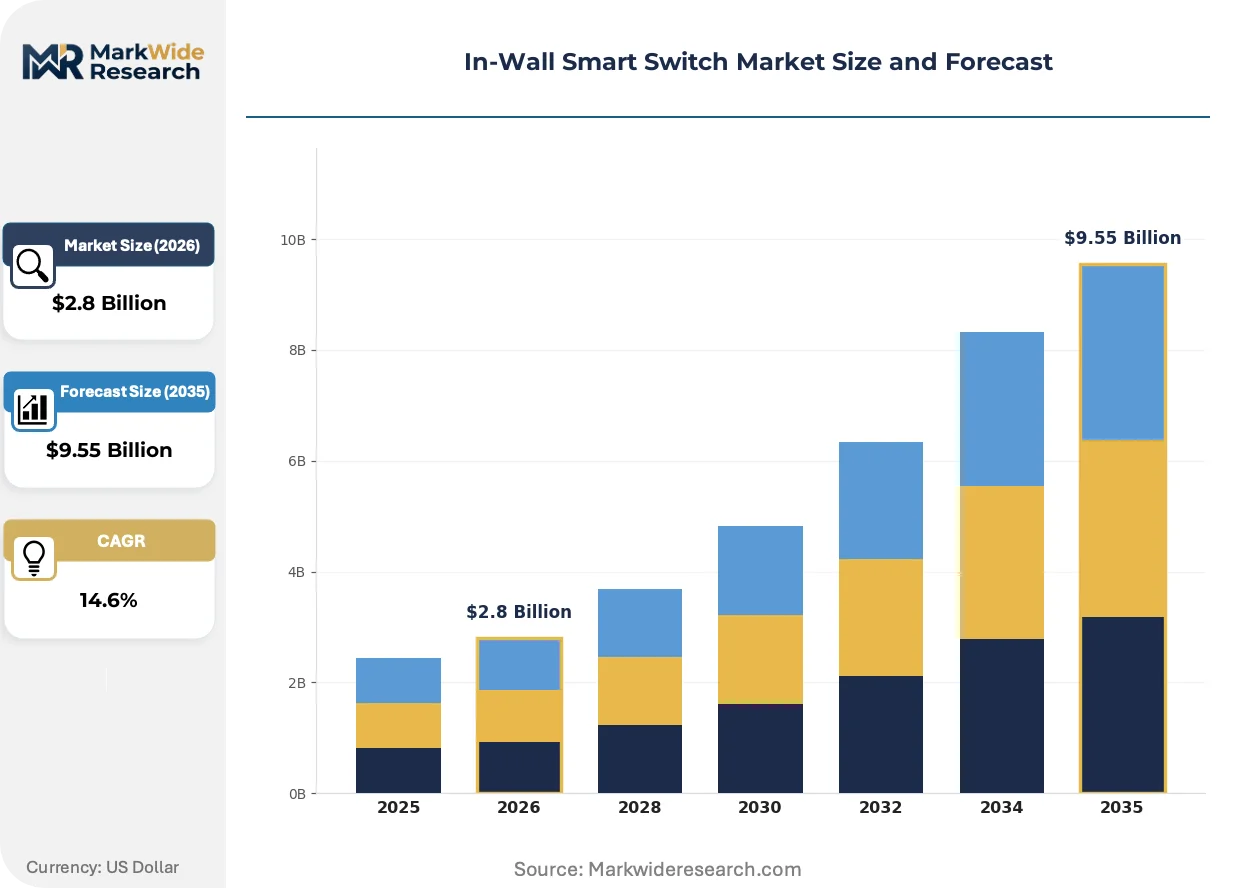
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toggle Switch, Dimmer Switch, Touch Switch, Remote-Controlled Switch Technology: Zigbee, Z-Wave, Bluetooth, Wi-Fi End User: Residential, Commercial, Industrial, Hospitality Installation Type: New Construction, Retrofit, Smart Home Integration, DIY |
| Companies Covered | Legrand, Lutron Electronics, Signify, Leviton, GE Lighting, TP-Link, Gira, BTicino, Igoto Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Wall Smart Switch Market Trends and Innovations
Wireless protocol consolidation and energy-efficiency mandates are compressing hardware differentiation while expanding software and service monetization layers across the value chain.
Capacitive sensing with haptic feedback is digitizing physical switch interaction models. Hospitality operators and luxury residential developers deploy glass-surface controls at accelerated rates. This interface shift is digitizing premium tier segmentation by collapsing mechanical component counts and enabling dynamic iconography updates.
The EU Ecodesign standards and F-Gas Regulation impose standby power limits and material disclosure requirements on connected building devices. Manufacturers redesign power supply architectures to meet sub-0.5W idle consumption thresholds. Germany's federal building codes incorporate these standards earliest, forcing vendors to lead product rollouts there before broader European distribution.
Installer channel consolidation is reshaping procurement patterns for specification-grade products. Electrical contractors increasingly bundle switch procurement with home automation system design, displacing retail self-installation in whole-home projects. This concentration is most pronounced in North American new construction where builder mandates standardize platform choices before homeowner occupancy.
In-Wall Smart Switch Market Segmentation
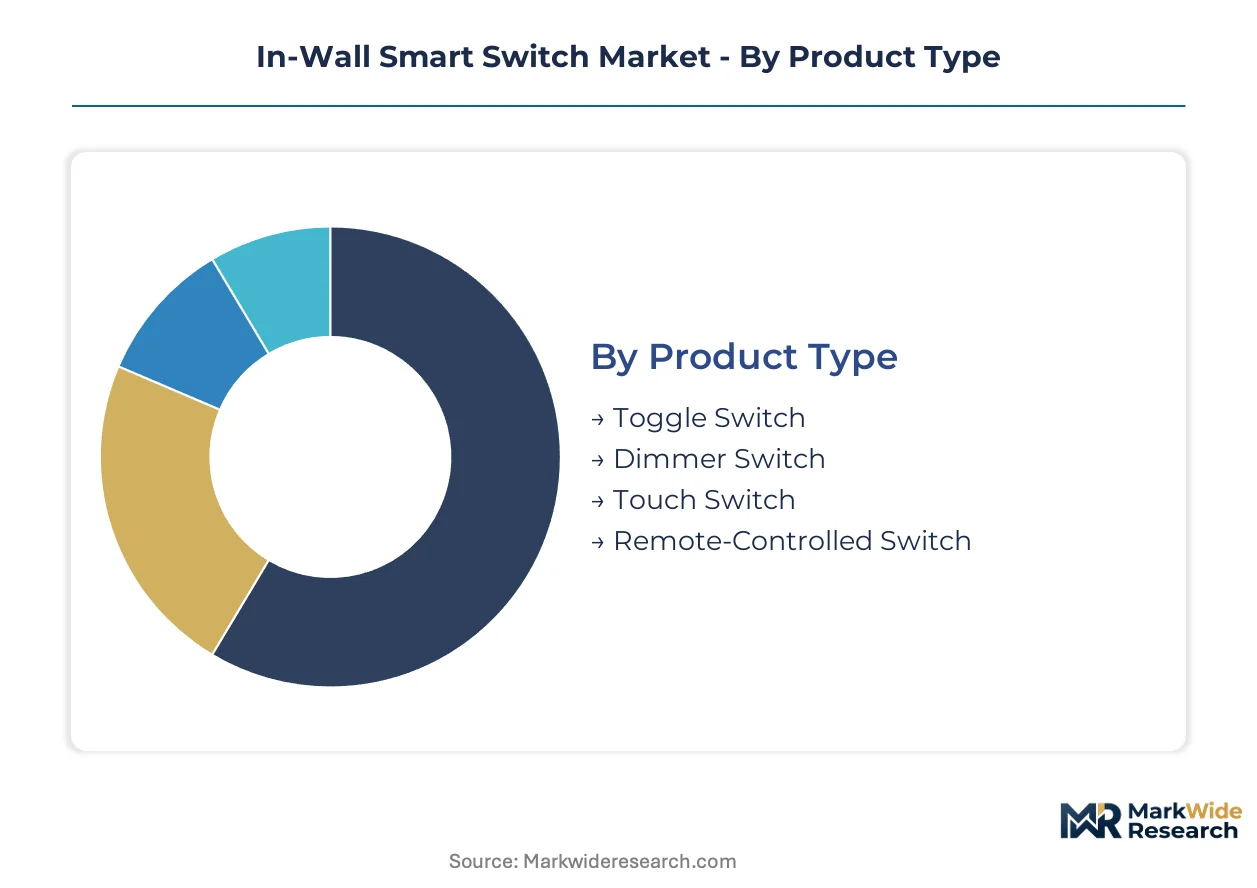
Segmentation in the in-wall smart switch market reveals how protocol choices, interface preferences, and installation contexts fragment procurement patterns. Vendors must architect SKU portfolios that span capacitive glass surfaces to mechanical toggles while navigating divergent wireless certification requirements across deployment environments.
Product Type:
Residential and hospitality operators select interfaces based on aesthetic tier and automation depth requirements.
- Touch Switch:Capacitive glass surfaces eliminate mechanical wear points and enable dynamic iconography updates through firmware. Luxury residential developers in Germany and hospitality chains across the United States specify these interfaces for premium positioning, driven by EU Ecodesign standby power mandates that favor solid-state switching architectures.
- Dimmer Switch:Phase-cut and trailing-edge circuitry modulates LED and incandescent loads across 10-300W ranges. Demand concentrates in aging urban housing stock across China and the United States where retrofit contractors replace legacy rotary dimmers with connected equivalents.
- Toggle Switch:Mechanical actuation retains installer familiarity in cost-sensitive residential segments.
- Remote-Controlled Switch:Battery-free kinetic harvesting or RF-linked wall plates serve hard-to-wire locations.
The dominant share belongs to Dimmer Switch, while Touch Switch is closing the gap fastest.
Technology:
Protocol selection determines hub dependency, mesh reliability, and certification complexity for multi-region product lines.
- Wi-Fi:Native IEEE 802.11 connectivity leverages existing router infrastructure without dedicated gateways. Volume concentrates in DIY residential channels across the United States and China where consumers prioritize plug-and-play simplicity over ecosystem integration depth.
- Zigbee:IEEE 802.15.4 mesh networking sustains whole-home reliability in concrete-walled European housing where Wi-Fi propagation degrades. Commercial and industrial end users in Germany specify Zigbee for its deterministic latency and self-healing topology.
- Z-Wave:Sub-GHz spectrum avoids 2.4GHz congestion in dense multi-unit deployments.
- Bluetooth:Low-energy stacks enable direct smartphone commissioning for single-point installations.
Wi-Fi commands the largest installed base, yet Zigbee is expanding most quickly in specification-grade channels.
End User:
Automation sophistication and procurement authority vary sharply across occupant types.
- Residential:Single-family and multi-unit dwellings drive volume through retail and electrical contractor channels. Retrofit activity in aging German and Chinese urban housing accelerates replacement cycles, constrained by legacy electrical contractor skill gaps in low-voltage integration.
- Hospitality:Guest room management systems demand centralized control and energy monitoring. Operators across the United States deploy glass-surface touch switches to differentiate property tiers while meeting corporate sustainability reporting requirements.
- Commercial:Office and retail spaces prioritize daylight harvesting and occupancy-based switching.
- Industrial:Harsh-environment ratings and 24/7 reliability specifications govern selection.
Residential captures the deepest volume, though Hospitality is gaining share fastest.
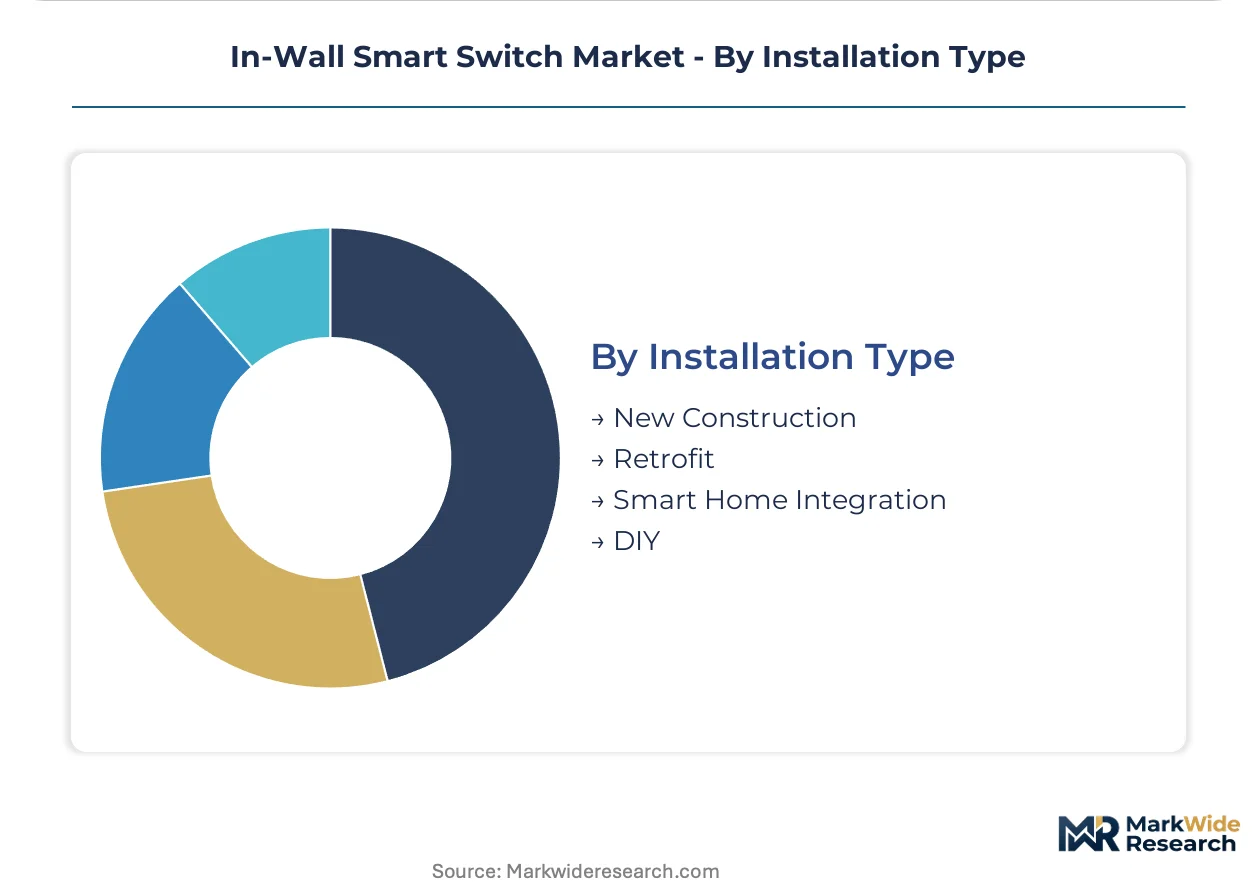
Installation Type:
Channel structure and margin profiles diverge between specification-driven and self-service procurement.
- Retrofit:Replacement of existing wall switches in occupied buildings demands shallow electrical boxes and neutral-wire flexibility. Contractors across Germany and the United States compress installation timelines through pre-certified multi-protocol hardware that satisfies fragmented FCC and CE marking requirements.
- New Construction:Builder mandates in North America standardize platform choices before homeowner occupancy, locking in ecosystem decisions at the electrical rough-in phase.
- Smart Home Integration:Whole-system design by automation specialists bundles switch procurement with hub and sensor selection.
- DIY:Consumer self-installation via retail channels prioritizes Wi-Fi native architectures and app-guided commissioning.
Retrofit holds the dominant position, while Smart Home Integration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing for in-wall smart switches concentrates in China, Germany, and the United States, with final assembly and certification distributed across these three markets to satisfy divergent radio equipment regulations.
United States
Retrofit demand in aging urban housing across Chicago, New York, and Los Angeles drives replacement cycles for legacy toggle switches. The FCC governs 2.4GHz and 5GHz radio emissions under Part 15 rules, mandating modular approval for Wi-Fi and Zigbee radios. Silicon Valley and Austin clusters host firmware development centers where vendors architect cloud-native commissioning flows for DIY residential channels.
Germany
Federal building codes incorporate EU Ecodesign standby power limits earliest, forcing vendors to lead sub-0.5W idle consumption rollouts here before broader European distribution. The EU F-Gas Regulation and CE marking under the Radio Equipment Directive create multi-layer compliance requirements. Munich and Stuttgart industrial corridors concentrate specification-grade channel partnerships with electrical contractors bundling automation system design.
China
MIIT enforces GB standard compliance for wireless transmitters, creating a parallel certification track that extends product launch timelines. Retrofit volumes accelerate in Shanghai, Beijing, and Shenzhen aging residential stock. The Pearl River Delta manufacturing cluster supplies relay components and capacitive glass panels to vendors serving both domestic and export markets.
India
Smart city mandates in Delhi, Mumbai, and Bangalore create institutional demand for hub-agnostic switch architectures in government building automation. BIS certification requirements for electrical safety and EMC compliance shape product development roadmaps. Hyderabad and Pune emerging as firmware development hubs serving cost-optimized residential segments.
United Kingdom
Post-Brexit regulatory divergence from EU CE marking creates dual certification burdens for vendors serving both markets. London and Southeast England concentrate hospitality sector demand for glass-surface touch switches in hotel renovation cycles. The Midlands manufacturing base supplies electromechanical components to European switch assemblers.
In-Wall Smart Switch Market Competitive Landscape
Electrical heritage conglomerates and consumer electronics specialists split the market across specification-grade and retail channels. The vendor base spans three tiers: legacy electrical manufacturers with installer channel density, Wi-Fi native consumer electronics brands, and automation-focused specialists with proprietary wireless protocols. Consolidation pressures intensify as cloud subscription revenue models favor scale players with sustained R&D budgets.
Within the electrical heritage tier, Legrand and Lutron Electronics exemplify divergent strategic positioning. Legrand leverages European channel density for recurring service revenue across multi-unit residential deployments. Lutron Electronics anchors premium positioning through proprietary wireless technology that commands installer specification loyalty. TP-Link represents the consumer electronics vector, competing on Wi-Fi native architectures that eliminate hub dependencies for cost-sensitive residential buyers.
| Leading Market Players |
|---|
| Legrand |
| Lutron Electronics |
| Signify |
| Leviton |
| GE Lighting |
| TP-Link |
| Gira |
| BTicino |
| Igoto Electric |
| Others |
Pricing and Supply Chain Analysis
Relay component manufacturing in China's Pearl River Delta feeds directly into margin compression dynamics for cost-sensitive residential SKUs, while capacitive glass panel sourcing from German industrial corridors sustains premium tier profitability. Copper price volatility in electromechanical switching elements propagates through vendor portfolios, forcing pricing discipline that separates specification-grade channels from retail self-installation markets.
Pricing Analysis
The EU F-Gas Regulation and Ecodesign standards dictate the pricing tier structure by imposing sub-0.5W standby power thresholds that stratify certification-grade premiums from uncertified economy offerings. Price differentiation rests on CE marking compliance and multi-protocol hardware pre-certification, with German federal building codes accelerating tier separation. Cost compression in Wi-Fi native residential SKUs is intensifying because router-dependency failures in concrete-walled European housing erode perceived value. Electrical contractors bundling automation system design exhibit lowest price sensitivity, while DIY retail channels face acute margin pressure from hub-agnostic competitors.
Supply Chain Analysis
Foxconn, Jabil, and Flex hold contract-manufacturing capacity for wireless radio modules and relay assemblies serving the in-wall smart switch industry. Component sourcing draws from China's Pearl River Delta for capacitive glass and electromechanical elements, Germany's industrial corridors for specification-grade certification testing, and Taiwan for IEEE 802.15.4 radio chipsets. Single-source vulnerability concentrates in MIIT GB standard compliance testing for Chinese market access. Distribution runs through electrical contractor specification channels in North American new construction and European multi-unit residential, with retail DIY segments served by direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where installer channel relationships and regulatory certification entrenchment create switching costs that protect incumbent positions from pure-play technology disruptors.
For Market Incumbents: Harden specification-grade channel control by deepening backward integration into capacitive glass panel production and securing exclusive electrical contractor partnerships in German multi-unit residential corridors. Neutral-wire flexibility in retrofit hardware architectures defends against emerging hub-agnostic entrants targeting aging urban housing stock. Certification investment in Matter protocol convergence reduces SKU complexity while raising compliance barriers for smaller competitors.
For New Entrants and Emerging Players: Mid-market commercial buildings in India's smart city corridors represent the most penetrable entry point, where government automation mandates create procurement authority without entrenched incumbent relationships. Hospitality renovation cycles in Southeast Asian urban centers offer second-mover advantages as glass-surface touch switch specifications outpace local supply capacity. A direct-to-installer go-to-market angle bypasses retail margin compression while building specification track records.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive relay component supply and established CE marking expertise across the analysis window. Acquisition targets should demonstrate firmware development capabilities that support recurring cloud connectivity revenue streams rather than pure hardware transaction models. The signal to watch is Matter protocol adoption velocity in North American builder mandates, which will determine which wireless technology architectures retain long-term viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Thread and Wi-Fi unification under CSA standards reduces SKU fragmentation for multi-ecosystem households. |
| Cloud Subscription Monetization | Firmware update revenue streams reconfigure lifetime value capture from one-time hardware placements. |
| Capacitive Glass Integration | Solid-state switching architectures meet EU Ecodesign standby power limits while eliminating mechanical wear points. |
| Electrical Contractor Channel Consolidation | Procurement bundling with home automation system design displaces retail self-installation in whole-home projects. |
| Multi-Protocol Hardware Pre-Certification | Parallel FCC, CE marking, and MIIT GB compliance compresses product launch timelines for fragmented regulatory environments. |
Research Methodology
A spread of perspectives from electrical contractor specification managers, smart home automation integrators, procurement leads at multi-unit residential developers, and regulatory compliance officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC equipment authorization databases, EU Radio Equipment Directive guidance documents, MIIT GB standard filings, and customs trade data for relay component flows. Bottom-up unit shipment estimates triangulated against top-down construction spending projections across the analysis window.
Demand-supply balance modeling anchored volume forecasts to retrofit penetration rates in aging German, United States, and Chinese urban housing stock, cross-referenced with new construction smart home mandate adoption curves. Segmentation dimensions included product type (touch, dimmer, toggle, remote-controlled), technology protocol (Wi-Fi, Zigbee, Z-Wave, Bluetooth), end user vertical (residential, hospitality, commercial, industrial), and installation context (retrofit, new construction, smart home integration, DIY). CAGRs derived from logistic diffusion curves fitted to historical connected device adoption patterns, with cross-checks against electrical contractor capacity expansion announcements and cloud service provider infrastructure spending disclosures.
Practitioners should monitor cybersecurity labeling requirement evolution and copper relay component price indices for early signals of forecast revision triggers. Regulatory fragmentation timelines for Matter protocol harmonization and installer skill gap remediation rates represent additional uncertainty factors. Quarterly review of builder mandate standardization announcements and hospitality chain glass-surface specification adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
India Switchgear Market
Switches
Disconnect Switch Market
Switches
Fixed Switch Cabinet Market
Switches
5G Solid State Switches Market
Switches
Smart Circuit Breaker Market
Switches
KVM Switch Market
Switches
DC Circuit Breaker Market
Switches
Level Switches Market
Switches
China Switchgear Market
Switches
Asia Pacific Safety Switches Market
Switches
Temperature and Pressure Switches Market
Switches
Matrix Switches Market
Switches
UAE Switchgear Market
Switches
Canada Switch Gear Market
Switches
Pressure Switch Market
Switches
Global Light Control Switches Market