
 Global Smart Switch Panel Market | 2026-2036
Global Smart Switch Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Switch Panel Market Outlook
Polycarbonate is realigning cost structures across smart switch panel manufacturing as it displaces legacy ABS housings in premium product lines. Schneider Electric leverages captive resin sourcing to sustain margin stability across European distribution channels. Legrand anchors its position through specialized glass-fronted touch switch variants aimed at luxury residential projects. ABB competes on industrial-grade Zigbee-enabled panels with extended temperature tolerances for factory automation environments.
A smart switch panel is an electronically actuated wall-mounted control interface that replaces conventional mechanical switches, typically incorporating capacitive touch sensors, relay modules rated for 10-15 amp loads, and wireless communication chipsets for remote actuation. Its primary purpose is to enable centralized or automated control of lighting, HVAC, and outlet circuits within building management systems. Touch switch variants command the highest margin pools in residential channels where aesthetic integration drives replacement cycles, while Wi-Fi connectivity dominates volume shipments due to router ubiquity and minimal hub requirements. Smart lighting applications represent the fastest-expanding demand segment as building codes in multiple jurisdictions mandate daylight-responsive controls.
The EU F-Gas Regulation and CE marking requirements shape product compliance pathways for panels with integrated environmental sensors, while the U.S. FCC governs wireless emission standards for Wi-Fi and Z-Wave radio modules. China's GB standards for electrical accessories impose additional testing protocols on imported smart switch assemblies. Stakeholders must weigh interoperability certification costs against the revenue premium of multi-protocol hardware that bridges fragmented smart home ecosystems.
Market Dynamics
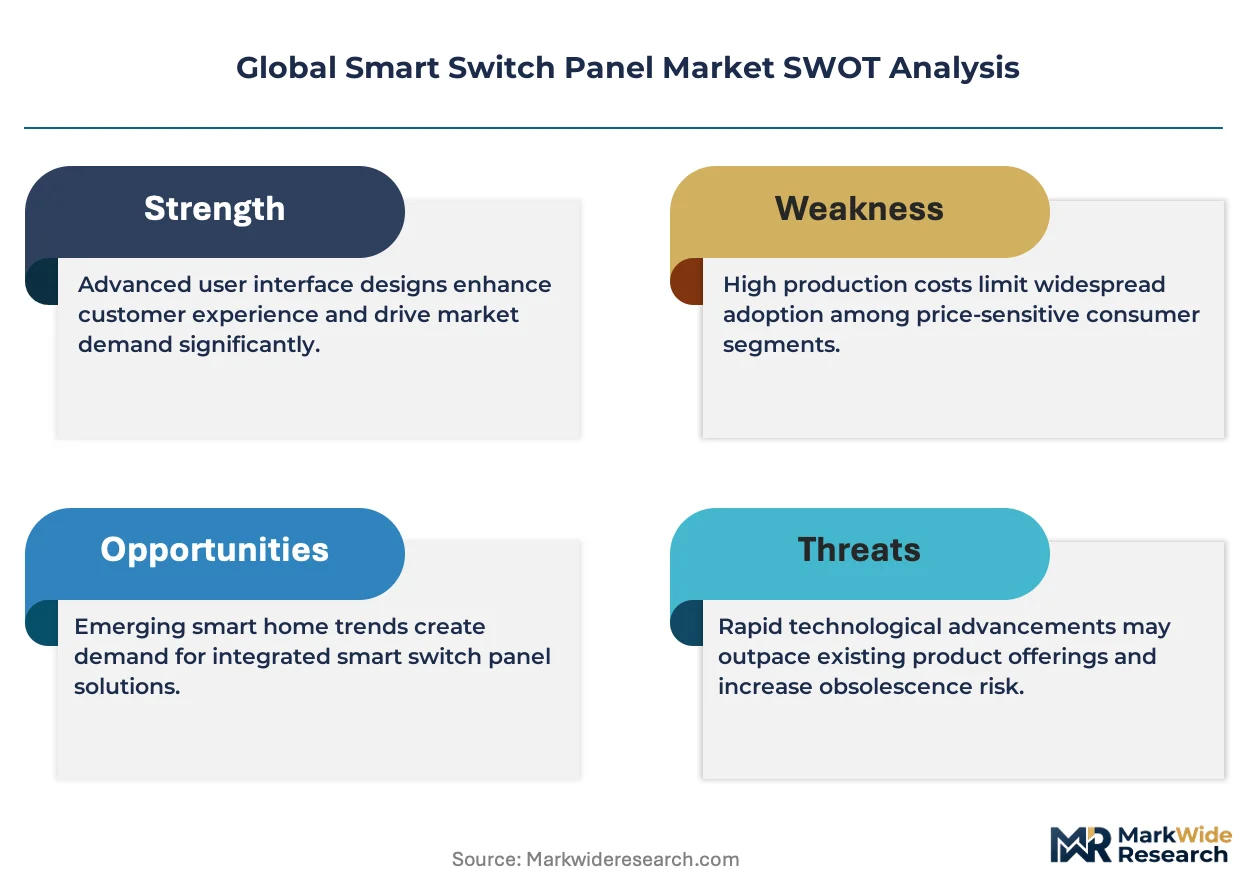
Polycarbonate resin sourcing concentration is compressing margin structures across smart switch panel manufacturing, forcing producers to secure captive supply chains or absorb volatile petrochemical feedstock costs.
Growth Catalysts
- EU Green Deal building mandates:The EU Green Deal's efficiency requirements are accelerating electrical infrastructure retrofits across German and French residential stocks, pulling demand for connected control interfaces.
- Zigbee protocol proliferation:Industrial automation buyers in China are specifying Zigbee-enabled panels for factory lighting networks, expanding the addressable market beyond residential channels.
- Daylight-responsive code adoption:Building codes in California and New York now mandate automated lighting controls, creating regulatory pull for sensor-integrated switch panels in new construction.
Market Restraints
- ABS resin dependency:Legacy housing production still relies on acrylonitrile butadiene styrene, exposing mid-tier manufacturers to styrene monomer price volatility from concentrated Asian petrochemical suppliers.
- CE marking friction:The EU F-Gas Regulation adds testing layers for panels with integrated environmental sensors, extending compliance timelines and freezing smaller vendors from European distribution.
- Mechanical switch substitution:Basic rocker switches retain cost advantage in price-sensitive Indian and Southeast Asian housing markets, capping premium smart panel penetration rates.
Strategic Opportunities
- India housing electrification:India's Smart Cities Mission and rural electrification programs are creating first-time demand for connected home infrastructure in tier-2 and tier-3 urban centers.
- Matter protocol convergence:The Matter interoperability standard is collapsing ecosystem fragmentation, enabling single-hardware SKUs to bridge Apple, Google, and Amazon smart home platforms.
- Glass-fronted luxury segment:Specialized touch interfaces with tempered glass surfaces are commanding design premiums in Dubai and Singapore high-rise residential developments.
Industry Challenges
- RF engineering talent scarcity:Wi-Fi and Z-Wave module integration requires specialized radio-frequency expertise that competes with telecommunications and automotive sectors for limited engineering pools.
- Legacy electrical contractor training:Residential retrofit installation depends on electrician familiarity with low-voltage wiring and hub configuration, creating bottlenecks in markets with aging trade workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Switch Panel Market |
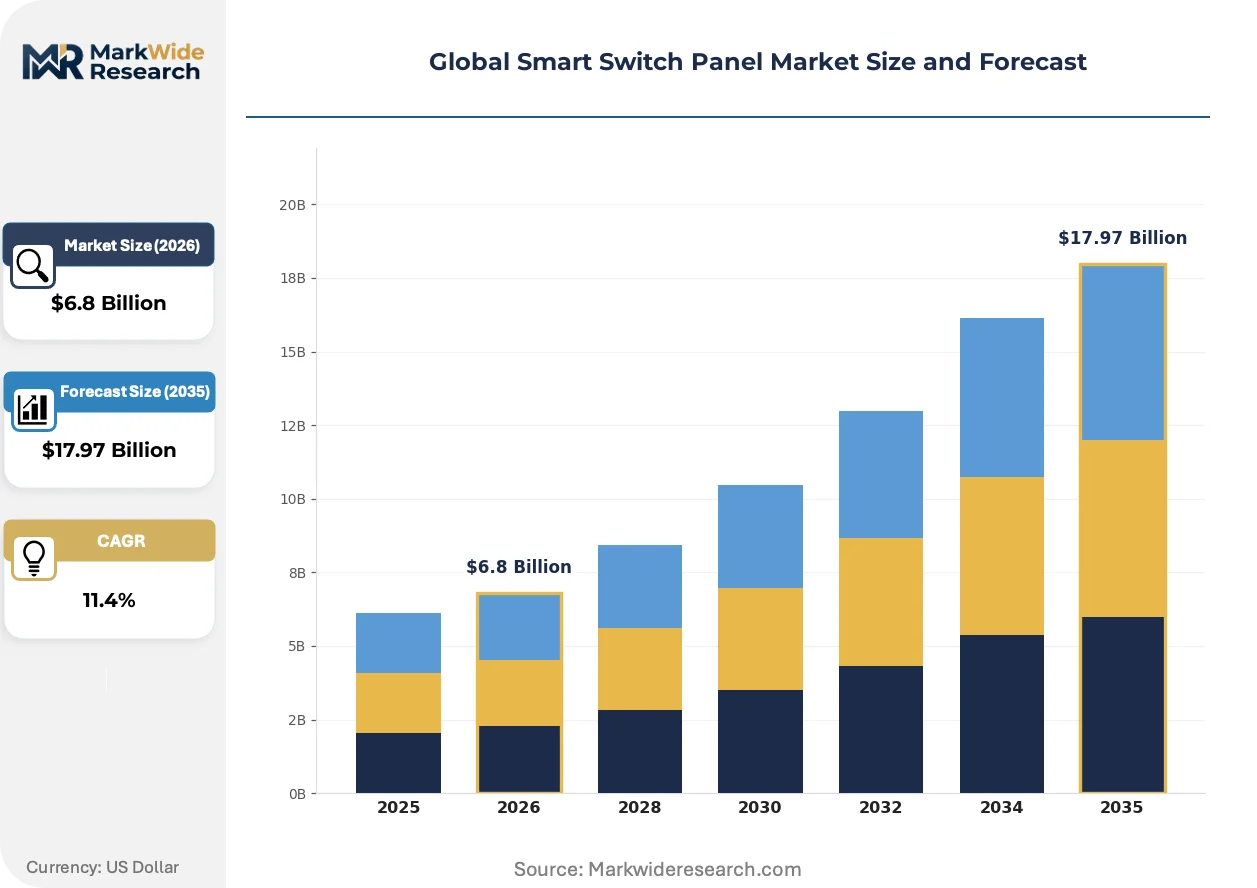
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Switches, Touch Switches, Remote-Controlled Switches, Smart Plugs Connectivity: Wi-Fi, Zigbee, Z-Wave, Bluetooth Application: Residential, Commercial, Industrial, Smart Lighting End User: Homeowners, Property Managers, Enterprises, Contractors |
| Companies Covered | Siemens, Leviton Manufacturing, Schneider Electric, Eaton Corporation, Lutron Electronics, Legrand, ABB, TP-Link Technologies, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Switch Panel Market Strategic Shifts
Smart switch panel architecture is fragmenting into interoperable subsystems, with hardware design separating from software platform control and opening entry points for specialized component suppliers.
Capacitive touch sensor modules are modularizing around standardized relay footprints, allowing manufacturers to swap glass, plastic, or metal front panels without redesigning base electronics. Boutique hotel chains in Milan and Tokyo are piloting rapid-swap faceplate programs that refresh room aesthetics without electrical contractor visits. This modularizing force is compressing product development cycles and eroding the tooling cost barrier for regional customizers.
The EU F-Gas Regulation is tightening refrigerant and sensor compliance for climate-integrated switch panels, forcing redesigns of HVAC-linked control units. Manufacturers serving German and French markets are segregating production lines to isolate F-Gas-affected SKUs from standard touch switches. Panels with embedded CO2 or temperature sensors now carry distinct certification pathways that add four to six months to product launch timelines.
Electrical contractors are unbundling hardware procurement from installation services, with buyers in Texas and Florida increasingly sourcing panels through Amazon Business and direct-to-consumer channels before hiring independent installers. This disintermediation is compressing traditional distributor margins and forcing Legrand and Schneider Electric to maintain price parity across conflicting channel structures. The shift is most pronounced in residential retrofit markets where homeowner research precedes professional engagement.
Global Smart Switch Panel Market Segmentation
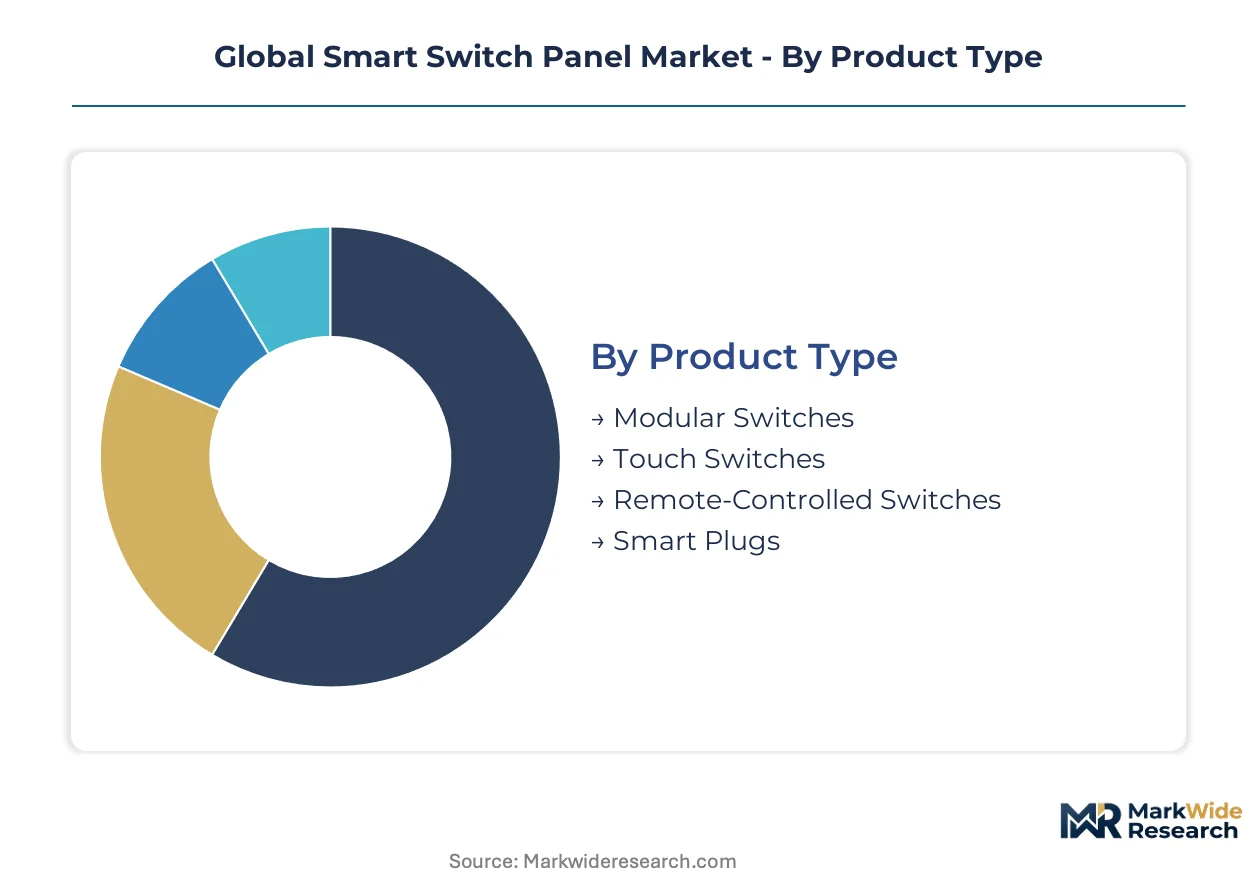
Segmentation in smart switch panels reveals divergent buyer priorities across residential retrofits, industrial automation, and commercial new construction. Product architecture, wireless protocol selection, and installation channel each create distinct margin profiles and competitive dynamics.
Product Type:
Buyers trade off aesthetic integration against functional complexity, with surface material and actuation mechanism driving price tier placement.
- Touch Switches:Capacitive glass or polycarbonate front panels enable gesture control and dimming without mechanical wear. Demand clusters in German and French luxury residential retrofits where EU Green Deal efficiency mandates accelerate electrical infrastructure replacement cycles.
- Modular Switches:Grid-based systems allow customizable gang configurations and interchangeable faceplates. Indian and Southeast Asian housing markets favor these for cost flexibility in first-time electrification projects, though mechanical actuation limits smart feature integration.
- Remote-Controlled Switches:Handheld or wall-mounted RF transmitters pair with relay receivers for retrofits without neutral wire access. Popular in older US housing stock where rewiring costs deter full smart home upgrades.
- Smart Plugs:Plug-in relay modules convert standard outlets into app-controlled circuits without wall modification. Volume concentrates in Chinese e-commerce channels as entry-level smart home components.
Modular switches lead on scale; touch switches lead on momentum.
Connectivity:
Protocol selection locks buyers into ecosystem compatibility and determines hub infrastructure requirements.
- Wi-Fi:Direct router communication eliminates hub costs and leverages ubiquitous residential networking hardware. California and New York building codes mandating daylight-responsive controls pull Wi-Fi panels into new commercial construction.
- Zigbee:Mesh networking extends range across large facilities with minimal power draw. Chinese factory automation buyers specify these for industrial lighting networks requiring extended temperature tolerances.
- Z-Wave:Sub-GHz frequency penetration through walls suits multi-story residential and hospitality deployments. FCC certification requirements add compliance friction for non-US vendors.
- Bluetooth:Low-energy beacon integration enables proximity-based automation without internet dependency. Boutique hotel pilots in Tokyo and Milan use Bluetooth for rapid-swap faceplate programs.
Wi-Fi dominates shipment volume; Zigbee climbs fastest in industrial channels.
Application:
Use case determines sensor integration depth and regulatory compliance burden.
- Smart Lighting:Daylight sensors and occupancy detectors automate illumination based on environmental conditions. Fastest-expanding demand segment as jurisdictions mandate responsive controls.
- Residential:Single-family and multi-family housing retrofits prioritize app convenience and voice assistant compatibility. German housing stock electrification drives replacement demand.
- Commercial:Office and retail installations require centralized building management integration and energy metering. Legrand and Schneider Electric compete on BACnet and Modbus protocol support.
- Industrial:Factory floor deployments demand IP ratings, vibration resistance, and extended temperature operation. ABB anchors this segment with hardened Zigbee-enabled assemblies.
Residential anchors volume; smart lighting gains share fastest.
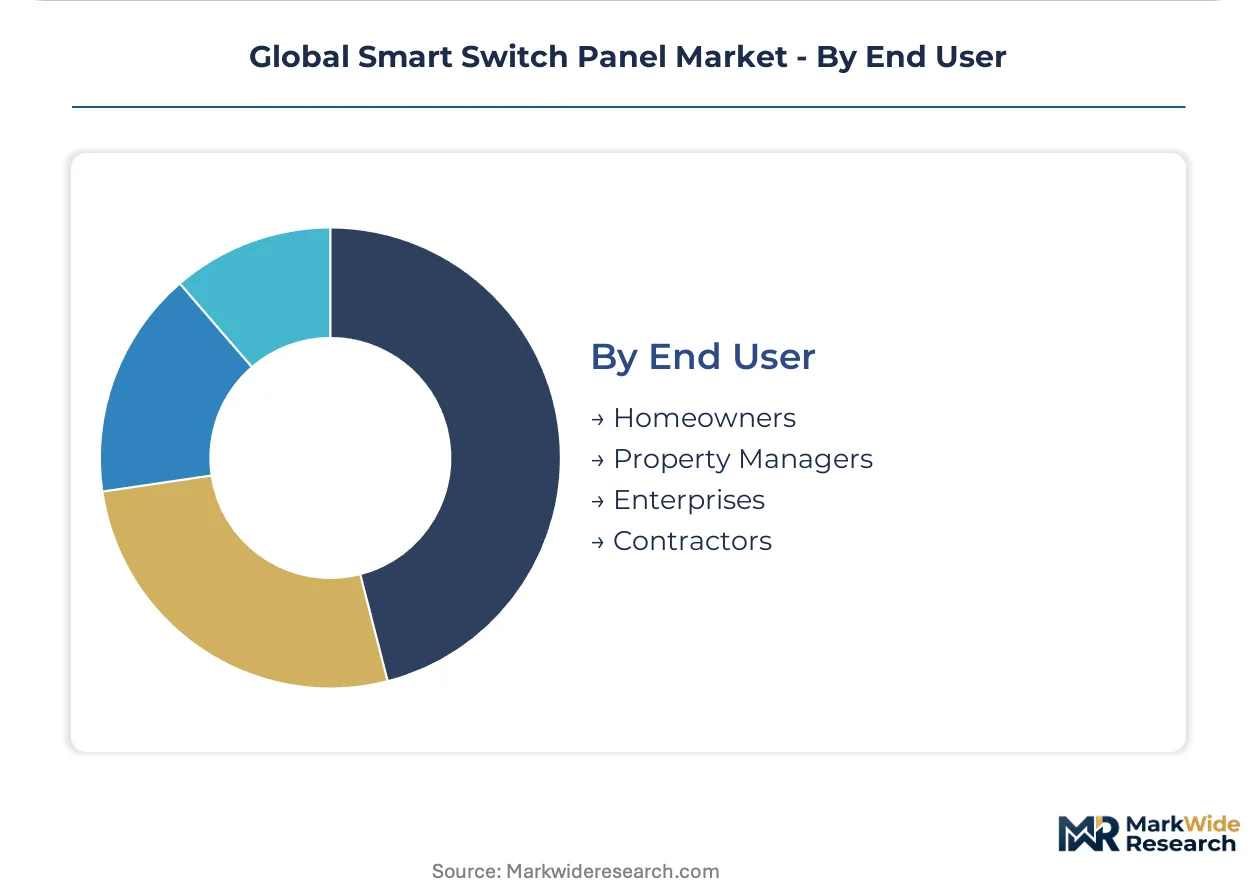
End User:
Procurement authority and technical sophistication shape channel strategy and support requirements.
- Homeowners:Direct-to-consumer research precedes professional installation, compressing traditional distributor margins. Texas and Florida buyers increasingly source through Amazon Business before hiring independent electricians.
- Contractors:Electrical trade professionals specify panels based on familiarity with low-voltage wiring and hub configuration. Aging workforces in North America create installation bottlenecks.
- Property Managers:Multi-unit residential operators prioritize remote diagnostics and bulk fleet management. Dubai and Singapore high-rise developments specify glass-fronted luxury variants.
- Enterprises:Corporate facility teams demand centralized energy dashboards and cybersecurity certification. EU F-Gas Regulation compliance adds testing layers for climate-integrated panels.
Contractors handle the most installation volume; property managers drive premium specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German housing stock electrification anchors smart switch panel demand across the European retrofit channel, while Chinese factory automation and US residential construction codes reshape procurement patterns in their respective markets.
United States
California and New York building codes now mandate daylight-responsive lighting controls in new commercial construction, pulling Wi-Fi-enabled panels into office and retail projects. The FCC governs wireless emission standards for Z-Wave and Zigbee modules, adding certification friction for imported assemblies. Dallas-Fort Worth and Houston electrical contractors increasingly source panels through direct-to-consumer channels before installation, compressing traditional distributor margins.
Germany
EU Green Deal efficiency mandates accelerate electrical infrastructure replacement across aging residential housing stocks in Berlin and Munich. The F-Gas Regulation imposes additional testing layers on panels with integrated CO2 or temperature sensors, extending compliance timelines by four to six months. Stuttgart and Frankfurt luxury developments specify glass-fronted touch variants where aesthetic integration drives premium procurement.
China
Zigbee-enabled industrial panels gain specification from factory automation buyers in Shenzhen and Dongguan for extended temperature tolerance requirements. GB standards for electrical accessories impose additional testing protocols on imported smart switch assemblies. Shanghai and Beijing smart home penetration deepens through e-commerce channels where TP-Link Technologies and local vendors compete on router-integrated Wi-Fi solutions.
India
Smart Cities Mission and rural electrification programs create first-time demand for connected home infrastructure in tier-2 urban centers like Pune and Ahmedabad. The Bureau of Indian Standards (BIS) certification requirements shape import pathways for foreign manufacturers. Bangalore and Hyderabad residential construction favors modular switch configurations for cost flexibility in first-time electrification projects.
United Arab Emirates
Dubai and Abu Dhabi high-rise residential developments specify tempered glass-fronted luxury variants commanding design premiums from property managers. MOHAP and local building codes govern electrical accessory safety standards for climate-integrated control units. Sharjah hospitality projects pilot rapid-swap faceplate programs that refresh room aesthetics without electrical contractor visits.
Global Smart Switch Panel Market Competitive Environment
Global majors compete with regional champions across protocol certification and channel access, producing a tiered structure where scale-driven conglomerates anchor premium segments and specialized fabricators capture retrofit niches. Three archetypes dominate: diversified electrical conglomerates with captive resin sourcing, connectivity-focused technology vendors leveraging router ubiquity, and boutique specialists in aesthetic-integrated touch interfaces. Competitive moves concentrate on M&A for sensor technology capabilities and strategic partnerships with building management system providers.
Among diversified electrical conglomerates, Schneider Electric, Legrand, and ABB occupy positions spanning residential, commercial, and industrial channels. Schneider Electric exemplifies the captive supply chain archetype through integrated resin sourcing that sustains margin stability. Legrand represents the aesthetic-specialist position with glass-fronted variants targeting luxury residential specifications. ABB anchors the industrial-grade segment with hardened assemblies for factory automation environments requiring extended temperature tolerances and IP ratings.
| Leading Market Players |
|---|
| Siemens |
| Leviton Manufacturing |
| Schneider Electric |
| Eaton Corporation |
| Lutron Electronics |
| Legrand |
| ABB |
| TP-Link Technologies |
| Panasonic |
| Others |
Value Chain & Pricing Dynamics
Polycarbonate resin contracts from Asian petrochemical suppliers cascade through three distinct pricing tiers, with captive sourcing agreements insulating Schneider Electric from volatility that compresses margins at mid-tier competitors lacking backward integration into resin production.
Pricing Analysis
Input-cost pass-through from styrene monomer and polycarbonate feedstocks stratifies pricing across premium, standard, and economy levels. Certification grade under EU F-Gas Regulation and CE marking requirements separates German and French premium touch panels from Indian modular variants. Cost compression in mid-tier ABS-dependent products is intensifying because concentrated Asian petrochemical supply exposes non-integrated manufacturers to spot price swings. Electrical contractors in Texas and Florida exhibit highest price sensitivity through Amazon Business sourcing, while Dubai property managers show least sensitivity specifying glass-fronted luxury variants.
Supply Chain Analysis
RF engineering talent shortages in Shenzhen and Dongguan constrain Zigbee module assembly capacity for industrial-grade panels. Manufacturing concentrates in China, Germany, and Vietnam, with production drawing from polycarbonate resin, relay modules, and capacitive sensor components. Single-source vulnerability in Taiwanese wireless chipset supply creates chokepoint exposure for Z-Wave and Zigbee protocol variants. Distribution runs through electrical wholesalers in European retrofit markets and direct-to-consumer e-commerce in North American residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's building efficiency mandates compound regulatory demand pull, with F-Gas Regulation compliance timelines creating captive market windows for prepared suppliers.
For Market Incumbents: Anchor market position through captive polycarbonate resin sourcing that sustains margin stability against petrochemical volatility. Defend against disintermediation by maintaining price parity across Amazon Business and traditional electrical wholesaler channels. Prioritize F-Gas Regulation pre-certification for sensor-integrated SKUs to freeze smaller competitors from German and French distribution. For New Entrants and Emerging Players: Electrical contractor training partnerships in Texas and Florida offer lowest-friction channel entry for residential retrofit specialization. Target India's tier-2 urban centers through modular switch configurations aligned with Smart Cities Mission electrification timelines. Pursue rapid-swap faceplate programs for Sharjah hospitality projects as design-forward differentiation. For Investors and Strategic Acquirers: Consolidation pressure builds where RF engineering capability scarcity intersects with Matter protocol certification requirements. Long-term viability favors acquirers of Zigbee module specialists with industrial temperature tolerance IP. Watch Matter interoperability adoption rates as inflection signal for ecosystem consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Resin Sourcing Agreement | Schneider Electric's integrated supply insulates margin from Asian petrochemical volatility. |
| Matter Protocol Certification | Single-hardware SKUs bridge Apple, Google, and Amazon smart home platform fragmentation. |
| Glass-Fronted Luxury Tier Launch | Legrand commands design premiums in Dubai and Singapore high-rise residential developments. |
| Industrial Zigbee Module Expansion | ABB extends temperature-tolerant assemblies for Shenzhen factory automation specifications. |
| Direct-to-Consumer Channel Entry | Amazon Business sourcing in Texas and Florida compresses traditional electrical distributor margins. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with electrical contractor trade associations, smart home platform engineers, property management procurement directors, and polycarbonate resin procurement leads informed demand-side dynamics. Secondary sources included FCC equipment authorization databases, EU F-Gas Regulation compliance filings, Chinese GB standards documentation, and SEC 10-K disclosures from listed electrical conglomerates. Bottom-up shipment estimates triangulated against top-down construction spend allocations.
Granularity-level modeling addressed product type, connectivity protocol, application segment, and end-user archetype across the analysis window. Wi-Fi versus Zigbee versus Z-Wave protocol splits derived from FCC authorization trends and industrial buyer specification surveys. Smart lighting application growth calibrated against California and New York building code adoption timelines. CAGRs emerged from logistic diffusion curves fitted to replacement cycle data and new construction permit flows.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Matter protocol adoption velocity, EU F-Gas Regulation enforcement stringency, and Indian BIS certification pathway duration. Forecasts reflect assumptions about regulatory implementation timelines, petrochemical feedstock stability, and electrical contractor workforce demographics. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Smart Plugs and Switches Market
Switches
Electronic Shift-By-Wire Selector Modules Market
Switches
Miniature-Circuit Breaker Market
Switches
DC Circuit Breaker Market
Switches
Reed Switch Market
Switches
Fusible Switches Market
Switches
Australia Switchgear Market
Switches
India Switchgear Market
Switches
Matrix Switches Market
Switches
United States Switchgear Market
Switches
Haptic Feedback Switch and Button Platforms Market
Switches
5G Electromechanical RF Switch Market
Switches
Drive Mode Selector Switch and Controller Systems Market
Switches
Europe Low Voltage Switchgear Market
Switches
North America Low Voltage Switchgear Market
Switches
Italy Reed Sensors Switches Market