
 Asia-Pacific Hair Conditioner Market | 2026-2036
Asia-Pacific Hair Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hair Conditioner Market Outlook
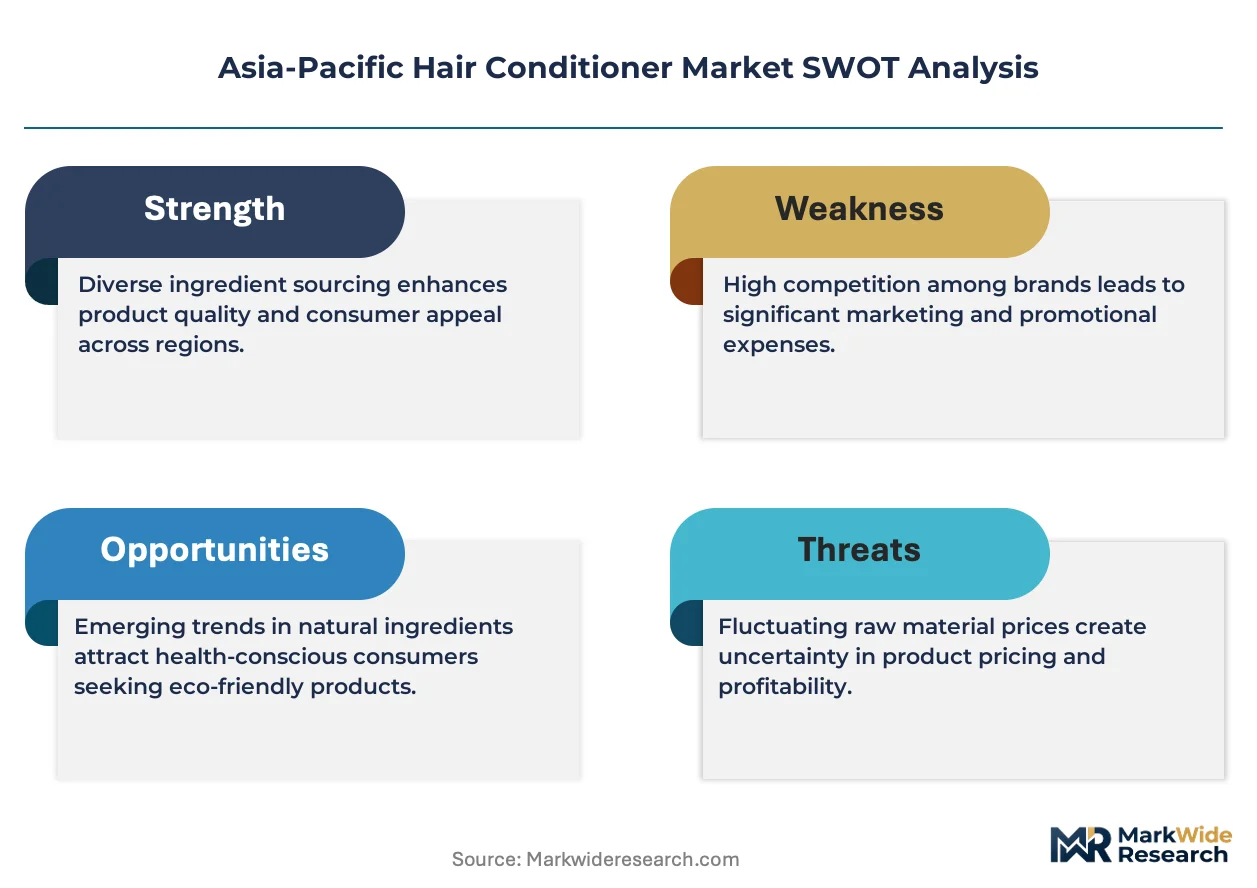
Salon professional demand is restructuring the Asia-Pacific hair conditioner landscape as consumers shift from basic rinse-out products to treatment-grade home care. Procter & Gamble Co. leverages its pan-Asian distribution infrastructure to sustain volume leadership in mass-market rinse-out segments. L'Oreal S.A. anchors premium positioning through professional salon channels and specialized treatment formulations. Unilever competes aggressively on price-accessible cream formats across tier-two Indian and Indonesian cities.
Asia-Pacific hair conditioner encompasses cationic surfactant-based formulations designed to deposit conditioning agents onto keratin surfaces, typically containing fatty alcohols, silicones, and hydrolyzed proteins at pH levels between 3.5 and 5.5 to seal cuticle layers and reduce combing friction. Rinse-out conditioners remain the volume backbone, though treatment and deep conditioner segments capture disproportionate margin pools as consumers extend salon rituals into home routines. Leave-in formats gain fastest traction among men and children end users, where convenience-driven application patterns favor spray and gel formulations over traditional cream bases.
Japan's Ministry of Health, Labour and Welfare through PMDA oversight and South Korea's MFDS enforce strict cosmetic ingredient safety thresholds that elevate R&D compliance costs for new market entrants. India's BIS labeling requirements and ASEAN cosmetic directive harmonization create divergent registration pathways that fragment go-to-market timelines across the region. Stakeholders must monitor regulatory divergence between national pharmacopoeia standards and emerging clean-beauty certification schemes to optimize portfolio allocation and manufacturing location decisions.
Market Dynamics
Salon-grade conditioning rituals are migrating into domestic routines across Asia-Pacific, compressing the traditional boundary between professional treatment and mass-market rinse-out products. This convergence is forcing reformulation pipelines to prioritize active ingredient stability at consumer-accessible price points.
Growth Catalysts
- K-Beauty Innovation Cycles:South Korean MFDS fast-track approval pathways accelerate new ingredient commercialization, compressing time-to-market for novel conditioning actives.
- ASEAN Harmonization:The ASEAN Cosmetic Directive's mutual recognition protocols reduce registration duplication costs across Indonesia, Thailand, and Vietnam.
- Professional Channel Expansion:Salon professionals in India and Vietnam are prescribing take-home treatment masks, extending service revenue into recurring product purchases.
Market Restraints
- Silicone Input Volatility:Cyclomethicone and dimethicone supply concentrates in Chinese petrochemical clusters, exposing margins to energy-price shocks.
- BIS Labeling Friction:India's Bureau of Indian Standards mandates ingredient percentage disclosure that conflicts with proprietary formulation protections.
- Water Scarcity Premiums:Manufacturing in drought-prone Indian states faces escalating municipal water tariffs that compress plant-level economics.
Strategic Opportunities
- Vietnam's Underpenetrated South:Ho Chi Minh City and Mekong Delta provinces show conditioner usage gaps versus Hanoi, offering first-mover positioning.
- Clean-Beauty Certification Convergence:EWG Verified and COSMOS standards are merging audit protocols, reducing multi-certification costs for export-oriented Thai manufacturers.
- Men's Leave-In Formats:Spray conditioners for male grooming routines remain underserved across Philippines and Indonesia urban centers.
Industry Challenges
- Formulation Chemist Scarcity:Cationic surfactant expertise concentrates in legacy Japanese and South Korean R&D centers, constraining ASEAN local product development.
- Legacy ERP Integration:Indian and Indonesian mid-tier manufacturers struggle to embed batch-level traceability required by MFDS and PMDA export protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hair Conditioner Market |
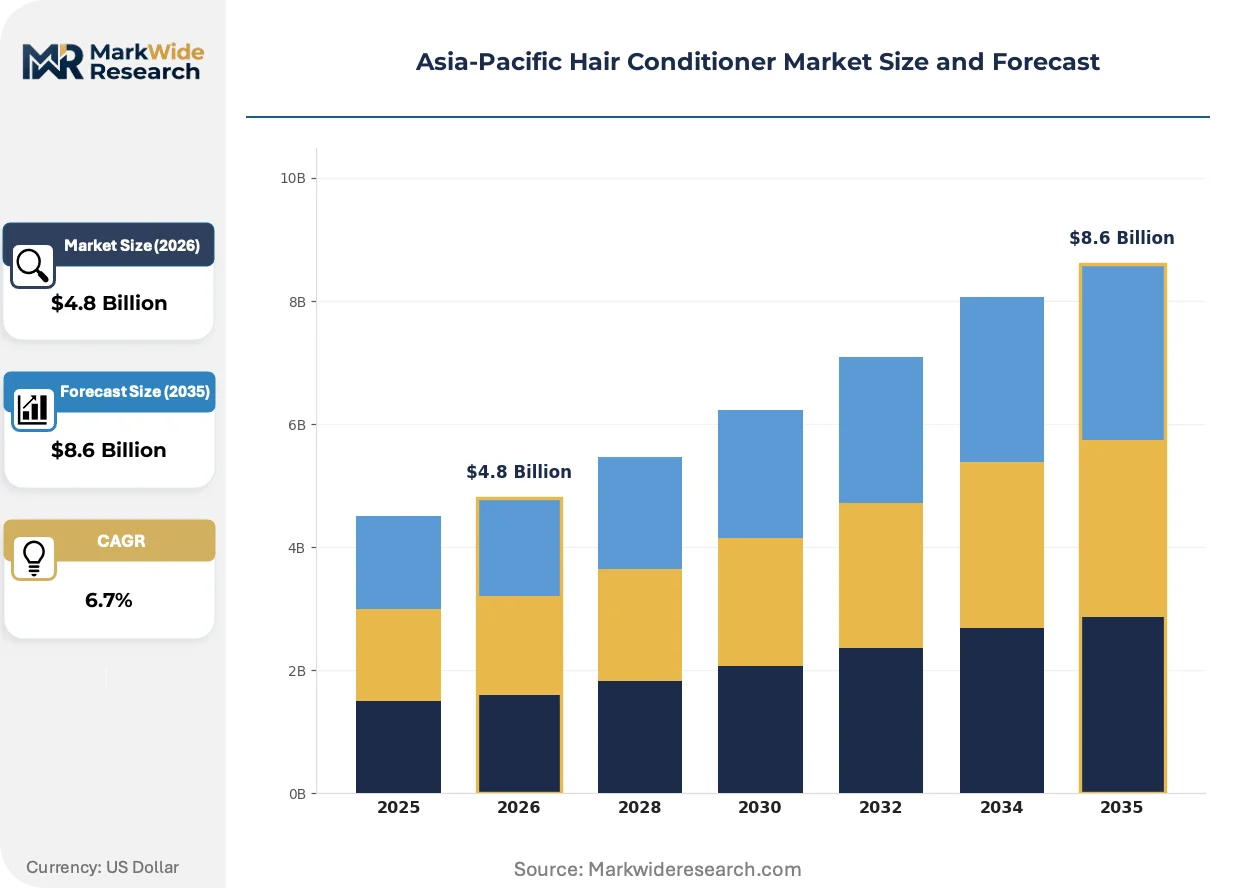
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leave-In, Rinse-Out, Deep Conditioner, Treatment Formulation: Cream, Gel, Liquid, Spray End User: Women, Men, Children, Salon Professionals Distribution Channel: Online, Hypermarkets, Specialty Stores, Beauty Salons |
| Companies Covered | Procter & Gamble Co., L'Oreal S.A., Unilever, Kao Corporation, Shiseido Company, Amorepacific, Johnson & Johnson Consumer Inc., Mandom Corporation, Amway, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hair Conditioner Market Strategic Shifts
Biotechnology-derived conditioning actives and waterless formats are restructuring competitive advantage away from silicone-centric legacy platforms. Regulatory disclosure mandates and professional-channel emulation are simultaneously elevating transparency expectations and performance thresholds.
Fermented rice water and postbiotic lysates are overtaking traditional quaternary ammonium compounds as the dominant conditioning technology in premium South Korean and Japanese formulations. Urban millennials in Seoul and Tokyo are adopting these biotech actives at three times the rate of silicone alternatives. The shift is overtaking established supply relationships with legacy petrochemical suppliers and forcing raw material procurement toward fermentation biotechnology partnerships.
India's BIS cosmetics standards are mandating full fragrance allergen disclosure on primary packaging, effective for all imports and domestic production. This regulatory friction is accelerating label redesign cycles and compressing SKU proliferation strategies for multinational portfolios. Mass-market rinse-out segments face the steepest compliance cost escalation, pushing portfolio rationalization toward treatment-grade concentrates with simpler ingredient decks.
Subscription-based replenishment models are capturing conditioner buyers in Australia's metropolitan corridors and New Zealand's urban centers. Traditional supermarket and pharmacy channels are losing traffic to direct-to-consumer platforms that bundle personalized scalp diagnostics with auto-shipped formulations. The behavior shift concentrates among time-constrained professionals in Sydney, Melbourne, and Auckland who prioritize convenience over in-store sampling.
Asia-Pacific Hair Conditioner Market Segmentation
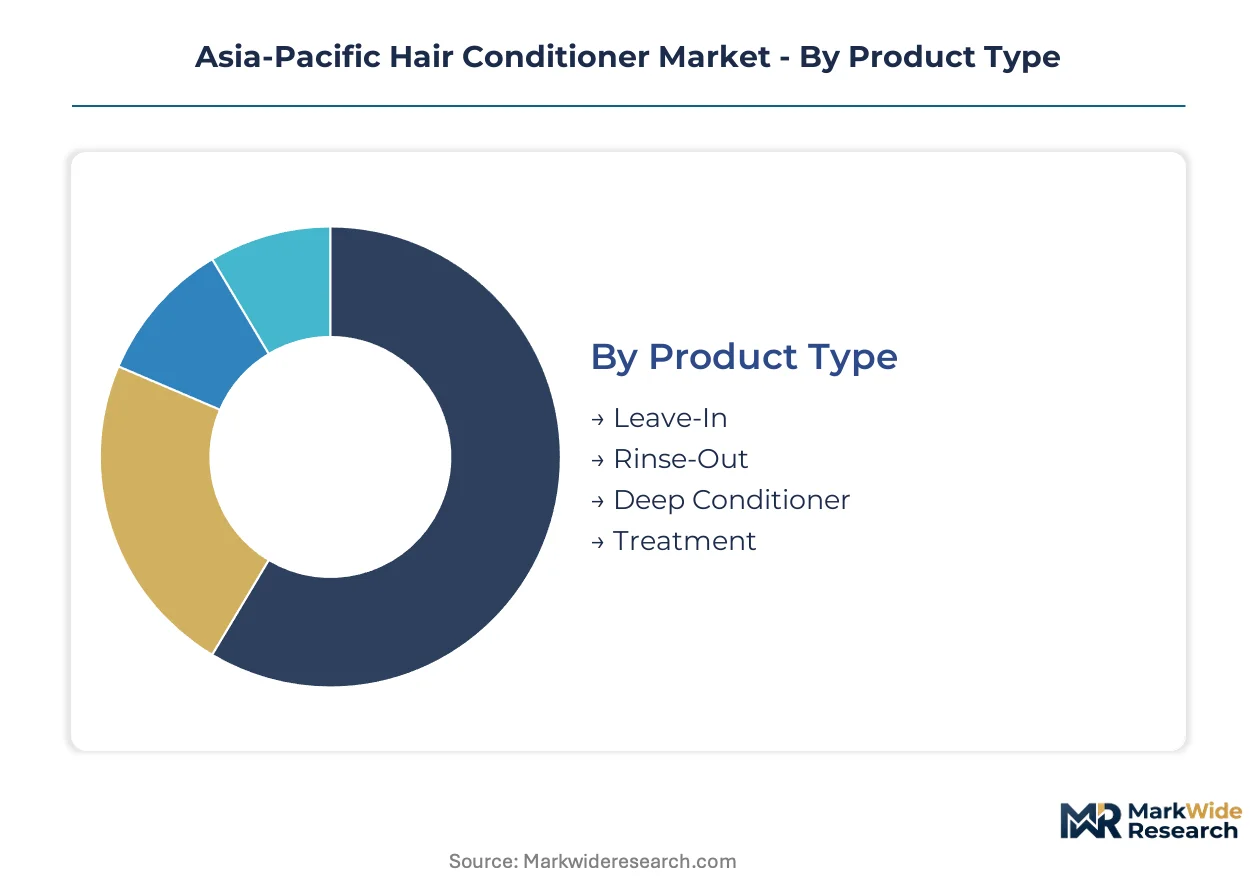
Asia-Pacific hair conditioner segmentation reveals how formulation complexity and channel access determine margin capture. Product architecture and distribution pathways shape where capital deploys for maximum returns.
Product Type:
Capital intensity peaks with treatment-grade formulations requiring active stabilization infrastructure and clinical validation protocols.
- Rinse-Out:Cationic surfactant-based formulations deposit conditioning agents during brief contact times. Mass-market volume concentrates in Indian tier-two cities and Indonesian urban corridors where price-accessible formats dominate household purchasing.
- Treatment:Intensive masks and bond-repair systems carry higher active loads and extended dwell-time specifications. Salon professionals in South Korea and Japan prescribe these for home maintenance, extending service revenue into recurring retail purchases.
- Leave-In:Lightweight spray and gel bases target convenience-driven application. Male grooming adoption in Philippine and Indonesian metropolitan centers drives format innovation.
- Deep Conditioner:Weekly-use concentrates with elevated protein and lipid content. Demand clusters among heat-styled hair consumers in Vietnam's emerging urban middle class.
Most installed capacity flows through Rinse-Out. Expansion is steepest in Treatment.
Formulation:
Manufacturing cost tiers separate emulsion-based systems from aqueous and aerosol alternatives.
- Cream:Fatty alcohol and silicone emulsions dominate mass-market production. Thai and Malaysian contract manufacturers maintain the region's largest cream filling capacity.
- Spray:Aerosol and pump-dispensed formats require pressurized filling lines and propellant handling permits. Leave-in adoption among male consumers in Australian cities accelerates spray segment growth.
- Gel:Polymer-thickened aqueous bases suit humid climate preferences. Southeast Asian consumers favor gel rinse-outs for non-greasy dry-down.
- Liquid:Low-viscosity pourable formats serve traditional rinse-out applications. Indian mass-market brands compete aggressively on liquid liter-plus family sizes.
Cream formulations carry the heaviest asset base. Spray capacity is climbing fastest.
End User:
Customer lifetime value varies sharply across demographic segments with divergent repurchase frequencies.
- Women:Multi-step conditioning routines span rinse-out, treatment, and leave-in categories. South Korean female consumers drive premium tier adoption across all product types.
- Salon Professionals:Licensed practitioners prescribe treatment-grade home care and stock back-bar conditioning systems. Indian salon chains are building private-label treatment lines for client retention.
- Men:Simplified leave-in and 2-in-1 formats dominate male purchasing. Jakarta and Manila barbershops are expanding retail conditioner adjacencies.
- Children:Tear-free and fragrance-minimized formulations target parental safety concerns. Australian and New Zealand regulatory disclosure requirements elevate formulation costs for this segment.
Women account for the largest installed demand base. Salon Professionals are gaining share fastest.
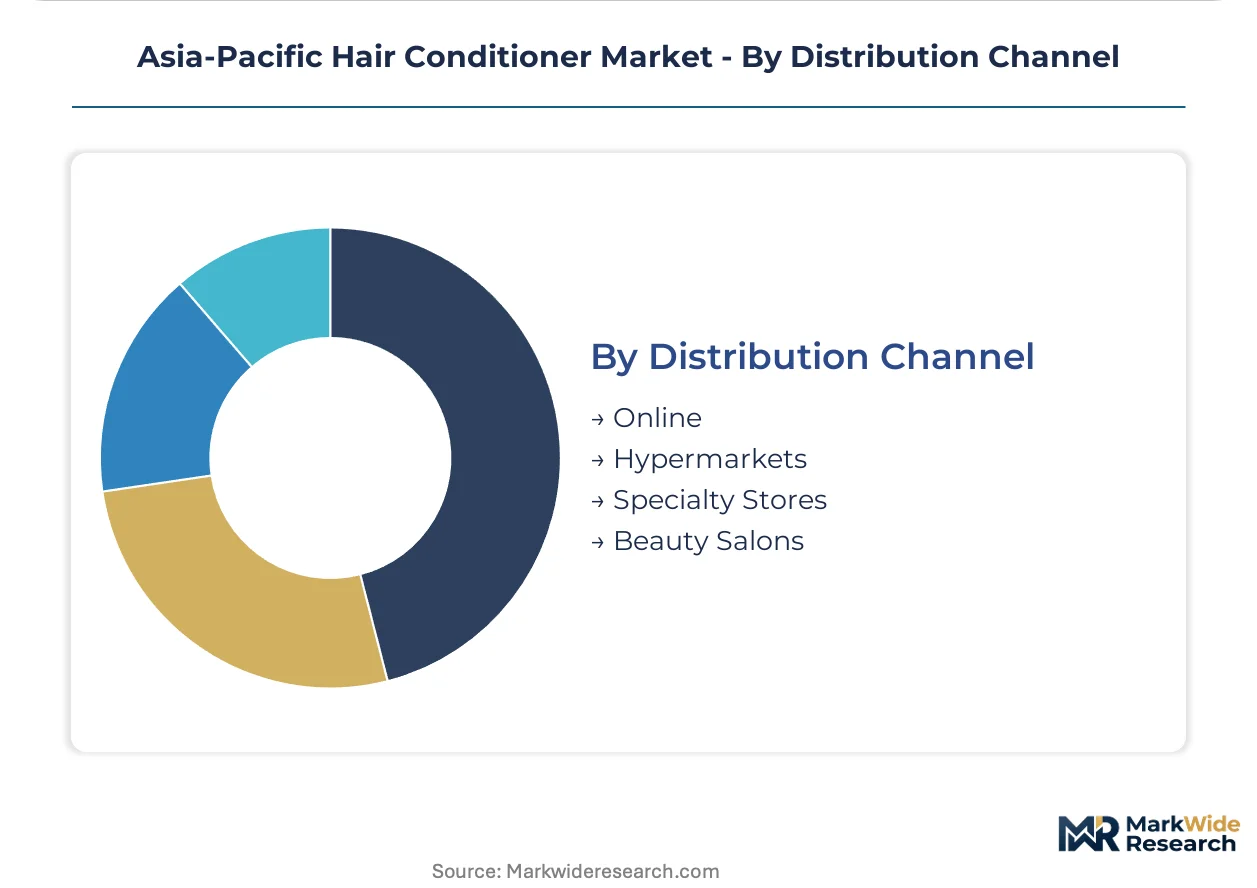
Distribution Channel:
Channel economics determine working capital intensity and margin retention.
- Hypermarkets:High-volume, low-margin throughput with prominent shelf placement fees. Indonesian and Vietnamese modern trade expansion is pulling conditioner penetration into secondary cities.
- Beauty Salons:Professional recommendation drives treatment-grade conversion with minimal price elasticity. South Korean salon chains operate integrated retail ecosystems.
- Online:Direct-to-consumer platforms capture subscription replenishment in Australian and New Zealand metropolitan corridors. Personalized scalp diagnostics bundle with auto-shipped formulations.
- Specialty Stores:Curated assortments and sampling services support premium positioning. Japanese drugstore chains elevate conditioner to skincare-adjacent merchandising.
Hypermarkets move the most unit volume. Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints across the Asia-Pacific hair conditioner landscape. Producers migrate toward jurisdictions with streamlined cosmetic registration protocols while maintaining export access to premium markets. This divergence between compliance burden and market proximity defines current capacity allocation decisions.
South Korea
K-beauty innovation cycles compress product development timelines to under six months. MFDS fast-track approval pathways for novel biotech actives accelerate commercialization of fermented conditioning ingredients. Seoul-based R&D clusters dominate cationic surfactant formulation expertise, with Gangnam district salons driving treatment-grade home care adoption.
Japan
PMDA oversight enforces stringent cosmetic ingredient safety thresholds that elevate barrier-to-entry for new market participants. METI industrial policy supports domestic fermentation biotechnology partnerships for next-generation conditioning actives. Osaka-Kobe manufacturing corridor maintains legacy silicone emulsion capacity serving pan-Asian export demand.
India
BIS cosmetics standards mandate percentage-level ingredient disclosure that conflicts with proprietary formulation protections. CDSCO registration pathways for imported conditioners create six-to-nine month approval delays versus domestic production. Maharashtra chemical clusters around Mumbai and Pune concentrate contract manufacturing for regional brands.
Vietnam
ASEAN Cosmetic Directive mutual recognition reduces registration duplication costs for Thai and Indonesian exporters targeting this market. Ho Chi Minh City and Mekong Delta provinces exhibit conditioner usage gaps versus Hanoi, offering first-mover positioning opportunities. Dong Nai province industrial zones attract toll manufacturing investments from South Korean mid-tier brands.
Australia
TGA cosmetic ingredient disclosure requirements exceed ASEAN baseline standards, elevating formulation costs for children's tear-free segments. Subscription-based replenishment models capture metropolitan buyers in Sydney and Melbourne through direct-to-consumer platforms. Victorian manufacturing corridor maintains specialized capacity for clean-beauty certified exports.
Asia-Pacific Hair Conditioner Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational consumer goods conglomerates anchoring mass-market rinse-out volumes while regional biotechnology firms capture premium treatment-grade margins. The vendor base organizes into three tiers: global scale players with pan-Asian distribution infrastructure, mid-tier Asian specialists with fermentation-derived active capabilities, and local contract fillers serving private-label salon chains. Consolidation pressures concentrate among Indian and Indonesian mid-tier manufacturers struggling to embed batch-level traceability for export compliance. Competitive moves prioritize backward integration into biotech raw material sourcing and strategic partnerships with salon professional networks.
Within the global scale tier, Procter & Gamble Co. and L'Oreal S.A. occupy positions defined by distribution depth and professional channel anchoring respectively. Unilever exemplifies price-accessible volume strategies across emerging Asian urban corridors. Among Asia-Pacific specialists, Kao Corporation and Shiseido Company represent distinct archetypes: the former leveraging chemical process expertise for mass-market efficiency, the latter anchoring premium positioning through skincare-adjacent conditioning narratives. Amorepacific sits within the biotechnology-forward segment, its Seoul-based R&D footprint aligning with fermented active commercialization trends. These named entities serve as structural anchors rather than exhaustive enumeration; market structure accommodates additional regional specialists and private-label operators not detailed here.
| Leading Market Players |
|---|
| Procter & Gamble Co. |
| L'Oreal S.A. |
| Unilever |
| Kao Corporation |
| Shiseido Company |
| Amorepacific |
| Johnson & Johnson Consumer Inc. |
| Mandom Corporation |
| Amway |
| Others |
Value Chain & Pricing Dynamics
Fermented biotechnology actives are displacing silicone-centric conditioning platforms across South Korean and Japanese R&D centers, simultaneously elevating formulation costs and concentrating supply relationships with specialized fermentation partners rather than legacy petrochemical distributors. This technology transition compresses margins for mass-market rinse-out producers while amplifying pricing power for treatment-grade specialists with captive biotech sourcing.
Pricing Analysis
Salon channel markups of 40-60 percent above wholesale sustain premium treatment-grade positioning, while hypermarket retail operates on 15-25 percent gross margins that force economy-tier producers toward volume scale. Three-tier pricing structure across premium, standard, and economy levels separates Amorepacific's fermented active lines from Unilever's cream formats and local private-label fillers. Price differentiation hinges on MFDS fast-track certification status and clean-beauty audit tier. Cost compression in mass-market segments is intensifying because BIS labeling mandates escalate compliance spend. Tier-two Indian cities exhibit highest price sensitivity; Gangnam district salons show minimal elasticity.
Supply Chain Analysis
Cyclomethicone and dimethicone feedstock rests on Chinese petrochemical clusters in Shandong and Jiangsu provinces, exposing formulators to energy-price volatility and carbon policy shocks. Cationic surfactant expertise draws from legacy Japanese and South Korean chemical processors, with fatty alcohol supply anchored in Malaysian palm derivatives and Thai oleochemical output. Single-source vulnerability concentrates in fermentation biotechnology partnerships where Seoul-based R&D centers control novel active commercialization. Distribution runs through Thai and Malaysian contract manufacturers serving pan-Asian brand portfolios, with Indonesian and Vietnamese modern trade expansion pulling volume into secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific hair conditioner manufacturing presents a geographic-arbitrage play between India's lower labor costs and BIS disclosure friction versus Vietnam's ASEAN harmonization benefits and underpenetrated southern provinces.
For Market Incumbents: Lock in backward integration into fermentation biotechnology partnerships before Korean R&D centers consolidate exclusive active supply. Defend salon channel positioning by embedding proprietary treatment protocols into licensed practitioner networks. Capacity addition in Dong Nai province industrial zones captures ASEAN mutual recognition advantages while insulating against Indian water scarcity premiums. For New Entrants and Emerging Players: Male grooming adopters in Jakarta and Manila barbershops represent the most penetrable buyer archetype with minimal incumbent leave-in format coverage. Ho Chi Minh City and Mekong Delta provinces offer white-space geographic positioning with conditioner usage gaps versus northern Vietnam. Direct-to-consumer subscription bundling with scalp diagnostics captures Australian metropolitan professionals disengaging from supermarket channels. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian mid-tier manufacturers struggling to embed batch-level traceability for MFDS and PMDA export protocols. Long-term viability favors fermentation biotechnology specialists with Seoul-based R&D footprints and clean-beauty certification convergence. Watch for ASEAN Cosmetic Directive expansion into additional mutual recognition protocols as inflection signal for contract manufacturing consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Biotech | Captures proprietary active supply from Seoul R&D clusters before exclusivity windows close. |
| Salon Channel Professional Certification | Locks in practitioner prescription behavior through licensed treatment protocol embedding. |
| Clean-Beauty Multi-Certification Convergence | Reduces audit costs for Thai manufacturers exporting to EWG Verified and COSMOS markets. |
| Direct-to-Consumer Subscription Launch | Bypasses Australian supermarket margin compression with personalized scalp diagnostic bundling. |
| Vietnam South Expansion | First-mover positioning in Ho Chi Minh City and Mekong Delta underpenetrated corridors. |
Study Parameters
Coverage spans South Korea, Japan, India, Vietnam, Thailand, Malaysia, Indonesia, Australia, and New Zealand, with primary inputs from each market's salon professional networks and retail channel operators. The analysis combines structured interviews with brand managers, category buyers at hypermarkets, formulation chemists at contract manufacturers, and regulatory affairs leads navigating BIS and MFDS pathways. Secondary validation draws from MFDS cosmetic registration databases, ASEAN Cosmetic Directive implementation reports, Indian customs import records, and Nielsen retail audit data across metropolitan corridors. Bottom-up volume estimates triangulate against top-down category sizing from national statistical agencies.
Granularity-level modeling captures product type, formulation base, end-user archetype, and distribution channel dynamics at country-level resolution across the analysis window. Segmentation dimensions include rinse-out versus treatment versus leave-in formats, cream versus spray versus gel versus liquid bases, women versus salon professionals versus men versus children end users, and hypermarket versus beauty salon versus online versus specialty store channels. CAGRs derive from trend extrapolation of salon professional channel expansion rates, K-beauty innovation cycle compression, and ASEAN harmonization implementation timelines. Industry-specific inputs incorporate MFDS fast-track approval velocity and BIS labeling compliance cost trajectories.
Inputs from MFDS registration databases and ASEAN implementation reports were available through the study window; gaps in real-time salon professional transaction data introduce uncertainty bands around channel-share estimates. Forecasts reflect assumptions regarding continued K-beauty innovation leadership, sustained ASEAN regulatory convergence, and stable petrochemical feedstock availability. Regulatory divergence between national pharmacopoeia standards and clean-beauty certification schemes, alongside water scarcity escalation in Indian manufacturing clusters, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Europe Hair Conditioner Market
Beauty & Personal Care
Elastomer Gel in Personal Care Market
Beauty & Personal Care
Pore Strips Market
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Spain Dermocosmetics Market
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Germany Cosmetics for Pregnancy Market
Beauty & Personal Care
Cosmetics Face Serum Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
Makeup Brush and Tool Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
At Home Hair Dye Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
United Kingdom Hair Care Market