
 Natural Cat Litter Products Market | 2026-2036
Natural Cat Litter Products Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Cat Litter Products Market Outlook
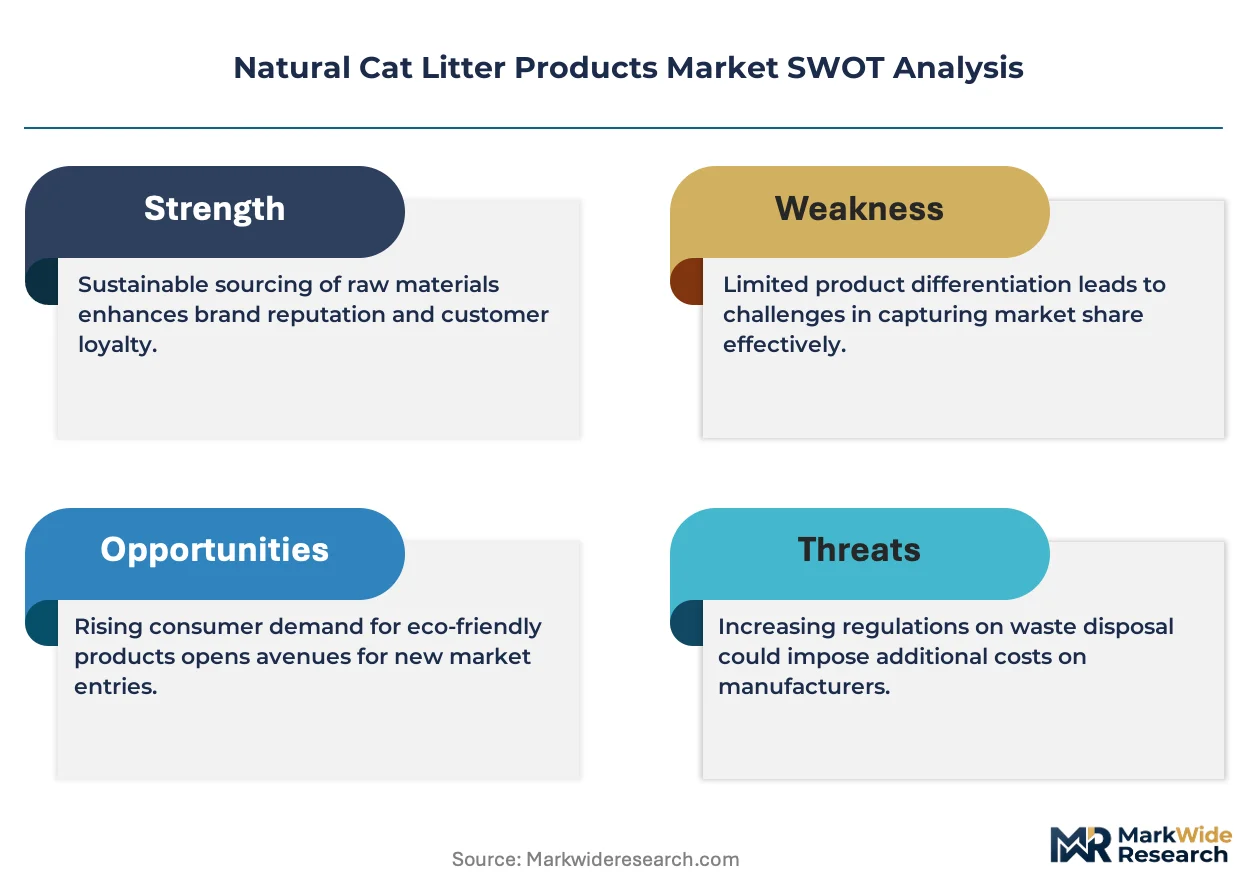
Subscription replenishment revenue is rewriting profit allocation across the natural cat litter value chain. Ökocat leverages its proprietary compressed wood fiber technology to command premium positioning in direct-to-consumer channels. World’s Best Cat Litter anchors its competitive stance through corn-based clumping formulations that dominate Midwest agricultural supply corridors. sWheat Scoop differentiates via enzymatic odor-control patents that extend brand loyalty beyond conventional performance benchmarks.
Natural cat litter products comprise absorbent substrates derived from plant fibers, reclaimed paper, or minimally processed clay alternatives, engineered to achieve moisture retention exceeding 200% by weight while maintaining friable clump integrity for mechanical scooping. The primary commercial purpose centers on replacing sodium bentonite and silica gel litters with biodegradable, compost-compatible alternatives that align with municipal organic waste stream requirements. Corn-based clumping formulations capture the dominant margin pool due to superior odor encapsulation and familiar handling characteristics that reduce switching friction for conventional litter users. Wood-based pellets represent the fastest-growing structural segment as industrial pelletizing equipment achieves scale economies that narrow price gaps with commodity clay alternatives.
The United States Department of Agriculture (USDA) biopreferred program and the European Union REACH chemical registration framework collectively shape ingredient transparency requirements and compostability certification standards that determine market access eligibility. The Federal Trade Commission (FTC) Green Guides enforcement actions against unsubstantiated biodegradability claims have tightened permissible marketing language, forcing reformulation documentation and third-party testing investments. Stakeholders must monitor evolving state-level extended producer responsibility legislation for pet care packaging to anticipate compliance cost structures and channel reconfiguration requirements.
Market Dynamics
Municipal composting mandates across Germany, France, and the Netherlands are compressing disposal pathways for sodium bentonite litters, forcing manufacturers to reengineer formulations around certified biodegradable substrates or forfeit shelf space in premium retail channels.
Growth Catalysts
- REACH chemical registration framework:The European Union's tightening disclosure requirements for synthetic additives are accelerating substitution toward plant-fiber substrates that bypass hazardous substance classifications.
- Compressed wood fiber pelletizing:Industrial-scale densification equipment is narrowing production cost gaps with commodity clay mining, enabling private-label penetration into mass-market retail.
- German pet specialty retail concentration:Dense networks of independent pet stores in Bavaria and North Rhine-Westphalia provide dedicated shelf space for certified compostable formulations.
Market Restraints
- Corn starch price volatility:Feedstock costs for clumping formulations fluctuate with Midwest agricultural commodity cycles, compressing margin stability for corn-based producers.
- Single-source pellet equipment dependency:European and North American manufacturers rely on a concentrated base of Italian and German extrusion machinery suppliers, creating capex bottleneck risks.
- FTC Green Guides enforcement:Substantiation requirements for biodegradability claims have forced reformulation documentation investments that disproportionately burden mid-tier brands.
Strategic Opportunities
- Subscription replenishment channels:Direct-to-consumer auto-ship models bypass retail slotting fees and capture recurring revenue streams with higher lifetime value metrics.
- Municipal organic waste stream integration:Partnerships with composting facilities in California and Washington State create closed-loop disposal credentials that command retail premiums.
- Enzymatic odor-control biotechnology:Convergence of agricultural enzyme processing with litter substrate engineering opens patent-protected differentiation in high-frequency purchase segments.
Industry Challenges
- Compostability certification timelines:Third-party validation through OK Compost and BPI programs requires 12-18 month testing cycles that delay product launches.
- Legacy clay supply chain reconfiguration:Established distribution infrastructure optimized for heavy mineral freight struggles to accommodate lightweight fiber logistics economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Cat Litter Products Market |
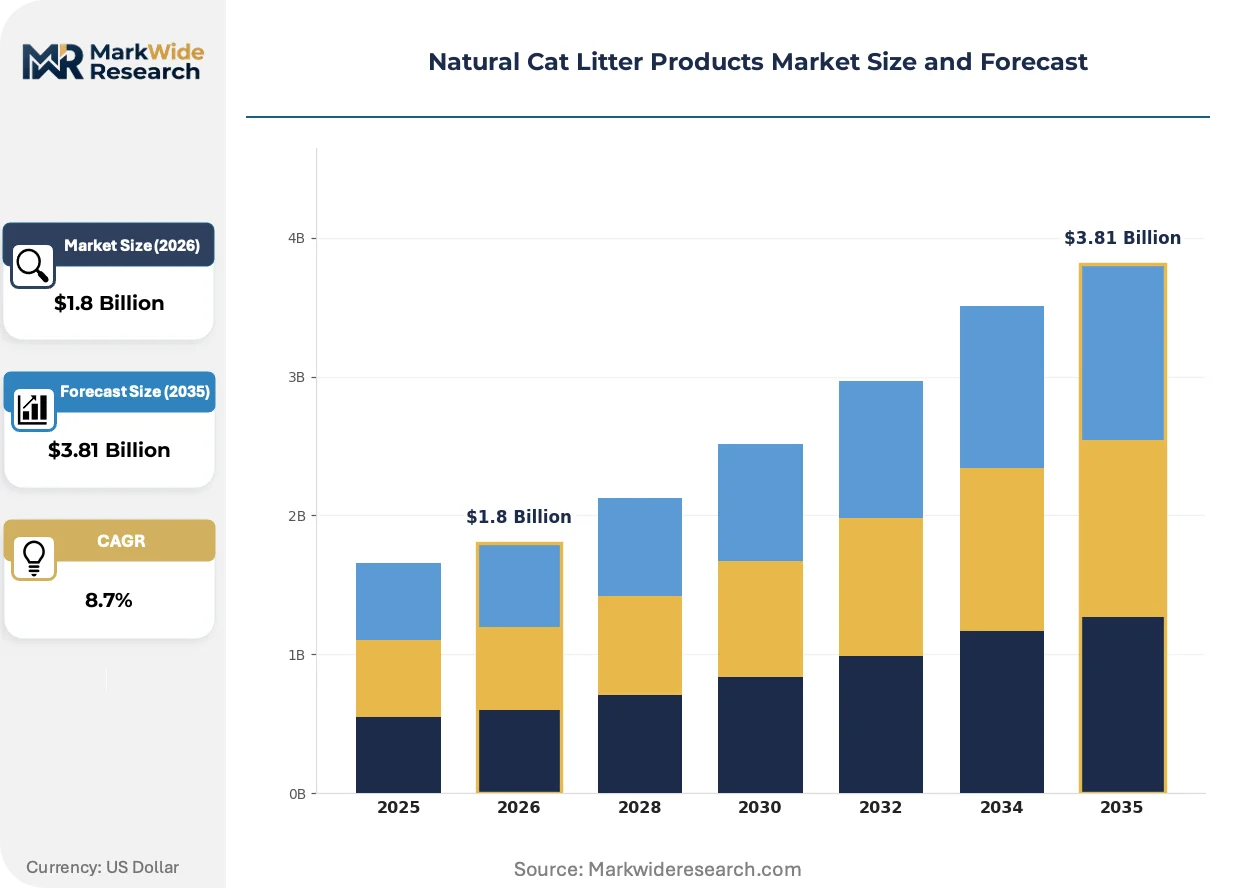
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bentonite, Corn Based, Wood Based, Paper Based Form: Granules, Clumping, Non-Clumping, Pellets Packaging Type: Bag, Box, Bulk, Refill Distribution Channel: Online Retail, Pet Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Ökocat, World’s Best Cat Litter, Naturally Fresh, Feline Pine, Blue Buffalo, Dr. Elsey’s, Ever Clean, sWheat Scoop, Fresh Step Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Cat Litter Products Market Strategic Shifts
Formulation chemistry and disposal infrastructure are converging to redefine performance benchmarks, as odor encapsulation technologies and municipal compost compatibility become inseparable purchase criteria rather than secondary attributes.
Enzymatic biodegradation accelerants derived from agricultural waste processing are rendering obsolete conventional fragrance-masking approaches that merely suppress odor perception. Premium pet specialty retailers in Germany and the Pacific Northwest are adopting these formulations at twice the rate of mass-market channels. The technology is compressing acceptable performance windows for legacy silica gel alternatives that lack active biological decomposition pathways.
The EU Green Deal's packaging waste directive is extending producer responsibility to pet care containers, forcing manufacturers to redesign multi-layer film structures or face per-unit environmental levies. Industrial consequence includes accelerated migration toward paper-based outer packaging and mono-material pouches that satisfy extended producer responsibility sorting requirements. Corn-based clumping segments in France and Belgium are responding fastest, with reformulation investments concentrated in facilities serving Benelux composting cooperatives.
Subscription auto-replenishment is displacing episodic retail purchasing among multi-cat households, with veterinary clinic partnerships emerging as a trusted channel for first-time natural litter conversion. Chewy and independent veterinary distributors are capturing switching moments through free-sample programs bundled with wellness examinations. This behavioral shift concentrates most visibly in suburban United States markets where pet humanization indices correlate with higher willingness-to-pay for certified sustainable materials.
Natural Cat Litter Products Market Segmentation
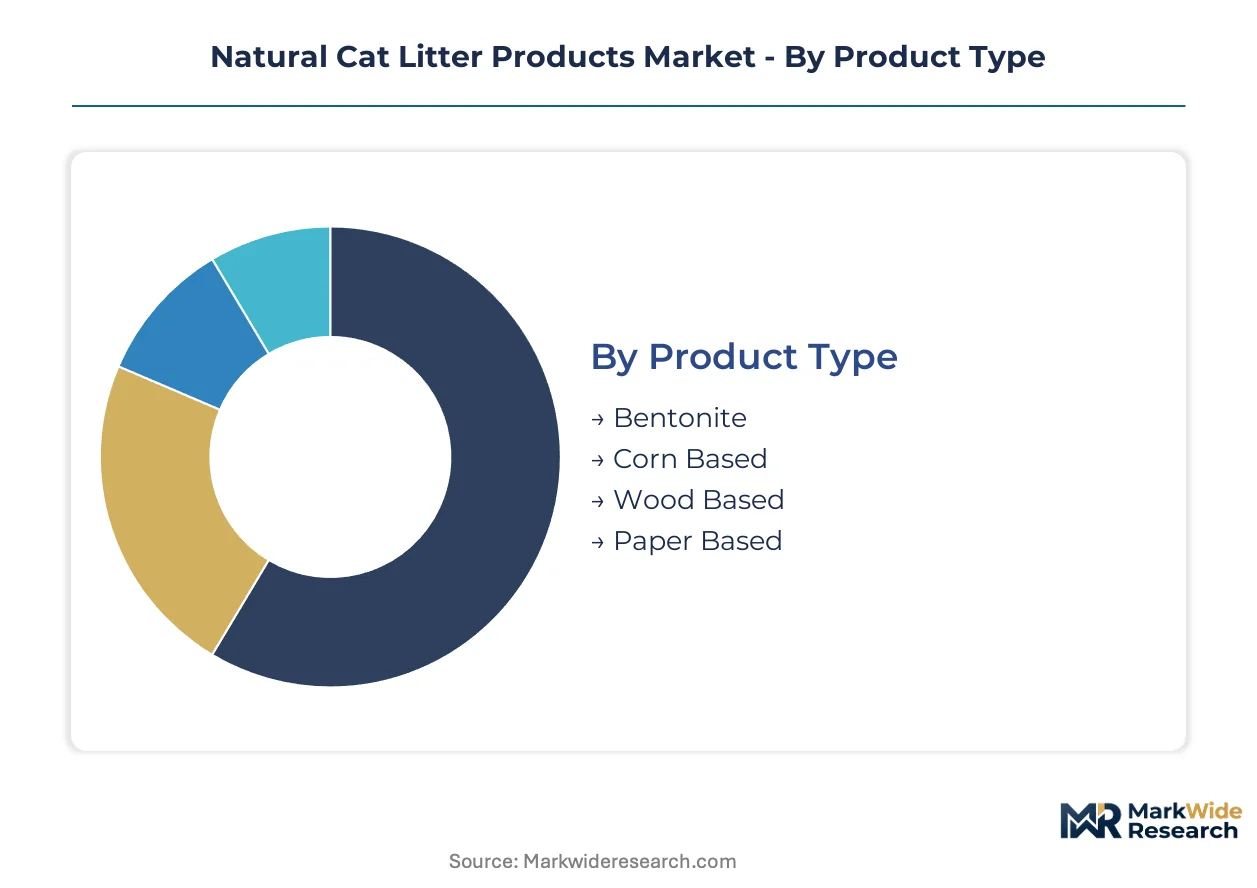
Natural cat litter segmentation reflects divergent supply chain economics and disposal infrastructure maturity across substrate technologies. Formulation chemistry and packaging format choices determine compostability certification eligibility and channel access.
Product Type:
Cost tier positioning separates mineral extraction from agricultural fiber processing economics.
- Corn Based:Clumping formulations derived from Midwest maize starch achieve superior odor encapsulation through protein-carbohydrate matrices. German pet specialty retailers concentrate demand here, driven by REACH-compliant ingredient transparency requirements and municipal composting mandates in Bavaria and North Rhine-Westphalia.
- Wood Based:Compressed softwood and hardwood fibers engineered via Italian and German extrusion equipment deliver pelletized substrates with moisture retention exceeding 200% by weight. Pacific Northwest composting facility partnerships in Washington State and California are rotating this segment up share rankings through closed-loop disposal credentials.
- Bentonite:Sodium-rich clay deposits mined in Wyoming and processed through legacy heavy mineral freight infrastructure.
- Paper Based:Reclaimed cellulose pulp from post-consumer waste streams, prevalent in Japanese metropolitan markets with space-constrained disposal.
Corn Based holds installed capacity. Wood Based is rotating up the share rankings.
Form:
Application requirements from multi-cat households versus single-pet owners drive format preference divergence.
- Clumping:Sodium bentonite or corn starch formulations create friable agglomerates enabling mechanical scooping and extended substrate life. Suburban United States markets with high pet humanization indices show concentrated demand, propelled by veterinary clinic sampling programs bundled with wellness examinations.
- Pellets:Densified wood fiber cylinders manufactured via industrial-scale pelletizing equipment achieve narrow price gaps with commodity clay. German independent pet stores in dense Bavarian networks anchor demand, responding to EU Green Deal packaging waste directive pressures on multi-layer film structures.
- Granules:Irregular particle substrates from mineral or plant sources with intermediate absorption characteristics.
- Non-Clumping:Traditional absorbent substrates requiring complete replacement rather than selective waste removal.
Clumping maintains volume leadership. Pellets are climbing the fastest.
Packaging Type:
Volume throughput and retail channel economics dictate format selection across the value chain.
- Bag:Multi-layer polyethylene or paper-based flexible structures dominate mass-market retail. Benelux composting cooperatives in France and Belgium are driving fastest adoption of mono-material pouch redesigns to satisfy extended producer responsibility sorting requirements.
- Bulk:Unpackaged substrate delivery for commercial catteries and municipal procurement.
- Box:Rigid corrugated containers for premium positioning in pet specialty channels.
- Refill:Concentrated substrate cartridges designed for reusable dispensing systems.
Bag formats hold installed capacity. Refill systems are gaining share fastest.
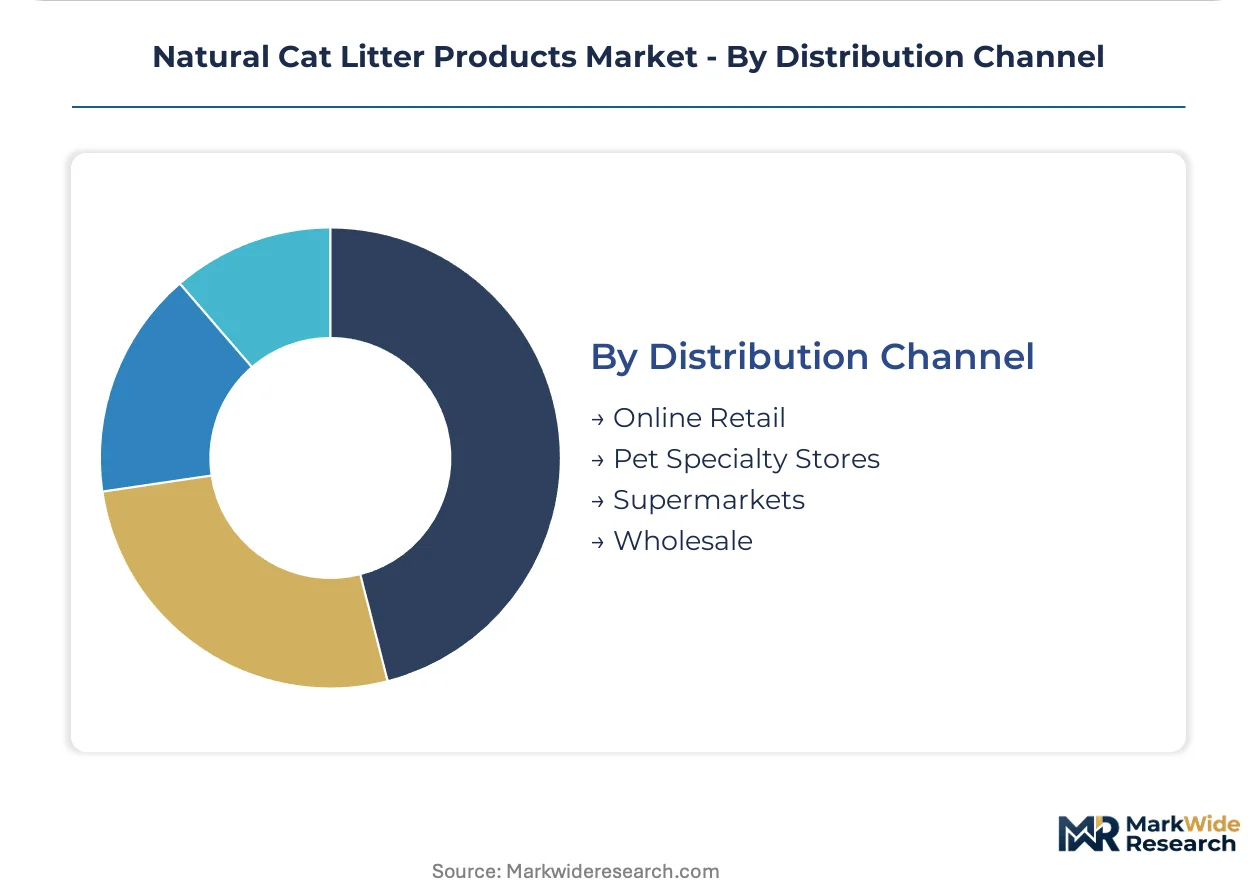
Distribution Channel:
Customer type segmentation separates episodic retail purchasers from subscription-committed multi-cat households.
- Online Retail:Direct-to-consumer auto-ship models bypass retail slotting fees and capture recurring revenue with superior lifetime value metrics. Chewy and independent veterinary distributors concentrate switching moments through free-sample programs in suburban United States markets.
- Pet Specialty Stores:Independent and chain retailers in Germany and the Pacific Northwest provide dedicated shelf space for certified compostable formulations, with enzymatic odor-control biotechnology products penetrating at twice the mass-market rate.
- Supermarkets:Mass-market retail with compressed margin structures and private-label penetration.
- Wholesale:Volume distribution to commercial catteries, shelters, and institutional buyers.
Pet Specialty Stores hold installed capacity. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pet owners demonstrate the highest willingness-to-pay for certified sustainable litter materials, while United States households concentrate demand through subscription auto-replenishment channels. This consumption-mix differential separates European regulatory-driven adoption from American convenience-oriented purchasing patterns.
United States
Midwest agricultural supply corridors anchor corn-based clumping production, with veterinary clinic partnerships in suburban markets driving first-time natural litter conversion. The USDA biopreferred program shapes ingredient transparency requirements for compostability certification eligibility. Washington State and California composting facility partnerships are rotating wood-based pellet segments up share rankings through closed-loop disposal credentials.
Germany
Dense networks of independent pet stores in Bavaria and North Rhine-Westphalia provide dedicated shelf space for certified compostable formulations. REACH chemical registration framework tightening accelerates substitution toward plant-fiber substrates that bypass hazardous substance classifications. Frankfurt and Munich metropolitan clusters concentrate enzymatic odor-control biotechnology penetration at twice the mass-market rate.
France
Benelux composting cooperatives drive fastest adoption of mono-material pouch redesigns to satisfy extended producer responsibility sorting requirements. EU Green Deal packaging waste directive pressures force redesign of multi-layer film structures or face per-unit environmental levies. Lyon and Paris basin facilities concentrate reformulation investments serving municipal organic waste stream integration partnerships.
Netherlands
Municipal composting mandates compress disposal pathways for sodium bentonite litters, forcing manufacturers to reengineer formulations around certified biodegradable substrates. Extended producer responsibility legislation for pet care packaging anticipates compliance cost structures and channel reconfiguration requirements. Rotterdam logistics clusters accommodate lightweight fiber logistics economics that legacy clay supply chain infrastructure struggles to match.
Japan
Space-constrained metropolitan disposal infrastructure elevates paper-based reclaimed cellulose pulp prevalence in Tokyo and Osaka corridor markets. METI standards influence industrial pelletizing equipment scale economies that narrow price gaps with commodity clay alternatives. Yokohama and Nagoya industrial zones concentrate post-consumer waste stream processing for premium absorbent substrate manufacturing.
Natural Cat Litter Products Market Competitive Environment
Capability concentration sits with biotechnology-specialized tier players holding enzymatic odor-control patents; scale advantage sits with agricultural commodity processors leveraging feedstock proximity. The vendor base organizes around three strategic archetypes: compressed wood fiber technology specialists, corn-based clumping formulators with Midwest supply chain integration, and enzymatic biotechnology patent holders. Dominant competitive moves include direct-to-consumer channel bypass of retail slotting fees and municipal composting facility partnership credentialing.
Within the compressed wood fiber tier, Ökocat and Feline Pine occupy positions exemplifying proprietary densification technology leverage. Among corn-based agricultural processors, World’s Best Cat Litter anchors the clumping formulation segment. At the biotechnology-specialized end, sWheat Scoop represents enzymatic odor-control patent differentiation. These three archetypes illustrate how substrate technology specialization, agricultural supply chain integration, and biological processing IP each create defensible positioning vectors against commodity clay alternatives.
| Leading Market Players |
|---|
| Ökocat |
| World’s Best Cat Litter |
| Naturally Fresh |
| Feline Pine |
| Blue Buffalo |
| Dr. Elsey’s |
| Ever Clean |
| sWheat Scoop |
| Fresh Step Naturals |
| Others |
Value Chain & Pricing Dynamics
Single-source pellet equipment dependency from Italian and German extrusion machinery suppliers determines both pricing tier spreads and supply chain shape, compressing margin stability for mid-tier brands while concentrating production economics around certified compostable formulations.
Pricing Analysis
Long-term offtake agreements between corn-based formulators and Midwest agricultural cooperatives dominate volume procurement, with spot-market exposure limited to feedstock shortfalls. Price differentiation stems from compostability certification tier and subscription auto-ship bundling, with premium channels capturing higher margins through closed-loop disposal credentials. Pricing pressure stems from corn starch commodity volatility that squeezes clumping formulation margins. Mass-market private-label buyers exhibit highest price sensitivity, while German pet specialty retailers show lowest elasticity for certified sustainable materials.
Supply Chain Analysis
Contract-manufacturing concentration sits with Italian and German extrusion equipment specialists that supply densification machinery to wood-based pellet producers across North America and Europe. Raw material flows draw from Wyoming sodium bentonite deposits, Midwest maize starch processing, and Pacific Northwest softwood fiber harvesting. Supply chain risk centers on single-source machinery dependency that creates capex bottleneck risks during capacity expansion cycles. Distribution runs through veterinary clinic partnerships and direct-to-consumer auto-ship platforms that bypass traditional retail slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment revenue layers expand faster than substrate hardware sales, converting episodic purchasers into recurring revenue streams with superior lifetime value metrics through auto-ship convenience and bundled wellness examinations.
For Market Incumbents: Entrench competitive position by deepening captive supply relationships with Midwest agricultural cooperatives for corn starch feedstock security, and accelerate enzymatic odor-control biotechnology patent filings to defend against emerging biotechnology specialists. Prioritize certification investment in OK Compost and BPI programs to maintain shelf access as EU Green Deal packaging directives tighten. For New Entrants and Emerging Players: Pacific Northwest municipal composting facility partnerships represent the most penetrable entry point for wood-based pellet formulations seeking closed-loop disposal credentials. Target veterinary clinic sampling programs bundled with wellness examinations as the primary go-to-market angle for first-time natural litter conversion in suburban United States markets. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors biotechnology-specialized players holding enzymatic odor-control patents over commodity substrate processors. Acquisition focus should center on enzymatic patent portfolios and direct-to-consumer channel infrastructure. Watch REACH chemical registration enforcement actions as the inflection signal for accelerated plant-fiber substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Auto-Ship Platform Launch | Chewy and independent veterinary distributors capture switching moments through bundled free-sample programs. |
| Municipal Composting Facility Partnership | Washington State and California closed-loop credentials command retail premiums in Pacific Northwest channels. |
| Enzymatic Odor-Control Patent Filing | sWheat Scoop biotechnology differentiation extends brand loyalty beyond conventional performance benchmarks. |
| Compressed Wood Fiber Capacity Expansion | Italian and German extrusion equipment scale economies narrow price gaps with commodity clay alternatives. |
| Mono-Material Pouch Redesign | Benelux composting cooperatives drive fastest adoption to satisfy EU Green Deal extended producer responsibility sorting requirements. |
Study Parameters
Initial hypotheses were tested against primary input from brand managers at natural litter manufacturers, category buyers at pet specialty retailers, procurement leads at agricultural cooperatives, and supply planners at composting facilities, then refined against customs records, Nielsen retail audit data, USDA biopreferred program filings, and EU REACH chemical registration disclosures. Bottom-up volume estimates from substrate production facilities were triangulated with top-down demand projections from household pet ownership databases.
Demand-supply-balance modeling across the projection horizon incorporated corn-based clumping, wood-based pellets, and enzymatic biotechnology segments, with adoption curves calibrated to municipal composting mandate implementation timelines and veterinary clinic partnership penetration rates. CAGRs were derived from segment-level growth trajectory convergence, with inputs including Midwest agricultural commodity price cycles and EU Green Deal packaging waste directive compliance cost structures.
Practitioners should monitor REACH chemical registration enforcement intensity and corn starch feedstock price volatility for early signals of margin compression or formulation substitution acceleration. Quarterly review of municipal composting mandate expansion timelines and FTC Green Guides substantiation requirement updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Car Seat Market
Pet Care Products
Pet Food Bowl Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
US and Mexico Cat Litter Market
Pet Care Products
Pet Care E-Commerce Market
Pet Care Products
Australia Pet Food Market
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Insulated Dog House Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
United Kingdom Pet Food Market
Pet Care Products
United Kingdom Cat Litter Market