
 Over-Night Hair Treatment Products Market | 2026-2036
Over-Night Hair Treatment Products Market Size, Share, and Industry Trends Forecast 2026-2036
Over-Night Hair Treatment Products Market Analytics
Specialty beauty retail is rewriting access patterns for intensive hair repair formats. Sephora and Ulta Beauty's curated shelf space allocations now determine which overnight formulas gain trial among premium consumers. L'Oréal S.A. leverages its professional division to anchor salon-exclusive distribution for high-concentration overnight masks. Shiseido Company, Limited competes through J-beauty positioning in Asian travel retail corridors. Unilever sustains mass-market penetration with multi-brand portfolio density in drugstore and grocery channels.
Over-night hair treatment products are leave-in formulations designed for extended contact time during sleep, typically incorporating ceramides, proteins, or plant-derived lipids in occlusive bases that prevent moisture loss over six to eight hours. Their primary commercial purpose is to deliver reparative or restorative benefits beyond what rinse-out conditioners achieve in two to three minutes of exposure. Overnight masks lead structural margin pools due to higher per-unit pricing and stronger professional endorsement, while serums occupy the fastest-growing position as consumers layer them under caps or wraps for enhanced penetration. Natural ingredient positioning dominates marketing narratives but synthetic ceramide complexes and modified silicones still underpin most clinically validated repair claims in the moisturizing and repairing application categories.
The U.S. FDA oversees cosmetic labeling and safety substantiation under the Federal Food, Drug, and Cosmetic Act, while the EU REACH framework and ECHA govern ingredient restriction and substitution protocols for cosmetic substances. These dual regulatory architectures elevate compliance costs for multi-market suppliers but also create defensible positioning for brands that preemptively eliminate contested preservatives or fragrance allergens. Stakeholders must monitor emerging state-level disclosure mandates in California and New York that extend beyond federal requirements.
Market Dynamics
The overnight hair treatment sector faces intensifying formulation complexity as EU REACH substance restrictions and emerging state-level disclosure mandates in California and New York force simultaneous multi-jurisdictional compliance. This regulatory layering compresses product development timelines while elevating qualification barriers for raw material suppliers.
Growth Catalysts
- Professional salon channel expansion:Freelance stylists and salon chains now drive volume for intensive repair formats, creating pull-through demand for take-home overnight masks.
- REACH-driven clean formulation premiums:Preemptive elimination of contested preservatives and fragrance allergens commands shelf space and price positioning in EU retail.
- Ceramide complex innovation:Synthetic ceramide technologies validated through extended contact protocols are displacing unproven natural lipid alternatives in clinical positioning.
Market Restraints
- Raw material concentration risk:Specialty ceramide and modified silicone supply clusters in German and Japanese chemical manufacturing, creating single-source vulnerability.
- Extended substantiation timelines:EU ECHA safety dossier requirements and US FDA cosmetic labeling scrutiny stretch new product launches to 18-24 month cycles.
- Substitution pressure from rinse-out innovations:Two-minute bond-building treatments using maleic acid technology capture repair-seeking consumers unwilling to commit to overnight protocols.
Strategic Opportunities
- South Korea K-beauty export infrastructure:Domestic salon culture and established duty-free retail networks create ready channels for premium overnight format expansion across Southeast Asia.
- Travel retail corridor capture:Asian airport retail and cross-border e-commerce platforms remain underpenetrated for J-beauty and K-beauty overnight repair positioning.
- California SB 312 disclosure tailwinds:Proactive fragrance ingredient transparency creates defensible positioning against competitors awaiting federal mandate harmonization.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in occlusive base design for six-to-eight-hour wear protocols remains concentrated among legacy professional hair care R&D teams.
- Multi-market label harmonization:Divergent US FDA, EU REACH, and emerging state disclosure requirements force SKU proliferation and inventory fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over-Night Hair Treatment Products Market |
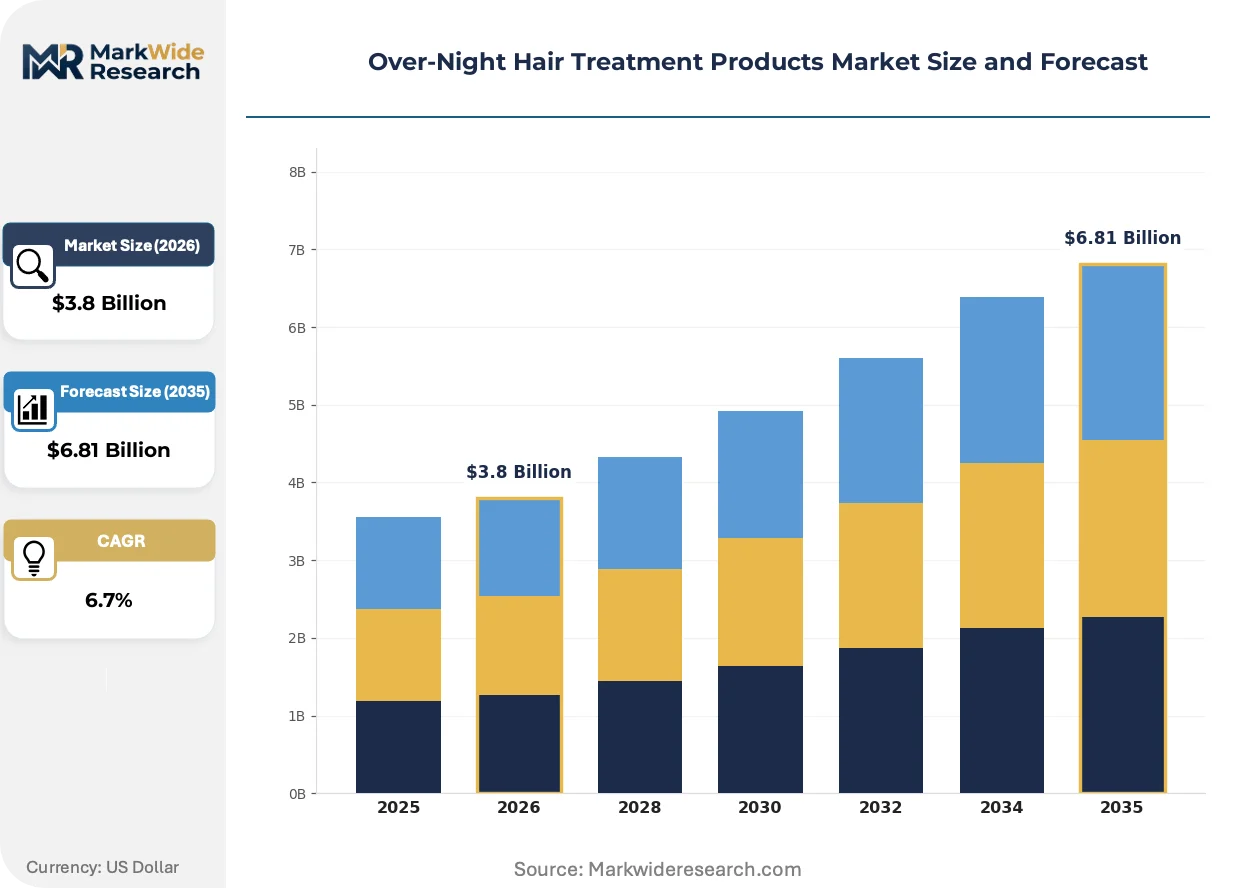
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Oils, Masks, Sprays Ingredient Type: Natural, Synthetic, Herbal, Organic End User: Women, Men, Professionals, Salons Application: Moisturizing, Repairing, Smoothing, Nourishing |
| Companies Covered | L'Oréal S.A., Unilever, Procter & Gamble Co., Estée Lauder Companies Inc., Henkel AG & Co. KGaA, Shiseido Company, Limited, Beiersdorf AG, Kao Corporation, Amorepacific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over-Night Hair Treatment Products Market Evolving Landscape
Biomimetic lipid technology and sleep-science positioning are converging to redefine efficacy claims in overnight hair repair. These shifts compress the boundary between cosmetic and dermatological credibility while reshaping channel access requirements.
Encapsulated time-release ceramide delivery systems are rendering obsolete conventional rinse-out bond builders for chemically processed hair recovery. Professional salons in Seoul and Tokyo have adopted these formats as standard post-coloring protocols. The technology is compressing consumer willingness to pay for extended-contact treatments versus conventional conditioning.
EU REACH candidate list expansions and ECHA substance restriction proposals are forcing accelerated reformulation cycles across preservative and fragrance portfolios. Manufacturers serving both European and North American markets now maintain parallel formulation streams to manage divergent compliance timelines. Professional-exclusive lines bear the heaviest adaptation burden due to higher concentration actives and more complex INCI declarations.
Subscription-based replenishment models for overnight treatment caps and serum wraps are displacing traditional retail trial-and-repurchase cycles. Direct-to-consumer brands capture recurring revenue while specialty beauty retailers lose basket attachment for accessory items. This behavioral shift concentrates most visibly in US urban markets where sleep-optimization wellness framing resonates with millennial and Gen-Z demographics.
Over-Night Hair Treatment Products Market Segmentation
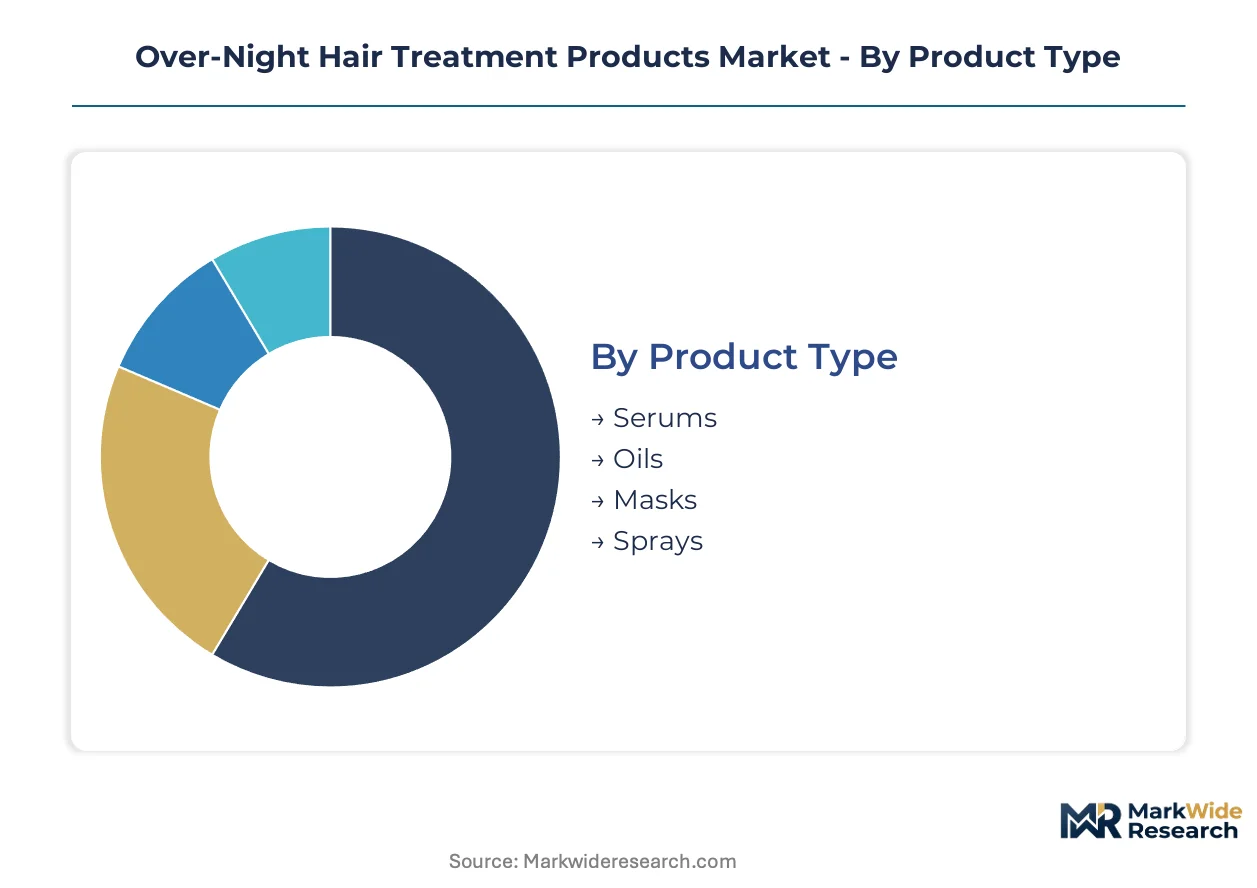
Segmentation in overnight hair treatment products determines formulation priorities, channel access, and regulatory compliance burdens. Product format and ingredient positioning create distinct margin pools and development timelines across the value chain.
Product Type:
Cycle times vary dramatically by format, with accessory-dependent formats turning inventory faster than standalone treatments requiring no additional purchase.
- Masks:Occlusive cream bases with ceramide or protein concentrations above 5% require extended contact protocols validated through salon professional endorsement. Demand concentrates in Seoul and Tokyo salon channels where post-coloring recovery protocols command premium positioning and repeat purchase loyalty.
- Serums:Lightweight fluid vehicles enable layering under thermal caps or silk wraps for enhanced penetration without residue transfer to bedding. South Korean direct-to-consumer brands capture fastest expansion through subscription replenishment models in urban US markets where sleep-optimization wellness framing resonates.
- Oils:Plant-derived lipid blends with jojoba or argan carrier bases target consumers seeking natural positioning despite slower absorption kinetics.
- Sprays:Aqueous mist formats with modified silicone dispersions offer convenience positioning for consumers unwilling to commit to overnight protocols.
Masks dominate installed base through professional channel anchoring. Serums concentrate expansion through direct-to-consumer subscription velocity.
Ingredient Type:
Cost tier stratification separates clinically validated synthetic complexes from narrative-driven natural positioning, with regulatory compliance burden increasing down the price curve.
- Synthetic:Modified silicone crosspolymers and ceramide NP analogs manufactured by German and Japanese chemical suppliers underpin most validated repair claims in moisturizing and repairing applications. EU REACH substance restrictions force parallel formulation streams for multi-market suppliers, elevating qualification barriers for raw material sourcing.
- Natural:Unprocessed plant lipids and cold-pressed seed oils command price premiums in clean beauty retail despite limited clinical substantiation for extended-contact efficacy.
- Herbal:Traditional botanical extracts from Ayurvedic or TCM pharmacopeias target ethnic hair care specialists and diaspora consumer segments.
- Organic:Certified organic positioning requires supply chain documentation that extends development timelines and limits sourcing flexibility.
Synthetic ingredients anchor professional-grade efficacy claims. Natural positioning drives premium retail markup in specialty beauty channels.
End User:
Volume concentration and margin capture diverge sharply between institutional procurement and individual consumption patterns.
- Salons:Professional chains and freelance stylists in South Korea and Japan drive volume for intensive repair formats, creating pull-through demand for take-home overnight masks with higher concentration actives and complex INCI declarations.
- Women:Individual consumers represent the core addressable market across all retail channels, with purchasing decisions influenced by social media tutorial content and influencer endorsement cycles.
- Men:Emerging segment concentrated in urban Asian markets where male grooming category expansion extends into hair repair protocols previously gender-coded as female.
- Professionals:Traveling business demographic targets travel retail corridors with single-use pod formats and TSA-compliant sizing.
Women constitute the installed base majority. Salons concentrate expansion through professional endorsement leverage.
Application:
Maturity gradient runs from established moisturizing claims to emerging smoothing technologies, with repair applications commanding highest development investment.
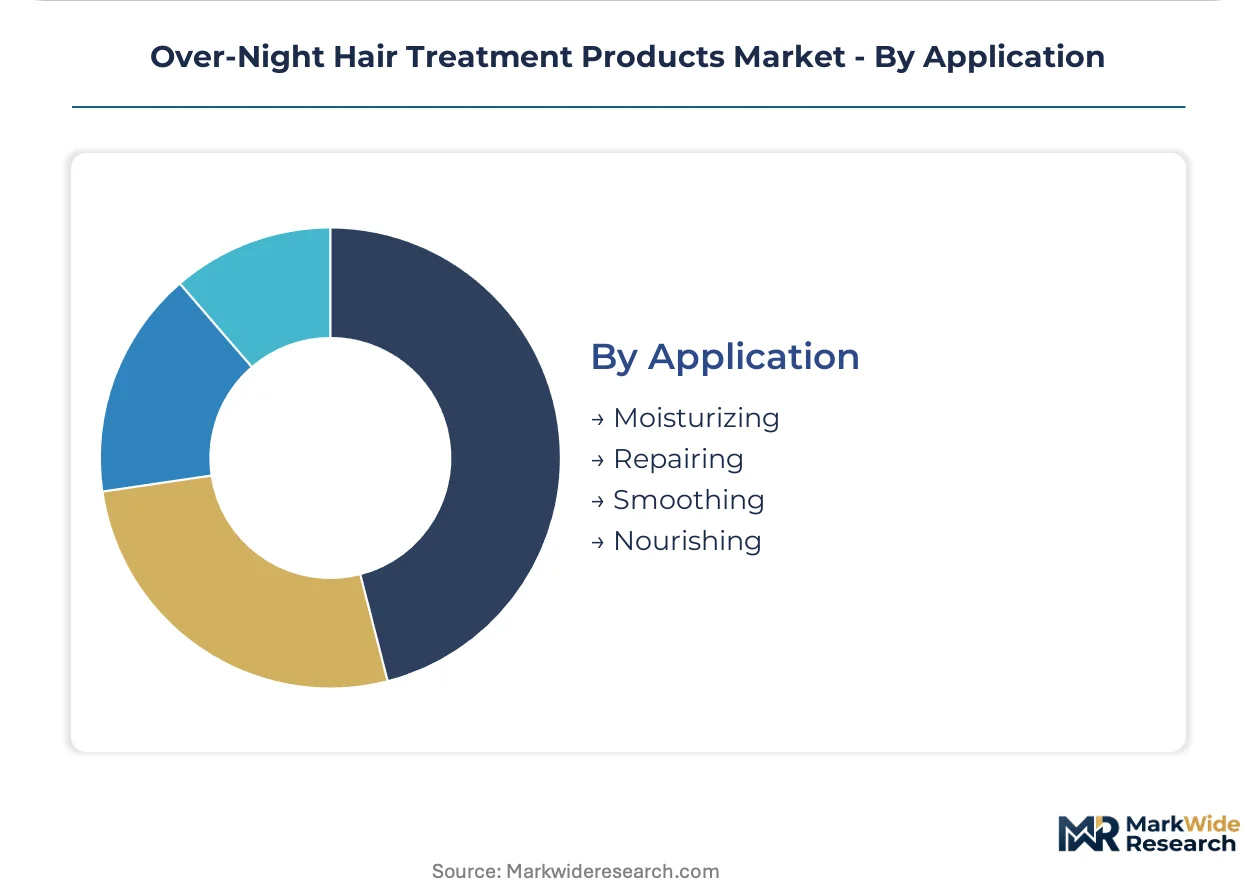
- Repairing:Bond-building and cuticle-sealing claims using maleic acid or synthetic ceramide technologies target chemically processed hair recovery. Professional salons in Seoul have adopted encapsulated time-release formats as standard post-coloring protocols.
- Moisturizing:Occlusive humectant systems with glycerin and panthenol bases represent the most saturated claim category with lowest differentiation potential.
- Nourishing:Vitamin and antioxidant positioning bridges cosmetic and dermatological credibility without requiring clinical trial investment.
- Smoothing:Anti-frizz and alignment claims using quaternary ammonium compounds compete with rinse-out conditioning innovations for consumer protocol commitment.
Moisturizing dominates installed base saturation. Repairing captures expansion through professional channel validation and premium pricing architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in South Korea and Japan, where salon culture and K-beauty export infrastructure sustain 40-60% markups over mass-market equivalents. Mass-market volume concentrates in the United States and Germany, where drugstore channel density and private-label competition compress margins.
South Korea
Seoul's Gangnam district hosts the densest concentration of professional salons prescribing overnight ceramide masks as post-coloring protocols. MFDS cosmetic safety standards enforce rigorous ingredient documentation that elevates qualification barriers for imported raw materials. Amorepacific Corporation anchors domestic R&D clusters in Yongin and Osan, exporting encapsulated time-release formats through Incheon airport duty-free corridors.
United States
Ulta Beauty and Sephora shelf-space allocations determine trial rates for premium overnight serum formats among millennial and Gen-Z consumers. FDA cosmetic labeling requirements under the Federal Food, Drug, and Cosmetic Act intersect with California SB 312 fragrance disclosure mandates, forcing dual compliance streams. Los Angeles and New York City concentrate influencer marketing infrastructure that drives subscription-based replenishment models.
Japan
Tokyo's Shibuya and Ginza retail corridors sustain J-beauty positioning for lightweight overnight serums targeting business travelers. METI oversees cosmetic manufacturing standards that align with, but diverge from, EU REACH protocols, complicating multi-market formulation. Shiseido Company, Limited maintains R&D facilities in Kakegawa and Osaka, deploying biomimetic lipid technologies through domestic salon channels and Asian airport retail.
Germany
Professional salon chains in Munich and Hamburg drive institutional procurement of high-concentration overnight masks for chemically processed hair recovery. ECHA substance restrictions under EU REACH force preemptive elimination of contested preservatives, elevating clean formulation premiums. BASF and Evonik anchor synthetic ceramide supply clusters in Ludwigshafen and Essen, creating single-source vulnerability for global formulators.
United Kingdom
London's specialty beauty retail and freelance stylist networks sustain demand for premium overnight repair formats despite post-Brexit regulatory divergence. The UK's retained EU REACH law maintains ingredient restrictions, though divergence risk looms under proposed cosmetic regulatory reform. Unilever leverages portfolio density across Boots and Superdrug channels to defend mass-market penetration against direct-to-consumer entrants.
Over-Night Hair Treatment Products Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The overnight hair treatment sector exhibits consolidated premium tiers alongside fragmented mass-market entry. Three archetypes dominate: multinational beauty conglomerates with professional-salon anchoring, Asian heritage houses with regional export infrastructure, and direct-to-consumer specialists with subscription velocity. Competitive moves concentrate on preemptive clean formulation certification and travel-retail corridor capture.
Within the multinational tier, L'Oréal S.A. and Unilever occupy positions that exemplify divergent channel strategies—professional-salon exclusivity versus mass-market density. Shiseido Company, Limited represents the Asian heritage house archetype, leveraging J-beauty credibility in travel retail corridors. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive vectors without requiring identical resource commitments.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Unilever |
| Procter & Gamble Co. |
| Estée Lauder Companies Inc. |
| Henkel AG & Co. KGaA |
| Shiseido Company, Limited |
| Beiersdorf AG |
| Kao Corporation |
| Amorepacific Corporation |
| Others |
Value Network & Pricing Analysis
Ludwigshafen's synthetic ceramide manufacturing cluster anchors global supply for high-concentration overnight repair formulations, with BASF and Evonik capacity utilization directly conditioning premium pricing power for professional-grade masks. Capacity constraints at these German chemical hubs transmit downstream through extended lead times and minimum order quantity pressures, compressing margins for mid-tier formulators while reinforcing markup capture by salon-exclusive brands.
Pricing Analysis
Customization-premium spreads separate configured-to-order professional salon lines from standard retail SKUs, with bespoke ceramide concentrations and INCI-compliant fragrance-free formulations commanding substantial uplifts. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and professional endorsement intensity, with EU REACH-compliant clean formulations sustaining the widest spreads. Cost compression in mass-market tiers intensifies as private-label entrants replicate core moisturizing claims without clinical substantiation investment. Salon procurement teams exhibit lowest price sensitivity due to protocol standardization requirements, while individual consumers in drugstore channels demonstrate highest elasticity.
Supply Chain Analysis
Supplier-financing facilities extended by German and Japanese chemical manufacturers enable qualified formulators to manage working capital through 90-120 day payment terms on ceramide NP analogs and modified silicone crosspolymers. Raw material dependencies center on specialty lipid inputs from Ludwigshafen, Essen, and Kobe manufacturing clusters, with jojoba and argan carrier oils sourced from established agricultural suppliers in Morocco and Argentina. Single-source vulnerability concentrates in synthetic ceramide production, where ECHA substance restriction timelines create qualification bottlenecks for alternative suppliers. Distribution runs through professional salon wholesalers in Seoul and Tokyo, direct-to-consumer subscription platforms in US urban markets, and Asian airport duty-free corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Overnight hair treatment penetration remains early-cycle in Western mass retail, with subscription replenishment velocity and sleep-science wellness framing providing sustained adoption tailwinds. Professional salon channel anchoring in Asian markets demonstrates scalable replication potential for brands navigating multi-jurisdictional compliance.
For Market Incumbents: Insulate professional-grade positioning through captive supply arrangements with German ceramide manufacturers, preempting qualification barriers that strand competitors during ECHA restriction cycles. Accelerate clean formulation certification investment ahead of California SB 312 fragrance disclosure harmonization, converting compliance burden into shelf-space defense against mass-market private-label substitution. Channel control through salon-exclusive distribution remains the critical lever for margin preservation. For New Entrants and Emerging Players: Southeast Asian travel retail corridors offer underpenetrated white-space for K-beauty format exporters seeking duty-free velocity outside saturated Seoul and Tokyo channels. US urban direct-to-consumer subscription models for serum-wrap combinations present the most penetrable entry vector, with sleep-optimization wellness framing differentiating against incumbent rinse-out bond builders. Go-to-market execution should prioritize influencer marketing infrastructure in Los Angeles and New York City. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biomimetic lipid specialists with validated extended-contact protocols and established professional salon endorsement networks. Five-to-ten year viability hinges on preemptive clean formulation portfolios and multi-jurisdictional regulatory navigation capabilities. Acquisition target archetypes include direct-to-consumer subscription brands with demonstrated recurring revenue velocity and Asian heritage houses with underexploited export infrastructure. The signal to watch is ECHA substance restriction acceleration forcing consolidation among undercapitalized formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Clean Formulation Certification | EU REACH compliance creates defensible positioning against competitors awaiting regulatory harmonization. |
| Professional Salon Channel Expansion | Seoul and Tokyo salon protocols generate pull-through demand for take-home overnight masks. |
| Biomimetic Lipid R&D Investment | Encapsulated time-release ceramide technologies displace unproven natural lipid alternatives. |
| Subscription Replenishment Model | Direct-to-consumer velocity captures recurring revenue while specialty retailers lose basket attachment. |
| Travel Retail Corridor Capture | Asian airport duty-free networks remain underpenetrated for premium overnight repair positioning. |
Research Methodology
Cross-validation between primary interviews with formulation chemists, salon chain procurement directors, and specialty beauty retail category managers anchors the qualitative findings against secondary validation from EU ECHA substance restriction databases, US FDA cosmetic labeling guidance, and South Korean MFDS safety documentation. Bottom-up triangulation incorporates customs records for ceramide and modified silicone trade flows, while top-down calibration draws from disclosed R&D expenditure patterns at multinational beauty conglomerates. Primary fieldwork concentrated on professional salon channels in Seoul, Tokyo, and New York City, with secondary synthesis of patent filings for biomimetic lipid delivery systems.
Calibration against historical adoption curves for extended-contact hair repair formats and professional endorsement diffusion patterns shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, ingredient type, end user archetype, and application claim, with geographic regulatory cluster differentiation for EU REACH, US FDA, and emerging state-level disclosure mandates. CAGRs derive from volume trajectory analysis incorporating salon channel expansion rates, subscription replenishment velocity, and travel retail penetration assumptions. Industry-specific inputs include synthetic ceramide supply capacity utilization and K-beauty export infrastructure development.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on premium beauty categories or cross-border e-commerce logistics costs would shift the trajectory. Forecasts incorporate assumptions regarding ECHA substance restriction timelines and FDA cosmetic regulatory modernization pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
North America Bath and Shower Products Market
Beauty & Personal Care
Hair Salon Equipment Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
North America Setting Spray Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Bio-Based Cosmetics Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
Wrinkle Release Spray Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Personal Care and Cosmetic Preservatives Market
Beauty & Personal Care
Powdered Hand Soap Market
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
Aluminium-Free Deodorants Market
Beauty & Personal Care
Personal Care Products Market