
 Hair Wig Market | 2026-2036
Hair Wig Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Wig Market Analysis
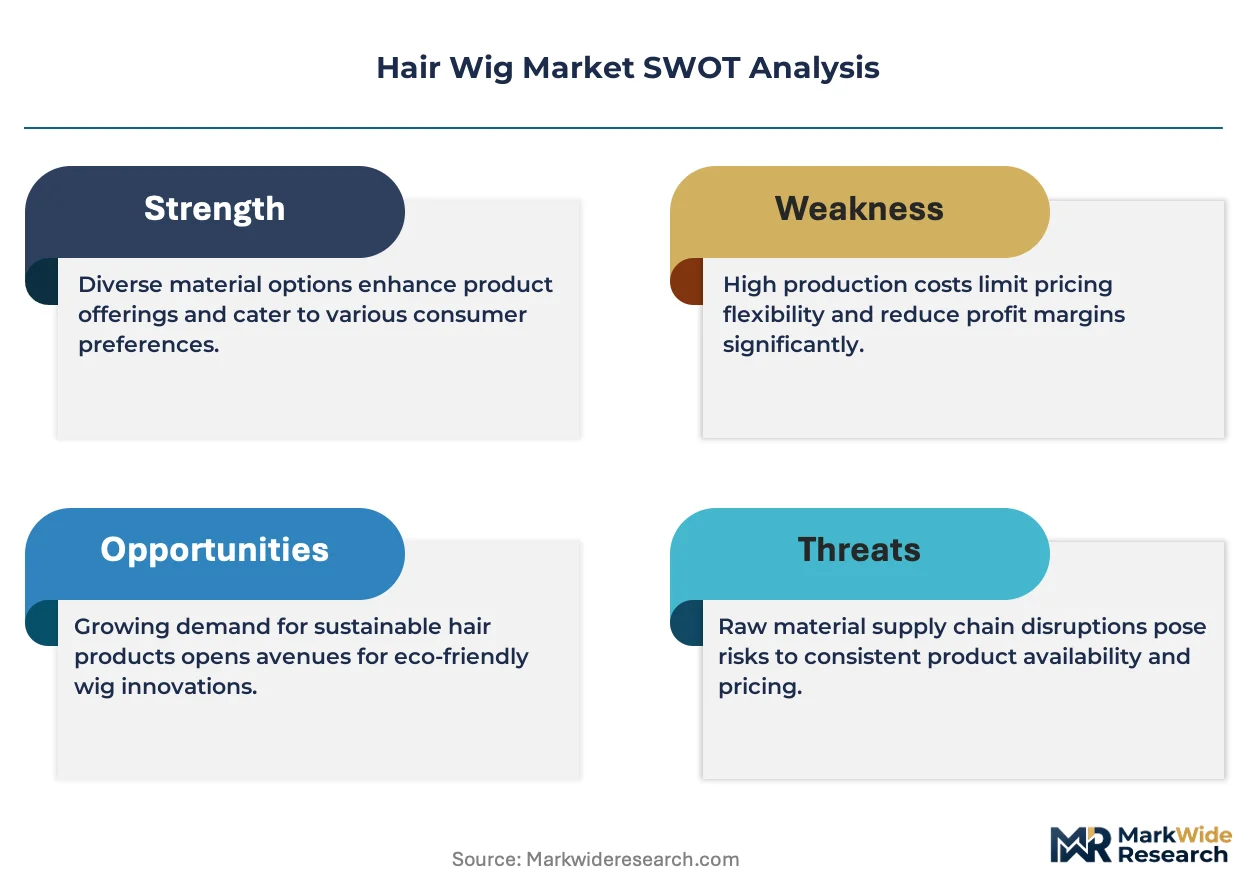
Medical-grade cap construction is redrawing value capture across the Hair Wig landscape. Aderans Co., Ltd. leverages its clinical distribution network to anchor premium positioning in therapeutic segments. Henan Rebecca Hair Products Co., Ltd. sustains manufacturing scale through backward integration into raw hair sourcing across central China. Evergreen Products Group competes on synthetic fiber R&D intensity, occupying the mid-market with heat-resistant polymer formulations.
Hair wigs are wearable hair systems constructed from either harvested human hair or engineered synthetic filaments, attached to lace, monofilament, or wefted cap bases through hand-knotting or machine-wefting processes; they serve cosmetic restoration, theatrical transformation, and medical concealment functions. Human hair variants command the deepest margin pools due to sourcing scarcity and labor-intensive processing, while synthetic hair segments expand fastest among price-sensitive fashion buyers. Lace front configurations dominate professional and medical channels where undetectable hairlines determine purchase decisions.
FDA oversight of medical wigs as Class I devices, REACH compliance for European synthetic fiber imports, and China's GB standards for textile safety collectively elevate barrier costs for new entrants. These frameworks shape demand by mandating dermatological testing, chemical disclosure, and flame-resistance certification before market access. Stakeholders must monitor evolving trade classifications for raw human hair and emerging biopolymer regulations that could recalibrate cost structures and competitive positioning.
Market Dynamics
3D-printed lace cap construction is fragmenting the traditional hand-knotting value chain, compressing lead times from weeks to days while elevating fit precision for medical-grade applications. This manufacturing shift is redistributing margin pools away from artisan-dependent suppliers toward digitally integrated producers.
Growth Catalysts
- Chemotherapy patient volumes:Oncology treatment centers in the United States and China are expanding scalp-cooling protocols, creating parallel demand for immediate-access medical wigs that restore patient dignity during hair loss episodes.
- REACH chemical disclosure mandates:European synthetic fiber imports now require full polymer traceability, which certified suppliers leverage to command premium positioning over non-compliant Asian competitors.
- Bio-fiber material science:Laboratory-cultured keratin filaments eliminate ethical sourcing constraints of harvested human hair while matching thermal styling performance.
Market Restraints
- Raw hair supply concentration:Temple-sourced Indian and Burmese hair dominates premium human hair grades, exposing processors to export restriction volatility and religious donation cycle fluctuations.
- FDA Class I device compliance:Medical wig manufacturers face dermatological testing costs and 510(k) documentation burdens that synthetic fashion wig producers avoid entirely.
- Heat-resistant polymer input costs:Specialized synthetic filaments depend on petrochemical derivatives whose pricing tracks crude oil volatility, compressing mid-market margins during energy price spikes.
Strategic Opportunities
- India's tier-2 city expansion:Bridal and entertainment demand in Hyderabad, Chennai, and Pune remains underserved by organized retail, favoring direct-to-consumer digital penetration.
- Japan's aging demographic:METI-supported silver economy initiatives subsidize medical wig procurement for alopecia patients over 65, creating a reimbursement-anchored revenue stream.
- Telemedicine prescription channels:Dermatology platforms in the United States now integrate wig fitting consultations, collapsing the traditional salon intermediary and capturing patient data for personalized cap construction.
Industry Challenges
- Hand-knotting artisan scarcity:Lace front construction requires 40-80 hours of skilled labor per unit, and training pipelines in China and Indonesia cannot match replacement demand as veteran craftspeople retire.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and GB standard compliance for medical-grade products extends product launch cycles by 14-22 months.
- Legacy ERP integration:Established manufacturers struggle to synchronize 3D scanning data with existing inventory management systems, delaying mass customization rollout.
Report Scope
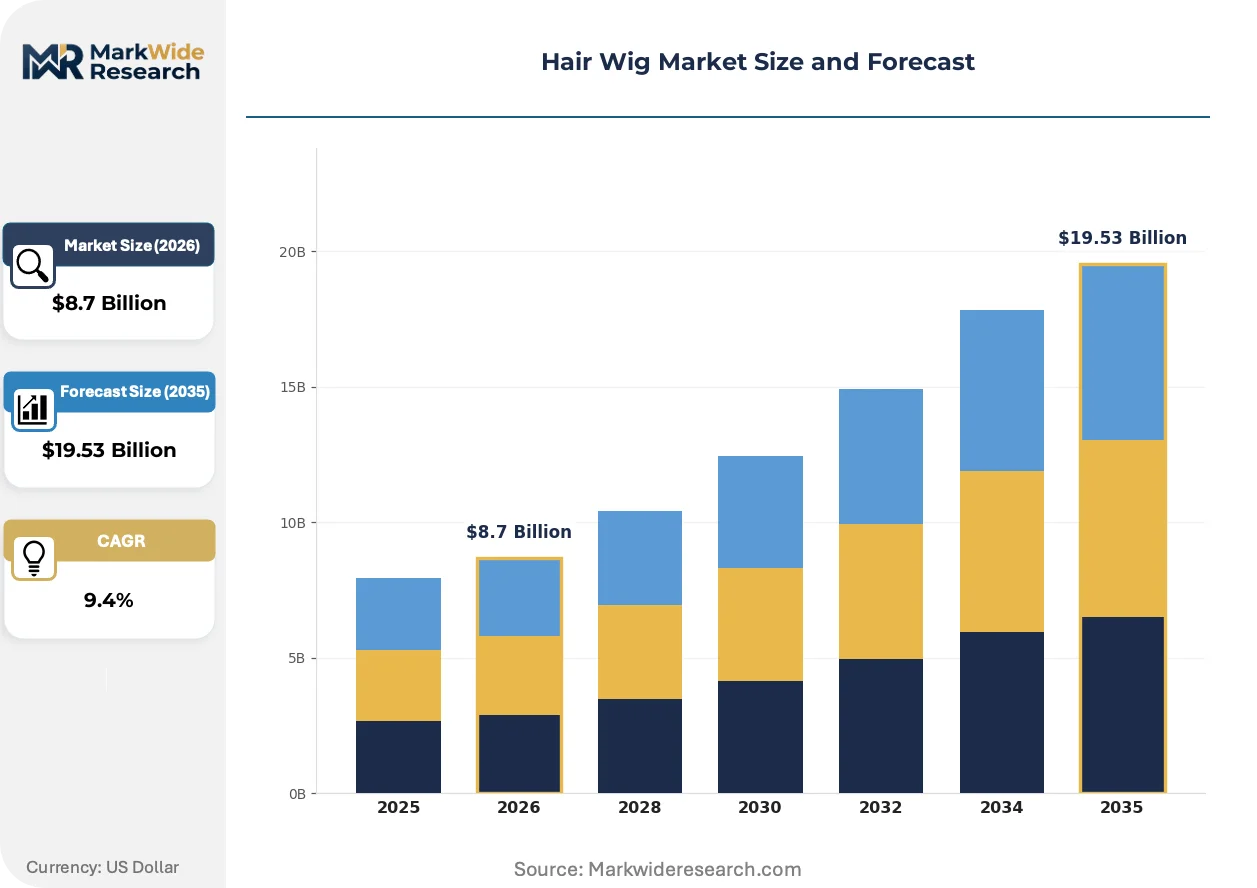
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Wig Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Human Hair, Synthetic Hair, Lace Front, Full Lace Application: Fashion, Medical, Cosplay, Theatrical Customer Type: Retail Consumers, Salons, Theaters, Professionals Distribution Channel: Online Stores, Specialty Retailers, Department Stores, Beauty Supply |
| Companies Covered | Evergreen Products Group, Ruimei, Rebecca, Estetica Designs, Raquel Welch Wigs, Great Lengths, Anhui Jinruixiang, Henan Rebecca Hair Products Co., Ltd., Aderans Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Wig Market Emerging Trajectories
Digital manufacturing and biomaterial science are converging to collapse the traditional trade-off between synthetic scalability and human hair realism. These forces are enabling new entrants to challenge incumbents across price-performance tiers.
Computational lace mapping is fragmenting the cap construction process. This technology generates patient-specific scalp topography from smartphone photogrammetry, eliminating plaster mold shipping. Oncology clinics in Germany and South Korea are piloting same-week fulfillment for chemotherapy patients. The structural consequence is compressing regional distributor networks as manufacturers sell direct.
China's GB standards for textile safety are tightening flame-resistance thresholds for synthetic hair products. Manufacturers must reformulate heat-resistant polymers or face market exclusion. Export-oriented producers in Henan and Shandong provinces are absorbing retooling costs to maintain European and North American access, while domestic-only players risk permanent competitive disadvantage.
Subscription-based refresh models are displacing single-unit ownership among fashion-conscious buyers. Younger consumers in the United States and United Kingdom now lease three to six wigs annually through styling-as-a-service platforms, trading capital expenditure for access to rotating inventory. This behavior concentrates demand with vertically integrated brands that control both manufacturing and digital styling content.
Hair Wig Market Segmentation
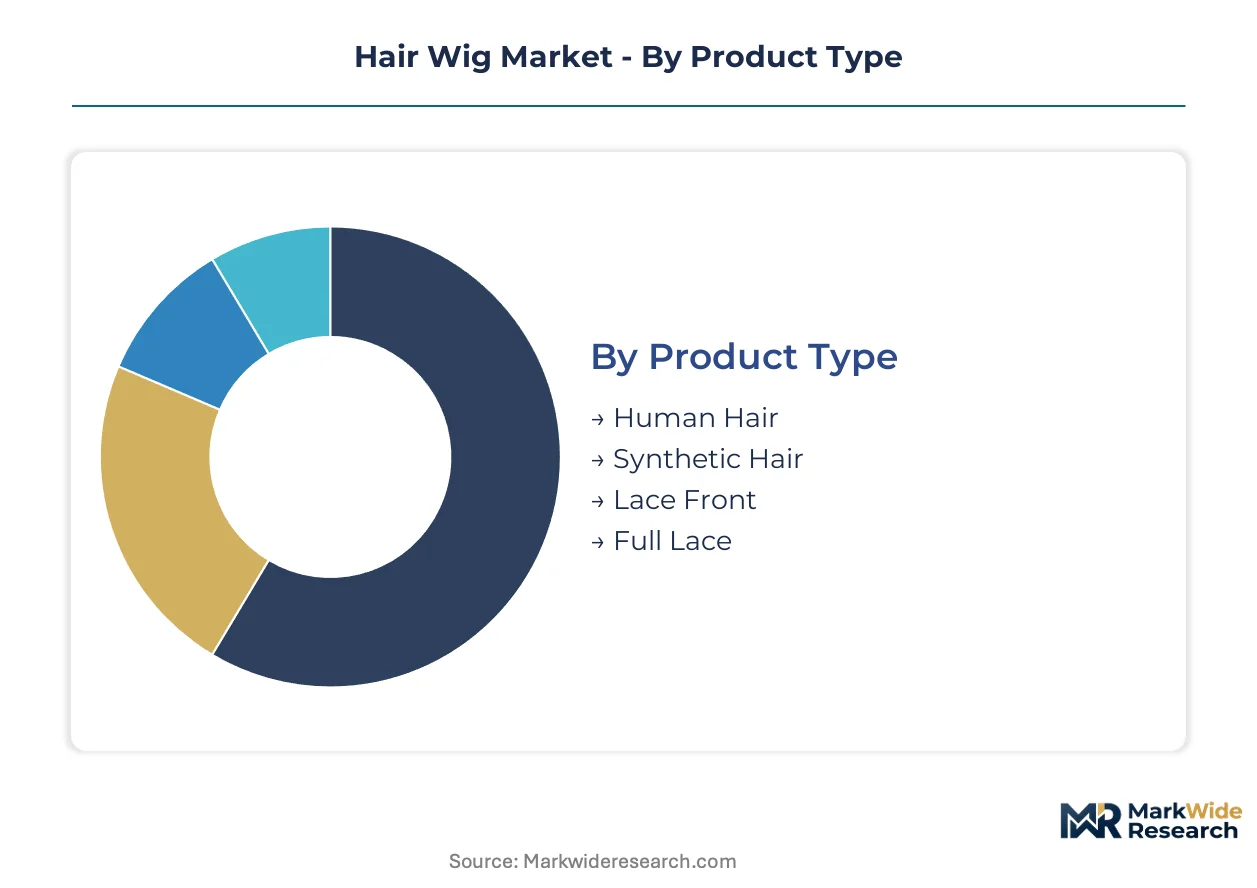
Segmentation in the Hair Wig Market separates volume-driven synthetic fashion buyers from margin-rich medical-grade purchasers. Each category reveals distinct procurement patterns, certification burdens, and channel preferences that reshape competitive positioning.
Product Type:
Human hair variants dominate export flows to North America and Europe, while synthetic production concentrates in domestic Chinese and Indian markets serving price-sensitive buyers.
- Human Hair:Harvested from temple donations in India and Myanmar, processed through labor-intensive sorting and cuticle-alignment protocols. Demand concentrates among chemotherapy patients in the United States and bridal buyers in Hyderabad seeking thermal-styling compatibility and 18-24 month lifespans.
- Synthetic Hair:Engineered from heat-resistant polymers and kanekalon filaments, manufactured at scale in Henan and Shandong provinces. Fashion-conscious consumers in China's tier-2 cities drive volume, trading durability for color variety and sub-$100 price points.
- Lace Front:Features hand-knotted hairlines on sheer lace bases, requiring 40-80 hours of artisan labor per unit. Medical channels and professional entertainers in Los Angeles and Mumbai prioritize undetectable hairline realism.
- Full Lace:Entire cap constructed from lace with multidirectional parting capability. Theater productions and drag performers in London and São Paulo value styling versatility despite premium positioning.
Human hair holds the largest share; momentum sits with synthetic hair as bio-fiber technology narrows the realism gap.
Application:
Medical applications carry the heaviest regulatory load, while fashion and cosplay segments compete on speed-to-trend and social media virality.
- Fashion:Seasonal color trends and celebrity-driven styles rotate inventory three to six times annually. Subscription platforms in the United Kingdom and United States collapse traditional retail intermediaries.
- Medical:FDA Class I device classification mandates dermatological testing and 510(k) documentation. Oncology clinics in Germany and South Korea pilot same-week fulfillment through computational lace mapping.
- Cosplay:Vibrant fantasy colors and exaggerated silhouettes dominate convention circuits in Tokyo and Anaheim. Buyers prioritize photographic impact over longevity.
- Theatrical:Custom builds for opera, ballet, and film productions require fire-retardant certification under GB standards and REACH mandates. Costume shops in Paris and New York maintain decade-long supplier relationships.
Medical applications command premium pricing; fashion buyers are expanding most quickly through digital-native channels.
Customer Type:
Professional intermediaries extract fitting and styling value, while direct-to-consumer brands capture patient data for personalized cap construction.
- Retail Consumers:Individual purchasers researching through TikTok tutorials and dermatology telemedicine platforms. Privacy concerns drive demand for discreet packaging and home fitting kits.
- Salons:Licensed stylists in Atlanta and Dubai provide cut-in services and maintenance education, anchoring local trust networks for medical wig buyers.
- Theaters:Repertory companies in Moscow and Mexico City maintain in-house wig departments with master craftspersons trained in historical construction techniques.
- Professionals:Television anchors, politicians, and corporate executives in Seoul and Washington D.C. procure through confidential concierge services.
Retail consumers generate the highest volume; professionals sustain the steepest price premiums.
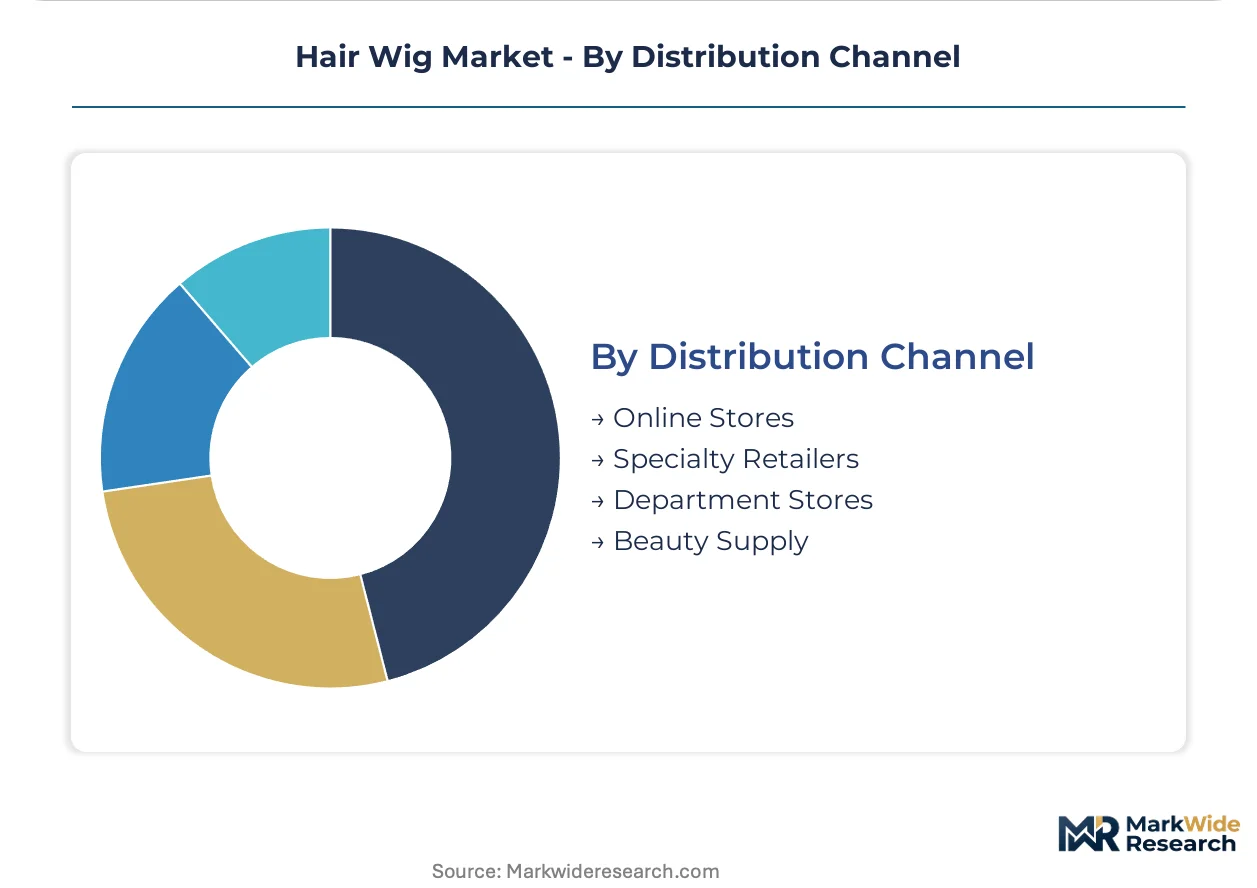
Distribution Channel:
Online penetration fragments regional distributor networks as manufacturers deploy smartphone photogrammetry for remote fitting.
- Online Stores:Direct-to-consumer brands leverage Instagram and Pinterest for discovery, offering virtual try-on through augmented reality filters. Returns management remains the primary operational challenge.
- Specialty Retailers:Dedicated wig boutiques in Brooklyn and Toronto provide private consultation rooms and medical insurance billing assistance for alopecia patients.
- Department Stores:Legacy retailers in London and Tokyo maintain beauty halls with trained fitters, though floor space allocation is compressing under e-commerce pressure.
- Beauty Supply:Independent shops in Atlanta and Houston serve African-American communities with textured hair specialists and same-day customization services.
Online stores are gaining share fastest; specialty retailers defend position through clinical partnerships and insurance navigation expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances define regional positioning. China maintains manufacturing dominance through captive raw material access. The United States absorbs premium medical-grade volumes. India supplies temple-sourced human hair while building domestic processing capacity.
United States
Oncology clinics and entertainment studios drive differentiated demand streams. FDA Class I device classification for medical wigs mandates dermatological testing and 510(k) documentation. Los Angeles anchors theatrical procurement networks serving film and television productions.
China
Henan and Shandong provinces concentrate synthetic fiber manufacturing at scale. GB standards for textile safety enforce flame-resistance thresholds that export-oriented producers must absorb. Zhengzhou-based processors backward integrate into raw hair sourcing across central provinces.
India
Temple donation cycles in Tamil Nadu and Andhra Pradesh supply premium human hair grades for export. DGFT export regulations periodically restrict unprocessed hair shipments to protect domestic value addition. Hyderabad's bridal market sustains organized retail expansion into tier-2 cities.
Japan
METI-subsidized silver economy programs reimburse medical wig procurement for alopecia patients over 65. JIS standards govern product safety for domestic distribution. Tokyo's dermatology clinics pioneer telemedicine-integrated fitting consultations.
Germany
REACH chemical disclosure mandates require full polymer traceability for synthetic fiber imports. ECHA compliance certifications enable premium positioning over non-compliant competitors. Berlin and Munich host computational lace mapping pilots for same-week chemotherapy patient fulfillment.
Hair Wig Market Vendor Landscape
Listed leaders compete with private specialists across manufacturing scale and clinical distribution reach. The vendor base separates into three tiers: multinational incumbents with regulatory certification depth, regional fabricators with raw material captive supply, and digital-native entrants with direct-to-consumer infrastructure. Strategic moves concentrate on M&A for clinical network access and capacity expansion into bio-fiber R&D.
Among Japanese and Chinese fabricators, Aderans Co., Ltd. and Henan Rebecca Hair Products Co., Ltd. exemplify divergent scale-specialist positioning. Aderans occupies the clinical distribution archetype through therapeutic segment focus. Henan Rebecca represents manufacturing-scale dominance through upstream control over raw hair sourcing. Evergreen Products Group sits within the synthetic fiber innovation tier, anchoring mid-market heat-resistant polymer development.
| Leading Market Players |
|---|
| Evergreen Products Group |
| Ruimei |
| Rebecca |
| Estetica Designs |
| Raquel Welch Wigs |
| Great Lengths |
| Anhui Jinruixiang |
| Henan Rebecca Hair Products Co., Ltd. |
| Aderans Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization in Henan and Shandong synthetic fiber plants anchors margin structures across the Hair Wig landscape, compressing unit economics for mid-market producers while elevating price floors for temple-sourced Indian human hair grades. Scale concentration in Chinese manufacturing clusters shapes competitive positioning by tethering cost structures to petrochemical input volatility and GB standard compliance burdens.
Pricing Analysis
Medical-grade purchasers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA Class I certification status and hand-knotting labor intensity, with lace front units commanding substantial premiums over machine-wefted alternatives. Cost compression in synthetic tiers is intensifying because heat-resistant polymer feedstock tracks crude oil benchmarks. Fashion-conscious consumers in China's tier-2 cities exhibit highest price sensitivity, while oncology patients in the United States show lowest sensitivity due to insurance reimbursement and dignity restoration priorities.
Supply Chain Analysis
Temple donation cycles in Tamil Nadu and Andhra Pradesh constitute a chokepoint that underwrites premium human hair availability for North American and European medical channels. Raw material dependencies draw from Indian temple networks, Burmese religious donations, and petrochemical derivatives for kanekalon filaments. Single-source vulnerability concentrates in hand-knotting artisan pools across China and Indonesia, where training pipelines lag replacement demand. Distribution runs through oncology clinic networks, specialty retail boutiques, and direct-to-consumer digital platforms with virtual try-on capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hair Wig landscape rewards actors who control scarce artisan labor pools and regulatory certification depth, with competitive advantage flowing to those who bridge manufacturing scale with clinical distribution relationships.
For Market Incumbents: Fortify backward integration into raw hair sourcing across central Chinese provinces to secure supply continuity against DGFT export restrictions. Deepen FDA 510(k) documentation capabilities and dermatological testing infrastructure to defend medical-grade positioning against synthetic bio-fiber substitutes. Expand computational lace mapping pilot programs in German and South Korean oncology clinics to collapse distributor intermediaries. For New Entrants and Emerging Players: Lead with subscription-based refresh models targeting fashion-conscious buyers in the United Kingdom and United States, trading capital expenditure for rotating inventory access. Penetrate India's tier-2 bridal markets in Hyderabad, Chennai, and Pune through direct-to-consumer digital platforms with augmented reality virtual try-on. Anchor go-to-market strategy on telemedicine-integrated fitting consultations that capture patient scalp topography data for personalized cap construction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with captive raw material supply and clinical network access. Long-term viability hinges on bio-fiber R&D intensity and 3D-printed lace cap construction capabilities. Acquisition target archetype combines synthetic fiber formulation expertise with medical-grade certification depth. Watch for inflection signals in laboratory-cultured keratin filament thermal performance parity with harvested human hair.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Fiber R&D Intensification | Laboratory-cultured keratin filaments eliminate ethical sourcing constraints while matching thermal styling performance. |
| Computational Lace Mapping Deployment | Smartphone photogrammetry compresses fulfillment timelines for chemotherapy patients in German and South Korean clinics. |
| Backward Integration into Raw Hair Sourcing | Henan-based processors secure temple-sourced Indian and Burmese hair against DGFT export restriction volatility. |
| Telemedicine Channel Integration | Dermatology platforms in the United States collapse traditional salon intermediaries and capture patient data for personalization. |
| Subscription Model Infrastructure | Styling-as-a-service platforms concentrate demand with vertically integrated brands controlling manufacturing and digital content. |
Methodological Framework
A spread of perspectives from lace front artisans, oncology clinic procurement officers, synthetic fiber R&D directors, specialty retail boutique owners, and GB standards compliance managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, FDA 510(k) filings, REACH compliance certifications, and hospital procurement databases. Bottom-up unit economics triangulated against top-down market sizing across product type, application, customer segment, and distribution channel dimensions.
Segmentation dimensions modeled include human versus synthetic hair origin, medical versus fashion versus theatrical application, retail consumer versus professional buyer archetype, and online versus specialty retail channel structure across the analysis window. CAGRs were derived from growth driver elasticity modeling and constraint boundary analysis. Industry-specific forecast inputs incorporated chemotherapy patient volume projections, temple donation cycle patterns, and petrochemical derivative pricing trajectories.
The analysis sits within stated boundaries; outcomes outside sustained FDA Class I device classification stability, DGFT export policy continuity, or heat-resistant polymer feedstock availability would require recalibration. Practitioners should keep alternative scenarios live as bio-fiber thermal performance benchmarks, REACH chemical disclosure mandate evolution, and 3D-printed cap construction adoption curves develop.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Liquid Soap Market
Beauty & Personal Care
At Home Hair Dye Market
Beauty & Personal Care
South America E-Commerce Skin Care Products Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
North America Setting Spray Market
Beauty & Personal Care
Asia-Pacific Hair Conditioner Market
Beauty & Personal Care
France Sustainable Personal Care Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
Beauty Oils Market
Beauty & Personal Care
Colombia Beauty and Personal Care Products Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
Europe Cosmetics Market