
 United Kingdom Cosmetics Products Market | 2026-2036
United Kingdom Cosmetics Products Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Cosmetics Products Market Analytics
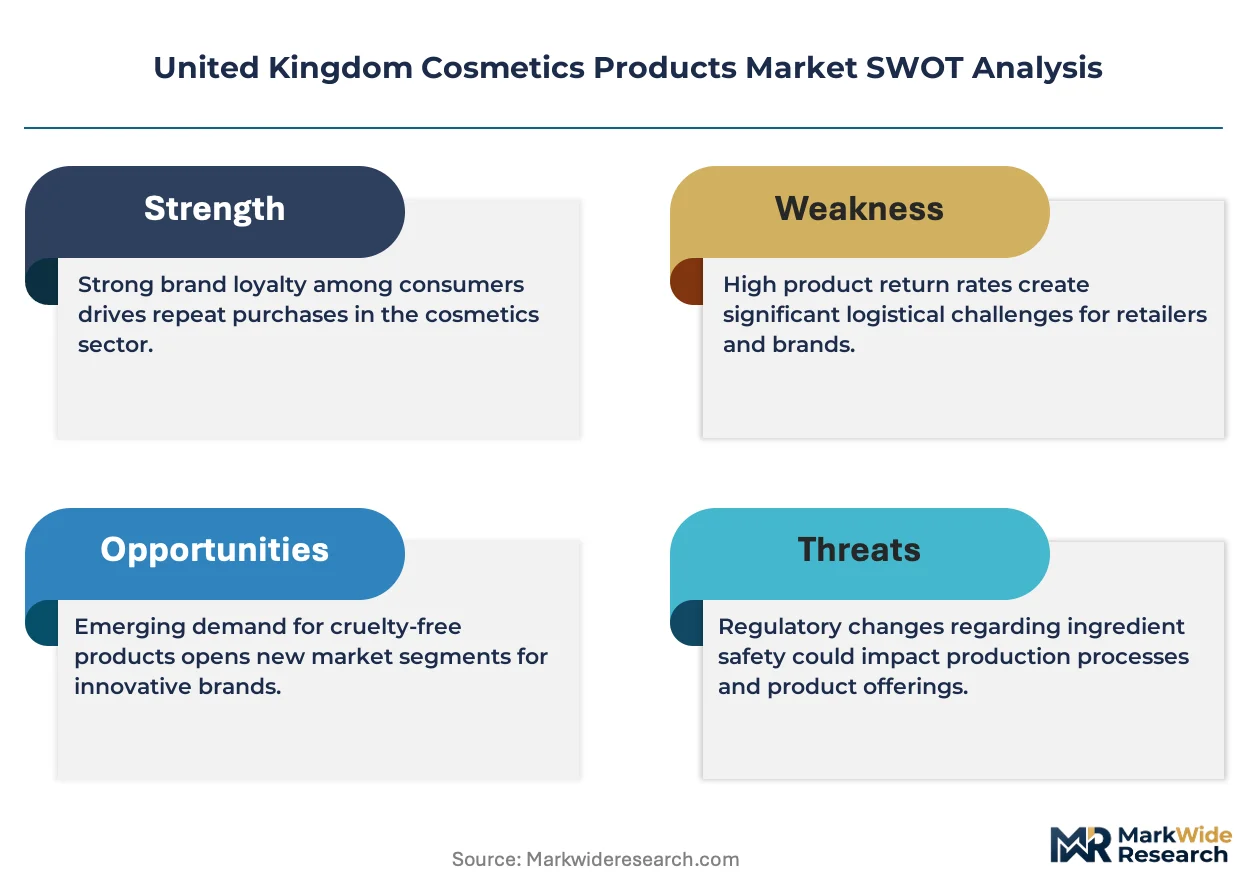
Domestic formulators in the South East is pivoting toward clean-beauty manufacturing to align with tightening ingredient standards. L'Oréal S.A. leverages its R&D footprint in Surrey to sustain innovation pipelines for prestige skincare. Unilever PLC anchors mass-market distribution through Boots UK Limited's nationwide retail network. Charlotte Tilbury Beauty Ltd differentiates through celebrity-led brand equity and direct-to-consumer channel control.
United Kingdom cosmetics products encompass topical formulations—emulsions, suspensions, and anhydrous systems—designed for skin conditioning, color modification, scent delivery, or hair fiber treatment, with stability governed by pH tolerance, preservative efficacy, and rheological behavior. Skincare leads value contribution as consumers prioritize barrier-repair and active-ingredient transparency, while fragrance experiences slower volume growth amid post-pandemic habit shifts. Online Retail captures the fastest-growing distribution channel as algorithm-driven personalization and subscription replenishment models reshape repurchase behavior.
REACH, the UK Cosmetics Regulation (retained EU law post-Brexit), and the Competition and Markets Authority's green-claims scrutiny collectively elevate compliance costs and reshape formulation priorities for UK-based manufacturers. The Medicines and Healthcare products Regulatory Agency monitors borderline cosmetic-therapeutic claims, constraining marketing language around anti-aging efficacy. Stakeholders must weigh the trade-off between reformulation investment for regulatory continuity and portfolio simplification to reduce SKU complexity across diverging UK-EU standards.
Market Dynamics
Professional women in Greater London and the South East are accelerating premium skincare adoption, tightening the link between disposable income concentration and formulation innovation pipelines. REACH spillover and the EU Green Deal's ingredient disclosure requirements are compressing reformulation cycles for domestic manufacturers.
Growth Catalysts
- REACH Compliance Alignment:Retained EU law post-Brexit mandates granular substance disclosure, forcing formulators to document supply chain chemistry. This transparency push rewards early movers with retailer shelf access.
- Algorithmic Personalization:Online Retail channels deploy machine learning for skin-type matching and subscription replenishment, capturing repurchase loyalty through data-driven recommendation engines.
- Greater London Demand Density:Higher disposable incomes in the capital and South East sustain luxury beauty spending, concentrating volume in premium skincare and fragrance categories.
Market Restraints
- Regulatory Divergence Friction:Post-Brexit divergence between UK Cosmetics Regulation and EU REACH creates dual compliance burdens for exporters, elevating SKU management complexity.
- Preservative Efficacy Constraints:Clean-beauty consumer preferences restrict traditional preservative options, narrowing formulation stability windows and shortening product shelf life.
- Raw Material Concentration:Specialty active ingredient supply concentrates in German and Swiss chemical clusters, exposing UK formulators to euro-denominated input volatility and logistics bottlenecks.
Strategic Opportunities
- Barrier-Repair Formulation White Space:Underpenetrated men's grooming segments in Northern England and Scotland present expansion vectors for gender-neutral skincare positioning.
- Direct-to-Consumer Channel Control:Owned digital storefronts bypass Boots UK Limited's mass-market gatekeeping, enabling margin capture and first-party data accumulation.
- MHRA Borderline Claim Navigation:The Medicines and Healthcare products Regulatory Agency's cosmetic-therapeutic boundary enforcement creates competitive moats for brands with regulatory affairs capabilities.
Industry Challenges
- Green Claims Scrutiny:The Competition and Markets Authority's enforcement against unsubstantiated sustainability marketing demands evidentiary infrastructure that mid-tier brands lack.
- Reformulation Capex Burden:Clean-beauty pivoting requires investment in alternative emulsifier and preservative systems, straining R&D budgets without guaranteed volume lift.
- Rheological Behavior Expertise Gap:Formulation chemists capable of engineering anhydrous systems and suspension stability command premium compensation, constraining talent pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Cosmetics Products Market |
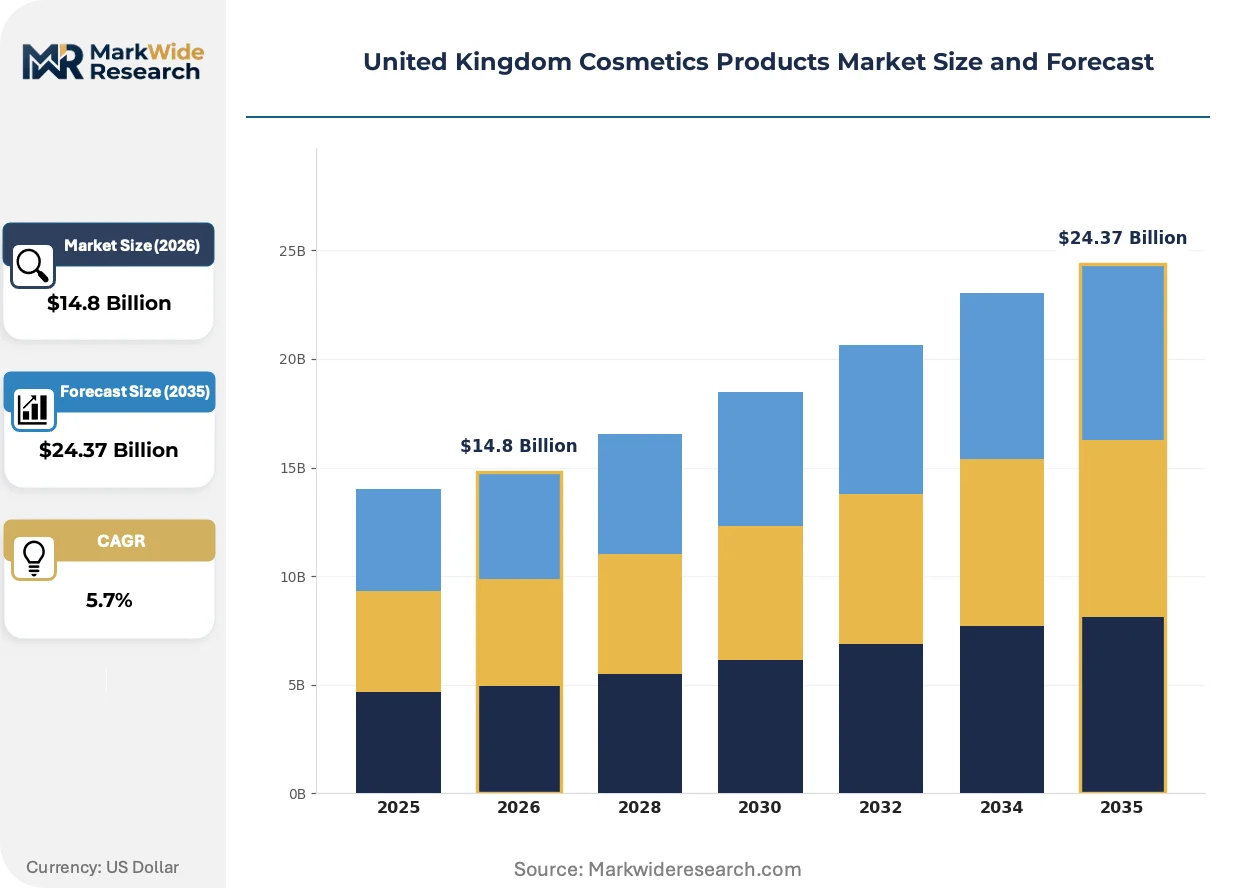
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Fragrance, Haircare Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Pharmacies Customer Type: Men, Women, Teenagers, Professionals Price Tier: Premium, Mid-range, Economy, Mass Market |
| Companies Covered | L'Oréal S.A., Unilever PLC, Procter & Gamble Co., Estée Lauder Companies Inc., Coty Inc., Boots UK Limited, The Body Shop International Limited, Charlotte Tilbury Beauty Ltd, Beiersdorf AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Cosmetics Products Market Evolving Landscape
Biotechnology-derived actives and AI-powered skin diagnostics are compressing the gap between clinical efficacy claims and consumer-accessible products. Formulators now balance microbiome science with regulatory conservatism.
Biotechnology is modularizing active ingredient production for UK formulators. Precision fermentation and enzymatic synthesis now yield peptides and ceramides previously extracted from botanicals. Premium skincare brands in Surrey and London adopt these bio-identical molecules to substantiate barrier-repair claims. This modularizing production architecture shortens development timelines from eighteen months to under nine.
REACH and the UK Cosmetics Regulation jointly elevate post-Brexit compliance documentation requirements. The retained EU law mandates safety assessor sign-off and nanomaterial notification, adding fixed costs per SKU. Mass-market manufacturers respond by consolidating fragrance and color cosmetic portfolios to reduce regulatory surface area.
Subscription replenishment models displace traditional retail repurchase cycles for skincare consumers. Algorithm-driven personalization engines at direct-to-consumer brands now predict serum and moisturizer depletion dates. This behavioral shift concentrates lifetime value in owned channels, most visible among professional women aged 28-42 in Greater London who prioritize convenience over in-store sampling.
United Kingdom Cosmetics Products Market Segmentation
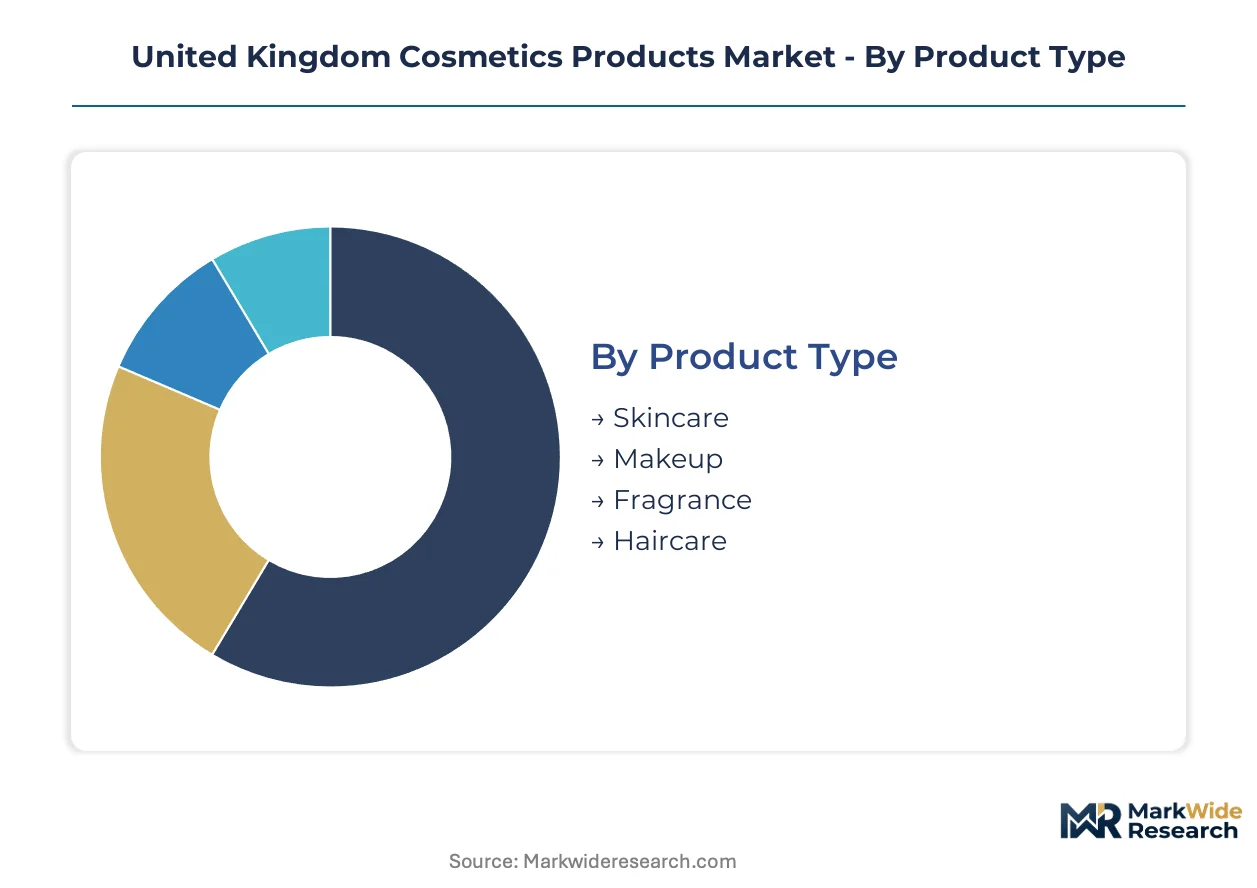
Segmentation in the United Kingdom cosmetics products market reveals how formulation complexity, channel control, and professional buyer concentration reshape competitive positioning. Distinct upgrade cycles operate across skincare replenishment, fragrance gifting, and algorithm-driven online discovery.
Product Type:
Replacement cycles vary sharply across topical categories, with daily-use formulations demanding faster replenishment than discretionary color cosmetics.
- Skincare:Emulsions, serums, and barrier-repair formulations dominate value contribution as consumers prioritize active-ingredient transparency and microbiome science. Professional women in Greater London and the South East sustain premium adoption, tightening the link between disposable income density and clinical-positioned SKUs.
- Makeup:Color modification products span foundations, lip formulations, and eye cosmetics with formulation stability governed by pigment dispersion and rheological behavior. Post-pandemic habit shifts have compressed volume in traditional color cosmetics while elevating hybrid skincare-makeup positioning.
- Fragrance:Scent delivery systems concentrate gifting demand around seasonal peaks with slower replenishment cycles than daily-use categories.
- Haircare:Fiber treatment formulations for conditioning and styling operate on mass-market replenishment rhythms through Boots UK Limited's nationwide network.
Volume placements concentrate in Skincare; the faster expansion belongs to barrier-repair and active-ingredient transparent formulations within that category.
Distribution Channel:
Channel economics diverge on data ownership, with controlled digital storefronts capturing margin and first-party accumulation that mass retail gatekeeping restricts.
- Supermarkets:Mass-market shampoo and body wash SKUs move through high-frequency grocery trips with price-driven switching behavior.
- Specialty Stores:Curated beauty retail in London's West End and Manchester's Trafford Centre enables sensory sampling for fragrance and color cosmetics.
- Online Retail:Algorithm-driven personalization engines and subscription replenishment models reshape repurchase loyalty. Machine learning skin-type matching concentrates lifetime value among professional women aged 28-42 in Greater London who prioritize convenience.
- Pharmacies:Boots UK Limited anchors dermocosmetic distribution with pharmacist-adjacent credibility for sensitive-skin positioning.
Margin capture concentrates in Online Retail; the steepest expansion trajectory belongs to subscription-enabled owned channels bypassing traditional gatekeepers.
Customer Type:
Buyer archetypes segment on usage intensity, professional identity, and willingness to navigate ingredient disclosure complexity.
- Women:Core demand anchors across all price tiers with professional cohorts in the South East driving premium skincare volume.
- Professionals:Time-constrained buyers aged 28-42 in Greater London exhibit highest subscription adoption and algorithmic personalization responsiveness.
- Men:Underpenetrated grooming segments in Northern England and Scotland present expansion vectors for gender-neutral barrier-repair positioning.
- Teenagers:TikTok-influenced discovery patterns concentrate in affordable color cosmetics with rapid trend turnover.
Value concentration sits with Women; the climbing-fastest cohort is Professionals migrating to subscription-enabled convenience.
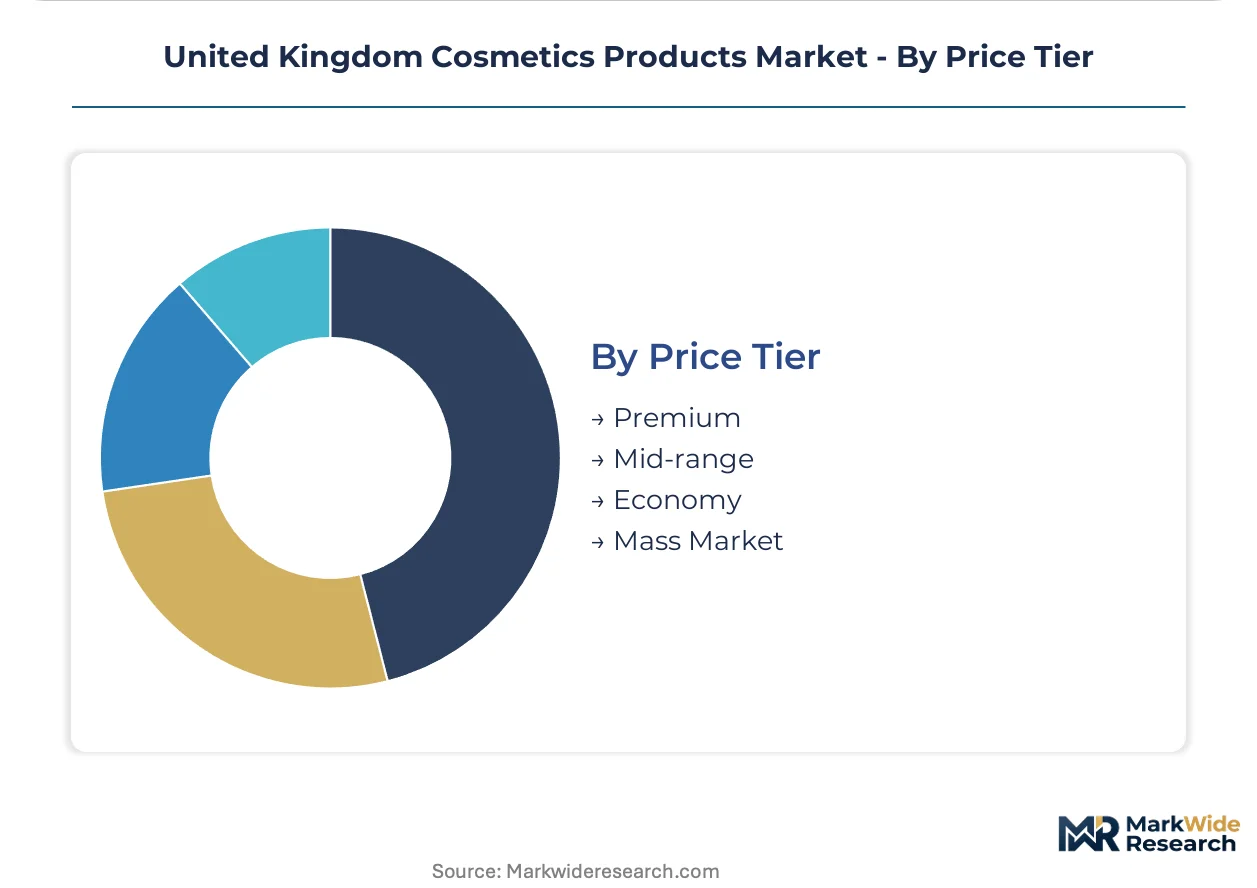
Price Tier:
Pricing stratification reflects formulation R&D intensity, supply chain transparency investment, and regulatory documentation burden.
- Premium:Biotechnology-derived actives from precision fermentation and enzymatic synthesis command price premiums. Surrey-based R&D footprints and MHRA borderline claim navigation capabilities sustain positioning.
- Mid-range:Accessible clinical credibility without full prestige markup captures professional women seeking efficacy evidence.
- Economy:Basic emulsion stability and conventional preservative systems serve price-sensitive replenishment in supermarket channels.
- Mass Market:High-volume fragrance and color cosmetic portfolios face consolidation pressure as REACH compliance adds fixed costs per SKU.
Investment intensity concentrates in Premium; the gaining-share-fastest tier is Mid-range as clinical credibility democratizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty active ingredient supply concentrates in German and Swiss chemical clusters, exposing UK formulators to euro-denominated input volatility and logistics bottlenecks. Domestic manufacturing pivots toward clean-beauty production to align with tightening REACH standards.
Greater London and South East
Professional women aged 28-42 drive premium skincare volume through subscription-enabled direct-to-consumer channels. The UK Cosmetics Regulation mandates safety assessor sign-off and nanomaterial notification, adding fixed costs per SKU. Surrey-based R&D footprints from multinational laboratories anchor biotechnology-derived active innovation for barrier-repair formulations.
Midlands
Mass-market manufacturing clusters serve Boots UK Limited's nationwide distribution network with conventional emulsion stability systems. The Competition and Markets Authority's green-claims scrutiny demands evidentiary infrastructure that mid-tier brands struggle to assemble. Birmingham and Leicester production facilities face consolidation pressure as REACH compliance elevates regulatory surface area.
North England
Underpenetrated men's grooming segments present expansion vectors for gender-neutral barrier-repair positioning. The Medicines and Healthcare products Regulatory Agency monitors borderline cosmetic-therapeutic claims, constraining marketing language. Manchester's Trafford Centre enables sensory sampling for fragrance and color cosmetics through curated beauty retail.
Scotland
Edinburgh and Glasgow concentrate demand for accessible clinical credibility without full prestige markup. The retained EU law post-Brexit creates dual compliance burdens for exporters targeting continental markets. Domestic formulators navigate preservative efficacy constraints as clean-beauty preferences restrict traditional options.
Wales and Northern Ireland
Economy-tier replenishment rhythms dominate through supermarket channels with price-driven switching behavior. Regulatory divergence friction between UK and EU standards elevates SKU management complexity for cross-border operators. Belfast and Cardiff distribution nodes handle bulk fragrance and haircare logistics for value-conscious segments.
United Kingdom Cosmetics Products Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer algorithmic personalization. The market structures around three tiers: multinational conglomerates with integrated R&D footprints, mid-range clinical credibility players, and specialty clean-beauty challengers. Strategic archetypes include biotechnology-anchored premium formulators, mass-market gatekeeper-dependent manufacturers, and owned-channel subscription specialists. Dominant competitive moves encompass portfolio consolidation to reduce regulatory surface area and backward integration into precision fermentation capabilities.
Within the multinational tier, L'Oréal S.A. and Unilever PLC exemplify divergent scale strategies. L'Oréal S.A. occupies a position emphasizing Surrey-based innovation pipelines for prestige skincare. Unilever PLC anchors mass-market distribution architecture through nationwide retail partnerships. Charlotte Tilbury Beauty Ltd represents the owned-channel archetype, leveraging direct-to-consumer control for margin capture and first-party data accumulation.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Unilever PLC |
| Procter & Gamble Co. |
| Estée Lauder Companies Inc. |
| Coty Inc. |
| Boots UK Limited |
| The Body Shop International Limited |
| Charlotte Tilbury Beauty Ltd |
| Beiersdorf AG |
| Others |
Value Network & Pricing Analysis
REACH compliance documentation and the EU Green Deal's ingredient disclosure spillover gates both qualified supply access and premium-tier pricing eligibility for UK formulators. Brands lacking safety assessor sign-off and nanomaterial notification infrastructure face exclusion from retailer shelf space while clean-beauty positioning commands margin premiums.
Pricing Analysis
Subscription bundling of replenishment cycles with algorithmic skin diagnostics separates premium direct-to-consumer pricing from unbundled supermarket transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by biotechnology-derived active inclusion and MHRA borderline claim navigation capabilities. Price differentiation hinges on certification grade—REACH-compliant formulations with full supply chain chemistry documentation sustain premiums while economy tiers face cost compression from preservative efficacy constraints. Professional women in Greater London exhibit lowest price sensitivity through subscription loyalty, whereas Northern England supermarket shoppers drive switching behavior.
Supply Chain Analysis
REACH safety assessor certification and nanomaterial notification requirements gate supplier qualification for UK manufacturers. Specialty active ingredient supply draws from German and Swiss chemical clusters, exposing formulators to euro-denominated input volatility. Biotechnology-derived peptides, ceramides from precision fermentation, and alternative emulsifier systems anchor raw material dependencies. Single-source vulnerability concentrates in enzymatic synthesis capabilities. Distribution runs through Boots UK Limited's nationwide pharmacy network for mass-market dermocosmetics and owned digital storefronts for premium subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into precision fermentation capabilities is reshaping competitive positioning as brands race to secure captive supply of biotechnology-derived actives and compress development timelines.
For Market Incumbents: Cement regulatory affairs capabilities as a defensive moat by expanding MHRA borderline claim navigation expertise. Consolidate fragrance and color cosmetic portfolios to reduce REACH compliance surface area. Backward integration into Surrey-based R&D footprints sustains innovation pipelines against emerging clean-beauty challengers with direct-to-consumer channel control.
For New Entrants and Emerging Players: Specialty retailers in Manchester's Trafford Centre and Edinburgh's George Street enable sensory sampling entry points for fragrance and hybrid skincare-makeup positioning. Underpenetrated men's grooming segments in Northern England and Scotland present the most penetrable white space for gender-neutral barrier-repair formulations. Algorithmic personalization engines deployed through owned digital storefronts bypass Boots UK Limited's gatekeeping.
For Investors and Strategic Acquirers: MHRA enforcement actions against unsubstantiated cosmetic-therapeutic claims are the leading indicator that regulatory affairs capabilities will separate viable acquisition targets from stranded assets. Long-term viability over the next decade rests on precision fermentation backward integration and subscription-enabled customer lifetime value concentration. Target mid-range clinical credibility players with evidentiary infrastructure for green claims substantiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Fermentation | Captive supply of bio-identical ceramides and peptides compresses development timelines from eighteen months to under nine. |
| Direct-to-Consumer Channel Launch | Owned digital storefronts accumulate first-party data from professional women aged 28-42 in Greater London. |
| Regulatory Affairs Capability Buildout | MHRA borderline claim navigation expertise creates competitive moats against green-claims scrutiny enforcement. |
| Portfolio Consolidation | Fragrance and color cosmetic SKU reduction lowers fixed REACH compliance costs per unit. |
| Subscription Replenishment Model Deployment | Algorithm-driven depletion prediction concentrates lifetime value and displaces traditional retail repurchase cycles. |
Research Methodology
Multi-period observation of REACH compliance cost trajectories, subscription adoption rates, and biotechnology active ingredient pricing anchored the trend analysis, supplemented by interviews with formulation chemists, regulatory affairs directors at Surrey-based R&D facilities, Boots UK Limited category buyers, and precision fermentation technology suppliers. Secondary validation drew from UK Cosmetics Regulation guidance documents, Competition and Markets Authority green-claims enforcement records, MHRA borderline determination rulings, and trade customs data for specialty chemical imports. Bottom-up SKU-level volume modeling and top-down macroeconomic demand assessment were triangulated against channel-specific growth patterns.
Input-output matrices mapped formulation R&D intensity, channel margin structures, and regional disposable income concentration against projected demand across the analysis window. Segmentation dimensions encompassed product type, distribution channel, customer archetype, and price tier with biotechnology adoption intensity as an industry-specific overlay. CAGRs were derived from regression analysis of historical replenishment cycle compression and algorithmic personalization penetration rates, incorporating REACH documentation burden escalation and clean-beauty preference shifts as structural modifiers.
Caveats apply where regulatory divergence between UK and EU standards, euro-denominated input volatility, or preservative efficacy constraint breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions regarding professional women's subscription stickiness and biotechnology cost curves. A model refresh is warranted upon material change in MHRA enforcement intensity or precision fermentation capacity expansion announcements from German and Swiss chemical clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
United Kingdom Dermocosmetics Market
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Cosmetic Wax Market
Beauty & Personal Care
Beauty Salon Market
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Saudi Arabia Body Care and Personal Hygiene Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Depilatories Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Hair Gel Market
Beauty & Personal Care
Eyelash Curler Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
Global Massage Oil Market