
 Europe and Asia Pacific Herbal Beauty Products Market | 2026-2036
Europe and Asia Pacific Herbal Beauty Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe and Asia Pacific Herbal Beauty Products Market Foresight
Subscription-based replenishment programs for herbal skincare routines is broadening how brands monetize recurring consumer relationships. Dabur India Ltd leverages its ayurvedic heritage to anchor portfolio depth across hair oils and skin serums. Weleda sustains European market presence through biodynamic certification and controlled retail distribution. Himalaya Global Holdings Ltd competes on pharmacy-channel density across Indian metros and Southeast Asian expansion markets.
Herbal beauty products comprise topical formulations derived from botanically sourced active ingredients, typically preserved through cold-press extraction or ethanol-free stabilization to maintain phytochemical integrity, serving cosmetic and dermatological functions with reduced synthetic additive loads. Face masks and serums carry premium positioning due to concentrated actives and shorter replenishment cycles, while hair oils retain volume leadership in South Asian markets through ritual usage patterns. Online retail channels capture accelerating traffic as ingredient transparency tools and AI-driven skin diagnostics reduce purchase friction for first-time herbal converts.
EMA cosmetic ingredient guidelines and REACH chemical safety protocols govern European formulation standards, while India's CDSCO and BIS frameworks regulate ayurvedic product claims and manufacturing site licensing across the Asia Pacific corridor. ECHA's expanded allergen disclosure requirements force reformulation investments that favor established players with dedicated regulatory affairs teams. Stakeholders must monitor divergence between European precautionary principles and Asia Pacific traditional medicine recognition frameworks when allocating R&D and compliance budgets.
Market Dynamics
ECHA's expanded allergen disclosure mandates under REACH are forcing wholesale reformulation across European herbal beauty portfolios, compressing product development timelines and favoring incumbents with dedicated regulatory infrastructure.
Growth Catalysts
- REACH compliance investments:European manufacturers accelerating clean-label certifications capture premium shelf positioning in German and French pharmacy networks as disclosure standards tighten.
- Seoul-Mumbai digital corridor:Urban consumers in these metropolitan clusters drive subscription adoption for ayurvedic skincare routines through mobile-first replenishment platforms.
- Cold-press extraction scale-up:Processing technology advances reduce phytochemical degradation in botanical actives, enabling concentrated serum formulations that command higher unit economics.
Market Restraints
- Wild-harvested botanical supply concentration:Dependence on Himalayan and Western Ghats sourcing regions for rare adaptogenic extracts creates weather-linked input volatility.
- Biodynamic certification timelines:Weleda-style certification protocols require 3-5 year farm conversion periods, capping supply elasticity for premium-tier positioning.
- Synthetic peptide substitution threat:Lab-engineered collagen boosters from Korean biotech firms undercut herbal retinol alternatives on efficacy-per-unit-cost metrics.
Strategic Opportunities
- Indonesian archipelago penetration:Underdeveloped pharmacy-channel density across Jakarta and Surabaya offers first-mover expansion space for ayurvedic hair oil portfolios.
- AI-driven skin diagnostics convergence:Integration of machine-learning diagnostic tools with herbal recommendation engines reduces purchase friction for first-time category entrants.
- CDSCO traditional medicine recognition:India's streamlined ayurvedic product licensing creates regulatory tailwind for export-oriented manufacturers targeting Southeast Asian markets.
Industry Challenges
- Phytochemistry analytical talent scarcity:Shortage of formulation chemists trained in ethanol-free stabilization methods slows R&D pipeline velocity for mid-tier players.
- BIS manufacturing site licensing backlogs:Multi-year approval queues for new ayurvedic production facilities in India constrain capacity expansion timelines.
- Legacy ERP integration friction:Batch-level ingredient traceability requirements under ECHA force costly supply chain software upgrades for established European manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe and Asia Pacific Herbal Beauty Products Market |
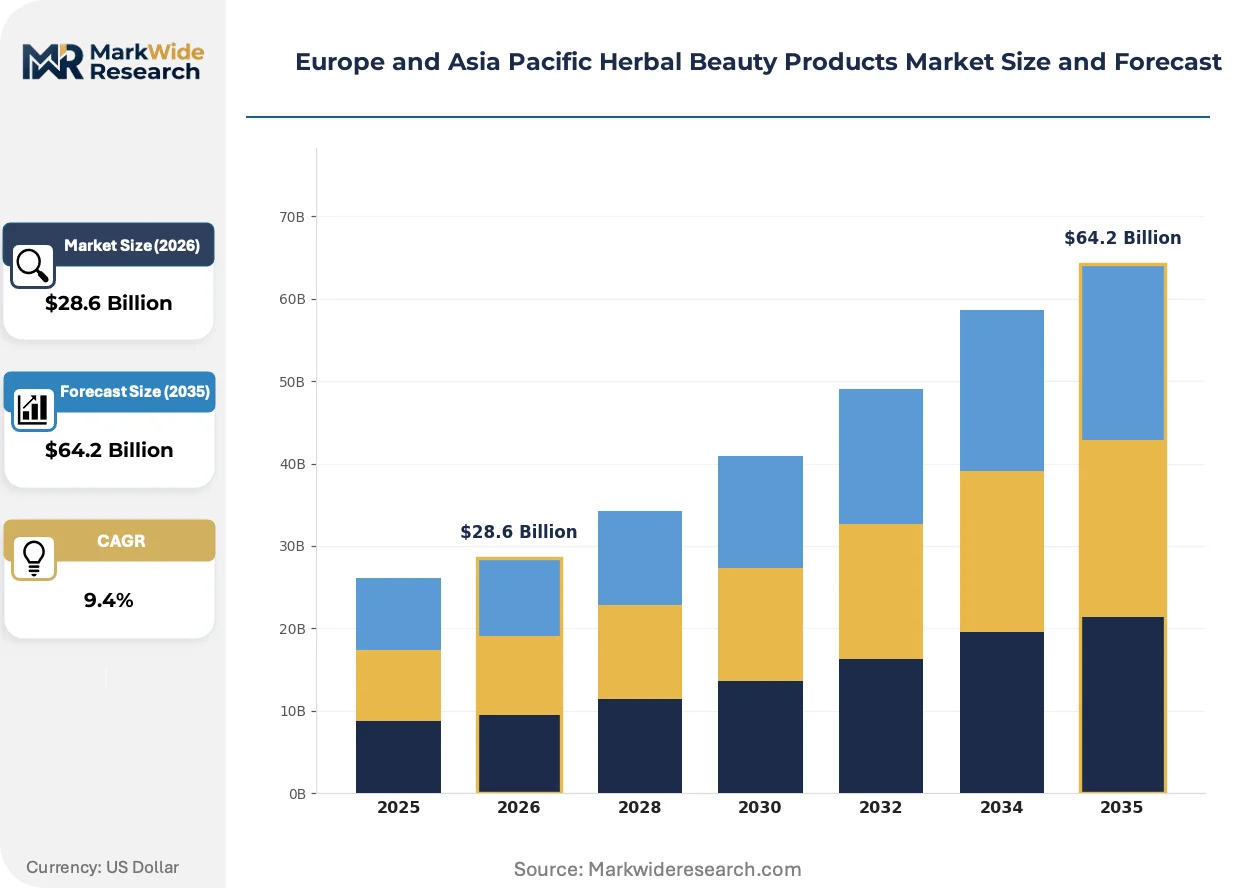
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Face Masks, Hair Oils, Body Scrubs, Serums Ingredient: Aloe Vera, Green Tea, Lavender, Chamomile Application: Moisturizing, Anti-Aging, Cleansing, Exfoliating Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Bio Veda Action Research Co., VLCC Personal Care Ltd., Surya Brasil, Dabur India Ltd, Himalaya Global Holdings Ltd, Lotus Herbals, Hemas Holdings Plc, Sheahnaz Herbals Inc., Weleda, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe and Asia Pacific Herbal Beauty Products Market Shifts & Advancements
Formulation science and distribution infrastructure are converging to reshape how botanical actives reach end consumers, with transparency tools and diagnostic technologies compressing traditional purchase cycles.
Biomimetic encapsulation technology is unifying lipid-delivery systems with cold-press botanical extracts to enhance dermal penetration of polyphenol actives. Premium serum manufacturers in Germany and South Korea are adopting these systems at accelerated pace to differentiate concentrated formulations. This convergence is compressing efficacy gaps between herbal and synthetic alternatives while preserving clean-label positioning.
REACH Annex III allergen expansion rules now mandate disclosure of 82 additional fragrance compounds in leave-on cosmetic products. European formulators are stripping complex essential oil blends from facial moisturizers and reconstituting simpler scent profiles with synthetic-free isolates. Color cosmetics and fragrance-heavy skin serums face the steepest compliance costs, with German natural cosmetics specialists leading reformulation investment.
Subscription replenishment models are displacing traditional retail stocking patterns for core skincare routines. Direct-to-consumer channels in Mumbai and Seoul capture recurring revenue through AI-curated product rotations based on seasonal skin condition shifts. This behavioral pivot concentrates lifetime value capture among digitally native urban demographics while reducing pharmacy-channel dependency for established herbal brands.
Europe and Asia Pacific Herbal Beauty Products Market Segmentation
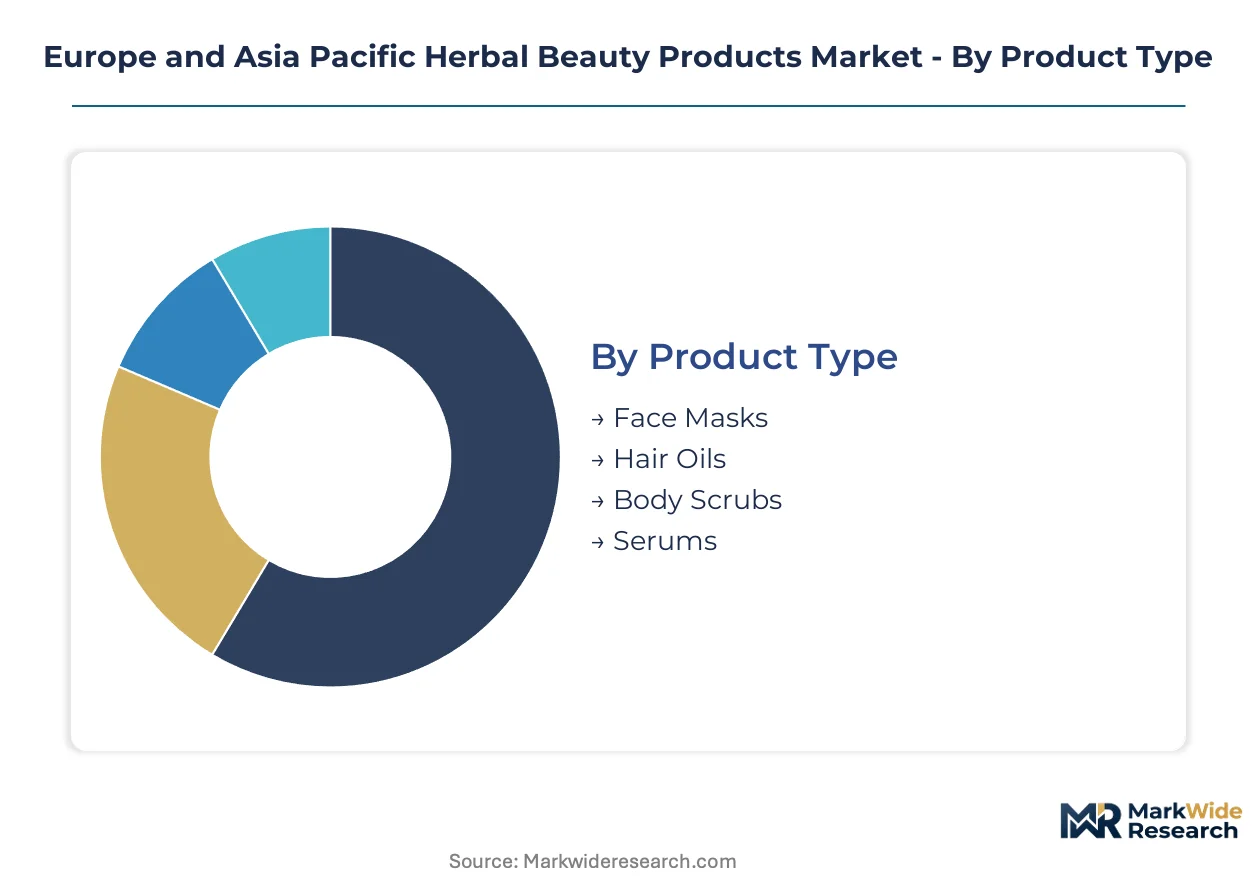
Herbal beauty markets fragment along ritual usage patterns and ingredient provenance, with premium capture concentrating where cold-press extraction meets pharmacy-channel density. Segmentation discipline separates volume-driven hair care from margin-accretive facial treatments.
Product Type:
Purchase frequency and unit economics diverge sharply between daily-use staples and occasion-driven treatments.
- Face Masks:Concentrated polyphenol formulations delivered through biomimetic encapsulation systems command premium positioning in Seoul's subscription channels. German pharmacy networks favor sheet-mask formats with ECHA-compliant allergen disclosure.
- Hair Oils:Cold-pressed ayurvedic blends anchor volume leadership through ritual application patterns across Mumbai and Jakarta metro corridors. Coconut-sesame infusions retain household penetration advantages over serum alternatives.
- Body Scrubs:Sugar-coffee exfoliants with ethanol-free preservation target spa-channel distribution in Bangkok and Kuala Lumpur wellness circuits.
- Serums:Low-molecular-weight hyaluronic acid pairings with botanical actives concentrate R&D investment among Korean biotech formulators.
Volume sits with Hair Oils; growth tilts toward Serums.
Ingredient:
Supply geography and extraction method determine cost structure and clean-label credibility.
- Aloe Vera:Rajasthan and Gujarat cultivation belts feed industrial-scale processing for moisturizer bases. REACH-compliant dehydration protocols favor integrated manufacturers with captive farm networks.
- Green Tea:EGCG retention through sub-critical water extraction commands antioxidant positioning in Japanese and South Korean premium tiers.
- Lavender:Provence and Bulgarian sourcing regions face ECHA allergen disclosure pressure on linalool content, compressing formulation flexibility.
- Chamomile:German biodynamic certification requirements stretch supply timelines for Weleda-tier positioning.
Supply concentrates in Aloe Vera; steepest expansion trajectory belongs to Green Tea.
Application:
Functional claims alignment with regulatory recognition frameworks shapes geographic deployment.
- Moisturizing:Glycerin-herbal hybrid formulations dominate mass-market penetration across Indian tier-2 cities with CDSCO-compliant hydration claims.
- Anti-Aging:Retinol-alternative positioning with bakuchiol and Centella asiatica extracts captures Seoul's dermatology-channel recommendations.
- Cleansing:pH-balanced micellar waters with chamomile infusion displace synthetic surfactants in French pharmacy networks.
- Exfoliating:Enzymatic papaya- pineapple blends avoid physical microbead restrictions under REACH microplastic protocols.
Moisturizing commands current volume; Anti-Aging gains share fastest.
Distribution Channel:
Channel selection determines customer acquisition cost and lifetime value capture mechanics.
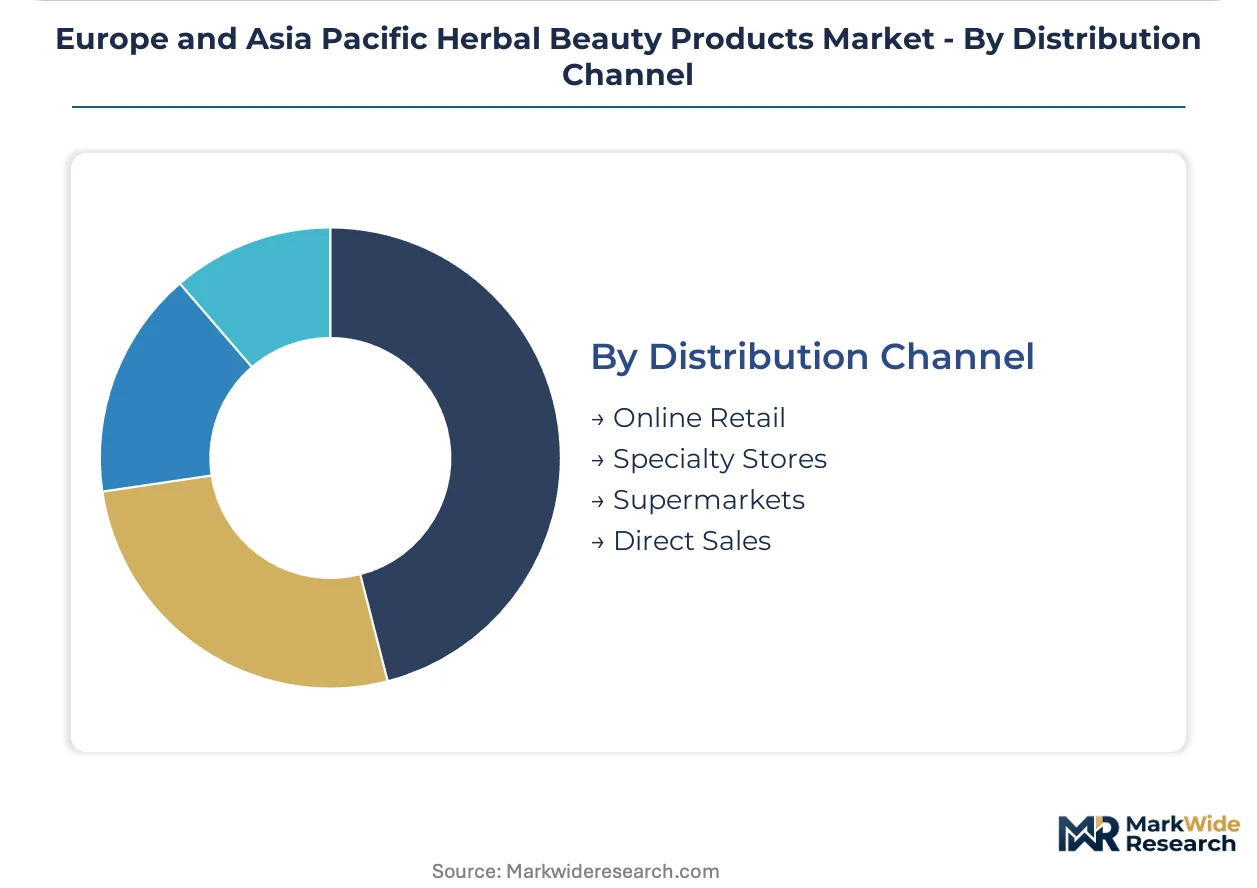
- Online Retail:AI-driven skin diagnostics and subscription replenishment platforms reduce purchase friction for first-time herbal converts in Mumbai and Seoul digital corridors.
- Specialty Stores:Biodynamic certification storytelling and controlled sensory experiences sustain Weleda-style premium positioning across German urban centers.
- Supermarkets:Mass-market aloe vera and coconut oil SKUs leverage existing FMCG distribution density across Indian metropolitan regions.
- Direct Sales:Ayurvedic practitioner networks and salon-channel recommendations retain importance for hair oil ritual education in South Asian markets.
Supermarkets hold installed base; Online Retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul and Mumbai anchor digital-native demand corridors for herbal beauty adoption, with subscription platforms capturing recurring revenue from urban millennials. European regulatory tightening under REACH and ECHA standards reshapes formulation economics across German and French pharmacy networks.
Germany
Biodynamic certification requirements stretch supply timelines for premium-tier positioning. ECHA's expanded allergen disclosure mandates under REACH force reformulation investments across natural cosmetics portfolios. The Baden-Württemberg region concentrates Weleda-style controlled retail distribution and pharmacy-channel density.
India
Ayurvedic hair oil rituals drive volume leadership through household replenishment patterns across metropolitan corridors. CDSCO streamlined licensing for traditional medicine exports creates regulatory tailwinds for manufacturers targeting Southeast Asian markets. Maharashtra and Gujarat cultivation belts feed industrial-scale aloe vera processing for moisturizer bases.
South Korea
AI-driven skin diagnostics convergence reduces purchase friction for first-time herbal converts in subscription channels. MFDS cosmetic safety standards govern botanical active claims and manufacturing site protocols. Seoul Capital Area biotech formulators concentrate R&D investment in low-molecular-weight hyaluronic acid pairings with botanical actives.
France
pH-balanced micellar waters with chamomile infusion displace synthetic surfactants in pharmacy networks. ANSM cosmetic ingredient guidelines align with EMA standards for botanical extract safety assessments. Provence lavender sourcing regions face ECHA allergen disclosure pressure on linalool content, compressing formulation flexibility.
Indonesia
Underdeveloped pharmacy-channel density across Jakarta and Surabaya offers first-mover expansion space for ayurvedic hair oil portfolios. The country's national pharmaceutical regulator maintains import licensing requirements for herbal cosmetic claims. Javanese and Sumatran urban corridors demonstrate accelerating traffic through mobile-first replenishment platforms.
Europe and Asia Pacific Herbal Beauty Products Market Competitive Landscape
Capital-heavy producers with captive farm networks and integrated extraction facilities compete with asset-light brand designers outsourcing manufacturing to third-party ayurvedic processors. The market structure tilts toward incumbents with dedicated regulatory affairs teams capable of navigating ECHA reformulation timelines. Three archetypes dominate: heritage ayurvedic houses with ritual usage moats, European biodynamic specialists with certification premiums, and digital-native direct-to-consumer platforms with AI-curated subscription mechanics. Competitive moves concentrate on pharmacy-channel density expansion and cold-press extraction scale-up partnerships.
Within the heritage ayurvedic tier, Dabur India Ltd and Himalaya Global Holdings Ltd anchor portfolio depth across hair oils and skin serums through pharmacy-channel density. Weleda occupies a position exemplifying European biodynamic certification premiums through controlled retail distribution. These three represent the dominant competitive archetypes: ritual-usage heritage, certification-driven premium positioning, and channel-density scale.
| Leading Market Players |
|---|
| Bio Veda Action Research Co. |
| VLCC Personal Care Ltd. |
| Surya Brasil |
| Dabur India Ltd |
| Himalaya Global Holdings Ltd |
| Lotus Herbals |
| Hemas Holdings Plc |
| Sheahnaz Herbals Inc. |
| Weleda |
| Others |
Supply & Pricing Matrix
Cold-press extraction equipment depreciation flows through premium serum unit costs into biodynamic-tier price positioning, while wild-harvested adaptogen scarcity in Himalayan corridors compresses margin structures for mid-market hair oil formulators.
Pricing Analysis
Value-based pricing anchors on phytochemical potency certification and ECHA-compliant allergen disclosure tiers. Three-tier pricing structure across biodynamic-certified, clean-label verified, and mass-market unverified levels separates Weleda-tier positioning from Dabur-style volume plays. Cost compression in standard-tier facial moisturizers is intensifying because REACH Annex III reformulation investments concentrate among established players with dedicated regulatory affairs teams. Pharmacy-channel buyers in Germany exhibit lowest price sensitivity; supermarket shoppers across Indian tier-2 cities demonstrate highest elasticity.
Supply Chain Analysis
Return flows of expired serum inventory from subscription channels feed into ethanol-free reprocessing for secondary-grade body scrub formulations. Wild-harvested ashwagandha and gotu kola concentrates draw from Himalayan foothills and Western Ghats monsoon belts. Cold-press jojoba and argan oil inputs rest on Moroccan and Rajasthan cultivation networks. Single-source vulnerability concentrates around rare adaptogenic extracts from high-altitude sourcing regions. Distribution runs through pharmacy-channel density in German urban centers and mobile-first replenishment platforms across Mumbai and Seoul corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating as ECHA reformulation timelines force mid-tier players without captive regulatory infrastructure toward exit or acquisition.
For Market Incumbents: Hedge synthetic peptide substitution risk by accelerating bakuchiol and Centella asiatica R&D partnerships with Seoul-based biotech formulators. Deepen backward integration into Rajasthan aloe vera cultivation belts to secure REACH-compliant dehydration capacity. Channel control through pharmacy-density expansion in Jakarta and Surabaya offers defensive moat construction against digital-native entrants.
For New Entrants and Emerging Players: Enter via underdeveloped pharmacy-channel density across Indonesian archipelago urban corridors where ayurvedic hair oil ritual education remains nascent. Target AI-curated subscription mechanics in Seoul's dermatology-adjacent digital channels as the most penetrable entry vector. Anchor go-to-market positioning through MFDS-compliant manufacturing partnerships that bypass multi-year BIS licensing queues.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap ayurvedic processors with captive Western Ghats sourcing networks and stalled CDSCO export licensing applications. Long-term viability hinges on regulatory affairs team depth and cold-press extraction asset ownership across the projection horizon. Watch for ECHA allergen disclosure enforcement intensity as inflection signal for premium-tier margin compression severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodynamic Certification Investment | 3-5 year farm conversion timelines lock in Weleda-tier pricing premiums across German pharmacy networks. |
| Cold-Press Extraction Scale-Up | Phytochemical integrity preservation enables concentrated serum formulations commanding superior unit economics. |
| AI-Driven Skin Diagnostics Integration | Machine-learning recommendation engines reduce purchase friction for first-time herbal converts in Seoul and Mumbai. |
| Pharmacy-Channel Density Expansion | Controlled retail distribution sustains premium positioning against supermarket and direct-to-consumer erosion. |
| CDSCO Export Licensing Streamlining | Traditional medicine recognition protocols create regulatory tailwinds for Southeast Asian market penetration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with ayurvedic formulators, pharmacy procurement managers, biodynamic certification auditors, and subscription platform operators. CDSCO licensing databases, ECHA REACH submission portals, and MFDS cosmetic safety filings provided regulatory validation. Nielsen retail audit data and customs import records captured channel flow verification. Bottom-up SKU-level triangulation against top-down regional consumption estimates reconciled volume outputs.
Data-stream reconciliation across product type, ingredient provenance, application function, and distribution channel dimensions shaped the analytical framework. CAGRs derived from segment-level growth rate convergence across the projection horizon. Cold-press extraction technology adoption curves and ECHA compliance investment trajectories informed herbal beauty-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH Annex III expansion scope and Himalayan monsoon disruption severity. Forecasts reflect documented assumptions on regulatory enforcement intensity and digital-channel adoption saturation. Practitioners should monitor CDSCO licensing queue clearance rates and Seoul subscription platform churn metrics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
South Korea Beauty and Personal Care Products Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
Body Care Products Market
Beauty & Personal Care
China Antibacterial Soap Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Cosmetics and Personal Care Products Direct Selling Market
Beauty & Personal Care
Hair Color Spray Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Makeup Brush and Tool Market
Beauty & Personal Care
Personal Care Wipes Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
Scalp Massager Market
Beauty & Personal Care
Color Protection Shampoo Market
Beauty & Personal Care
Luxury Beauty Devices Market