
 India Hair Oil Market | 2026-2036
India Hair Oil Market Size, Share, and Industry Trends Forecast 2026-2036
India Hair Oil Market Foresight
Maharashtra's manufacturing corridor is fragmenting as new processing units multiply around Nashik and Pune. Marico Limited anchors the premium coconut oil segment through extensive cold-press infrastructure. Dabur India Ltd. competes across Ayurvedic formulations with heritage brand equity in North and East India. Emami Group differentiates through menthol-based therapeutic variants targeting male consumers.
India hair oil comprises lipid-based formulations derived from plant seeds, nuts, or fruit pulps, typically containing triglycerides with linoleic or oleic acid profiles exceeding 60% composition, designed for scalp nourishment, follicle strengthening, and hair shaft lubrication. Coconut oil dominates volume due to indigenous supply chains and price accessibility, while herbal oil captures expanding margin pools as consumers shift toward botanical actives. The salon customer type remains underpenetrated relative to retail households, presenting a structural growth vector for professional-grade treatment oils.
BIS mandates govern labeling accuracy and heavy-metal thresholds, while FSSAI oversight applies to edible-grade carrier oils crossing into cosmetic use. The Ayush Ministry's certification framework shapes competitive access for Ayurvedic claims, compelling documentation of traditional ingredient sourcing. Stakeholders must monitor regulatory convergence between cosmetic and food safety standards as enforcement intensifies across state-level drug control administrations.
Market Dynamics
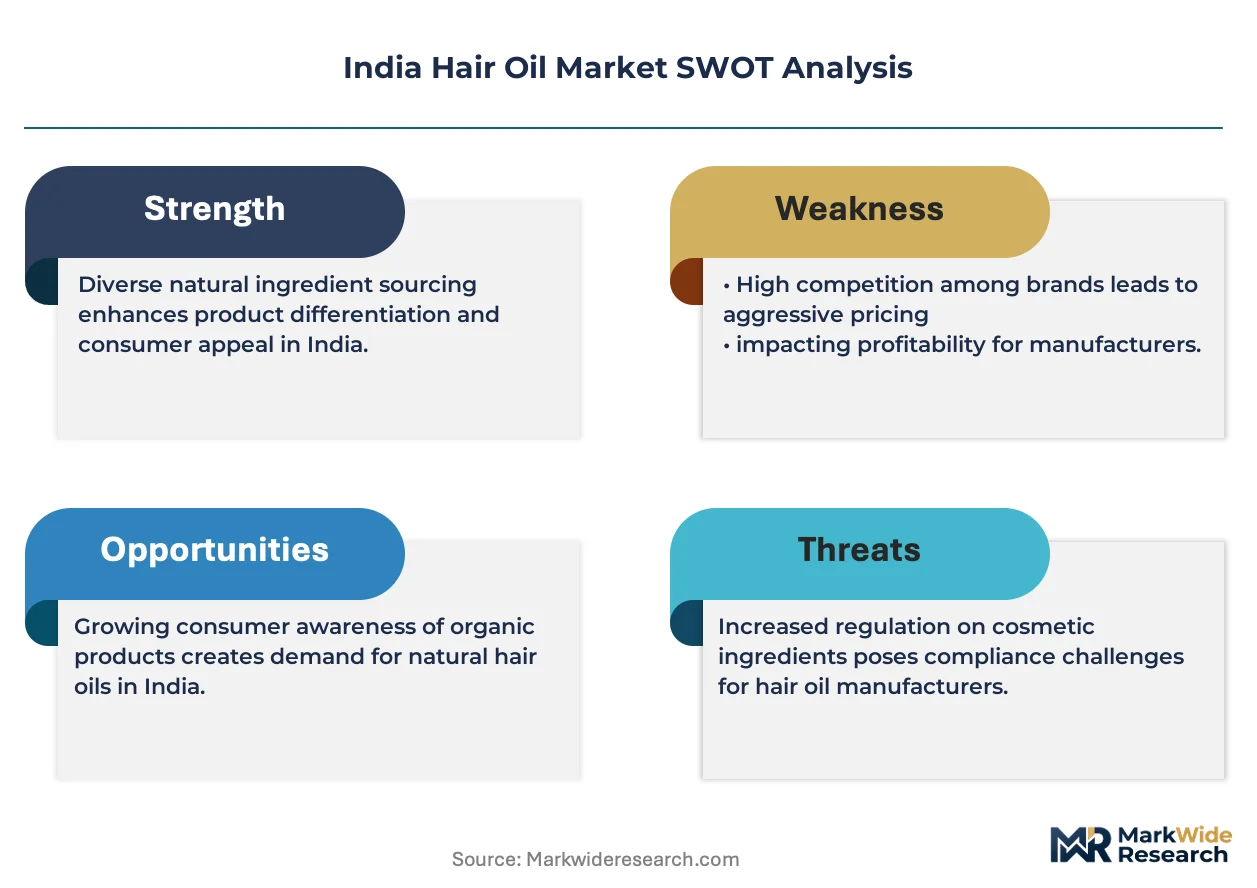
Branded penetration into rural and semi-urban households is compressing the unorganized sector's historical dominance across India's hair oil landscape. BIS quality mandates and Ayush certification protocols are simultaneously raising compliance costs and creating tiered market access based on documentation capabilities.
Growth Catalysts
- Ayush Certification Framework:The Ministry of Ayush's documentation requirements for traditional ingredient sourcing are locking in competitive access for heritage Ayurvedic formulations, rewarding firms with established botanical supply networks.
- Rural Distribution Expansion:Modern retail chains and e-commerce logistics are penetrating tier-3 towns and village clusters, converting household production to packaged branded consumption.
- Cold-Press Infrastructure:Mechanical extraction technologies preserving heat-sensitive fatty acid profiles are enabling premium positioning for coconut and almond oil variants in urban markets.
Market Restraints
- Copra Price Volatility:Kerala and Tamil Nadu supply concentration for coconut raw material exposes margin structures to monsoon-dependent harvest fluctuations and speculative trading.
- FSSAI-Cosmetic Regulatory Convergence:Edible-grade carrier oils crossing into cosmetic applications face dual compliance burdens, lengthening product launch timelines and testing expenditures.
- Synthetic Serum Substitution:Silicone-based leave-in treatments from personal care multinationals are capturing scalp-care occasions among younger urban demographics.
Strategic Opportunities
- Salon Channel Underpenetration:Professional-grade treatment oils for pre-wash scalp therapy and post-styling finishing remain nascent versus retail household saturation, offering margin expansion.
- PLI Scheme for Herbal Processing:Production-linked incentives for active pharmaceutical ingredient and botanical extraction infrastructure reduce capital intensity for domestic manufacturing scale-up.
- Menthol-Therapeutic Male Positioning:Cooling variants targeting post-gym and stress-relief rituals are capturing share in grooming-oriented male segments underserved by floral-positioned legacy brands.
Industry Challenges
- Ayush Documentation Talent Scarcity:Firms struggle to hire personnel capable of navigating traditional knowledge digital library submissions and ethnopharmacological validation protocols.
- Capex Intensity for Cold-Press Scale:Low-temperature mechanical extraction equipment requires substantial upfront investment relative to solvent-based alternatives, constraining mid-tier manufacturer expansion.
- Heavy-Metal Testing Bottlenecks:BIS-mandated laboratory certification for lead, arsenic, and mercury thresholds creates queue delays at accredited facilities, extending batch release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Hair Oil Market |
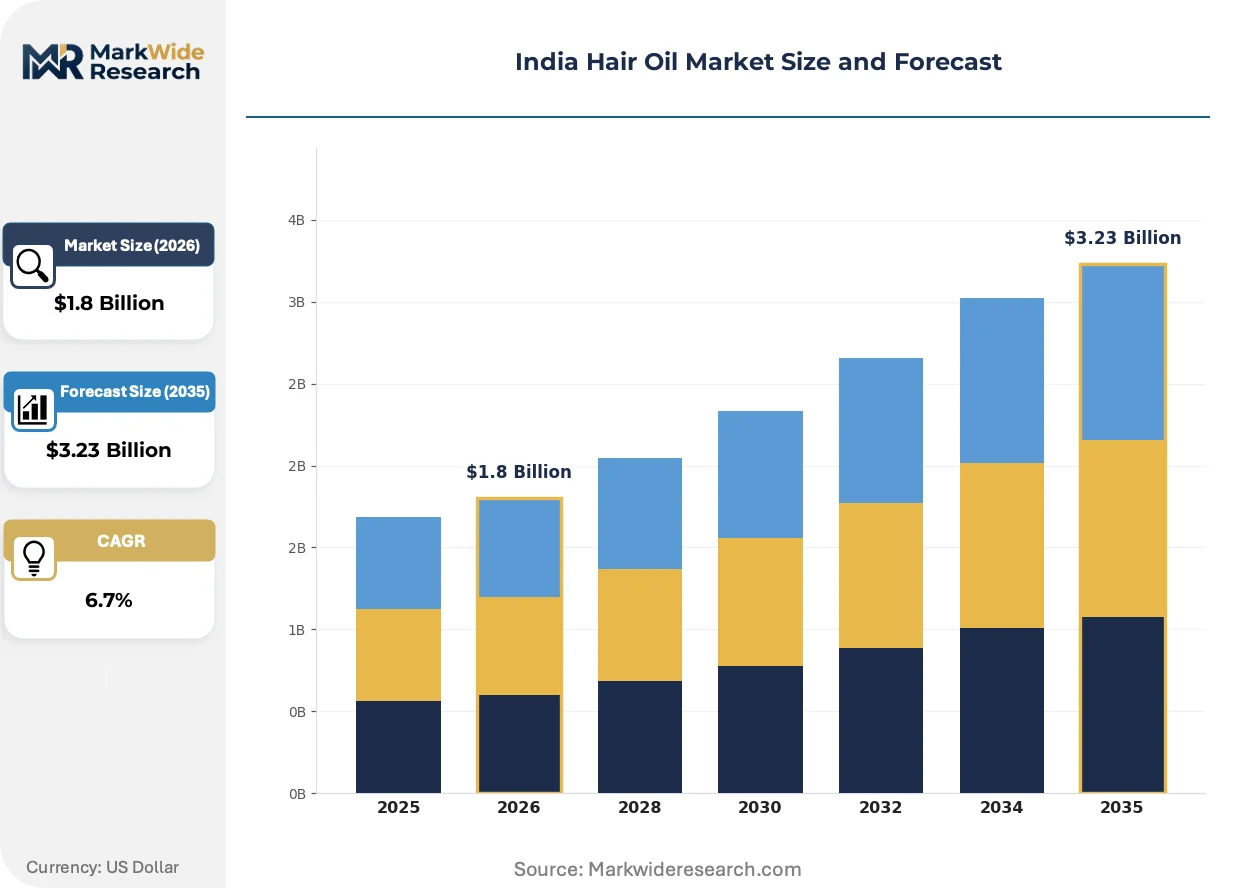
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Oil, Almond Oil, Olive Oil, Herbal Oil Application: Therapeutic, Styling, Conditioning, Treatment Customer Type: Women, Men, Children, Salons Formulation: Organic, Synthetic, Ayurvedic, Natural |
| Companies Covered | Bajaj Consumer Care Ltd., Patanjali Ayurved Limited, Marico Limited, Henkel AG, Himalaya Wellness Company, Dabur India Ltd., Unilever PLC, Procter & Gamble Company, Emami Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Hair Oil Market Shifts & Advancements
Formulation science and distribution architecture are converging to reshape competitive positioning across India's hair oil sector. Technology migration, regulatory tightening, and channel fragmentation are simultaneously compressing legacy operating models and opening white space for differentiated entrants.
Cold-pressed extraction technology is migrating from artisanal micro-producers to scaled manufacturing facilities. Nashik and Pune processing clusters are installing mechanical presses capable of sub-40°C operation to preserve linoleic acid integrity. This capability compression is enabling premium-tier pricing for mass-market production volumes previously confined to small-batch Ayurvedic pharmacies.
BIS labeling accuracy mandates and heavy-metal threshold enforcement are intensifying scrutiny across Maharashtra, Tamil Nadu, and Uttar Pradesh manufacturing corridors. State-level drug control administrations are conducting unannounced facility audits, compelling investment in in-house chromatography and spectroscopy equipment. Heritage brands with pre-existing quality infrastructure are absorbing compliance costs more efficiently than unorganized sector competitors.
Direct-to-consumer subscription models are disrupting traditional kirana and modern trade dependence among metropolitan millennials. Digital-native brands are capturing recurring revenue through personalized scalp diagnostic questionnaires and quarterly oil regimen shipments. This channel pivot is most visible in Bengaluru and Mumbai, where app-based purchasing has compressed switching costs and fragmented brand loyalty previously anchored to generational household preferences.
India Hair Oil Market Segmentation
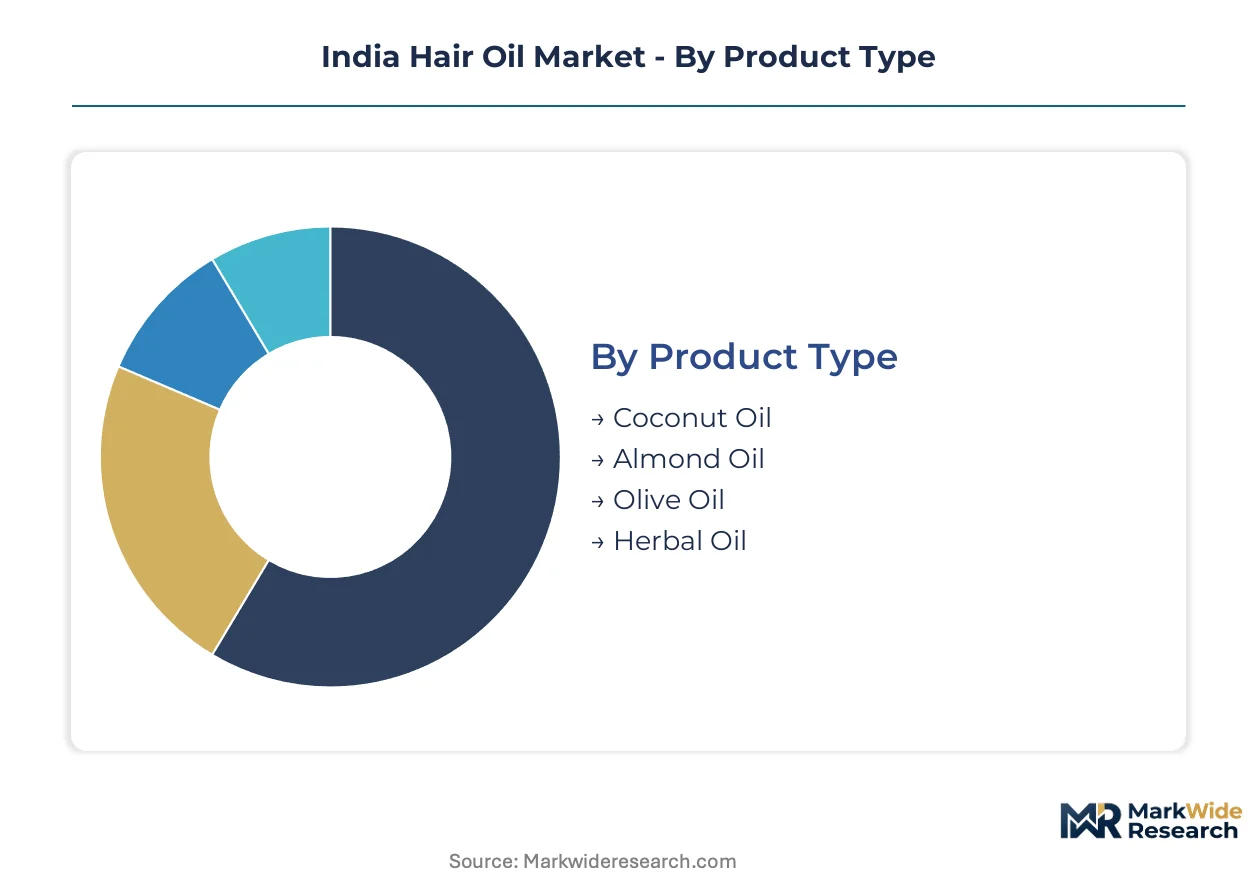
India hair oil segmentation reveals how formulation chemistry, ritual occasion, and buyer identity intersect to create distinct margin pools. Each dimension carries regulatory and supply-chain implications that shape competitive entry costs.
Product Type:
Mature commodity oils anchor volume throughput while botanical variants command expanding premium positioning.
- Coconut Oil:Triglyceride-dominant formulations with lauric acid profiles exceeding 45% composition serve daily scalp nourishment rituals across Kerala and Tamil Nadu supply belts. Maharashtra and Uttar Pradesh households drive branded conversion as cold-press infrastructure scales near Nashik processing clusters.
- Herbal Oil:Complex botanical infusions requiring Ayush Ministry documentation for traditional knowledge claims capture margin expansion in urban markets. North Indian heritage brands leverage established ethnopharmacological sourcing networks to lock in competitive access against synthetic serum substitution.
- Almond Oil:Oleic acid-rich carrier formulations target conditioning-intensive consumers in metropolitan salons and direct-to-consumer subscription channels.
- Olive Oil:Import-dependent supply chains constrain price accessibility, limiting penetration to premium-tier positioning in South Indian urban households.
Coconut oil handles the majority of throughput; herbal oil is the fastest mover on share.
Application:
Functional occasion determines channel routing and pricing architecture across retail and professional segments.
- Therapeutic:Menthol-infused scalp treatments targeting post-gym and stress-relief rituals capture male grooming segments underserved by floral-positioned legacy formulations. Emami Group's cooling variants exemplify this positioning in East and North India distribution networks.
- Conditioning:Pre-wash lipid replenishment formulations dominate household consumption frequency, with coconut and almond oil bases commanding repeat purchase loyalty in kirana and modern trade channels.
- Styling:Post-wash finishing oils face silicone-based serum competition among younger urban demographics in Bengaluru and Mumbai.
- Treatment:Professional-grade scalp therapy oils remain underpenetrated in salon channels relative to retail saturation, offering margin expansion for specialized entrants.
Conditioning applications absorb the highest purchase frequency; therapeutic positioning is climbing the fastest as male grooming rituals formalize.
Customer Type:
Demographic targeting intensity varies sharply between mass household penetration and specialized professional channels.
- Women:Multi-generational ritual continuity drives brand loyalty in Maharashtra and Tamil Nadu, where traditional oiling practices merge with modern retail distribution. Marico Limited and Dabur India Ltd. anchor positioning through heritage equity and cold-press quality infrastructure.
- Salons:Professional-grade treatment oils for pre-wash scalp therapy and post-styling finishing remain structurally underpenetrated versus retail household saturation.
- Men:Grooming-oriented segments show preference for menthol-based therapeutic variants with functional positioning over floral heritage branding.
- Children:Gentle formulation requirements drive organic and Ayurvedic certification demand among quality-sensitive urban parents.
Women's segments concentrate the revenue base; salon channels are expanding most quickly as professional-grade treatment oils penetrate urban service infrastructure.
Formulation:
Certification tier creates compliance-based market access differentiation between heritage players and new entrants.
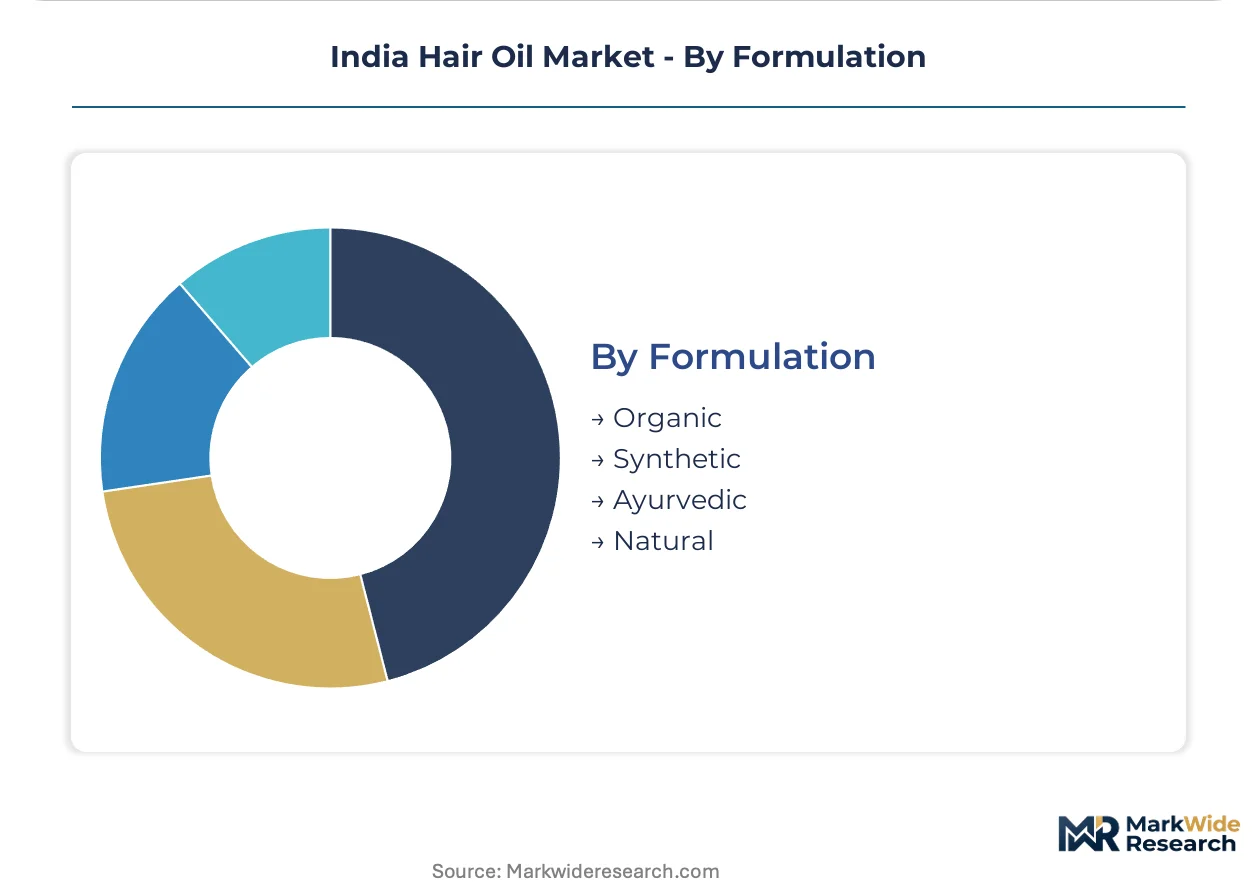
- Ayurvedic:Ministry of Ayush documentation requirements for traditional ingredient sourcing reward firms with established botanical supply networks and heritage brand equity. BIS quality mandates and heavy-metal threshold enforcement intensify scrutiny across manufacturing corridors.
- Organic:Chemical-free positioning commands premium pricing in metropolitan direct-to-consumer channels, though supply chain integrity verification remains costly.
- Natural:Plant-derived claims without full organic certification occupy mid-tier positioning in modern retail chains.
- Synthetic:Silicone-based formulations face substitution pressure from botanical alternatives as consumer preference shifts toward scalp-friendly lipid profiles.
Ayurvedic formulations dominate heritage brand portfolios; organic certification is gaining share fastest among digital-native entrants targeting subscription revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS quality mandates and Ayush certification protocols anchor Maharashtra's manufacturing corridor as the regulatory fulcrum for India's hair oil sector. State-level enforcement intensifies across Tamil Nadu and Uttar Pradesh processing clusters.
Maharashtra
Cold-press infrastructure investment accelerates around Nashik and Pune as branded penetration converts rural households. BIS labeling accuracy mandates and heavy-metal threshold enforcement drive unannounced facility audits. Nashik processing clusters install mechanical presses capable of sub-40°C operation to preserve linoleic acid integrity for premium-tier positioning.
Tamil Nadu
Copra supply concentration exposes margin structures to monsoon-dependent harvest fluctuations in Kerala-Tamil Nadu supply belts. FSSAI oversight applies to edible-grade carrier oils crossing into cosmetic applications across state boundaries. Chennai and Coimbatore manufacturing corridors face dual compliance burdens as regulatory convergence lengthens product launch timelines.
Uttar Pradesh
Heritage Ayurvedic formulations leverage established ethnopharmacological sourcing networks in North Indian distribution. Ayush Ministry documentation requirements for traditional ingredient sourcing reward firms with pre-existing botanical supply infrastructure. Kanpur and Lucknow processing units absorb compliance costs more efficiently than unorganized sector competitors through in-house chromatography equipment.
Karnataka
Direct-to-consumer subscription models disrupt traditional kirana dependence among Bengaluru metropolitan millennials. Digital-native brands capture recurring revenue through personalized scalp diagnostic questionnaires and quarterly oil regimen shipments. Bengaluru's app-based purchasing compresses switching costs and fragments generational brand loyalty.
West Bengal
Menthol-based therapeutic variants target male grooming segments underserved by floral-positioned legacy formulations. Emami Group's cooling positioning exemplifies functional ritual capture in East India distribution networks. Kolkata manufacturing clusters specialize in post-gym and stress-relief oil formulations for grooming-oriented demographics.
India Hair Oil Market Competitive Landscape
Heritage Ayurvedic houses and modern FMCG conglomerates split the market between documentation-intensive traditional positioning and scale-driven mass distribution. The competitive structure tierizes around certification capabilities, with Ayush-compliant botanical networks creating moats against synthetic serum substitution. Three archetypes dominate: legacy Ayurvedic pharmacies with ethnopharmacological sourcing, cold-press infrastructure specialists, and menthol-therapeutic male grooming innovators. Dominant competitive moves include rural distribution expansion through modern retail chains and backward integration into copra processing to hedge raw material volatility.
Among heritage Ayurvedic anchors, Patanjali Ayurved Limited and Dabur India Ltd. exemplify the documentation-intensive tier with established botanical supply networks. Marico Limited occupies a position representing cold-press infrastructure scale for premium coconut oil positioning. These three entities anchor competitive archetypes rather than discrete market shares, with their strategic postures shaping sector-wide responses to BIS quality mandates and Ayush certification protocols.
| Leading Market Players |
|---|
| Bajaj Consumer Care Ltd. |
| Patanjali Ayurved Limited |
| Marico Limited |
| Henkel AG |
| Himalaya Wellness Company |
| Dabur India Ltd. |
| Unilever PLC |
| Procter & Gamble Company |
| Emami Group |
| Others |
Supply & Pricing Matrix
Nashik and Pune processing clusters anchor Maharashtra's cold-press capacity expansion, compressing unit economics for premium coconut oil variants while Kerala-Tamil Nadu copra supply belts exert upstream pricing leverage through monsoon-dependent harvest cycles. BIS quality mandates and FSSAI cosmetic-grade compliance create tiered certification costs that stratify final pricing across branded and unorganized sector competitors.
Pricing Analysis
Inter-state price spreads between Maharashtra manufacturing corridors and Tamil Nadu supply belts reflect cold-press premiumization against commodity copra spot markets. Pricing stratifies across premium, standard, and economy tiers based on Ayush certification grade and cold-press extraction method. Cost compression in economy-tier unbranded oils is intensifying because of copra price volatility and speculative trading in Kerala auction markets. Rural households in Uttar Pradesh and semi-urban clusters in West Bengal demonstrate highest price sensitivity, while metropolitan salon channels in Bengaluru and Mumbai absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Extended payment terms from modern trade chains and supply-chain finance facilities from processing cooperatives lubricate working capital across the copra-to-shelf pipeline. Geographic supply concentration centers on India for coconut raw material, with secondary almond oil sourcing from Afghanistan and Iran. Raw material dependencies include copra from Kerala-Tamil Nadu belts, menthol crystals from Uttar Pradesh, and botanical actives from Madhya Pradesh tribal sourcing networks. Single-source vulnerability in monsoon-exposed copra harvests creates margin volatility. Distribution runs through kirana networks for rural penetration, modern trade for urban branded conversion, and direct-to-consumer platforms for subscription-based recurrence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's hair oil sector functions as a regulatory-entrenchment defensive moat, where Ayush certification documentation and BIS quality infrastructure create switching costs that heritage brands exploit against unorganized sector fragmentation.
For Market Incumbents: Harden cold-press infrastructure moats through captive copra processing in Nashik corridor expansions, locking in quality-grade differentiation against solvent-extracted unbranded substitutes. Deepen Ayush documentation capabilities through in-house ethnopharmacological validation teams, preempting CDSCO enforcement intensification that threatens heritage formulation claims. Channel control through salon-grade professional lines offers margin defense against direct-to-consumer digital entrants. For New Entrants and Emerging Players: Pursue underpenetrated salon channels for professional-grade scalp therapy oils, where retail household saturation has left structural white space in Bengaluru and Mumbai metropolitan service infrastructure. Target male grooming segments with menthol-therapeutic positioning, capturing post-gym ritual occasions underserved by floral heritage branding. Direct-to-consumer subscription models with personalized diagnostic questionnaires offer lowest-friction go-to-market entry against kirana-dependent incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital-native brands with subscription oil regimens, suggesting superior cash-flow quality versus transactional kirana-dependent competitors. Long-term viability over a multi-year horizon favors acquisition targets with pre-existing Ayush documentation infrastructure and cold-press mechanical capabilities, as regulatory convergence between FSSAI and cosmetic standards intensifies compliance burdens. The signal to watch is BIS laboratory certification queue lengths at Maharashtra state facilities, which indicate enforcement velocity and batch-release cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copra Processing | Captive supply from Kerala-Tamil Nadu belts hedges monsoon-driven raw material volatility for Maharashtra manufacturers. |
| Ayush Certification Investment | Ministry documentation capabilities lock competitive access for heritage botanical claims against synthetic serum substitution. |
| Salon Channel Penetration | Professional-grade treatment oils capture margin expansion in structurally underpenetrated urban service infrastructure. |
| Direct-to-Consumer Launch | Subscription models with scalp diagnostics fragment generational brand loyalty in Bengaluru and Mumbai metropolitan clusters. |
| Cold-Press Infrastructure Scale-Up | Sub-40°C mechanical extraction preserves linoleic acid profiles for premium-tier positioning against solvent-based competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers at heritage Ayurvedic houses, category buyers at modern retail chains, cold-press processing engineers at Nashik facilities, and salon channel distributors across Maharashtra and Tamil Nadu. Secondary validation drew from FSSAI cosmetic-grade compliance circulars, BIS quality mandate amendments, Ayush Ministry traditional knowledge digital library submissions, and customs records for almond oil import dependencies. Bottom-up volume triangulation across product type and application segments converged with top-down value sizing through branded penetration rate assumptions.
Calibration against historical branded conversion trajectories in rural Uttar Pradesh and semi-urban West Bengal anchored volume projections across the analysis window. Segmentation dimensions modeled include product chemistry tier, ritual occasion, buyer demographic identity, and certification grade. CAGRs were derived from trend extrapolation of cold-press infrastructure investment cycles and copra supply elasticity estimates. Forecast inputs incorporated PLI scheme uptake rates for herbal processing equipment and e-commerce logistics penetration indices for tier-3 town clusters.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by unorganized sector cooperatives or sudden FSSAI-cosmetic regulatory divergence would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Aftershave Market
Beauty & Personal Care
Deodorant Roll-Ons Market
Beauty & Personal Care
Europe Shampoo Market
Beauty & Personal Care
Cosmetics and Personal Care Stores Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Japan Beauty Fridges Market
Beauty & Personal Care
US Skincare Market
Beauty & Personal Care
BB Cushions Market
Beauty & Personal Care
Underarm Antiperspirant and Deodorant Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
Bar Soap Market
Beauty & Personal Care
Personal Care Wipes Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
Europe Hair and Skincare Market