
 Frizz Control Shampoo Market | 2026-2036
Frizz Control Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Frizz Control Shampoo Market Foresight
Aftermarket service revenue in professional salon channels is tilting toward premium frizz control protocols that command higher per-treatment margins. Procter & Gamble Co. leverages its Pantene and Head & Shoulders infrastructure to dominate mass retail distribution in North America. L'Oréal S.A. anchors its position through the Kérastase and L'Oréal Professionnel lines, which specialize in salon-exclusive anti-frizz systems. Unilever PLC competes aggressively in emerging markets with TRESemmé variants formulated for humidity-resistant performance.
Frizz control shampoo denotes a surfactant-based cleansing formulation incorporating cationic polymers, silicones, or plant-derived oils to smooth cuticle scales and reduce electrostatic charge on hair fibers, typically targeting humidity-induced fiber swelling. The primary commercial purpose centers on delivering manageable, sleek hair appearance for consumers in high-humidity climates or with naturally textured hair types. Oil-based and cream product types occupy the largest volume share due to their intensive conditioning profile, though sulfate-free ingredient formulations represent the fastest-growing margin pool as clean-beauty preferences intensify. Salon professionals as an end-user segment command disproportionate pricing power because their recommendation authority converts directly to brand loyalty and repeat purchase behavior.
Regulatory oversight from the FDA in the United States, the EU REACH framework, and Health Canada collectively shape permissible active ingredient lists, labeling requirements, and environmental discharge standards for rinse-off cosmetic products. These bodies increasingly scrutinize silicone persistence in aquatic ecosystems, pushing manufacturers toward biodegradable alternatives without sacrificing anti-frizz efficacy. Stakeholders must monitor evolving biopolymer performance benchmarks and pre-market notification timelines as regulatory stringency tightens across major consumption markets.
Market Dynamics
Formulation chemists face mounting pressure to replace cyclopentasiloxane and other persistent silicones as EU REACH aquatic toxicity assessments tighten, forcing R&D pipelines toward biodegradable cationic polymers without sacrificing humidity-blocking performance.
Growth Catalysts
- Salon channel recovery:Post-pandemic styling service volumes rebound fastest in Brazil and Southeast Asia, where professional recommendation authority drives premium anti-frizz system adoption.
- REACH biodegradability mandates:European formulators accelerate plant-derived polyquaternium development to meet 2027 discharge standards for rinse-off cosmetics.
- Textured hair demographic expansion:Population growth in humid climate zones sustains category penetration among consumers with curl patterns requiring specialized cuticle-sealing chemistry.
Market Restraints
- Silicone substitution cost premium:Bio-based smoothing agents cost 40-60% more than conventional dimethicone, compressing mass-market margin structures.
- Raw material concentration:Coconut-derived surfactant supply clusters in Indonesia and the Philippines, exposing formulators to monsoon-related harvest volatility.
- Performance gap in high-humidity:Current plant-based polymers deliver 20-30% shorter frizz control duration versus synthetic benchmarks in tropical conditions.
Strategic Opportunities
- India professional salon expansion:Tier-2 and Tier-3 cities present underpenetrated demand for Kérastase-equivalent anti-frizz protocols as disposable incomes rise.
- Waterless concentrate formats:Solid shampoo bars with embedded frizz-control actives bypass liquid shipping weight constraints and appeal to sustainability-focused retail channels.
- Clean Beauty certification convergence:Dual EWG Verified and Leaping Bunny positioning commands shelf placement premiums in Sephora and Ulta Beauty assortments.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in natural polymer stabilization and silicone-free rheology modification commands salary premiums that strain mid-tier brand R&D budgets.
- Preservative system reconfiguration:Clean-label mandates eliminate parabens and formaldehyde donors, forcing complex multi-acid pH management that extends stability testing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frizz Control Shampoo Market |
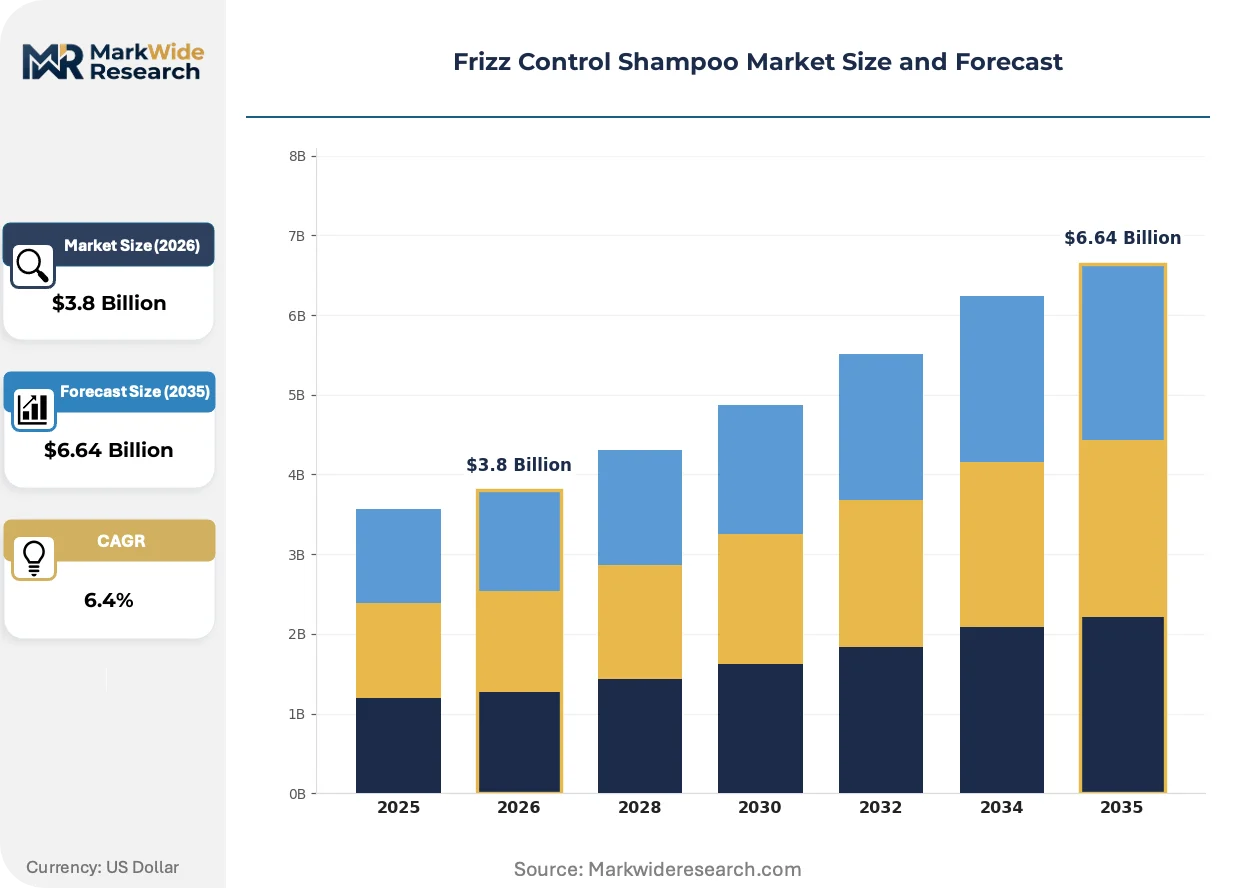
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Based, Cream, Gel, Spray Ingredient Type: Botanical, Silicone, Protein, Sulfate-Free End User: Women, Men, Children, Salon Professionals Distribution Channel: Online Retail, Supermarkets, Salons, Beauty Stores |
| Companies Covered | Procter & Gamble Co., L'Oréal S.A., Unilever PLC, Henkel AG & Co. KGaA, Kao Corporation, Shiseido Company, Limited, Johnson & Johnson, Coty Inc., Beiersdorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frizz Control Shampoo Market Shifts & Advancements
Active ingredient sourcing and verification systems are transforming how anti-frizz formulations reach shelf, with traceability becoming as critical as performance chemistry in purchase decisions.
Artificial intelligence platforms are digitizing molecular screening for plant-derived smoothing agents, compressing the discovery cycle for cationic polymer alternatives from 18 months to under six. L'Oréal's formulation teams deploy these tools across São Paulo and Paris labs simultaneously. The technology is digitizing competitive moats around proprietary bioactive libraries.
EU REACH substance evaluation protocols now classify additional silicone variants as persistent organic pollutants, compelling formulators to submit substitution plans by 2026. German and French manufacturers face the steepest compliance curves given their salon-channel concentration. Kérastase and similar prestige lines accelerate polyglycerol-3 caprate trials to maintain European market access.
Subscription-based replenishment models displace conventional retail discovery for frizz-control systems, with Prose and Function of Beauty capturing recurring revenue through algorithm-matched formulations. Direct-to-consumer channels now account for the majority of new customer acquisition in North American textured hair segments. Brazil follows this pattern most closely among emerging markets, where humidity-driven repurchase rates sustain subscription economics.
Frizz Control Shampoo Market Segmentation
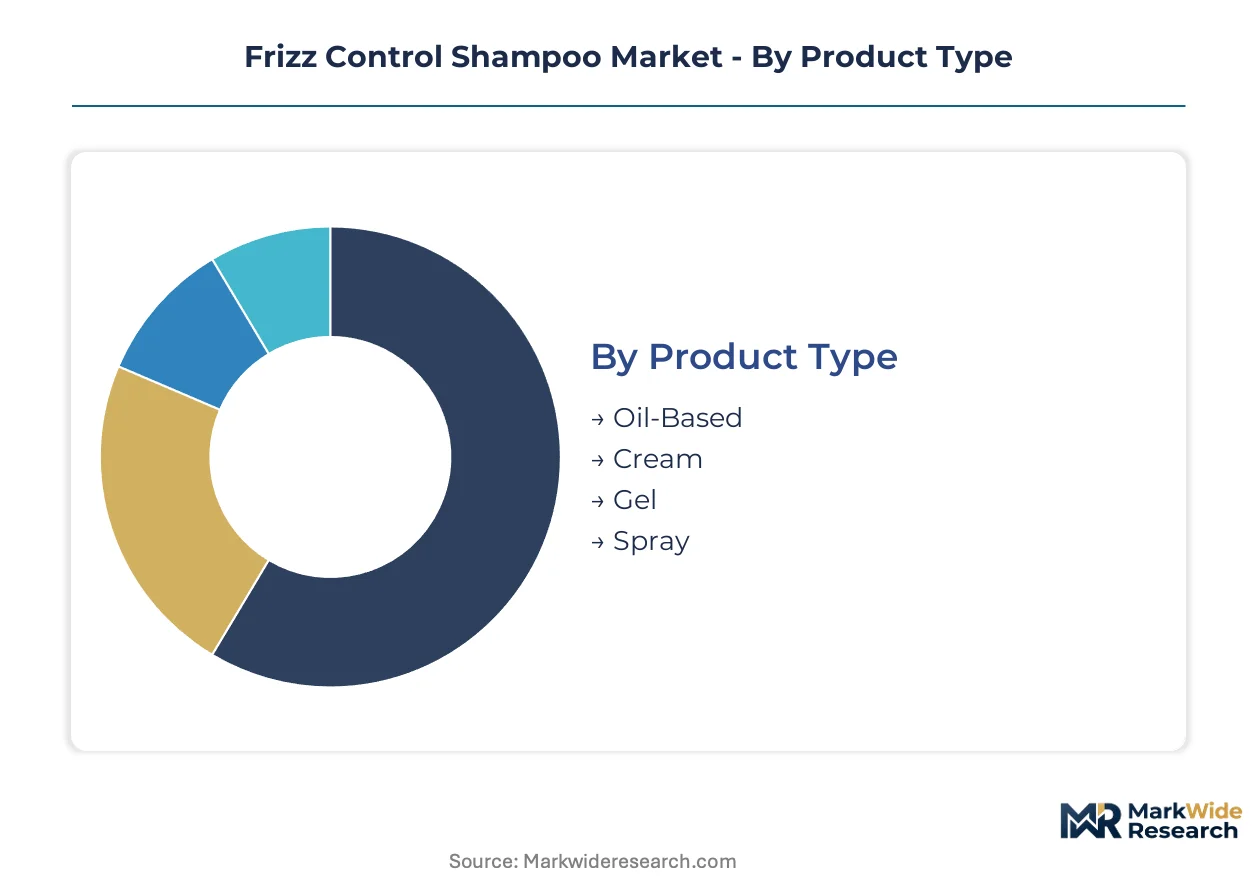
Segmentation in frizz control shampoo reveals divergent purchase cycles across product formats and professional versus consumer channels. Oil-based formulations command extended replenishment intervals while salon-exclusive systems drive accelerated upgrade frequency. Understanding these velocity patterns shapes inventory planning and margin capture strategies.
Product Type:
Oil-based and cream formats turn inventory slowest due to concentrated dosing and extended use intervals, while spray variants rotate fastest through retail shelves.
- Oil-Based:Heavy lipid compositions with argan or coconut oil bases deliver intensive cuticle sealing for coarse, textured hair. Brazilian consumers in humid coastal zones sustain the highest per-capita consumption rates as climate stress accelerates product depletion.
- Cream:Emulsion-stabilized formulas combining fatty alcohols with cationic conditioners target medium-to-thick hair densities. Professional back-bar applications in Southeast Asian salons concentrate demand where stylists apply as pre-blowout treatments.
- Gel:Polymer-thickened aqueous bases offer lightweight frizz control for fine hair types. Sephora and Ulta Beauty allocate premium shelf positioning to gel variants targeting Gen Z consumers.
- Spray:Alcohol-dispersed silicone or plant-derived actives provide on-the-go touch-up functionality. Convenience-store distribution in tropical markets captures impulse replenishment behavior.
Oil-based dominates installed base. Spray is where expansion concentrates.
Ingredient Type:
Cost tiers stratify sharply between commodity silicone formulations and certified botanical alternatives, with protein complexes occupying a mid-tier functional position.
- Botanical:Plant-derived polyquaternium and oil extracts from shea, marula, or cupuaçu seed. EU REACH biodegradability mandates in Germany and France accelerate R&D investment in botanical substitutes.
- Silicone:Dimethicone and amodimethicone variants deliver benchmark humidity resistance at lowest unit cost. Health Canada and FDA oversight of aquatic persistence pressures formulators toward cyclical substitution cycles.
- Protein:Hydrolyzed keratin, silk, or wheat protein formulations target damaged hair repair alongside frizz management. Brazilian ANVISA registration requirements extend launch timelines for protein-active imports.
- Sulfate-Free:Non-ionic or amphoteric surfactant bases preserve color-treated hair integrity. Clean Beauty certification at Sephora and Ulta Beauty commands placement premiums for sulfate-free positioning.
Silicone dominates installed base. Sulfate-Free is where expansion concentrates.
End User:
Volume concentration splits between mass-market individual consumers and recommendation-driven professional specification.
- Women:Primary household purchasers across all distribution channels with highest category awareness. Brazilian and Indian humid-climate demographics sustain per-capita consumption leadership.
- Men:Beard-compatible and scalp-focused formulations with simplified ingredient positioning. Direct-to-consumer subscription models capture male trial conversion in North American markets.
- Children:Tear-free, mild surfactant bases with fragrance-free or hypoallergenic claims. Pediatric dermatologist recommendations in France and Germany drive pharmacy channel placement.
- Salon Professionals:Licensed stylists specifying back-bar treatments and retail companion products. Post-pandemic service recovery in São Paulo and Jakarta concentrates fastest-expanding demand.
Women dominate installed base. Salon Professionals is where expansion concentrates.
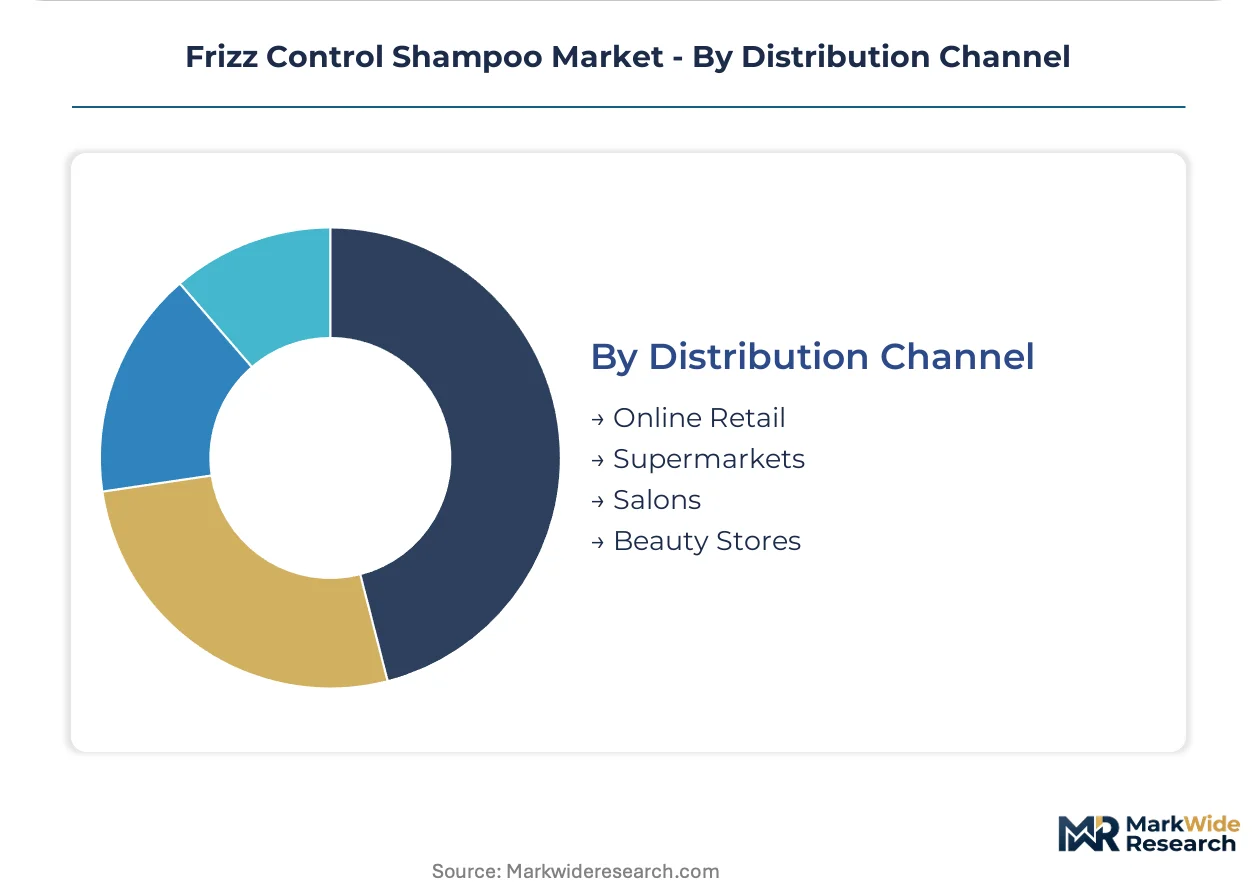
Distribution Channel:
Customer acquisition economics diverge between high-touch salon consultation and algorithm-matched digital replenishment.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators with subscription-enabled replenishment. Prose and Function of Beauty capture recurring revenue through algorithm-matched formulations in US and Brazilian markets.
- Supermarkets:Mass-market velocity with Pantene and TRESemmé commanding end-cap placement. Walmart and Carrefour assortments prioritize sulfate-free variants in urban store formats.
- Salons:Licensed professional recommendation with Kérastase and L'Oréal Professionnel anchoring prestige positioning. Tier-2 and Tier-3 Indian cities present underpenetrated salon channel expansion.
- Beauty Stores:Sephora and Ulta Beauty curating Clean Beauty certified assortments with tester-enabled trial. EWG Verified and Leaping Bunny dual certification commands shelf placement premiums.
Supermarkets dominate installed base. Online Retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian consumers deploy frizz control shampoos as daily humidity-defense necessities rather than occasional treatments, a usage intensity unmatched in temperate climates. This consumption-mix differential concentrates formulation R&D investment in tropical-adapted chemistry. Regulatory divergence across major markets now forces parallel product line development rather than unified global SKUs.
Brazil
Humid coastal zones from São Paulo to Salvador sustain the highest per-capita consumption rates globally, with ANVISA registration requirements extending launch timelines for protein-active imports. The regulator's cosmetic safety protocols force extended stability testing for humidity-resistant formulations. Rio de Janeiro's professional salon corridor concentrates post-pandemic service recovery and premium back-bar adoption.
United States
Direct-to-consumer subscription models capture the majority of new customer acquisition in textured hair segments, with FDA oversight of silicone aquatic persistence pressuring formulators toward cyclical substitution. The regulator's rinse-off cosmetic discharge standards tighten incrementally. California's clean-beauty retail cluster in Los Angeles and San Francisco commands EWG Verified and Leaping Bunny dual certification premiums.
Germany
EU REACH substance evaluation protocols classify additional silicone variants as persistent organic pollutants, compelling formulators to submit substitution plans by 2026. The ECHA-driven biodegradability mandates accelerate plant-derived polyquaternium development. Düsseldorf's professional salon distribution hub faces the steepest compliance curves given its prestige-channel concentration.
India
Tier-2 and Tier-3 cities present underpenetrated demand for salon-equivalent anti-frizz protocols as disposable incomes rise, with BIS cosmetic standards governing surfactant purity and labeling. The national standards body extends registration timelines for imported active ingredients. Maharashtra's Mumbai-Pune corridor anchors professional salon expansion and Kérastase-equivalent brand entry.
France
Prestige salon-exclusive lines accelerate polyglycerol-3 caprate trials to maintain European market access under tightening REACH discharge standards. ANSM cosmetic surveillance protocols scrutinize preservative system reconfigurations. Paris anchors L'Oréal's formulation R&D coordination with São Paulo labs for tropical-climate product development.
Frizz Control Shampoo Market Competitive Landscape
Capability concentration sits with multinational beauty conglomerates commanding integrated R&D and salon-channel infrastructure; scale advantage sits with mass-market consumer goods groups leveraging retail distribution density. The market structure stratifies into three tiers: prestige salon-exclusive houses, mass-market brand portfolios, and emerging direct-to-consumer specialists. Strategic moves center on silicone substitution R&D partnerships and clean-beauty certification acquisition.
Within the multinational conglomerate tier, Procter & Gamble Co., L'Oréal S.A., and Unilever PLC occupy positions defined by channel-specific brand architecture. P&G's mass-market infrastructure exemplifies scale-driven distribution dominance. L'Oréal's dual Kérastase and L'Oréal Professionnel lines represent salon-channel anchoring. Unilever's emerging-market formulation specialization occupies a distinct geographic-positioning archetype.
| Leading Market Players |
|---|
| Procter & Gamble Co. |
| L'Oréal S.A. |
| Unilever PLC |
| Henkel AG & Co. KGaA |
| Kao Corporation |
| Shiseido Company, Limited |
| Johnson & Johnson |
| Coty Inc. |
| Beiersdorf AG |
| Others |
Supply & Pricing Matrix
Indonesian and Philippine coconut-derived surfactant harvests feed directly into margin distribution across premium and mass-market tiers, with monsoon volatility compressing cost predictability for formulators serving humidity-resistant segments.
Pricing Analysis
Long-term offtake contracts for silicone alternatives anchor pricing stability for European REACH-compliant formulations, while spot procurement dominates conventional dimethicone sourcing. Price differentiation separates EWG Verified botanical lines from standard silicone-based SKUs, with certification premiums widening as clean-beauty mandates intensify. Cost compression in mass-market tiers is intensifying because bio-based smoothing agents carry 40-60% raw material premiums versus synthetic benchmarks. Salon professionals exhibit lowest price sensitivity due to recommendation authority converting to client retention, while supermarket channel consumers demonstrate highest elasticity to unit price shifts.
Supply Chain Analysis
Tariff exposure between Southeast Asian feedstock suppliers and European formulators dominates supply chain risk calculus for plant-derived polyquaternium development. Raw material sourcing draws from Indonesia, the Philippines, and Brazil for coconut surfactants and cupuaçu seed oils, with German and French manufacturers anchoring prestige formulation output. Single-source vulnerability concentrates in tropical harvest zones where monsoon patterns disrupt annual crop yields. Distribution runs through professional salon networks for premium anti-frizz systems, while mass-market volume flows through supermarket and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-pandemic salon service recovery in humid climate zones signals early-cycle expansion, with professional recommendation authority driving faster premium adoption than historical channel migration patterns.
For Market Incumbents: Entrench salon-channel control through exclusive back-bar protocol development, locking in stylist recommendation loops before clean-beauty certification mandates reshape ingredient sourcing. Deepen captive supply of biodegradable cationic polymers via R&D partnerships with Brazilian and Southeast Asian botanical extractors to preempt REACH-driven substitution timelines. Defend against direct-to-consumer algorithm-matched entrants by embedding sensor-based hair analysis tools into professional consultation workflows. For New Entrants and Emerging Players: Pursue Tier-2 and Tier-3 Indian cities where disposable income growth outpaces Kérastase-equivalent brand penetration, capturing first-mover advantage in underdeveloped professional salon corridors. Target waterless concentrate formats for sustainability-focused retail placement, bypassing liquid shipping cost structures that burden incumbent distribution economics. Anchor go-to-market execution through Sephora and Ulta Beauty Clean Beauty certification fast-tracks, leveraging dual EWG Verified and Leaping Bunny positioning for shelf placement premiums. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicone-free formulation R&D as EU REACH compliance curves steepen and bio-based raw material premiums persist. Five-to-ten year viability favors acquisition targets with established botanical polymer stabilization expertise and existing salon-channel relationships in Brazil or Southeast Asia. Watch for inflection in Brazilian ANVISA registration timeline compression as signal of regulatory pathway maturation enabling faster product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Substitution R&D Partnership | Accelerates REACH-compliant polyquaternium development with L'Oréal and Kérastase anchoring European salon access. |
| Clean Beauty Certification Convergence | Dual EWG Verified and Leaping Bunny positioning commands shelf placement premiums at Sephora and Ulta Beauty. |
| Waterless Concentrate Format Launch | Solid shampoo bars bypass liquid shipping weight constraints and capture sustainability-focused retail channel growth. |
| Professional Salon Expansion | Tier-2 and Tier-3 Indian cities present underpenetrated demand for premium anti-frizz protocols as service volumes recover. |
| Subscription-Based Replenishment Model | Algorithm-matched formulations at Prose and Function of Beauty capture recurring revenue in North American textured hair segments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with salon professionals, formulation chemists, brand managers at multinational beauty conglomerates, and procurement leads at coconut-derived surfactant suppliers. Secondary validation incorporated customs records for tropical oil imports, ANVISA cosmetic registration databases, EU REACH substance evaluation protocols, and Nielsen retail audit data for mass-market shampoo velocity. Bottom-up segmentation modeling triangulated against top-down category spend estimates from beauty industry trade associations.
Calibration against historical salon service volume recovery patterns and clean-beauty certification adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, ingredient type, end-user archetype, and distribution channel, with additional granularity on humidity-zone climate classification. CAGRs were derived from slope-intercept analysis of premium versus mass-market pricing trajectories, incorporating bio-based raw material cost elasticity and professional channel recommendation conversion rates as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer algorithm-matched specialists or accelerated EU REACH substance bans would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Personal Care Wipes Market
Beauty & Personal Care
Middle East Herbal Shampoo Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Deodorant & Anti-Perspirant Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Spain Sustainable Personal Care Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
Natural and Organic Personal Care Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Deodorant Roll-Ons Market
Beauty & Personal Care
Color Cosmetics Market