
 Malt Whiskey Market | 2026-2036
Malt Whiskey Market Size, Share, and Industry Trends Forecast 2026-2036
Malt Whiskey Market Foresight
Scottish distillery capacity is hardening as aged stock scarcity intensifies. Diageo plc leverages its vast warehousing network across Speyside and Islay to sustain long-maturation programs. William Grant & Sons anchors its competitive position through family-owned cask reserves and limited-edition releases. Suntory Holdings Limited differentiates via Japanese terroir storytelling and precision blending techniques.
Malt whiskey comprises a distilled spirit produced solely from malted barley, water, and yeast, typically aged in oak casks for a minimum of three years and bottled at 40% alcohol by volume or higher, serving both connoisseur collections and premium on-premise consumption. Single malt commands the deepest margin pools due to scarcity-driven pricing and provenance narratives, while blended malt competes on accessibility and mixology versatility. Cask strength expressions attract enthusiast segments willing to pay substantial premiums for unfiltered, higher-proof authenticity.
The Scotch Whisky Association enforces strict geographic indication protocols that limit "Scotch" labeling to Scottish production, while the U.S. Alcohol and Tobacco Tax and Trade Bureau mandates age-statement accuracy and origin disclosure on American-imported labels. India's FSSAI and BIS frameworks are gradually aligning with international whiskey standards as domestic consumption of imported malt rises. Stakeholders must monitor evolving tariff structures and aging-stock availability to calibrate portfolio depth against premiumization timelines.
Market Dynamics
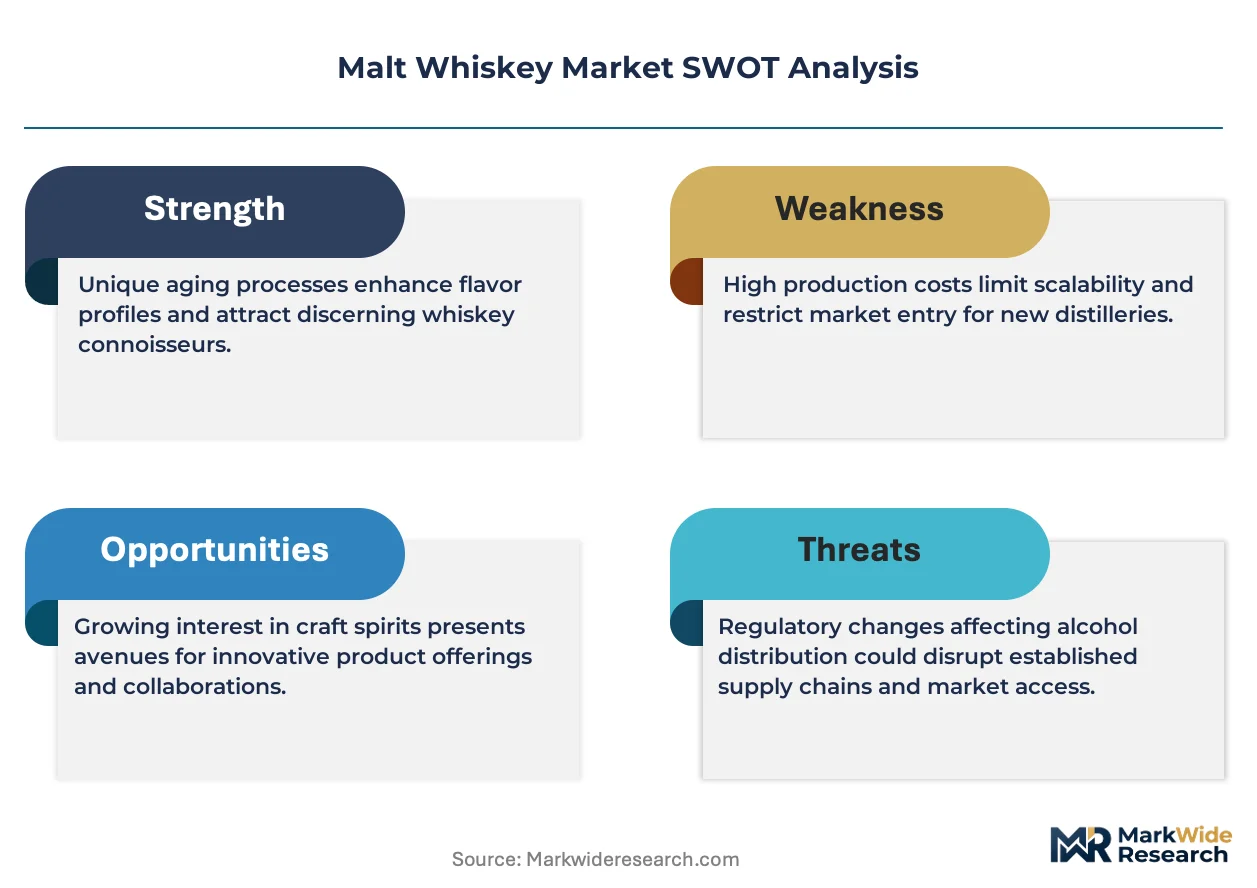
Aged stock scarcity across Scottish warehouses is tightening supply elasticity and forcing portfolio rebalancing toward NAS (no age statement) expressions and accelerated wood management programs.
Growth Catalysts
- TTB Labeling Modernization:The U.S. Alcohol and Tobacco Tax and Trade Bureau streamlined additive disclosure rules, reducing import friction for cask-finished expressions entering American distribution.
- Experiential Hospitality:Premium on-premise venues in Singapore and London are building dedicated malt whiskey libraries with guided tasting protocols, converting casual drinkers into collectors.
- Oak Cask Innovation:Secondary maturation in ex-wine barrels—particularly sherry, port, and sauternes casks—is generating differentiated flavor profiles that command price premiums in enthusiast circles.
Market Restraints
- Barley Supply Concentration:Malting-grade barley production concentrates in Scotland's eastern agricultural belt, exposing distillers to weather-induced crop volatility and regional price spikes.
- Extended Capital Lockup:Minimum three-year maturation requirements under Scotch Whisky Association rules tie up working capital for over thirty-six months before revenue realization.
- Spirits Substitution:Premium agave tequila and aged rum are capturing share among younger drinkers seeking alternative brown-spirit provenance narratives.
Strategic Opportunities
- Indian Market Liberalization:FSSAI alignment with international whiskey standards is reducing import certification timelines, opening paths for Scottish and Japanese producers to build direct distribution.
- Direct-to-Consumer Channels:Distillery-exclusive bottlings and membership clubs are bypassing traditional three-tier systems, capturing full margin on limited releases.
- Carbon-Neutral Maturation:Warehouse energy retrofits and biomass-fueled kilns qualify producers for EU Green Deal–aligned sustainability certifications that resonate with ESG-mandated institutional buyers.
Industry Challenges
- Cooperage Skill Shortage:Master coopers capable of repairing and rebuilding ex-bourbon barrels are retiring faster than apprenticeships replenish the trade, threatening cask quality consistency.
- Geographic Indication Enforcement:Scotch Whisky Association litigation against non-Scottish "Scotch-style" labeling drains legal resources and creates jurisdictional complexity across export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malt Whiskey Market |
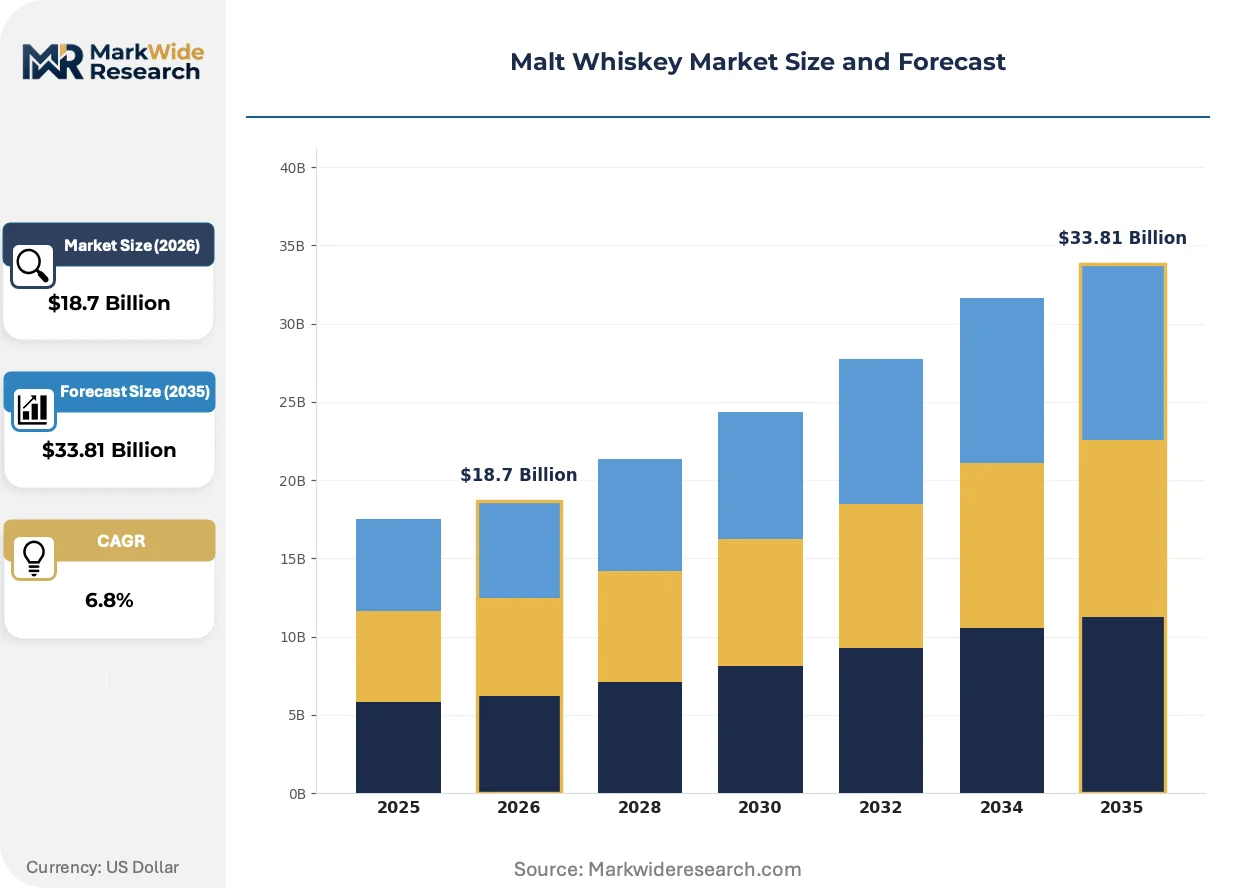
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Malt, Blended Malt, Cask Strength, Vintage Packaging Type: Glass Bottle, Tetra Pak, Miniature Bottle, Keg Price Tier: Premium, Super Premium, Economy, Luxury Distribution Channel: Online Retail, Supermarkets, Liquor Stores, Bars |
| Companies Covered | Diageo plc, Pernod Ricard, Bacardi Limited, Suntory Holdings Limited, The Edrington Group, William Grant & Sons, The Brown-Forman Corporation, Rémy Cointreau, Asahi Group Holdings, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malt Whiskey Market Shifts & Advancements
Precision sensing and data-driven maturation monitoring are compressing traditional warehouse management cycles while regulatory transparency mandates reshape competitive disclosure standards.
Sensor-equipped cask monitoring systems are automating temperature and humidity tracking across bonded warehouses. Distillers deploying IoT-enabled ricks in Speyside and Islay facilities are reducing angel's share losses through predictive climate adjustment. The technology is automating quality assurance workflows that previously required manual sampling and human sensory evaluation.
REACH chemical disclosure requirements in Europe are mandating full constituent transparency for flavor-active compounds transferred from oak casks. Compliance teams must now document vanillin, lactone, and tannin migration rates across finishing protocols. Small-batch producers without dedicated regulatory affairs staff are outsourcing documentation to specialized spirits consultancies.
Collector behavior is fragmenting across digital secondary markets and traditional auction houses. Enthusiasts in the United States are bypassing retail allocation lotteries through blockchain-verified peer-to-peer trading platforms. This channel disintermediation is most pronounced in California and Texas, where state-level shipping law liberalization enables direct collector-to-collector transactions outside licensed distribution.
Malt Whiskey Market Segmentation
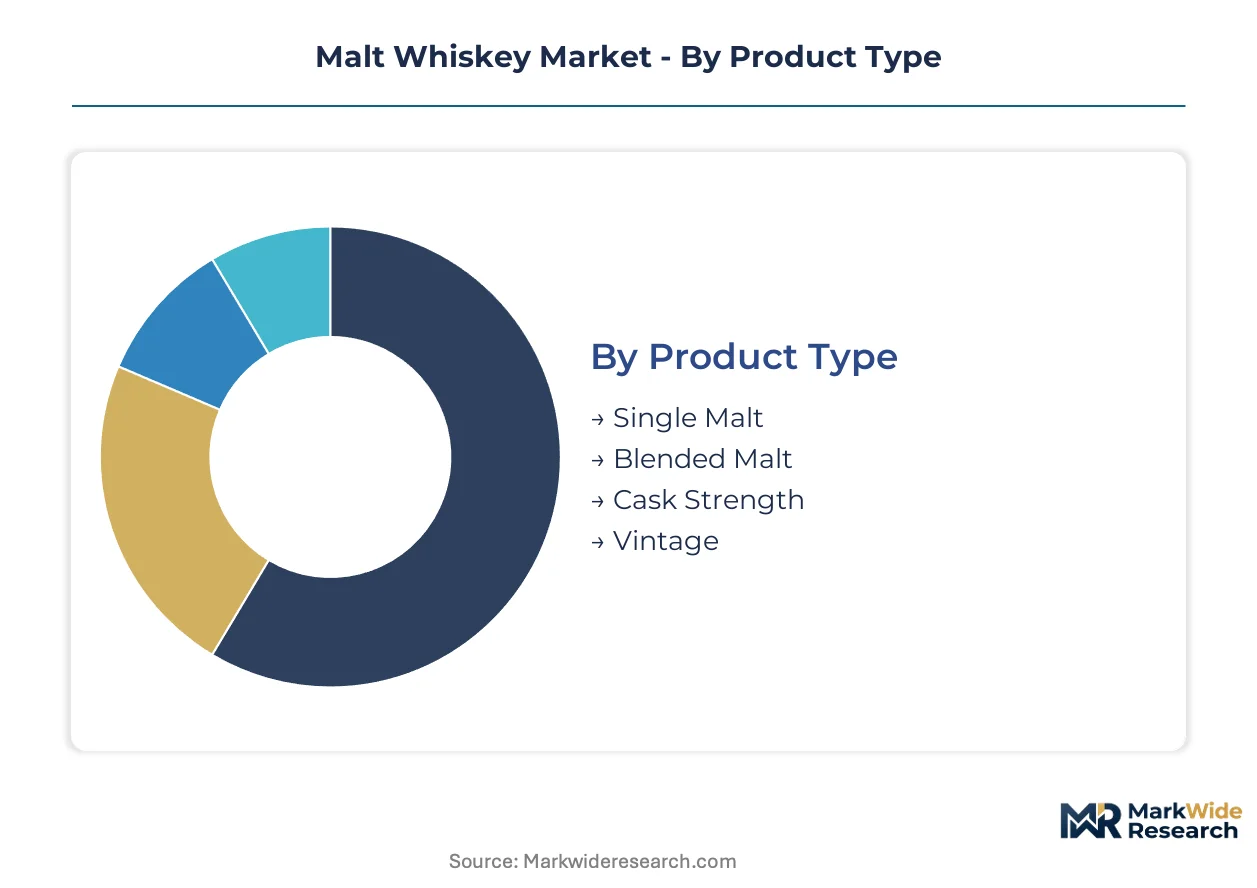
Malt whiskey segmentation separates capital-heavy maturation programs from volume-oriented bottling strategies. Distillers calibrate portfolio depth across these dimensions to balance aged-stock scarcity against revenue realization timelines.
Product Type:
Single malt demands the steepest upfront investment due to three-year minimum maturation and dedicated pot still infrastructure.
- Single Malt:Produced entirely from malted barley at a single distillery using copper pot stills, this expression ties up working capital for 36+ months before release. Demand concentrates in the United States, where bourbon-influenced palates are migrating toward Scottish and Japanese provenance narratives amid tightening TTB labeling scrutiny.
- Blended Malt:Combines single malts from multiple distilleries without grain whiskey, offering mixology versatility and faster stock turnover. Singapore's premium hospitality venues are expanding blended malt programs as experiential drinking formats gain traction among affluent Asian consumers.
- Cask Strength:Bottled directly from the cask without dilution, typically 50-60% ABV. Enthusiast segments in Texas and California pay substantial premiums for unfiltered authenticity.
- Vintage:Distilled in a specific year with declared bottling date. Collector markets in London and New York drive allocation lotteries for limited releases.
Most installed capacity flows through Single Malt. Expansion is steepest in Cask Strength.
Packaging Type:
Glass bottle formats dominate premium positioning, while alternative packaging reduces logistics costs for entry-tier expressions.
- Glass Bottle:Standard 700ml and 750ml formats with heavy-base designs signal quality through tactile weight. The United Kingdom's on-premise sector specifies custom bottle shapes for back-bar visibility.
- Miniature Bottle:50ml airline and hotel formats enable trial conversion without full-bottle commitment. Japanese duty-free channels allocate disproportionate miniature volumes to Chinese tourist segments.
- Tetra Pak:Aseptic cartons for ready-to-drink malt-based cocktails. European supermarket private labels are testing this format for summer seasonal releases.
- Keg:Stainless steel containers for draft malt whiskey service. Scottish distillery visitor centers deploy kegs for tasting-room efficiency.
Glass Bottle commands the deepest margin pools. Tetra Pak is gaining share fastest in experimental channels.
Price Tier:
Super Premium and Luxury tiers absorb the majority of aged-stock scarcity premiums, while Economy segments face agave tequila substitution pressure.
- Luxury:Expressions above $500 retail with age statements exceeding 25 years or single-cask provenance. Auction houses in London and Hong Kong transact these bottles as alternative assets.
- Super Premium:$100-$500 range with 12-21 year age statements or distinctive cask finishes. New York's Michelin-starred restaurants build programs around allocated Super Premium releases.
- Premium:$40-$100 segment including 10-12 year standard expressions and NAS cask-finished variants. United States liquor stores rotate Premium SKUs through seasonal promotional cycles.
- Economy:Sub-$40 blended malts and young single malts competing with aged rum. India's FSSAI import alignment is gradually opening this tier to Scottish volume players.
Super Premium captures the highest per-unit margins. Luxury is climbing the fastest in collector channel development.
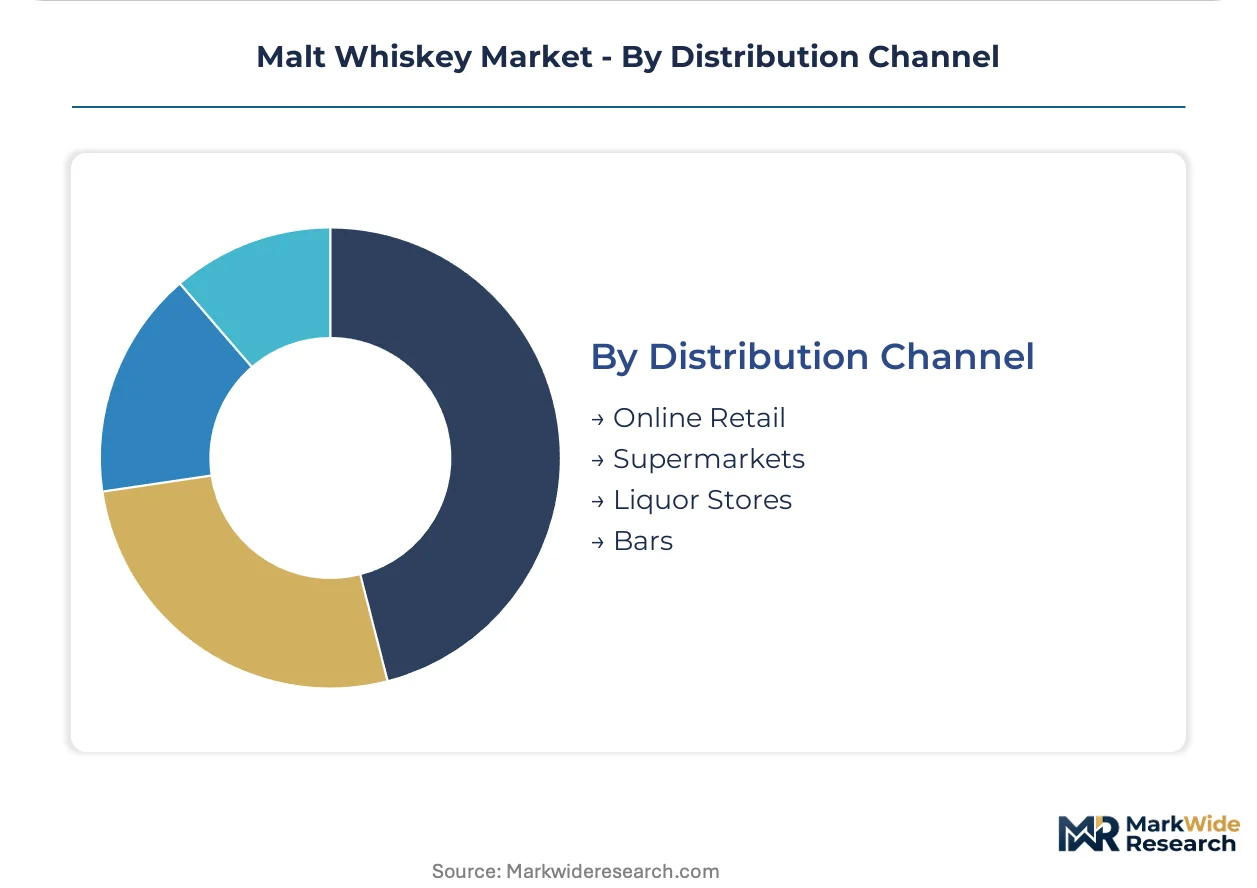
Distribution Channel:
Three-tier system constraints in the United States favor liquor store concentration, while online retail bypasses traditional wholesale markups where regulations permit.
- Liquor Stores:Specialist retailers in Texas and California control allocated releases through loyalty programs. Staff expertise drives conversion rates for first-time single malt buyers.
- Online Retail:Direct-to-consumer platforms exploit shipping law liberalization in select states. Blockchain-verified peer-to-peer trading is fragmenting secondary market liquidity outside licensed distribution.
- Supermarkets:Grocery chains in the United Kingdom dominate volume sales for standard 10-12 year expressions. Shelf placement negotiations determine brand visibility in high-footfall locations.
- Bars:On-premise venues in Singapore and London build dedicated malt libraries with guided tasting protocols. Experiential formats convert casual drinkers into collector behavior.
Liquor Stores retain the deepest allocation control. Online Retail is expanding most quickly in regulatory-permissive jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as maturation cost differentials widen between bonded warehouse jurisdictions. Distillers are relocating aged-stock programs toward markets with favorable excise structures and streamlined certification pathways.
United States
Bourbon-influenced palates are migrating toward single malt expressions, particularly in Texas and California where liquor store allocation lotteries control scarce releases. The TTB streamlined additive disclosure rules, reducing import friction for cask-finished expressions. Premium hospitality venues in New York are building dedicated malt libraries with guided tasting protocols.
United Kingdom
Scottish warehouses face tightening supply elasticity as aged stock scarcity intensifies across Speyside and Islay. The Scotch Whisky Association enforces strict geographic indication protocols that limit "Scotch" labeling to domestic production. London's auction houses transact luxury-tier bottles as alternative assets for collector networks.
Japan
Precision blending techniques and terroir storytelling differentiate domestic producers in enthusiast circles. METI standards govern quality benchmarks for export-bound expressions. Tokyo and Osaka anchor premium on-premise consumption as experiential drinking formats gain traction among affluent consumers.
India
FSSAI alignment with international whiskey standards is reducing import certification timelines for Scottish and Japanese producers. Maharashtra and Karnataka dominate domestic consumption growth as urban affluence expands. The country's central bank monitors foreign exchange impacts on premium spirits pricing.
Singapore
Premium hospitality venues are expanding malt whiskey programs as experiential drinking gains traction among Asian collectors. The city-state's streamlined import documentation reduces clearance friction for limited-edition releases. Marina Bay and Orchard Road clusters host dedicated tasting rooms converting casual drinkers into collector behavior.
Malt Whiskey Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cask-finished innovation and direct-to-consumer channels. The market structures around three distinct layers: multinational spirits conglomerates with vast warehousing networks, family-owned distilleries leveraging cask reserves, and Japanese precision-blending specialists. Consolidation pressures favor players with aged-stock depth, while cooperage skill shortages threaten cask quality consistency. Dominant competitive moves include portfolio diversification into NAS expressions and geographic expansion into liberalizing Asian markets.
Within the multinational tier, Diageo plc and Pernod Ricard occupy positions anchored by scale-driven distribution reach. Suntory Holdings Limited exemplifies the precision-blending archetype through Japanese terroir differentiation. William Grant & Sons represents family-owned competitive positioning through limited-release strategies.
| Leading Market Players |
|---|
| Diageo plc |
| Pernod Ricard |
| Bacardi Limited |
| Suntory Holdings Limited |
| The Edrington Group |
| William Grant & Sons |
| The Brown-Forman Corporation |
| Rémy Cointreau |
| Asahi Group Holdings, Ltd. |
| Others |
Supply & Pricing Matrix
Collector networks in London, New York, and Singapore concentrate demand for luxury-tier expressions, anchoring a scarcity-driven pricing model where allocation lotteries and auction premiums replace traditional retail markups. This buyer concentration amplifies price volatility for aged-stock releases while compressing margins on volume-oriented blended malts.
Pricing Analysis
Distributor margins in the United States three-tier system absorb significant value before products reach Texas and California liquor stores, where allocation lotteries add scarcity premiums atop standard retail markups. Three-tier pricing structure across premium, standard, and economy levels separates cask-strength collector releases from NAS bartender expressions and entry-tier blended malts. Pricing pressure stems from agave tequila substitution among younger drinkers, forcing malt producers to defend provenance narratives. Economy-tier buyers show highest price sensitivity, while cask-strength enthusiasts tolerate substantial premiums for unfiltered authenticity.
Supply Chain Analysis
Empty cask returns from bourbon distilleries in Kentucky and Tennessee feed Scottish cooperages, creating a reverse-logistics loop that sustains ex-bourbon barrel supply for Speyside and Islay maturation programs. Malting-grade barley production concentrates in Scotland's eastern agricultural belt and France's Champagne region, exposing distillers to weather-induced crop volatility. Supply chain risk centers on retiring master coopers outpacing apprenticeship replenishment, threatening cask quality consistency. Distribution runs through bonded warehouse networks before licensed importers navigate TTB labeling scrutiny for American market entry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Scottish production costs and Asian consumption premiums, with India's FSSAI alignment creating regulatory cost differentials against legacy European import certification timelines.
For Market Incumbents: Hedge aged-stock scarcity through accelerated NAS expression development and strategic cask finishing programs that compress revenue realization timelines. Diageo plc and William Grant & Sons should deepen warehouse network control across Speyside and Islay to defend allocation leverage against Japanese precision-blending competitors. Certification investment in EU Green Deal sustainability credentials captures ESG-mandated institutional buyer segments. For New Entrants and Emerging Players: Capture direct-to-consumer channel white space through distillery-exclusive membership clubs that bypass three-tier margin extraction in regulatory-permissive jurisdictions. India's liberalizing import certification offers the most penetrable geography for Scottish and Japanese volume entrants seeking to build distribution before incumbent portfolio saturation. Carbon-neutral maturation storytelling unlocks premium positioning without aged-stock depth. For Investors and Strategic Acquirers: Family-owned distilleries with deep cask reserves are the most active acquirer targets in this space, as multinational spirits conglomerates seek aged-stock depth to sustain luxury-tier allocation programs. Long-term viability hinges on warehouse capacity expansion and cooperage skill pipeline development rather than brand marketing alone. Watch for FSSAI import timeline compression as the inflection signal for Indian market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| NAS Expression Development | Compresses revenue realization timelines against aged-stock scarcity constraints. |
| Cask Finishing Innovation | Secondary maturation in ex-wine barrels commands enthusiast price premiums. |
| Direct-to-Consumer Launch | Membership clubs capture full margin on limited releases outside three-tier systems. |
| Carbon-Neutral Certification | EU Green Deal alignment resonates with ESG-mandated institutional buyers. |
| Indian Distribution Buildout | FSSAI timeline reduction opens paths for Scottish and Japanese volume players. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with master distillers, cooperage specialists, TTB compliance officers, and premium hospitality beverage directors with secondary validation from Scotch Whisky Association production data, TTB import filings, and bonded warehouse inventory disclosures. Bottom-up cask inventory modeling and top-down consumption trend analysis triangulated volume and value estimates.
Historical reference periods anchored the projection horizon to maturation cycle timelines and regulatory implementation phases, with CAGRs derived from segment-level growth rate reconciliation across product type, price tier, and distribution channel dimensions. Modeled inputs included aged-stock scarcity curves, barley harvest volatility patterns, and hospitality venue expansion rates in Singapore and London.
Underlying measurement precision varies by segment; luxury-tier auction data carries tighter precision than emerging direct-to-consumer channel estimates. Forecasts reflect assumptions around FSSAI alignment timelines and cooperage skill replenishment rates that could shift with regulatory acceleration or apprenticeship program expansion. Practitioners should monitor TTB labeling enforcement intensity and Indian state-level excise revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
East Africa Alcoholic Beverages Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Crystal Malt Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Beer Bottle Market