
 Europe Home Textile Market | 2026-2036
Europe Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Home Textile Market Analysis
Recycled polyester is pivoting toward virgin cotton in mid-tier bedding economics as energy costs and carbon accounting alter fiber sourcing decisions. IKEA Group leverages its captive cotton procurement networks across South Asia to sustain margin stability in European retail. Lenzing Group anchors its position through specialty cellulosic fiber R&D that differentiates its TENCEL-branded inputs from commodity alternatives. John Lewis plc competes on British-made heritage positioning that occupies a defensible niche against Scandinavian value players.
Europe home textiles encompass woven, knitted, and non-woven fabric products designed for interior residential and commercial environments, typically specified by thread count, fabric weight measured in grams per square meter, and flame-retardant certification for hospitality applications. These products serve functional purposes including thermal insulation, light control, hygiene maintenance, and aesthetic coordination of interior spaces. Bed linen and cushion covers dominate volume flows through European distribution channels, with cotton-based materials commanding the deepest margin pools due to consumer preference for breathability and natural fiber claims. The hospitality end-user segment generates the fastest expansion trajectory as hotel chains across Spain, Italy, and Portugal accelerate renovation cycles deferred during earlier economic uncertainty.
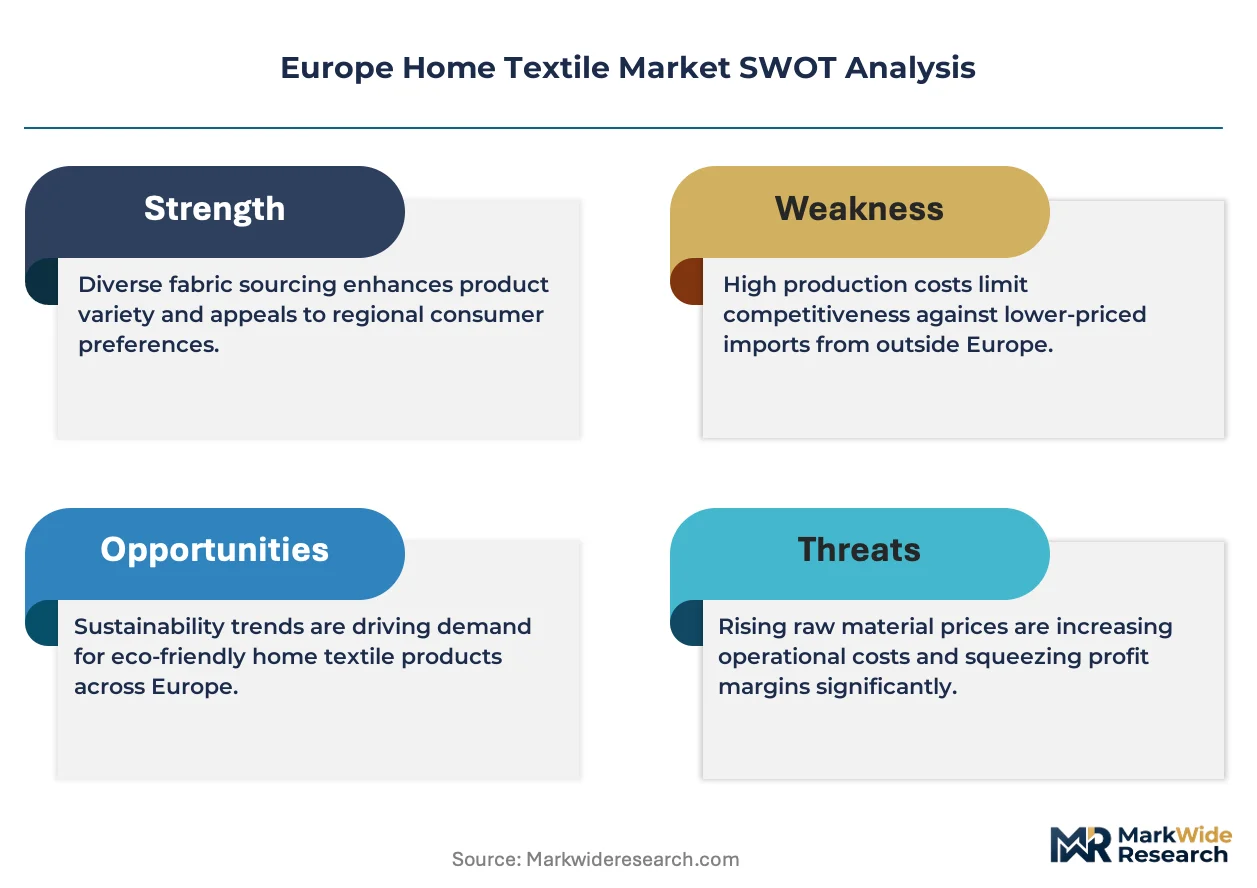
REACH regulation and the EU Green Deal textile strategy enforce chemical disclosure and extended producer responsibility requirements that reshape manufacturing compliance costs across the value chain. ECHA substance restrictions on formaldehyde and certain azo dyes directly limit formulation choices for printed curtain and tablecloth producers serving European buyers. Stakeholders must monitor how the EU AI Act's forthcoming product traceability mandates intersect with existing CSRD reporting obligations to determine whether digital labeling investments become competitive necessities or discretionary differentiators.
Market Dynamics
The EU Green Deal's textile strategy is compressing lead times for circular production certification while redirecting capital toward traceable supply chains. REACH chemical disclosure mandates and extended producer responsibility frameworks now determine which manufacturers retain access to hospitality procurement channels.
Growth Catalysts
- Hospitality renovation cycles:Hotel chains across Spain, Italy, and Portugal are accelerating linen replacement programs deferred during earlier economic uncertainty. Post-pandemic guest experience upgrades prioritize certified sustainable bedding.
- REACH compliance differentiation:ECHA substance restrictions on formaldehyde and azo dyes create competitive separation between compliant and non-compliant curtain producers. Manufacturers with verified chemical-free formulations capture premium positioning.
- Cellulosic fiber innovation:Specialty fiber R&D programs are commercializing alternative inputs that reduce water intensity compared to conventional cotton cultivation. These materials penetrate mid-tier bedding segments previously dominated by polyester blends.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings in Germany and Poland destabilize synthetic fiber production economics. Recycled polyester processing faces margin compression when grid tariffs spike.
- Supply concentration risk:Captive cotton procurement networks concentrate in South Asian agricultural zones. European converters remain exposed to monsoon variability and export policy shifts in origin countries.
- Regulatory friction from CSRD overlap:The EU AI Act's forthcoming product traceability mandates intersect with existing corporate sustainability reporting obligations. Manufacturers face ambiguous compliance sequencing without harmonized implementation timelines.
Strategic Opportunities
- Portuguese hospitality corridor:Algarve and Lisbon hotel construction pipelines lack qualified local linen suppliers. Regional production facilities could capture renovation contracts with shorter logistics loops than Asian competitors.
- Digital labeling convergence:Blockchain-based fiber provenance systems are integrating with EU Digital Product Passport requirements. Early movers secure data infrastructure advantages before 2030 mandatory disclosure deadlines.
- Flame-retardant certification gap:Hospitality procurement specifications increasingly require certified fire-resistant bedding. Domestic testing laboratories in France and Germany command premium pricing for rapid certification turnaround.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation expertise for bio-based flame retardants concentrates among retiring specialists in Swiss and German research institutes. Knowledge transfer programs struggle to attract polymer science graduates to textile applications.
- Circular production capex intensity:Mechanical recycling lines for post-consumer cotton require seven-figure capital commitments with five-year depreciation schedules. Mid-tier manufacturers defer investment pending demand certainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Home Textile Market |
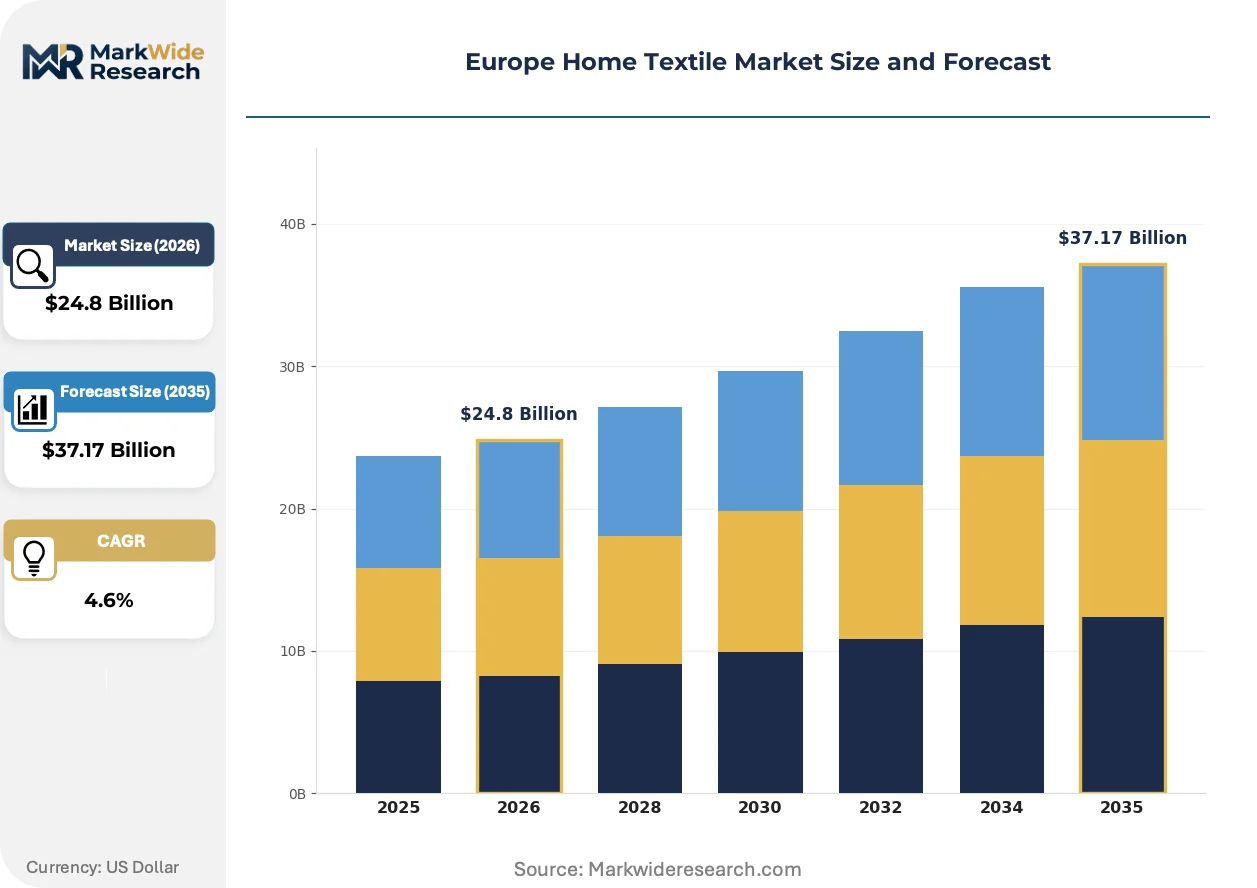
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bed Linen, Curtains, Cushion Covers, Tablecloths Material: Cotton, Polyester, Linen, Velvet End User: Residential, Hospitality, Institutional, Retail Distribution Channel: Online, Specialty Stores, Department Stores, Supermarkets |
| Companies Covered | Dunelm Group plc, Trident Group, IKEA Group, Hermès International, Lenzing Group, H&M Home, John Lewis plc, HORNBACH Group, JYSK, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Home Textile Market Emerging Trajectories
Digital traceability infrastructure is displacing paper-based certification while compressing supplier qualification timelines. Material science advances and regulatory disclosure mandates are converging to reshape fiber sourcing hierarchies.
Blockchain-enabled fiber provenance systems are integrating with ERP platforms across major hospitality procurement departments. Hotel chains in Germany and Scandinavia now require batch-level traceability data for cotton and cellulosic inputs. This technology is compressing supplier onboarding from quarterly cycles to monthly validations while elevating compliance costs for non-integrated competitors.
REACH substance restrictions are tightening formulation choices for printed curtain and tablecloth producers serving European buyers. ECHA's expanded candidate list now captures additional dye intermediates previously common in decorative textiles. Spanish and Italian converters are responding by consolidating supplier bases toward pre-certified chemical houses in the Basel region.
Certification-driven preference shifts are restructuring wholesale procurement relationships. Independent retailers in France and the Netherlands now prioritize OEKO-TEX and GOTS-labeled inventory over undifferentiated commodity bedding. This behavior concentrates volume toward vertically integrated mills with in-house certification capabilities, marginalizing trading-house intermediaries without direct manufacturing control.
Europe Home Textile Market Segmentation
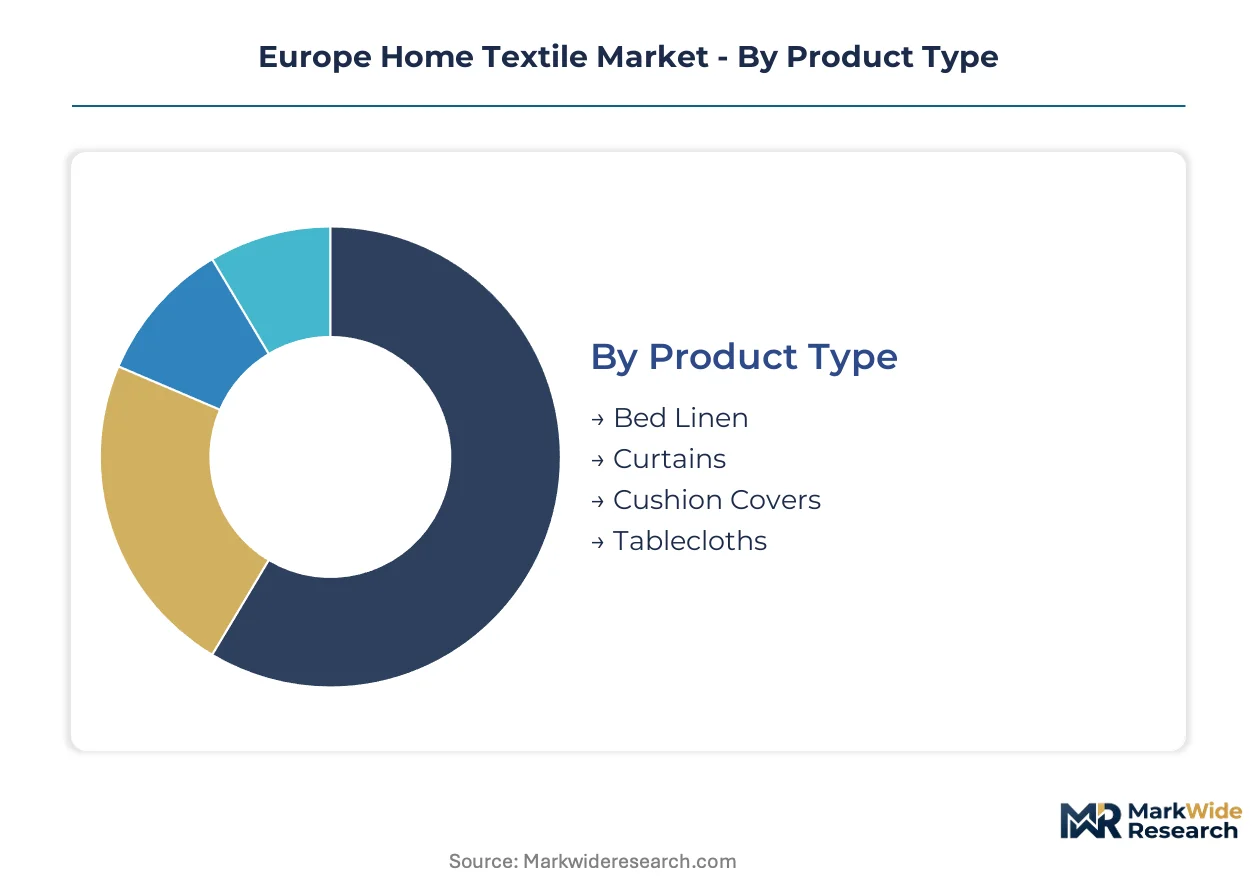
Home textile procurement in Europe operates through distinct specification tiers where certification requirements, fiber provenance, and end-use durability standards determine supplier eligibility. Segmentation reveals how REACH compliance and hospitality procurement protocols create divergent margin structures across product categories.
Product Type:
Certification burdens vary sharply across product categories: bed linen carries OEKO-TEX and GOTS requirements for skin contact, while curtains face additional flame-retardant testing under EN 13773 for hospitality contracts.
- Bed Linen:Thread-count specifications and GSM weight ratings define commercial grades for hospitality versus residential channels. German and Scandinavian hotel chains now mandate batch-level cotton traceability, compressing supplier pools toward vertically integrated mills with in-house certification capabilities.
- Curtains:Flame-retardant certification under EN 13773 and REACH dye restrictions constrain formulation choices for printed decorative textiles. Spanish and Italian converters consolidate supplier bases toward pre-certified chemical houses in the Basel region to ensure compliance.
- Cushion Covers:Decorative accessories with lower durability specifications than bed linen, serving frequent refresh cycles in residential and hospitality interiors.
- Tablecloths:Stain-resistant treatments and wash-cycle durability prioritize institutional food-service procurement over premium residential positioning.
Leading the category by volume: Bed Linen. Expanding most quickly: Curtains, driven by post-pandemic hospitality renovation cycles across Iberia and Italy.
Material:
Raw material selection determines energy intensity, water footprint, and eligibility for EU Green Deal circular production incentives.
- Cotton:Long-staple varieties command premium positioning in German retail, with captive procurement networks concentrated in South Asian agricultural zones. Monsoon variability and export policy shifts in origin countries expose European converters to supply concentration risk.
- Polyester:Recycled feedstock economics destabilize when German and Polish grid tariffs spike, altering fiber sourcing decisions toward virgin cotton in mid-tier bedding segments.
- Linen:Belgian and French flax cultivation supports heritage positioning with lower water intensity than conventional cotton, penetrating premium residential channels.
- Velvet:Dense pile construction requires specialized weaving equipment concentrated in Italian and Portuguese manufacturing clusters.
Highest margin capture: Cotton. Steepest expansion trajectory: Linen, as water-scarcity concerns reshape consumer preference hierarchies.
End User:
Procurement sophistication and compliance documentation requirements separate institutional buyers from discretionary residential purchasers.
- Residential:Individual consumers prioritize tactile quality and natural fiber claims, with French and Dutch independent retailers now favoring OEKO-TEX and GOTS-labeled inventory over undifferentiated commodity bedding.
- Hospitality:Hotel chains across Spain, Italy, and Portugal accelerate linen replacement programs deferred during earlier economic uncertainty, requiring certified sustainable bedding with batch-level traceability data.
- Institutional:Healthcare and educational facilities emphasize durability metrics and total cost-of-ownership over aesthetic differentiation.
- Retail:Corporate buyers for furniture and department store channels balance margin requirements with certification thresholds for private-label programs.
Deepest volume concentration: Residential. Gaining share fastest: Hospitality, as renovation cycles concentrate procurement toward qualified suppliers.
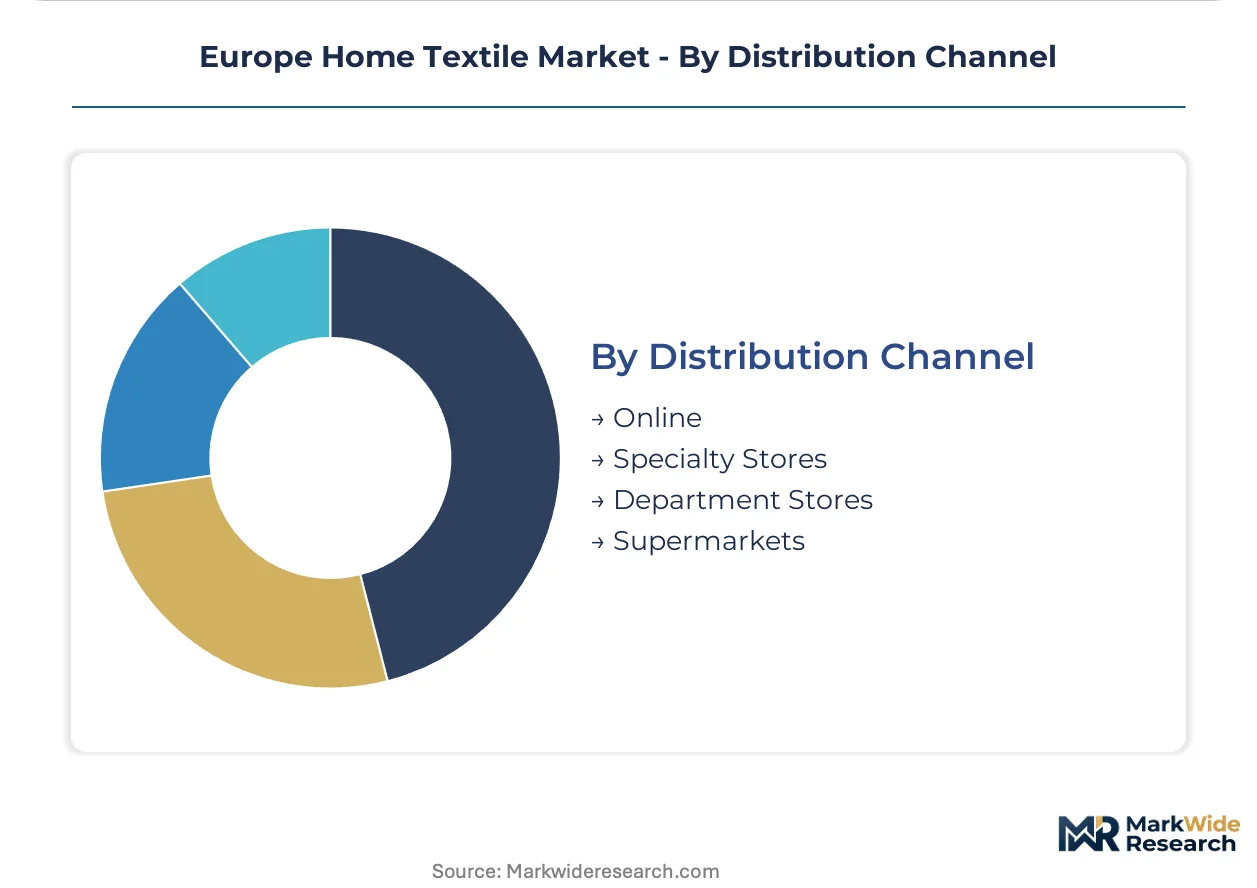
Distribution Channel:
Channel selection determines traceability data requirements, return logistics complexity, and exposure to direct-to-consumer margin compression.
- Online:Digital-native brands leverage blockchain-enabled provenance systems to compress supplier onboarding timelines, though last-mile returns logistics erode margin on bulky textile shipments.
- Specialty Stores:Curated assortments and staff expertise support premium positioning for heritage British-made and Scandinavian design-led collections.
- Department Stores:John Lewis plc and comparable retailers compete on British-made heritage positioning against value-oriented Scandinavian players, with private-label programs requiring vertical manufacturing control.
- Supermarkets:Volume-driven basic bedding and seasonal textile rotations prioritize cost efficiency over certification differentiation.
Climbing the fastest: Online, as digital labeling convergence with EU Digital Product Passport requirements reshapes competitive infrastructure. Dominant by transaction value: Department Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers command the deepest loyalty for premium bedding and curtain segments, driving higher average transaction values than any other European market. Hotel renovation cycles across Iberia and Italy are accelerating procurement of certified sustainable linens. REACH and EU Green Deal textile strategy requirements are redirecting manufacturer investment toward circular production systems continent-wide.
Germany
Premium bedding and curtain segments command exceptional consumer loyalty with higher average transaction values than neighboring markets. ECHA substance restrictions on formaldehyde and azo dyes directly limit formulation choices for domestic producers. The Stuttgart and Munich metropolitan areas concentrate specialty retailers competing on OEKO-TEX and GOTS certification differentiation.
Spain
Hotel chains across the Algarve corridor and Barcelona accelerate linen replacement programs deferred during earlier economic uncertainty. REACH chemical disclosure mandates determine which manufacturers retain access to hospitality procurement channels. Valencia hosts specialized weaving clusters serving flame-retardant certification requirements for institutional buyers.
Italy
Post-pandemic guest experience upgrades prioritize certified sustainable bedding across Milan and Rome hospitality markets. EU Green Deal textile sustainability requirements redirect manufacturer investment toward traceable supply chains. The Como silk district and Prato textile zone concentrate heritage producers consolidating supplier bases toward pre-certified chemical houses.
France
Independent retailers in Paris and Lyon now prioritize OEKO-TEX and GOTS-labeled inventory over undifferentiated commodity bedding. The EU AI Act's forthcoming product traceability mandates intersect with existing CSRD reporting obligations for domestic manufacturers. Lille and Roubaix anchor northern textile clusters adapting mechanical recycling lines for post-consumer cotton.
Netherlands
Digital-native brands leverage blockchain-enabled provenance systems to compress supplier onboarding timelines for Rotterdam and Amsterdam retail channels. Extended producer responsibility frameworks reshape manufacturing compliance costs for converters serving Benelux distribution networks. Eindhoven's technical textile research institutes support bio-based flame retardant formulation development.
Europe Home Textile Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical retail chains commanding volume in basic bedding while heritage positioning secures premium residential positioning. The vendor base organizes around three strategic archetypes: Scandinavian value players leveraging captive cotton procurement networks, British heritage specialists competing on domestic manufacturing claims, and Austrian-German fiber innovators differentiating through specialty cellulosic R&D. Competitive moves concentrate on M&A for certification capabilities and geographic expansion into Portuguese hospitality corridors.
Among British heritage specialists, Dunelm Group plc and John Lewis plc occupy positions defined by domestic manufacturing narratives that resist Scandinavian value competition. IKEA Group exemplifies the scale-driven archetype through its South Asian captive procurement networks. Lenzing Group anchors the fiber innovation tier through TENCEL-branded specialty cellulosic inputs that reduce water intensity versus conventional cotton cultivation.
| Leading Market Players |
|---|
| Dunelm Group plc |
| Trident Group |
| IKEA Group |
| Hermès International |
| Lenzing Group |
| H&M Home |
| John Lewis plc |
| HORNBACH Group |
| JYSK |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap weavers in Belgium and northern Italy anchor supply discipline through generational capital patience, insulating premium linen and heritage cotton segments from the margin volatility that pressures PE-rolled synthetic fiber specialists. This ownership pattern concentrates pricing power in OEKO-TEX-certified tier-one suppliers while forcing commodity converters into cost-pass-through fragility when REACH compliance costs spike.
Pricing Analysis
Volume concentrates in undifferentiated bed linen through German and Scandinavian mass retailers, while margin pools deepen in certified sustainable tiers where hospitality procurement mandates batch-level traceability. Three-tier pricing structure across premium heritage, certified mid-market, and economy private-label segments separates OEKO-TEX and GOTS-labeled inventory from commodity alternatives. Cost compression in recycled polyester bedding intensifies because German and Polish grid tariff volatility erodes synthetic fiber processing economics. Hospitality buyers show least price sensitivity due to guest experience upgrade mandates, whereas supermarket channel procurement exhibits acute cost consciousness.
Supply Chain Analysis
REACH and EU Green Deal qualification gates compress supplier pools toward vertically integrated mills with in-house certification capabilities, marginalizing trading-house intermediaries. Geographic concentration centers on India, Pakistan, and Bangladesh for long-staple cotton cultivation, with Belgian and French flax cultivation supporting premium linen heritage positioning. Raw material dependencies rest on South Asian monsoon patterns for cotton fiber, Austrian cellulosic specialty inputs from Lenzing, and Basel-region pre-certified dye intermediates. Single-source vulnerability concentrates in captive cotton procurement networks exposed to export policy shifts in origin countries. Distribution runs through hospitality procurement departments, department store private-label programs, and digital-native direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe home textile market functions as a cost-of-compliance story where REACH substance restrictions and extended producer responsibility frameworks erect barrier-to-entry moats that favor pre-certified incumbents with amortized compliance infrastructure.
For Market Incumbents: Deepen backward integration into South Asian cotton procurement networks to secure fiber supply against monsoon variability and export policy volatility. Reinforce certification capabilities through in-house OEKO-TEX and GOTS testing laboratories that compress supplier onboarding timelines for hospitality clients. The threat of digital-native brands with blockchain-enabled provenance systems demands preemptive data infrastructure investment before EU Digital Product Passport mandates crystallize.
For New Entrants and Emerging Players: Capture the Portuguese hospitality corridor where Algarve and Lisbon hotel construction pipelines lack qualified local linen suppliers with REACH-compliant production. Target flame-retardant certification services for institutional buyers, where domestic testing laboratories in France and Germany command premium pricing for rapid EN 13773 turnaround. A go-to-market angle anchored in regional production facilities with shorter logistics loops than Asian competitors bypasses incumbent scale advantages.
For Investors and Strategic Acquirers: M&A activity consolidating certification capabilities among mid-tier Italian and Spanish converters is the leading indicator that compliance infrastructure is becoming the scarce competitive asset. Long-term viability over a multi-year horizon favors vertically integrated mills with in-house dye formulation and mechanical recycling lines over trading-house intermediaries without manufacturing control. The signal to monitor is hospitality procurement departments mandating blockchain-enabled batch-level traceability as a contractual prerequisite.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Capability Acquisition | Captures OEKO-TEX and GOTS infrastructure that hospitality procurement now mandates. |
| Portuguese Hospitality Corridor Expansion | Establishes regional production foothold where qualified local suppliers remain scarce. |
| Blockchain Provenance System Deployment | Aligns data infrastructure with EU Digital Product Passport disclosure deadlines. |
| Specialty Cellulosic Fiber R&D Partnership | Reduces water intensity versus cotton while differentiating from commodity polyester. |
| Mechanical Recycling Line Investment | Positions for circular production incentives under EU Green Deal textile strategy. |
Methodological Framework
Multi-period observation of hospitality renovation cycle velocity, REACH enforcement intensity, and fiber substitution patterns anchored the trend analysis, supplemented by interviews with procurement directors at German and Scandinavian hotel chains, category buyers at British and Dutch department stores, technical directors at Belgian and Italian weaving mills, and regulatory affairs leads at fiber producers. Secondary validation drew from ECHA substance restriction updates, EU Green Deal textile strategy documentation, customs data on cotton and cellulosic fiber imports, and hospitality industry capital expenditure disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Input-output matrices mapped fiber sourcing costs, certification compliance expenditures, and channel margin structures across product type, material composition, end-user segment, and distribution channel dimensions. CAGRs were derived from trend extrapolation moderated by regulatory phase-in schedules and capital investment cycle timing. Forecast inputs included energy price trajectory assumptions for German and Polish synthetic fiber production, South Asian agricultural yield projections, and hospitality construction pipeline data for Iberia and Italy.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act traceability mandate implementation sequencing and CSRD reporting obligation harmonization. Forecasts reflect assumptions regarding regulatory timeline adherence, monsoon pattern stability, and grid tariff normalization that material deviation would revise. A model refresh is warranted upon material change in REACH substance restriction scope or EU Digital Product Passport technical specification release.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Bangladesh Home Textile Market
Home Textiles
Saudi Arabia Home Textile Market
Home Textiles
Japan Home Textile Market
Home Textiles
Turkey Home Textile Market
Home Textiles
Baby Crib Sheet Market
Home Textiles
Linen Bed Sheets Market
Home Textiles
Bath Towel Market
Home Textiles
Cotton Towel Market
Home Textiles
Towel Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Microfiber Cleaning Cloth Market
Home Textiles
Asia-Pacific Home Textile Market
Home Textiles
Canada Home Textile Market
Home Textiles
Australia Home Textiles Market
Home Textiles
Russia Home Textile Market
Home Textiles
United Kingdom Home Textile Market