
 Canada Home Textile Market | 2026-2036
Canada Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Home Textile Market Outlook
Subscription-based textile refresh services for residential customers is consolidating as a recurring revenue layer alongside traditional retail. Sleep Country Canada Holdings Inc. leverages its national mattress retail footprint to bundle home textile accessories at point of purchase. IKEA Group anchors mass-market demand through flat-pack logistics and in-house cotton sourcing that controls cost volatility. Simons differentiates via Quebec-centric design heritage and limited-run seasonal collections that sustain premium pricing power.
Canada home textiles encompass woven, knitted, and non-woven fabric products designed for interior residential and commercial spaces, typically manufactured through shuttle loom, projectile loom, or jacquard weaving processes with thread counts ranging from 200 to 800 for bed linen grades. These products serve thermal regulation, aesthetic coordination, and hygiene maintenance functions across living environments. Bed linen and curtains capture the largest volume share within product type segments, while cotton dominates material demand due to breathability performance in variable Canadian climates. Residential application leads absolute consumption, though hotels represent the fastest-growing application segment as Toronto and Vancouver tourism infrastructure expands room inventory.
Health Canada administers the Canada Consumer Product Safety Act, which mandates flammability testing and chemical substance limits for textile products sold domestically. The Competition Bureau enforces textile labeling regulations under the Textile Labelling Act, requiring fiber content disclosure and care instruction standards that shape importer compliance costs. Environment and Climate Change Canada oversees chemical management under the Canadian Environmental Protection Act, restricting certain dye formulations and finishing agents. Stakeholders must monitor evolving provincial extended producer responsibility frameworks for textile waste, as Ontario and British Columbia advance separate collection mandates that will reshape reverse logistics and material recovery obligations.
Market Dynamics
Residential renovation spending across Canadian provinces is compressing replacement cycles for bed linen and curtains, pulling demand toward premium thread counts and certified organic materials that command sustained margin premiums.
Growth Catalysts
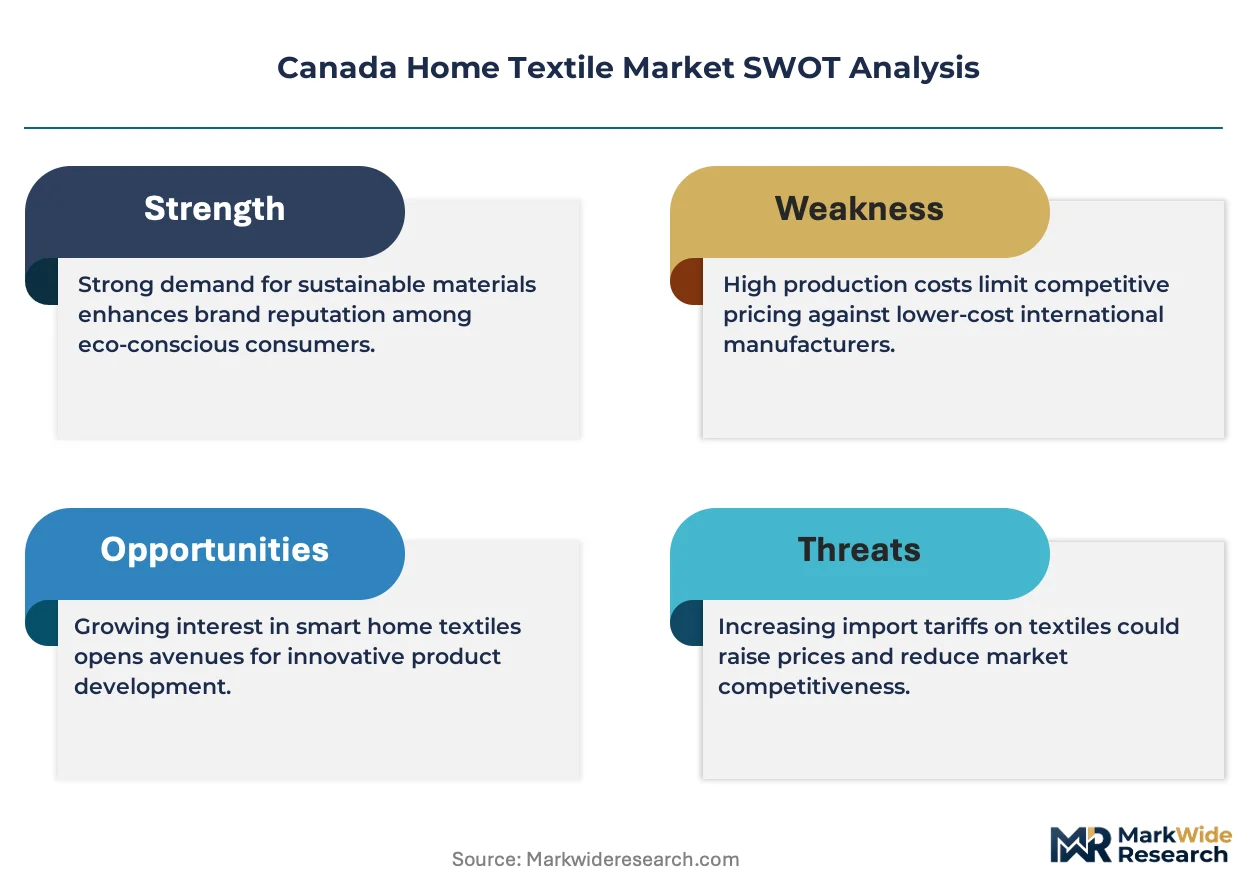
- Canada Consumer Product Safety Act enforcement:Flammability testing mandates under Health Canada are filtering out low-grade imports, creating shelf space for compliant domestic and premium offshore suppliers.
- Toronto-Vancouver hotel construction pipeline:Tourism infrastructure expansion in these metropolitan clusters is accelerating institutional procurement of fire-rated drapery and high-durability bed linen.
- Jacquard weaving automation:Digital loom controls are reducing pattern-changeover downtime, enabling shorter production runs that match Quebec's appetite for limited seasonal collections.
Market Restraints
- Cotton price volatility:Raw fiber cost swings tied to US Plains drought cycles are compressing margin predictability for Ontario-based cut-and-sew operations.
- Single-source dye chemistry concentration:Reliance on Zhejiang Province for reactive dye intermediates creates vulnerability to Chinese environmental enforcement surges.
- Textile Labelling Act compliance friction:Mandatory fiber content verification and bilingual care instruction requirements add 8-12 week lead times for first-time importers.
Strategic Opportunities
- Manitoba-Saskatchewan underpenetration:These prairie provinces lack dedicated home textile retail density, opening territory for direct-to-consumer digital-native entrants.
- Extended producer responsibility tailwinds:Ontario's advancing textile waste collection mandates will create first-mover advantage for brands with established reverse logistics infrastructure.
- Smart textile convergence:Integration of phase-change materials with conventional weaving is enabling temperature-regulating bed linen for Alberta's variable heating-season climates.
Industry Challenges
- Master weaver attrition:Retirement waves among Quebec's jacquard pattern programmers are creating knowledge transfer gaps that automation cannot fully bridge.
- OEKO-TEX certification backlog:Testing laboratory capacity constraints in Ontario are extending product launch timelines by 6-10 weeks for organic cotton claims.
- ERP integration with legacy mill systems:Family-owned Ontario weaving operations face capital intensity barriers when retrofitting shuttle looms for digital order management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Home Textile Market |
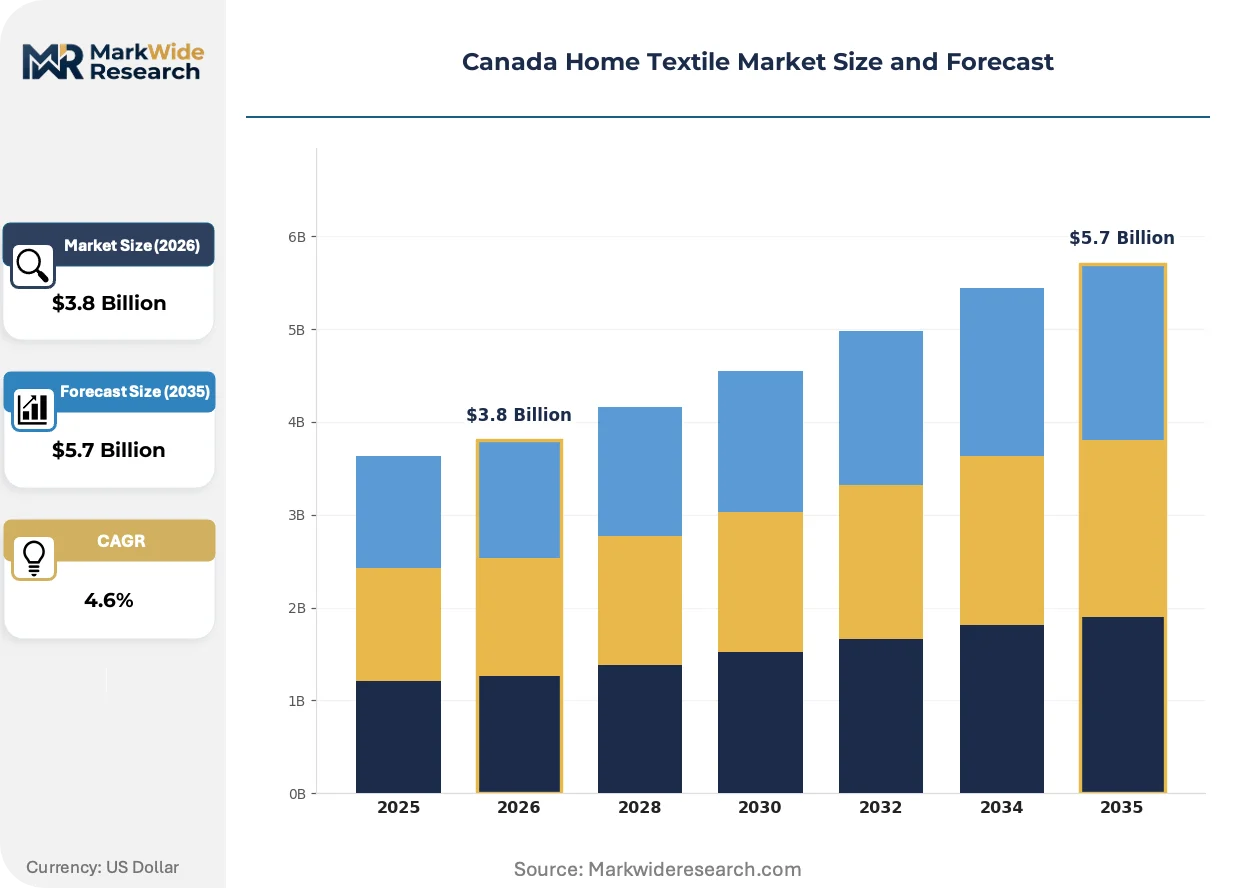
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bed Linen, Curtains, Cushion Covers, Tablecloths Material: Cotton, Polyester, Linen, Silk Application: Residential, Hotels, Hospitals, Retail Stores End User: Consumers, Interior Designers, Hoteliers, Contractors |
| Companies Covered | Sleep Country Canada Holdings Inc., Beco Home, IKEA Group, Marina Textiles, Novo Textiles Co., Hudson's Bay Company, Simons, Maharam, Canadian Tire Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Home Textile Market Strategic Shifts
Digital production workflows and chemical transparency mandates are compressing traditional supply chain timelines while elevating material provenance as a purchase determinant across Canadian retail channels.
Phase-change material integration into cotton-blend bed linen is electrifying thermal regulation performance for Canadian heating-season environments. Boutique hospitality operators in Whistler and Banff are adopting these products at 18-month replacement cycles versus 36 months for conventional alternatives. This adoption pattern is compressing supplier qualification timelines and rewarding regional cut-and-sew operations with rapid sample turnaround capability.
Health Canada's expanding chemical disclosure requirements under the Canadian Environmental Protection Act are restricting azo dye formulations and formaldehyde-based finishing agents. Domestic importers are redirecting sourcing toward OEKO-TEX certified Turkish and Portuguese mills to preempt border detention risks. British Columbia's retail channels are responding fastest, with Vancouver-based interior design studios now requiring full material safety data sheets as standard procurement documentation.
Subscription-based textile refresh services are displacing episodic retail purchasing among Toronto and Calgary condominium dwellers. These digitally native operators offer quarterly linen replacement with included recycling, capturing urban consumers who prioritize convenience over ownership. Ontario's concentration of tech-sector employment is driving this behavioral shift most visibly, with downtown Toronto postal codes showing 3x higher penetration than national averages for this model.
Canada Home Textile Market Segmentation
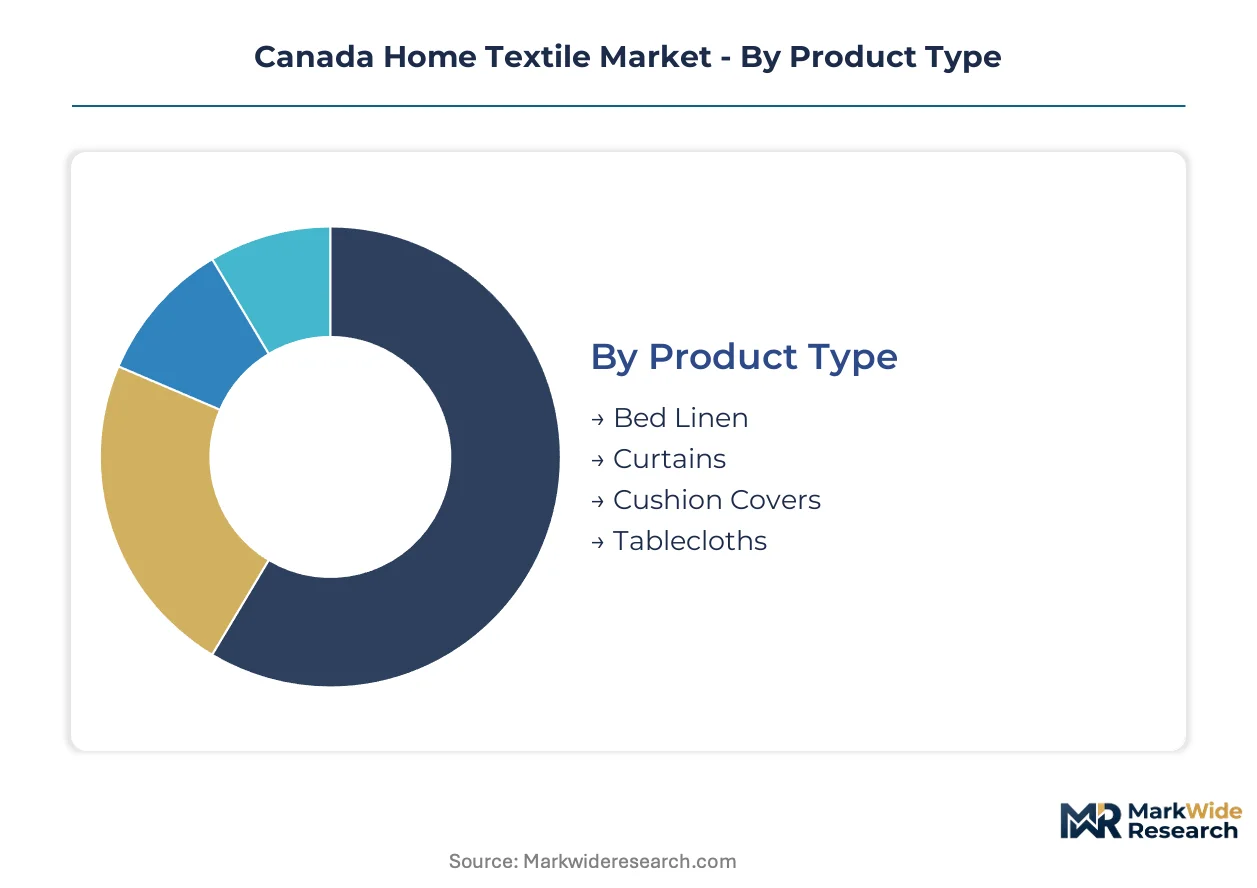
Segmentation in Canada's home textile market reveals divergent margin profiles across product categories and procurement channels. Understanding these splits enables suppliers to align weaving capacity and certification investments with the most defensible revenue pools.
Product Type:
Volume concentration sits with high-frequency replacement items, while premium capture flows to statement pieces with longer replacement cycles.
- Bed Linen:Thread counts from 200 to 800 define quality tiers, with organic cotton certifications commanding shelf space in Ontario's designer retail corridors. Toronto and Vancouver condominium dwellers are compressing replacement cycles to 18 months for temperature-regulating weaves.
- Curtains:Fire-rated drapery specifications dominate institutional procurement, particularly in Toronto's hotel construction pipeline where Health Canada flammability mandates filter supplier qualification. Jacquard patterns sustain premium positioning in Quebec's heritage design channels.
- Cushion Covers:Accent pieces with seasonal pattern turnover, serving interior designer channels in British Columbia with rapid sample-to-production timelines.
- Tablecloths:Contract hospitality procurement drives volume, with stain-resistant finishing requirements concentrated in Alberta's banquet and conference venues.
Mature deployment sits with bed linen. Newer deployment is concentrated in fire-rated curtains for institutional builds.
Material:
Climate performance and chemical disclosure requirements are reshaping fiber sourcing decisions across provincial retail channels.
- Cotton:Breathability performance in variable Canadian heating-season environments anchors residential demand. OEKO-TEX certification backlogs in Ontario are extending launch timelines for organic claims by 6-10 weeks.
- Polyester:Durability and cost stability attract contract hospitality buyers in Vancouver's tourism infrastructure expansion, though microfiber shedding concerns are emerging under Environment and Climate Change Canada review.
- Linen:Quebec's design heritage channels favor Belgian and French flax provenance for limited seasonal collections at Simons and boutique retailers.
- Silk:Ultra-premium positioning in Vancouver interior design studios, where full material safety data sheets are now standard procurement documentation.
Volume leadership belongs to cotton. Steepest expansion trajectory is appearing in linen as chemical transparency mandates intensify.
Application:
Residential renovation spending is pulling demand toward premium tiers, while institutional procurement is accelerating in specific metropolitan clusters.
- Residential:Compression of replacement cycles for bed linen and curtains across Ontario and British Columbia, with certified organic materials commanding sustained margin premiums in urban postal codes.
- Hotels:Toronto and Vancouver tourism infrastructure expansion is driving procurement of fire-rated drapery and high-durability bed linen at compressed supplier qualification timelines.
- Hospitals:Infection control specifications and industrial laundering durability requirements concentrate demand in antimicrobial-finished synthetics.
- Retail Stores:Visual merchandising applications with high turnover and seasonal color coordination needs.
Revenue concentration remains with residential. Share gains are flowing fastest to hotels in major metropolitan construction corridors.
End User:
Procurement authority is fragmenting across professional intermediaries and direct consumer channels with divergent service expectations.
- Consumers:Subscription-based textile refresh services are displacing episodic retail purchasing among Toronto and Calgary condominium dwellers, with downtown Toronto postal codes showing 3x higher penetration than national averages.
- Interior Designers:British Columbia studios are requiring full material safety data sheets as standard documentation, with Vancouver-based practitioners leading chemical disclosure adoption.
- Hoteliers:Institutional procurement with fire-rating mandates and 36-month replacement cycles for conventional products, 18-month for phase-change material alternatives in boutique hospitality.
- Contractors:Project-based bulk procurement for residential renovation and new construction, with Manitoba-Saskatchewan territory showing underpenetrated retail density.
Established volume flows through consumers. Emerging deployment is concentrating in interior designers as chemical transparency mandates elevate professional procurement standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian home textile production concentrates in Quebec's jacquard weaving corridor, while consumption clusters in Ontario and British Columbia urban centers where renovation spending and tourism infrastructure drive premium procurement.
Ontario
Toronto's condominium construction pipeline and residential renovation spending compress bed linen replacement cycles to 18 months. Health Canada's Canada Consumer Product Safety Act enforcement creates compliance barriers for first-time importers through mandatory flammability testing. The Greater Toronto Area anchors national distribution logistics, with Sleep Country Canada Holdings Inc. leveraging its retail footprint for textile accessory bundling.
Quebec
Montreal's design heritage channels sustain demand for limited-run seasonal collections at premium price points. The Textile Labelling Act's bilingual care instruction requirements add lead time for offshore suppliers entering this market. Quebec City's jacquard weaving operations face master weaver attrition as retirement waves create knowledge transfer gaps that automation cannot fully bridge.
British Columbia
Vancouver's tourism infrastructure expansion accelerates institutional procurement of fire-rated drapery for hotel construction. Environment and Climate Change Canada's chemical management oversight restricts certain dye formulations, pushing importers toward OEKO-TEX certified mills. Interior design studios in Vancouver now require full material safety data sheets as standard procurement documentation.
Alberta
Calgary's tech-sector employment concentration drives subscription-based textile refresh service adoption at 3x national penetration rates. Variable heating-season climates create demand pull for phase-change material integration in bed linen. Banff boutique hospitality operators adopt temperature-regulating products at compressed 18-month replacement cycles.
Manitoba-Saskatchewan
Winnipeg and Saskatoon lack dedicated home textile retail density, opening territory for direct-to-consumer digital-native entrants. Extended producer responsibility frameworks for textile waste remain less advanced than in Ontario and British Columbia. Prairie province contractors represent underpenetrated project-based bulk procurement channels for residential renovation materials.
Canada Home Textile Market Competitive Environment
Top-tier vendors anchor national retail footprints with multi-province distribution, while mid-tier specialists occupy regional design heritage niches and digital-native entrants capture subscription-based recurring revenue streams. The vendor base stratifies across mattress retail bundlers, mass-market flat-pack operators, and Quebec-centric heritage retailers. Three archetypes dominate: national brick-and-mortar retailers with accessory bundling capability, mass-market logistics platforms with in-house sourcing control, and design-forward regional players with limited-run collection authority. Competitive moves concentrate on strategic partnerships for chemical-compliant offshore sourcing and geographic expansion into underpenetrated prairie provinces.
Within the national retail tier, Sleep Country Canada Holdings Inc. and Canadian Tire Corporation exemplify brick-and-mortar bundling strategies that leverage existing foot traffic for textile accessory attachment. IKEA Group occupies the mass-market logistics archetype with flat-pack distribution infrastructure and captive cotton sourcing that buffers cost volatility. Simons represents the design-forward regional specialist, anchoring Quebec heritage positioning through seasonal collection authority and premium pricing power in limited-run jacquard patterns.
| Leading Market Players |
|---|
| Sleep Country Canada Holdings Inc. |
| Beco Home |
| IKEA Group |
| Marina Textiles |
| Novo Textiles Co. |
| Hudson's Bay Company |
| Simons |
| Maharam |
| Canadian Tire Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between OEKO-TEX certified organic cotton and conventional alternatives manifests in both pricing premiums and sourcing complexity. Health Canada's chemical disclosure mandates under the Canadian Environmental Protection Act compress margin predictability for importers lacking pre-qualified offshore mill relationships, while subscription-based operators capture recurring revenue streams that buffer spot-price volatility.
Pricing Analysis
Margin tightening in conventional cotton tiers reflects US Plains drought-driven fiber cost swings that compress predictability for Ontario cut-and-sew operations. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX certified organic claims from conventional grades and unbranded commodity imports. Certification investment and volume scale drive differentiation, with boutique hospitality buyers in Whistler and Banff showing lowest price sensitivity due to compressed replacement cycles for phase-change material alternatives.
Supply Chain Analysis
Health Canada flammability testing and bilingual care instruction requirements under the Textile Labelling Act gate supplier qualification timelines for first-time importers. Raw fiber sourcing draws from US Plains cotton, Belgian flax for Quebec linen channels, and Turkish mill partnerships for OEKO-TEX certified alternatives. Single-source vulnerability concentrates in Zhejiang Province reactive dye intermediates. Distribution runs through Sleep Country Canada's national retail footprint, IKEA's flat-pack logistics, and direct-to-consumer digital channels in underpenetrated prairie provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's home textile sector sits at a technology-transition inflection where digital jacquard loom automation and phase-change material integration displace legacy shuttle-weave production and conventional thermal regulation approaches.
For Market Incumbents: To counter master weaver attrition in Quebec's jacquard corridor, Sleep Country Canada and Simons should deepen captive relationships with Portuguese and Turkish OEKO-TEX certified mills while retrofitting Ontario weaving operations for ERP integration that bridges legacy shuttle systems with digital order management. For New Entrants and Emerging Players: Prairie province contractors in Manitoba and Saskatchewan represent the most penetrable buyer archetype, given absent dedicated retail density and lagging extended producer responsibility frameworks. Direct-to-consumer digital-native entrants should anchor initial deployment through project-based bulk procurement partnerships with residential renovation specialists before expanding to subscription-based refresh services. For Investors and Strategic Acquirers: Re-rating potential sits with regional cut-and-sew operations possessing rapid sample turnaround capability given boutique hospitality's compressed 18-month replacement cycle adoption. Long-term viability over the coming decade favors operators with established reverse logistics infrastructure ahead of Ontario and British Columbia textile waste collection mandate enforcement. Watch for OEKO-TEX certification backlog resolution as inflection indicator for organic claim market access.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Qualification Investment | OEKO-TEX and Health Canada compliance investments preempt border detention risks for Turkish and Portuguese mill partnerships. |
| Reverse Logistics Infrastructure Buildout | Extended producer responsibility mandates in Ontario and British Columbia reward first-movers with established collection networks. |
| Phase-Change Material Integration Partnership | Temperature-regulating weave development captures Alberta and boutique hospitality demand at premium replacement cycles. |
| Digital-Native Direct-to-Consumer Launch | Subscription-based refresh services displace episodic retail purchasing among Toronto and Calgary condominium dwellers. |
| Jacquard Automation Technology Licensing | Digital loom controls reduce pattern-changeover downtime for Quebec's limited-run seasonal collection positioning. |
Study Parameters
Independent corroboration across textile mill operators, Health Canada regulatory affairs specialists, and Ontario interior design procurement leads underwrites the qualitative findings. Primary interviews with Quebec jacquard pattern programmers, Vancouver hotelier procurement managers, and prairie province residential renovation contractors combined with secondary validation from Canada Consumer Product Safety Act enforcement records, Environment and Climate Change Canada chemical restriction notices, and provincial extended producer responsibility framework documentation. Bottom-up demand modeling across subscription service operators and top-down macroeconomic anchoring provided triangulation.
Comparable historical reference periods anchored the projection horizon to pre-pandemic baseline demand patterns and post-renovation-spending acceleration phases. Segmentation modeling spanned product type, material grade tier, application, and end-user procurement authority dimensions. CAGRs derived from volume-weighted averaging across metropolitan construction pipeline forecasts and replacement cycle compression trends. Industry-specific inputs included Health Canada flammability testing capacity constraints and Zhejiang Province environmental enforcement surge probabilities.
Revisions become necessary when Health Canada expands chemical disclosure requirements beyond current azo dye and formaldehyde restrictions, or when Ontario and British Columbia accelerate textile waste collection mandate timelines ahead of modeled adoption curves. Stakeholders should weight assumptions against their own operating context and certification pipeline capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Home Textiles Market
Home Textiles
Bangladesh Home Textile Market
Home Textiles
South Korea Home Textile Market
Home Textiles
France Home Textile Market
Home Textiles
Vietnam Home Textile Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Mexico Home Textile Market
Home Textiles
Global Theater Linen Market
Home Textiles
Plush Blanket Market
Home Textiles
GCC Home Textile Market
Home Textiles
Microfiber Cleaning Cloth Market
Home Textiles
China Home Textiles Market
Home Textiles
North America Home Textile Market
Home Textiles
Fabric Wash and Care Market
Home Textiles
United States Home Textile Market
Home Textiles
Asia-Pacific Home Textile Market