
 Microfiber Cleaning Cloth Market | 2026-2036
Microfiber Cleaning Cloth Market Size, Share, and Industry Trends Forecast 2026-2036
Microfiber Cleaning Cloth Market Foresight
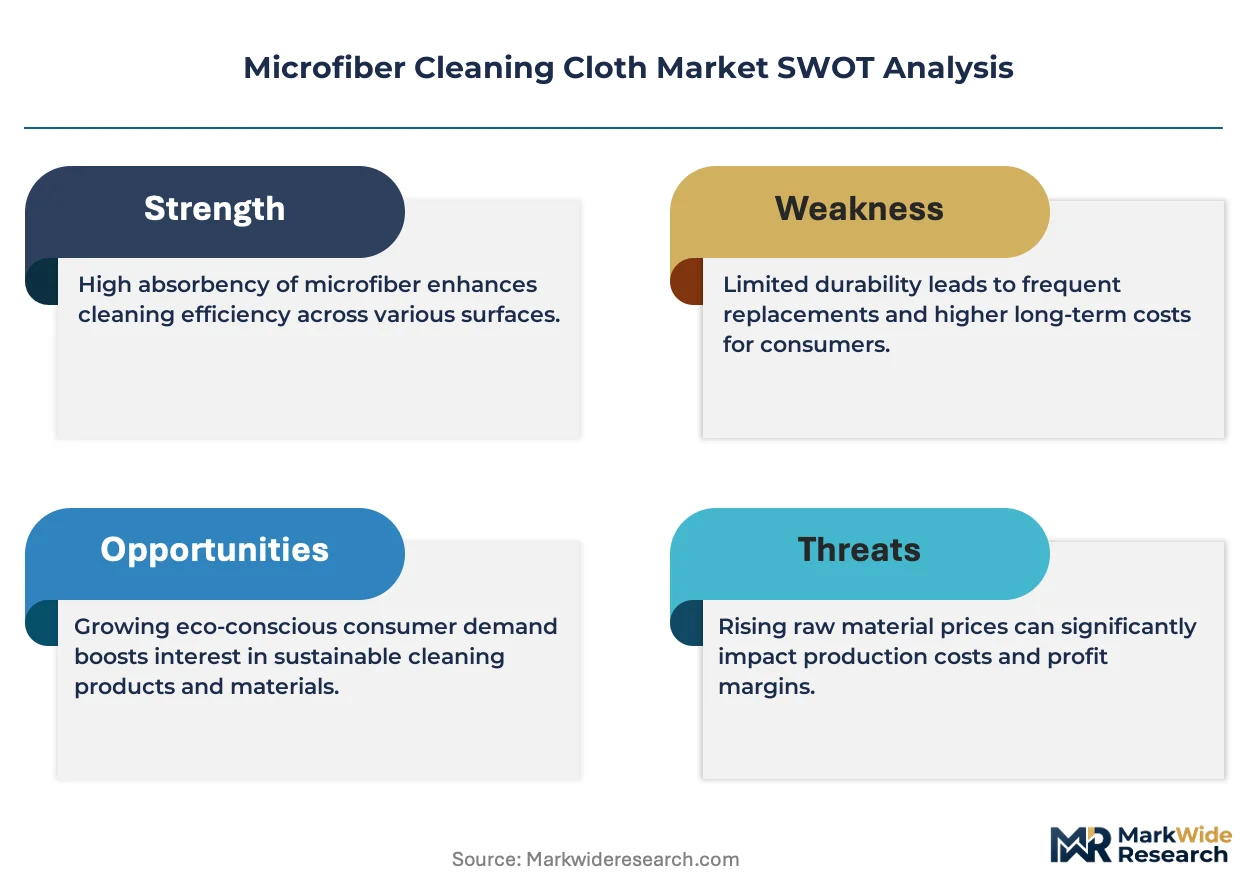
ISO 9001 certification is reorganizing supplier eligibility for institutional procurement contracts across the microfiber cleaning cloth value chain. Toray Industries leverages its filament manufacturing scale to supply premium polyester-polyamide substrates to downstream converters. Scotch-Brite competes through brand recognition in North American retail channels, while Freudenberg Home and Cleaning Solutions anchors European private-label production with integrated nonwoven capabilities.
Microfiber cleaning cloths are woven or knitted textiles composed of synthetic fibers typically below one denier in diameter, with polyester-polyamide blends engineered to capture particulates through electrostatic attraction and capillary action. General purpose cloths dominate volume shipments due to universal household penetration, while healthcare facilities represent the fastest-growing application area as hospitals replace cotton mops with launderable microfiber systems to reduce cross-contamination. Eco-friendly fibers command premium positioning as commercial buyers face Scope 3 emissions reporting obligations.
EPA Design for the Environment criteria influence chemical-free cleaning claims in the United States, while REACH compliance governs azo dye and heavy metal restrictions for European imports. The EU Ecodesign for Sustainable Products Regulation will extend digital product passport requirements to textile cleaning tools, reshaping supplier documentation burdens. Stakeholders must monitor evolving textile recycling infrastructure investments to assess closed-loop feedstock availability for recycled polyester microfiber production.
Market Dynamics
The EU Ecodesign for Sustainable Products Regulation is compressing supplier documentation timelines while antimicrobial microfiber specifications are tightening eligibility for healthcare procurement contracts across institutional buyers.
Growth Catalysts
- Antimicrobial Filament Integration:Healthcare facilities are mandating silver-ion or copper-infused microfiber substrates for infection control protocols in operating theaters and patient rooms.
- REACH Compliance as Market Gate:European import restrictions on azo dyes and heavy metals are filtering out low-cost Asian suppliers unable to certify chemical-free production.
- Germany's Facility Management Concentration:Bundled service contracts in Frankfurt and Munich are specifying ISO 9001-certified microfiber standards, consolidating demand around qualified vendors.
Market Restraints
- Petrochemical Feedstock Volatility:Polyester and polyamide resin prices fluctuate with crude oil indices, squeezing converter margins on fixed-price institutional contracts.
- Filament Manufacturing Concentration:Premium denier fiber production clusters in Japan and South Korea, creating single-source vulnerability for European and North American weavers.
- Laundering Infrastructure Gaps:Commercial microfiber systems require industrial wash cycles above 60°C to maintain antimicrobial efficacy, limiting deployment where on-premise laundry capacity is absent.
Strategic Opportunities
- India's Healthcare Expansion:Hospital accreditation standards under the National Accreditation Board for Hospitals are driving first-time microfiber adoption in tier-2 and tier-3 cities.
- Digital Product Passport Mandates:The EU Ecodesign Regulation's traceability requirements will favor suppliers with blockchain-enabled fiber provenance systems.
- Recycled Polyester Feedstock:Chemical recycling infrastructure investments in the Netherlands and Belgium are opening closed-loop supply channels for post-consumer PET microfiber production.
Industry Challenges
- ISO 9001 Certification Timelines:Small-scale converters face 12-18 month accreditation periods, delaying eligibility for institutional tenders.
- Antimicrobial Efficacy Testing Costs:Third-party validation of silver-ion retention through 150+ wash cycles requires capital-intensive laboratory partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microfiber Cleaning Cloth Market |
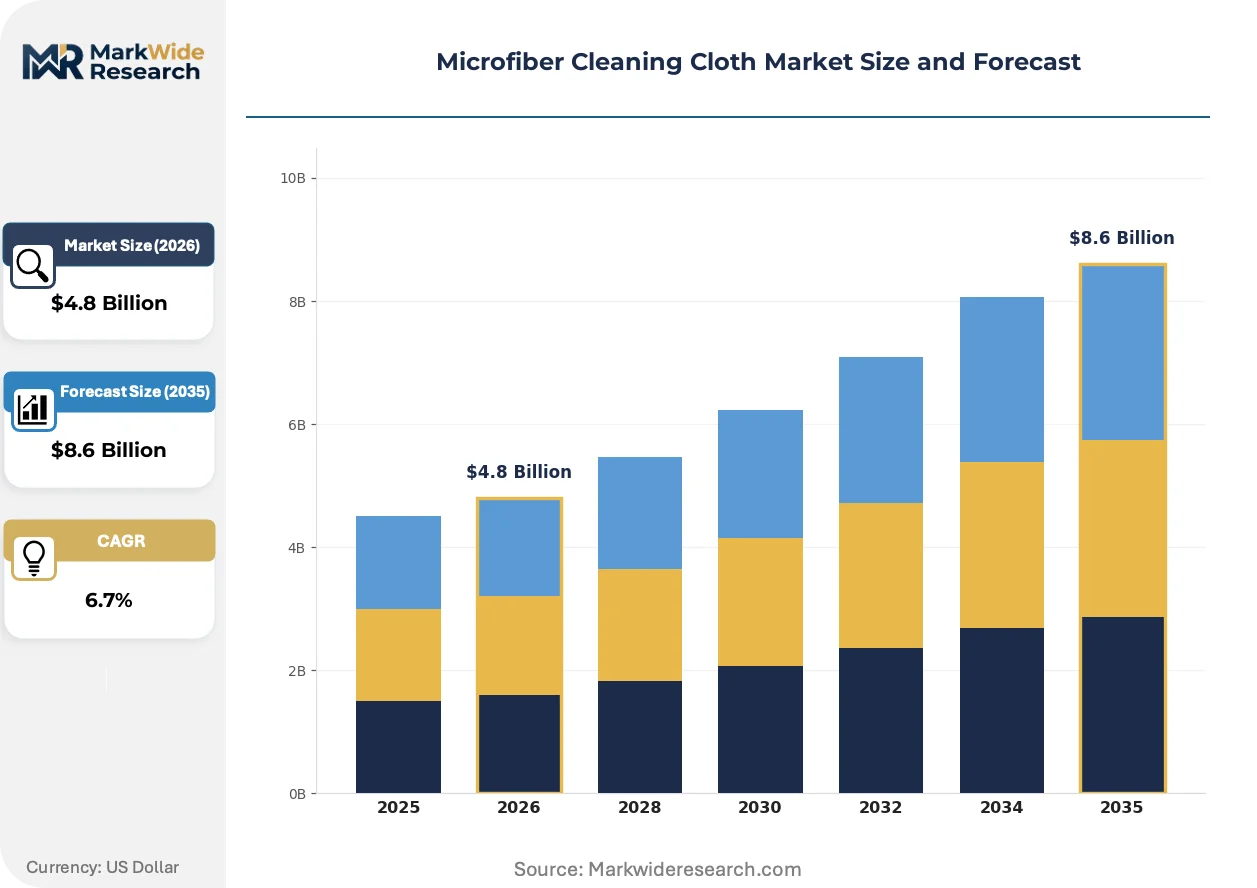
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose Cloths, Window Cloths, Bath Towels, All-Purpose Wipes Material Composition: Polyester, Polyamide, Blends, Eco-Friendly Fibers Application Area: Household Cleaning, Automotive Care, Industrial Use, Healthcare Facilities End User: Consumers, Professional Cleaners, Businesses, Educational Institutions |
| Companies Covered | Toray Industries, Scotch-Brite, Norwex USA, Freudenberg Home and Cleaning Solutions, E-Cloth, Zwipes, Atlas Graham Furgale, kingmaxclean, Vileda Professional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microfiber Cleaning Cloth Market Shifts & Advancements
Electrospun nanofiber deposition, regulatory traceability mandates, and performance-based procurement contracts are converging to reshape competitive requirements across the microfiber cleaning cloth value chain.
Split-fiber microfilament technology with denier below 0.3 is supplanting conventional 1.0 denier substrates in critical cleaning applications. German automotive OEMs and semiconductor fabs in Dresden are specifying ultra-fine fiber grades for particulate capture below 0.5 microns. This specification compression is forcing Asian converters to retool extrusion equipment or exit premium supply tiers entirely.
REACH authorization procedures for biocidal silver compounds are tightening antimicrobial claim substantiation requirements. ECHA's 2024 guidance on nanomaterial characterization now demands quantitative release-rate data across product lifecycles. European private-label brands are responding by consolidating supplier bases to entities with in-house toxicology testing capabilities.
Performance-based cleaning contracts are displacing unit-price procurement in Dutch and Belgian facility management sectors. Service providers in Rotterdam and Antwerp now specify microfiber durability metrics tied to guaranteed wash-cycle thresholds. This contractual evolution compresses supplier margins while locking in multi-year volume commitments for certified producers.
Microfiber Cleaning Cloth Market Segmentation
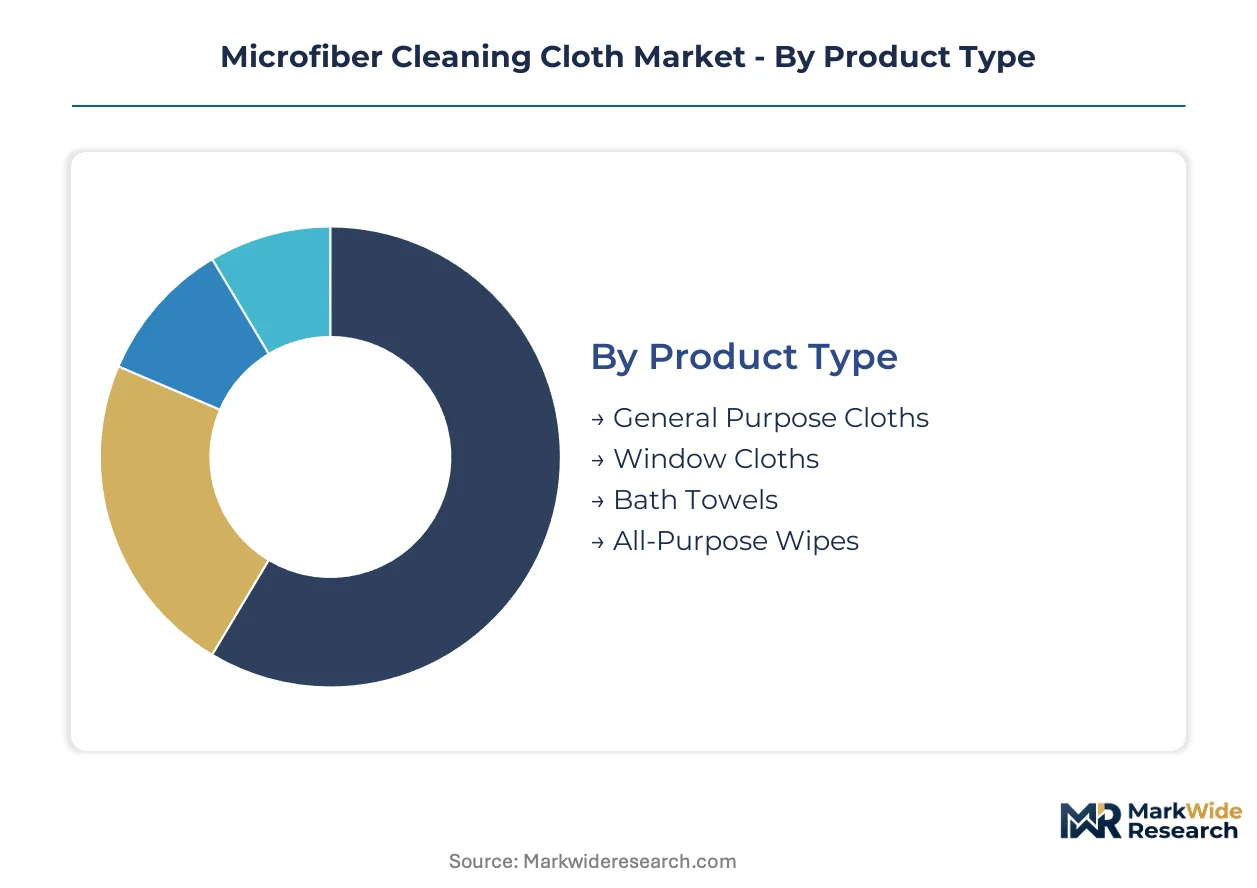
Microfiber cleaning cloth procurement channels diverge sharply between retail consumer pickup and institutional contract bidding, with each channel demanding distinct certification tiers and volume specifications. Understanding these segment-channel pairings determines supplier positioning and margin capture across the value chain.
Product Type:
General purpose cloths flow predominantly through mass retail and e-commerce channels, while specialized formats concentrate in professional supply houses and healthcare distributors.
- General Purpose Cloths:Woven or knitted polyester-polyamide substrates with 0.5-1.0 denier filaments engineered for universal surface cleaning. German facility management contracts in Frankfurt and Munich specify these for bundled service agreements, consolidating volume around ISO 9001-certified suppliers.
- Window Cloths:Ultra-fine split-fiber constructions below 0.3 denier optimized for streak-free glass cleaning without chemical additives. Automotive OEMs in Stuttgart and Wolfsburg mandate these specifications for pre-delivery vehicle preparation, driving premium tier demand.
- Bath Towels:Higher GSM constructions with enhanced capillary action for moisture retention, primarily penetrating consumer retail channels in North America and European home goods sectors.
- All-Purpose Wipes:Pre-moistened or dry disposable formats targeting convenience-oriented consumers and light commercial applications through grocery and club store distribution.
General purpose cloths dominate installed base. Window cloths are where expansion concentrates.
Material Composition:
Raw material selection determines regulatory compliance pathways and end-market eligibility, with petrochemical-derived fibers facing mounting disclosure requirements against emerging recycled alternatives.
- Polyester:Petroleum-derived PET filaments providing structural durability and abrasion resistance at lowest unit cost. REACH azo dye restrictions filter non-compliant Asian suppliers from European import channels.
- Polyamide:Nylon 6 or 6,6 substrates contributing electrostatic charge retention for particulate capture. Japanese and South Korean filament manufacturers concentrate premium denier production, creating supply bottlenecks for European weavers.
- Blends:Engineered polyester-polyamide ratios (typically 70:30 to 80:20) balancing absorbency, durability, and cost. These formulations anchor Toray Industries' substrate supply to downstream converters worldwide.
- Eco-Friendly Fibers:Post-consumer recycled PET or bio-based alternatives commanding premium positioning as commercial buyers face Scope 3 emissions reporting obligations under EU Ecodesign regulations.
Polyester-polyamide blends anchor volume production. Eco-friendly fibers are climbing the fastest.
Application Area:
End-use specifications compress fiber grades and antimicrobial requirements, with healthcare and industrial segments imposing performance thresholds that consumer applications do not require.
- Household Cleaning:Universal penetration segment with lowest performance barriers, distributed through retail and e-commerce channels across all geographies.
- Automotive Care:Ultra-fine denier requirements for paint-safe surface preparation, with German OEMs and semiconductor fabs in Dresden specifying sub-0.5 micron particulate capture grades.
- Industrial Use:Heavy-duty constructions for manufacturing facility maintenance, requiring industrial laundering compatibility above 60°C wash cycles.
- Healthcare Facilities:Silver-ion or copper-infused antimicrobial substrates for infection control in operating theaters and patient rooms. EPA Design for the Environment criteria and ECHA biocidal authorization procedures tighten claim substantiation requirements, consolidating supply around toxicology-capable producers.
Household cleaning holds volume leadership. Healthcare facilities are gaining share fastest.
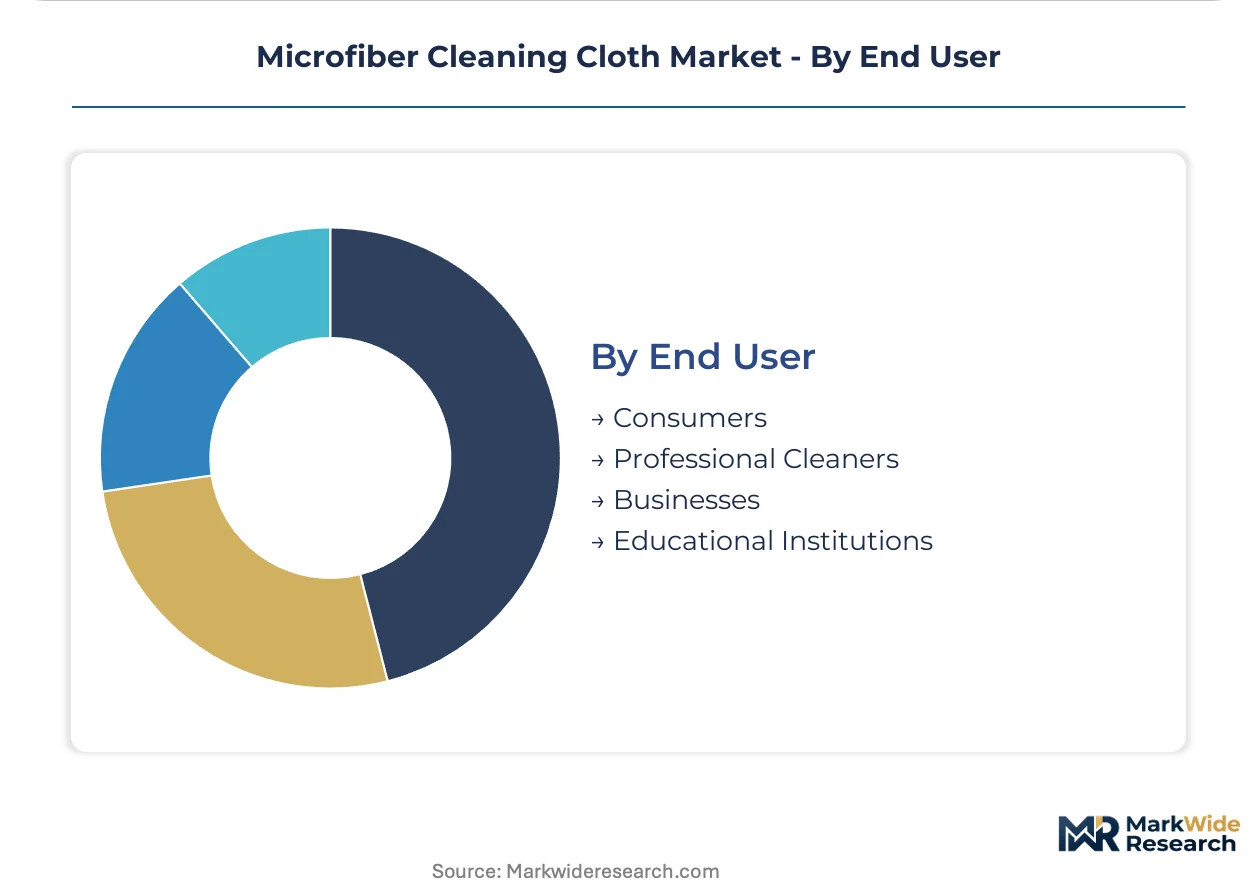
End User:
Buyer type determines contract structure, certification burden, and pricing methodology, with institutional procurement displacing unit-price models in favor of performance guarantees.
- Consumers:Price-sensitive retail purchasers with minimal certification requirements, served through mass merchants and digital marketplaces.
- Professional Cleaners:Service providers in Rotterdam and Antwerp now specify durability metrics tied to guaranteed wash-cycle thresholds, compressing margins while locking in multi-year volume commitments.
- Businesses:Corporate facility management departments bundling microfiber procurement into integrated service contracts, with ISO 9001 certification reorganizing supplier eligibility.
- Educational Institutions:Emerging segment under budget constraints, with India's tier-2 and tier-3 cities driving first-time adoption as hospital accreditation standards expand.
Consumer channels maintain volume dominance. Professional cleaners are where pricing power concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management procurement concentrates demand in Germany's commercial cleaning sector, while healthcare expansion drives adoption in India's tier-2 cities and Japanese filament manufacturers anchor premium substrate supply.
Germany
Frankfurt and Munich facility management contracts specify ISO 9001-certified microfiber standards, consolidating volume around qualified vendors. REACH compliance governs azo dye and heavy metal restrictions for textile imports. The Stuttgart automotive cluster mandates ultra-fine denier grades for pre-delivery vehicle preparation.
United States
EPA Design for the Environment criteria influence chemical-free cleaning claims across institutional and retail channels. Healthcare facilities in the Midwest and Southeast are replacing cotton mops with launderable microfiber systems. The report identifies professional cleaning service expansion in Chicago and Atlanta as a demand driver.
India
Hospital accreditation standards under the National Accreditation Board for Hospitals are driving first-time microfiber adoption in tier-2 and tier-3 cities. The country's central textile regulator enforces quality benchmarks for imported synthetic fibers. Maharashtra and Gujarat host emerging distribution hubs for antimicrobial healthcare products.
Japan
Toray Industries leverages filament manufacturing scale to supply premium polyester-polyamide substrates globally. METI standards govern synthetic fiber quality and environmental disclosure requirements. The Osaka-Kobe industrial corridor concentrates denier fiber production for export markets.
Netherlands
Rotterdam facility management providers specify microfiber durability metrics tied to guaranteed wash-cycle thresholds. The EU Ecodesign for Sustainable Products Regulation will extend digital product passport requirements to textile cleaning tools. Chemical recycling infrastructure investments in Belgium and the Netherlands are opening closed-loop supply channels for post-consumer PET microfiber production.
Microfiber Cleaning Cloth Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with captive filament production and specialized cleaning product manufacturers with brand recognition in regional retail channels. The structure concentrates substrate supply among Asian petrochemical players while European and North American competitors differentiate through formulation expertise and distribution reach. Two strategic archetypes dominate: integrated filament-to-cloth producers and brand-focused downstream converters. Competitive moves center on antimicrobial technology licensing and certification-driven supplier consolidation for institutional contracts.
Within the integrated chemical conglomerate tier, Toray Industries and Freudenberg Home and Cleaning Solutions exemplify upstream-downstream coordination strategies. Toray Industries occupies a position as a filament manufacturing anchor supplying premium substrates to downstream converters worldwide. Freudenberg represents European private-label production capabilities with integrated nonwoven expertise. Among brand-recognized specialists, Scotch-Brite sits within the North American retail channel establishment. These three companies illustrate how scale-driven substrate control and regional brand equity constitute alternative pathways to procurement eligibility.
| Leading Market Players |
|---|
| Toray Industries |
| Scotch-Brite |
| Norwex USA |
| Freudenberg Home and Cleaning Solutions |
| E-Cloth |
| Zwipes |
| Atlas Graham Furgale |
| kingmaxclean |
| Vileda Professional |
| Others |
Supply & Pricing Matrix
ISO 9001 certification gates supplier eligibility for institutional procurement contracts while simultaneously stratifying price tiers across the microfiber cleaning cloth value chain. German facility management contracts in Frankfurt and Munich specify certified standards, compressing margins for non-compliant converters while enabling premium capture for accredited producers.
Pricing Analysis
Fixed-price institutional contracts with polyester resin indexation dominate procurement between healthcare systems and qualified suppliers. Three-tier pricing structure across premium antimicrobial grades, standard ISO-certified tiers, and economy retail SKUs reflects certification burden and filament quality. Cost compression in economy tiers is intensifying because Asian converters face REACH compliance investments to maintain European export eligibility. Consumer retail channels exhibit highest price sensitivity, while German automotive OEMs accept substantial premiums for sub-0.3 denier specifications.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates landed costs for European weavers dependent on Japanese and South Korean filament shipments. Premium denier fiber production clusters in Japan, South Korea, and coastal China, while downstream conversion concentrates in Bangladesh, Vietnam, and Turkey for cost-competitive retail supply. Raw material dependencies center on purified terephthalic acid, caprolactam, and silver-ion antimicrobial additives. Single-source vulnerability in Japanese filament supply creates exposure for European converters. Distribution runs through healthcare distributors, facility management service providers, and mass retail channels with diverging certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microfiber cleaning cloth market tracks cyclical recovery patterns tied to healthcare capital expenditure cycles, with hospital accreditation waves in emerging economies driving replacement demand. Procurement consolidation around certified suppliers creates defensive moats for qualified incumbents.
For Market Incumbents: Shield market position by deepening captive filament supply through backward integration into polyester-polyamide substrate production, countering Japanese supply concentration. Accelerate toxicology testing partnerships to satisfy ECHA biocidal authorization timelines, locking out capital-constrained competitors from antimicrobial healthcare contracts.
For New Entrants and Emerging Players: Lead with blockchain-enabled fiber provenance systems to satisfy EU Ecodesign digital product passport mandates, targeting Rotterdam and Antwerp facility management providers seeking traceability guarantees. India's tier-2 and tier-3 hospital accreditation expansion offers the most penetrable geography for first-time antimicrobial microfiber adoption.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming textile divisions holding captive filament capacity but lacking healthcare channel access. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity scale. Monitor chemical recycling facility commissioning in the Netherlands and Belgium as the inflection signal for closed-loop feedstock cost competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Technology Licensing | Toray Industries' silver-ion substrate patents enable premium tier capture in German healthcare procurement. |
| ISO 9001 Certification Investment | Twelve-to-eighteen month accreditation timelines filter small-scale converters from Frankfurt facility management tenders. |
| Backward Integration into Filament Production | European weavers reduce Japanese supply dependency by acquiring extrusion capacity in Portugal or Turkey. |
| Blockchain Provenance System Deployment | Rotterdam service providers specify digital product passport readiness under EU Ecodesign traceability mandates. |
| Chemical Recycling Partnership | Belgian and Dutch post-consumer PET infrastructure opens closed-loop supply for eco-friendly fiber positioning. |
Research Methodology
Cross-validation between primary interviews with facility management procurement directors, healthcare infection control officers, and textile converter operations managers anchors the qualitative findings against secondary validation from REACH authorization databases, EU Ecodesign regulatory filings, and customs trade records. Bottom-up volume estimates from filament manufacturer capacity disclosures triangulate with top-down healthcare procurement spend analysis.
Sensitivity analysis across petrochemical feedstock price scenarios, certification timeline delays, and healthcare accreditation adoption curves stress-tests projection robustness. Segmentation modeling incorporates product type, material composition, application area, and end user archetype dimensions. CAGRs derive from weighted average of historical volume trends and forward-looking procurement contract visibility, with antimicrobial efficacy testing cost inflation and digital passport compliance burden as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU Ecodesign implementation and REACH authorization procedures; material policy shifts would require re-modeling. Supply disruption scenarios from Japanese filament manufacturing concentration and chemical recycling infrastructure delays represent specific risk factors that could revise volume projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Towel Market
Home Textiles
Home Textile Products Market
Home Textiles
GCC Home Textile Market
Home Textiles
Japan Home Textile Market
Home Textiles
Cotton Towel Market
Home Textiles
Vietnam Home Textile Market
Home Textiles
Baby Crib Sheet Market
Home Textiles
Mexico Home Textile Market
Home Textiles
Home Textiles Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Bath Towel Market
Home Textiles
India Home Textile Market
Home Textiles
Australia Home Textiles Market
Home Textiles
Blanket Market
Home Textiles
Latin America Home Textiles Market
Home Textiles
Europe Home Textile Market