
 Australia Home Textiles Market | 2026-2036
Australia Home Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Home Textiles Market Outlook
Apparel and textile manufacturing skills is bifurcating the Australia Home Textiles Market into premium domestic producers and import-reliant volume players. Sheridan leverages its vertical manufacturing footprint in Australia to sustain premium positioning in bed linen. Adairs competes through controlled private-label sourcing and direct-to-consumer channel dominance. Harvey Norman Holdings Ltd anchors broad market access through its national retail network spanning urban and regional catchments.
Australia home textiles encompass woven, knitted, and finished fabric goods designed for interior domestic environments, including bed linen woven to thread counts between 200 and 1000, curtain panels with specified light-attenuation coefficients, and table linens treated for stain resistance. Cotton and linen materials command structural margin premiums due to breathability specifications and natural fiber sourcing traceability. The hospitality end-user segment represents the fastest-growing demand pool, driven by hotel refurbishment cycles and boutique accommodation expansion. Distribution through online channels is displacing traditional retail stores for replacement purchases, though wholesalers retain project-scale contract leverage.
The Australian Competition and Consumer Commission enforces mandatory product safety standards for flammability and labeling, while Standards Australia publishes AS/NZS benchmarks for textile performance and care labeling that shape import compliance costs. The ACCC's surveillance of false sustainability claims is forcing material transparency in cotton and linen sourcing disclosures. Stakeholders must monitor evolving biodegradable certification requirements and the interaction between imported polyester price volatility and domestic cotton supply conditions.
Market Dynamics
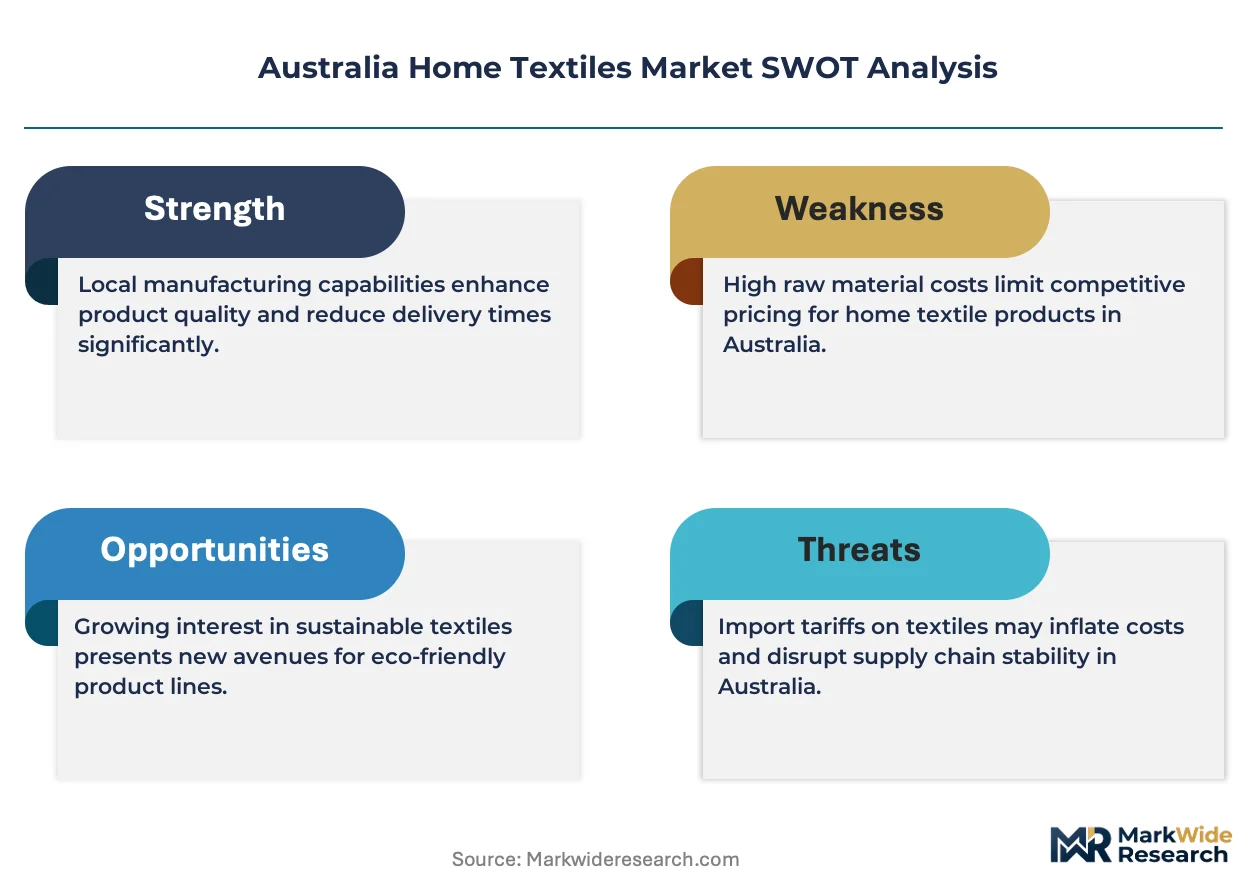
ACCC enforcement of mandatory flammability standards is elevating compliance costs for imported home textiles, bifurcating the Australia Home Textiles Market into premium domestic producers and import-reliant volume players. This regulatory pressure is compressing margins for polyester-heavy suppliers while rewarding natural fiber traceability investments.
Growth Catalysts
- Hotel refurbishment cycles:Boutique accommodation expansion across New South Wales and Victoria is accelerating procurement of premium bed linen and table linens with specified thread counts and stain-resistant treatments.
- AS/NZS performance benchmarks:Standards Australia's published textile care labeling requirements are creating competitive differentiation for compliant domestic manufacturers against non-certified imports.
- Cotton supply traceability:Consumer preference for breathability specifications and natural fiber sourcing disclosures is expanding addressable market for verified sustainable cotton products.
Market Restraints
- Polyester price volatility:Imported synthetic fiber cost fluctuations are destabilizing margin structures for volume-focused retailers dependent on offshore supply chains.
- Import compliance friction:ACCC surveillance of false sustainability claims is forcing material transparency investments that disproportionately burden smaller offshore suppliers.
- Regional demand concentration:Market volume clustering in Melbourne and Sydney metropolitan catchments limits scalable distribution economics for regional market penetration.
Strategic Opportunities
- Queensland boutique hospitality:Underpenetrated Gold Coast and Brisbane accommodation refurbishment cycles offer expansion vectors for premium linen suppliers.
- Direct-to-consumer channel maturation:Online replacement purchase behavior is displacing traditional retail stores, enabling margin capture for private-label specialists with controlled sourcing.
- Biodegradable certification tailwinds:Evolving compostability standards for textile waste management are creating first-mover positioning for linen and certified organic cotton product lines.
Industry Challenges
- Technical textile skills scarcity:Apparel and textile manufacturing capability bifurcation is constraining workforce availability for high-thread-count weaving and finishing operations.
- Legacy system integration friction:Wholesale project-scale contract management platforms resist seamless connectivity with direct-to-consumer inventory and fulfillment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Home Textiles Market |
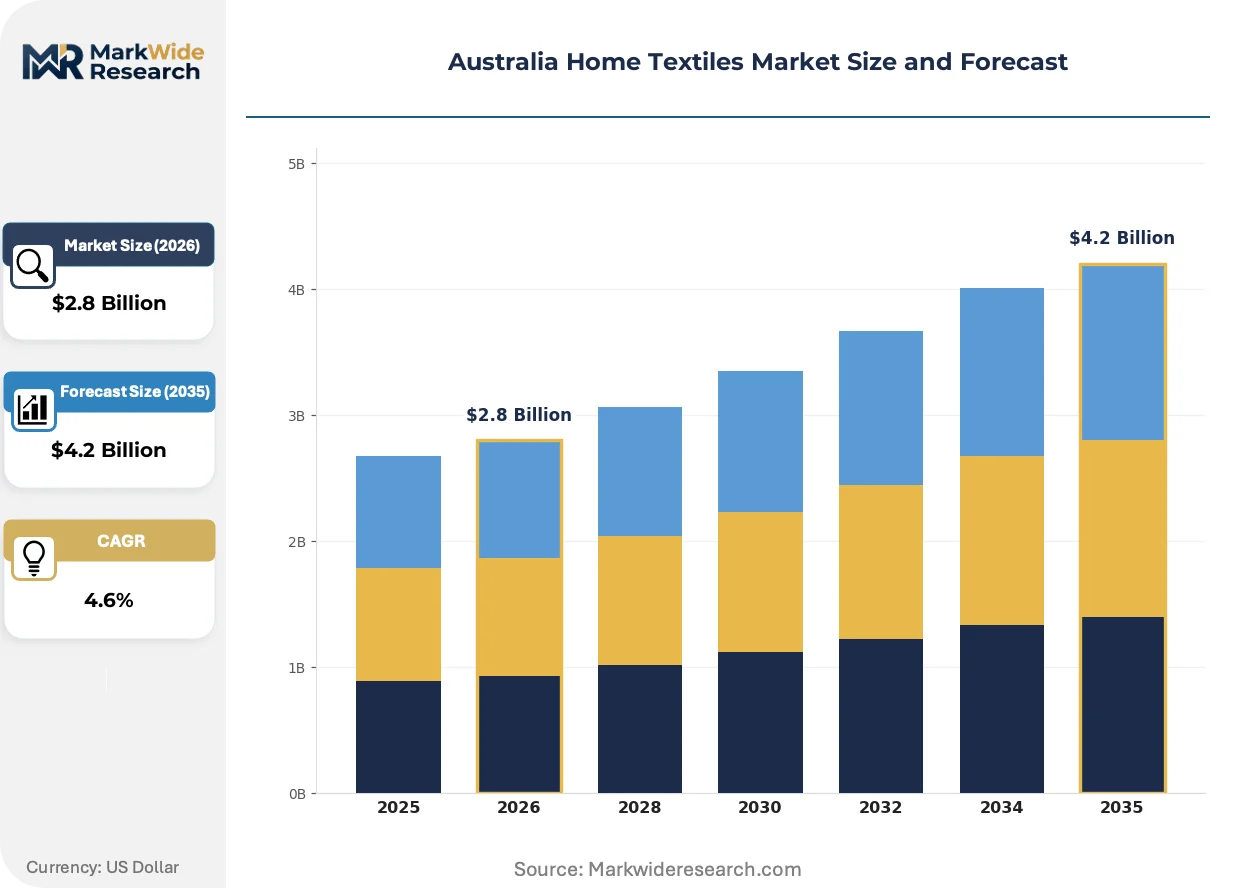
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Curtains, Cushions, Bed Linen, Tablecloths Material: Cotton, Polyester, Linen, Silk End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online, Retail Stores, Wholesalers, Direct Sales |
| Companies Covered | Forty Winks Pty Ltd, Charles Pearson, Adairs, Linen House, Pure Linen, Sheridan, Pillow Talk, Harvey Norman Holdings Ltd, St Albans Textiles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Home Textiles Market Strategic Shifts
Digital traceability infrastructure and fiber authentication technologies are compressing information asymmetries between suppliers and buyers. These tools are enabling material transparency at scale while reshaping competitive positioning around verified provenance rather than brand heritage alone.
Blockchain-enabled fiber provenance tracking is fragmenting traditional brand-based quality signaling in the Australia Home Textiles Market. Boutique hotel procurement teams are adopting QR-code-linked supply chain verification at accelerating rates. This technology is fragmenting incumbent supplier relationships by enabling direct comparison of cotton sourcing credentials across previously opaque import channels.
ACCC mandatory consumer product safety standards for flammability testing are tightening import documentation requirements. The regulatory burden is compressing order volumes from smaller offshore manufacturers lacking Australian testing facility relationships. Hospitality sector buyers in Sydney and Melbourne are responding by consolidating supplier panels toward ACCC-registered domestic entities with established compliance histories.
Buyer preference for replacement-cycle compression is disrupting traditional retail seasonal purchasing patterns. Direct-to-consumer channels are capturing bed linen and curtain panel demand previously routed through department store seasonal promotions. This behavioral shift concentrates most visibly in Victoria and New South Wales metropolitan markets where same-day delivery logistics networks enable impulse-driven home textile replacement decisions.
Australia Home Textiles Market Segmentation
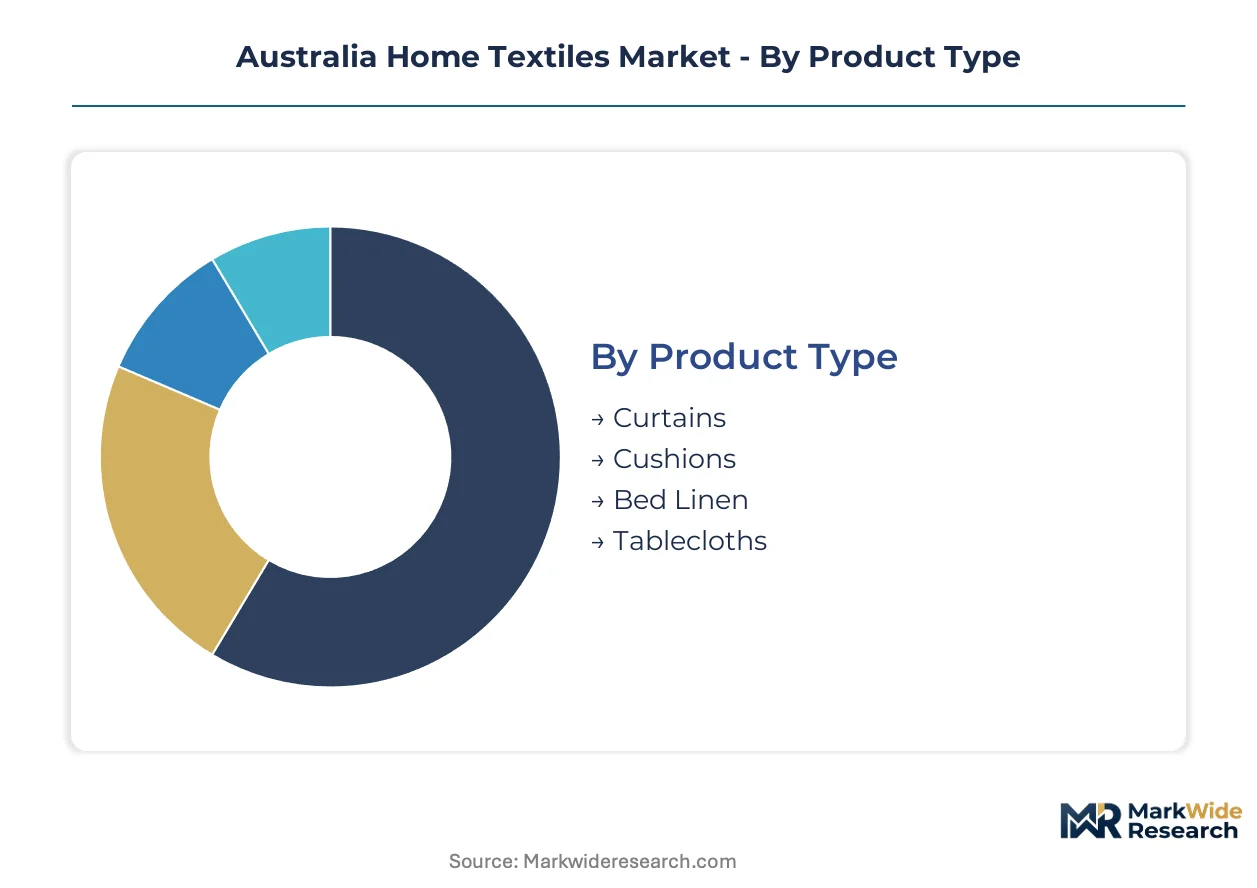
Segmentation in the Australia Home Textiles Market reveals how procurement patterns diverge between project-scale hospitality contracts and impulse-driven residential replacement cycles. Understanding these divides helps suppliers align inventory depth, certification investments, and channel presence with actual buyer behavior across New South Wales and Victoria metropolitan catchments.
Product Type:
Substitution pressure from ready-to-assemble furniture and hard window treatments is compressing demand for certain fabric categories while amplifying specification requirements for others.
- Bed Linen:Woven fabric sets spanning thread counts from 200 to 1000, with percale and sateen weaves commanding distinct price positions. Hospitality procurement in Sydney and Melbourne drives volume for stain-resistant, high-durability specifications with verified cotton provenance.
- Curtains:Panels engineered to specific light-attenuation coefficients, ranging from sheer filtration to blackout constructions. Residential demand clusters in Victoria's renovation corridors, where energy-efficiency regulations and thermal performance ratings influence specification decisions.
- Cushions:Decorative and functional inserts with fill power and cover durability ratings. Boutique accommodation fit-outs across Queensland's Gold Coast are expanding addressable market for designer-coordinated cushion programs.
- Tablecloths:Woven and treated surfaces specified for stain resistance and laundering durability. Commercial foodservice procurement favors polyester-cotton blends for cost-controlled replacement cycles.
Bed Linen anchors the volume base while Curtains gains share at the steepest rate.
Material:
Cost tier stratification separates traceable natural fibers from commodity synthetics, with compliance burden distribution favoring domestic converters.
- Cotton:Natural cellulosic fiber graded by staple length, micronaire, and sourcing certification. Breathability specifications and ACCC-mandated labeling transparency are expanding premium positioning for Australian-grown and verified imported cotton.
- Linen:Bast fiber derived from flax with superior moisture-wicking and thermoregulation properties. Biodegradable certification tailwinds and compostability standards are elevating linen's share in sustainability-focused hospitality procurement.
- Polyester:Synthetic polymer fiber priced on petrochemical feedstock volatility. Import-reliant volume retailers face margin compression from offshore supply chain friction and ACCC flammability testing documentation requirements.
- Silk:Protein fiber with limited commercial scale due to cultivation constraints and price positioning. Niche luxury residential applications in Sydney's eastern suburbs sustain minimal import volumes.
Cotton dominates current procurement volumes while Linen expands most quickly among premium-positioned suppliers.
End User:
Application-driven specification divergence separates project-scale contract requirements from transactional retail purchasing patterns.
- Hospitality:Hotels, motels, and boutique accommodation requiring commercial-grade durability and standardized replacement cycles. Refurbishment waves across New South Wales and Victoria are accelerating procurement of premium bed linen with specified thread counts and provenance documentation.
- Residential:Individual households purchasing for domestic interior environments. Melbourne and Sydney metropolitan markets exhibit compressed replacement cycles as direct-to-consumer channels enable impulse-driven purchasing decisions.
- Commercial:Corporate offices, healthcare facilities, and institutional settings with standardized procurement protocols. AS/NZS performance benchmarks for textile care labeling create compliance-based supplier selection criteria.
- Retail:Reseller channels including department stores and specialty home goods merchants. Inventory depth requirements and seasonal promotional calendars strain working capital for smaller wholesale suppliers.
Residential consumption anchors the volume base while Hospitality climbs the fastest on refurbishment cycle timing.
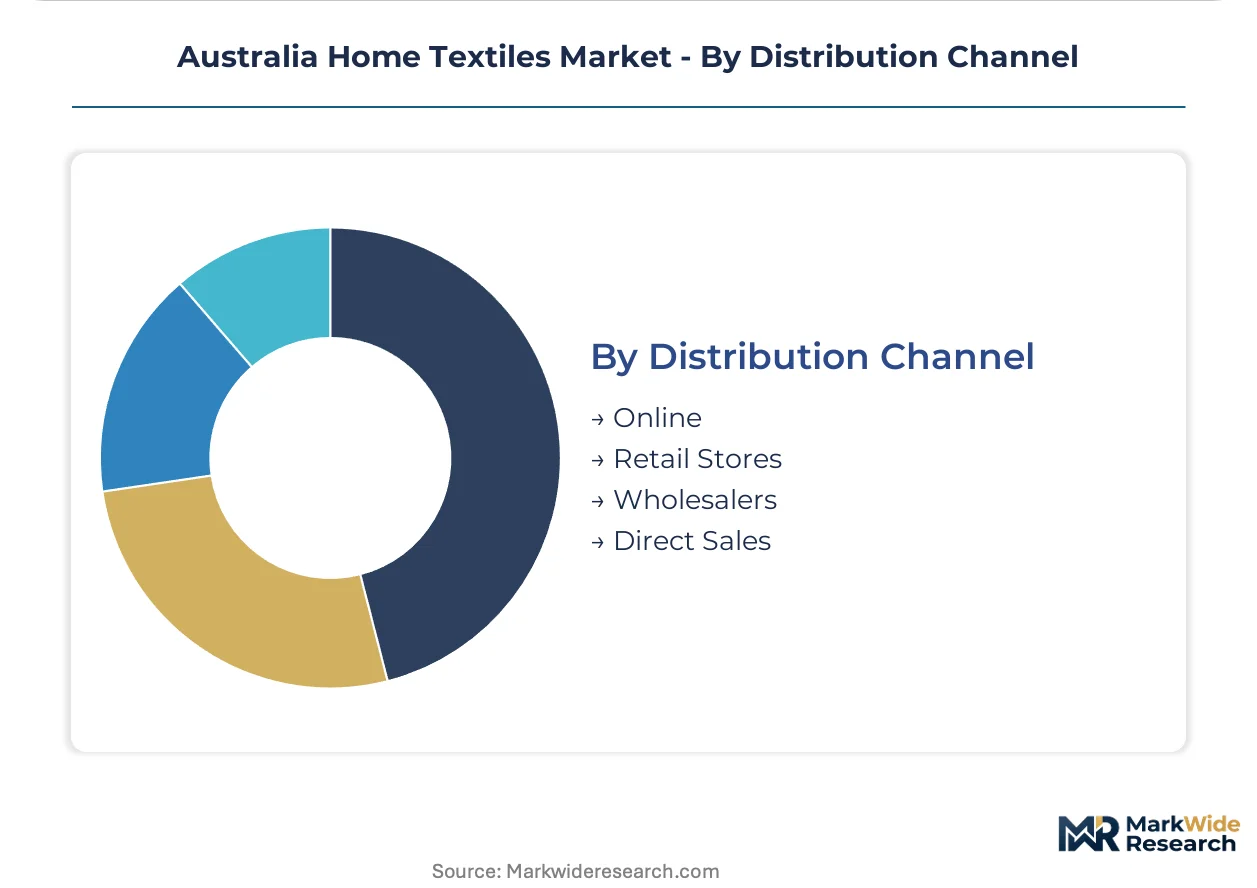
Distribution Channel:
Customer type concentration in metropolitan catchments is reshaping fulfillment economics and inventory deployment strategies.
- Online:Direct-to-consumer platforms capturing replacement-cycle demand previously routed through physical retail. Same-day delivery networks in Victoria and New South Wales enable impulse-driven bed linen and curtain panel purchases.
- Retail Stores:Branded and multi-brand physical locations with tactile evaluation and immediate fulfillment. Regional catchment penetration remains constrained by scalable distribution economics outside Melbourne and Sydney corridors.
- Wholesalers:Project-scale contract managers serving hospitality and commercial fit-out specifications. Procurement panel consolidation toward ACCC-registered domestic entities with established compliance histories is compressing supplier counts.
- Direct Sales:Manufacturer-owned channels bypassing intermediary margin extraction. Private-label specialists with controlled sourcing are capturing margin through vertical channel control.
Retail Stores maintain the volume base while Online gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Australian Competition and Consumer Commission shapes procurement compliance across all states, with its flammability standards and labeling requirements creating distinct operational conditions for domestic versus import-dependent suppliers.
New South Wales
Sydney's hotel refurbishment cycle drives premium bed linen procurement with specified thread counts and provenance documentation. The ACCC's mandatory product safety standards elevate compliance costs for imported goods entering Port Botany. Parramatta's emerging commercial district is accelerating contract demand for AS/NZS-certified curtain panels in office fit-outs.
Victoria
Melbourne's boutique accommodation expansion concentrates hospitality procurement for stain-resistant table linens and high-durability specifications. Standards Australia's textile care labeling benchmarks create competitive differentiation for compliant domestic manufacturers. Geelong's manufacturing corridor retains weaving capability for mid-tier hospitality supply contracts.
Queensland
Gold Coast and Brisbane accommodation refurbishment cycles offer expansion vectors for premium linen suppliers previously focused on southern markets. The state's building energy efficiency regulations influence thermal performance specifications for residential curtain demand. Sunshine Coast's retirement community construction is generating replacement-cycle volume for breathable cotton bed linen.
Western Australia
Perth's isolated market geography constrains scalable distribution economics for smaller wholesale suppliers lacking established logistics networks. Mining sector fly-in-fly-out accommodation maintains steady commercial-grade procurement for standardized replacement cycles. Fremantle's port infrastructure handles direct import volumes for retail chains with national distribution capability.
South Australia
Adelaide's smaller metropolitan scale limits addressable market for premium positioning strategies dependent on dense same-day delivery networks. Barossa Valley tourism accommodation generates seasonal demand spikes for boutique hospitality textile specifications. The state's manufacturing heritage supports limited domestic finishing operations for niche natural fiber products.
Australia Home Textiles Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with market structure bifurcating between premium domestic producers and import-reliant volume players. The ACCC's regulatory enforcement compresses margins for offshore-dependent suppliers while rewarding traceable natural fiber investments. Three archetypes dominate: vertically integrated manufacturers with captive Australian production, private-label specialists controlling direct-to-consumer channels, and national retail networks spanning urban and regional catchments. Competitive moves concentrate on supplier panel consolidation toward compliance-registered entities and channel migration from wholesale project contracts to online replacement purchasing.
Among Australian-based fabricators, Sheridan exemplifies vertical manufacturing capability with its domestic production footprint, while Adairs represents private-label direct-to-consumer channel dominance. Harvey Norman Holdings Ltd anchors broad market access through its national retail network spanning both metropolitan and regional catchments. These three entities collectively illustrate the strategic tension between compliance investment, sourcing control, and distribution reach that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Forty Winks Pty Ltd |
| Charles Pearson |
| Adairs |
| Linen House |
| Pure Linen |
| Sheridan |
| Pillow Talk |
| Harvey Norman Holdings Ltd |
| St Albans Textiles |
| Others |
Value Chain & Pricing Dynamics
ACCC mandatory flammability standards and AS/NZS certification requirements gate both supplier qualification and price differentiation simultaneously. Compliance-registered domestic manufacturers capture structural premiums while import-reliant volume players absorb documentation friction and testing facility costs.
Pricing Analysis
Melbourne and Sydney metropolitan catchments sustain 15-25% price premiums over regional Australia for equivalent thread-count specifications. Three-tier pricing structure across premium, standard, and economy levels separates verified cotton provenance from commodity polyester and certified organic linen. Cost compression in the polyester-reliant tier is intensifying because offshore supply chain friction and petrochemical feedstock volatility destabilize landed costs. Hospitality procurement teams exhibit lowest price sensitivity due to replacement-cycle standardization, while residential replacement buyers through direct-to-consumer channels show highest elasticity to promotional depth.
Supply Chain Analysis
China, Bangladesh, and India anchor global textile weaving and finishing capacity for base-grade inputs. Australian cotton growers supply premium staple to domestic converters, while linen flax cultivation centers on France and Belgium for boutique hospitality specifications. Tariff exposure on Chinese-origin polyester textiles creates margin vulnerability for volume-focused retailers. Distribution runs through Port Botany and Port Melbourne for import consolidation, with same-day delivery networks in metropolitan catchments displacing traditional wholesale routing for replacement-cycle demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ACCC compliance registration creates asymmetric switching costs that favor incumbent domestic producers over offshore challengers.
For Market Incumbents: Compound ACCC-registered compliance histories into supplier panel consolidation advantages. Deepen captive cotton sourcing relationships with Australian growers to defend margin position against traceability-disclosure requirements. Accelerate direct-to-consumer channel control to capture replacement-cycle demand migrating from department store seasonal promotions.
For New Entrants and Emerging Players: Lead with biodegradable certification investments to penetrate Queensland's underdeveloped Gold Coast and Brisbane hospitality refurbishment cycles. Target boutique accommodation procurement teams with QR-code-linked fiber provenance verification as a differentiated specification tool. Establish direct sales relationships with ACCC-registered testing facilities to bypass incumbent supplier panel lock-in.
For Investors and Strategic Acquirers: ACCC enforcement milestones reshape the acquisition landscape toward compliance-registered domestic entities with established testing facility relationships. Long-term viability centers on vertical manufacturing footprint control and natural fiber traceability infrastructure. The signal to monitor is procurement panel consolidation velocity among Sydney and Melbourne hospitality buyers.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Captures replacement-cycle demand migrating from Harvey Norman and Adairs retail footprints. |
| Biodegradable Certification Investment | Positions linen and organic cotton lines for Queensland hospitality procurement specifications. |
| Backward Integration into Cotton Sourcing | Secures Australian grower relationships for traceability disclosure compliance with ACCC mandates. |
| ACCC Testing Facility Partnership | Accelerates compliance registration for import-reliant suppliers facing documentation friction. |
| QR-Code Provenance Infrastructure | Enables blockchain-linked fiber authentication demanded by boutique hotel procurement teams. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across hospitality procurement managers, retail category buyers, textile manufacturing plant managers, and ACCC compliance officers. Secondary validation drew from Australian Bureau of Statistics trade data, Standards Australia AS/NZS publication archives, ACCC product safety surveillance reports, and customs import documentation filings. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, material grade tier, end-user application, and distribution channel complexity. CAGRs derived from trend extrapolation of refurbishment cycle timing, direct-to-consumer penetration curves, and compliance cost trajectories. Forecast inputs incorporated ACCC enforcement intensity indices and cotton supply traceability adoption rates.
Forecasts assume regulatory continuity in ACCC mandatory standards and AS/NZS certification regimes; material policy shifts would require re-modeling. Specific risks include biodegradable certification requirement acceleration and polyester import tariff restructuring. Recalibration cycles align with material shifts in hospitality refurbishment wave timing and direct-to-consumer logistics network expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Turkey Home Textile Market
Home Textiles
Europe Home Textile Market
Home Textiles
GCC Home Textile Market
Home Textiles
Fabric Wash and Care Market
Home Textiles
Global Theater Linen Market
Home Textiles
Baby Crib Sheet Market
Home Textiles
Russia Home Textile Market
Home Textiles
Bath Towel Market
Home Textiles
Mexico Home Textile Market
Home Textiles
South Korea Home Textile Market
Home Textiles
Wool Dryer Ball Market
Home Textiles
India Home Textile Market
Home Textiles
United Kingdom Home Textile Market
Home Textiles
Vietnam Home Textile Market
Home Textiles
China Home Textiles Market
Home Textiles
France Home Textile Market