
 Baby Crib Sheet Market | 2026-2036
Baby Crib Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Crib Sheet Market Analysis
Aftermarket service revenue from subscription-based bedding replacement programs is tilting toward direct-to-consumer brands. Carter's Inc. leverages its omnichannel retail footprint to sustain volume leadership in mass-market distribution. Naturepedic anchors the premium organic segment through GOTS-certified manufacturing and physician endorsements. aden + anais differentiates via muslin fabric expertise and gift-registry penetration in hospital channels.
A baby crib sheet is a fitted textile covering designed to secure tightly over a crib mattress, typically constructed with elasticized edges and thread counts ranging from 200 to 400 for breathability and softness against infant skin. Its primary commercial purpose is to provide a hygienic, comfortable sleeping surface that meets safety standards for flame resistance and fit tightness to prevent suffocation hazards. Cotton commands the largest material share due to proven breathability and parent familiarity, while bamboo fabrics represent the fastest-growing category as temperature-regulating properties attract climate-conscious buyers. Standard sizing dominates volume production, though mini and portable segments expand alongside travel crib and co-sleeper accessory sales.
The Consumer Product Safety Commission enforces mandatory flammability standards under 16 CFR Part 1615, compelling manufacturers to maintain testing documentation for every production lot. Oeko-Tex Standard 100 and GOTS certification increasingly function as market access filters rather than premium differentiators, particularly in European retail channels governed by REACH chemical restrictions. Stakeholders must monitor evolving state-level chemical disclosure laws in California and New York, as these jurisdictions typically prefigure broader federal requirements.
Market Dynamics
Certification creep from voluntary premium markers to mandatory retail access filters is compressing margin structures for non-compliant manufacturers across European and North American distribution channels.
Growth Catalysts
- Oeko-Tex Standard 100 penetration:Retail buyers in Germany and South Korea now require this certification as a baseline procurement condition, elevating compliant suppliers above commodity competitors.
- Millennial parent cohort expansion:This demographic segment demonstrates disproportionate willingness to pay for organic cotton and GOTS-verified supply chains in direct-to-consumer channels.
- Temperature-regulating fabric innovation:Bamboo-derived textiles are capturing climate-conscious buyers seeking alternatives to conventional cotton in warmer regions.
Market Restraints
- Raw cotton price volatility:Weather-driven supply fluctuations in major producing regions create input cost instability for manufacturers lacking forward contracting capabilities.
- Testing documentation burden:16 CFR Part 1615 lot-level flammability compliance imposes fixed administrative costs that disproportionately burden smaller production runs.
- Synthetic microfiber substitution:Lower-cost polyester blends from concentrated Asian manufacturing bases threaten cotton's volume position in mass-market retail.
Strategic Opportunities
- Subscription replacement programs:Direct-to-consumer brands can capture recurring revenue through automated sizing upgrades as infants grow.
- Hospital gift-registry channel expansion:Partnerships with maternity wards and birthing centers create captive audience access at decision-point moments.
- REACH chemical restriction alignment:Early compliance with evolving European substance limitations positions suppliers for preferential retail placement.
Industry Challenges
- GOTS certification timeline compression:The 12-18 month farm-to-finished-goods verification process delays product launches for new organic entrants.
- Elasticized edge durability testing:Repeated wash-cycle performance validation requires capital-intensive laboratory infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Crib Sheet Market |
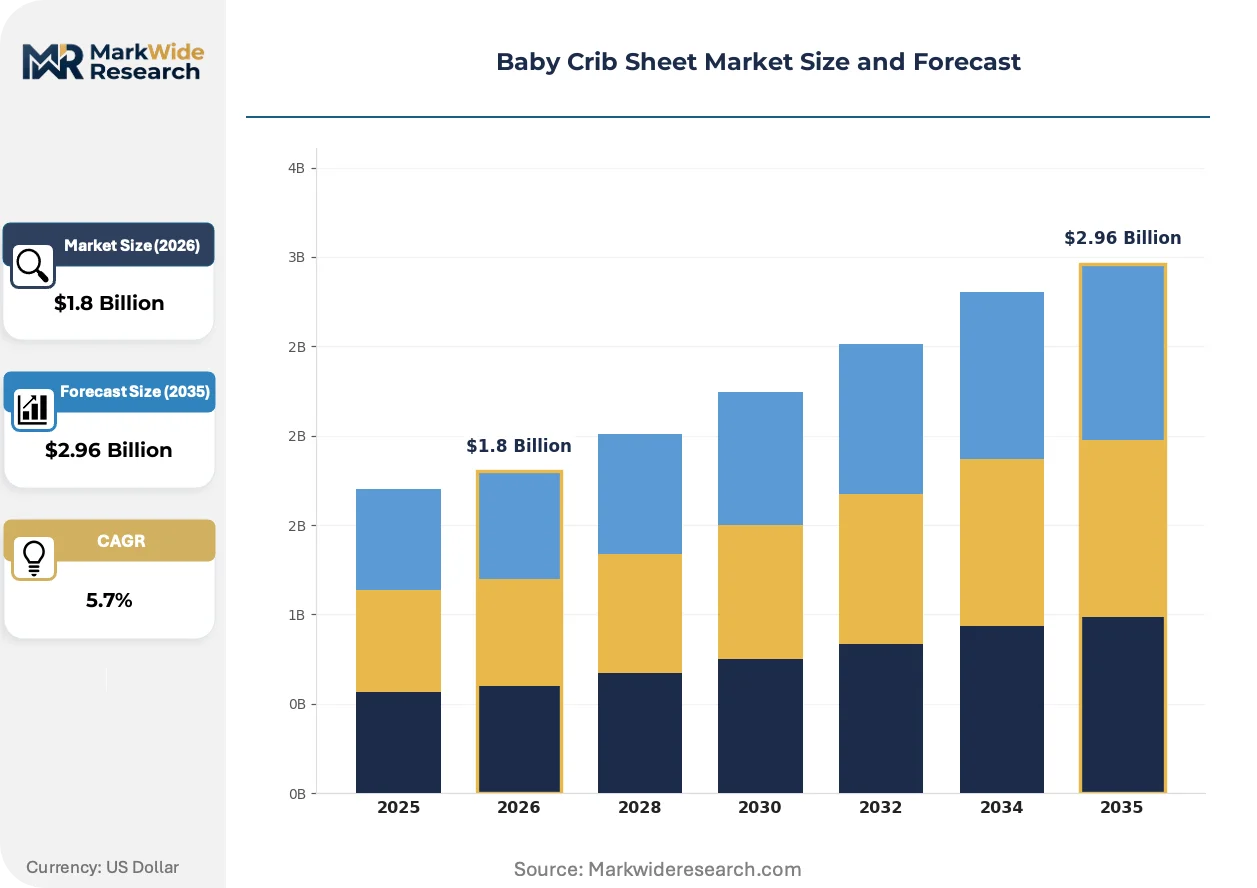
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Cotton, Microfiber, Bamboo, Muslin Size: Standard, Mini, Portable, Customized Design: Solid, Patterned, Printed, Embroidered End User: Parents, Retailers, Wholesalers, Hospitals |
| Companies Covered | Carter's Inc., Pottery Barn Kids, Naturepedic, Brooklinen, Burt's Bees Baby, Avocado, aden + anais, Parachute, Keababies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Crib Sheet Market Emerging Trajectories
Digital traceability infrastructure is virtualizing supply chain transparency from raw fiber to finished goods, enabling verification-driven purchasing decisions that reshape competitive positioning across premium and mass-market tiers.
Blockchain-enabled fiber provenance tracking is virtualizing the authentication process for organic cotton claims. Millennial parents in the United States and Germany scan QR codes on packaging to access immutable farm-level documentation. This technology is virtualizing trust mechanisms that previously required third-party physical audits, compressing verification costs while expanding consumer confidence.
REACH chemical restrictions in the European Union are forcing reformulation of dyes and finishing treatments used in crib sheet production. Manufacturers serving German and French retail channels must eliminate specific flame retardants and formaldehyde-based resins previously common in mass-market goods. Suppliers with early substitution capabilities are securing preferential shelf placement in specialty baby boutiques.
Hospital-based gift registry systems are displacing traditional baby shower purchasing patterns. Expectant parents in Japan and South Korea pre-select crib sheet specifications during prenatal consultations, with fulfillment triggered by birth events. This channel concentrates demand among registry-integrated brands while fragmenting traditional retail foot traffic.
Baby Crib Sheet Market Segmentation
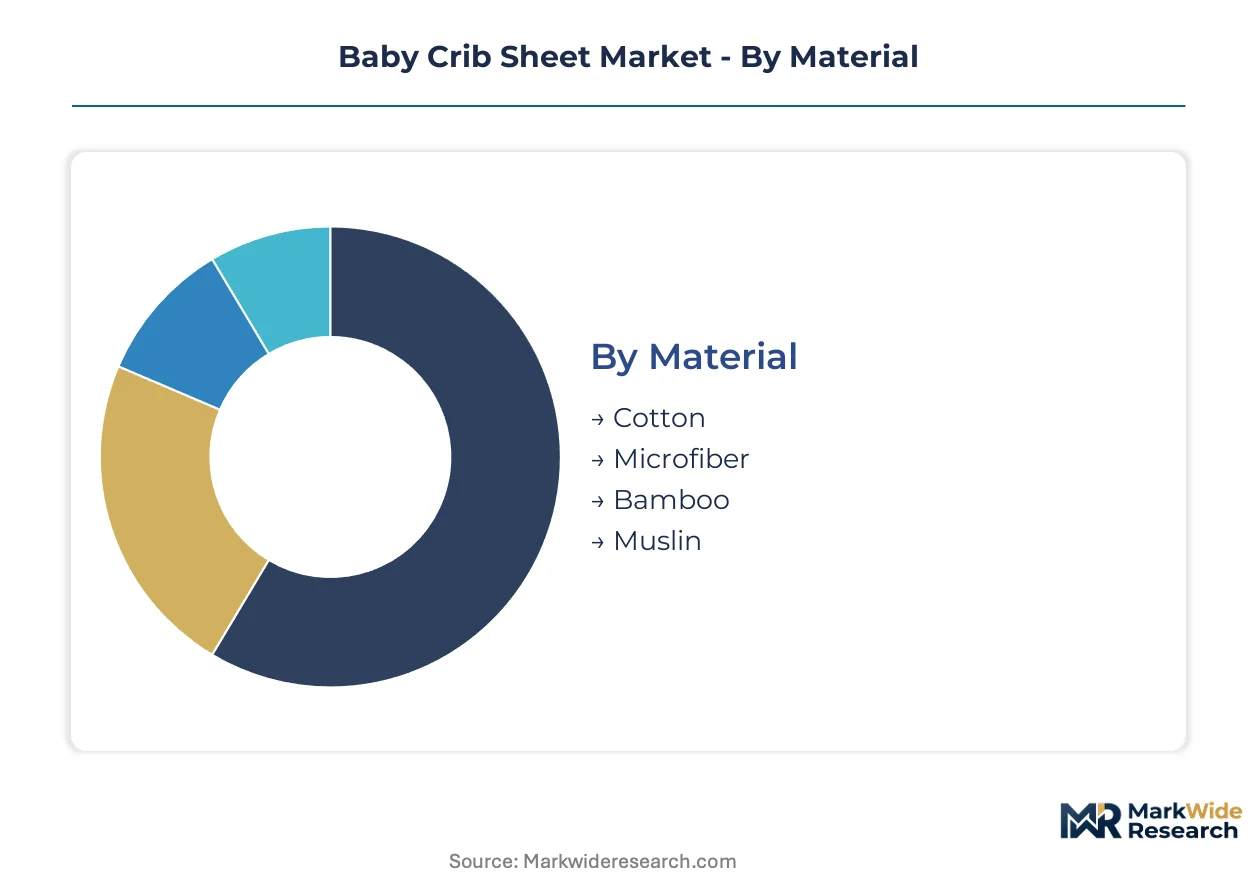
Crib sheet purchasing cycles vary dramatically across material types and end-user channels, with replacement frequency spanning weeks for institutional buyers to years for individual consumers. Understanding these velocity differentials helps manufacturers align inventory models and certification investments with actual turnover economics.
Material:
Cycle times compress from natural fibers to synthetics, as durability and wash tolerance reshape replacement calendars across household and commercial settings.
- Cotton:Breathable cellulosic fibers with 200-400 thread counts dominate parent preference in the United States and Germany due to thermal regulation and dermatological familiarity. Demand concentrates in direct-to-consumer channels where Oeko-Tex Standard 100 certification functions as a baseline procurement filter rather than premium markup.
- Bamboo:Cellulose-derived viscose fabrics with inherent moisture-wicking properties are capturing climate-conscious buyers in warmer regions. Temperature-regulating performance drives fastest expansion in South Korean and Japanese specialty boutiques where parents prioritize sleep quality in humid conditions.
- Microfiber:Polyester-polyamide blends deliver stain resistance and rapid drying for high-turnover institutional environments.
- Muslin:Lightweight open-weave cotton gauze construction enables superior airflow for newborn thermoregulation.
Cotton anchors the volume base while bamboo gains share at the steepest rate.
Size:
Manufacturing cost tiers scale inversely with production volume, as tooling amortization and fabric yield economics favor standardized dimensions over bespoke configurations.
- Standard:Dimensions of 28 by 52 inches fit regulated full-size crib mattresses with elasticized perimeter construction. Mass-market retail in the United States and Germany concentrates demand here, though mini crib proliferation in urban apartments fragments volume concentration.
- Mini:Reduced 24 by 38 inch specifications serve space-constrained nurseries and convertible furniture systems. Japanese and South Korean demand for compact urban housing solutions drives fastest category expansion alongside co-sleeper accessory sales.
- Portable:Travel-specific dimensions accommodate foldable play yards and inflatable mattresses.
- Customized:Non-standard specifications serve specialty mattress manufacturers and interior design commissions.
Standard sizing commands production scale advantages while mini formats climb fastest among metropolitan demographics.
Design:
Margin structures diverge sharply between commodity solids and value-added surface treatments, with decoration complexity determining price realization independent of base fabric costs.
- Solid:Undyed or uniformly pigmented surfaces minimize chemical finishing complexity and accelerate REACH compliance in European channels. German retail buyers prioritize this category for inventory velocity and reduced regulatory documentation burdens.
- Patterned:Woven or knitted-in geometric and organic motifs command gift-registry premiums in hospital channels. Japanese maternity ward partnerships concentrate demand here, as expectant parents pre-select visually distinctive options during prenatal consultations.
- Printed:Rotary or digital surface application enables seasonal theme rotation and licensed character partnerships.
- Embroidered:Needlework embellishments target heirloom positioning and personalized gifting occasions.
Solids dominate institutional procurement while patterned designs expand most quickly through registry-integrated channels.
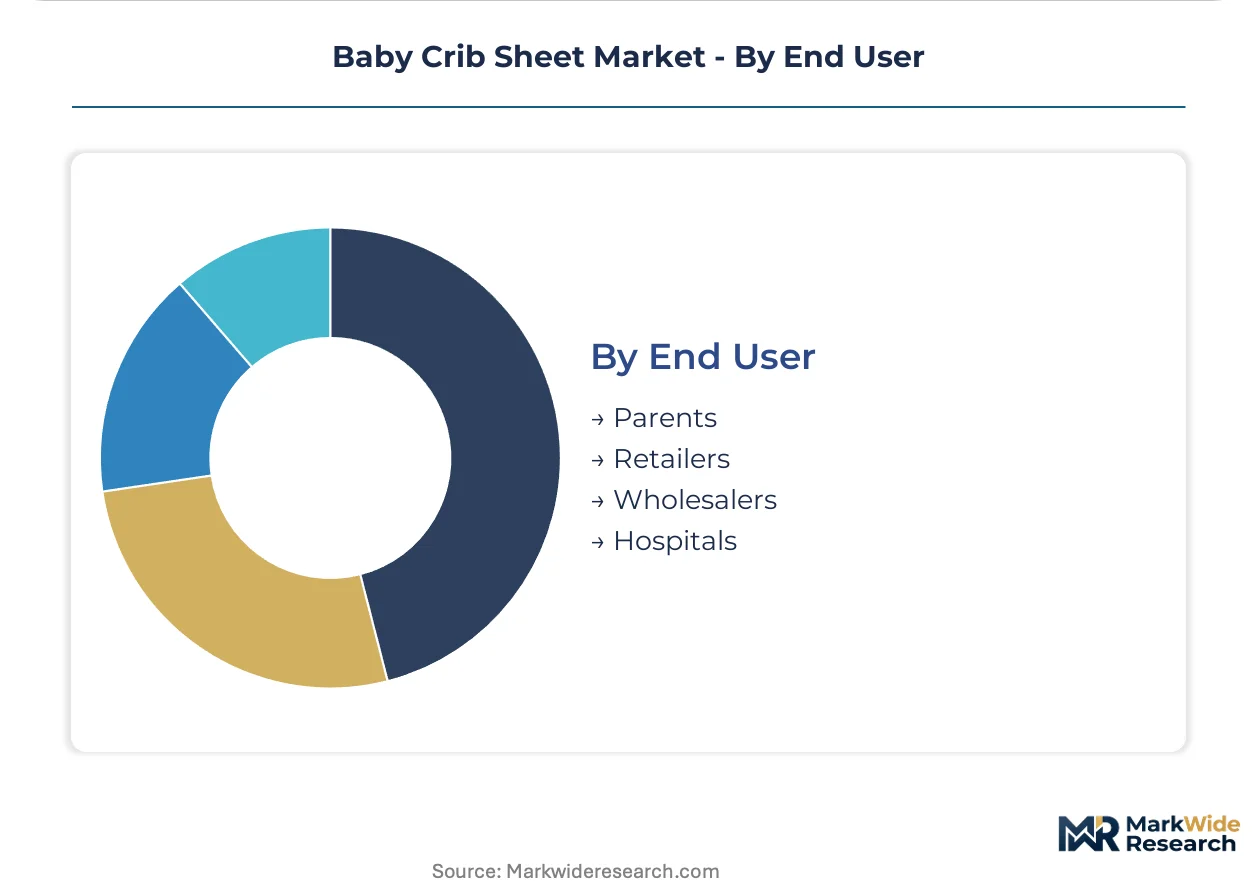
End User:
Procurement sophistication and compliance stringency separate household purchasers from institutional buyers, with documentation requirements and volume scale creating distinct supplier qualification barriers.
- Parents:Individual consumers purchasing one to six units per child demonstrate highest willingness-to-pay for GOTS-certified organic supply chains in United States direct-to-consumer channels. Millennial demographic concentration here drives subscription replacement program adoption.
- Retailers:Specialty baby boutiques and mass-market chains in Germany and South Korea now mandate Oeko-Tex Standard 100 as baseline shelf access. Consolidated buying power compresses margins while demanding lot-level flammability documentation under 16 CFR Part 1615 for United States distribution.
- Wholesalers:Distribution intermediaries serving fragmented independent retailers concentrate volume in emerging markets.
- Hospitals:Maternity ward gift-registry systems in Japan and South Korea create captive audience access at decision-point moments with pre-selected fulfillment triggered by birth events.
Parents generate the highest per-unit margins while hospital channels deliver the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing for baby crib sheets concentrates in textile clusters across China, India, and Pakistan, with finishing and certification operations anchored in Germany, the United States, and Japan. Distribution networks radiate from these hubs to serve distinct national regulatory environments.
United States
Millennial parents in California and New York drive premium organic cotton demand through direct-to-consumer channels. The Consumer Product Safety Commission enforces 16 CFR Part 1615 flammability standards with mandatory lot-level testing documentation. Carter's Inc. maintains volume leadership from its Atlanta headquarters, leveraging omnichannel retail partnerships.
Germany
REACH chemical restrictions from ECHA eliminate formaldehyde-based resins and specific flame retardants from retail-accessible goods. Specialty baby boutiques in Munich and Hamburg now mandate Oeko-Tex Standard 100 as baseline procurement conditions. Bavarian textile finishers specialize in GOTS-certified organic processing for export markets.
Japan
Hospital gift-registry systems in Tokyo and Osaka concentrate demand among pre-selected brands triggered by birth events. METI oversees product safety standards while JIS certification governs textile quality claims. Mini crib formats expand fastest in space-constrained urban apartments across the Kanto region.
South Korea
MFDS regulates infant product safety while climate-conscious parents in Seoul prioritize bamboo-derived temperature-regulating fabrics. Specialty boutiques in Gangnam and Seongnam districts drive fastest category expansion. Domestic brands compete with imported organic cotton lines through aggressive subscription replacement programs.
United Kingdom
London-based direct-to-consumer brands capture premium positioning through GOTS supply chain transparency. The Office for Product Safety and Standards enforces flammability requirements aligned with EU legacy frameworks. Manchester textile clusters handle finishing operations for brands targeting European export channels.
Baby Crib Sheet Market Vendor Landscape
Mass-market volume leaders and premium organic specialists split the market into distinct competitive spheres with minimal direct overlap. Carter's Inc. anchors mass distribution through retail partnerships while Naturepedic and aden + anais occupy certification-driven premium tiers. Three archetypes dominate: scale-driven omnichannel retailers, GOTS-certified organic specialists, and direct-to-consumer digitally native brands. Competitive moves center on subscription program expansion and hospital gift-registry channel penetration.
Within the premium organic tier, Naturepedic exemplifies physician-endorsed GOTS manufacturing while aden + anais represents muslin fabric expertise and hospital channel integration. Carter's Inc. anchors mass-market volume through retail distribution scale. These three entities illustrate the strategic divergence between certification-premium positioning and price-accessible volume capture.
| Leading Market Players |
|---|
| Carter's Inc. |
| Pottery Barn Kids |
| Naturepedic |
| Brooklinen |
| Burt's Bees Baby |
| Avocado |
| aden + anais |
| Parachute |
| Keababies |
| Others |
Supply Flow & Price Mechanics
Nantong textile clusters in Jiangsu Province anchor global crib sheet finishing capacity, with dyehouse concentration creating downstream pricing leverage for Oeko-Tex certified output. This supply density compresses margins for non-compliant manufacturers while amplifying premium realization for GOTS-verified organic cotton lines in German and United States retail channels.
Pricing Analysis
Subscription-based bedding replacement programs drive lifetime value capture among millennial parent cohorts in direct-to-consumer channels. Three-tier pricing structure across premium organic, standard certified, and economy synthetic levels separates GOTS-verified supply chains from commodity polyester blends. Price differentiation hinges on certification grade and elasticized edge durability guarantees. Pricing pressure stems from synthetic microfiber substitution threatening cotton's mass-market position. Institutional buyers in hospital gift-registry channels demonstrate lowest price sensitivity, while mass-market retailers concentrate bargaining power.
Supply Chain Analysis
Extended payment terms from German specialty boutiques strain working capital for Pakistani and Indian raw cotton suppliers. Manufacturing concentrates in China, India, and Pakistan, with finishing operations drawing from Bavarian GOTS-certified processors. Raw material dependencies rest on long-staple cotton varieties, elasticized edge components, and REACH-compliant dye formulations. Single-source vulnerability runs through concentrated organic cotton farm networks in India. Distribution runs through direct-to-consumer platforms, hospital gift-registry systems, and consolidated mass-market retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated direct-to-consumer platforms and hospital gift-registry systems, fragmenting traditional retail channel leverage. This consolidation elevates procurement sophistication and certification stringency as baseline access conditions.
For Market Incumbents: Harden GOTS certification moats through backward integration into organic cotton ginning operations in India. Secure exclusive elasticized edge component supply agreements to outlast durability-testing capital requirements that burden smaller competitors. Carter's Inc. and Naturepedic exemplify divergent defensive positions—scale-driven retail footprint versus physician-endorsed organic specialization. For New Entrants and Emerging Players: Mini crib formats in Japanese and South Korean urban apartment markets represent the most penetrable entry point, with space-constrained demographics underserved by standard-sizing incumbents. Bamboo-derived temperature-regulating fabrics in humid climate zones offer material differentiation white space. Hospital gift-registry channel partnerships provide captive audience access at decision-point moments with pre-selected fulfillment triggers. For Investors and Strategic Acquirers: Long-term, this sits as a certification-anchored recurring revenue play because subscription replacement programs and Oeko-Tex baseline requirements create durable customer lock-in and regulatory barriers. Acquisition targets should demonstrate GOTS supply chain transparency and direct-to-consumer platform integration. Watch for Oeko-Tex Standard 100 adoption velocity in South Korean retail channels as inflection indicator for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Replacement Program Launch | Captures recurring revenue from millennial parents through automated sizing upgrades across infant growth stages. |
| GOTS Certification Investment | Secures retail access filters in German specialty boutiques and United States direct-to-consumer channels. |
| Hospital Gift-Registry Integration | Creates captive audience access at birth-event decision points in Japanese and South Korean maternity wards. |
| Bamboo Fabric Line Expansion | Addresses climate-conscious demand in humid regions through temperature-regulating viscose properties. |
| Blockchain Traceability Deployment | Virtualizes organic cotton authentication for millennial parents scanning QR codes for farm-level documentation. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of CPSC flammability documentation, Oeko-Tex certification databases, and REACH regulatory filings. Primary interviews engaged brand managers at direct-to-consumer platforms, category buyers at German specialty boutiques, supply planners at textile finishers, and procurement leads at hospital gift-registry systems. Secondary sources included Consumer Product Safety Commission enforcement records, ECHA substance restriction updates, and customs trade data for cotton textile flows. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Forecast inputs incorporate material substitution dynamics, certification adoption curves, and channel shift velocities across the projection horizon. Segmentation modeling addressed material type, size specification, design complexity, and end-user procurement sophistication. CAGRs derived from regression analysis against macroeconomic indicators and demographic cohort expansion patterns. Industry-specific inputs included GOTS certification timeline compression effects and elasticized edge durability testing capital requirements.
Macroeconomic conditions sit as an overlay; deviation in raw cotton commodity prices, freight rate volatility, or consumer discretionary spending would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and certification standard persistence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Home Textiles Market
Home Textiles
Japan Home Textile Market
Home Textiles
North America Home Textile Market
Home Textiles
South Korea Home Textile Market
Home Textiles
Canada Home Textile Market
Home Textiles
China Home Textiles Market
Home Textiles
Turkey Home Textile Market
Home Textiles
Latin America Home Textiles Market
Home Textiles
Fabric Wash and Care Market
Home Textiles
Linen Bed Sheets Market
Home Textiles
Europe Home Textile Market
Home Textiles
Vietnam Home Textile Market
Home Textiles
France Home Textile Market
Home Textiles
Germany Home Textile Market
Home Textiles
India Home Textile Market
Home Textiles
Russia Home Textile Market