
 Turkey Home Textile Market | 2026-2036
Turkey Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Home Textile Market Analytics
Hospitality procurement is consolidating as Turkish hotels and resort operators upgrade linen standards ahead of peak tourism seasons. Zorlu Textiles Group leverages integrated spinning-to-finishing operations to serve premium hotel chains. Karaca Home competes through design-led positioning in domestic retail channels. Vakko Tekstil anchors its presence in silk and luxury fabric segments for upscale hospitality contracts.
Turkey home textile encompasses woven and knitted fabric products designed for residential and commercial interior environments, typically manufactured from natural or synthetic fibers with thread counts ranging from 200 to 800 for bed linen applications. Cotton bed linen dominates production volumes due to breathability and durability specifications favored by institutional buyers. Polyester material is gaining share in hospitality applications where rapid-cycle laundering demands synthetic resilience. Online distribution channels are expanding fastest among end users, though offline retail still controls the majority of residential transactions through established home goods networks.
The Turkish Standards Institution sets mandatory fiber content labeling and flammability standards for domestic textile sales, while OEKO-TEX certification shapes export access to European retail buyers. BIS-equivalent import compliance requirements from destination markets constrain smaller producers lacking testing infrastructure. Stakeholders must monitor evolving EU textile sustainability regulations and digital traceability mandates to preserve competitive positioning in cross-border trade.
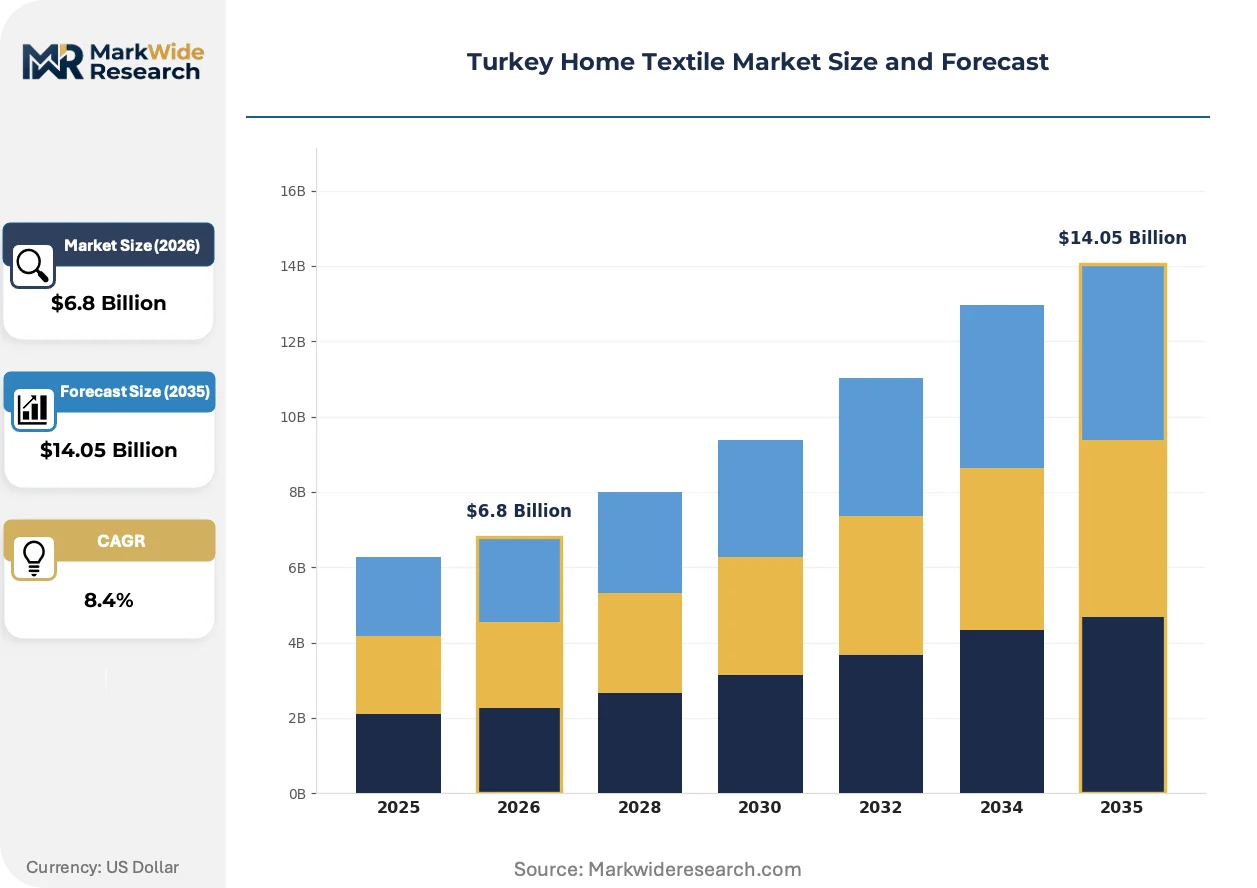
Market Dynamics
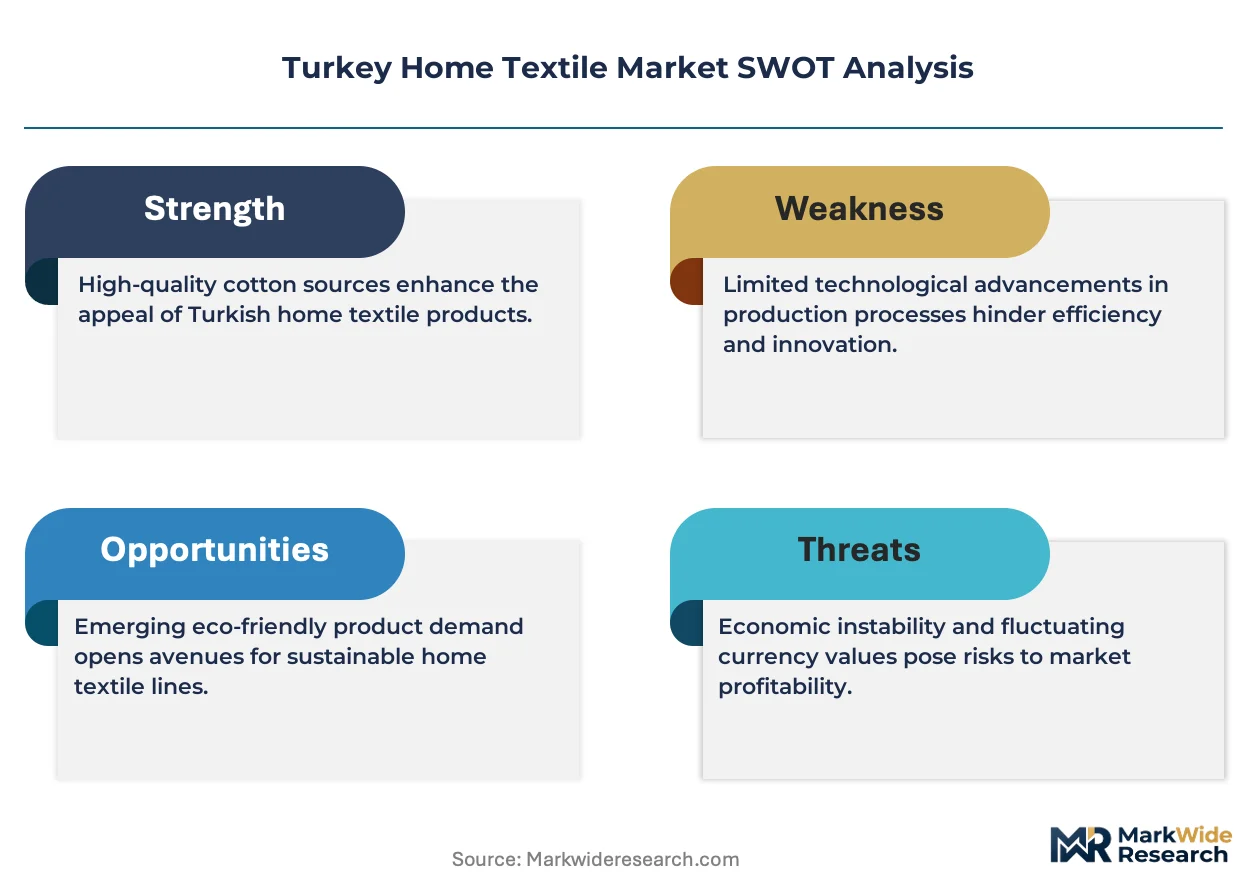
Turkey's home textile sector faces intensifying pressure from OEKO-TEX certification mandates that filter export access to European retail buyers. Istanbul's manufacturing corridor concentrates spinning-to-finishing capacity, creating supply-side leverage for integrated producers serving hospitality procurement upgrades.
Growth Catalysts
- EU Green Deal textile sustainability regulations:Turkish exporters with certified organic cotton supply chains capture preferential placement in German and French retail channels.
- Hospitality linen standard upgrades:Istanbul hotel operators and Aegean resort chains are replacing polyester blends with higher-thread-count cotton specifications ahead of peak tourism cycles.
- Digital traceability infrastructure:Blockchain-enabled fiber tracking is expanding into premium bed linen segments, satisfying Scandinavian buyer audit requirements.
Market Restraints
- Raw cotton price volatility:Turkish spinners depend on imported upland cotton from Central Asian suppliers, exposing margin structures to currency and commodity swings.
- Testing infrastructure concentration:OEKO-TEX certification laboratories cluster in Istanbul and Izmir, forcing Anatolian producers into costly logistics or informal subcontracting.
- Polyester substitution in hospitality:Rapid-cycle commercial laundering demands are displacing cotton share in mid-tier hotel contracts.
Strategic Opportunities
- Antalya and Bodrum resort corridor:Underpenetrated luxury villa rental operators present white-space demand for bespoke linen services.
- Digital textile printing convergence:Reactive inkjet systems combined with AI-driven pattern generation enable micro-batch customization for design-led domestic retailers.
- Domestic e-commerce channel expansion:Trendyol and Hepsiburada marketplace infrastructure is opening direct-to-consumer pathways bypassing traditional home goods networks.
Industry Challenges
- Certification timeline compression:OEKO-TEX Standard 100 renewal cycles strain quality control departments at mid-scale weaving operations.
- Legacy ERP integration with traceability platforms:Family-owned textile mills face technical debt barriers when connecting inventory systems to EU digital product passport requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Home Textile Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bed Linen, Curtains, Towels, Cushion Covers Material: Cotton, Polyester, Linen, Silk End User: Residential, Hospitality, Healthcare, Retail Distribution Channel: Online, Offline Retail, Wholesalers, Direct Sales |
| Companies Covered | Zorlu Textiles Group, Karaca Home, Vakko Tekstil, Sanko Holding, Kipas Holding, Teksin Group, Yünsa, Kardem Tekstil, Sasa Polyester Sanayi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Home Textile Market Evolving Landscape
Digital traceability infrastructure and sustainable fiber chemistry are reshaping competitive positioning in Turkey's home textile sector. Manufacturers are racing to align production systems with tightening EU compliance windows while capturing hospitality procurement upgrades.
Recycled cotton fiber processing is expanding into mainstream bed linen production. Denizli-based spinning operations are installing mechanical recycling lines to blend post-industrial cotton waste with virgin fiber. Hospitality procurement teams at Istanbul hotel chains are specifying minimum recycled content thresholds. This technology is expanding into mid-market export contracts previously closed to premium organic positioning.
Turkish Standards Institution mandatory fiber content labeling is tightening enforcement ahead of EU digital product passport alignment. Domestic retail inspectors are escalating penalties for mislabeled blends in bazaar and mall channels. Export-oriented producers in Bursa and Gaziantep are pre-emptively adopting blockchain-backed composition certificates. Small-scale Anatolian weavers lacking documentation infrastructure face exclusion from cross-border trade.
Certification-driven buyer preference is compressing sourcing cycles for uncertified suppliers. German and Dutch retail procurement teams are requiring OEKO-TEX and GOTS dual certification as table stakes. Turkish exporters with single-certification portfolios are losing bid rounds to integrated competitors. This shift is most visible in cotton bed linen tenders for Nordic hospitality groups.
Turkey Home Textile Market Segmentation
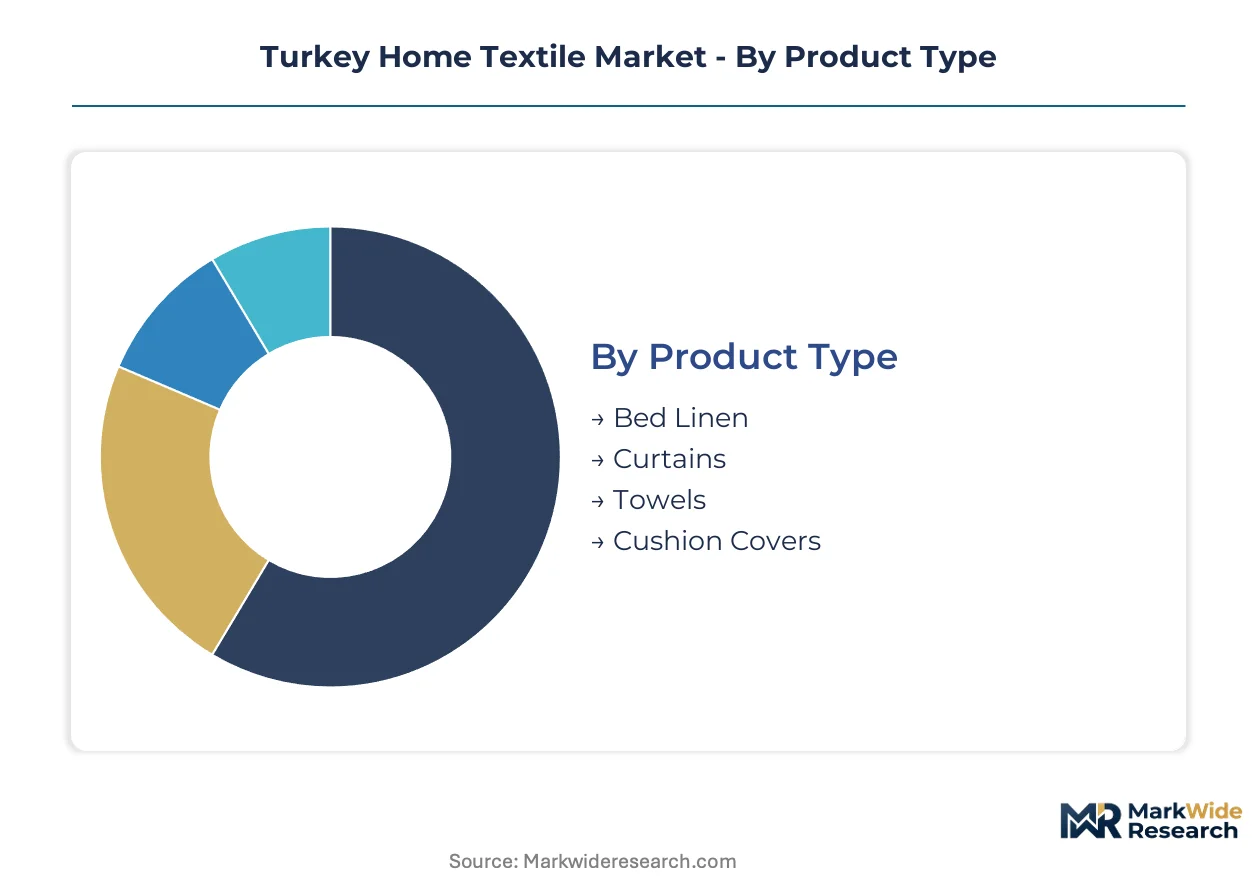
Segmentation in Turkey's home textile market reveals how procurement specifications diverge across institutional buyers versus residential consumers. Thread count, fiber certification, and laundering durability separate premium hospitality contracts from mass-market retail positioning.
Product Type:
Thread count and finishing specifications define competitive positioning across interior textile categories.
- Bed Linen:Thread counts ranging from 200 to 800 distinguish institutional hospitality procurement from economy retail tiers. Istanbul hotel operators and Aegean resort chains specify higher-count cotton percale ahead of peak tourism cycles, driving premium fiber sourcing.
- Towels:GSM weight and ring-spun construction determine absorption performance for commercial laundering environments. Turkish hospitality procurement teams prioritize 500-700 GSM terry specifications for durability under rapid-cycle industrial washing.
- Curtains:Blackout lining and thermal insulation layers serve commercial and residential energy efficiency requirements.
- Cushion Covers:Decorative accent pieces with lower technical specifications dominate domestic retail channels.
Mature deployment sits with bed linen serving institutional buyers. Newer deployment is concentrated in technical curtain specifications for hospitality energy compliance.
Material:
Fiber chemistry and certification status shape export access and margin structures.
- Cotton:Breathability and durability specifications favor natural fiber for institutional bed linen applications. Denizli-based spinning operations blend post-industrial recycled cotton with virgin fiber to meet emerging hospitality procurement thresholds.
- Polyester:Synthetic resilience supports rapid-cycle commercial laundering demands displacing cotton in mid-tier hotel contracts. Bursa producers leverage polyester blends for cost-sensitive export tenders.
- Linen:High-moisture-wicking properties serve upscale residential and boutique hospitality positioning.
- Silk:Luxury fabric segments anchor Vakko Tekstil's presence in upscale hospitality contracts.
Certified organic cotton supply chains capture preferential placement in German and French retail channels. Recycled fiber processing is expanding most quickly into mainstream bed linen production.
End User:
Procurement authority and volume scale separate institutional buyers from fragmented residential demand.
- Hospitality:Consolidated procurement by Istanbul hotel operators and Aegean resort chains drives linen standard upgrades. Zorlu Textiles Group leverages integrated spinning-to-finishing operations to serve premium hotel chains with certified fiber documentation.
- Residential:Fragmented demand channels through established home goods networks and emerging e-commerce platforms. Karaca Home competes through design-led positioning in domestic retail channels.
- Healthcare:Antimicrobial finishing and industrial laundering compatibility define technical specifications.
- Retail:Intermediary buyers aggregate volume for private-label distribution across European markets.
Volume concentration sits with hospitality procurement. Digital traceability adoption is climbing the fastest among healthcare institutional buyers facing audit requirements.
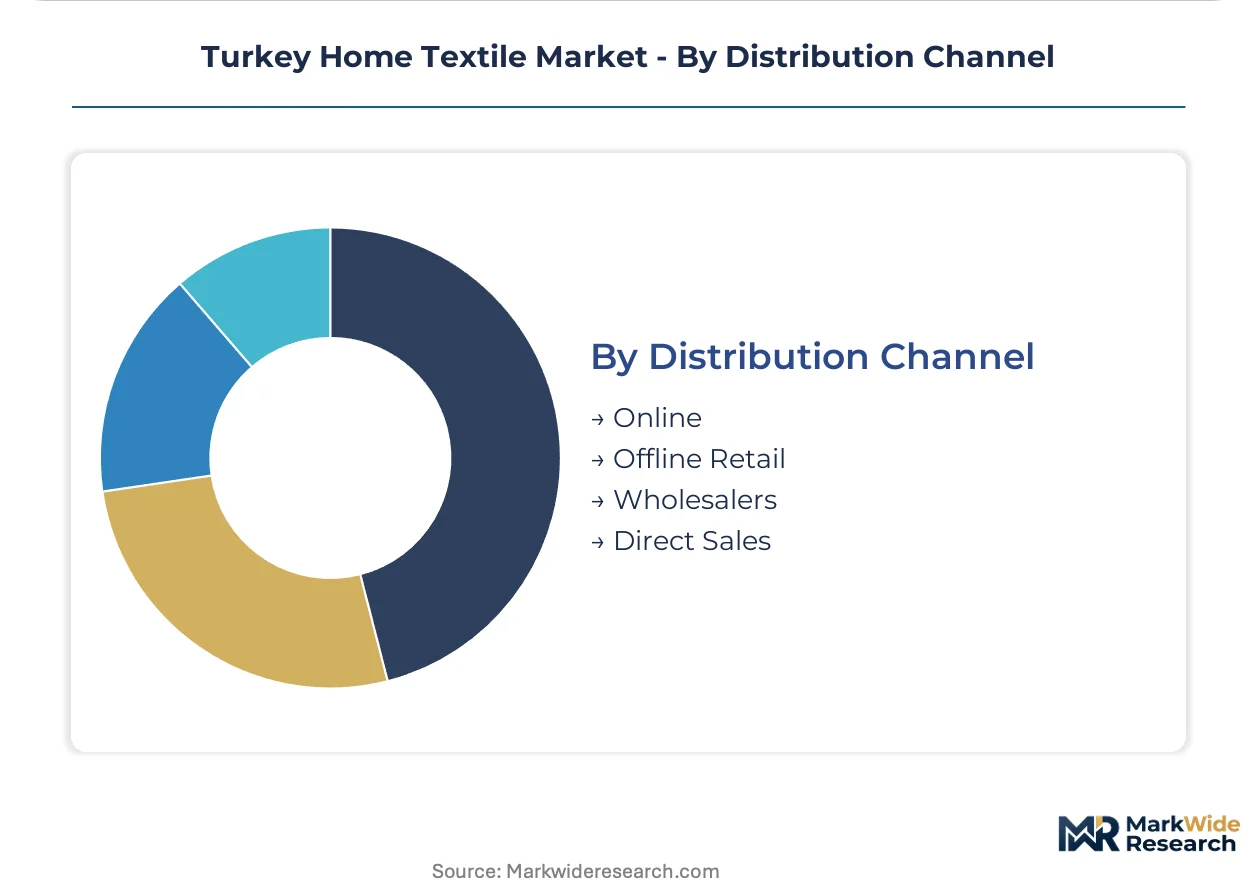
Distribution Channel:
Channel economics and buyer documentation requirements reshape competitive access.
- Online:Direct-to-consumer pathways bypass traditional home goods networks through Trendyol and Hepsiburada marketplace infrastructure. Digital channels are expanding most quickly among residential end users seeking design-led positioning.
- Offline Retail:Established home goods networks still control majority residential transactions requiring tactile evaluation. Mall and bazaar channels face tightening Turkish Standards Institution enforcement on fiber content labeling.
- Wholesalers:Volume aggregation for export markets demands OEKO-TEX certification documentation.
- Direct Sales:Bespoke linen services target underpenetrated luxury villa rental operators in Antalya and Bodrum resort corridors.
Established control sits with offline retail in residential segments. Marketplace infrastructure is gaining share fastest in domestic e-commerce channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey's home textile production concentrates in Istanbul's manufacturing corridor and Aegean industrial zones, while domestic consumption spreads across Anatolian population centers and coastal tourism hubs. Export demand pulls output toward European retail buyers and Middle Eastern hospitality operators.
Marmara Region
Istanbul hotel operators and Aegean resort chains drive premium linen procurement ahead of peak tourism cycles. The Turkish Standards Institution enforces mandatory fiber content labeling and flammability standards across domestic retail channels. Bursa hosts integrated spinning-to-finishing operations serving export-oriented hospitality contracts with OEKO-TEX certification documentation.
Aegean Region
Denizli-based spinning operations blend post-industrial recycled cotton with virgin fiber to meet emerging hospitality procurement thresholds. EU Green Deal textile sustainability regulations shape export access for producers targeting German and French retail channels. Izmir clusters OEKO-TEX certification laboratories, creating testing infrastructure leverage for regional exporters.
Mediterranean Region
Antalya and Bodrum resort corridors present white-space demand for bespoke linen services targeting luxury villa rental operators. The country's national textile quality regulator mandates OEKO-TEX certification requirements for cross-border trade. Gaziantep weaving operations pre-emptively adopt blockchain-backed composition certificates to satisfy EU digital product passport alignment.
Central Anatolia
Polyester material gains share in hospitality applications where rapid-cycle laundering demands synthetic resilience. BIS-equivalent import compliance requirements from destination markets constrain smaller producers lacking testing infrastructure. Kayseri and surrounding industrial zones concentrate mid-scale weaving operations facing certification timeline compression from OEKO-TEX Standard 100 renewal cycles.
Turkey Home Textile Market Competitive Landscape
Top-tier vendors anchor integrated spinning-to-finishing operations, while mid-scale weavers compete through design-led positioning or specialized fiber segments. The vendor base stratifies across three tiers: multinational hospitality suppliers with captive certification infrastructure, regional specialists leveraging domestic retail channels, and commodity producers serving cost-sensitive export tenders. Strategic archetypes include backward-integrated fiber-to-fabric operators, design-forward home goods brands, and synthetic fiber specialists. Dominant competitive moves encompass certification pre-positioning for EU compliance windows and e-commerce marketplace expansion bypassing traditional distribution networks.
Within the integrated operations tier, Zorlu Textiles Group and Kipas Holding represent archetypes of spinning-to-finishing control serving institutional procurement. Vakko Tekstil occupies a position in silk and luxury fabric segments for upscale hospitality contracts. Among design-led domestic retailers, Karaca Home exemplifies positioning through aesthetic differentiation in residential channels.
| Leading Market Players |
|---|
| Zorlu Textiles Group |
| Karaca Home |
| Vakko Tekstil |
| Sanko Holding |
| Kipas Holding |
| Teksin Group |
| Yünsa |
| Kardem Tekstil |
| Sasa Polyester Sanayi |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap weaving operations across Denizli and Gaziantep anchor supply-side discipline through generational capital constraints that limit speculative inventory builds. Their reliance on informal subcontracting networks for OEKO-TEX certification documentation compresses pricing power at the lower tier while integrated spinners in Bursa capture premium hospitality contract margins.
Pricing Analysis
Margin tightening in mid-tier bed linen reflects polyester substitution pressure from rapid-cycle commercial laundering demands. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX dual-certified organic cotton from single-certified blends and uncertified commodity tiers. Certification grade and volume scale drive price differentiation, with institutional buyers negotiating long-term offtake contracts. Hospitality procurement teams show least price sensitivity for certified fiber documentation, while mass-market domestic retailers face acute cost compression.
Supply Chain Analysis
Turkish Standards Institution fiber content labeling mandates reshape sourcing toward documented supply chains with blockchain-backed composition certificates. Geographic supply concentrates in Turkey, Uzbekistan, and Turkmenistan for upland cotton inputs. Raw material dependencies rest on Central Asian cotton shipments, synthetic fiber feedstock from Bursa petrochemical complexes, and reactive dye chemicals from German specialty suppliers. Single-source vulnerability sits with Istanbul-Izmir laboratory clustering for OEKO-TEX certification. Distribution runs through wholesale aggregators for European export markets, direct sales for Antalya-Bodrum luxury villa operators, and marketplace platforms for domestic e-commerce.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's home textile sector is consolidating around certification infrastructure investments that filter out Anatolian weavers lacking testing access. EU digital product passport alignment pressures accelerate this Darwinian selection.
For Market Incumbents: Anchor defensive positioning through captive OEKO-TEX laboratory partnerships in Izmir and preemptive blockchain traceability integration. Zorlu Textiles Group and Kipas Holding should deepen backward integration into Denizli spinning capacity to secure recycled cotton fiber thresholds specified by Istanbul hotel operators. Certification timeline compression from Standard 100 renewal cycles threatens mid-scale competitors lacking quality control department scale. For New Entrants and Emerging Players: Marketplace infrastructure operators like Trendyol and Hepsiburada present the most penetrable channel for design-led micro-batch positioning. White-space demand concentrates in Antalya and Bodrum bespoke linen services for luxury villa rental operators underserved by incumbent hospitality suppliers. Direct-to-consumer pathways bypassing traditional home goods networks offer the cleanest go-to-market angle for AI-driven pattern generation capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Denizli weavers with mechanical recycling line installations and dormant OEKO-TEX certification relationships. Long-term viability over a multi-year horizon hinges on EU Green Deal textile sustainability regulation pre-positioning. Watch for inflection signals in German retail procurement team dual-certification mandates tightening from preferred to required status.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Denizli Spinning | Captures recycled cotton fiber thresholds demanded by Istanbul hotel procurement teams. |
| Blockchain Traceability Infrastructure | Satisfies EU digital product passport alignment requirements for Scandinavian buyer audits. |
| Direct-to-Consumer Marketplace Launch | Bypasses traditional home goods networks through Trendyol and Hepsiburada platform infrastructure. |
| Dual-Certification Portfolio Expansion | Secures bid competitiveness against OEKO-TEX and GOTS requirements from German retail buyers. |
| AI-Driven Pattern Generation Capability | Enables micro-batch customization for design-led domestic retailers seeking reactive inkjet differentiation. |
Research Methodology
Document review covered Turkish Standards Institution regulatory filings, EU Green Deal textile sustainability directive drafts, and OEKO-TEX association certification databases, complemented by interviews with spinning operations managers, hospitality procurement directors at Istanbul hotel chains, and domestic retail category buyers. Secondary validation drew from customs export records, Turkish Exporters Assembly trade statistics, and Bursa Denim and Apparel Exporters Association capacity reports. Bottom-up facility-level capacity aggregation and top-down trade flow analysis provided cross-triangulation.
Historical shipment volumes were cross-referenced against panel input from Aegean resort chain linen buyers and Central Asian cotton trading desks. The analytical framework modeled product type, material certification tier, end-user procurement authority, and distribution channel documentation requirements across the projection horizon. CAGRs were derived from segment-level volume buildups adjusted for fiber substitution elasticities and regulatory compliance cost pass-through assumptions.
Caveats apply where raw cotton price volatility from Uzbekistan supply disruptions or accelerated EU digital product passport enforcement timelines could materially shift the outlook. Forecasts reflect assumptions on certification laboratory capacity expansion and hospitality tourism cycle recovery patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Baby Crib Sheet Market
Home Textiles
France Home Textile Market
Home Textiles
Mexico Home Textile Market
Home Textiles
Russia Home Textile Market
Home Textiles
Microfiber Cleaning Cloth Market
Home Textiles
United States Home Textile Market
Home Textiles
Blanket Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Saudi Arabia Home Textile Market
Home Textiles
Cotton Towel Market
Home Textiles
Wool Dryer Ball Market
Home Textiles
Australia Home Textiles Market
Home Textiles
GCC Home Textile Market
Home Textiles
Germany Home Textile Market
Home Textiles
India Home Textile Market
Home Textiles
Global Theater Linen Market