
 Global Product Cost Management Market | 2026-2036
Global Product Cost Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Product Cost Management Market Foresight
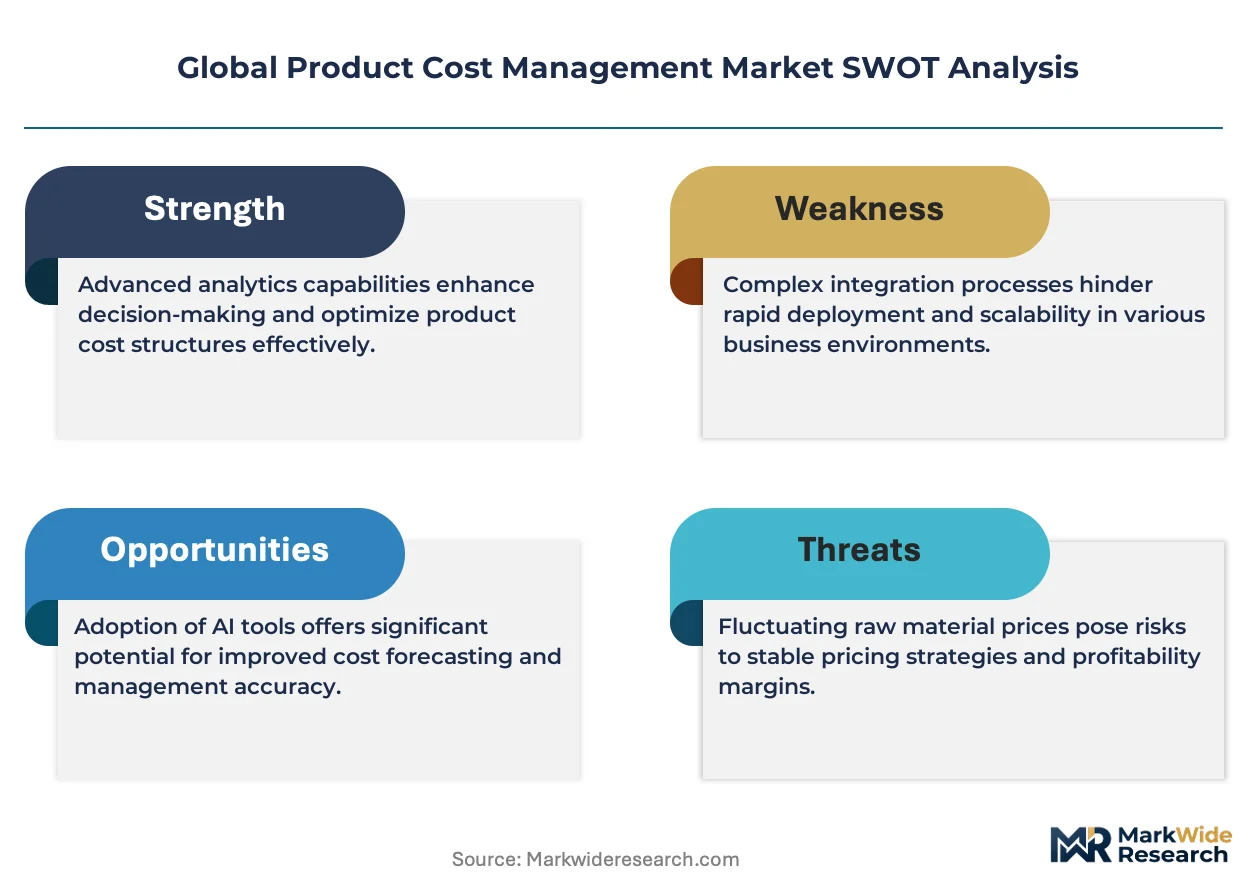
The EU CSRD is decoupling cost reporting from traditional financial statements, forcing manufacturers to adopt granular product cost management platforms. SAP SE leverages its S/4HANA architecture to anchor enterprise-wide cost transparency across European automotive supply chains. Siemens AG sustains competitive positioning through its Teamcenter integration, which dominates digital thread deployments in industrial machinery. aPriori Technologies specializes in automated design-to-cost analytics, competing directly with incumbent PLM providers in aerospace material sourcing.
Product cost management encompasses methodologies, software platforms, and organizational processes that forecast, track, and optimize direct material, labor, and overhead costs across a product's lifecycle from concept through end-of-life. Core functional parameters include real-time should-cost modeling, parametric estimation algorithms, and multi-currency supplier quote normalization for global sourcing decisions. Cloud-based deployment modes now lead segment growth as manufacturers prioritize scalable supplier collaboration without heavy infrastructure commitments. Cost estimation solutions command the deepest margin pools due to their integration with CAD and PLM systems, while spend analysis applications represent the fastest-growing category as procurement teams demand predictive supplier risk scoring.
The U.S. SEC climate disclosure rules and China's GB standards on product carbon footprinting are reshaping how cost platforms incorporate environmental compliance data into total landed cost calculations. Japan's METI has issued guidance linking cost management systems to supply chain resilience certification, creating new procurement criteria for platform vendors. Stakeholders must monitor whether emerging AI-driven cost prediction modules will consolidate around PLM-native architectures or remain as standalone specialist offerings.
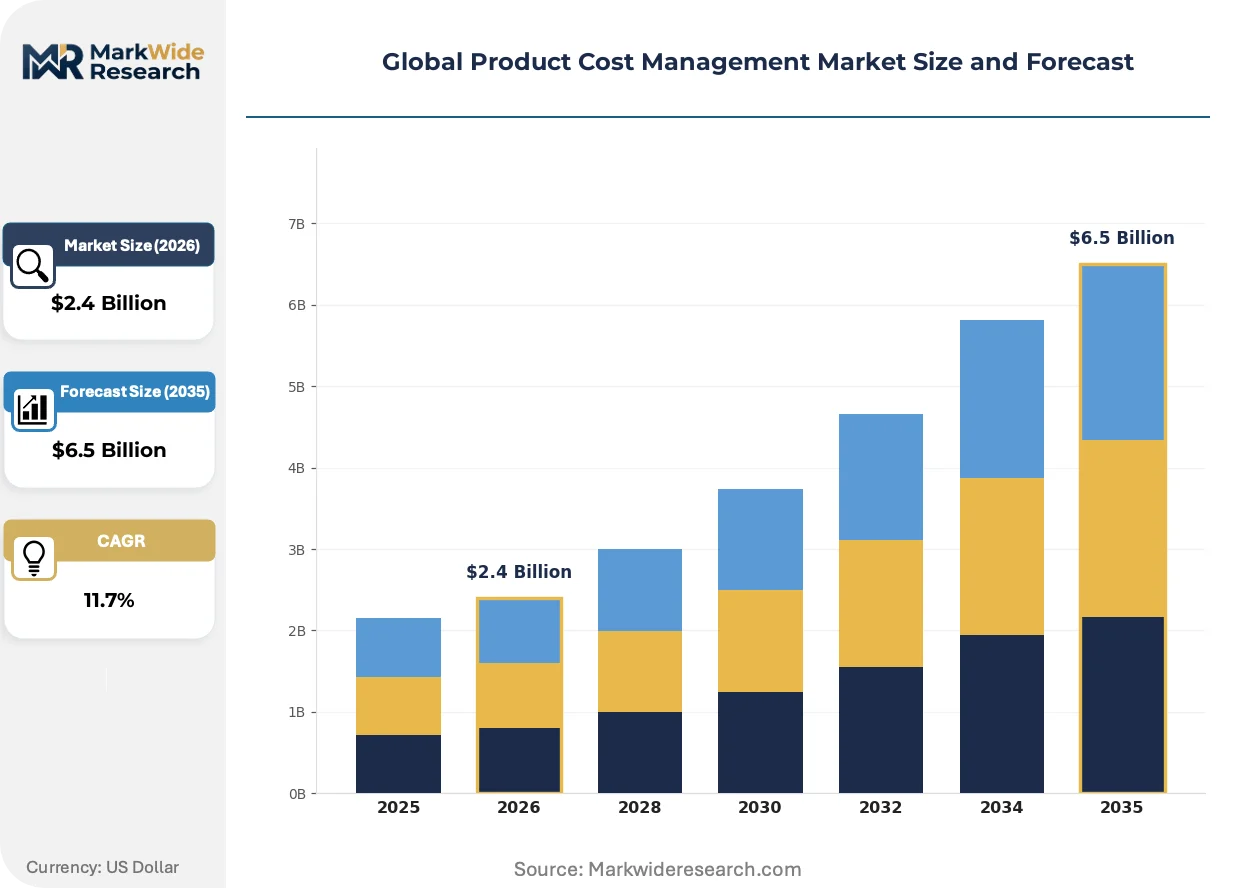
Market Dynamics
The EU CSRD is decoupling cost reporting from traditional financial statements, forcing manufacturers to adopt granular product cost management platforms that embed environmental compliance data into total landed cost calculations across multi-tier supply chains.
Growth Catalysts
- Aerospace material volatility:Titanium and composite price swings are accelerating deployment of should-cost modeling platforms among aircraft OEMs and tier-1 suppliers managing long-lead procurement cycles.
- CSRD supply chain mandates:The EU directive requires granular cost transparency from third-country suppliers, compelling platform adoption for automated data collection and audit-ready reporting.
- Cloud infrastructure maturation:Scalable SaaS architectures are eliminating heavy on-premise commitments, enabling mid-market manufacturers to access enterprise-grade cost estimation capabilities previously reserved for large enterprises.
Market Restraints
- Legacy system integration costs:ERP and PLM environments built over decades create prohibitive data mapping expenses when connecting to modern cost management platforms.
- Supplier data asymmetry:Tier-2 and tier-3 suppliers in emerging manufacturing clusters lack digital maturity, creating blind spots in should-cost calculations for critical components.
- Skills scarcity in parametric modeling:The shortage of engineers trained in design-to-cost methodologies limits deployment velocity even where software budgets exist.
Strategic Opportunities
- India PLI scheme alignment:Production-linked incentive beneficiaries require granular cost tracking for compliance and margin optimization across electronics and automotive component manufacturing.
- AI-driven predictive costing:Machine learning modules converging with CAD environments enable real-time cost feedback during design iterations, compressing traditional estimation timelines.
- Carbon-embedded pricing models:The EU Green Deal and China's dual carbon goals are creating demand for platforms that unify financial and environmental cost dimensions in supplier negotiations.
Industry Challenges
- Multi-currency quote normalization complexity:Procurement teams struggle to reconcile volatile exchange rate impacts against long-term supplier agreements spanning diverse geographies.
- Cross-functional adoption friction:Cost engineers, procurement specialists, and design teams operate with conflicting KPIs, creating organizational resistance to unified platform workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Product Cost Management Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cost Estimation, Price Optimization, Supplier Management, Spend Analysis, Budget Planning Deployment Mode: Cloud-Based, On-Premises, Hybrid, SaaS, Hosted Application: Manufacturing, Electronics Design, Construction Planning, Supply Chain Negotiation, New Product Development End User Industry: Consumer Electronics, Aerospace, Chemicals Processing, Telecommunications, Automotive OEMs |
| Companies Covered | SAP SE, Oracle Corporation, Siemens AG, Dassault Systèmes, IBM Corporation, PTC Inc., Autodesk Inc., aPriori Technologies, Coupa Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Product Cost Management Market Shifts & Advancements
Generative AI architectures are unifying previously siloed cost data streams, enabling predictive supplier risk scoring and automated should-cost generation that compresses traditional estimation cycles from weeks to hours.
Digital thread technology is unifying CAD, PLM, and ERP cost data into continuous feedback loops. Aerospace and industrial machinery manufacturers are adopting these integrations fastest, with Germany's automotive supply chains showing particular deployment velocity. This convergence is compressing the gap between design decisions and cost validation, reducing late-stage engineering change orders.
The U.S. SEC climate disclosure rules are mandating Scope 3 emissions reporting that embeds carbon costs into financial statements. Industrial manufacturers with complex global supplier networks face the steepest compliance burdens, driving demand for platforms that automate environmental cost allocation across multi-tier sourcing structures. Automotive OEMs are responding fastest, integrating these capabilities into existing procurement workflows.
Design-to-cost methodologies are displacing traditional target-costing approaches in capital-intensive industries. Heavy machinery and defense contractors are leading this behavioral shift, embedding cost engineers earlier in product development cycles. Japan's METI guidance on supply chain resilience certification has accelerated this transition among precision equipment manufacturers seeking procurement preference in government tenders.
Global Product Cost Management Market Segmentation
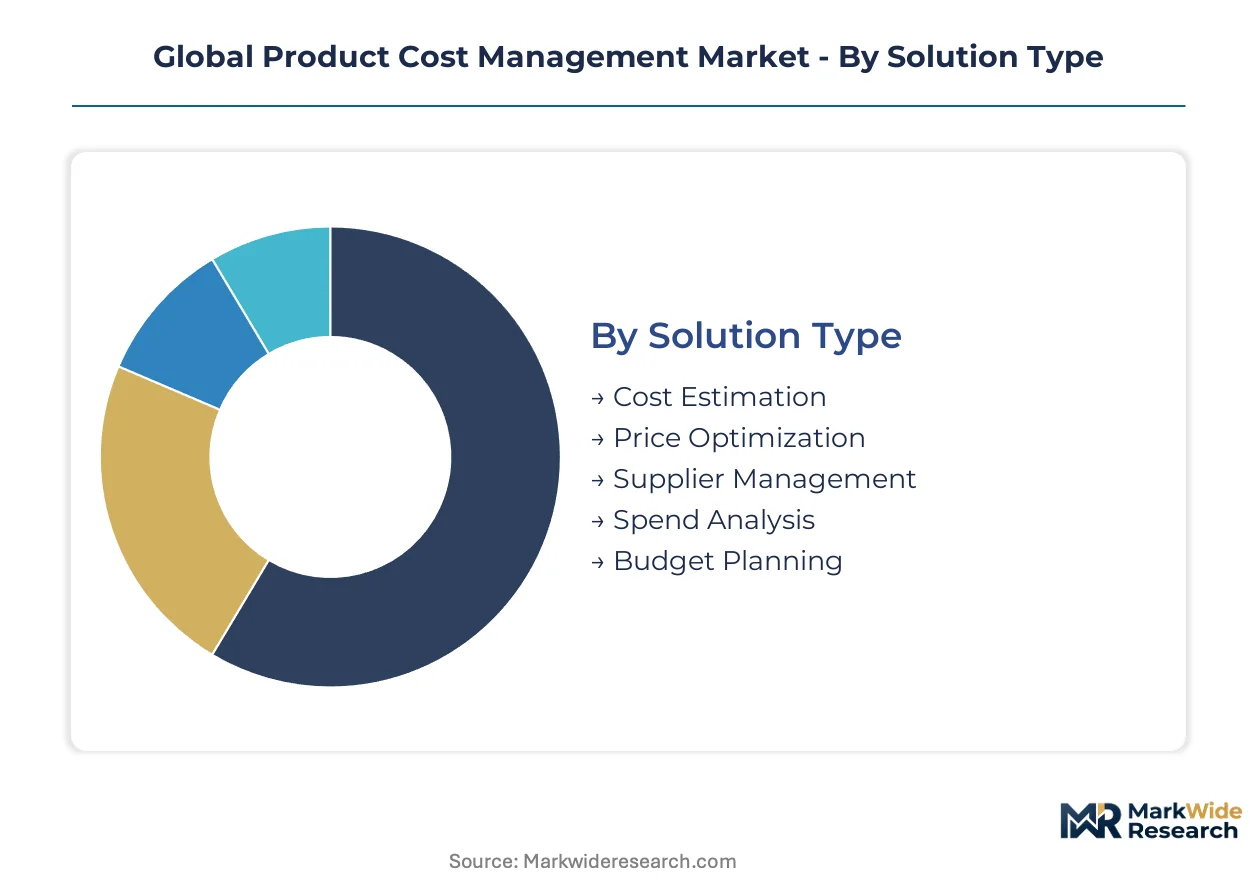
Product cost management platforms must align with distinct operational workflows across manufacturing environments. Solution architectures vary dramatically in implementation complexity and integration requirements. Deployment choices directly constrain supplier collaboration scope and real-time data accessibility.
Solution Type:
Capital intensity concentrates in modules requiring deep CAD and PLM integration, where licensing and customization costs scale with enterprise complexity.
- Cost Estimation:Parametric algorithms generate should-cost models from geometric CAD data and material specifications. Aerospace OEMs in Germany and the United States anchor demand as titanium and composite volatility forces earlier cost validation in design cycles.
- Price Optimization:Machine learning modules analyze historical quote patterns and commodity indices to recommend negotiation positions. Automotive OEMs in Japan leverage these tools under METI supply chain resilience guidelines that reward procurement sophistication in government tenders.
- Supplier Management:Multi-tier supplier onboarding and performance scorecarding.
- Spend Analysis:Predictive supplier risk scoring and category intelligence dashboards.
- Budget Planning:Cross-functional cost target allocation and variance tracking.
Most installed capacity flows through Cost Estimation. Expansion is steepest in Spend Analysis.
Deployment Mode:
Mid-market manufacturers gravitate toward lower-commitment architectures that preserve capital for production equipment.
- Cloud-Based:Scalable infrastructure with browser-based access for distributed engineering teams. Electronics manufacturers in South Korea and Taiwan prioritize these deployments to synchronize cost data across geographically dispersed design centers without dedicated IT overhead.
- SaaS:Subscription pricing eliminates perpetual license commitments. Industrial machinery producers in Italy and Spain adopt these models to access enterprise-grade capabilities previously reserved for large enterprises with dedicated infrastructure budgets.
- On-Premises:Air-gapped installations for defense and aerospace security requirements.
- Hybrid:Sensitive cost data on-premise with supplier collaboration tools in cloud.
- Hosted:Managed private cloud with vendor-operated infrastructure.
Cloud-Based deployments carry the heaviest current installed base. SaaS models are climbing the fastest among new implementations.
Application:
Engineering change frequency determines platform ROI, with volatile design environments justifying the steepest investment.
- Manufacturing:Shop-floor cost tracking and production variance analysis. Chemicals processors in Germany deploy these modules to manage energy-intensive process costs under EU ETS carbon pricing mechanisms.
- New Product Development:Design-to-cost integration from concept through prototype. Consumer electronics brands in China align these deployments with GB standards on product carbon footprinting to embed environmental compliance into financial planning.
- Electronics Design:Component cost forecasting for PCB and semiconductor sourcing.
- Construction Planning:Material takeoff and subcontractor quote normalization.
- Supply Chain Negotiation:Real-time should-cost validation during supplier discussions.
Manufacturing applications dominate current deployments. New Product Development shows the steepest expansion trajectory as design cycles compress.
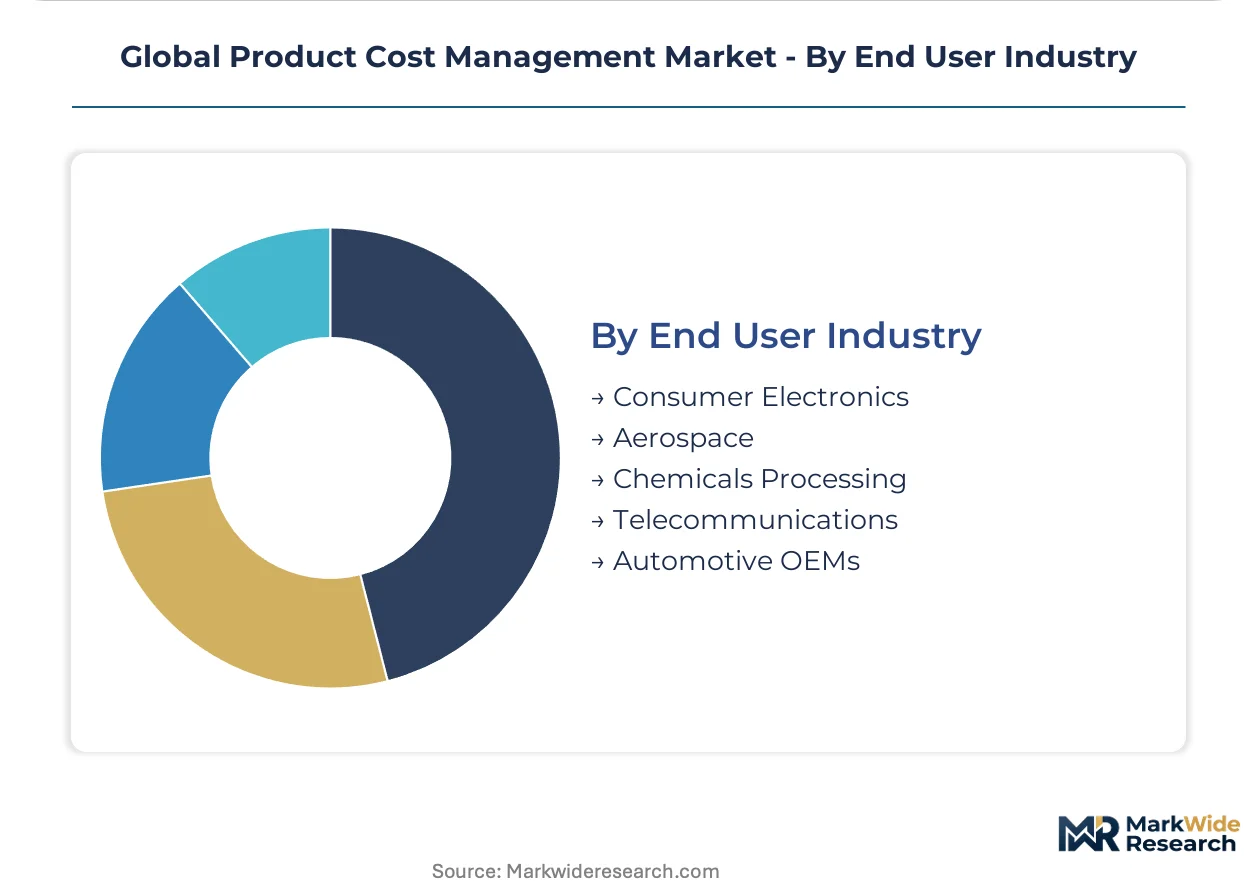
End User Industry:
Regulatory compliance burden and material cost volatility create divergent platform requirements across verticals.
- Automotive OEMs:Platform deployments spanning powertrain, chassis, and electronics cost engineering. Manufacturers in Germany anchor European adoption as CSRD mandates force granular supply chain cost transparency from third-country suppliers.
- Aerospace:Long-lead material sourcing and program cost control. Boeing and Airbus tier-1 suppliers in France and the United States drive specialized requirements for titanium and composite cost modeling.
- Consumer Electronics:Rapid component cost forecasting for high-volume assembly.
- Chemicals Processing:Feedstock cost volatility management and regulatory compliance allocation.
- Telecommunications:Infrastructure project cost control and vendor quote normalization.
Automotive OEMs command the deepest installed base. Aerospace is gaining share fastest as material volatility accelerates platform procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Product cost management platforms trace their industrial lineage to Germany's automotive supply chains, where Siemens and SAP pioneered digital cost engineering integration with manufacturing execution systems during the 1990s.
Germany
Automotive OEMs in Stuttgart and Munich anchor European platform deployment as CSRD mandates force granular cost transparency from third-country suppliers. The KBA enforces supply chain documentation standards that favor integrated cost management architectures. Industrial machinery producers in Baden-Württemberg deploy Teamcenter-integrated solutions for digital thread cost validation.
United States
Aerospace manufacturers in Seattle and Wichita accelerate should-cost modeling adoption to manage titanium and composite price volatility across long-lead procurement cycles. The SEC climate disclosure rules mandate Scope 3 emissions reporting that embeds carbon costs into financial statements. Defense contractors in Virginia integrate cost platforms with ERP environments for program cost control.
China
Consumer electronics brands in Shenzhen and Dongguan align cost management deployments with GB standards on product carbon footprinting. The MIIT promotes digital supply chain integration that rewards granular cost tracking across multi-tier supplier networks. Automotive component manufacturers in Shanghai deploy cloud-based solutions for scalable supplier collaboration.
Japan
Precision equipment manufacturers in Nagoya and Osaka respond to METI supply chain resilience certification by embedding cost engineers earlier in product development cycles. The guidance rewards procurement sophistication in government tenders. Electronics assemblers in Tokyo integrate price optimization modules for component cost forecasting.
India
Production-linked incentive beneficiaries in Pune and Chennai require granular cost tracking for compliance and margin optimization across electronics and automotive component manufacturing. The PLI scheme mandates documented cost structures for incentive eligibility. Industrial machinery producers in Gujarat adopt SaaS models to access enterprise-grade capabilities without dedicated infrastructure budgets.
Global Product Cost Management Market Competitive Landscape
The competitive structure tilts toward enterprise software incumbents with established PLM and ERP integration pathways. Consolidation pressure intensifies as mid-market manufacturers demand pre-configured connectors to SAP and Oracle environments. Three archetypes dominate: legacy enterprise suite providers, PLM-native specialists, and cloud-native challengers. Strategic moves concentrate on API ecosystem expansion and vertical solution templates for automotive and aerospace workflows.
Among enterprise suite providers, SAP SE and Oracle Corporation occupy positions anchored by S/4HANA and Fusion Cloud architectures that embed cost transparency across procurement and finance workflows. Siemens AG represents the PLM-native archetype through Teamcenter integration that dominates digital thread deployments in industrial machinery. aPriori Technologies exemplifies the specialist tier with automated design-to-cost analytics that compete directly with incumbent providers in aerospace material sourcing environments.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Siemens AG |
| Dassault Systèmes |
| IBM Corporation |
| PTC Inc. |
| Autodesk Inc. |
| aPriori Technologies |
| Coupa Software Inc. |
| Others |
Supply & Pricing Matrix
Parametric modeling specialists concentrated in Germany's Baden-Württemberg engineering cluster anchor labor-cost differentials that widen pricing-tier spreads between enterprise PLM-integrated suites and standalone SaaS offerings. Cost engineers command premium compensation in Stuttgart and Munich, forcing vendors to stratify subscription tiers by implementation complexity and support depth.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the product cost management landscape, with differentiation driven by CAD integration depth and CSRD compliance certification tier. Premium tiers bundle Teamcenter or S/4HANA native connectors, while economy offerings target mid-market manufacturers with browser-based estimation modules. Pricing pressure stems from cloud infrastructure maturation compressing deployment margins. Mid-market electronics manufacturers in South Korea exhibit highest price sensitivity, whereas aerospace OEMs in France prioritize integration reliability over cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by EU CSRD audit-readiness standards compel platform vendors to maintain redundant cloud infrastructure across Germany and Ireland. Software development draws from engineering talent pools in India and Poland, while customer success operations rest on technical specialists in Japan and the United States. Single-source vulnerability concentrates in generative AI training data pipelines anchored to North American hyperscalers. Distribution runs through direct enterprise sales teams supplemented by SAP and Oracle channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Product cost management platforms function as a geographic-arbitrage play, with EU CSRD compliance costs in Germany running substantially higher than equivalent implementation burdens in India's PLI scheme environment.
For Market Incumbents: Cement dominance in aerospace digital thread deployments by deepening Teamcenter integration partnerships and acquiring specialist parametric modeling boutiques. Cloud-native challengers with automated should-cost algorithms threaten incumbent margin pools. Prioritize backward integration into CAD kernel licensing to lock out specialist competitors. For New Entrants and Emerging Players: Tier-2 automotive suppliers in India's PLI scheme represent the most penetrable buyer archetype, with documented cost structures mandated for incentive eligibility but limited legacy PLM baggage. Target SaaS-native deployments with pre-configured GB standards compliance for carbon footprinting. Lead with procurement-team workflows rather than engineering-centric design-to-cost positioning. For Investors and Strategic Acquirers: Enterprise software conglomerates pursuing supply chain resilience portfolios are the most active acquirer in this space, with SAP and Oracle seeking specialist design-to-cost capabilities to fill S/4HANA and Fusion Cloud gaps. Long-term viability hinges on AI-driven predictive costing module differentiation. Watch for CSRD enforcement intensity in Germany as the inflection signal for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native S/4HANA connectors satisfy KBA supply chain documentation standards for German automotive OEMs. |
| Acquisition of Specialist Firm | Parametric modeling boutiques in Stuttgart deliver immediate CSRD-compliant cost transparency capabilities. |
| Geographic Expansion | Pune and Chennai deployment centers capture PLI scheme compliance demand from electronics manufacturers. |
| Product Launch | AI-driven should-cost modules compress estimation cycles from weeks to hours for aerospace tier-1 suppliers. |
| Strategic Partnership | Hyperscaler alliances secure redundant cloud infrastructure for EU CSRD dual-sourcing audit requirements. |
Research Methodology
Bottom-up manufacturing application modeling reconciled against top-down cloud deployment tracking forms the analytical core of this study. Primary interviews with cost engineering directors, procurement VPs at automotive OEMs, PLM integration specialists, and SaaS vendor product managers combined with secondary validation from SEC climate disclosure filings, EU CSRD implementation guidance documents, and METI supply chain resilience certification standards. Trade data from Germany's KBA and India's DGFT provided cross-border platform adoption benchmarks.
Historical trendline analysis across solution type, deployment mode, and end-user industry dimensions established baseline growth patterns over the analysis window. Segmentation modeling incorporated cost estimation versus spend analysis splits, cloud versus on-premises deployment preferences, and aerospace versus automotive versus electronics vertical adoption curves. CAGRs derived from regression analysis against industrial production indices and regulatory implementation timelines.
Underlying measurement precision varies by segment; cloud-based SaaS deployments carry tighter precision than legacy on-premises installations given transparent subscription reporting. Forecasts reflect assumptions regarding CSRD enforcement consistency and titanium price volatility stabilization. Deviation in EU Green Deal carbon-embedded pricing mandate timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Cash Logistics Market
Financial Services
Global Financial Consulting Software Market
Financial Services
Hong Kong Trade Finance Market
Financial Services
Global Power Bank Rental Service Market
Financial Services
North America Financial Advisory Services Market
Financial Services
Financial Services Application Market
Financial Services
United States Credit Agency Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Financial Advisory Services Market
Financial Services
China Trade Finance Market
Financial Services
Virtual Account Management Software Market
Financial Services
Australia Online Gambling Market
Financial Services
Asia-Pacific Factoring Services Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
China Supply Chain Financing Market
Financial Services
Mobile Notary Service Market