
 Netted Fabrics Market | 2026-2036
Netted Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Netted Fabrics Market Outlook
REACH is expanding the cost-of-entry calculus for European netted fabric suppliers, forcing reformulation of polyester and nylon mesh chemistries to meet SVHC thresholds. Jason Mills leverages deep vertical integration in U.S. technical knitting to sustain margin control against compliance-driven raw material inflation. Fiberflon anchors its position through fluoropolymer-coated mesh specialization that navigates stringent chemical safety protocols. Stannek Netting competes via precision raschel manufacturing scale serving industrial filtration and agricultural shading segments.
Netted fabrics are open-structured textile constructions engineered with interlooped yarns forming geometric apertures, typically manufactured through warp knitting, weft knitting, or weaving processes with mesh counts ranging from 2 to 100 openings per inch; they function primarily as permeable barriers enabling air circulation, liquid filtration, or load distribution across industrial and consumer applications. Knitted nets dominate volume throughput due to production velocity on multi-bar raschel machines, while composite fabrics command premium positioning where bonded multilayer constructions address ballistic or medical barrier requirements. Woven nets retain structural primacy in heavy-load agricultural and construction netting where dimensional stability under tension determines performance.
FDA material biocompatibility standards and EPA chemical emissions frameworks in the United States, alongside REACH and the EU Green Deal chemical sustainability mandates in Europe, collectively reshape formulation roadmaps and supplier qualification protocols for synthetic mesh producers. China's GB standards and MEE environmental enforcement add compliance layers for export-oriented manufacturers operating within its technical textile clusters. Stakeholders must monitor evolving PFAS restrictions and polymer recycling mandates, as these regulatory vectors will determine which material platforms and geographic supply bases retain market access.
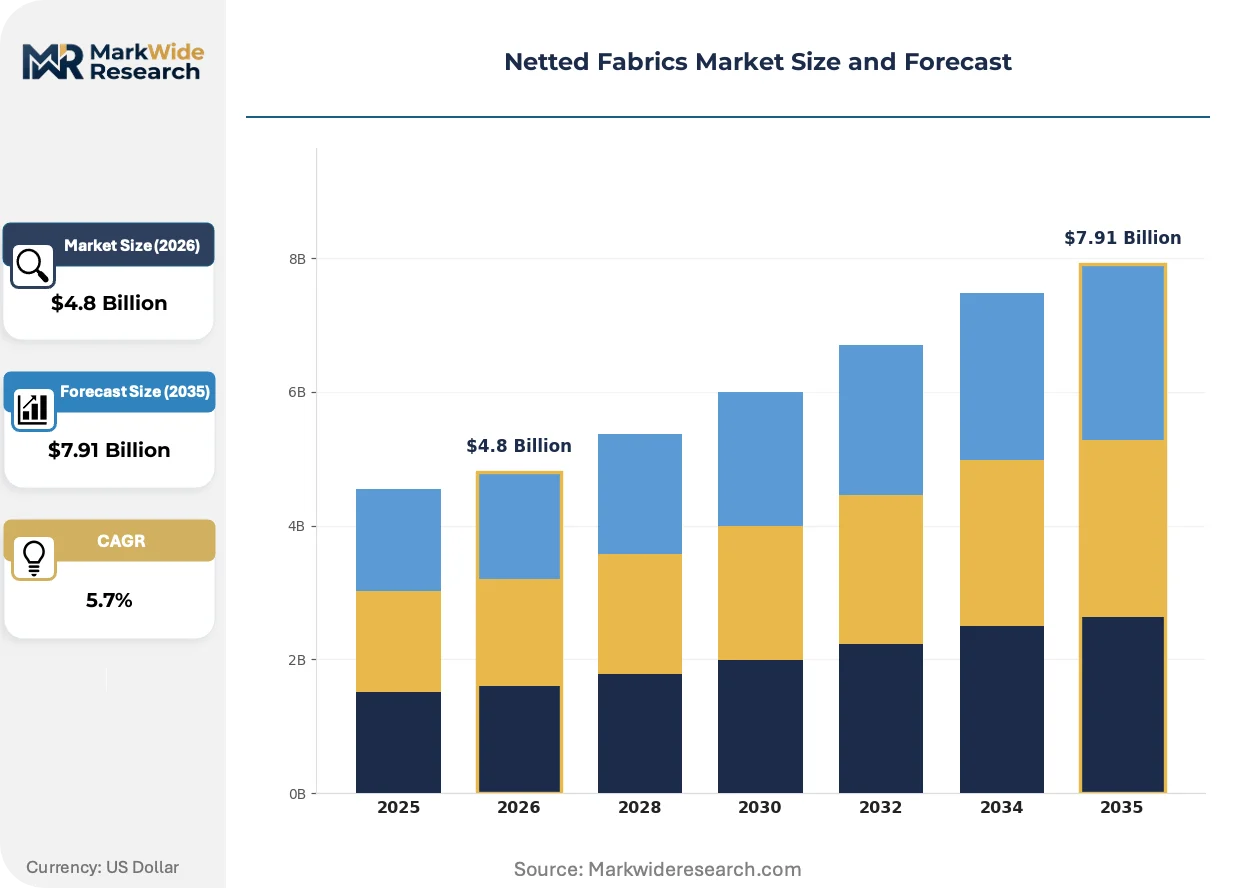
Market Dynamics
REACH compliance in Europe is forcing synthetic mesh producers to reformulate polyester and nylon chemistries, elevating raw material costs while technical textile clusters in China scale raschel capacity for export markets.
Growth Catalysts
- Technical textile cluster expansion:Chinese manufacturers in Zhejiang and Jiangsu provinces are scaling warp-knitting and raschel production lines to capture export demand for industrial filtration and agricultural shading applications.
- REACH SVHC thresholds:ECHA's expanding substance restrictions are accelerating certified material adoption among European sports gear manufacturers seeking compliant breathable performance apparel inputs.
- Fluoropolymer mesh specialization:Chemical safety protocol navigation through coated fiber platforms is opening premium positioning in medical barrier and industrial chemical processing segments.
Market Restraints
- Petrochemical feedstock volatility:Crude oil price fluctuations directly compress margins for polyester and nylon mesh producers lacking backward integration into polymer production.
- Single-region supply concentration:Technical knitting capacity clustering in eastern China creates vulnerability to MEE environmental enforcement actions and regional logistics disruptions.
- Natural fiber substitution:Jute and hemp netting alternatives are gaining traction in agricultural shading applications where biodegradability outweighs synthetic durability requirements.
Strategic Opportunities
- EU Green Deal chemical sustainability mandates:Circular economy requirements for polymer recycling are creating first-mover advantage for producers investing in chemically recyclable mesh platforms.
- Medical barrier convergence:FDA biocompatibility standards and composite fabric bonding technologies are converging to enable premium multilayer constructions for surgical and isolation applications.
- Direct-to-manufacturer digital channels:Technical textile procurement platforms are disintermediating traditional distributor networks for mid-volume industrial buyers in North American filtration markets.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and GB standard compliance creates 18-24 month product qualification cycles that freeze formulation iteration.
- Legacy raschel equipment integration:Smart factory sensor deployment on 1990s-era multi-bar machines requires custom mechanical retrofitting that strains maintenance engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netted Fabrics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knitted Nets, Woven Nets, Composite Fabrics, Raschel Fabrics Application: Home Textiles, Industrial Textiles, Sports Gear, Medical Textiles Material: Polyester, Nylon, Cotton, Polypropylene End User: Fashion Industry, Automotive Sector, Agriculture, Construction |
| Companies Covered | Jason Mills, Fiberflon, Stannek Netting, Snyder Manufacturing, Ultraflexx, Birdair, Taconic, Seattle Fabrics, Guilford Performance Textiles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netted Fabrics Market Strategic Shifts
Material science advances and regulatory chemistry constraints are actively restructuring competitive positioning across synthetic mesh platforms, with production technology and compliance capability emerging as the primary differentiation vectors.
Recycled PET engineered mesh is overtaking virgin polyester in sports apparel applications as Nike and Adidas tier-one suppliers mandate post-consumer content thresholds. European athletic wear contractors are accelerating adoption to meet CSRD supply chain disclosure requirements. This material transition is compressing pricing power for conventional polymer mesh producers without certified recycling infrastructure.
EU F-Gas Regulation phase-down schedules are forcing fluoropolymer-coated mesh producers to transition toward PFAS-free barrier chemistries by 2030. Industrial filtration manufacturers in Germany and France face reformulation deadlines that threaten existing product qualification status. Medical device netting segments are responding fastest, with Swissmedic-registered suppliers already piloting silicone-based alternatives.
Certification-driven procurement is consolidating buyer preference around dual-registered suppliers holding both FDA device master files and REACH-compliant material safety documentation. North American industrial distributors are trimming vendor rosters to reduce qualification overhead. This concentration is most visible in ballistic and aerospace netting segments where NHTSA and FAA material traceability requirements overlap.
Netted Fabrics Market Segmentation
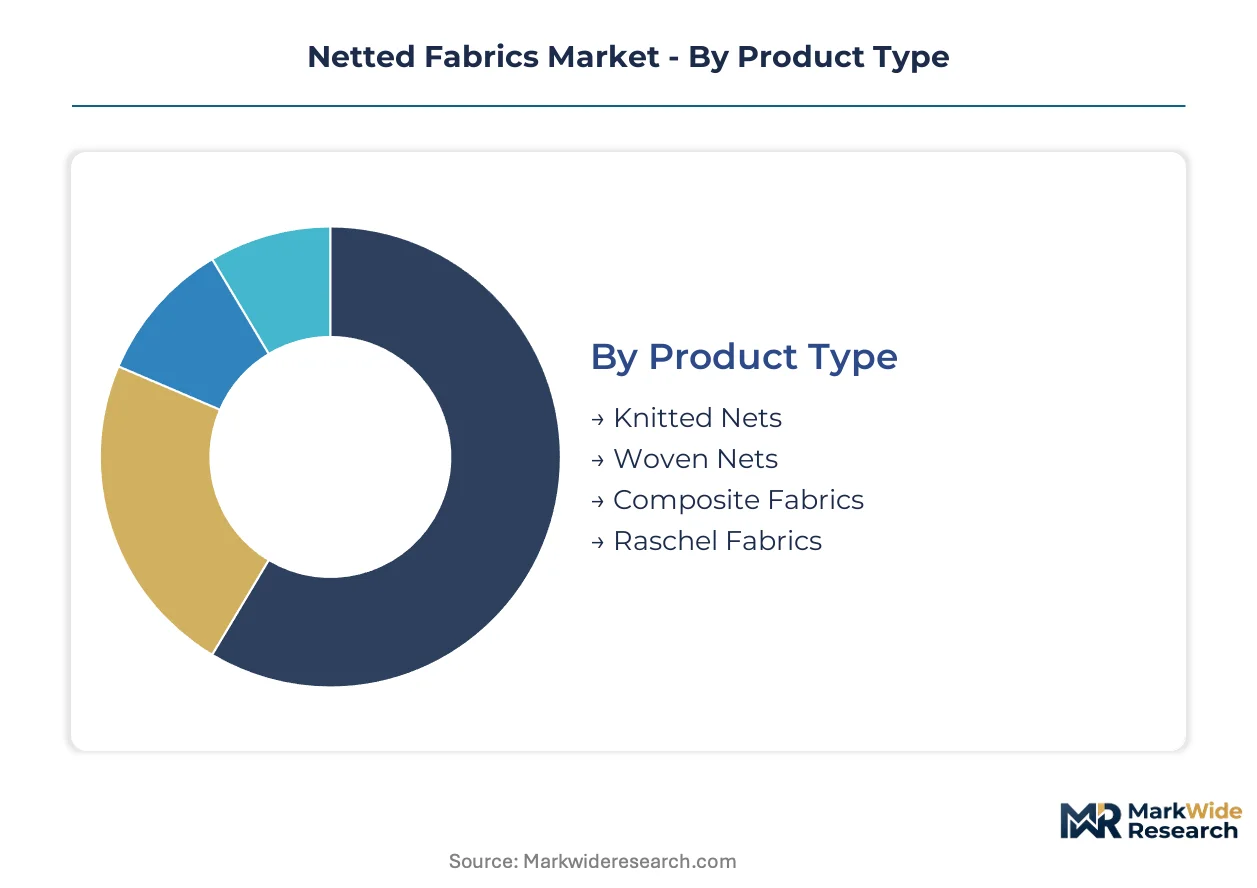
Netted fabrics serve radically different performance requirements across breathable athletic wear, load-bearing construction barriers, and sterile medical environments. Segmentation reveals how manufacturing process, material chemistry, and end-use certification requirements split the competitive landscape into distinct margin tiers and qualification barriers.
Product Type:
Buyers select manufacturing process based on required aperture precision, production velocity, and structural load tolerance.
- Knitted Nets:Interlooped yarn constructions produced on multi-bar raschel machines deliver the highest throughput velocity for sports apparel and filtration media. Demand concentrates in Zhejiang province technical textile clusters serving Nike and Adidas tier-one suppliers requiring REACH-compliant breathable mesh for performance wear.
- Raschel Fabrics:Warp-knitted constructions with controlled geometric apertures dominate agricultural shading and industrial filtration where dimensional consistency determines performance. Chinese manufacturers in Jiangsu province are scaling dedicated raschel lines to capture export orders from European agricultural equipment distributors.
- Woven Nets:Interlaced perpendicular yarns provide structural stability under tension for construction safety netting and heavy-load applications.
- Composite Fabrics:Bonded multilayer constructions address ballistic protection and medical barrier requirements where single-layer permeability is insufficient.
Knitted nets lead on scale; raschel fabrics lead on momentum in technical textile export markets.
Application:
Certification requirements and performance specifications fragment demand across consumer, industrial, and regulated medical segments.
- Industrial Textiles:Filtration media, conveyor belting, and chemical processing screens require fluoropolymer-coated or high-tenacity polyester mesh meeting EPA emissions and OSHA safety standards. German and French filtration equipment manufacturers drive specification tightening through EU F-Gas Regulation compliance deadlines.
- Sports Gear:Breathable performance apparel for running, cycling, and team sports demands lightweight mesh with moisture-wicking surface treatments. Recycled PET engineered mesh is displacing virgin polyester as Nike and Adidas mandate post-consumer content thresholds from contract manufacturers.
- Medical Textiles:Surgical meshes, isolation barriers, and implantable netting require FDA device master files and biocompatibility testing under ISO 10993 protocols.
- Home Textiles:Decorative and functional netting for curtains, mosquito screens, and furniture upholstery prioritizes cost efficiency over performance certification.
Industrial textiles command premium pricing through compliance barriers; sports gear represents the steepest expansion trajectory as recycled material mandates accelerate.
Material:
Polymer feedstock selection determines chemical resistance, tensile strength, and regulatory compliance pathway.
- Polyester:Dominant synthetic platform for sports apparel and industrial filtration due to dimensional stability and dye affinity. Virgin PET faces margin compression as recycled PET engineered mesh gains certification for CSRD supply chain disclosure compliance in European athletic wear.
- Nylon:Superior abrasion resistance and elasticity serve automotive airbag containment, cargo netting, and high-wear industrial applications. ECHA SVHC threshold expansions are forcing reformulation of traditional nylon 6,6 chemistries for REACH-compliant European market access.
- Polypropylene:Lightweight hydrophobic fiber dominates agricultural shading and marine applications where UV degradation resistance outweighs tensile strength requirements.
- Cotton:Natural fiber retains niche positioning in decorative home textiles and medical applications where biodegradability or skin contact sensitivity matters.
Polyester holds volume leadership; nylon faces the most urgent reformulation pressure from European chemical safety mandates.
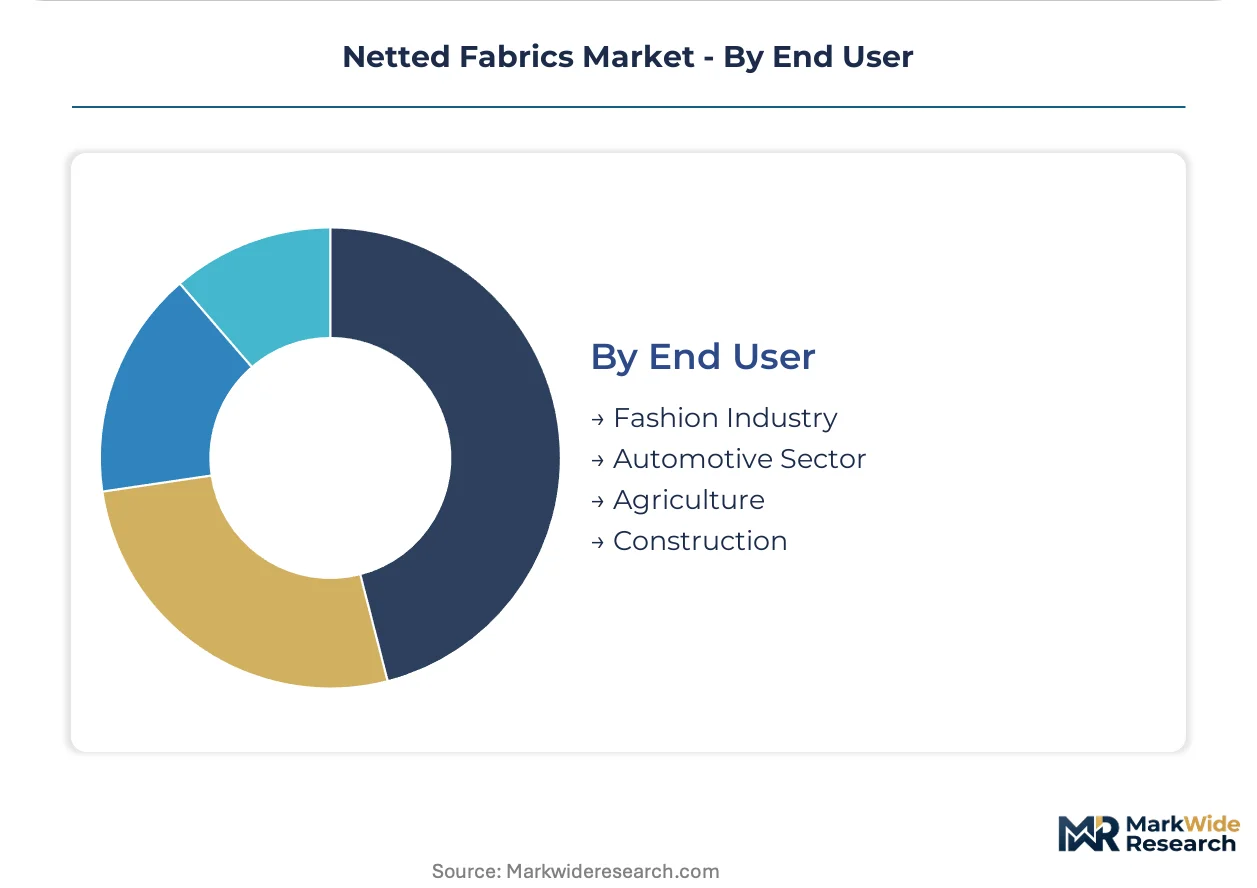
End User:
Procurement sophistication and qualification overhead separate commodity buyers from specification-driven industrial purchasers.
- Agriculture:Crop protection netting, greenhouse shading, and livestock containment drive demand for UV-stabilized polypropylene and raschel polyester with calibrated light transmission. Chinese manufacturers in Shandong province target Brazilian and Southeast Asian export markets where climate adaptation requirements differ from European specifications.
- Automotive Sector:Airbag deployment meshes, seat suspension systems, and cargo containment require NHTSA material traceability and flame resistance certification. Tier-one suppliers in Michigan and South Carolina consolidate vendor rosters around dual-registered producers holding both FDA device files and automotive PPAP documentation.
- Construction:Safety netting, debris containment, and scaffolding enclosures prioritize tensile strength and weather resistance over chemical compliance complexity.
- Fashion Industry:Designer apparel and accessory applications favor aesthetic customization and small-batch flexibility over technical performance metrics.
Agriculture leads on unit volume throughput; automotive commands the highest qualification barriers and longest contract cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical knitting expertise concentrates in eastern China's Zhejiang and Jiangsu provinces, where multi-bar raschel machine operators supply Nike and Adidas contract manufacturers with REACH-certified breathable mesh.
United States
Sports gear manufacturers in North Carolina and South Carolina drive demand for FDA-compliant surgical meshes and NHTSA-traceable automotive airbag containment fabrics. EPA chemical emissions frameworks govern polyester and nylon formulation for industrial filtration applications. Michigan-based tier-one automotive suppliers consolidate vendor rosters around dual-registered producers holding both FDA device master files and automotive PPAP documentation.
Germany
Industrial filtration equipment manufacturers in Bavaria and North Rhine-Westphalia specify fluoropolymer-coated mesh for chemical processing screens. EU F-Gas Regulation phase-down schedules force reformulation of barrier chemistries by 2030. Stuttgart-area automotive suppliers demand REACH-compliant material safety documentation for seat suspension and cargo containment systems.
China
Domestic technical textile clusters in Zhejiang province scale raschel and warp-knitting capacity for export markets serving European agricultural equipment distributors. MEE environmental enforcement actions create supply vulnerability for single-region concentration. Jiangsu province manufacturers invest in dedicated raschel lines targeting Brazilian and Southeast Asian crop protection netting demand.
France
Luxury fashion houses in Paris and Lyon commission small-batch decorative netting for designer apparel and accessories. ECHA SVHC threshold expansions elevate certification requirements for synthetic mesh imports. Auvergne-Rhône-Alpes technical textile specialists pilot silicone-based PFAS-free alternatives for medical barrier applications ahead of Swissmedic-registered supplier timelines.
India
Domestic apparel manufacturers in Tamil Nadu and Gujarat adopt recycled PET engineered mesh to meet CSRD-aligned supply chain disclosure requirements from European athletic wear contractors. BIS standards govern UV-stabilized polypropylene for agricultural shading exports. Maharashtra-based technical knitting operations target Middle Eastern construction safety netting markets.
Netted Fabrics Market Competitive Environment
The competitive structure tilts toward vertically integrated specialists with captive polymer supply and certified recycling infrastructure. Mid-scale regional fabricators compete on raschel production velocity for agricultural and filtration segments. Three archetypes dominate: compliance-forward European specialists navigating REACH reformulation, scale-driven Chinese export manufacturers, and U.S.-based technical knitters with backward integration into yarn production. Capacity expansion and portfolio diversification toward medical barrier composites represent the dominant competitive moves.
Among U.S.-based technical knitters, Jason Mills exemplifies the vertically integrated archetype with in-house polymer production capabilities. Fiberflon occupies a position within the fluoropolymer-coated mesh specialization tier, while Stannek Netting represents precision raschel manufacturing scale serving industrial filtration and agricultural shading demand. These three anchors illustrate how geographic regulatory exposure and production technology choices stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Jason Mills |
| Fiberflon |
| Stannek Netting |
| Snyder Manufacturing |
| Ultraflexx |
| Birdair |
| Taconic |
| Seattle Fabrics |
| Guilford Performance Textiles |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal chemical sustainability mandates gate qualified supply and premium-tier pricing access for netted fabric producers, as REACH-compliant certification becomes a non-negotiable entry ticket for European sports apparel and medical barrier contracts. Buyers without verified recycling infrastructure or SVHC-compliant material documentation face automatic disqualification from tier-one supplier rosters, compressing pricing power into the hands of dual-registered specialists.
Pricing Analysis
Certification-bundled versus unbundled raw material supply splits pricing structures across the netted fabrics market. Three-tier pricing stratifies across REACH-certified premium mesh, standard industrial-grade polyester, and economy agricultural netting without environmental documentation. Price differentiation hinges on ECHA SVHC compliance status and post-consumer recycled content thresholds demanded by Nike and Adidas contractors. Cost compression in virgin polyester mesh is intensifying because recycled PET engineered alternatives gain CSRD-aligned supply chain disclosure preference. Agricultural distributors in Brazil and Southeast Asia exhibit highest price sensitivity, while medical device manufacturers absorb premium pricing for FDA device master file documentation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Nike and Adidas tier-one suppliers, while distributor networks serve fragmented agricultural and construction segments. Supply concentrates in China's Zhejiang and Jiangsu provinces, with secondary capacity emerging in Tamil Nadu and Gujarat for recycled PET processing. Raw material flows draw from petrochemical feedstocks, fluoropolymer coating chemistries, and post-consumer PET flake streams. Single-region concentration in eastern China creates vulnerability to MEE environmental enforcement actions and regional logistics disruptions. Distribution runs through technical textile procurement platforms that disintermediate traditional networks for mid-volume North American industrial filtration buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The netted fabrics market functions as a stable compounder, with regulatory compliance mandates creating durable pricing power for certified producers across multiple industrial cycles.
For Market Incumbents: Lock in backward integration into polymer production to sustain margin control against petrochemical feedstock volatility and REACH-driven raw material inflation. Expand raschel capacity in Jiangsu province to capture Brazilian and Southeast Asian agricultural export demand before regional competitors scale. Certification investment in simultaneous FDA and REACH registration creates 18-24 month qualification barriers that freeze out formulation laggards. For New Entrants and Emerging Players: Capture white-space in silicone-based PFAS-free medical barrier mesh ahead of EU F-Gas Regulation phase-down deadlines. Target Auvergne-Rhône-Alpes technical textile specialists and Swissmedic-registered suppliers as early pilot customers for fluoropolymer alternatives. Go-to-market leverage rests on positioning as the first mover in PFAS-free barrier chemistries for surgical and isolation applications. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale raschel fabricators with REACH-compliant infrastructure and established European agricultural distributor relationships because certification-driven procurement is consolidating buyer preference around dual-registered suppliers. The 5-10 year viability window favors producers with captive recycling infrastructure and medical barrier composite capabilities. Watch for PFAS restriction acceleration as the inflection indicator that triggers rapid portfolio repositioning toward silicone and bio-based alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Investment | ECHA SVHC threshold navigation secures European sports apparel and medical barrier contract access. |
| Recycled PET Infrastructure Buildout | Post-consumer content certification satisfies CSRD-aligned supply chain disclosure requirements from Nike and Adidas contractors. |
| PFAS-Free Chemistry Transition | Silicone-based barrier development addresses EU F-Gas Regulation phase-down deadlines ahead of Swissmedic-registered competitors. |
| Raschel Capacity Expansion | Dedicated warp-knitting lines in Jiangsu province capture Brazilian and Southeast Asian agricultural shading export demand. |
| Dual-Registration Certification | Simultaneous FDA device master files and REACH-compliant documentation qualify producers for Michigan automotive tier-one supplier consolidation. |
Study Parameters
Multiple input streams — technical textile plant managers, Nike and Adidas procurement leads, ECHA regulatory affairs specialists, and agricultural equipment distributors — were reconciled against secondary validation from customs/trade data, SEC filings of listed synthetic fiber producers, and ECHA SVHC candidate list updates. Primary fieldwork encompassed interviews with raschel machine operators in Zhejiang province, FDA regulatory consultants, and GPO contracts managers at North American hospital systems. Bottom-up segment sizing across knitted nets, raschel fabrics, woven nets, and composite fabrics was cross-checked against top-down petrochemical feedstock demand models.
Historical shipment trajectories were cross-referenced against panel input from technical knitting equipment manufacturers and polymer suppliers to establish baseline elasticity assumptions across the projection horizon. Segmentation dimensions modeled include manufacturing process, material chemistry platform, end-use certification tier, and regional production hub cluster. CAGRs were derived through iterative convergence of demand-side adoption curves and supply-side capacity expansion schedules. Industry-specific forecast inputs incorporated REACH SVHC list revision timelines and recycled PET engineered mesh certification velocity.
Underlying measurement precision varies by segment; medical barrier and automotive airbag containment categories carry tighter precision than decorative home textiles due to stricter documentation requirements. Forecasts reflect assumptions about ECHA enforcement intensity, MEE environmental action frequency, and PFAS restriction acceleration that could shift materially with regulatory announcements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
Textile Printer Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Saddle Stitching Machine Market
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
Industrial Laundry Market
Textile Machinery and Equipment
United States Fabric Shavers Market
Textile Machinery and Equipment
Global Spinning Machinery Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Braiding Equipment Market
Textile Machinery and Equipment
Global Textile Machinery Market
Textile Machinery and Equipment
Heel Tampography Printing Machine Market
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Braiding Machine Market