
 Braiding Equipment Market | 2026-2036
Braiding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Braiding Equipment Market Intelligence
Multi-source procurement for high-performance carriers and servo drives is realigning how tier-one cable and hose builders secure braiding capacity. Mayer & Cie. GmbH & Co. KG leverages its German engineering base to dominate circular and radial braiding platforms for automotive hose producers. HERZOG GmbH anchors the medical textile segment with cleanroom-compatible machines that sustain ISO 13485 compliance. Jiangsu Nantong Huayi Braiding Machine Co., Ltd. competes on cost-adjusted throughput for Asian protective sleeving markets.
Braiding equipment encompasses mechanical systems that interlace three or more strands of wire, yarn, or composite tow into tubular or flat structures, typically operating at spindle speeds between 100 and 1,200 rpm depending on carrier count and material fineness. These machines produce reinforcement layers for hydraulic hoses, signal shields for telecommunication cables, and structural preforms for aerospace components. Automatic braiders command the value pool due to labor-cost arbitrage and repeatability requirements in medical suture and aerospace applications. Track braiding technology leads growth in carbon-fiber preform manufacturing where programmable tension control enables complex near-net-shape geometries. Horn gear braiding remains mature in low-mix, high-volume hose and cable segments where mechanical simplicity sustains uptime metrics.
FDA device-quality regulations and ISO 13485 standards compel surgical equipment makers to validate braiding process parameters for dimensional tolerance and biocompatibility. The EU Green Deal and REACH chemical restrictions are pressuring European hose producers to phase out solvent-based lubricants in braiding operations, redirecting R&D toward water-based carrier coatings. Stakeholders must monitor how FAA airworthiness directives and EASA certification updates for composite primary structures reshape qualification protocols for aerospace braiding suppliers.
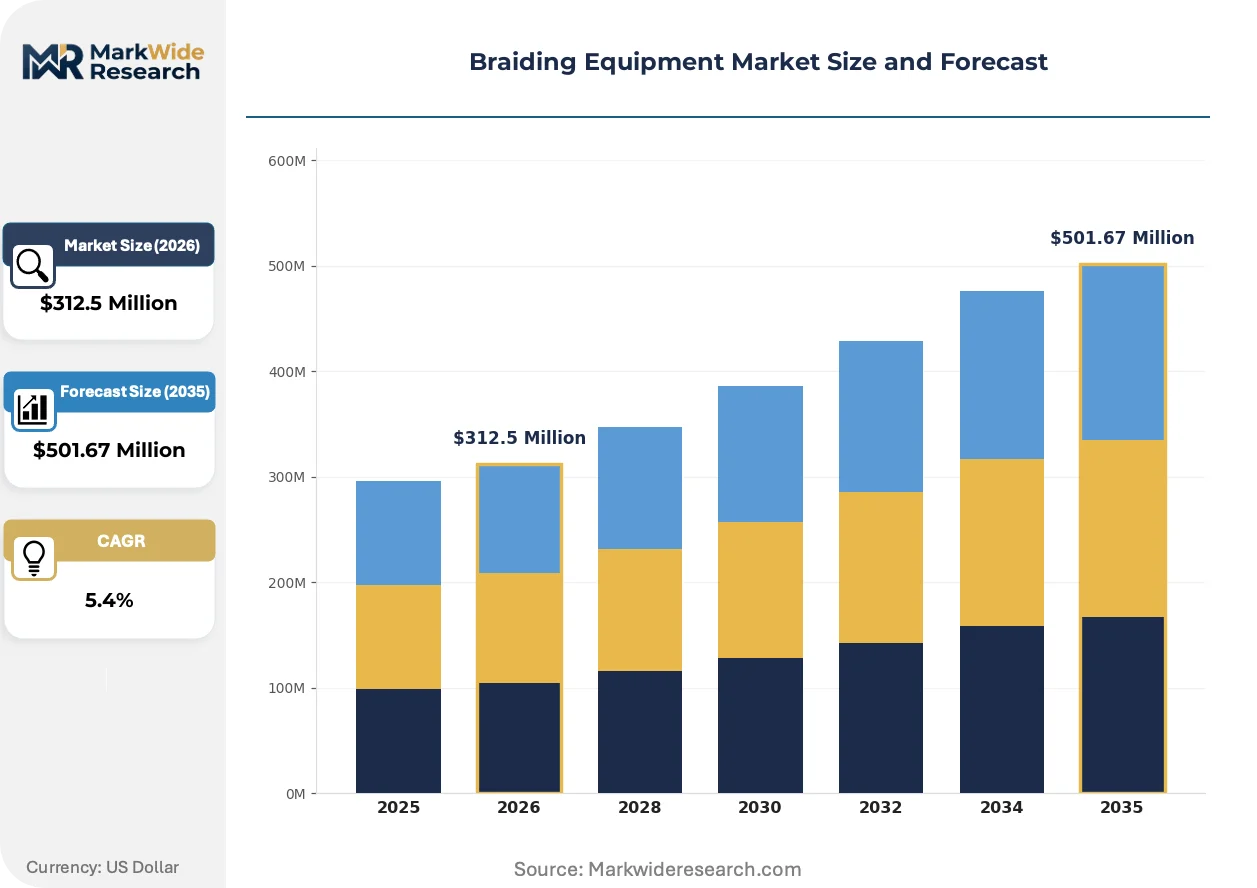
Market Dynamics
Automated braiding lines with programmable tension control are compressing lead times for carbon-fiber aerospace preforms while medical suture manufacturers absorb FDA validation costs to lock in multi-year supply contracts.
Growth Catalysts
- ISO 13485 Certification Mandates:Surgical equipment manufacturers in Germany and Switzerland are expanding cleanroom-compatible braiding capacity to meet device-quality standards for cardiovascular and orthopedic sutures.
- Carbon-Fiber Tow Compatibility:Advances in track braiding technology enable near-net-shape preform geometries that reduce scrap rates for primary aerospace structures governed by FAA airworthiness directives.
- REACH Chemical Restrictions:EU Green Deal pressure on solvent-based lubricants is redirecting R&D investment toward water-based carrier coatings that maintain braid integrity without environmental penalties.
Market Restraints
- High-Performance Servo Drive Concentration:Sourcing dependency on Japanese and German motion-control suppliers creates vulnerability when lead times for precision spindles extend beyond 26 weeks.
- Biocompatibility Validation Costs:FDA 510(k) pathway requirements for braided medical devices impose six-figure qualification expenses that deter mid-tier equipment entrants.
- Steel Carrier Price Volatility:Cold-rolled steel input costs for horn gear braiding machines fluctuate with energy-intensive European smelter output, compressing margins on standard hose equipment.
Strategic Opportunities
- Indian Protective Sleeving Demand:Infrastructure buildout for renewable energy cabling in Gujarat and Maharashtra is creating import substitution potential for cost-adjusted braiding platforms.
- Outcome-Based Maintenance Contracts:Brazilian offshore oil producers are unbundling equipment purchases from uptime-guaranteed service agreements that lock in decade-long aftermarket revenue streams.
- Dual Carbon Goals in China:NMPA alignment with carbon-neutral manufacturing standards is accelerating domestic procurement of energy-efficient braiders with regenerative drive systems.
Industry Challenges
- Multi-Axis Programming Talent Scarcity:Track braiding machine operation requires specialized CAM software skills that outpace vocational training output in Midwestern US manufacturing hubs.
- Legacy System Integration Friction:Retrofitting servo-controlled tension systems onto mechanical horn gear frames demands custom mechanical engineering that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Braiding Equipment Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Braiders, Semi-Automatic Braiders, Manual Braiders, High-Speed Braiders, Programmable Braiding Machines Technology: Ring Braiding, Horn Gear Braiding, Maypole Braiding, Track Braiding, Circular Braiding Application: Telecommunication Cables, Hydraulic Hoses, Medical Sutures, Protective Sleeving, Aerospace Components End User: Cable Manufacturers, Hose Producers, Surgical Equipment Makers, Protective Gear Fabricators, Aviation Parts Suppliers |
| Companies Covered | The Steeger USA, KOKUBUN Ltd., Mayer & Cie. GmbH & Co. KG, Jiangsu Nantong Huayi Braiding Machine Co., Ltd., Murata Machinery, Ltd., HERZOG GmbH, Cobra Braiding Machinery Ltd., A&P Technology, Wardwell Braiding Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Braiding Equipment Market Strategic Shifts & Innovations
Digital thread integration and predictive maintenance algorithms are redefining how braiding equipment suppliers capture lifetime value from aerospace and medical textile customers.
Servo-electric tension control systems is overtaking pneumatic and mechanical alternatives in carbon-fiber preform manufacturing. Aerospace tier-one suppliers in Germany and Japan are specifying programmable closed-loop systems that maintain tow tension within 2% variance across complex mandrel geometries. This precision is overtaking legacy mechanical dancers that require manual calibration between production runs.
EU MDR medical device regulations are tightening traceability requirements for braided implantable devices. Manufacturers must now document every process parameter from spindle speed to humidity levels for batch-level genealogy. German suture producers are responding by embedding OPC-UA data logging directly into braiding machine PLCs to automate compliance evidence generation.
Consolidated procurement by multinational cable and hose builders is compressing vendor lists and extending contract durations. Tier-one automotive suppliers in Stuttgart and Detroit are shifting from transactional equipment purchases to five-year framework agreements that bundle machines, spare parts, and remote diagnostics. This concentration is most visible in hydraulic hose segments where three buyers now account for the majority of European braiding capacity additions.
Braiding Equipment Market Segmentation
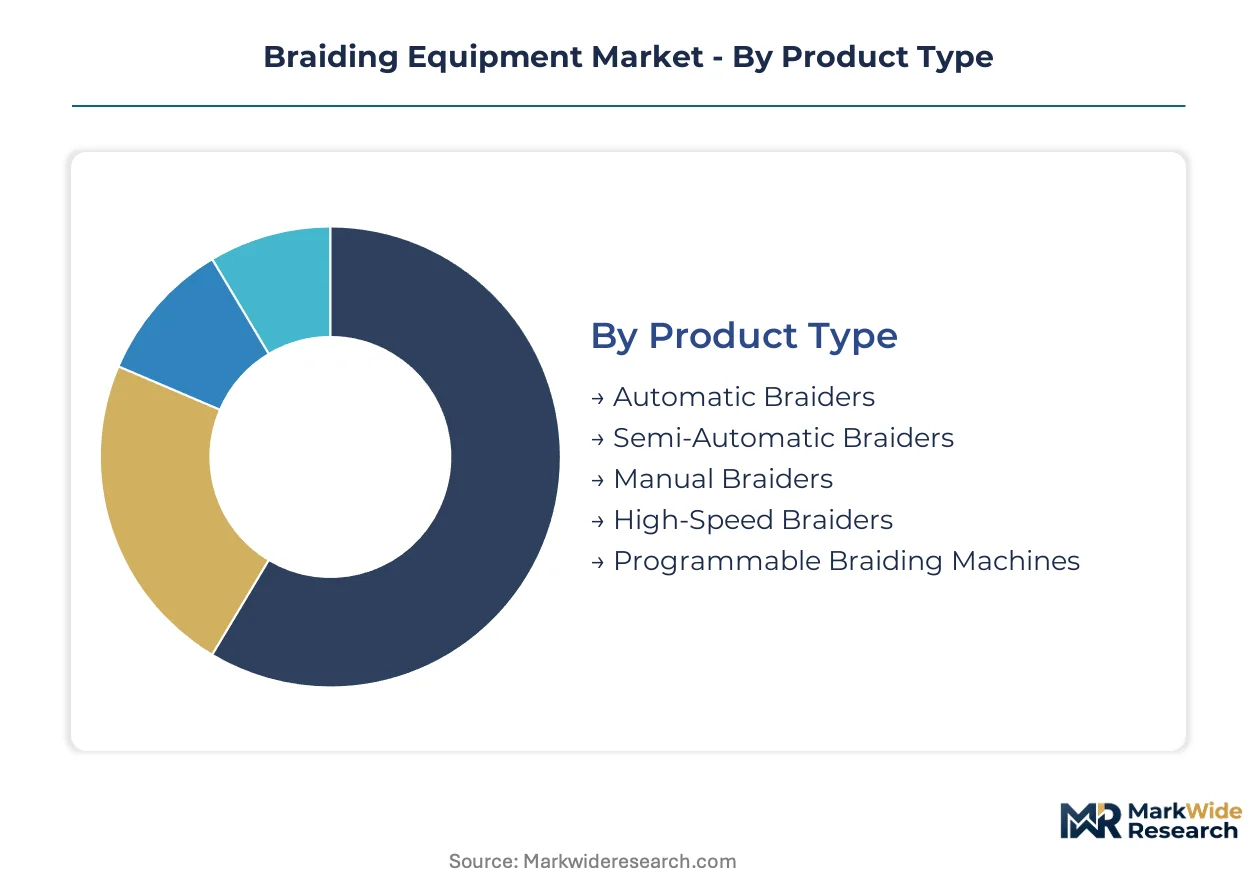
Braiding equipment procurement patterns diverge sharply across automation levels and end-use precision requirements. Manufacturers segment their offerings to match FDA validation burdens in medical textiles against throughput priorities in automotive hose production.
Product Type:
Buyers differentiate primarily by labor-cost arbitrage potential and repeatability mandates in their target end markets.
- Automatic Braiders:Closed-loop servo systems maintain dimensional tolerance within 0.1 mm for cardiovascular suture production. German surgical equipment makers absorb six-figure FDA 510(k) validation costs to lock in multi-year supply contracts with these platforms.
- Programmable Braiding Machines:Multi-axis track configurations enable near-net-shape carbon-fiber preforms for FAA-governed aerospace primary structures. Japanese tier-one suppliers specify these for complex mandrel geometries with programmable tension control.
- Semi-Automatic Braiders:Hybrid mechanical-servo architectures serve mid-volume hose producers in Stuttgart seeking uptime reliability without full automation premiums.
- High-Speed Braiders:Spindle speeds exceeding 800 rpm target telecommunication cable shielding where throughput trumps geometric complexity.
- Manual Braiders:Mechanical simplicity sustains prototype workshops and artisanal textile operations with minimal capital deployment.
Automatic braiders lead volumes today; programmable machines are gaining share fastest.
Technology:
Equipment selection tracks material stiffness and the complexity of required braid architectures.
- Track Braiding:Programmable carrier paths weave carbon-fiber tows into aerospace preforms with 3D near-net-shape capability. German and Japanese suppliers dominate this segment for FAA and EASA qualification pathways.
- Horn Gear Braiding:Mechanical simplicity using interlocking horn gears sustains 24/7 uptime in hydraulic hose factories where solvent-based lubricants face REACH phase-out pressure.
- Circular Braiding:Radial carrier arrangements produce seamless tubular structures for automotive hose reinforcement layers.
- Maypole Braiding:Traditional carrier dance patterns persist in legacy cable manufacturing with established maintenance protocols.
- Ring Braiding:Compact footprints serve protective sleeving applications where space-constrained operations predominate.
Horn gear systems anchor installed base volumes; track braiding is climbing the fastest.
Application:
End-use validation requirements and material specifications reshape equipment feature priorities.
- Medical Sutures:ISO 13485 mandates compel cleanroom-compatible machines with OPC-UA data logging for batch-level genealogy. Swiss and German manufacturers expand capacity to capture cardiovascular and orthopedic device contracts.
- Aerospace Components:FAA airworthiness directives for composite primary structures demand programmable tension control within 2% variance across complex geometries.
- Hydraulic Hoses:Automotive tier-one suppliers in Stuttgart and Detroit consolidate procurement around five-year framework agreements bundling machines and remote diagnostics.
- Telecommunication Cables:Signal shielding applications prioritize spindle speed and copper-wire compatibility over geometric complexity.
- Protective Sleeving:Infrastructure buildout for renewable energy cabling in Gujarat and Maharashtra creates import substitution opportunities for cost-adjusted platforms.
Hydraulic hoses dominate current procurement volumes; medical sutures show the steepest expansion trajectory.
End User:
Customer scale and vertical integration depth determine pricing power and contract structure preferences.
- Surgical Equipment Makers:FDA device-quality mandates and EU MDR traceability requirements drive specification of machines with embedded compliance documentation systems.
- Hose Producers:REACH chemical restrictions on solvent-based lubricants redirect R&D toward water-based carrier coatings without sacrificing braid integrity.
- Cable Manufacturers:Consolidated procurement by multinational builders compresses vendor lists and extends contract durations toward multi-year frameworks.
- Aviation Parts Suppliers:EASA certification updates for composite structures reshape qualification protocols and supplier approval timelines.
- Protective Gear Fabricators:Brazilian offshore oil producers unbundle equipment purchases from uptime-guaranteed service agreements capturing decade-long aftermarket revenue.
Hose producers represent the largest installed base; surgical equipment makers are expanding procurement most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision-engineering clusters anchor procurement patterns for aerospace and medical textile braiding equipment, with Mayer & Cie. GmbH & Co. KG and HERZOG GmbH concentrating R&D and manufacturing capacity in the country's southwestern industrial corridor.
Germany
Automotive hose producers in Stuttgart and Wolfsburg drive demand for circular braiding platforms with integrated quality assurance systems. REACH chemical restrictions on solvent-based lubricants are redirecting equipment specifications toward water-based carrier compatibility. Baden-Württemberg hosts the densest concentration of cleanroom-compatible machine builders serving ISO 13485-certified suture manufacturers.
United States
FAA airworthiness directives for composite primary structures are reshaping qualification protocols for aerospace braiding suppliers in Washington State and California. FDA 510(k) pathway requirements impose validation burdens that favor established equipment vendors with documented compliance histories. The Pacific Northwest corridor concentrates track braiding procurement for defense and commercial aviation applications.
China
NMPA alignment with carbon-neutral manufacturing standards is accelerating domestic procurement of energy-efficient braiders with regenerative drive systems. The Yangtze River Delta industrial belt hosts the fastest-growing installed base of high-speed braiders for telecommunication cable shielding. Jiangsu province anchors cost-adjusted platform manufacturing for protective sleeving export markets.
Japan
METI industrial policy supports precision motion-control component sourcing for track braiding systems serving aerospace tier-one suppliers in Nagoya and Tokyo. JIS standards compliance requirements filter equipment procurement toward vendors with documented spindle precision certification. The Chubu region concentrates carbon-fiber preform manufacturing capacity for commercial aviation programs.
India
Infrastructure buildout for renewable energy cabling in Gujarat and Maharashtra is creating import substitution potential for cost-adjusted braiding platforms. BIS certification requirements for industrial machinery are extending qualification timelines for European and Japanese equipment entrants. The Maharashtra industrial corridor hosts emerging protective sleeving fabricators serving domestic cable manufacturers.
Braiding Equipment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue modular retrofit kits and regional service partnerships as entry vectors. The vendor base stratifies across three tiers: German and Japanese precision-engineering houses with aerospace certification track records; Chinese and Indian cost-optimized fabricators capturing volume segments; and specialized medical-textile equipment builders with cleanroom expertise. Dominant competitive moves include strategic partnerships for servo drive supply security and geographic expansion through distributor networks in Southeast Asia and Latin America.
Among German precision-engineering specialists, Mayer & Cie. GmbH & Co. KG and HERZOG GmbH exemplify the medical-aerospace dual-track archetype, anchoring premium-tier positioning through regulatory compliance depth. Jiangsu Nantong Huayi Braiding Machine Co., Ltd. represents the cost-adjusted throughput archetype, occupying a position within Asian protective sleeving supply chains. Wardwell Braiding Co. and Cobra Braiding Machinery Ltd. sit within the established North American vendor tier, serving hose and cable builders with regionally anchored service networks.
| Leading Market Players |
|---|
| The Steeger USA |
| KOKUBUN Ltd. |
| Mayer & Cie. GmbH & Co. KG |
| Jiangsu Nantong Huayi Braiding Machine Co., Ltd. |
| Murata Machinery, Ltd. |
| HERZOG GmbH |
| Cobra Braiding Machinery Ltd. |
| A&P Technology |
| Wardwell Braiding Co. |
| Others |
Cost & Logistics Intelligence
Cold-rolled steel index movements cascade through braiding equipment manufacturing, compressing margins on horn gear systems while carbon-fiber tow compatibility premiums sustain pricing power in track braiding platforms. Buyers in Stuttgart and Detroit absorb input-cost volatility through multi-year framework agreements that bundle machines with remote diagnostics.
Pricing Analysis
Input-cost pass-through from Japanese and German servo drive suppliers sustains premium pricing for programmable braiding platforms serving FAA-governed aerospace applications. Pricing stratifies across ISO 13485-certified medical tiers, REACH-compliant environmental tiers, and standard hose equipment tiers based on certification depth and after-sales bundling. Cost compression in standard horn gear segments intensifies because steel carrier price volatility outpaces OEM pricing power. Protective sleeving fabricators in Gujarat demonstrate highest price sensitivity; Swiss surgical equipment makers show least sensitivity due to FDA validation lock-in effects.
Supply Chain Analysis
Dual-sourcing requirements from tier-one automotive suppliers mandate qualified supplier lists spanning German precision-engineering houses and Japanese motion-control specialists. Manufacturing concentration centers on Germany, Japan, and China for complete machines; high-performance servo drives and precision spindles draw from Japanese and German component ecosystems. Single-source vulnerability in 26-week lead-time precision spindles creates qualification bottlenecks for aerospace braiding programs. Distribution runs through OEM-direct channels for large automotive and medical accounts, regional distributor networks for mid-tier hose producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH chemical restrictions in Europe compress margins on solvent-dependent legacy equipment while NMPA carbon-neutral standards in China accelerate premium procurement of energy-efficient platforms.
For Market Incumbents: Anticipate margin compression in standard horn gear segments by accelerating backward integration into water-based carrier coating R&D and locking in five-year service contracts with Brazilian offshore oil producers. Defend aerospace tier-one relationships through FAA qualification pathway investments that extend supplier approval timelines beyond entrant reach.
For New Entrants and Emerging Players: Mid-tier protective sleeving fabricators in Maharashtra and Gujarat represent the most penetrable buyer archetype, underserved by German precision-engineering lead times and Japanese pricing premiums. Capture this white-space through cost-adjusted track braiding platforms with modular retrofit compatibility for existing mechanical frames.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized medical-textile equipment builders possessing cleanroom expertise and embedded OPC-UA compliance documentation systems. Long-term viability hinges on EU MDR traceability mandate expansion and FDA 510(k) pathway consolidation favoring documented regulatory histories. Watch NMPA procurement acceleration signals as inflection indicator for energy-efficient platform demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Supply | Mitigates 26-week lead-time vulnerability from Japanese and German motion-control concentration. |
| Water-Based Carrier Coating R&D Partnership | Aligns with REACH phase-out timelines for solvent-based lubricants in European hose production. |
| Five-Year Outcome-Based Service Contract | Locks in decade-long aftermarket revenue with Brazilian offshore oil producers. |
| OPC-UA Data Logging Platform Integration | Automates EU MDR batch-level genealogy requirements for Swiss and German suture manufacturers. |
| Maharashtra Regional Service Hub Expansion | Captures import substitution demand from Gujarat renewable energy cabling infrastructure buildout. |
Research Approach
Direct dialogue with plant engineers at automotive hose manufacturers, procurement leads at surgical equipment makers, aftermarket service heads at tier-one cable builders, and technical R&D directors at carbon-fiber preform suppliers grounded qualitative findings. Secondary validation drew from FAA airworthiness directive filings, EASA certification update registers, SEC 10-K equipment supplier disclosures, and customs trade data for braiding machine imports. Bottom-up and top-down triangulation cross-checked unit economics against aggregate market sizing.
Bottom-up modeling aggregated segment-level demand across automation tiers, technology types, and end-use applications; top-down validation pressure-tested totals against industrial machinery capex patterns. The analytical framework incorporated spindle speed specifications, carrier count configurations, and cleanroom compatibility grades as industry-specific forecast inputs. CAGRs derived from regression analysis of historical equipment procurement against composite materials adoption curves and medical device regulatory expansion timelines.
Underlying measurement precision varies by segment; medical suture and aerospace component applications carry tighter precision than standard hose equipment due to documented FDA and FAA qualification pathways. Forecasts reflect assumptions about REACH enforcement timelines, NMPA procurement acceleration, and carbon-fiber tow price trajectories. Deviation in FAA airworthiness directive scope expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Global Knitting Machinery Market
Textile Machinery and Equipment
Electric Fabric Shaver Market
Textile Machinery and Equipment
Industrial Laminating Machines Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Asia Pacific Fabric Shavers Market
Textile Machinery and Equipment
US Textile Processing Machinery Market
Textile Machinery and Equipment
Embroidery Machine Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Warping Machines Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Global Textile Machinery Market