
 Cotton Processing Equipment Market | 2026-2036
Cotton Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cotton Processing Equipment Market Insights
Multi-source procurement for precision components is consolidating around a handful of Asian and European specialists. Rieter leverages its Swiss engineering heritage to sustain premium positioning in automated cleaning lines. Bajaj Steel Industries anchors the Indian subcontinent with dense fabrication networks and aftermarket density. Trützschler Group competes through deep specialization in pneumatic transport systems for high-volume gins.
Cotton processing equipment encompasses mechanical systems designed to separate lint from seed, clean foreign matter, and compress fiber into standardized bales for downstream textile manufacturing. Modern ginning machines operate at throughput rates exceeding 15 bales per hour while maintaining fiber length preservation below 3% damage thresholds. Ginning machines dominate installed base value due to their capital intensity and replacement cycles, while optical sensor technology represents the fastest-expanding margin pool as mills pursue automated quality grading. Pneumatic handling systems now penetrate mid-scale gins previously served by mechanical conveyance, reflecting a structural shift toward labor reduction and contamination control.
FDA textile contact standards, India's BIS baling specifications, and REACH-compliant lubricant mandates in Europe collectively elevate equipment compliance costs and filter out low-tier suppliers. India's CEA electrical safety codes and China's GB machinery standards further fragment certification requirements for multinational vendors. Stakeholders must weigh regional regulatory divergence against platform standardization economics when configuring product portfolios for cross-border deployment.
Market Dynamics
Automated ginning lines are compressing labor dependence while India's BIS baling density mandates force hardware upgrades across South Asian textile clusters, creating simultaneous pull-and-push pressure on equipment procurement cycles.
Growth Catalysts
- Optical sensor grading:Textile mills in Gujarat's cotton belt deploy machine-vision systems to automate fiber quality classification, reducing manual inspection headcount while meeting export-grade specifications.
- CEA electrical safety codes:India's mandatory compliance deadlines for ginning facility electrification are accelerating replacement of legacy mechanical drive systems with synchronized motor controls.
- Pneumatic compression mandates:BIS certification requirements for standardized bale density are pushing domestic manufacturers toward pneumatic baling systems that achieve uniform compression ratios.
Market Restraints
- Steel price volatility:Fabrication costs for ginning machinery frames fluctuate with regional steel input prices, compressing margin buffers for mid-scale equipment assemblers.
- Specialized component concentration:Precision pneumatic valves and high-speed saw cylinders concentrate among a handful of European and East Asian suppliers, creating single-source vulnerability.
- Mechanical conveyance lock-in:Existing ginning facilities with sunk capital in belt-and-elevator systems face technical barriers to retrofitting pneumatic transport without full line replacement.
Strategic Opportunities
- Integrated ginning-to-spinning clusters:Greenfield textile parks in Maharashtra and Telangana offer captive demand for turnkey processing lines with unified control architecture.
- REACH-compliant lubricant convergence:European environmental mandates for biodegradable hydraulic fluids create upgrade cycles for seal and pump technologies in export-oriented gins.
- Aftermarket sensor retrofit kits:Legacy ginning lines in Bangladesh and Pakistan present attach-rate expansion for modular quality-monitoring hardware without full equipment replacement.
Industry Challenges
- Mechatronics skill scarcity:Maintenance of automated cleaning lines requires technicians proficient in both mechanical alignment and PLC diagnostics, a combination scarce in rural ginning districts.
- Multi-standard certification timelines:Vendors targeting cross-border sales must sequence India's BIS, China's GB, and EU CE marking processes, extending product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cotton Processing Equipment Market |
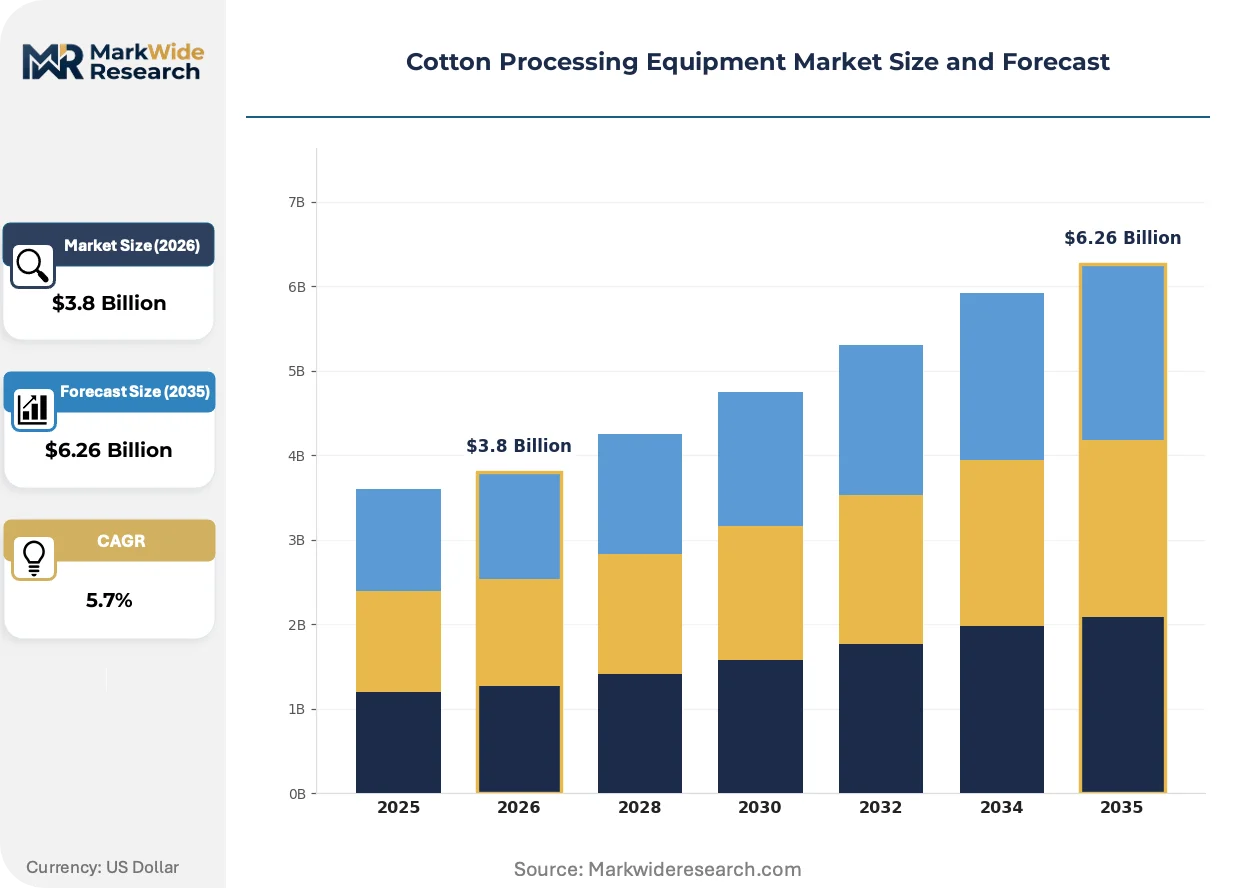
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ginning Machines, Lint Cleaners, Cotton Pickers, Cotton Compressors, Bale Presses Technology: Mechanical, Pneumatic, Automation, Optical Sensors, Hydraulic Application: Fiber Extraction, Seed Removal, Bale Formation, Quality Grading, Waste Management End User: Textile Mills, Cotton Farms, Spinning Units, Seed Oil Manufacturers |
| Companies Covered | Lummus Corporation, Bajaj Steel Industries, Rieter, Trützschler Group, Nipha Exports, Shandong Swan Cotton Industrial Machinery Stock, Cherokee Fabrication, Toyota Industries, Continental Eagle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cotton Processing Equipment Market Trends and Innovations
Digital thread-tracing and closed-loop contamination control are redefining equipment specifications as mills face downstream pressure for fiber provenance documentation.
Machine-vision lint classification is unifying quality grading with real-time process adjustment. High-volume gins in Gujarat deploy spectral cameras that map trash content and color grade simultaneously, feeding data directly to gin stand speed controllers. This convergence is compressing the traditional separation between inspection and processing stages into a single automated loop.
REACH substance restrictions are forcing lubricant formulation changes across European-installed equipment bases. Manufacturers must now qualify biodegradable hydraulic fluids that maintain viscosity under pneumatic compression heat loads. Gin operators in Germany and Italy are responding by specifying seal materials compatible with ester-based oils at equipment procurement stage.
Service contracting is fragmenting from bundled maintenance toward component-level subscription models. Independent ginning cooperatives in Maharashtra now procure saw cylinder replacement programs separate from motor-drive service agreements. This unbundling is most pronounced among mid-scale operators lacking in-house mechanical departments.
Cotton Processing Equipment Market Segmentation
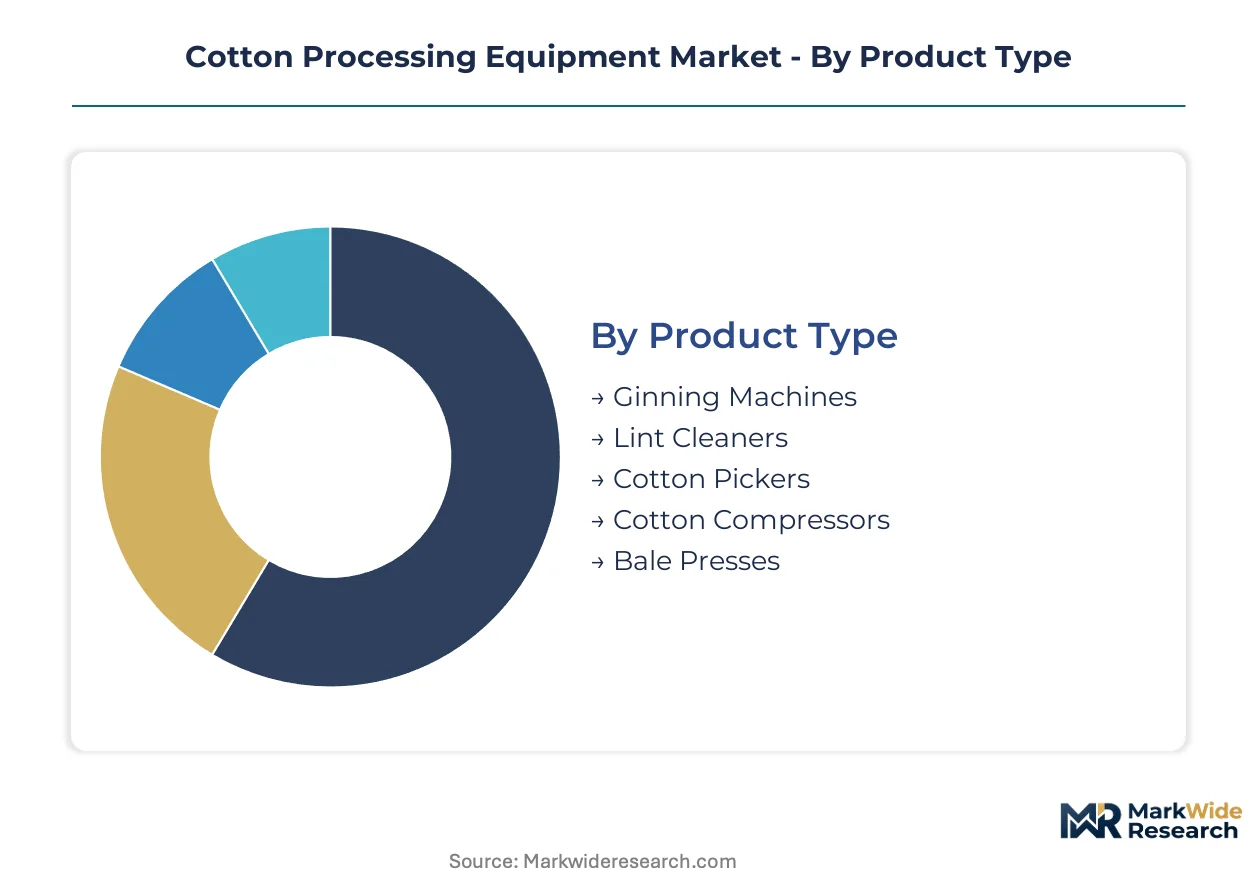
Equipment segmentation in cotton processing reveals divergent capital requirements and margin profiles across hardware categories. Procurement patterns cluster around ginning infrastructure in South Asia while sensor technology commands premium pricing in European quality-focused installations.
Product Type:
Ginning machines demand the heaviest upfront investment due to precision-engineered saw cylinders and high-torque drive systems, while downstream equipment operates at lower capital intensity with faster replacement cycles.
- Ginning Machines:Rotary-knife and saw-gin configurations separate lint from seed at throughput rates exceeding 15 bales per hour. Gujarat's integrated ginning-to-spinning clusters drive procurement volume as BIS density mandates force hardware upgrades across legacy facilities.
- Lint Cleaners:Mechanical and pneumatic trash removal systems preserve fiber length below 3% damage thresholds. Demand concentrates in export-oriented mills seeking USDA-equivalent grade certification for international yarn sales.
- Cotton Pickers:Self-propelled harvesting equipment with spindle-drum assemblies. Large mechanized farms in Telangana and Maharashtra deploy these units to reduce labor dependence during peak harvest windows.
- Cotton Compressors:Pneumatic density systems achieve uniform bale compression ratios. India's BIS certification requirements are accelerating displacement of mechanical screw presses in domestic ginning operations.
- Bale Presses:Final-stage hydraulic or pneumatic compression into standardized transport dimensions. Mid-scale cooperatives in Bangladesh prioritize these units for containerized export logistics.
Ginning machines absorb the bulk of installed capacity; optical-enabled lint cleaners are expanding most quickly.
Technology:
Technology segmentation tracks the shift from mechanical drive systems toward sensor-integrated automation, with capital deployment clustering around pneumatic transport and machine-vision quality systems.
- Mechanical:Belt-driven conveyors and gear-reduction drives dominate legacy installations. Sunk capital in mechanical systems creates retrofit barriers for mid-scale gins in Pakistan and Bangladesh.
- Pneumatic:Vacuum transport and compressed-air handling reduce contamination and labor. India's CEA electrical safety codes accelerate adoption as ginning facilities modernize power infrastructure.
- Automation:PLC-controlled line synchronization and automated bale handling. Greenfield textile parks in Maharashtra specify turnkey automated architectures for labor reduction.
- Optical Sensors:Spectral cameras map trash content, color grade, and fiber length simultaneously. These systems gain attach rates fastest among export-oriented mills facing downstream provenance documentation pressure.
- Hydraulic:High-pressure fluid systems for compression and drive applications. REACH-compliant lubricant mandates in Europe force seal material upgrades for ester-based oil compatibility.
Pneumatic systems capture the largest share of new capital deployment; optical sensors are climbing the fastest as quality automation penetrates mid-scale installations.
Application:
Application segmentation follows the physical processing sequence from field to bale, with procurement timing staggered by regulatory compliance deadlines and export contract cycles.
- Fiber Extraction:Initial ginning operations separating lint from cottonseed. Gujarat's cotton belt concentrates demand as integrated clusters scale automated extraction lines.
- Seed Removal:Post-ginning seed cleaning and lint recovery. Seed oil manufacturers in Maharashtra and Telangana drive secondary demand for efficient seed processing.
- Bale Formation:Compression and wrapping into standardized densities. BIS certification mandates force hardware upgrades across Indian domestic manufacturers.
- Quality Grading:Machine-vision and manual inspection protocols. Export-grade specifications from European textile buyers accelerate sensor deployment in South Asian mills.
- Waste Management:Collection and processing of gin trash and motes. Environmental compliance in European installations drives pneumatic waste handling retrofits.
Fiber extraction commands the largest equipment base; quality grading applications are gaining share fastest as automation replaces manual inspection protocols.
End User:
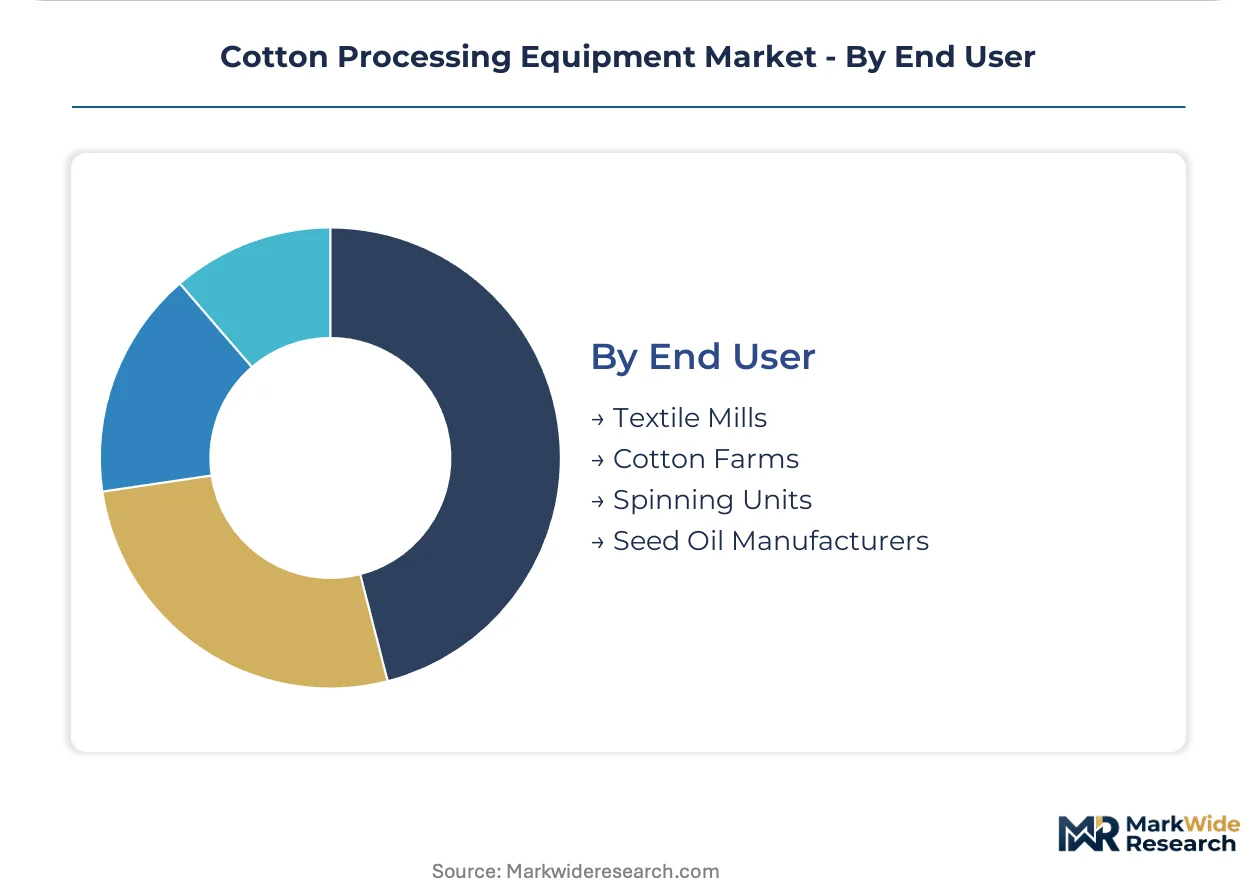
End-user segmentation reveals divergent procurement authority between integrated textile operations and independent ginning cooperatives, with specification power concentrated in downstream spinning units.
- Textile Mills:Integrated ginning-to-spinning operations with captive processing capacity. These buyers specify unified control architectures and demand optical grading integration for yarn quality consistency.
- Cotton Farms:Large mechanized holdings with on-site ginning or picker deployment. Telangana and Maharashtra farming collectives prioritize harvesting equipment over processing hardware.
- Spinning Units:Downstream yarn manufacturers sourcing ginned lint. These end users exert indirect pressure on ginning equipment specifications through fiber quality contracts.
- Seed Oil Manufacturers:Processors of cottonseed for edible oil and meal production. Secondary equipment demand concentrates in seed cleaning and lint recovery systems.
Textile mills deploy the largest cumulative equipment value; spinning units are expanding procurement influence fastest as quality specifications tighten across export supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Deccan Plateau and Gujarat cotton belt anchor the heaviest equipment procurement volumes, while regulatory fragmentation across major producing regions shapes vendor certification strategies.
India
Gujarat's integrated ginning-to-spinning clusters drive automated line procurement as BIS baling density mandates force hardware upgrades. India's CEA electrical safety codes accelerate synchronized motor control adoption across Maharashtra ginning cooperatives. Telangana's greenfield textile parks specify turnkey pneumatic systems for labor reduction.
China
Xinjiang's mechanized cotton base sustains demand for high-throughput ginning machinery despite export market pressures. China's GB machinery standards and dual carbon goals elevate compliance costs for hydraulic system vendors. Shandong Province's industrial machinery corridor concentrates domestic equipment fabrication capacity.
United States
Texas High Plains and Mississippi Delta ginning cooperatives prioritize optical sensor retrofits for USDA grade certification. FDA textile contact standards and EPA emissions rules shape lubricant and pneumatic system specifications. Georgia's legacy ginning infrastructure faces mechanical-to-pneumatic transport conversion decisions.
Brazil
Mato Grosso's large-scale farming operations deploy self-propelled picker fleets to compress harvest labor windows. ANVISA agricultural machinery regulations align with international safety protocols for export-oriented lint production. São Paulo state's textile processing corridor generates secondary demand for seed oil extraction equipment.
Turkey
Çukurova cotton belt mills invest in automated cleaning lines to serve European yarn export contracts. REACH-compliant lubricant mandates from EU buyers force seal material upgrades in pneumatic compression systems. Izmir's machinery distribution hub channels European and Asian equipment into regional markets.
Cotton Processing Equipment Market Competitive Landscape
Global majors compete with regional champions across automation intensity and aftermarket service density. The vendor base stratifies between premium Swiss-German engineering houses, dense Indian fabrication networks, and specialized East Asian component suppliers. Three archetypes dominate: integrated turnkey providers, precision component specialists, and regional full-line fabricators. Capacity expansion in South Asian service networks and technology licensing for pneumatic control systems represent the dominant competitive vectors.
Within the premium engineering tier, Rieter and Trützschler Group occupy positions defined by deep specialization in automated cleaning and pneumatic transport architectures. Bajaj Steel Industries anchors the Indian subcontinent through dense fabrication networks and aftermarket service infrastructure. These three exemplify how geographic origin and organizational structure shape competitive positioning without requiring identical capability profiles.
| Leading Market Players |
|---|
| Lummus Corporation |
| Bajaj Steel Industries |
| Rieter |
| Trützschler Group |
| Nipha Exports |
| Shandong Swan Cotton Industrial Machinery Stock |
| Cherokee Fabrication |
| Toyota Industries |
| Continental Eagle Corporation |
| Others |
Pricing and Supply Chain Analysis
Pneumatic compression system adoption across Indian ginning cooperatives simultaneously elevates equipment capital intensity and consolidates procurement authority around integrated turnkey providers. India's BIS baling density mandates force hardware upgrades that compress margin buffers for mid-scale assemblers while rewarding vendors with certified pneumatic architectures.
Pricing Analysis
Warranty and aftermarket service bundling now separates premium Swiss-German engineering houses from Indian fabrication networks competing on stripped hardware pricing. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and optical sensor integration depth. Cost compression in economy-tier mechanical systems intensifies as steel input volatility erodes fabricator margins. Independent ginning cooperatives in Maharashtra exhibit highest price sensitivity; integrated textile mills in Gujarat prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Workforce availability constraints in Shandong Province and Gujarat's industrial corridors limit precision component fabrication capacity for high-speed saw cylinders. Supply concentration centers on China for steel frames, India for dense fabrication networks, and Switzerland for precision pneumatic valves. Raw material dependencies rest on specialty alloy steels, optical sensor arrays, and REACH-compliant hydraulic seals. Single-source vulnerability concentrates around European pneumatic valve suppliers. Distribution runs through regional machinery distributors anchored in Izmir, São Paulo, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where India's BIS certification requirements erect barrier-to-entry moats favoring vendors with pre-certified pneumatic architectures.
For Market Incumbents: Anticipate margin compression from Chinese domestic equipment fabricators scaling automated production lines. Defend positioning by deepening aftermarket sensor retrofit capabilities for legacy mechanical installations in Bangladesh and Pakistan. Prioritize certification investment across India's CEA electrical safety codes and China's GB machinery standards to extend cross-border product launch windows.
For New Entrants and Emerging Players: Begin with modular optical sensor kits targeting mid-scale ginning cooperatives in Maharashtra lacking in-house mechatronics capabilities. White-space opportunity concentrates in aftermarket quality-monitoring hardware attach rates. Pursue component-level subscription service models unbundled from bundled maintenance contracts.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated textile mills seeking captive processing capacity. Long-term viability favors vendors with demonstrated compliance across fragmented regulatory clusters. Target acquisition archetype: regional full-line fabricators with dense service networks and BIS-certified pneumatic system portfolios. Watch for inflection in India's CEA enforcement timelines accelerating synchronized motor control replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Swiss-German engineering houses secure saw cylinder supply against European valve supplier concentration. |
| Optical Sensor Platform Integration | Machine-vision lint classification unifies quality grading with real-time gin stand speed adjustment. |
| Regional Service Network Expansion | Dense aftermarket infrastructure in Maharashtra and Telangana captures maintenance subscription revenue. |
| Multi-Standard Certification Investment | Sequenced BIS, GB, and CE marking processes compress product launch windows for cross-border vendors. |
| Greenfield Textile Park Partnerships | Turnkey automated line procurement in Maharashtra and Telangana locks in captive demand. |
Research Methodology
Independent corroboration across ginning facility maintenance directors, textile mill procurement heads, and pneumatic component distributors underwrites the qualitative findings. Primary interviews engaged plant engineers at integrated ginning-to-spinning clusters, aftermarket service managers at regional fabrication networks, and regulatory compliance officers navigating India's BIS and CEA frameworks. Secondary validation drew from customs trade data for cotton processing machinery imports, SEC filings of listed textile equipment manufacturers, and certification databases tracking BIS and CE marking timelines. Bottom-up equipment procurement surveys triangulate against top-down market sizing from national cotton production statistics.
Rate-of-change decomposition across the analysis window separates volume effects from price-mix shifts in pneumatic versus mechanical system adoption. Segmentation dimensions span product type, technology architecture, application stage, and end-user procurement authority. CAGRs derive from installed base replacement cycles, greenfield textile park development pipelines, and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporate India's BIS enforcement timeline and REACH-compliant lubricant formulation transitions in European installations.
Underlying measurement precision varies by segment; optical sensor technology and pneumatic system procurement carry tighter precision than legacy mechanical equipment estimates. Forecasts reflect assumptions regarding regulatory enforcement consistency and steel input price stability. Material deviation in India's CEA compliance deadlines or Xinjiang cotton export policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Global Industrial Fabric Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Saddle Stitching Machine Market
Textile Machinery and Equipment
Global Weaving Machinery Market
Textile Machinery and Equipment
Direct to Garment Printing Market
Textile Machinery and Equipment
Global Circular Knitting Machine Market
Textile Machinery and Equipment
Global Digital Printing and Dyeing Machine Market
Textile Machinery and Equipment
Dyeing Machine Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Braiding Equipment Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Multifunctional Clothes Folding Machine Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market