
 Hydroxymethylbutyrate (HMB) Market | 2026-2036
Hydroxymethylbutyrate (HMB) Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxymethylbutyrate (HMB) Market Outlook
Single-ingredient HMB powder formats is consolidating buyer preference as consumers abandon complex pre-workout blends for transparent, stackable supplements. TSI Group leverages its position as a primary raw material supplier to dominate bulk ingredient supply chains. NutraBio differentiates through third-party testing protocols that sustain premium positioning in direct-to-consumer channels. Glanbia Nutritionals extends its dairy-derived ingredient expertise into HMB adjacent formulations for sports nutrition brands.
Hydroxymethylbutyrate is a leucine metabolite, specifically beta-hydroxy-beta-methylbutyrate, produced through fermentation or chemical synthesis at purity grades typically exceeding 98% for pharmaceutical and nutraceutical applications. Its primary commercial purpose centers on attenuating proteolysis in skeletal muscle, particularly under catabolic stress from intense exercise, immobilization, or age-related sarcopenia. Powder formulations capture the largest volume share due to cost efficiency and flexible dosing, while liquid HMB represents the fastest-growing configuration as ready-to-drink sports nutrition expands shelf presence. Capsule demand anchors the elderly segment where convenience and precise dosing override price sensitivity, with online retail channels capturing disproportionate margin pools through subscription models.
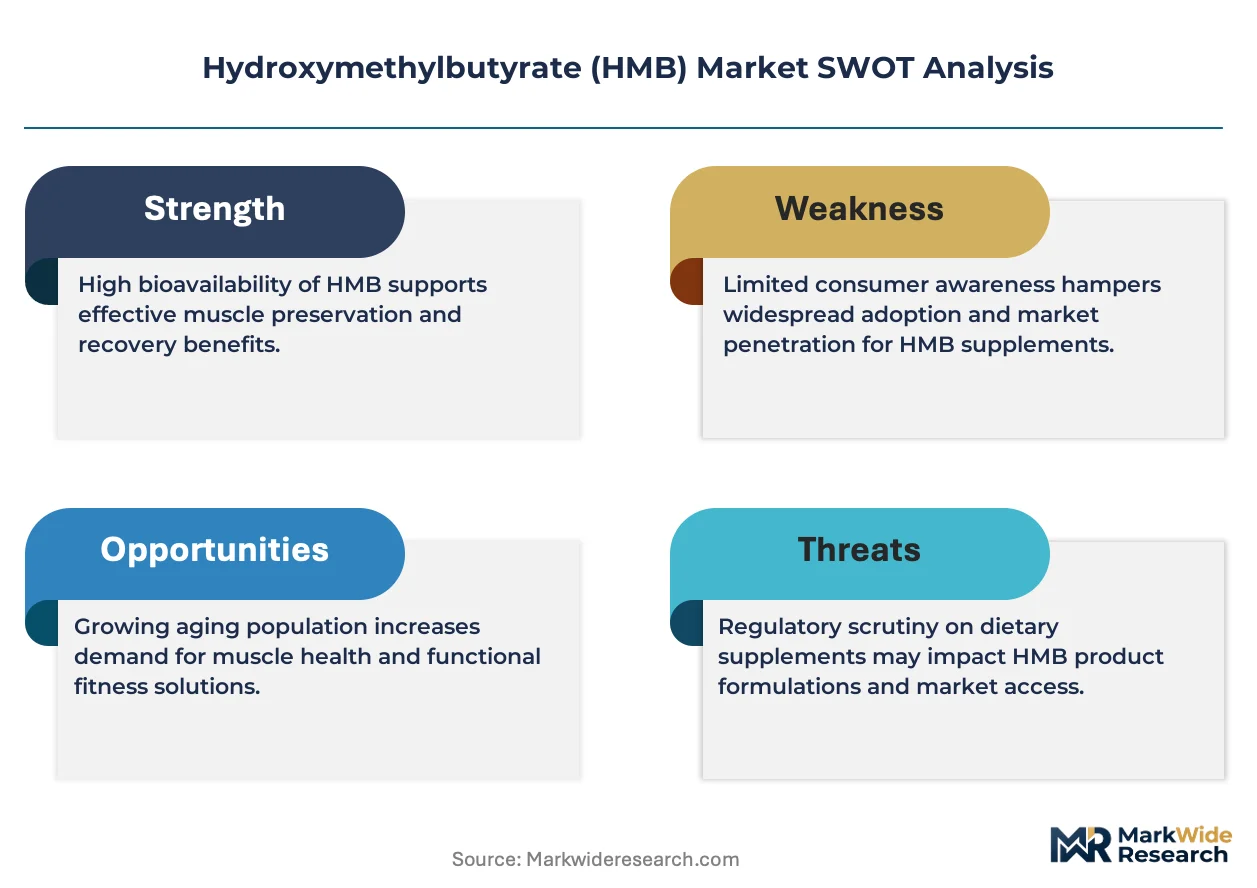
FDA cGMP enforcement and DSHEA framework requirements shape manufacturing compliance costs and barrier thresholds for new entrants in the United States dietary supplement space. EFSA health claim regulations in Europe restrict permitted marketing language around muscle maintenance, constraining brand messaging latitude compared to less regulated jurisdictions. China's NMPA and SAMR oversight of imported health foods creates additional registration hurdles for cross-border HMB products. Stakeholders must monitor evolving substantiation standards for structure-function claims as regulatory scrutiny intensifies across major demand centers.
Market Dynamics
FDA cGMP enforcement and DSHEA compliance costs are restructuring manufacturing economics, forcing smaller contract manufacturers toward consolidation while advantaging vertically integrated suppliers with captive fermentation capacity.
Growth Catalysts
- Sarcopenia awareness campaigns:Geriatric medicine protocols in Japan and the United States now incorporate HMB supplementation for muscle preservation in patients over sixty-five, expanding the clinical nutrition addressable base.
- Clean label mandates:EFSA health claim substantiation requirements are filtering out unsubstantiated competitors, creating shelf space for clinically validated HMB formulations in European retail channels.
- Fermentation technology maturation:Microbial production methods are displacing chemical synthesis for pharmaceutical-grade HMB, reducing residual solvent concerns and unlocking pharmaceutical channel access.
Market Restraints
- Leucine price volatility:Corn and soybean feedstock fluctuations transmit directly to HMB input costs, compressing margin stability for non-integrated producers dependent on spot leucine markets.
- Single-source fermentation equipment:Bioreactor manufacturing concentrates among German and Swiss engineering firms, creating eighteen-month lead times for capacity expansion.
- Plant protein substitution:Pea and rice protein isolates with added leucine are capturing budget-conscious sports nutrition buyers, constraining HMB powder pricing power in the value tier.
Strategic Opportunities
- Clinical enteral nutrition:Hospital formulary adoption for post-surgical recovery represents an underpenetrated channel where HMB's proteolysis-inhibition mechanism commands premium reimbursement.
- India's PLI scheme for nutraceuticals:Production-linked incentives for active pharmaceutical ingredient manufacturing are attracting contract fermentation investment for export-oriented HMB supply.
- Direct-to-consumer subscription platforms:Personalized nutrition algorithms are integrating HMB into automated replenishment models, reducing customer acquisition costs versus traditional retail.
Industry Challenges
- Analytical chemistry talent scarcity:Validated HMB assay methods require specialized chromatography expertise that contract laboratories struggle to staff, delaying batch release timelines.
- Cross-border registration complexity:China's SAMR health food blue-hat certification demands eighteen-to-twenty-four month clinical dossier preparation, freezing market entry for unprepared entrants.
- Legacy ERP integration:Track-and-trace serialization requirements for FDA compliance are forcing mid-tier manufacturers into expensive system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxymethylbutyrate (HMB) Market |
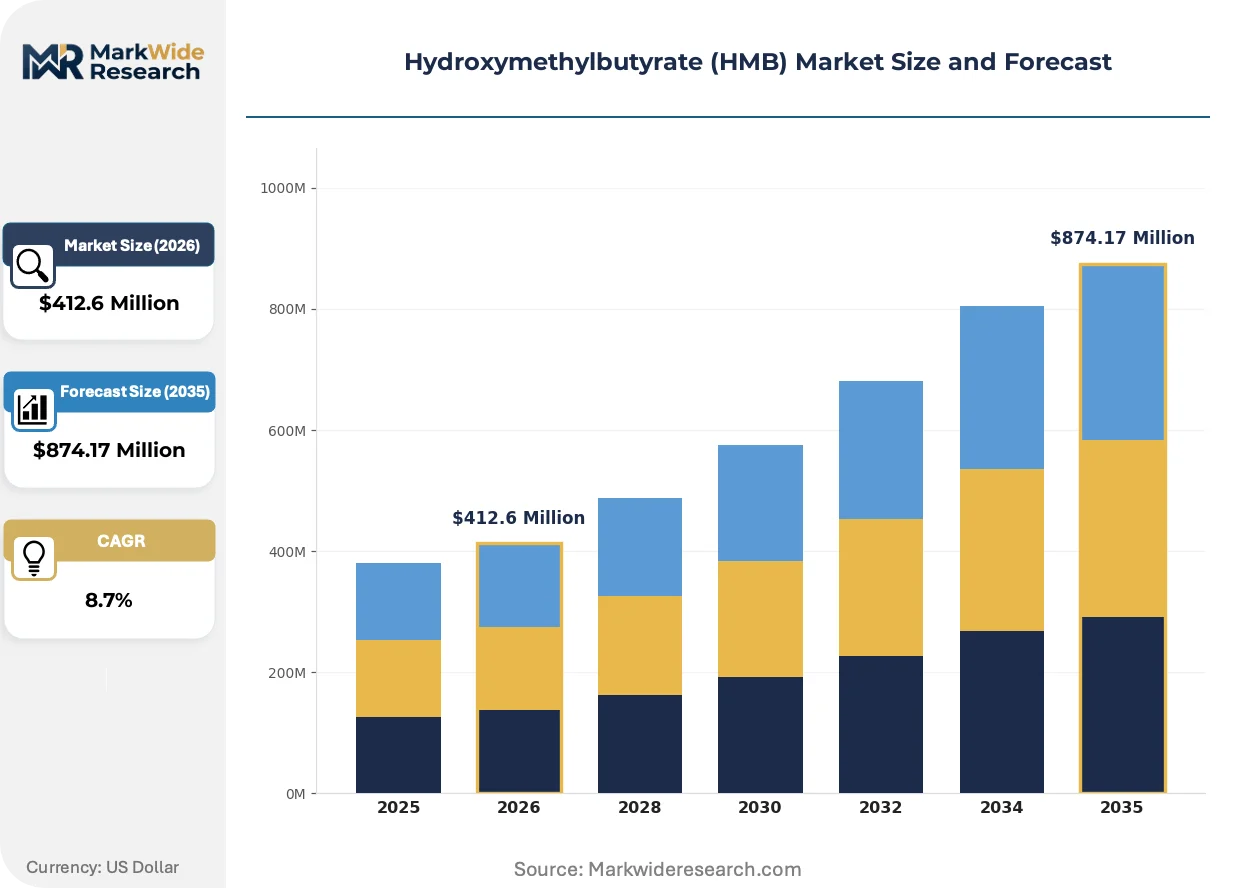
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Tablets, Liquids End User: Athletes, Bodybuilders, Elderly, General Fitness Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Application: Muscle Recovery, Weight Loss, Performance Enhancement, Dietary Supplementation |
| Companies Covered | Enomark, NutraBio, TSI Group, Xi'an Virgin Biotechnology, Optimum Nutrition, Merck & Co., Zhejiang Zetian Fine Chemicals Co. Ltd., Glanbia Nutritionals, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxymethylbutyrate (HMB) Market Strategic Shifts
Biomanufacturing advances and regulatory digitization are compressing development cycles while fragmenting traditional supply hierarchies across the HMB value chain.
Continuous fermentation technology is decentralizing production economics by enabling smaller-scale, distributed manufacturing nodes that bypass centralized multi-ton batch economics. Regional contract manufacturers in the United States and Germany are deploying skid-mounted bioreactor systems that slash capital intensity for pharmaceutical-grade HMB. This distributed model is compressing freight costs and customs exposure for finished goods distribution.
EFSA's evolving substantiation standards for muscle maintenance claims are forcing reformulation transparency across European sports nutrition portfolios. Brands must now disclose HMB sourcing and purity grades that previously remained proprietary, shifting competitive advantage toward suppliers with documented cGMP compliance. The ready-to-drink segment faces the steepest compliance burden given shorter shelf-life documentation requirements.
Subscription-driven replenishment models are displacing retail shelf reliance among performance-oriented consumers seeking stackable, single-ingredient inputs. Direct-to-consumer brands are capturing lifetime value through automated dosing protocols that integrate HMB with creatine and protein timing. This behavioral shift concentrates most visibly in United States metropolitan markets where fitness app ecosystems enable seamless supplement integration.
Hydroxymethylbutyrate (HMB) Market Segmentation
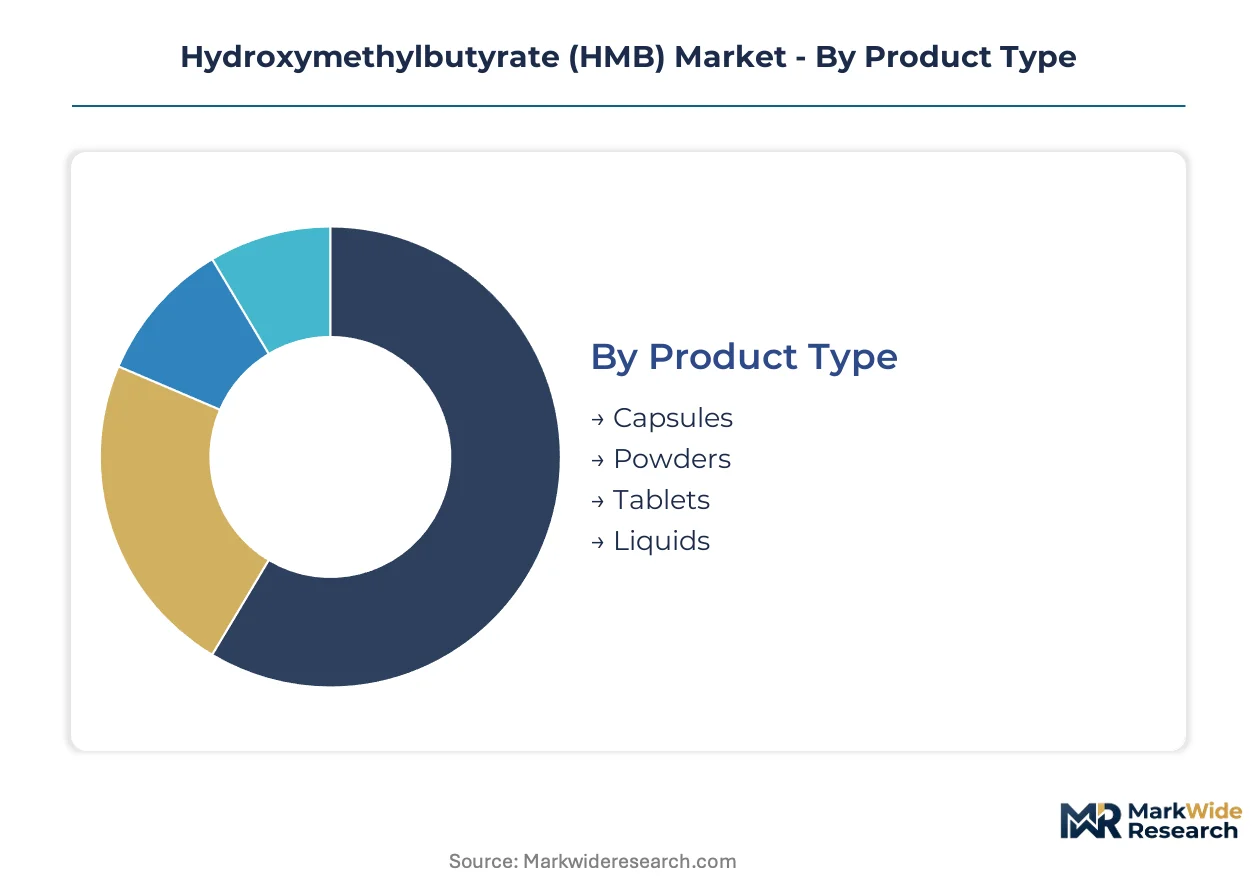
HMB formulation diversity reflects divergent consumer priorities across age, fitness commitment, and channel preference. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that shape supplier strategy.
Product Type:
Purity grades and manufacturing complexity separate pharmaceutical-grade from nutraceutical-grade supply tiers, with fermentation-derived HMB commanding premium positioning over chemical synthesis routes.
- Powders:Bulk crystalline HMB delivered in flexible packaging formats enables precise dosing protocols favored by competitive athletes stacking multiple ergogenic aids. Cost efficiency per gram and compatibility with protein shake integration sustain dominance in United States sports nutrition channels.
- Liquids:Ready-to-drink formulations with stabilized HMB suspension technology address convenience demand from metropolitan fitness consumers. Germany and United States ready-to-drink sports nutrition expansion drives this configuration's commercial momentum.
- Capsules:Pre-measured gelatin or vegetable-based shells target elderly consumers prioritizing dosing accuracy over unit economics. Japan's geriatric nutrition protocols and United States Medicare-adjacent wellness programs anchor demand.
- Tablets:Compressed excipient matrices with extended-release coatings serve pharmacy and clinical nutrition channels requiring shelf-stable, tamper-evident presentation. Hospital formulary procurement in France and Switzerland favors this format for post-surgical protocols.
Powders lead on scale; liquids lead on momentum.
End User:
Physiological stress markers and protein turnover rates determine HMB dosing intensity, creating four distinct value pools with divergent price elasticity.
- Bodybuilders:High-frequency resistance training generates proteolytic stress requiring gram-scale daily HMB intake during cutting phases. United States physique competitors and strength sport athletes sustain the highest per-capita consumption rates.
- Elderly:Age-related sarcopenia drives clinical validation requirements and insurance-adjacent reimbursement pathways. Japanese geriatric medicine protocols and United States long-term care facilities represent concentrated demand centers.
- Athletes:Endurance and team sport competitors use HMB for recovery acceleration between training blocks. NCAA-adjacent nutrition programs and European professional football clubs standardize supplementation.
- General Fitness:Recreational exercisers with inconsistent training patterns show higher churn and lower lifetime value. Budget-tier pricing and retail impulse placement characterize this segment.
Bodybuilders dominate volume concentration; elderly consumers anchor margin expansion.
Distribution Channel:
Channel selection determines compliance burden, with pharmacy and online retail facing divergent serialization and substantiation requirements.
- Online Retail:Direct-to-consumer platforms with subscription automation capture recurring revenue and bypass retail slotting fees. United States metropolitan fitness app ecosystems integrate HMB into personalized nutrition stacks.
- Specialty Stores:Independent supplement retailers with educated staff support premium single-ingredient positioning and stack-building consultation. Germany's Reformhaus network and United States GNC-adjacent boutiques sustain this channel.
- Supermarkets:Mass-market placement requires price compression and simplified messaging, favoring blended formulations over pure HMB. France's Carrefour and United States Kroger chains test sports nutrition aisle expansion.
- Pharmacies:Behind-the-counter or pharmacist-recommended positioning demands clinical trial dossiers and stability documentation. Swiss pharmacy chains and Japanese drugstores enforce stringent quality verification.
Online retail captures the steepest expansion trajectory; pharmacies command the highest unit economics.
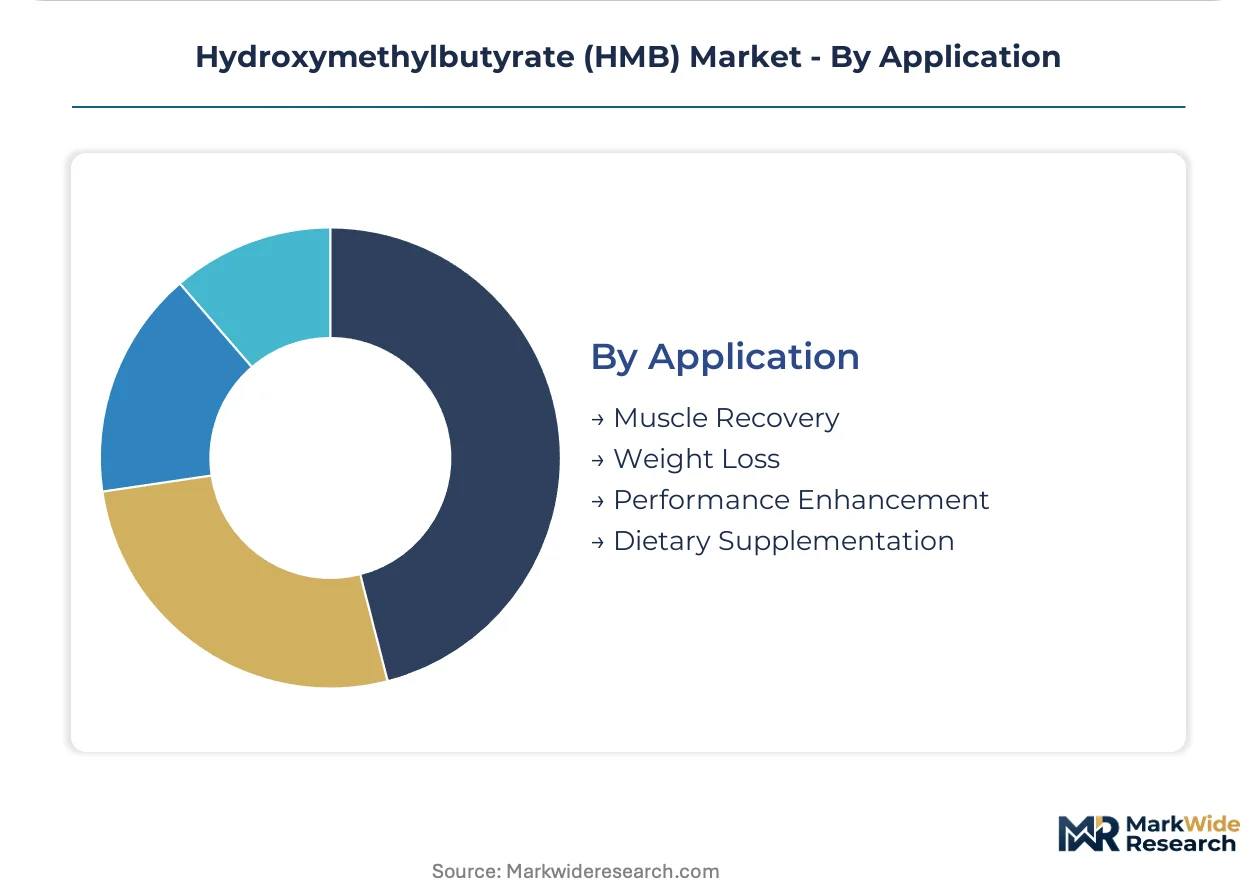
Application:
Claim substantiation requirements vary sharply by intended use, with muscle maintenance facing stricter regulatory scrutiny than general wellness positioning.
- Muscle Recovery:Post-exercise proteolysis attenuation represents the most clinically validated mechanism, supported by peer-reviewed trials in resistance-trained populations. EFSA health claim restrictions in Europe constrain marketing language despite strong evidence base.
- Performance Enhancement:Strength and power output claims require more extensive human performance data, limiting permissible messaging to training capacity rather than competitive outcomes. United States structure-function claim framework permits broader positioning than European jurisdictions.
- Dietary Supplementation:General wellness and nutritional insurance positioning avoids disease claims, minimizing regulatory exposure. India's emerging nutraceutical market and United States broad supplement adoption sustain baseline demand.
- Weight Loss:Lean mass preservation during caloric deficit represents a secondary mechanism with emerging but less robust clinical support. Fitness-focused female demographics in United States and South Korea drive trial.
Muscle recovery anchors revenue concentration; performance enhancement offers the highest claim premium potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HMB commercialization traces to United States sports nutrition innovation in the 1990s, with clinical validation subsequently expanding manufacturing footprints into Asia-Pacific fermentation clusters and European pharmaceutical corridors.
United States
FDA cGMP enforcement and DSHEA compliance requirements sustain elevated quality barriers that favor established suppliers with captive analytical capabilities. The country's national pharmaceutical regulator maintains stringent batch release documentation for structure-function claims. Greater Boston and San Diego biotech corridors host contract fermentation facilities serving both nutraceutical and clinical nutrition channels.
Germany
EFSA health claim substantiation mandates filter unsubstantiated competitors from European retail shelves, creating shelf space for clinically validated formulations. REACH chemical safety protocols govern residual solvent thresholds for chemically synthesized HMB imports. The Eindhoven-adjacent bioprocessing cluster in neighboring Netherlands supplies German contract manufacturers with skid-mounted bioreactor systems.
China
NMPA and SAMR oversight of imported health foods creates eighteen-to-twenty-four month registration timelines that freeze unprepared entrants. The country's national pharmaceutical regulator enforces dual carbon goals that favor fermentation-derived production over chemical synthesis. Zhejiang province's fine chemicals corridor concentrates HMB precursor manufacturing for export-oriented nutraceutical supply.
Japan
Geriatric medicine protocols incorporate HMB supplementation for sarcopenia patients over sixty-five, expanding clinical nutrition addressable demand. METI industrial policy supports domestic fermentation capacity for pharmaceutical-grade amino acid derivatives. The Kansai region's Osaka-Kobe pharmaceutical cluster maintains specialized bioreactor infrastructure for leucine metabolite production.
India
Production-linked incentives for active pharmaceutical ingredient manufacturing attract contract fermentation investment for export-oriented HMB supply. The country's national pharmaceutical regulator harmonizes with ICH guidelines for impurity profiling of fermentation-derived products. Maharashtra's Mumbai-Pune pharmaceutical corridor hosts emerging nutraceutical contract manufacturing organizations serving Middle Eastern and African export markets.
Hydroxymethylbutyrate (HMB) Market Competitive Environment
Premium-margin players sit above commodity-margin players across purity grade and clinical validation tiers, with pharmaceutical-grade fermentation-derived HMB commanding substantial pricing separation from nutraceutical-grade chemical synthesis alternatives. The supplier base concentrates around raw material specialists, finished goods marketers, and vertically integrated dairy-derived ingredient platforms. Three archetypes dominate: primary fermentation suppliers with captive leucine access, direct-to-consumer brands with third-party testing protocols, and dairy processors extending into adjacent metabolite formulations. Capacity expansion through distributed bioreactor deployment and strategic partnerships for cross-border regulatory navigation represent the dominant competitive moves.
Within the primary supplier tier, TSI Group and Zhejiang Zetian Fine Chemicals Co. Ltd. exemplify contrasting geographic anchoring for fermentation and chemical synthesis routes respectively. NutraBio occupies a position in the premium direct-to-consumer testing protocol segment. Glanbia Nutritionals represents the dairy-derived ingredient extension archetype, leveraging upstream milk protein processing expertise into HMB-adjacent formulation supply for sports nutrition brand customers.
| Leading Market Players |
|---|
| Enomark |
| NutraBio |
| TSI Group |
| Xi'an Virgin Biotechnology |
| Optimum Nutrition |
| Merck & Co. |
| Zhejiang Zetian Fine Chemicals Co. Ltd. |
| Glanbia Nutritionals |
| Abbott |
| Others |
Value Chain & Pricing Dynamics
Captive fermentation capacity anchors both supply security and pricing power for pharmaceutical-grade HMB producers, while chemical synthesis routes compete on cost in nutraceutical tiers. This integration choice separates premium-margin players from commodity suppliers facing leucine feedstock volatility.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and economy-tier chemical synthesis separates HMB suppliers by purity certification and clinical validation depth. Price differentiation rests on fermentation-derived versus synthetic origin, with FDA cGMP compliance commanding substantial premiums over basic DSHEA adherence. Pricing pressure stems from plant protein substitution in budget sports nutrition, compressing powder margins. Bodybuilders show highest price sensitivity through stack-building behavior, while elderly consumers in clinical channels accept premium positioning for dosing precision.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan compress lead times for temperature-sensitive finished goods. Raw material flows draw from Zhejiang province's fine chemicals corridor for precursors, German and Swiss bioreactor engineering for fermentation infrastructure, and Midwestern US corn-belt leucine feedstock. Single-source fermentation equipment vulnerability concentrates risk among specialized engineering firms. Distribution runs through direct-to-consumer platforms for subscription replenishment and pharmacy networks for clinical-grade products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HMB commercialization has matured into a late-cycle quality story where clinical validation and cGMP certification now filter out undifferentiated competitors. Demand is concentrating toward premium specifications as EFSA substantiation requirements and FDA enforcement elevate compliance thresholds.
For Market Incumbents: Cement analytical chemistry capabilities as a defensive moat against batch release delays that plague contract laboratories. Deepen captive fermentation capacity in Greater Boston or San Diego biotech corridors to secure leucine supply continuity. Plant protein substitution with added leucine threatens powder pricing power in value-tier sports nutrition, requiring certification investment to defend premium positioning.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable channel for automated HMB replenishment integrated with fitness app ecosystems. Target clinical enteral nutrition for post-surgical recovery where reimbursement pathways remain underdeveloped. White-space exists in India's export-oriented contract fermentation under PLI scheme incentives.
For Investors and Strategic Acquirers: Roll-up economics work for regional contract manufacturers with skid-mounted bioreactor deployment because distributed production nodes bypass centralized batch economics and compress freight exposure. Five-to-ten year viability hinges on pharmaceutical channel access through fermentation-derived purity grades. Watch EFSA health claim expansion for muscle maintenance as the signal for European margin inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive bioreactor deployment in US biotech corridors secures pharmaceutical-grade supply and reduces residual solvent concerns. |
| Third-Party Testing Protocol Investment | Independent certification builds direct-to-consumer trust and sustains premium positioning against unvalidated competitors. |
| Clinical Enteral Nutrition Partnership | Hospital formulary adoption for post-surgical protocols unlocks reimbursement pathways beyond retail sports nutrition. |
| Regulatory Navigation Capability Build | China SAMR blue-hat certification expertise accelerates cross-border market entry for prepared entrants. |
| Subscription Platform Integration | Automated replenishment models reduce customer acquisition costs and capture lifetime value in metropolitan fitness markets. |
Study Parameters
Multiple input streams — primary interviews with fermentation plant managers, sports nutrition brand procurement leads, and regulatory affairs directors; secondary validation through FDA cGMP inspection records, EFSA health claim submissions, and customs trade data — were reconciled through bottom-up and top-down triangulation. Conversations with contract manufacturing executives and hospital formulary directors supplied capacity utilization and clinical adoption patterns. SEC filings from publicly traded ingredient suppliers and NMPA registration databases provided cross-border regulatory timelines.
Data-stream reconciliation across formulation type, end-user physiology, distribution channel compliance burden, and geographic regulatory cluster enabled granular segmentation modeling. CAGRs were derived from volume trajectory analysis anchored to leucine metabolite demand curves and sports nutrition channel expansion rates. Fermentation technology maturation curves and geriatric medicine protocol adoption supplied industry-specific forecast inputs throughout the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to leucine feedstock volatility, bioreactor equipment lead times, and evolving substantiation standards for structure-function claims. Forecasts reflect documented assumptions about regulatory enforcement intensity and clinical validation requirements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Prenatal Supplements Market
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Europe Nutrition and Supplements Market
Nutritional Supplements
Global Collagen Peptides Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Zinc Supplement Market
Nutritional Supplements
Fish Collagen Market
Nutritional Supplements
Pregnenolone Supplements Market
Nutritional Supplements
Europe Botanical Supplements Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
Organic Protein Powder Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
CBD Nutraceuticals Market