
 Brazil Compound Feed Market | 2026-2036
Brazil Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Compound Feed Market Outlook
The capital-intensity divergence between integrated protein giants and regional cooperatives is bifurcating competitive dynamics across Brazil's feed sector. JBS S.A. leverages its captive slaughter capacity to backward-integrate into compound feed production at scale. Aurora Alimentos anchors its position through cooperative ownership structures that lock in grain supply from member farms across Paraná.
Brazil compound feed comprises blended formulations of cereal grains, oilseeds, protein meals, and micro-nutrient additives manufactured through pelleting or mash processing to deliver standardized metabolizable energy and crude protein levels for targeted livestock performance. Poultry feed dominates volume flows, reflecting the country's position as the world's largest chicken exporter and the density of integrated avian production systems. Swine feed represents the fastest-growing product category, driven by herd expansion in Mato Grosso and western Bahia where land costs support new sow unit development.
ANVISA governs veterinary drug and feed additive registrations, while MAPA enforces sanitary standards under federal inspection regulations that determine facility operating permits. SEBI's rural credit directives and BNDES lending programs indirectly structure working capital availability for feed mill expansion. Stakeholders must monitor how pending revisions to MAPA's ingredient labeling requirements will reshape formulation disclosure practices and procurement negotiations with livestock integrators.
Market Dynamics
Integrated protein processors are compressing margins for independent feed mills through captive demand absorption, forcing standalone operators to specialize in niche species or regional micro-segments to survive.
Growth Catalysts
- MAPA's streamlined sanitary inspection protocols:Federal facility permits now process faster for mills adopting automated hazard monitoring, accelerating capacity expansion in Mato Grosso.
- Precision nutrition platforms:Real-time formulation software linked to NIR spectroscopy cuts feed conversion ratios by optimizing metabolizable energy delivery per batch.
- São Paulo's integrated corridor density:Proximity between slaughterhouses, hatcheries, and grain terminals reduces logistics costs and enables just-in-time ingredient procurement.
Market Restraints
- Soybean meal price volatility:Brazil's dependence on international commodity exchanges for protein meal inputs exposes margins to currency fluctuation and export parity swings.
- ANVISA additive registration timelines:Novel enzyme and probiotic approvals require multi-year toxicology studies, delaying product launches versus competitors with grandfathered formulations.
- Regional supply concentration:Corn production clusters in Mato Grosso and Paraná leave northeastern feed mills exposed to freight cost spikes during harvest bottlenecks.
Strategic Opportunities
- Western Bahia sow unit expansion:Land cost advantages and MAPA's agricultural frontier incentives attract greenfield swine operations requiring dedicated feed supply contracts.
- SEBI rural credit restructuring:BNDES lending programs now prioritize working capital for cooperatives investing in on-farm feed mixing equipment.
- Digital procurement platforms:Blockchain-tracked grain sourcing from member farms lets cooperatives bypass traditional trading house markups.
Industry Challenges
- Formulation chemist scarcity:Universities produce insufficient graduates with combined nutrition science and regulatory compliance expertise to staff expanding quality control departments.
- Legacy ERP integration:Mid-sized mills struggle to connect pelleting line sensors with enterprise software, delaying real-time moisture and durability monitoring.
- ANVISA-MAPA jurisdictional overlap:Dual agency inspections for medicated feeds create redundant documentation burdens and inconsistent enforcement interpretations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Compound Feed Market |
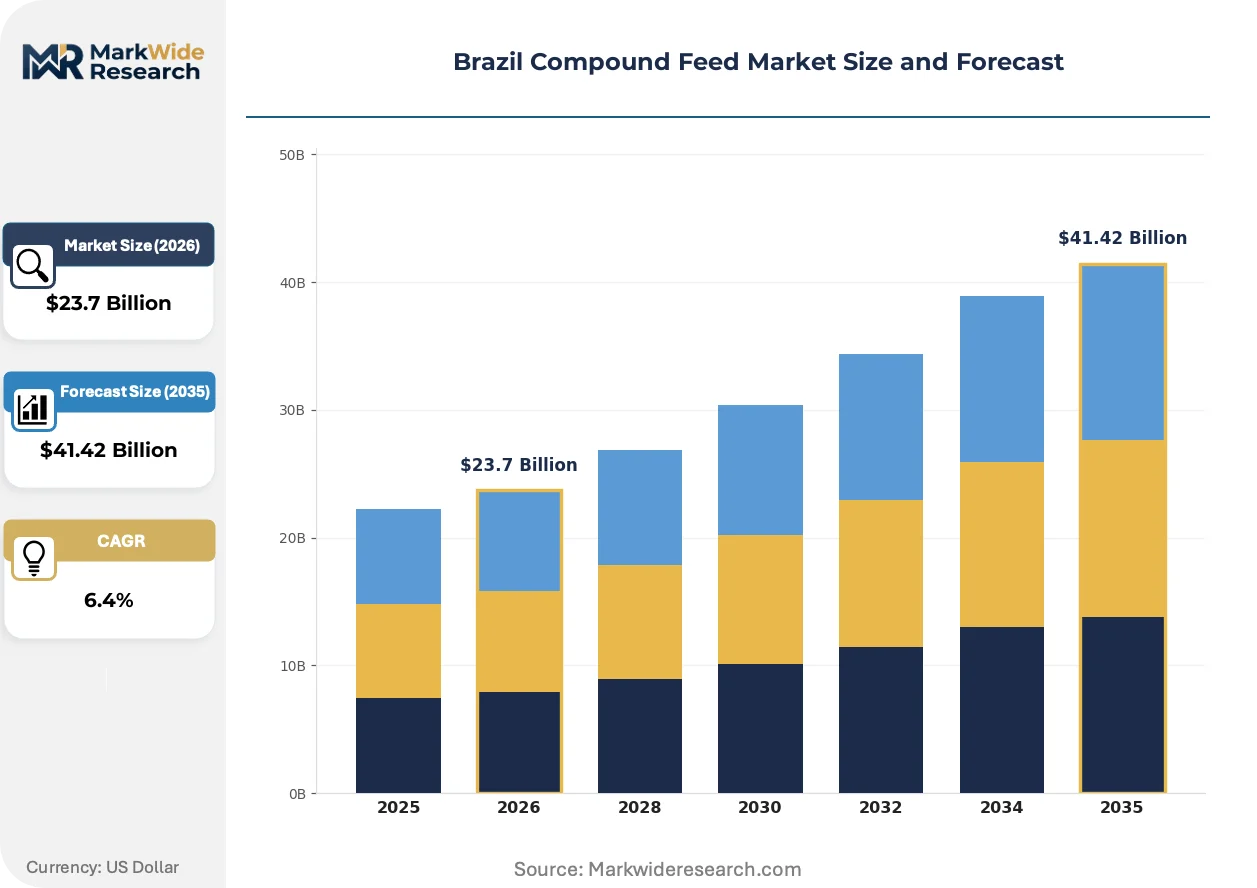
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $41.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Swine Feed, Ruminant Feed, Aquafeed Ingredient Type: Cereal Grains, Oilseeds, Additives, Vitamins Distribution Channel: Wholesale, Retail, Direct Sales, E-commerce End User: Farmers, Feed Manufacturers, Livestock Producers, Aquaculture Operations |
| Companies Covered | JBS S.A., Alltech, BRF S.A., ADM do Brasil, Aurora Alimentos, Cargill, Nutreco, Copagril, Archer Daniels Midland, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Compound Feed Market Strategic Shifts
Automation and data-driven formulation are compressing production cycles while regulatory disclosure requirements tighten ingredient transparency standards across Brazilian feed operations.
Near-infrared spectroscopy is miniaturizing quality control workflows by enabling on-truck protein and moisture analysis before grain unloading. Large integrators like JBS deploy handheld NIR units at receiving bays to reject out-of-spec corn before demurrage costs accumulate. This technology is miniaturizing laboratory functions onto the production floor, collapsing the time between ingredient receipt and ration adjustment.
MAPA's pending ingredient labeling revisions will mandate quantitative disclosure of all additives above threshold limits, replacing current percentage-range declarations. Feed mills must reformat packaging and reformulate borderline inclusion rates to maintain proprietary blend confidentiality. Poultry integrators in São Paulo state are pre-negotiating specification locks to prevent mid-contract disclosure-driven price renegotiations.
Livestock producers are consolidating procurement decisions at the integrated processor level rather than individual farm purchasing. Independent growers now receive pre-mixed rations as contract terms rather than buying feed separately, compressing the addressable market for standalone mills. This concentration is most visible in Santa Catarina's turkey sector, where cooperatives have shifted entirely to processor-managed supply programs.
Brazil Compound Feed Market Segmentation
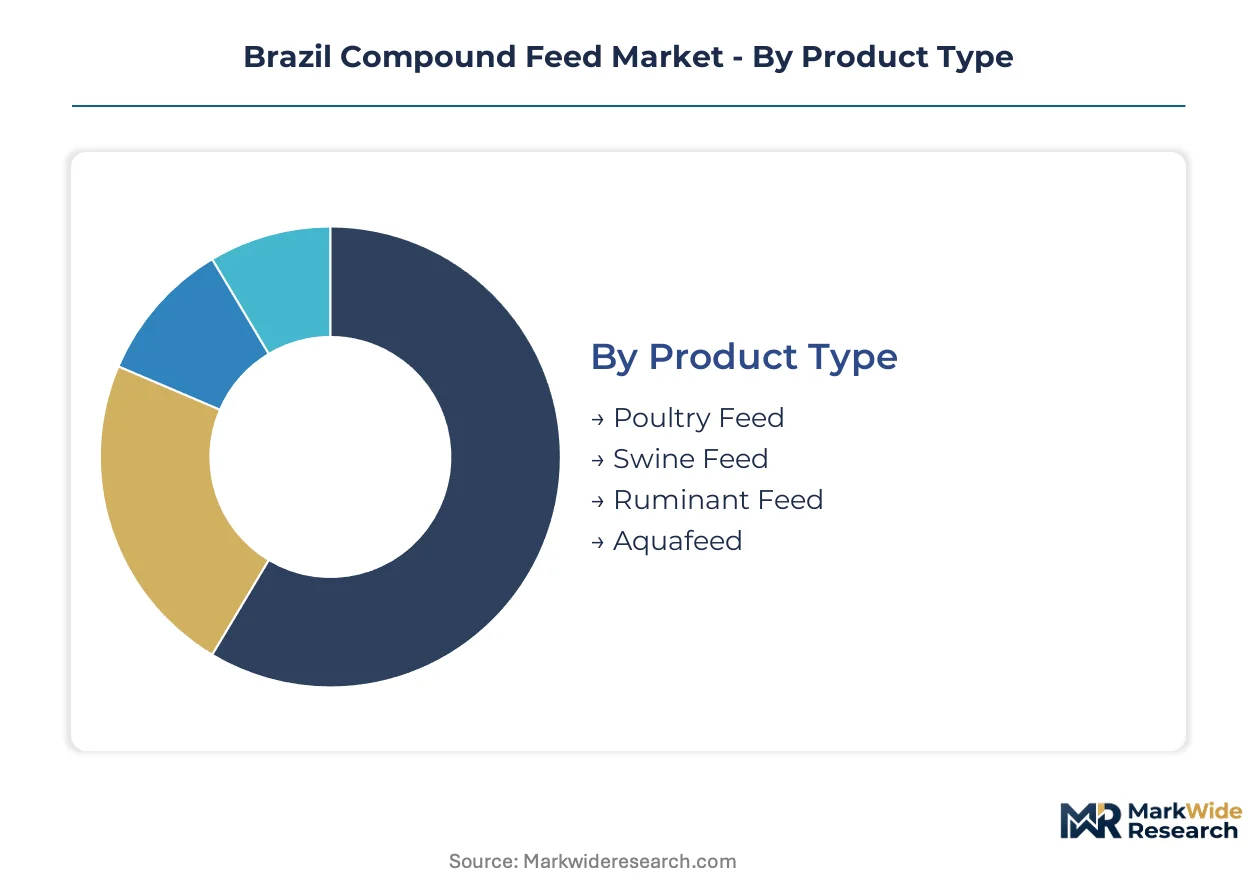
Segmentation reveals how margin pools concentrate across Brazil's compound feed landscape, where poultry feed volumes dominate but swine feed expansion reshapes investment priorities. Understanding these divides exposes where integrated processors capture value versus where independent mills retain pricing power.
Product Type:
Margins pool thickest in species-specific formulations requiring precision nutrient calibration and regulatory compliance overhead.
- Poultry Feed:Formulations optimize metabolizable energy and crude protein for broiler growth rates, with pelleting durability critical for automated feeding systems. São Paulo's integrated corridor absorbs the majority of volume, where JBS and BRF contract structures lock in multi-year supply agreements with captive feed mills.
- Swine Feed:Sow gestation and nursery diets demand phased amino acid profiles adjusted for genetic line performance targets. Western Bahia's greenfield sow unit expansion in Luís Eduardo Magalhães and Formosa do Rio Preto generates dedicated contract demand for mills willing to co-locate.
- Ruminant Feed:Beef and dairy concentrates incorporate bypass proteins and ionophores for rumen efficiency. Pasture-based systems in Mato Grosso do Sul limit complete feed penetration compared to confinement dairy clusters in Minas Gerais.
- Aquafeed:Extruded floating and sinking pellets for tilapia and tambaqui require specialized lipid oxidation control. Amazon basin pond systems in Pará and Rondônia drive regional mill specialization despite smaller absolute volumes.
The dominant share belongs to Poultry Feed, while Swine Feed is closing the gap fastest.
Ingredient Type:
Cost tier stratification separates commodity bulk inputs from value-added functional additives with regulatory approval barriers.
- Cereal Grains:Corn and sorghum provide basal metabolizable energy, with moisture and mycotoxin variability driving pre-receiving NIR testing protocols. Mato Grosso harvest flows through the Ferrovia Norte-Sul corridor to São Paulo mills, while Paraná's surplus supplies southern integrated operations.
- Oilseeds:Soybean meal dominates protein contribution, with full-fat soy and extruded expeller meals gaining traction in antibiotic-free poultry formulations. Export parity pricing links domestic meal costs to Chinese import demand swings.
- Additives:Enzymes, acidifiers, and probiotics require ANVISA registration with multi-year toxicology dossiers. Phytase and xylanase inclusion rates are standardizing across major integrator specifications.
- Vitamins:Premix stability challenges in tropical humidity drive demand for coated and encapsulated forms. MAPA's pending quantitative disclosure rules will expose inclusion rate strategies previously shielded by percentage-range labeling.
Cereal Grains command the volume base, though Additives extract the highest margin per kilogram as regulatory barriers limit supplier proliferation.
Distribution Channel:
Customer type determines channel viability, with integrated processors bypassing traditional wholesale structures entirely.
- Wholesale:Regional distributors aggregate bagged and bulk deliveries to mid-sized independent farms. Santa Catarina's cooperative-dominated poultry sector relies on Aurora Alimentos' wholesale network for member farm supply.
- Retail:Agricultural supply stores serve hobby farmers and small-scale beef finishing operations. Credit terms through SEBI-backed rural financing programs structure payment cycles.
- Direct Sales:Large integrators negotiate formula-priced contracts with mill direct delivery to company-owned farms or contract growers. JBS's captive slaughter capacity enables backward integration into feed production with zero third-party markup.
- E-commerce:Digital platforms for specialty additives and small-batch premixes remain nascent, constrained by freight economics for low-margin bulk products.
Direct Sales captures the value concentration as processor integration accelerates, while Wholesale retains relevance only where cooperative structures persist.
End User:
Procurement authority is consolidating at the integrated processor level, displacing individual farm purchasing decisions.
- Farmers:Independent growers face margin compression as contract terms mandate processor-supplied rations. Remaining autonomy concentrates in beef cattle backgrounding and smallholder dairy.
- Feed Manufacturers:Toll milling and private-label production for branded integrators represents survival strategy for standalone mills without captive demand. Quality control staffing shortages constrain expansion.
- Livestock Producers:Corporate-owned sow units and broiler complexes in Mato Grosso specify custom formulations with real-time formulation software integration.
- Aquaculture Operations:Tilapia cage farms in the São Francisco River valley and reservoir systems in Ceará require specialized extrusion capacity that most terrestrial feed mills lack.
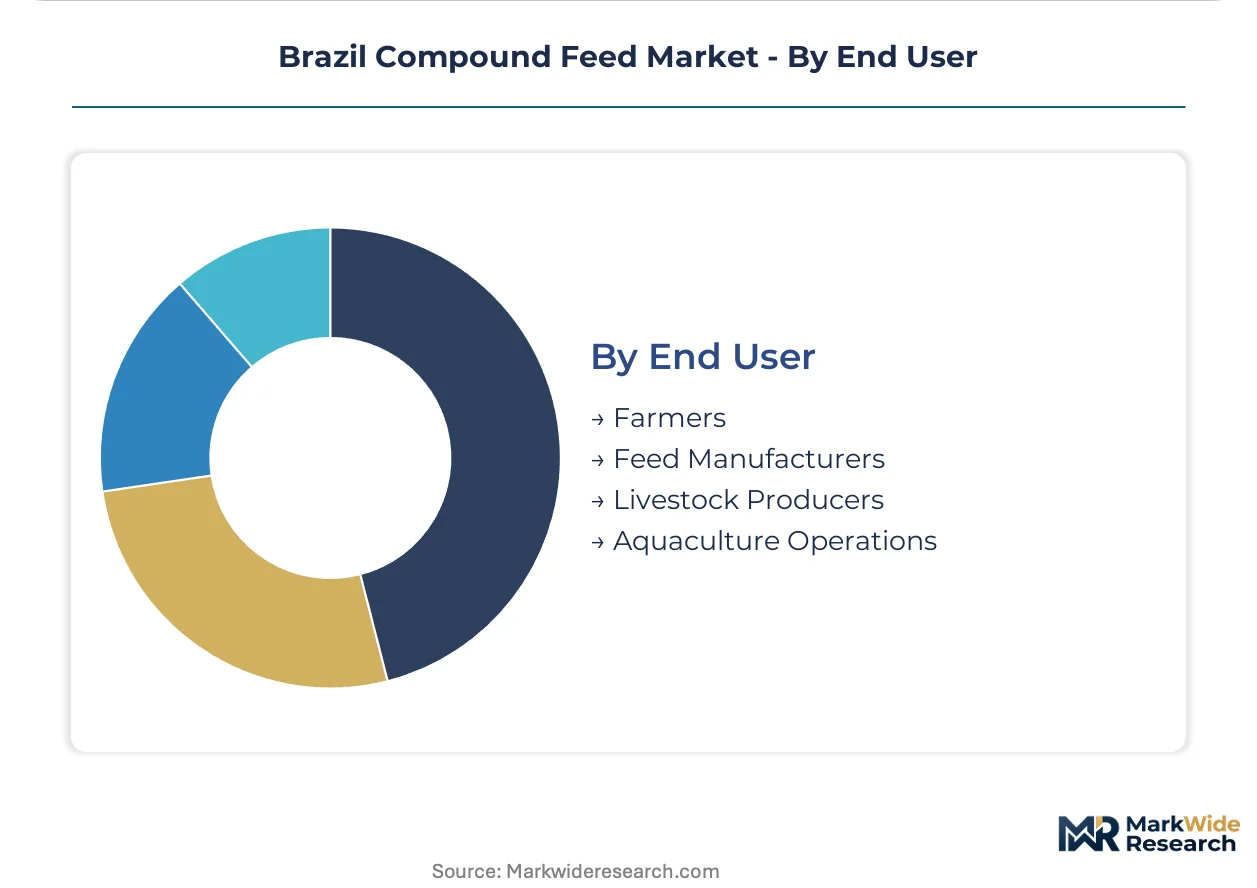
Livestock Producers now dictate formulation specifications, while Feed Manufacturers are repositioning as toll processors to retain equipment utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's compound feed sector tracks the country's agricultural export engine, with domestic consumption and foreign sales of poultry and pork driving formulation demand. Regional production clusters align with grain corridors and integrated processor locations.
São Paulo
Integrated poultry operations dominate feed consumption in the state's western production corridor. MAPA's federal inspection facilities cluster near Presidente Prudente and Marília, enabling rapid permit processing for new mill capacity. JBS and BRF coordinate just-in-time ingredient flows between grain terminals at Santos port and captive feed mills serving company-owned farms.
Paraná
Cooperative ownership structures anchor feed supply for member farms across the state's northern grain belt. Aurora Alimentos locks in corn and soybean meal procurement through backward integration with Copagril's member production base. Cascavel and Maringá serve as distribution hubs for bagged and bulk deliveries to independent growers.
Mato Grosso
Swine herd expansion in the state's agricultural frontier generates dedicated feed demand from new sow units. SEBI rural credit programs and BNDES working capital facilities accelerate greenfield mill development near Lucas do Rio Verde. Corn harvest flows through the Ferrovia Norte-Sul corridor to supply both local consumption and export markets.
Minas Gerais
Confinement dairy clusters in the state's southern milk belt drive ruminant feed consumption distinct from poultry-dominant regions. Bypass protein formulations and ionophore inclusion target rumen efficiency in high-production Holstein herds. Uberaba and Uberlândia concentrate toll milling capacity for regional dairy cooperatives.
Bahia
Western agricultural expansion in Luís Eduardo Magalhães and Formosa do Rio Preto attracts greenfield swine operations requiring dedicated feed supply contracts. Land cost advantages and MAPA's frontier incentives displace production from traditional southeastern centers. Mills co-locating with new sow units capture long-term formulation agreements.
Brazil Compound Feed Market Competitive Environment
Concentration sits with integrated protein processors that have backward integrated into captive feed production. The competitive structure bifurcates between scale-driven integrated giants and cooperative-owned regional mills serving member farms. Three archetypes dominate: protein processors with in-house milling, agricultural cooperatives with locked grain supply, and multinational traders with formulation expertise. Capacity expansion and strategic toll-milling partnerships represent the primary competitive moves as independents seek equipment utilization.
Among Brazil-based integrated processors, JBS S.A. and BRF S.A. exemplify the protein-processor archetype through captive slaughter capacity that absorbs feed production internally. Aurora Alimentos occupies a position within the cooperative tier, representing member-locked supply structures that compete on grain procurement cost rather than scale. ADM do Brasil and Cargill sit within the multinational trader archetype, leveraging global ingredient sourcing networks to serve third-party formulation demand where integration has not occurred.
| Leading Market Players |
|---|
| JBS S.A. |
| Alltech |
| BRF S.A. |
| ADM do Brasil |
| Aurora Alimentos |
| Cargill |
| Nutreco |
| Copagril |
| Archer Daniels Midland |
| Others |
Value Chain & Pricing Dynamics
Formula-priced contracts with multi-year specification locks anchor supply access for São Paulo's integrated processors while freezing input cost visibility against currency and commodity swings. This structure binds captive feed mills to protein giants through take-or-pay volumes that transfer price risk downstream to contract growers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in Brazil's compound feed sector. Premium formulations with ANVISA-registered enzyme additives command spreads over standard mash feeds, while economy tiers serve backgrounding operations with minimal micro-nutrient inclusion. Cost compression in standard poultry rations is intensifying because JBS and BRF backward-integrate into captive milling with zero third-party markup. Independent toll mills face the steepest price sensitivity as integrators consolidate procurement authority at the processor level.
Supply Chain Analysis
Ferrovia Norte-Sul corridor bottlenecks during Mato Grosso harvest windows expose northeastern feed mills to demurrage spikes and moisture-degraded corn deliveries. Brazil's compound feed sector draws from Argentine soybean meal, Paraguayan corn, and domestic oilseed crushing in Paraná to balance protein-energy ratios. Single-source vulnerability concentrates in MAPA-licensed additive premixes where ANVISA toxicology dossiers lock out alternative suppliers for multi-year cycles. Distribution runs through processor-owned silo networks that bypass traditional wholesale channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's compound feed market functions as a defensive-moat arena where regulatory entrenchment through ANVISA additive registrations and MAPA facility permits creates switching costs that lock in integrated processor dominance.
For Market Incumbents: Consolidate formulation chemist talent pools through university partnership pipelines to offset quality control staffing shortages that constrain toll-milling competitors. Deepen upstream control over grain origination by deploying blockchain-tracked procurement platforms that bypass trading house markups and lock in Copagril-style member-farm supply structures. Defend against emerging digital-native cooperatives by pre-empting SEBI rural credit restructuring to capture BNDES working capital flows. For New Entrants and Emerging Players: ANVISA fast-track pathways for grandfathered probiotic strains offer entry wedges into antibiotic-free poultry formulations where novel enzyme approvals face multi-year delays. Target western Bahia's greenfield sow unit corridor with co-located mill investments that capture dedicated supply contracts from Luís Eduardo Magalhães and Formosa do Rio Preto expansions. Lead with precision nutrition platform integration that links real-time NIR spectroscopy to automated formulation adjustment. For Investors and Strategic Acquirers: Toll-milling specialists with MAPA federal inspection permits and underutilized pelleting capacity represent prime acquisition targets as independent mills reposition for equipment utilization survival. Long-term viability hinges on feed manufacturers securing processor-managed supply program contracts rather than standalone sales to shrinking independent grower bases. Watch for ANVISA-MAPA jurisdictional harmonization as the inflection signal that would streamline medicated feed compliance burdens and unlock margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Blockchain-tracked member-farm procurement bypasses trading house markups for cooperative structures like Aurora Alimentos. |
| Precision Nutrition Platform Deployment | Real-time NIR-linked formulation software cuts feed conversion ratios for São Paulo integrated poultry operations. |
| Co-Located Mill Development | Western Bahia sow unit expansion in Luís Eduardo Magalhães generates dedicated contract demand for greenfield capacity. |
| Additive Registration Fast-Track | ANVISA grandfathered probiotic pathways accelerate product launches versus novel enzyme toxicology timelines. |
| Toll-Milling Partnership Structuring | Equipment utilization agreements let standalone mills survive processor consolidation through private-label production. |
Study Parameters
Operator-level perspectives from feed mill quality control directors, SEBI rural credit officers, MAPA sanitary inspectors, and integrated processor procurement heads anchored the qualitative base for this study. Primary fieldwork combined with secondary validation against MAPA federal inspection registries, ANVISA additive approval databases, BNDES lending program disclosures, and grain corridor logistics data from Ferrovia Norte-Sul operators. Bottom-up volume triangulation across state-level production clusters reconciled with top-down value estimates from protein processor segment disclosures.
Sensitivity analysis framed the projection horizon through scenario-weighted CAGRs derived from poultry export parity swings, sow herd expansion rates in Mato Grosso, and cooperative membership growth patterns. Segmentation dimensions modeled include species-specific formulation types, ingredient cost tiers, distribution channel structures, and end-user procurement authority levels. Industry-specific inputs incorporated ANVISA approval pipeline velocities, MAPA facility permit processing timelines, and SEBI credit allocation shifts toward on-farm feed mixing equipment.
Decision-makers should treat outputs as directional under assumptions of sustained Brazilian poultry export competitiveness and stable ANVISA-MAPA regulatory overlap; material deviation in currency volatility or jurisdictional harmonization would warrant model refresh. Specific risk factors include soybean meal export parity spikes driven by Chinese import demand shifts and legacy ERP integration failures that delay real-time moisture monitoring adoption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Asia-Pacific Rapeseed Oil Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Livestock and Meat Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Agrimony Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
India Agriculture Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
Alfalfa Pellets Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market