
 Dextrose Monohydrate Market | 2026-2036
Dextrose Monohydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Dextrose Monohydrate Market Analysis
Fructose syrup is realigning sweetener economics in beverage applications, pressuring dextrose monohydrate suppliers to defend position through purity differentiation and vertical integration. Cargill, Incorporated leverages its corn wet-milling infrastructure across the North American interior to sustain cost-advantaged feedstock access. Roquette Frères anchors European pharmaceutical-grade supply through its Lestrem facility, while Tate & Lyle competes on modified-starch adjacencies that extend dextrose utility into functional food systems.
Dextrose monohydrate is a crystalline reducing sugar with the molecular formula C6H12O6·H2O, produced through enzymatic hydrolysis of corn or wheat starch followed by controlled crystallization; it functions as a humectant, bulking agent, and fermentable substrate across food, pharmaceutical, and industrial processes. Food-grade material dominates volume throughput in bakery and confectionery channels where moisture retention and browning control command steady offtake, while pharmaceutical-grade product captures disproportionate margin pools through USP/EP-certified excipient demand from sterile formulation manufacturers. Industrial-grade segments occupy a mature, price-sensitive position in fermentation feedstocks and chemical derivatives.
The FDA enforces USP-NF monograph compliance for pharmaceutical-grade dextrose monohydrate used in injectable and dialysis applications, while the EMA's MDR framework tightens traceability requirements for excipient-grade material entering European medical device supply chains. India's CDSCO aligns with ICH Q3D guidelines on elemental impurities, compelling domestic refiners to upgrade purification trains or cede hospital procurement contracts to import-reliant distributors. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards, as divergence in heavy-metal limits and microbial specifications threatens to fragment contract manufacturing qualification protocols across export destinations.
Market Dynamics
Pharmaceutical-grade purity mandates from the FDA and EMA are compressing supplier margins while concentrating procurement power among hospital networks and sterile formulation manufacturers. This regulatory tightening is forcing corn wet-millers to upgrade crystallization trains or exit the excipient segment entirely.
Growth Catalysts
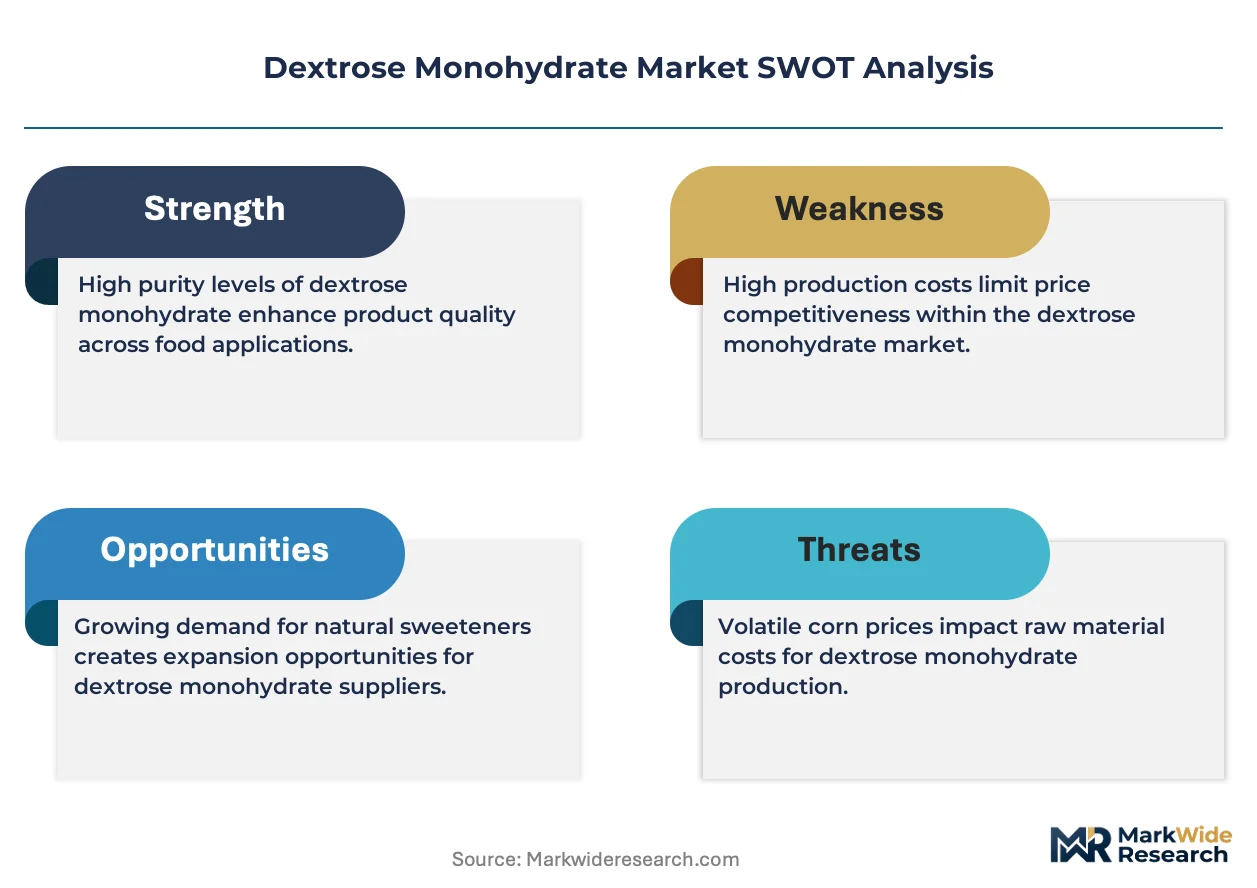
- CDSCO's ICH Q3D alignment:India's pharmaceutical regulator now enforces elemental impurity limits that match USP standards, compelling domestic refiners to invest in purification capacity and displacing import-reliant distributors from hospital procurement.
- Production-linked incentive schemes:India's PLI schemes for bulk drugs and medical devices are accelerating captive dextrose consumption by contract manufacturers serving export markets.
- Enzymatic hydrolysis optimization:Advances in glucoamylase immobilization are reducing starch conversion costs and improving crystallization yield for food-grade material in high-volume bakery channels.
Market Restraints
- Corn price volatility:Feedstock costs fluctuate with drought cycles in the US Midwest and Black Sea grain flows, compressing margins for non-integrated refiners lacking captive corn crushing.
- Fructose syrup substitution:High-fructose corn syrup offers equivalent sweetness functionality at lower cost in beverage applications, pressuring dextrose suppliers to defend position through purity certification rather than price.
- European supply concentration:Pharmaceutical-grade capacity clusters in northeastern France and Belgium, creating single-source risk for sterile formulation manufacturers dependent on USP/EP dual-certified material.
Strategic Opportunities
- Indian domestic pharmaceutical manufacturing:Government-backed API parks in Andhra Pradesh and Gujarat are creating localized demand for excipient-grade material that bypasses import duty exposure.
- Modified-starch adjacencies:Maltodextrin and cyclodextrin derivatives extend dextrose utility into functional food systems targeting glycemic response management.
- Clean-label formulation mandates:FDA and EMA tightening of excipient disclosure requirements creates premium positioning for non-GMO corn and wheat-derived dextrose in pediatric and geriatric formulations.
Industry Challenges
- Pharmacopeial harmonization gaps:Divergent heavy-metal limits between USP, EP, and IP standards fragment contract manufacturing qualification protocols and extend validation timelines for multi-destination exporters.
- Crystallization train capex intensity:USP-grade production requires continuous vacuum crystallizers and multi-stage centrifugation that demand 7-10 year depreciation horizons, constraining mid-cap entrants.
- Microbial specification compliance:Sterile formulation manufacturers now require endotoxin testing and bioburden controls that exceed food-grade capabilities, forcing dual-track quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dextrose Monohydrate Market |
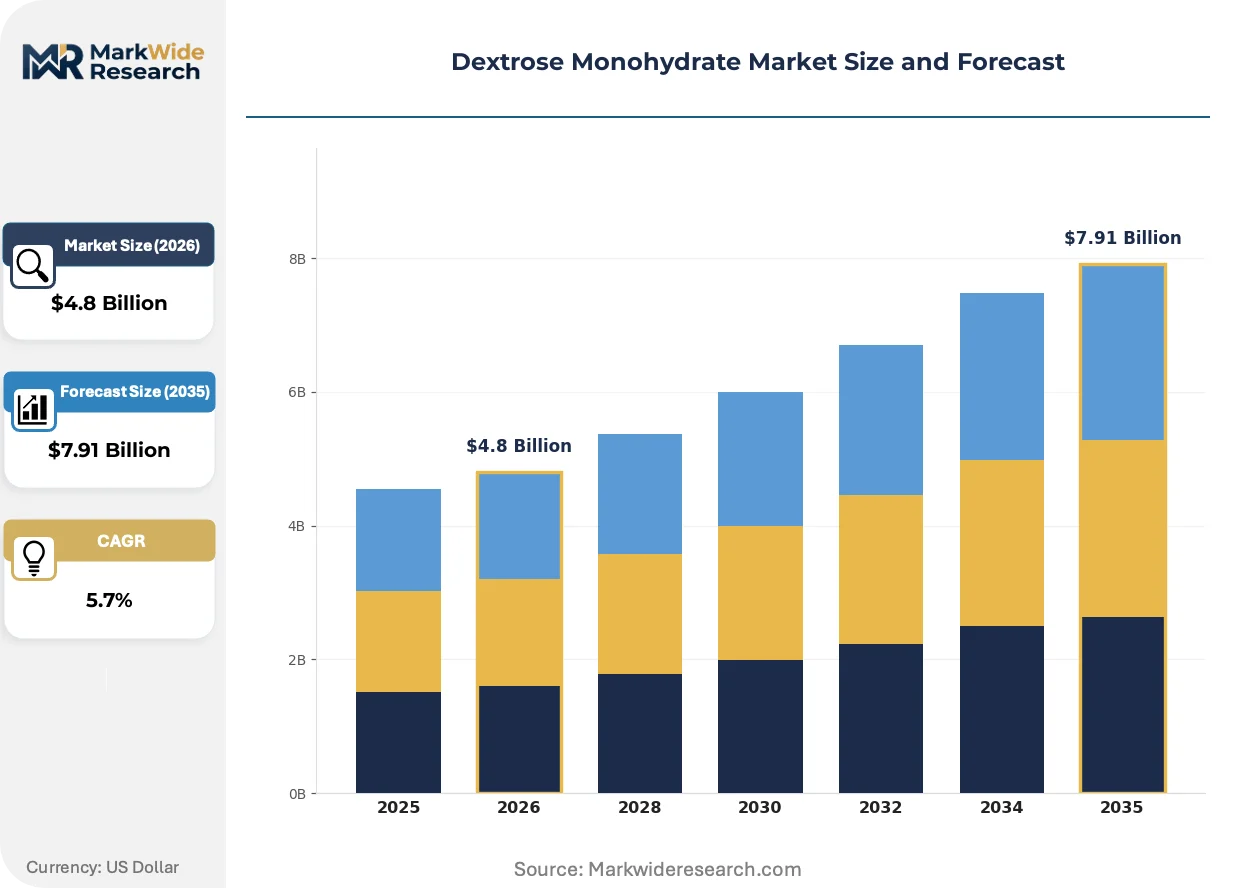
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Feed Grade Application: Beverages, Bakery Products, Dairy Products, Confectionery End User: Food Industry, Beverage Industry, Pharmaceutical Companies, Nutraceuticals Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Ingredion, Roquette Frères, Tate & Lyle, Tereos, Agrana, Gulshan Polyols Ltd, Belgosuc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dextrose Monohydrate Market Emerging Trajectories
Continuous processing technologies and regulatory disclosure requirements are reshaping how dextrose monohydrate is manufactured, certified, and procured across pharmaceutical and food channels.
Continuous crystallization systems are modularizing production architecture for pharmaceutical-grade material. Sterile formulation manufacturers in the United States and Germany are adopting these systems to compress batch cycle times from 48 hours to 12 hours. This technology is modularizing quality assurance by embedding PAT sensors directly into crystallization loops, enabling real-time release testing that reduces quarantine inventory.
REACH Annex XVII restrictions on residual solvents are tightening specification windows for excipient-grade dextrose entering European medical device supply chains. The EMA's MDR framework now requires traceability documentation from starch source through final crystallization. Sterile dialysis solution manufacturers are responding by qualifying single-source corn supply contracts with identity-preserved segregation.
Hospital procurement consortia are consolidating sterile formulation purchasing through centralized tenders that bundle parenteral nutrition, dialysis, and irrigation solutions. This buyer concentration is compressing supplier margins while rewarding multi-product portfolios with dedicated quality liaison teams. The shift is most visible in India's corporate hospital chains, where pharmacy committees now mandate USP-grade certification for all intravenous additives regardless of therapeutic category.
Dextrose Monohydrate Market Segmentation
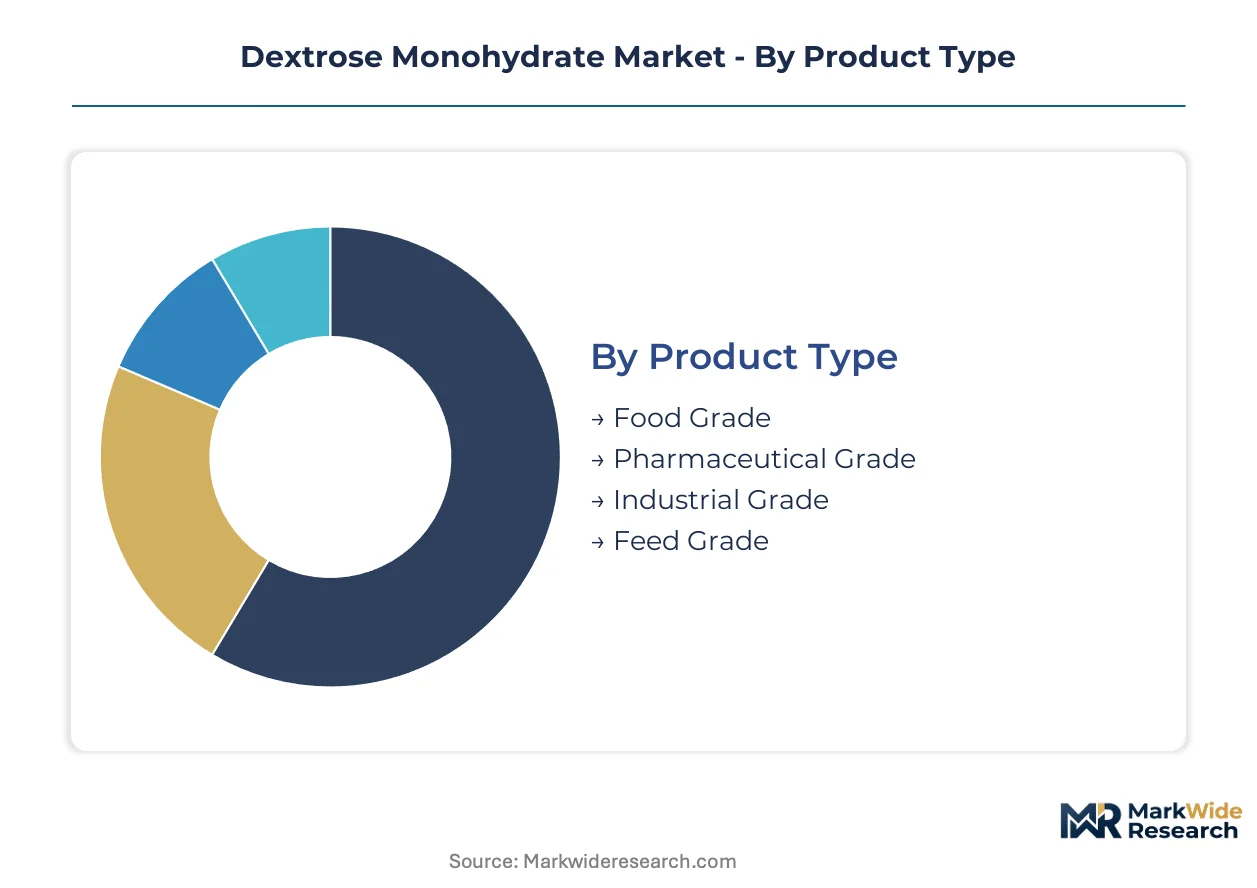
Dextrose monohydrate segments diverge sharply in purity specifications, regulatory burden, and margin structure. Corn wet-millers configure crystallization trains differently for each tier, creating distinct competitive dynamics across food, pharmaceutical, and industrial channels.
Product Type:
Supply concentration clusters in pharmaceutical-grade capacity where USP/EP dual-certification requirements limit viable producers to integrated wet-millers with captive corn crushing and multi-stage purification infrastructure.
- Food Grade:Crystalline reducing sugar meeting FCC specifications for moisture retention, browning control, and fermentable substrate functionality. Demand concentrates in high-volume bakery channels across the US Midwest and European industrial baking clusters, where enzymatic hydrolysis optimization is compressing conversion costs and squeezing non-integrated refiners.
- Pharmaceutical Grade:USP-NF monograph-compliant material with endotoxin testing, bioburden controls, and elemental impurity limits per ICH Q3D. Sterile formulation manufacturers in Germany and the United States are consolidating procurement through hospital network tenders, concentrating purchasing power among dual-certified suppliers with dedicated quality liaison teams.
- Industrial Grade:Fermentation feedstock and chemical derivative precursor with minimal purification overhead. Price sensitivity dominates as ethanol and organic acid producers prioritize feedstock cost over trace impurity profiles.
- Feed Grade:Animal nutrition supplement with lower crystallization purity requirements. Livestock operations in Brazil and Argentina absorb volume through distributor networks with limited specification differentiation.
Today's leader: Pharmaceutical Grade. Tomorrow's challenger: Food Grade.
Application:
Cost tier stratification separates premium positioning in pediatric and geriatric formulations from commodity throughput in mass-market beverages where fructose syrup substitution exerts persistent price pressure.
- Beverages:Sweetener and fermentation substrate for sports drinks and flavored waters. High-fructose corn syrup offers equivalent sweetness functionality at lower cost, forcing dextrose suppliers to defend position through non-GMO certification and clean-label positioning rather than price competition.
- Bakery Products:Humectant and browning agent controlling moisture retention and Maillard reaction kinetics. Industrial baking operations in India and Mexico are expanding capacity, creating localized demand for bulk food-grade material with consistent granulometry.
- Dairy Products:Cryoprotectant and texture modifier in ice cream and frozen desserts. Premium positioning in European clean-label dairy segments rewards identity-preserved corn sourcing with full traceability documentation.
- Confectionery:Hard candy and chocolate applications requiring precise crystallization control. Seasonal demand volatility and cocoa price correlation create working capital intensity for suppliers without forward contracting discipline.
Beverages command volume leadership. Bakery Products are climbing the fastest as industrial baking scales in emerging manufacturing clusters.
End User:
Customer type determines qualification protocols, with pharmaceutical companies imposing multi-year validation timelines that lock in supplier relationships and create switching costs unmatched in food channels.
- Food Industry:Industrial bakeries, confectionery manufacturers, and processed food operations purchasing through annual volume contracts. Procurement committees prioritize specification consistency and logistics reliability over purity differentiation.
- Beverage Industry:Carbonated soft drink and sports drink formulators with dual-source strategies balancing cost and supply security. Clean-label mandates from major brand owners are tightening non-GMO and identity-preserved sourcing requirements.
- Pharmaceutical Companies:Sterile formulation manufacturers requiring USP/EP dual-certification, endotoxin testing, and batch-specific CoA documentation. Hospital procurement consortia in India and Germany are bundling parenteral nutrition and dialysis solution tenders, compressing margins while rewarding multi-product portfolios.
- Nutraceuticals:Dietary supplement and functional food producers occupying a middle tier between food-grade commodity and pharmaceutical-grade premium. FSSAI and CDSCO alignment on elemental impurity limits is forcing domestic Indian refiners to upgrade purification capacity.
Pharmaceutical Companies anchor margin pools. Nutraceuticals represent the steepest expansion trajectory as functional food regulation converges with pharmaceutical standards.
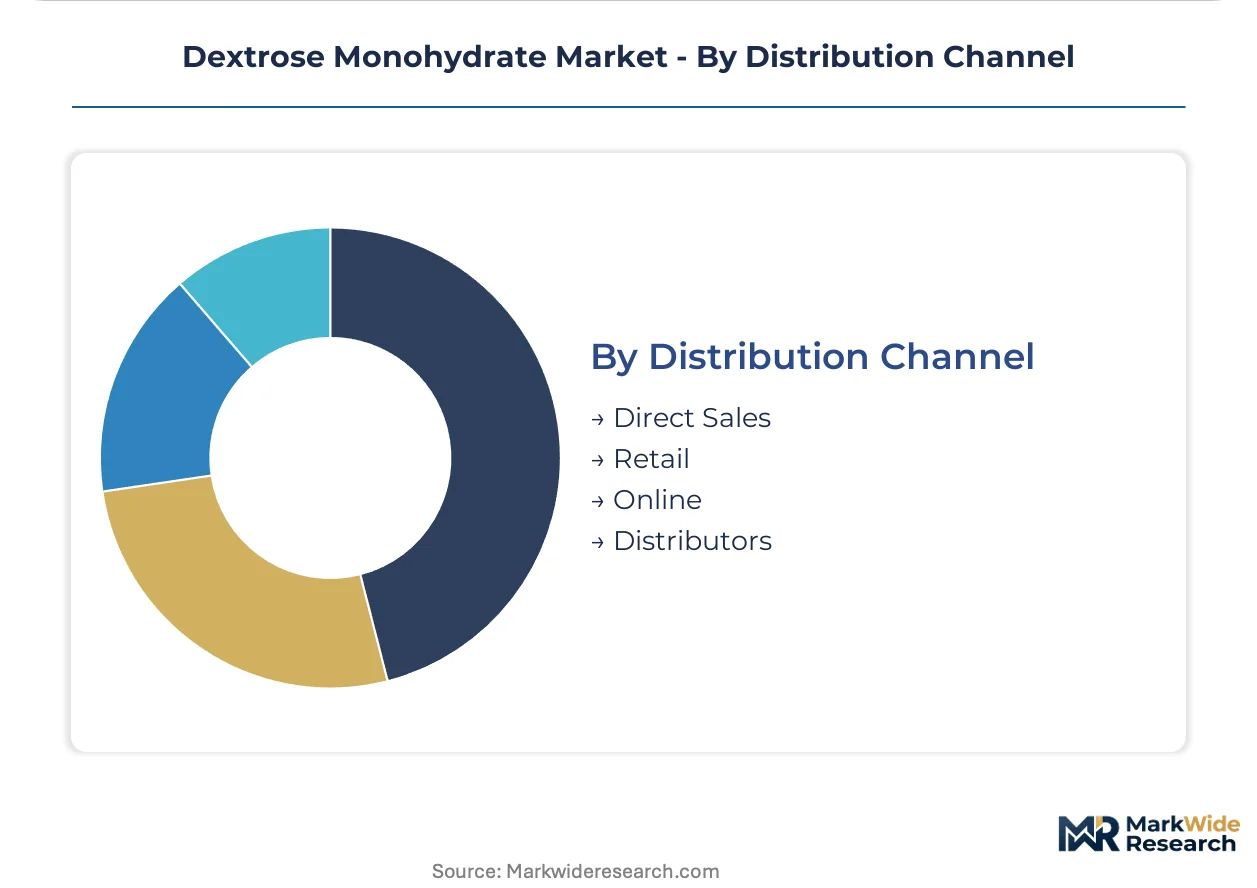
Distribution Channel:
Volume concentration favors direct sales relationships for pharmaceutical-grade material, while food-grade throughput flows through distributor networks with inventory risk transfer to intermediaries.
- Direct Sales:Long-term supply agreements between integrated wet-millers and pharmaceutical manufacturers, industrial bakeries, and beverage formulators. Contract structures include take-or-pay provisions and dedicated quality liaison teams.
- Retail:Small-format packaging for artisanal bakers, home confectioners, and specialty food producers. Premium positioning in European and North American natural food channels rewards organic and non-GMO certification.
- Online:E-commerce platforms serving nutraceutical formulators and small-batch food producers with rapid fulfillment requirements. Limited penetration in pharmaceutical channels due to cold-chain and documentation complexity.
- Distributors:Regional chemical and ingredient distributors carrying inventory risk for non-integrated refiners. Indian and Southeast Asian markets rely heavily on distributor networks with import duty exposure and currency hedging requirements.
Direct Sales dominate value capture. Online channels are expanding most quickly as small-batch formulators bypass traditional procurement minimums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn wet-milling clusters in the US Midwest anchor global pharmaceutical-grade dextrose supply, while government-backed production incentives in India are redrawing procurement geography for sterile formulation manufacturers.
United States
Hospital procurement consortia in Illinois and Ohio are consolidating parenteral nutrition tenders, concentrating purchasing power among dual-certified suppliers. FDA enforcement of USP-NF monograph compliance for injectable applications is tightening batch documentation requirements. The Cedar Rapids-Iowa City corridor hosts integrated wet-milling operations serving sterile dialysis solution manufacturers with captive corn crushing infrastructure.
Germany
Sterile formulation manufacturers in North Rhine-Westphalia are adopting continuous crystallization systems to compress batch cycle times. EMA's MDR framework mandates traceability documentation from starch source through final crystallization for medical device supply chains. The Cologne-Düsseldorf industrial cluster concentrates pharmaceutical-grade capacity with USP/EP dual-certification serving hospital networks across the Benelux region.
India
API parks in Andhra Pradesh and Gujarat are creating localized demand for excipient-grade material that bypasses import duty exposure. CDSCO alignment with ICH Q3D guidelines on elemental impurities is compelling domestic refiners to upgrade purification trains. Mumbai-Pune pharmaceutical manufacturing corridors are displacing import-reliant distributors from hospital procurement contracts through captive dextrose consumption.
China
Modified-starch derivative producers in Shandong Province are extending dextrose utility into functional food systems targeting glycemic response management. NMPA enforcement of pharmacopeial standards for intravenous solutions is tightening microbial specification compliance. The Yangtze River Delta fermentation feedstock clusters absorb industrial-grade volume for ethanol and organic acid production.
France
Clean-label formulation mandates from major European brand owners are tightening non-GMO and identity-preserved sourcing requirements for pediatric applications. ECHA REACH Annex XVII restrictions on residual solvents are narrowing specification windows for excipient-grade material. The Lestrem facility in northeastern France anchors European pharmaceutical-grade supply with dedicated quality liaison teams serving sterile formulation manufacturers.
Dextrose Monohydrate Market Vendor Landscape
Global majors compete with regional champions across certification tiers, with integrated wet-millers commanding pharmaceutical-grade margins while non-integrated refiners retreat to food-grade commoditization. The vendor base stratifies into three archetypes: corn-crushing conglomerates with captive starch supply, regional specialists with purification expertise, and distributor-dependent traders lacking crystallization assets. Dominant competitive moves include backward integration into identity-preserved corn sourcing and multi-year hospital tender bundling that locks in sterile formulation relationships.
Among North American agribusiness conglomerates, Archer Daniels Midland Company and Cargill, Incorporated exemplify the integrated wet-miller archetype with Midwestern corn crushing infrastructure sustaining cost-advantaged feedstock access. Roquette Frères occupies a position within the European pharmaceutical-grade specialist tier, anchoring dual-certified supply through northeastern French manufacturing concentration. Tate & Lyle represents the modified-starch adjacency strategy, extending dextrose utility into functional food systems through cyclodextrin and maltodextrin derivative portfolios.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Ingredion |
| Roquette Frères |
| Tate & Lyle |
| Tereos |
| Agrana |
| Gulshan Polyols Ltd |
| Belgosuc |
| Others |
Supply Flow & Price Mechanics
Corn wet-milling engineers concentrated in the US Midwest and northeastern France command wage premiums that widen spreads between pharmaceutical-grade and food-grade dextrose pricing tiers, with labor-cost differentials between these specialized crystallization facilities and commodity food-grade plants in Brazil or Southeast Asia translating directly into certification-grade price gaps.
Pricing Analysis
Input-cost pass-through from corn feedstock dominates dextrose monohydrate pricing, with US Midwest drought cycles and Black Sea grain flow disruptions transmitting immediately into contract renegotiations for non-integrated refiners lacking captive crushing infrastructure. Three-tier pricing structure across USP-certified pharmaceutical, FCC food-grade, and industrial fermentation tiers separates sterile formulation manufacturers paying traceability premiums from beverage producers substituting toward high-fructose corn syrup. Pricing pressure stems from fructose syrup substitution in mass-market sweetener applications, compressing dextrose margins in beverage channels. Industrial ethanol producers exhibit highest price sensitivity, while sterile dialysis solution manufacturers absorb premiums for dual-certified USP/EP material without volume elasticity.
Supply Chain Analysis
Pharmaceutical-grade dextrose supply rests on corn wet-milling clusters in the United States, France, and Belgium, where integrated processors with captive starch hydrolysis and multi-stage purification infrastructure control dual-certified capacity. Raw material dependencies center on identity-preserved non-GMO corn contracts, glucoamylase enzyme supply from Danish and Japanese specialty producers, and high-purity process water systems. Single-source vulnerability concentrates in the Lestrem-Cologne corridor, where USP/EP dual-certified sterile formulation supply funnels through three integrated facilities. Distribution runs through long-term direct sales agreements for pharmaceutical grade, while food-grade volume flows via regional chemical distributors carrying inventory risk and import duty exposure in Indian and Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in dextrose monohydrate hinges on enzymatic hydrolysis yield improvements and the premium-tier shift toward USP/EP dual-certified material for parenteral nutrition applications, with cost-down drivers in continuous crystallization technology widening spreads between integrated and non-integrated producers.
For Market Incumbents: Lock in sterile formulation relationships through multi-year hospital procurement tenders bundling parenteral nutrition, dialysis, and irrigation solutions before CDSCO-mandated ICH Q3D upgrades displace import-reliant distributors from Indian hospital networks. Backward integration into identity-preserved corn sourcing in the US Midwest and Black Sea regions defends against feedstock volatility threatening non-integrated refiners. Certification investment in continuous processing technology with embedded PAT sensors compresses batch cycle times and reduces quarantine inventory costs. For New Entrants and Emerging Players: The 40-60% price-point gap between pharmaceutical-grade and food-grade dextrose creates entry space for mid-tier nutraceutical specialists targeting FSSAI-aligned elemental impurity standards in Indian dietary supplement manufacturing. Target API parks in Andhra Pradesh and Gujarat where government-backed production incentives localize excipient demand and bypass import duty exposure. Go-to-market leverage rests on rapid CoA documentation turnaround and dedicated quality liaison teams matching hospital procurement committee requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated food-grade refiners in Southeast Asia and Latin America lacking purification infrastructure to meet tightening USP-NF monograph compliance. Long-term viability favors integrated wet-millers with corn crushing assets and multi-stage crystallization trains capable of grade-tier switching. Watch CDSCO enforcement consistency on ICH Q3D elemental impurity limits as the inflection signal determining whether domestic Indian refiners capture hospital procurement share or cede to import-dependent distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Crystallization Technology Deployment | Modular PAT-embedded systems enable real-time release testing that reduces quarantine inventory for sterile formulation manufacturers. |
| Identity-Preserved Corn Supply Contracting | Single-source traceability documentation satisfies EMA MDR framework requirements for European medical device supply chains. |
| Indian API Park Co-Location | Proximity to Andhra Pradesh and Gujarat bulk drug manufacturing clusters bypasses import duty exposure and captures PLI scheme benefits. |
| Dual-Certification Infrastructure Investment | USP/EP dual-compliant purification trains unlock hospital procurement tenders bundling parenteral nutrition and dialysis solutions. |
| Modified-Starch Derivative Expansion | Maltodextrin and cyclodextrin portfolios extend dextrose utility into functional food systems targeting glycemic response management. |
Methodological Framework
Bottom-up pharmaceutical and food manufacturing demand modeling reconciled against top-down corn wet-milling capacity tracking forms the analytical core of this study. Primary interviews with sterile formulation procurement managers, hospital pharmacy committee directors, corn wet-milling plant engineers, and Indian API park development officers combined with secondary validation against FDA USP-NF monograph filings, EMA MDR submission databases, CDSCO regulatory circulars, and SEC 10-K disclosures from listed agribusiness conglomerates. Trade data from customs records and Cefic starch industry reports provided cross-reference points for volume triangulation.
Input-output matrices mapping corn feedstock flows through enzymatic hydrolysis, crystallization yield curves, and end-use absorption by grade tier structured the forecast framework across the projection horizon. Segmentation dimensions modeled include product grade tier, application channel, end-user industry, and regional regulatory cluster. CAGRs derived from capacity utilization trends, hospital procurement tender volumes, and substitution elasticity estimates for fructose syrup in beverage applications. Forecast inputs incorporated PLI scheme disbursement trajectories in India and REACH Annex XVII solvent restriction enforcement patterns in Europe.
Caveats apply where pharmacopeial harmonization gaps between USP, EP, and IP standards, corn price volatility from climate-driven yield shocks, or abrupt fructose syrup substitution acceleration could materially shift the outlook. A small set of named triggers—CDSCO enforcement consistency, Midwest drought frequency, and European hospital procurement consolidation velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Non-Fish Omega 3 Supplements Market
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
North America Omega-3 Products Market
Nutritional Supplements
Vitamin B12 Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Asia-Pacific Nutraceutical Excipients Market
Nutritional Supplements
Dhea Supplement Market
Nutritional Supplements
Throat Lozenges Market