
 Europe Coffee Market | 2026-2036
Europe Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Coffee Market Analysis
The gap between premium single-origin offerings and mass-market commodity blends is shifting how European roasters allocate capital and build brand equity. Jacobs Douwe Egberts leverages its pan-European distribution network to sustain volume leadership in mainstream retail. Illycaffè SpA anchors its position through vertical integration into bean sourcing and quality grading systems. Lavazza competes aggressively in the office and automated vending segments with specialized equipment-coffee bundles.
Coffee comprises roasted seeds of Coffea arabica and Coffea canephora (robusta), processed through wet or dry methods to achieve moisture content below 12 percent, then roasted at temperatures between 180°C and 240°C to develop volatile aromatic compounds for beverage extraction. Ground coffee occupies the largest volume share in European households, though coffee pods capture disproportionate margin pools through convenience premiums and proprietary format lock-in. Specialty stores and online retail represent the fastest-growing distribution channels, reflecting direct-to-consumer engagement and subscription model expansion.
The EU Green Deal and EUDR deforestation regulations impose traceability mandates on supply chains, while REACH governs chemical residues in processing aids and packaging migration limits. EFSA guidelines on acrylamide and other process contaminants further tighten roasting protocols and quality thresholds. Stakeholders must monitor regulatory evolution on carbon border adjustments and packaging waste directives to anticipate compliance costs and sourcing restructuring requirements.
Market Dynamics
The EU Green Deal and EUDR deforestation regulations are forcing a fundamental restructuring of European coffee supply chains, compelling roasters to abandon opaque spot-market sourcing in favor of fully traceable, farm-level verification systems that carry significant compliance premiums.
Growth Catalysts
- Specialty café expansion:Germany's out-of-home sector and Italy's espresso culture are driving premiumization, with independent roasters capturing margin through direct-trade narratives and origin storytelling that commands price premiums over commodity blends.
- EUDR traceability mandates:The EU Deforestation Regulation is accelerating investment in blockchain-enabled supply chain mapping, creating competitive advantage for early adopters who can demonstrate farm-to-cup transparency before the 2025 enforcement deadline.
- Cold brew and RTD innovation:Nitrogen-infused formats and ready-to-drink coffee are displacing traditional hot-brew consumption among urban professionals in France and the Netherlands, opening new occasions beyond morning rituals.
Market Restraints
- Arabica price volatility:Brazilian frost events and Colombian labor disruptions expose European roasters to input cost swings that compress margins on fixed-price retail contracts, particularly for mid-tier supermarket brands.
- Supply concentration risk:Vietnam and Brazil collectively control over 60 percent of global robusta and arabica exports, creating vulnerability to simultaneous climate shocks that would strain European inventory buffers.
- REACH chemical compliance:Roasting byproducts including acrylamide face tightening EFSA thresholds, requiring capital-intensive process modifications and real-time monitoring systems that disadvantage smaller operators.
Strategic Opportunities
- Nordic sustainable certification:Sweden and Norway's consumer willingness to pay for carbon-neutral and organic labels exceeds southern European markets, creating white space for roasters who can credibly demonstrate regenerative agriculture partnerships.
- Office coffee service automation:Bean-to-cup machines with IoT-enabled predictive maintenance are displacing traditional filter systems in corporate settings, bundling hardware, software, and exclusive coffee supply into recurring revenue models.
- Packaging waste directive alignment:The EU's Single-Use Plastics Directive and emerging national extended producer responsibility schemes favor compostable pod formats and refillable systems that reduce per-unit environmental liability.
Industry Challenges
- Green coffee sourcing expertise:The shift from commodity traders to direct origin relationships demands agronomists and cupping specialists that European roasters struggle to recruit at scale, creating talent bottlenecks for quality-driven expansion.
- Legacy roasting infrastructure:Traditional drum roasters lack the data capture and energy efficiency profiles required for ESG reporting under CSRD, forcing difficult capex decisions between retrofitting and replacement.
- Certification audit backlogs:Rainforest Alliance and Fairtrade verification queues now exceed 18 months in key origin countries, delaying market access for new European entrants seeking differentiated positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Coffee Market |
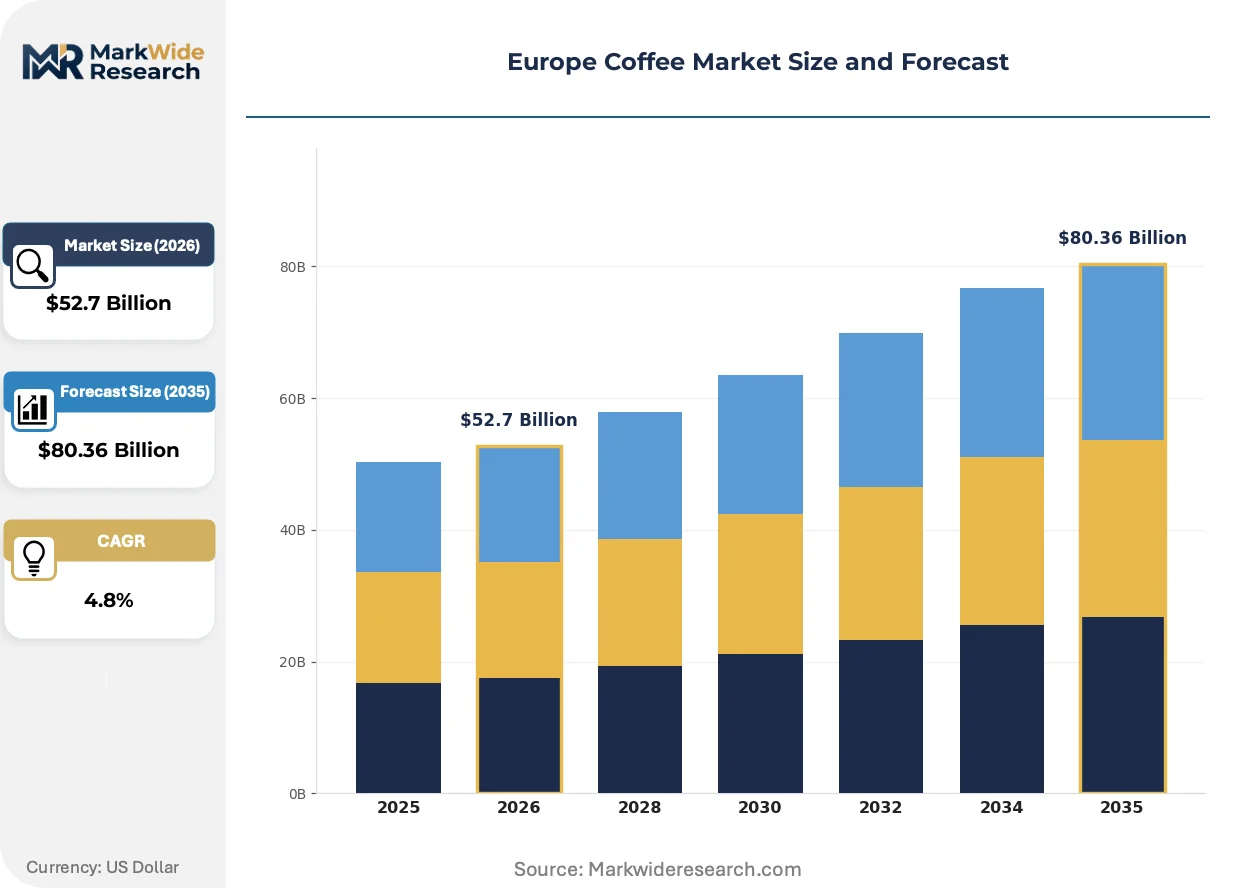
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Coffee, Instant Coffee, Coffee Pods, Whole Beans Roast Level: Light Roast, Medium Roast, Dark Roast, Espresso Roast Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Cafés Customer Type: Households, Offices, HoReCa, Retailers |
| Companies Covered | Starbucks Corporation, Costa Coffee, Nestlé SA, Melitta Group, Strauss Group, Jacobs Douwe Egberts (JDE Peet's), Illycaffè SpA, Tchibo GmbH, Luigi Lavazza SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Coffee Market Emerging Trajectories
Digital traceability infrastructure and precision roasting control systems are converging to transform how European coffee quality is defined, measured, and communicated to increasingly sophisticated buyers who demand granular provenance data.
Blockchain-enabled supply chain platforms are converging with satellite-based deforestation monitoring to create immutable farm-level documentation. Major German and Italian roasters are piloting these systems ahead of EUDR deadlines. This convergence is compressing the competitive advantage window for traceability, rendering basic certification insufficient for premium positioning.
The EU Green Deal's carbon border adjustment mechanism and REACH chemical governance are tightening roasting emissions standards and processing aid restrictions. Roasters must now quantify scope 3 agricultural emissions and migrate away from certain cleaning solvents. Medium-sized operators in France and Spain face the steepest compliance curves due to limited technical staffing.
Subscription-based direct-to-consumer models are displacing traditional supermarket distribution for specialty coffee in urban centers. Nordic consumers lead adoption, with Danish and Swedish roasters achieving 40 percent recurring revenue ratios. This channel shift is most visible among millennial professionals who prioritize convenience and origin transparency over price comparison.
Europe Coffee Market Segmentation
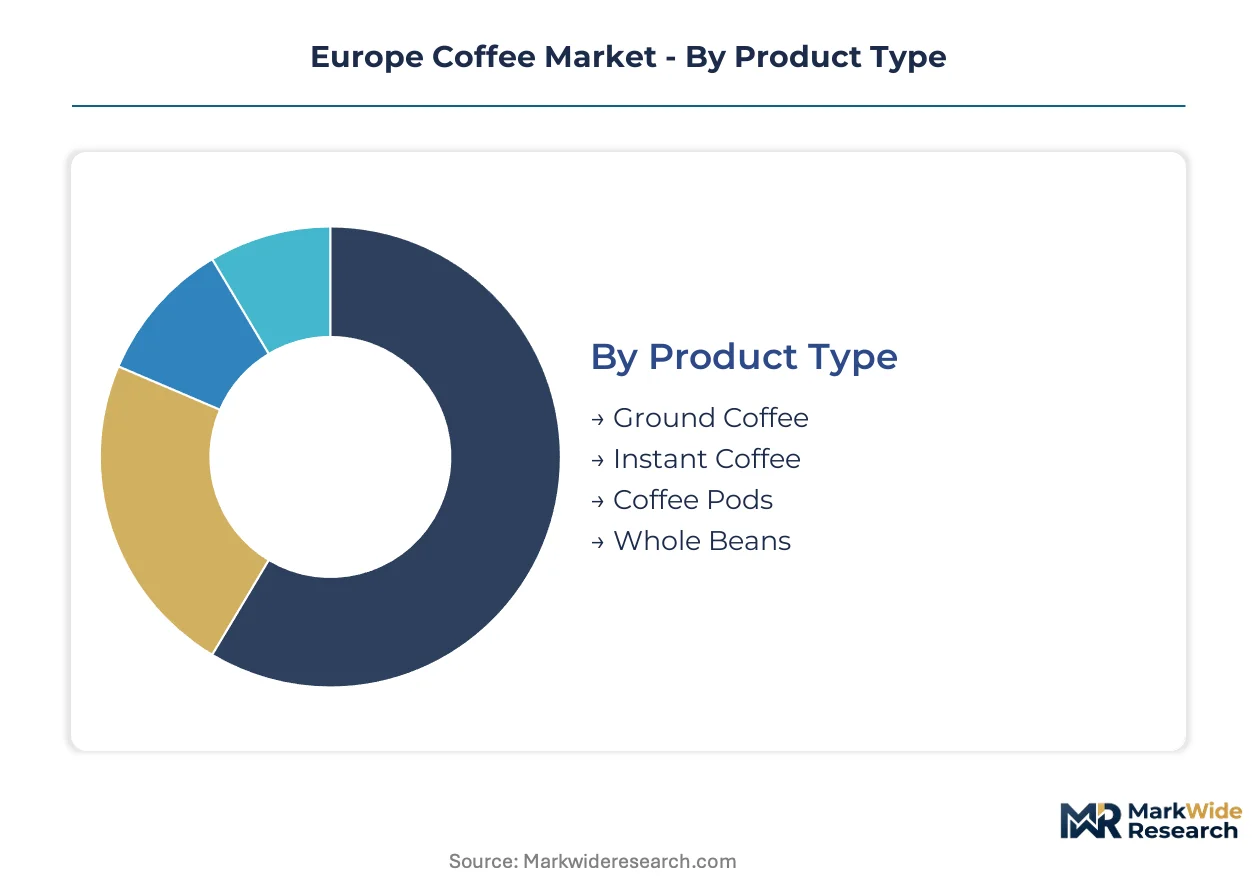
European coffee segmentation reveals how technology, convenience, and occasion-based consumption fragment purchasing behavior across distinct channel and product hierarchies. Roast specifications and distribution format choices determine margin capture and brand positioning strategies for roasters operating under tightening EUDR compliance requirements.
Product Type:
Grind specification and extraction format define the technical axis of product differentiation, with moisture retention, particle size distribution, and packaging atmosphere controlling shelf stability and flavor delivery.
- Ground Coffee:Medium-fine grind profiles optimized for drip filtration and French press extraction dominate household pantry staples across Germany and France. German discounters and French hypermarkets move the highest volumes through private-label programs that compete on price rather than origin narrative.
- Instant Coffee:Spray-dried and freeze-dried soluble extracts deliver convenience for workplace catering and travel occasions, with premium freeze-dried variants gaining traction in UK and Dutch urban markets where speed competes with quality expectations.
- Coffee Pods:Aluminum and compostable single-serve formats lock consumers into proprietary brewing ecosystems; Nespresso-compatible systems and licensed private-label alternatives fragment what was once a concentrated premium segment.
- Whole Beans:Unprocessed roasted seeds requiring domestic grinding equipment attract enthusiasts seeking freshness control and customizable extraction parameters, concentrated in Italian espresso culture and Nordic specialty café households.
Mature deployment sits with Ground Coffee. Newer deployment is concentrated in Coffee Pods.
Roast Level:
Time-temperature profiles during pyrolysis determine volatile aromatic compound development and solubility characteristics that match regional taste preferences and brewing equipment.
- Light Roast:Short roasting cycles preserve origin-specific acidity and terroir expression, appealing to Nordic specialty consumers and third-wave café operators who prioritize traceability storytelling over roast-induced caramelization.
- Medium Roast:Balanced development of Maillard reaction products delivers approachable flavor profiles for mainstream supermarket retail across France, Belgium, and the Netherlands, where consistency trumps exoticism.
- Dark Roast:Extended roasting diminishes acidity while amplifying bitter compounds and body, aligning with traditional preferences in Southern European markets and the Turkish diaspora communities in Germany.
- Espresso Roast:Specific profiles engineered for high-pressure extraction equipment emphasize crema stability and low oil migration, dominating Italian household consumption and professional café supply chains.
Volume concentration favors Medium Roast. Margin expansion is steepest in Light Roast.
Distribution Channel:
Channel selection determines customer acquisition economics, with inventory velocity, margin retention, and data capture capabilities varying sharply across format types.
- Online Retail:Direct-to-consumer subscriptions and marketplace storefronts enable origin storytelling and recurring revenue models, expanding most quickly among Danish and Swedish millennial professionals who prioritize convenience.
- Supermarkets:High-velocity mass retail moves standardized SKUs through price-promotion cycles, with German and French hard discounters commanding substantial volume through aggressive private-label positioning.
- Specialty Stores:Curated assortments and trained staff guidance support premium single-origin and micro-lot sales, concentrated in London, Amsterdam, and Berlin neighborhoods with high specialty coffee literacy.
- Cafés:Out-of-home consumption venues double as brand experience centers and wholesale account development tools, with Italian espresso bars and German bakery-café hybrids serving distinct occasion-based demand.
Volume leadership remains with Supermarkets. Channel expansion is climbing the fastest in Online Retail.
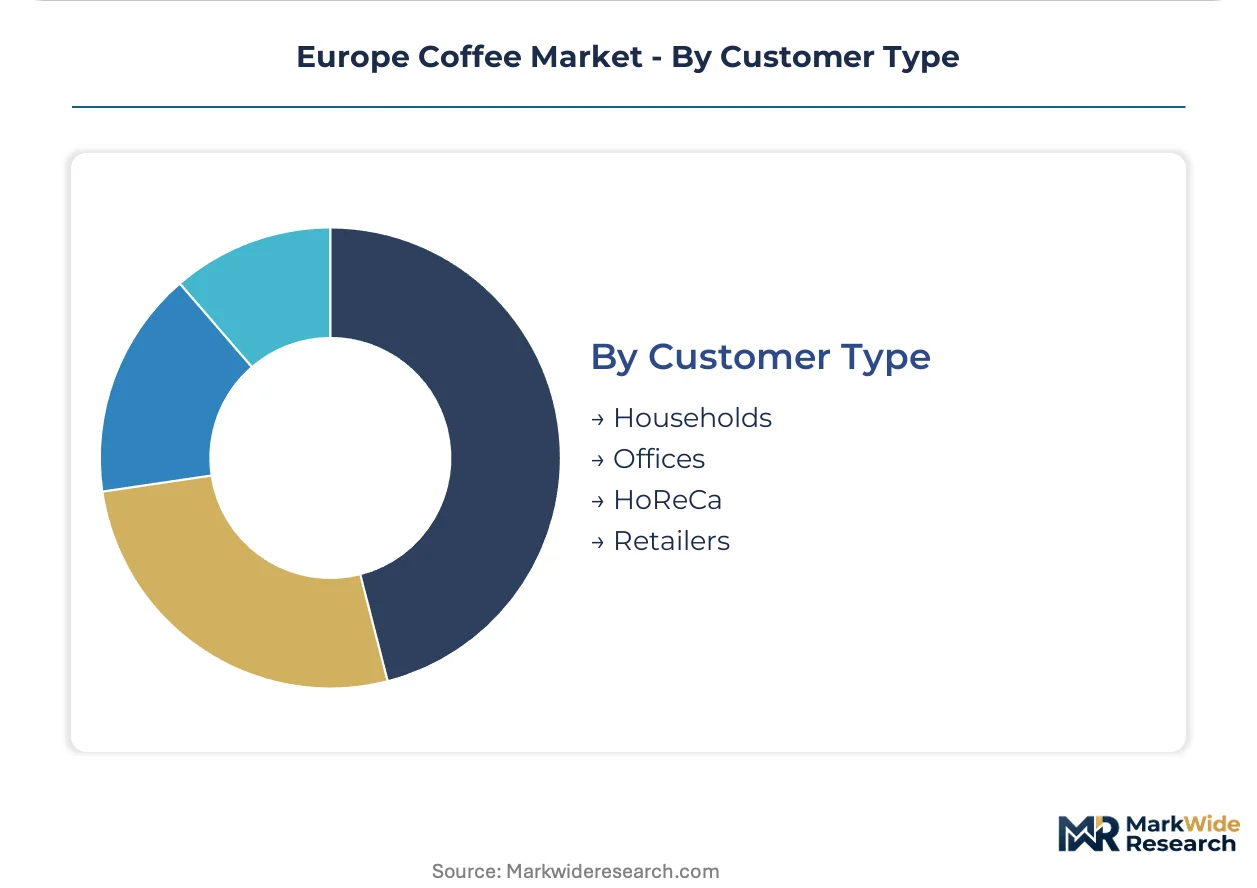
Customer Type:
End-use segmentation separates individual consumption from institutional procurement, with contract structures, quality specifications, and service requirements diverging substantially.
- Households:Individual consumers purchasing for domestic preparation drive volume across all product formats, with Italian and German households showing highest per-capita consumption and willingness to trade up for certified sustainable options.
- Offices:Corporate catering and break-room supply contracts favor automated bean-to-cup equipment with service bundling, displacing traditional filter systems in Dutch and UK workplace environments.
- HoReCa:Hotels, restaurants, and cafés demand consistent quality at scale with technical support and equipment provision, with independent roasters competing against Lavazza and JDE through localized service relationships.
- Retailers:Grocery and convenience store operators purchasing for resale impose stringent private-label specifications and traceability documentation under EUDR preparedness protocols.
Established demand concentration sits with Households. Emerging deployment is concentrated in Offices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European coffee trade through its historic Speicherstadt warehouse district and modern container terminals handling green bean imports from Brazil and Vietnam. The city's roasting clusters process substantial volumes for redistribution across northern Europe.
Germany
Out-of-home consumption drives premiumization in Berlin and Munich, where independent roasters command price premiums through direct-trade sourcing narratives. The country's national packaging regulator enforces extended producer responsibility schemes under the EU Single-Use Plastics Directive. Bremen's coffee exchange maintains price discovery functions for arabica and robusta futures traded by northern European buyers.
Italy
Espresso culture sustains household consumption of dark-roast blends concentrated in Milan and Turin manufacturing corridors. EFSA guidelines on acrylamide thresholds tighten roasting protocols for domestic producers exporting across southern Europe. Trieste's port infrastructure handles Illycaffè's vertical integration into quality grading systems and specialized logistics.
France
Parisian café terraces and bakery-café hybrids anchor out-of-home demand for medium-roast profiles suited to French press extraction. REACH chemical governance restricts processing aids in soluble coffee manufacturing based in the Hauts-de-France industrial zone. Lyon specialty stores pioneer subscription-based direct-to-consumer models displacing traditional supermarket distribution.
Netherlands
Amsterdam's trading houses and Utrecht roasting facilities serve as entry points for beans entering northwest European markets. The Dutch national environmental agency implements carbon border adjustment monitoring ahead of EU Green Deal enforcement deadlines. Rotterdam's automated port systems accelerate green coffee throughput for just-in-time roasting operations.
Sweden
Stockholm consumers demonstrate willingness-to-pay premiums for carbon-neutral and organic certifications exceeding southern European markets. The Swedish Chemicals Agency enforces stringent REACH compliance on packaging migration limits affecting pod format producers. Gothenburg specialty roasters achieve recurring revenue ratios approaching forty percent through subscription model penetration.
Europe Coffee Market Vendor Landscape
Premium-margin players sit above commodity-margin players across traceability certification and origin storytelling dimensions, with tiered competitive dynamics separating direct-trade specialists from volume-driven supermarket suppliers. The vendor base clusters around three strategic archetypes: pan-European distribution networks sustaining retail leadership, vertically integrated quality graders controlling bean sourcing, and automated equipment-coffee bundlers capturing office service contracts. Dominant competitive moves include strategic partnerships with origin-country cooperatives and portfolio diversification into cold brew and ready-to-drink formats.
Within the premium-tier vector, Illycaffè SpA exemplifies quality-centric positioning through its Trieste-based grading infrastructure, while Jacobs Douwe Egberts anchors mass-market retail through its Dutch-originated distribution scale. Luigi Lavazza SpA occupies the equipment-coffee bundling archetype targeting automated vending deployment. These three corporate structures represent contrasting margin capture strategies across European channel hierarchies.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Costa Coffee |
| Nestlé SA |
| Melitta Group |
| Strauss Group |
| Jacobs Douwe Egberts (JDE Peet's) |
| Illycaffè SpA |
| Tchibo GmbH |
| Luigi Lavazza SpA |
| Others |
Supply Flow & Price Mechanics
Blockchain-enabled traceability platforms are simultaneously elevating compliance costs and consolidating purchasing power among early-adopter roasters who can pass farm-level verification premiums to EUDR-aligned buyers. This technological shift compresses margins for commodity-dependent operators while rewarding integrated sourcing networks with pricing leverage.
Pricing Analysis
Origin-verification premiums anchor value-based pricing, with roasters commanding measurable markups for EUDR-compliant farm documentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and traceability depth. Cost compression in mid-tier supermarket blends is intensifying because Brazilian frost volatility and Vietnamese logistics disruptions expose fixed-contract roasters to margin erosion. German and French hard-discount consumers exhibit highest price sensitivity, while Nordic specialty subscribers demonstrate lowest elasticity.
Supply Chain Analysis
Green coffee supply rests on Brazilian arabica plantations, Vietnamese robusta estates, and Colombian high-altitude cooperatives as the three dominant origin nodes. Roasters draw from dried cherry processing infrastructure, ocean freight container networks, and Hamburg-Trieste-Rotterdam port handling systems as critical input dependencies. Single-source vulnerability concentrates around Vietnamese robusta for instant manufacturing and espresso blending. Distribution runs through pan-European roasting clusters with just-in-time redistribution to national retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's coffee sector sits in a technology-transition phase, with digital traceability infrastructure replacing paper-based certification and spot-market sourcing. Roasters must align capital allocation with this shift to capture compliance-driven margin pools.
For Market Incumbents: Extend blockchain-enabled origin mapping to preempt EUDR enforcement advantages before certification audit backlogs widen. Acquire cupping specialist talent and agronomist teams to defend against direct-trade specialists capturing premium shelf space. Prioritize retrofitting legacy drum roasters with energy-efficient data-capture systems to meet CSRD reporting thresholds.
For New Entrants and Emerging Players: Launch via subscription-based direct-to-consumer channels in Stockholm and Copenhagen where recurring revenue ratios exceed southern European benchmarks. Target office coffee service automation in Dutch and UK corporate environments where bean-to-cup equipment bundling displaces traditional filter contracts. Penetrate through compostable pod formats aligned with EU Single-Use Plastics Directive compliance.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated quality graders given EUDR traceability mandates and carbon border adjustment monitoring. Long-term viability favors roasters with captive supply relationships and in-house grading infrastructure over commodity traders. Watch Nordic certification penetration rates as the inflection indicator for sustainable premium pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Trade Origin Partnerships | Secures EUDR-compliant farm documentation ahead of enforcement deadlines. |
| Blockchain Supply Chain Mapping | Creates immutable traceability records for premium positioning against commodity blends. |
| Compostable Pod Format Development | Aligns packaging portfolios with EU Single-Use Plastics Directive requirements. |
| Office Equipment-Coffee Bundling | Captures recurring revenue through IoT-enabled bean-to-cup service contracts. |
| Carbon-Neutral Certification Investment | Exploits Nordic willingness-to-pay premiums exceeding southern European markets. |
Methodological Framework
Trade databases, customs records, and EUDR regulatory filings formed the secondary backbone for supply chain mapping and compliance cost estimation. Primary interviews with green coffee procurement directors, roasting plant managers, specialty café operators, and sustainability certification auditors validated sourcing narratives and pricing dynamics. Bottom-up volume modeling across grind specifications, roast levels, and distribution channels triangulated against top-down trade flow analysis.
Historical trendline analysis of green coffee import volumes and roasted product shipments informed baseline calibration across the projection horizon. Segmentation dimensions modeled include product format, roast specification, distribution channel, and customer type with regional regulatory cluster overlays. CAGRs were derived from trend extrapolation adjusted for EUDR implementation pacing and carbon border adjustment phasing. Forecast inputs incorporated arabica-robusta price ratio volatility and certification adoption curve assumptions.
The model assumes a particular technology adoption path; alternative pathways for blockchain traceability platform deployment would alter the outlook. Forecasts reflect assumptions regarding EUDR enforcement consistency, REACH chemical threshold stability, and Nordic premium pricing sustainability. A small set of named triggers warrants ongoing watch: Brazilian climate events, Vietnamese export policy shifts, and EU packaging waste directive amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Global Coffee Machine Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Raw Coffee Beans Market
Coffee
Butter Coffee Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
Chewable Coffee Market
Coffee
Coffee Cherry Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Tea and Coffee Bags Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Coffee Bottle Market
Coffee
Encapsulated Caffeine Market
Coffee
China Coffee Market
Coffee
US Coffee Machine Market
Coffee
High Protein Coffee Market