
 Europe Mobile Cloud Market | 2026-2036
Europe Mobile Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mobile Cloud Market Foresight
Project finance and leasing arrangements for hyperscale data centers is fragmenting competitive dynamics across the Europe Mobile Cloud Market. Deutsche Telekom leverages its fiber infrastructure and sovereign cloud certifications to anchor enterprise demand in German-speaking markets. Orange competes through edge computing nodes positioned across France, Spain, and Poland. OVHcloud specializes in GDPR-compliant bare-metal offerings that appeal to public sector buyers seeking data localization.
Europe Mobile Cloud denotes distributed computing architectures where storage, processing, and application delivery occur via remote server infrastructure accessed through cellular or Wi-Fi networks, typically operating with latency thresholds below 50 milliseconds for real-time workloads. Its primary commercial purpose is enabling scalable, location-independent access to enterprise software and data analytics without on-premises hardware investment. Infrastructure as a Service dominates capital deployment as enterprises migrate legacy workloads, while Function as a Service represents the fastest-expanding margin pool for vendors serving event-driven application development. Hybrid Cloud deployments are gaining structural importance among financial services firms requiring burst capacity alongside on-premises core systems.
GDPR enforcement by national data protection authorities, the EU AI Act's risk classification framework, and CE marking requirements for telecommunications equipment collectively shape product roadmaps and market access conditions across member states. EMA guidelines on clinical data hosting further direct cloud procurement patterns in pharmaceutical hubs such as Basel and Cambridge. Stakeholders must evaluate sovereign cloud partnerships before the next wave of sector-specific compliance mandates crystallizes procurement criteria.
Market Dynamics
Sovereign cloud mandates from the EU AI Act and GDPR enforcement are fragmenting vendor architectures across member states, compelling hyperscalers to restructure data residency protocols and localize infrastructure ownership.
Growth Catalysts
- GDPR data localization:German healthcare providers and French financial institutions now require certified sovereign infrastructure, expanding procurement for EU-based cloud operators.
- Edge computing deployment:Manufacturing facilities in the Netherlands and Belgium are installing cellular-connected edge nodes to process industrial IoT streams below 20-millisecond latency thresholds.
- EMA clinical data hosting:Pharmaceutical clusters in Basel and Cambridge must maintain trial records within EU jurisdiction, directing cloud spend toward compliant providers.
Market Restraints
- Energy input volatility:Nordic and German data centers face electricity cost swings from natural gas dependency, compressing margin forecasts for compute-intensive workloads.
- Hyperscaler supply concentration:Three non-EU providers control over 60% of foundational IaaS capacity, creating procurement risk for defense and public sector buyers under sovereignty scrutiny.
- Cross-border data friction:Schrems II rulings invalidate Privacy Shield successor mechanisms, forcing contractual renegotiation for transatlantic analytics pipelines.
Strategic Opportunities
- Polish and Romanian enterprise lag:These markets show 40% lower cloud penetration than Western European peers, presenting first-mover advantage for localized sales channels.
- AI Act risk-tier compliance:High-risk AI system classification creates mandatory audit trails, opening managed services revenue for GDPR-certified operators.
- 5G network slicing convergence:Telecommunications infrastructure in Spain and Italy now supports dedicated mobile cloud slices for autonomous vehicle telemetry and remote surgery applications.
Industry Challenges
- DevSecOps talent scarcity:European enterprises report 18-month average hiring timelines for engineers fluent in both Kubernetes orchestration and GDPR Article 32 technical measures.
- Legacy mainframe integration:German insurers and Italian banks require middleware layers to connect 1970s-era core systems with containerized cloud workloads, extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mobile Cloud Market |
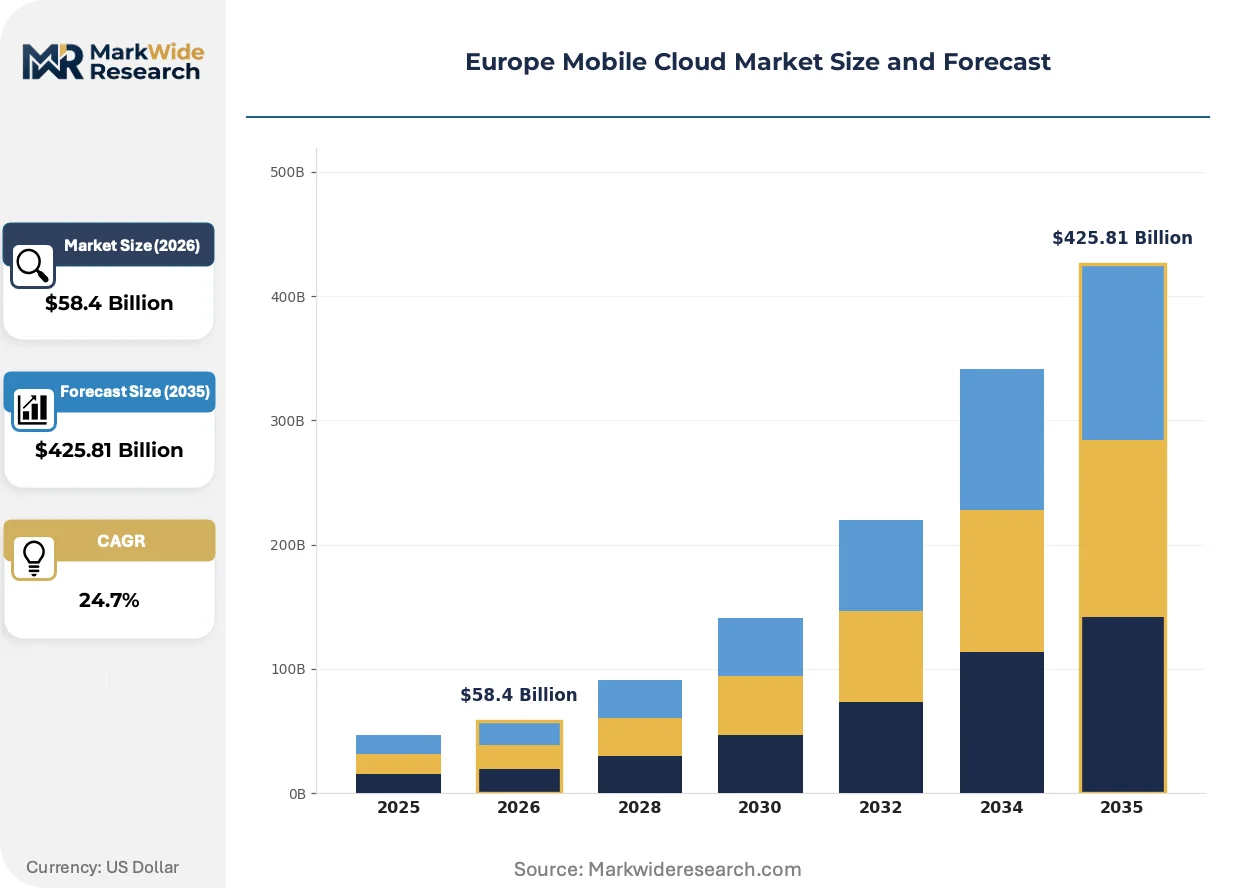
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $425.81 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud, Distributed Cloud Application: Real-time Analytics, Mobile Backend as a Service, Collaboration Tools, Content Delivery, Streaming Services End User Industry: Telecommunications, Manufacturing, Financial Services, Education, Transportation Service Model: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service, Container as a Service |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Deutsche Telekom, OVHcloud, SAP, Orange, IBM, Oracle, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mobile Cloud Market Shifts & Advancements
Multi-cloud orchestration tools and sovereign infrastructure certifications are reconfiguring how European enterprises evaluate vendor relationships, shifting procurement criteria from price-per-compute to compliance-verified resilience.
Confidential computing using hardware-based trusted execution environments is migrating from experimental pharmaceutical research to production financial services deployments. Dutch banks and Luxembourg wealth managers are adopting Intel SGX and AMD SEV technologies for privacy-preserving analytics on pooled datasets. This migration from pilot to production is compressing competitive differentiation around data-in-use protection rather than encryption-at-rest capabilities.
The EU AI Act's risk classification framework now mandates conformity assessments for high-risk AI systems deployed via cloud infrastructure. Healthcare diagnostic algorithms and credit-scoring models require documented technical documentation and human oversight protocols. German medical device manufacturers and French fintech operators are restructuring product roadmaps to embed these requirements before the 2026 enforcement deadline.
Consumption-based billing models are displacing reserved instance commitments among mid-market enterprises. Italian retail chains and Spanish logistics providers now prefer pay-per-query analytics over fixed-capacity contracts, forcing vendors to reprice storage and compute as unbundled metered services. This behavioral shift is most visible in Southern European markets where capital expenditure constraints outweigh latency sensitivity.
Europe Mobile Cloud Market Segmentation
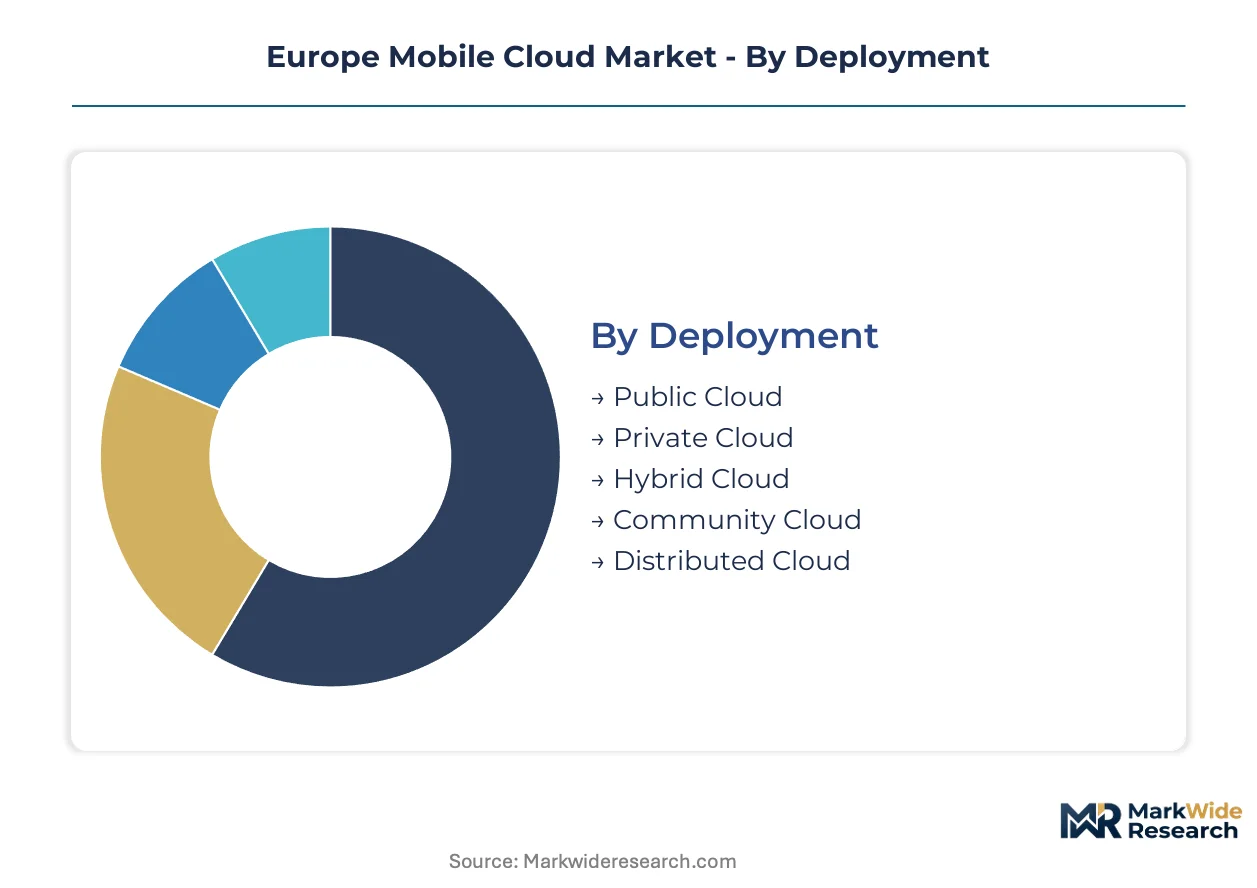
European enterprises evaluate mobile cloud procurement through four intersecting lenses: deployment architecture, application workload, industry compliance requirements, and service abstraction layers. Each dimension carries distinct regulatory weight under GDPR and the EU AI Act, reshaping how vendors structure sovereign-certified offerings across member states.
Deployment:
The use-case spectrum spans burst-capacity development environments to mission-critical systems requiring jurisdictional control over data residency.
- Public Cloud:Shared infrastructure delivers elastic compute pools with sub-hour provisioning. German retail chains and Dutch logistics operators favor this model for seasonal demand spikes where data classification permits multi-tenant architectures.
- Private Cloud:Dedicated single-tenant environments satisfy Article 32 GDPR technical measures through hardware isolation. French defense contractors and Swiss pharmaceutical manufacturers mandate this architecture for clinical trial data and classified project files.
- Hybrid Cloud:Orchestrated workload portability between on-premises and remote infrastructure. Italian banks deploy this model to retain core banking systems locally while bursting customer analytics to compliant cloud nodes.
- Community Cloud:Shared infrastructure restricted to organizations with common compliance profiles. Nordic healthcare consortiums and Benelux research universities utilize this deployment for pooled genomics datasets under harmonized data processing agreements.
- Distributed Cloud:Geographically dispersed micro-datacenters extending cloud services to edge locations. Spanish autonomous vehicle testbeds and Finnish industrial IoT networks deploy these nodes to meet sub-20 millisecond latency thresholds for real-time telemetry.
The dominant share belongs to Hybrid Cloud, while Distributed Cloud is closing the gap fastest as edge computing requirements proliferate across manufacturing and mobility sectors.
Application:
Cost tier differentiation separates high-frequency transactional workloads from batch-processed content pipelines.
- Real-time Analytics:Stream processing engines ingesting cellular telemetry and sensor feeds for instantaneous decision support. Luxembourg wealth managers and Frankfurt trading desks deploy these applications for millisecond-sensitive risk calculations on pooled market data.
- Mobile Backend as a Service:Pre-configured server infrastructure abstracting authentication, database, and push notification management. French fintech startups and Berlin e-commerce ventures accelerate time-to-market through these managed middleware layers.
- Collaboration Tools:Synchronous document editing and video conferencing platforms with EU data residency guarantees. Belgian professional services firms and Austrian public administrations procure these applications under strict procurement frameworks mandating local hosting.
- Content Delivery:Caching and acceleration networks optimizing media distribution across heterogeneous cellular and Wi-Fi topologies. Italian broadcasters and Spanish streaming platforms utilize these services to reduce origin server load during peak consumption windows.
- Streaming Services:Continuous media transmission with adaptive bitrate protocols for variable network conditions. Central European music platforms and Nordic gaming operators deploy these applications with strict latency budgets to maintain quality-of-experience metrics.
Real-time Analytics commands the premium pricing tier, though Mobile Backend as a Service is expanding most quickly among venture-backed software developers seeking operational leverage.
End User Industry:
Customer type segmentation reveals divergent procurement maturity between regulated incumbents and digitally-native challengers.
- Telecommunications:Network operators leveraging cloud-native infrastructure for 5G core virtualization and network slicing orchestration. Deutsche Telekom and Orange deploy these architectures to monetize dedicated mobile cloud slices for enterprise verticals.
- Manufacturing:Industrial facilities integrating cellular-connected edge nodes for predictive maintenance and quality control. Dutch semiconductor fabs and Polish automotive suppliers process machine vision streams through localized cloud infrastructure.
- Financial Services:Banks and insurers subject to ECB guidance on cloud outsourcing and DORA operational resilience requirements. German insurers and French asset managers maintain hybrid deployments balancing burst capacity with on-premises core system integrity.
- Education:Universities and research institutions managing collaborative platforms and high-performance computing workloads. Cambridge and Basel pharmaceutical research clusters utilize sovereign-certified infrastructure for cross-border academic partnerships.
- Transportation:Logistics providers and mobility operators processing fleet telemetry and autonomous navigation data. Belgian port authorities and Italian highway operators deploy edge-cloud architectures for real-time traffic optimization.
Financial Services retains the largest committed cloud spend, while Manufacturing is gaining share fastest as Industry 4.0 investments accelerate across Eastern European production corridors.
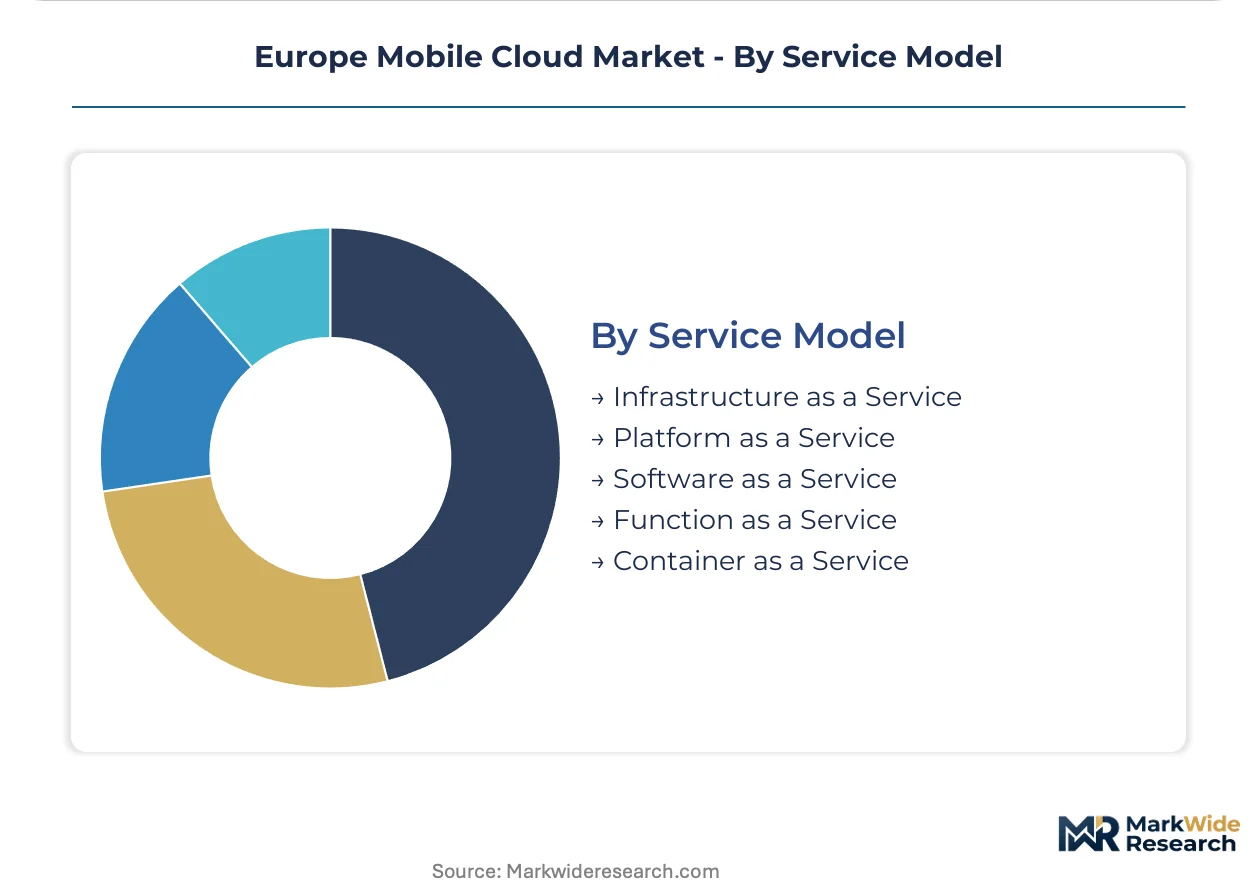
Service Model:
Margin structure varies dramatically across abstraction layers, from commoditized compute commodities to high-value managed development environments.
- Infrastructure as a Service:Raw compute, storage, and networking resources provisioned through API-driven interfaces. Enterprises migrating legacy workloads from German and French data centers represent the core demand pool for this foundational layer.
- Platform as a Service:Application development frameworks with pre-integrated middleware and database services. Parisian software houses and Munich industrial IoT developers utilize these environments to accelerate containerized deployment pipelines.
- Software as a Service:End-user applications delivered through subscription licensing with zero infrastructure management. Healthcare providers across the Netherlands and Spain procure electronic health record systems through this model under strict EMA and national health authority guidelines.
- Function as a Service:Event-driven compute executing code snippets in response to triggers without persistent server allocation. This model exhibits the steepest expansion trajectory among European developers building microservices architectures for variable workloads.
- Container as a Service:Managed Kubernetes orchestration abstracting cluster provisioning and scaling operations. Fintech operators in London and Dublin leverage these platforms for portable, multi-cloud deployments spanning EU and UK jurisdictions.
Infrastructure as a Service absorbs the greatest capital deployment, though Function as a Service is climbing the fastest as event-driven architectures displace monolithic application patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act and GDPR enforcement are redirecting procurement budgets toward certified sovereign infrastructure, with national data protection authorities imposing divergent technical standards that favor localized operators over pan-European deployments.
Germany
Healthcare providers in Berlin and Munich are migrating patient records to GDPR-certified sovereign clouds under Bundesdatenschutzgesetz mandates. The Federal Office for Information Security (BSI) maintains strict certification protocols for critical infrastructure operators. Frankfurt's financial district anchors hybrid cloud demand as Deutsche Börse participants require sub-millisecond latency for algorithmic trading platforms.
France
French defense contractors and aerospace clusters in Toulouse now mandate data localization under Military Programming Law provisions. ANSM and CNIL coordinate oversight of health data hosting for pharmaceutical research in the Paris-Saclay corridor. Orange leverages its metropolitan fiber footprint to deliver edge computing nodes for autonomous vehicle testing in Lyon.
Netherlands
Amsterdam's trading infrastructure and Rotterdam port logistics drive real-time analytics workloads requiring sub-20-millisecond latency. The Dutch Authority for Digital Infrastructure enforces GDPR Article 32 technical measures for financial services cloud outsourcing. Eindhoven's semiconductor fabs deploy distributed cloud nodes for predictive maintenance on EUV lithography equipment.
Switzerland
Basel's pharmaceutical research clusters maintain clinical trial data within EU jurisdiction per EMA guidelines, with Swissmedic coordinating parallel compliance requirements. Swiss banks in Geneva and Zurich adopt confidential computing for privacy-preserving analytics on cross-border wealth management datasets. The Federal Act on Data Protection mandates contractual safeguards that exceed standard GDPR processor agreements.
Poland
Warsaw-based enterprises exhibit 40% lower cloud penetration than Western European peers, creating first-mover opportunities for localized sales channels. The Polish Financial Supervision Authority (KNF) implements DORA-aligned operational resilience requirements for banking cloud migrations. Kraków's shared services centers and Wrocław's automotive suppliers are installing edge nodes for Industry 4.0 quality control systems.
Europe Mobile Cloud Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure concentrated among telecommunications incumbents and hyperscale platforms. Three non-EU providers dominate foundational IaaS capacity, while EU-based operators capture sovereign-certified segments through data residency guarantees. Strategic archetypes include fiber-anchored telecom clouds, GDPR-specialist bare-metal providers, and platform-integrated software vendors. Competitive moves center on sovereign cloud certification acquisition and edge node densification in manufacturing corridors.
Within the telecommunications-anchored tier, Deutsche Telekom and Orange exemplify infrastructure leverage strategies, with the former utilizing German fiber assets and the latter deploying edge computing nodes across Southern European markets. OVHcloud occupies a position as a GDPR-native specialist, appealing to public sector buyers through bare-metal sovereignty guarantees. These three entities represent distinct responses to regulatory fragmentation: network asset monetization, geographic edge densification, and compliance-native architecture.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Deutsche Telekom |
| OVHcloud |
| SAP |
| Orange |
| IBM |
| Oracle |
| Others |
Supply & Pricing Matrix
Overcapacity in Nordic data center regions compresses margin forecasts for compute-intensive workloads while simultaneously forcing suppliers toward extended financing terms and sovereign certification investments. German and French enterprises now demand BSI and ANSSI-certified infrastructure, creating pricing power for compliant operators and cost penalties for non-certified alternatives.
Pricing Analysis
Certification level creates the primary spread between infrastructure tiers, with GDPR-sovereign and EU AI Act-compliant deployments commanding substantial premiums over standard multi-tenant offerings. Three-tier pricing structure separates sovereign-certified bare-metal from hybrid-managed and standard public cloud tiers. Pricing pressure stems from electricity cost volatility in German and Nordic markets, compressing margins for hyperscale operators. Mid-market enterprises in Southern Europe exhibit highest price sensitivity, preferring consumption-based billing over reserved commitments, while defense and pharmaceutical buyers prioritize compliance over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now anchor procurement relationships as hyperscalers restructure vendor agreements to manage capital intensity. Hardware concentration rests on Taiwan, South Korea, and USA for advanced semiconductors powering confidential computing and edge nodes. Energy inputs draw from Norwegian hydroelectric, French nuclear, and German natural gas-dependent grids. Single-source vulnerability in advanced GPU supply creates procurement risk for AI training workloads. Distribution runs through telecommunications incumbents with fiber assets, direct enterprise sales forces, and systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. Switching costs for sovereign-certified infrastructure exceed eighteen months for financial services and pharmaceutical enterprises.
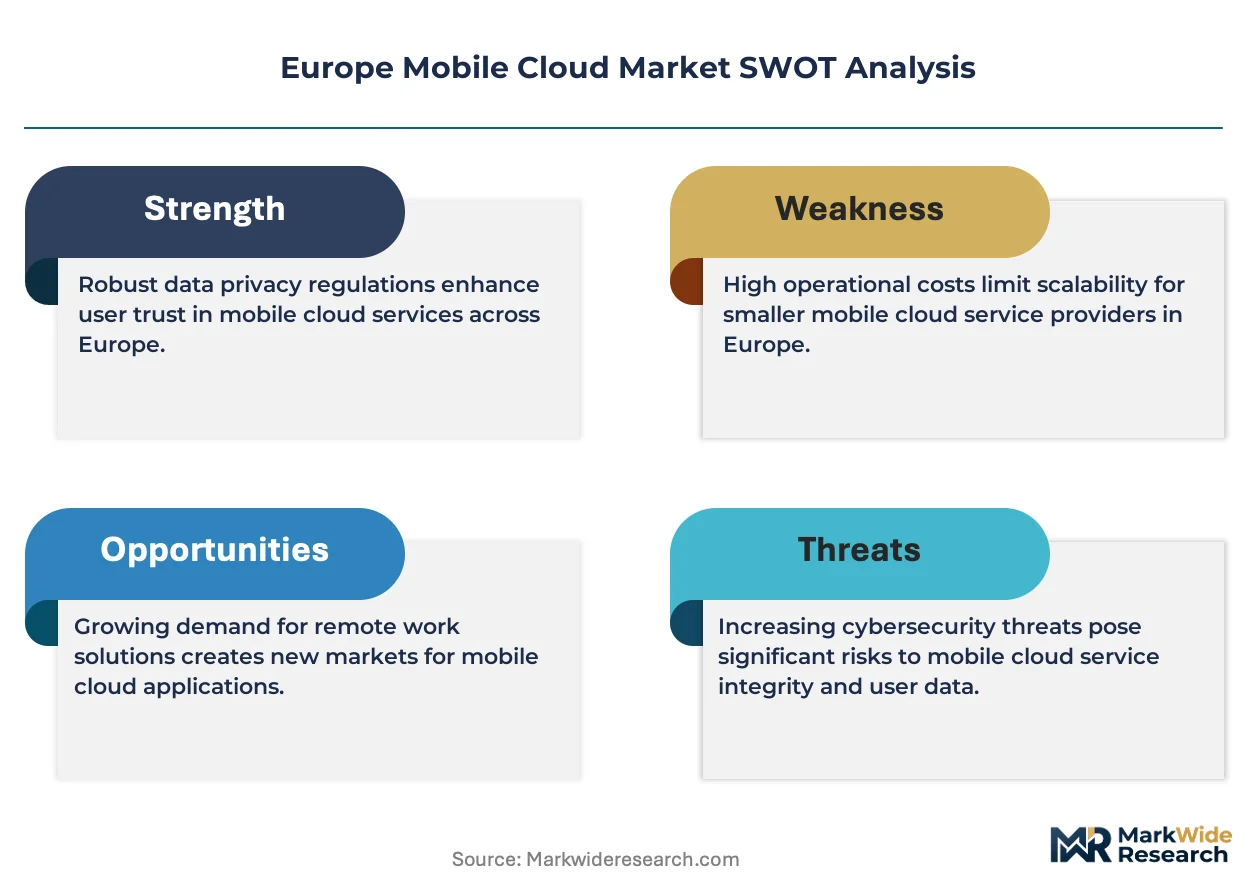
For Market Incumbents: Entrench competitive position through accelerated sovereign cloud certification acquisition across German BSI, French ANSSI, and Dutch Authority for Digital Infrastructure frameworks. Invest in edge node densification along Polish and Romanian manufacturing corridors before sector-specific AI Act mandates crystallize procurement criteria. Vertical integration into renewable energy sourcing mitigates electricity cost volatility threatening margin stability. For New Entrants and Emerging Players: Mid-market manufacturing enterprises in Poland and Romania represent the most penetrable entry point, with cloud penetration forty percent below Western European peers. Target sovereign-certified bare-metal offerings for public sector buyers in Benelux and Nordic markets where GDPR enforcement is most stringent. Partner with telecommunications operators possessing existing fiber infrastructure to bypass capital-intensive network buildouts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among GDPR-native operators with established public sector relationships and multi-year framework agreements. Long-term viability favors entities with demonstrated sovereign certification maintenance capabilities and localized data center ownership structures. Monitor AI Act enforcement timelines and national data protection authority penalty patterns as inflection indicators for compliance-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | BSI and ANSSI credentials unlock German defense and French aerospace procurement frameworks. |
| Edge Node Densification | Cellular-connected micro-datacenters in Polish automotive corridors capture Industry 4.0 workloads. |
| Confidential Computing Deployment | Intel SGX and AMD SEV adoption differentiates financial services offerings in Dutch and Luxembourg markets. |
| Renewable Energy Sourcing | Nordic hydroelectric and French nuclear power agreements stabilize electricity cost exposure. |
| 5G Network Slicing Integration | Dedicated mobile cloud slices for autonomous vehicle telemetry create Spanish and Italian revenue streams. |
Research Methodology
A spread of perspectives from cloud infrastructure executives, data center operations directors, enterprise IT procurement officers, and telecommunications network planners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC filings from hyperscale operators, EU regulatory databases tracking GDPR enforcement actions, and national data protection authority penalty registers. Bottom-up triangulation across deployment architecture segments and top-down validation against telecommunications capex disclosures anchored the analytical framework.
Demand-supply balance modeling across sovereign certification tiers, edge computing capacity, and enterprise workload migration patterns structured the projection methodology. Segmentation dimensions incorporated deployment architecture, service abstraction layer, end-user industry compliance requirements, and regional regulatory intensity. CAGRs derived from adoption curve analysis and infrastructure investment trajectories. Forecast inputs included electricity cost scenarios for German and Nordic markets and AI Act implementation timelines across member states.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial production, energy price volatility, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding sovereign certification adoption rates and hyperscaler localization investments. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Commerce Cloud Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Virtual Machines Market
Cloud Computing
Global Cloud Migration Market
Cloud Computing
Cloud API Market
Cloud Computing
Global Cloud Business Email Market
Cloud Computing
India Cloud Computing Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
AI Platform Cloud Service Market
Cloud Computing
Japan Cloud Computing Market
Cloud Computing
Nigeria Cloud Computing Market
Cloud Computing
North America Mobile Cloud Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
Global Cloud Collaboration Market
Cloud Computing
Cloud Based Backup Services Market