
 Global Cloud-Native Software Market | 2026-2036
Global Cloud-Native Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud-Native Software Market Foresight
Capital-intensity divergence between hyperscale infrastructure operators and specialized platform vendors is redrawing competitive boundaries in cloud-native software. Amazon Web Services leverages its global data center footprint to dominate container orchestration workloads. Microsoft Corporation anchors enterprise trust through deep Azure Kubernetes Service integration with existing Office 365 deployments. Red Hat competes via its open-source subscription model, sustaining margin pools in hybrid cloud middleware.
Cloud-native software denotes applications architected as microservices, packaged in containers, and dynamically orchestrated across distributed infrastructure, typically leveraging Kubernetes for automated deployment, scaling, and failover management. These systems eliminate OS-level dependencies through containerization, enabling portable runtime environments across heterogeneous infrastructure. Public cloud deployment models command the largest revenue share due to elastic consumption economics, while multi-cloud configurations represent the fastest-expanding segment as enterprises seek vendor-agnostic resilience. Container orchestration solutions capture disproportionate margin pools because they sit at the control plane layer, whereas serverless computing segments attract developer-centric volume growth.
FDA guidelines on software-as-a-medical-device, EU GDPR data residency mandates, and China's GB standards for cloud service security classification collectively shape product architecture and market access pathways. GDPR's cross-border data transfer restrictions force vendors to engineer region-locked Kubernetes clusters, adding compliance cost layers. Stakeholders must monitor whether emerging sovereign AI regulations fragment container registry standards and require country-specific certification pipelines.
Market Dynamics
Container orchestration platforms are consolidating control over enterprise IT budgets as organizations dismantle monolithic legacy systems. Kubernetes distributions now function as the primary abstraction layer between application workloads and underlying infrastructure, redistributing vendor power toward platform-native ecosystems.
Growth Catalysts
- EU AI Act compliance mandates:European financial institutions must deploy auditable, explainable AI systems. Cloud-native architectures provide the granular logging and version control required for algorithmic accountability.
- Microservices decomposition:Payment processors are fragmenting core banking functions into containerized services. This modularization enables independent scaling of high-throughput transaction pathways during peak load periods.
- Frankfurt financial cluster concentration:Germany's systemically important banks are standardizing on multi-cloud Kubernetes configurations. Their procurement decisions cascade through European banking consortia, accelerating platform adoption continent-wide.
Market Restraints
- Specialized engineering talent scarcity:Site reliability engineering and Kubernetes administration skills command premium compensation. Smaller enterprises cannot sustain competitive recruitment against hyperscale operators.
- Cross-border data transfer friction:GDPR's Schrems II ruling invalidated the Privacy Shield framework. Vendors must provision region-locked infrastructure, duplicating operational overhead across sovereignty zones.
- Legacy COBOL integration complexity:Core banking systems running decades-old code resist containerization. Parallel runtime environments inflate total cost of ownership during extended migration windows.
Strategic Opportunities
- Edge-native workload expansion:Manufacturing automation and autonomous vehicle telemetry require sub-10ms latency. Kubernetes distributions optimized for resource-constrained edge nodes address this latency-critical segment.
- India's data localization requirements:The country's central bank mandates domestic storage for payment system data. Cloud-native platforms with in-country control planes satisfy this regulatory constraint for foreign vendors.
- GitOps operational convergence:Infrastructure-as-code practices are merging with continuous deployment pipelines. Platforms integrating declarative configuration management reduce deployment failure rates and accelerate release velocity.
Industry Challenges
- Certified Kubernetes administrator pipeline gaps:The Cloud Native Computing Foundation's credential program cannot match hiring velocity. Organizations compromise on operational standards or defer platform expansions.
- Service mesh interoperability fragmentation:Istio, Linkerd, and Consul compete for adoption without standardized APIs. Engineering teams face lock-in risks when selecting control plane technologies.
- Multi-cluster security posture management:Federated identity and secrets rotation across distributed Kubernetes instances exceed existing security operations center capabilities. Breach surface area expands non-linearly with cluster count.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud-Native Software Market |
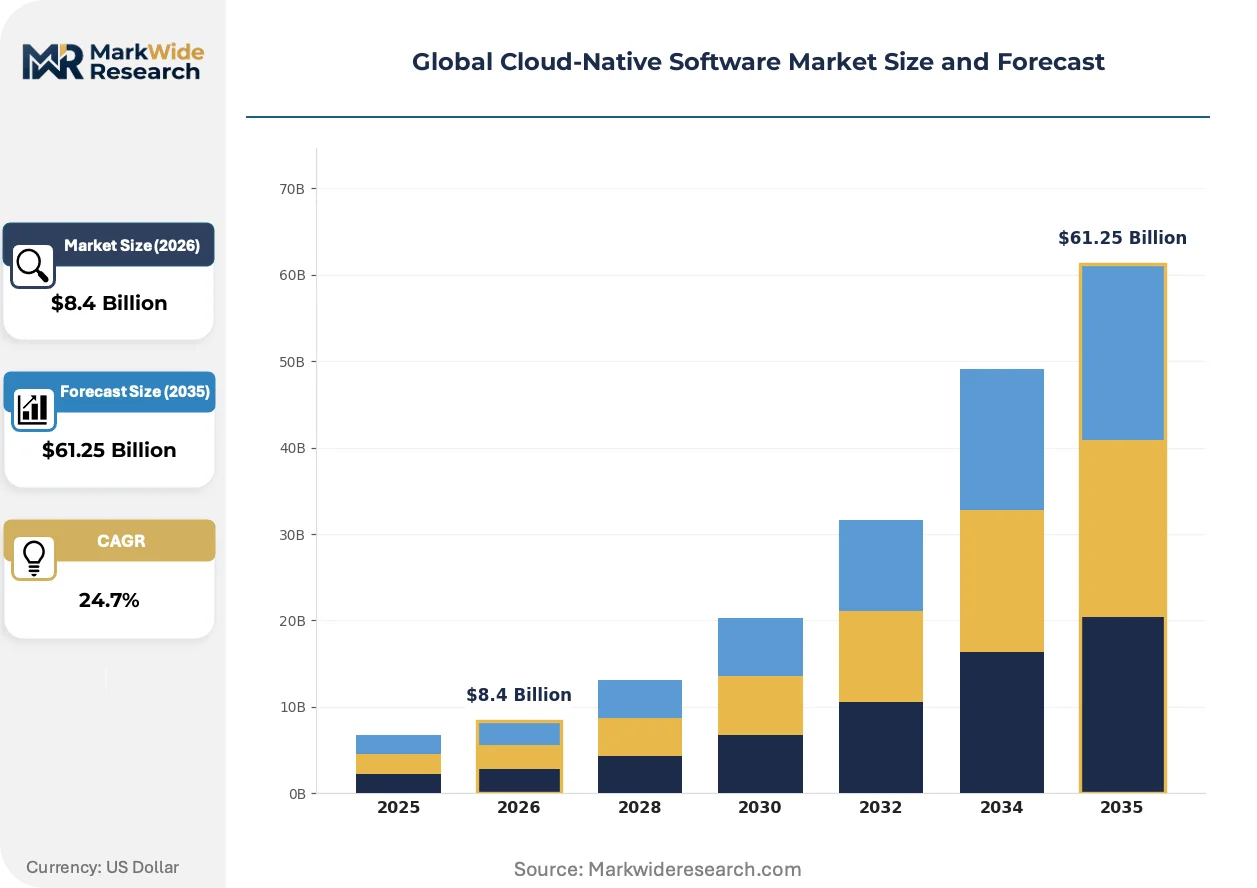
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $61.25 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
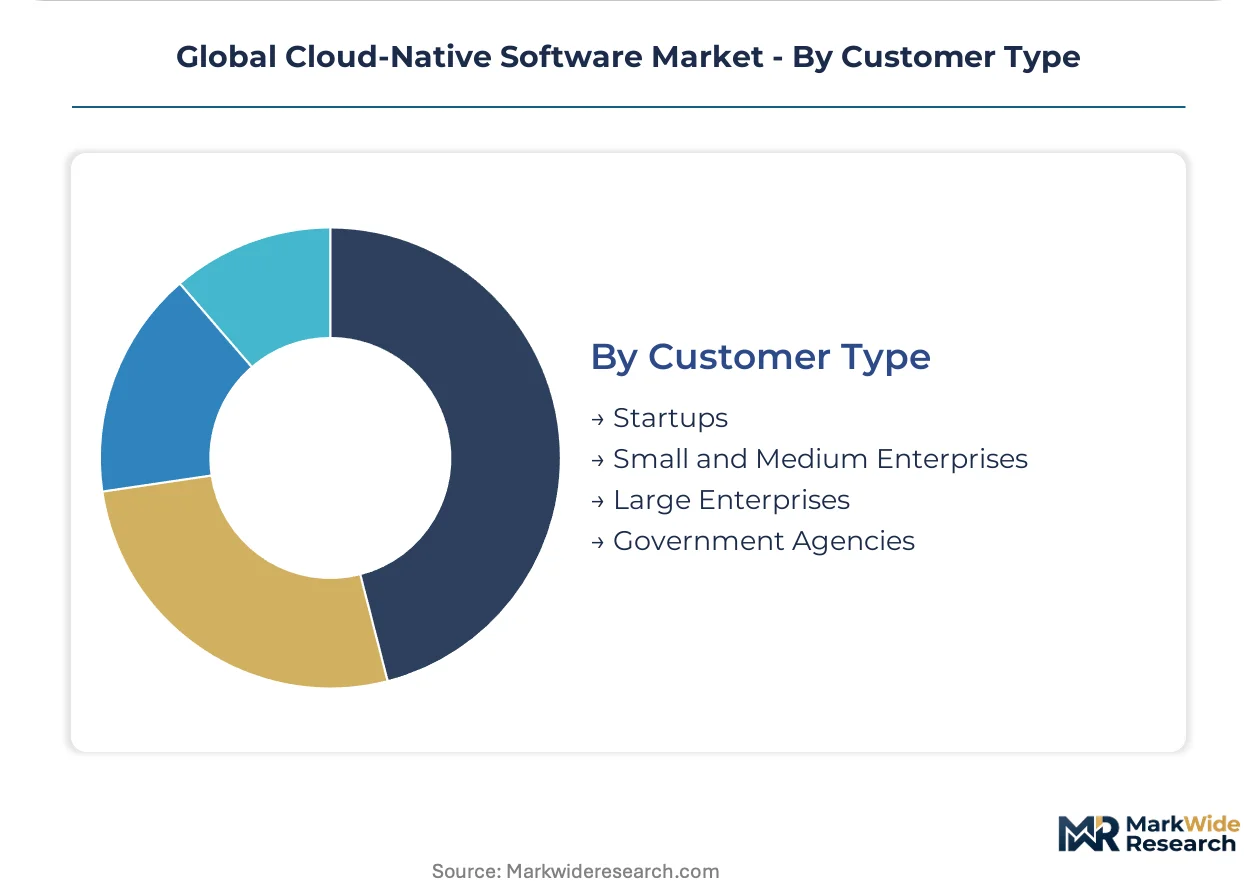
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Container Orchestration, Microservices, Serverless Computing, API Management, Service Mesh Application: Financial Services, Telecommunications, E-Commerce, Media & Entertainment, Education Technology Customer Type: Startups, Small and Medium Enterprises, Large Enterprises, Government Agencies |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google Cloud, IBM Corporation, Oracle Corporation, Alibaba Cloud, Red Hat, Broadcom, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud-Native Software Market Shifts & Advancements
Platform engineering teams are treating internal developer platforms as product offerings rather than infrastructure utilities. This organizational reframing accelerates standardization of deployment patterns and self-service provisioning interfaces across enterprise technology functions.
eBPF-based observability tooling is supplanting traditional agent-based monitoring systems. These kernel-level instrumentation frameworks capture system calls and network flows with negligible overhead. Financial services firms in Singapore and London are deploying eBPF for real-time fraud detection pipelines. The technology is compressing telemetry collection costs while enabling previously infeasible security analytics at production scale.
China's GB standards for cloud service security classification now mandate cryptographic module certification for container runtime environments. Domestic hyperscale providers must integrate government-approved encryption libraries into their Kubernetes distributions. Foreign vendors seeking market access must establish joint ventures with licensed local partners, restructuring their China go-to-market architectures.
Platform engineering procurement is consolidating around internal developer experience metrics rather than raw infrastructure specifications. Enterprise buyers now evaluate vendor offerings based on developer onboarding time and deployment frequency benchmarks. This behavioral shift is most pronounced among North American technology companies with mature DevOps practices, where platform teams report directly to product engineering leadership rather than traditional IT operations.
Global Cloud-Native Software Market Segmentation
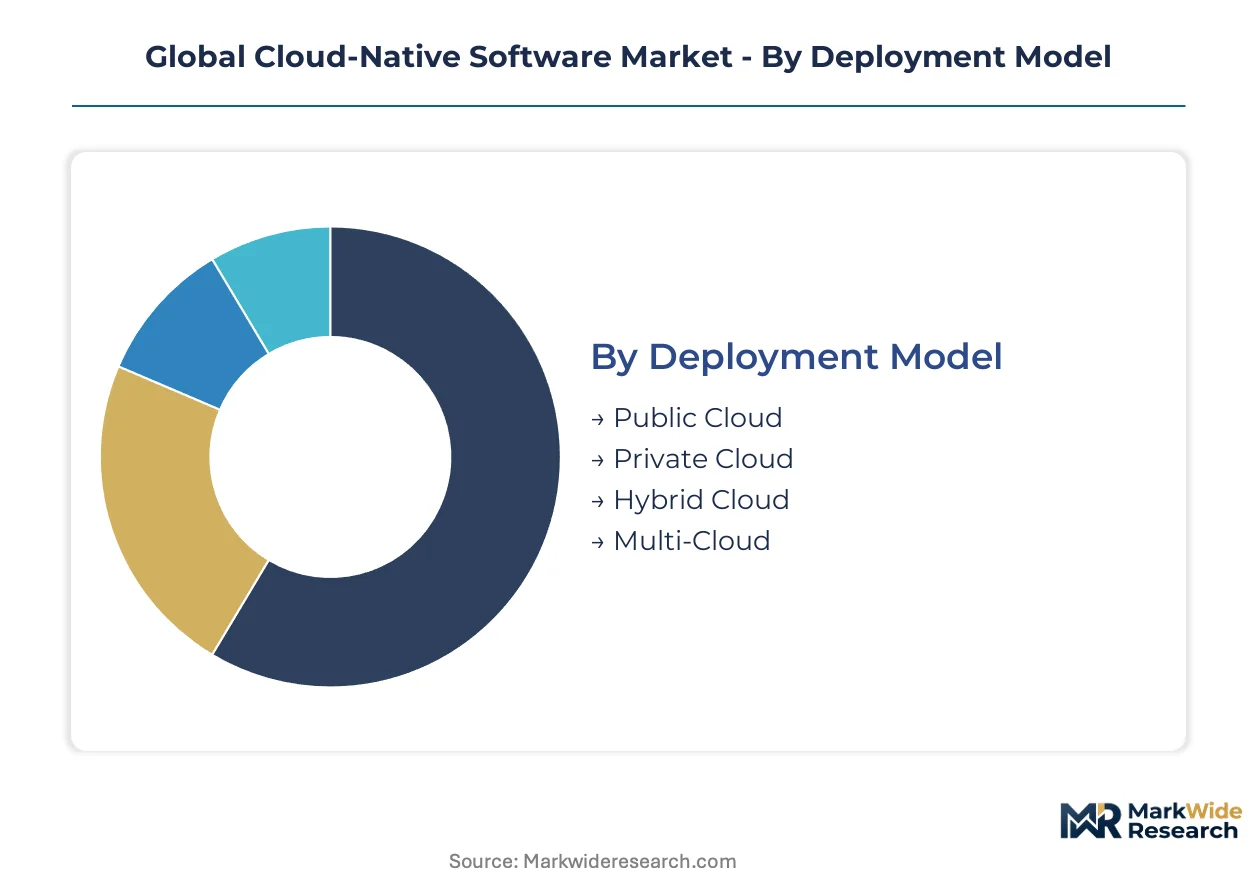
Cloud-native software segmentation reveals how architectural choices reshape procurement patterns across enterprise IT budgets. Deployment models, solution architectures, and customer scale operate as interconnected variables that determine vendor selection criteria and implementation complexity.
Deployment Model:
Substitution pressure from sovereign cloud mandates and data residency requirements is fragmenting deployment strategies across regulated industries.
- Public Cloud:Elastic consumption economics dominate volume procurement. Financial services firms in Singapore and London deploy public Kubernetes clusters for non-sensitive workloads, though GDPR's Schrems II ruling constrains cross-border data flows into US hyperscale regions.
- Multi-Cloud:Vendor-agnostic resilience drives procurement among systemically important banks. Germany's Frankfurt financial cluster standardizes on multi-cloud Kubernetes configurations, cascading procurement decisions through European banking consortia seeking operational continuity guarantees.
- Hybrid Cloud:Bridges on-premises legacy systems with cloud-native workloads. Manufacturing automation in Japan's automotive sector deploys hybrid configurations to maintain sub-10ms latency for production line control systems.
- Private Cloud:Dedicated infrastructure satisfies China's GB standards for cloud service security classification. Domestic hyperscale providers integrate government-approved encryption libraries into private Kubernetes distributions.
Public cloud anchors the volume base while multi-cloud gains share at the steepest rate.
Solution Type:
Margin concentration follows control plane layer positioning, with orchestration platforms capturing disproportionate value pools.
- Container Orchestration:Kubernetes distributions function as the primary abstraction layer between application workloads and infrastructure. Amazon Web Services leverages its global data center footprint to dominate this segment, while Red Hat sustains margin pools through open-source subscription models.
- Service Mesh:Istio, Linkerd, and Consul compete for adoption without standardized APIs. Engineering teams at North American technology companies face lock-in risks when selecting control plane technologies for microservices communication.
- Microservices:Modular application architecture enables independent scaling of high-throughput pathways. Payment processors fragment core banking functions into containerized services for peak load management.
- Serverless Computing:Developer-centric volume growth attracts cloud-native platforms. The segment compresses operational overhead for event-driven workloads but limits fine-grained resource control.
- API Management:Gateway and lifecycle tools standardize service interfaces across distributed systems. E-commerce platforms deploy API management to unify payment, inventory, and fulfillment microservices.
Container orchestration captures the deepest margin pools while service mesh expands most quickly among enterprises maturing beyond basic Kubernetes adoption.
Application:
End-use concentration in regulated sectors elevates compliance architecture to a primary selection criterion.
- Financial Services:EU AI Act mandates drive demand for auditable, explainable systems. Cloud-native architectures provide granular logging and version control required for algorithmic accountability across European banking consortia.
- Telecommunications:5G network function virtualization requires containerized control planes. India's central bank data localization requirements push telecom operators toward in-country cloud-native infrastructure.
- E-Commerce:Seasonal demand volatility favors elastic scaling. Container orchestration enables flash sale traffic surges without permanent infrastructure overprovisioning.
- Media & Entertainment:Streaming platforms deploy microservices for content delivery optimization. Edge-native Kubernetes distributions address latency-critical live broadcast scenarios.
- Education Technology:Learning management systems transition from monolithic to modular architectures. The segment trails in cloud-native maturity but accelerates post-pandemic digital infrastructure investment.
Financial services commands the highest compliance-driven premium while telecommunications climbs the fastest on 5G virtualization demand.
Customer Type:
Engineering talent scarcity creates divergent implementation paths between resource-constrained and capital-rich adopters.
- Large Enterprises:Platform engineering teams treat internal developer platforms as product offerings. North American technology companies with mature DevOps practices evaluate vendors on developer onboarding time and deployment frequency benchmarks.
- Startups:Cloud-native architecture enables rapid scaling without legacy debt. The segment prioritizes managed Kubernetes services to bypass site reliability engineering recruitment challenges.
- Small and Medium Enterprises:Premium compensation for Kubernetes administration skills constrains competitive recruitment. Smaller enterprises defer platform expansions or compromise on operational standards.
- Government Agencies:Sovereign cloud requirements dominate procurement. China's GB standards mandate cryptographic module certification for container runtime environments in public sector deployments.
Large enterprises anchor current spending while startups drive volume expansion through cloud-native-first development patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border data flow restrictions are redrawing trade patterns in cloud-native software licensing. Vendors now engineer region-locked infrastructure to satisfy divergent sovereignty mandates, fragmenting previously unified deployment architectures.
United States
Hyperscale operators anchor global Kubernetes distribution capacity. FDA software-as-a-medical-device guidelines shape container runtime certification requirements for healthcare AI deployments. Seattle and San Francisco Bay Area clusters concentrate site reliability engineering talent pools for platform development.
Germany
Frankfurt's financial hub drives multi-cloud standardization among systemically important banks. EU AI Act compliance mandates force auditable logging architectures for algorithmic decision systems. Bavaria's automotive sector deploys edge-native Kubernetes for manufacturing automation latency requirements.
China
Domestic hyperscale providers capture sovereign cloud procurement under GB standards for cryptographic module certification. MIIT regulations mandate government-approved encryption libraries in container runtime environments. Yangtze River Delta technology corridors concentrate joint venture partnerships for foreign vendor market access.
India
RBI data localization requirements for payment systems push foreign vendors toward in-country control plane deployments. PLI scheme incentives attract cloud-native platform engineering investment from multinational software providers. Karnataka's Bangalore technology cluster concentrates DevOps talent for financial services modernization projects.
Singapore
Monetary Authority of Singapore guidelines on cloud risk management shape regional procurement standards for ASEAN banking consortia. eBPF-based observability tooling from local fintechs compresses fraud detection latency for real-time transaction monitoring. The city-state's data center capacity serves as a hub for Asia-Pacific multi-cloud failover architectures.
Global Cloud-Native Software Market Competitive Landscape
Concentration sits with hyperscale infrastructure operators controlling global data center footprints. Three tiers structure vendor positioning: cloud-native-first platforms with integrated developer tooling, legacy enterprise software vendors retrofitting container orchestration capabilities, and open-source distribution specialists monetizing support subscriptions. Dominant competitive moves include strategic partnerships with systemically important banks for multi-cloud standardization and geographic expansion through sovereign cloud joint ventures.
Within the hyperscale tier, Amazon Web Services and Microsoft Corporation exemplify infrastructure-scale competitive positioning. Red Hat occupies a position representing open-source subscription archetypes. These three anchors illustrate how vendor power redistributes toward platform-native ecosystems that control the Kubernetes control plane layer.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google Cloud |
| IBM Corporation |
| Oracle Corporation |
| Alibaba Cloud |
| Red Hat |
| Broadcom |
| SAP SE |
| Others |
Supply & Pricing Matrix
GB standards for cryptographic module certification gate both vendor qualification and price stratification in China's sovereign cloud segment. Foreign platforms must absorb joint venture structuring costs and government-approved encryption library integration expenses, compressing margin pools for non-compliant competitors while enabling domestic hyperscale providers to command premium positioning.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS pricing across container orchestration platforms. Three-tier pricing structure across premium, standard, and economy levels segments by support response time, cluster size, and compliance certification grade. Cost compression in the economy tier is intensifying because hyperscale operators bundle Kubernetes services with compute commitments. Small and medium enterprises exhibit highest price sensitivity, while systemically important banks prioritize auditability over unit economics.
Supply Chain Analysis
Inventory lead times for specialized silicon extend 16-24 weeks for edge-optimized Kubernetes nodes, constraining deployment velocity for latency-critical manufacturing automation. Supply concentrates in Taiwan for advanced semiconductors, South Korea for memory modules, and China for commodity server components. Raw material dependencies span rare earth elements for magnetic storage, high-purity silicon for processors, and copper for data center interconnects. Single-source vulnerability in advanced node fabrication threatens platform scaling timelines. Distribution runs through direct hyperscaler procurement channels and regional systems integrators serving sovereign cloud deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Frankfurt's systemically important banks, whose multi-cloud standardization decisions cascade through European banking consortia and reshape vendor negotiation leverage.
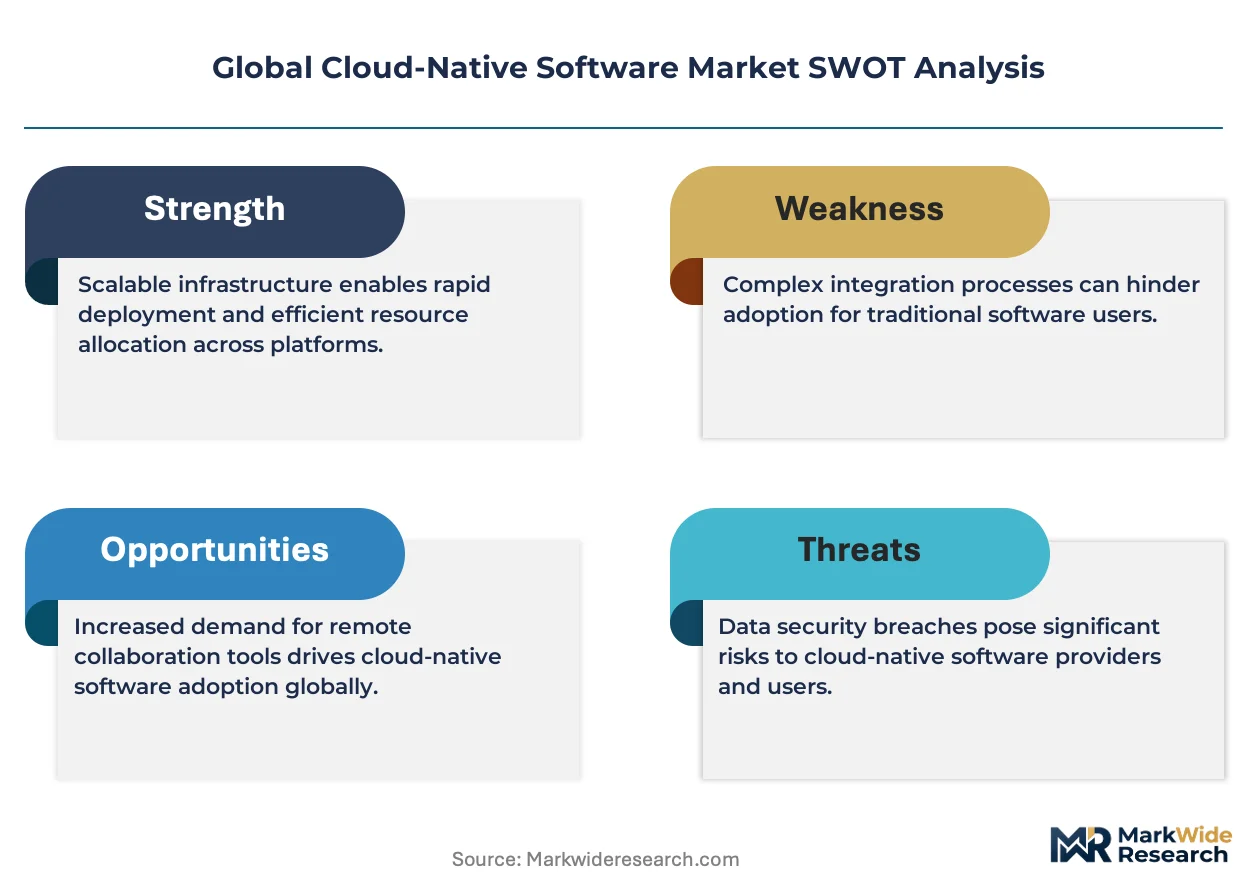
For Market Incumbents: Secure Kubernetes control plane dominance through deep Azure Kubernetes Service or Amazon EKS integration with existing enterprise productivity suites. Invest in EU AI Act-compliant logging architectures to defend against sovereign cloud specialists capturing regulated financial services procurement. Prioritize certification pipelines for China's GB standards through joint venture structures that preserve margin extraction. For New Entrants and Emerging Players: CNCF-certified Kubernetes administrator training fast-tracks credibility gaps among site reliability engineering talent-scarce mid-market enterprises. Target India's data localization requirements for payment system infrastructure, where RBI mandates create procurement urgency foreign hyperscalers cannot satisfy directly. Lead with GitOps-native platforms that compress deployment failure rates for DevOps-immature organizations. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward platforms with built-in algorithmic accountability tooling. Five-to-ten year viability favors vendors controlling edge-native Kubernetes distributions for manufacturing automation latency requirements. Watch for eBPF observability tooling consolidation as real-time fraud detection demand compresses telemetry collection cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Azure Kubernetes Service embedding with Office 365 deployments anchors enterprise trust and switching costs. |
| Geographic Expansion | Sovereign cloud joint ventures in China's Yangtze River Delta satisfy GB standards while preserving market access. |
| Acquisition of Specialist Firm | eBPF observability tooling targets real-time fraud detection pipelines in Singapore and London financial services. |
| Strategic Partnership | Multi-cloud standardization alliances with Frankfurt banking consortia cascade procurement decisions continent-wide. |
| Product Launch | Edge-native Kubernetes distributions address sub-10ms latency requirements in Bavaria's automotive manufacturing sector. |
Research Methodology
A spread of perspectives from platform engineering directors, Kubernetes site reliability engineers, financial services CTOs, and sovereign cloud procurement officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings from hyperscale operators, Cloud Native Computing Foundation adoption surveys, and EU regulatory implementation guidance documents. Bottom-up cluster counting and top-down macroeconomic anchoring were triangulated to constrain variance.
Segmentation dimensions modeled span deployment model, solution architecture layer, end-use vertical, organization scale, and regional regulatory cluster across the analysis window. CAGRs were derived from logistic diffusion curves fitted to adoption rate observations and elasticity-adjusted price trajectories. Forecast inputs incorporated hyperscaler capital expenditure disclosures and certified administrator pipeline growth rates.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act enforcement or abrupt GDPR cross-border data flow restrictions would require recalibration. Forecasts reflect documented assumptions about sovereign cloud fragmentation trajectories and talent scarcity persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud ELN Service Market
Cloud Computing
Cloud Database Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Cloud Computing Services Market
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Cloud Continuum Market
Cloud Computing
Commerce Cloud Market
Cloud Computing
Application Hosting Market
Cloud Computing
Cloud Data Warehouse Market
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Global Cloud Based ITSM Market
Cloud Computing
Cloud Management Market
Cloud Computing
Automotive Cloud Based Solutions Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Saudi Arabia Cloud Services Market