
 Cloud Encryption Gateways Market | 2026-2036
Cloud Encryption Gateways Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Encryption Gateways Market Analysis
Enterprise reseller channels is reconfiguring how cloud encryption gateways reach mid-market buyers, with distributors now bundling managed key services alongside hardware appliances. Microsoft leverages its Azure ecosystem to embed encryption gateways within hybrid cloud subscriptions. Thales Group anchors its position through dedicated hardware security modules that integrate with multi-cloud key management. Palo Alto Networks competes by extending its SASE portfolio to include cloud-native encryption proxy functions.
Cloud encryption gateways are network security appliances that intercept data traffic between enterprise infrastructure and cloud service providers, applying AES-256 or post-quantum cryptographic algorithms to enforce confidentiality before transmission. These systems perform real-time encryption and decryption at the network perimeter, enabling organizations to retain control over encryption keys while utilizing third-party cloud storage and compute resources. The solution type dimension shows post-quantum encryption emerging as the fastest-growing category as NIST-standardized algorithms reach commercial deployment, while data encryption maintains the largest installed base among regulated industries. Deployment model dynamics reveal hybrid cloud configurations capturing disproportionate investment from enterprises operating split workloads across on-premises and public infrastructure.
The Federal Risk and Authorization Management Program in the United States mandates encryption gateway certification for federal cloud deployments, while GDPR and the EU AI Act in Europe impose strict cryptographic safeguards on transatlantic data flows. HIPAA requirements in healthcare and PCI-DSS in retail further segment product roadmaps by compliance vertical. Stakeholders must evaluate whether their key escrow architectures satisfy emerging quantum-resistant standards before regulator-mandated transition deadlines crystallize procurement priorities.
Market Dynamics
Post-quantum cryptographic standardization is collapsing traditional encryption gateway architectures, forcing vendors to reengineer hardware security modules and key management fabrics before NIST-mandated deadlines crystallize procurement cycles.
Growth Catalysts
- GDPR and EU AI Act mandates:Cross-border data flows from Europe now require demonstrable encryption controls, compelling financial services and healthcare enterprises to deploy gateway appliances with sovereign key escrow.
- Hybrid cloud workload distribution:Enterprises operating split infrastructure across on-premises and public environments are consolidating encryption policy enforcement at network perimeters.
- Federal Risk and Authorization Management Program certification:United States federal agencies must validate encryption gateway deployments before cloud adoption, creating a compliance-driven procurement pipeline.
Market Restraints
- Hardware security module supply concentration:Dedicated cryptographic processors depend on specialized semiconductor fabrication concentrated in East Asian foundries, exposing lead time volatility.
- Post-quantum algorithm computational overhead:Lattice-based and hash-based cryptographic schemes impose latency penalties that degrade real-time encryption throughput for high-volume data streams.
- Key escrow jurisdictional fragmentation:Divergent national requirements for law enforcement access to encrypted data create architectural incompatibility across multi-cloud deployments.
Strategic Opportunities
- Japan's financial sector modernization:METI guidelines for quantum-safe transition are accelerating replacement cycles for legacy encryption appliances in banking and insurance.
- Managed encryption service bundling:Distributors are assembling subscription offerings that combine gateway hardware with operational key lifecycle management, penetrating mid-market buyers previously served by direct enterprise sales.
- Healthcare data localization requirements:HIPAA-aligned encryption gateways are capturing demand from hospital systems consolidating patient records into regional cloud instances.
Industry Challenges
- Cryptographic engineering talent scarcity:Implementation of NIST-standardized post-quantum algorithms requires specialized expertise in lattice mathematics and side-channel resistance that outstrips current workforce supply.
- Legacy PKI integration complexity:Existing certificate infrastructures and hierarchical trust models must be rearchitected to accommodate quantum-resistant signature schemes without disrupting operational continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Encryption Gateways Market |
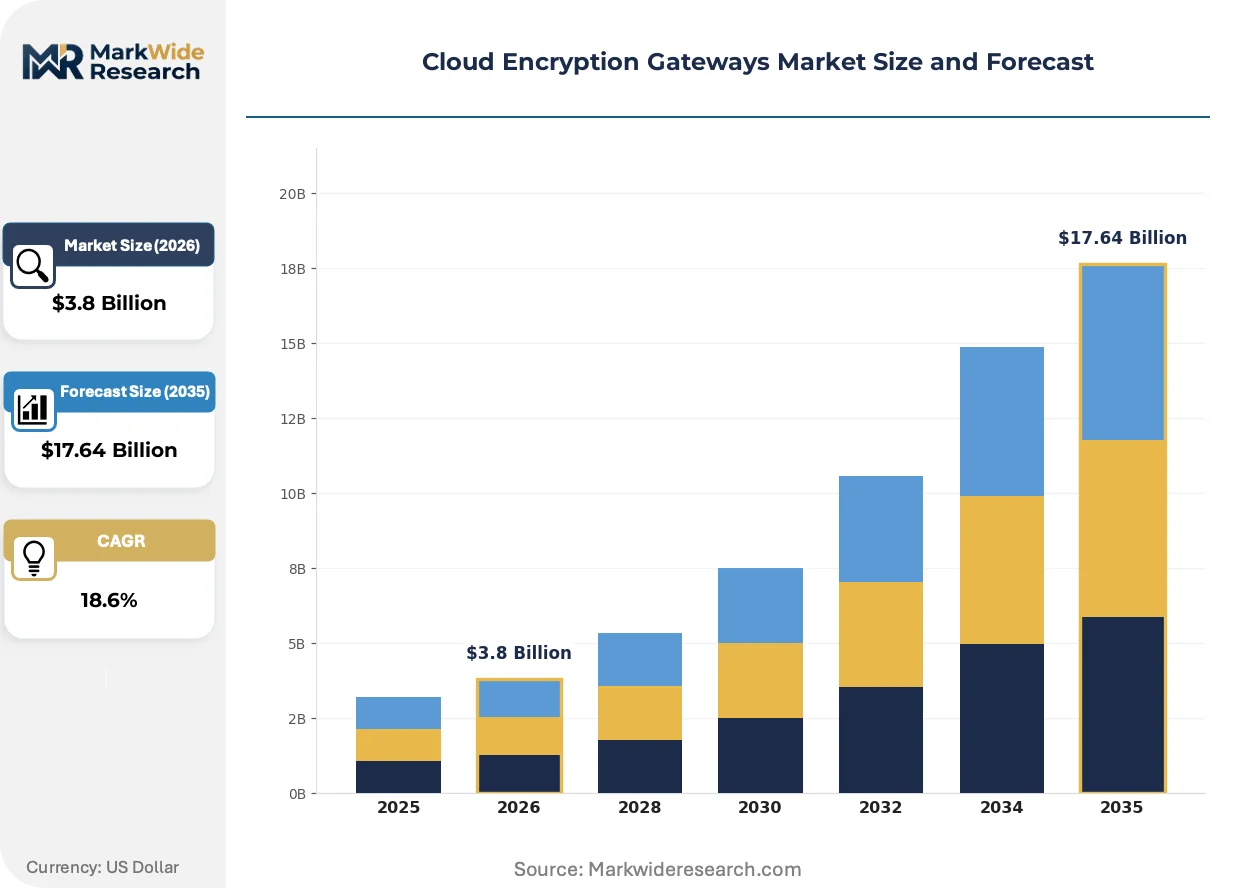
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Data Encryption, Key Management, Tokenization, Post-Quantum Encryption End User: BFSI, Healthcare, Retail, Government Compliance Standard: GDPR, HIPAA, PCI-DSS, ISO 27001 |
| Companies Covered | Microsoft, IBM, Palo Alto Networks, Cisco Systems, Netskope, Thales Group, Fortinet, Check Point Software Technologies, Sophos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Encryption Gateways Market Emerging Trajectories
Encryption gateway architectures are converging with zero-trust network fabrics and software-defined perimeters, dissolving the boundary between data protection and access control functions.
Post-quantum key encapsulation mechanisms are collapsing the performance gap between classical and quantum-resistant encryption, enabling financial clearinghouses in Germany and Japan to pilot lattice-based TLS handshakes without latency penalties. NIST-standardized CRYSTALS-Kyber algorithms are now shipping in production firmware from hardware security module vendors. This transition is compressing replacement cycles for appliances with fixed cryptographic accelerators.
The EU AI Act's risk-classification framework now mandates encryption safeguards for high-risk artificial intelligence systems processing personal data, requiring gateway deployments that segregate training data flows by jurisdictional boundary. European data protection authorities are interpreting these provisions to require cryptographic separation of model inputs from third-party cloud inference services. Healthcare and financial services verticals are responding by embedding encryption proxies directly into MLOps pipelines.
Enterprise buyers are consolidating vendor relationships around integrated SASE platforms that subsume standalone encryption gateway functions into broader secure access service edge contracts. Channel partners in the United States are displacing point-product resellers with managed service providers offering bundled policy orchestration. This concentration is most visible among mid-market enterprises in regulated industries seeking to reduce operational fragmentation across security tool stacks.
Cloud Encryption Gateways Market Segmentation
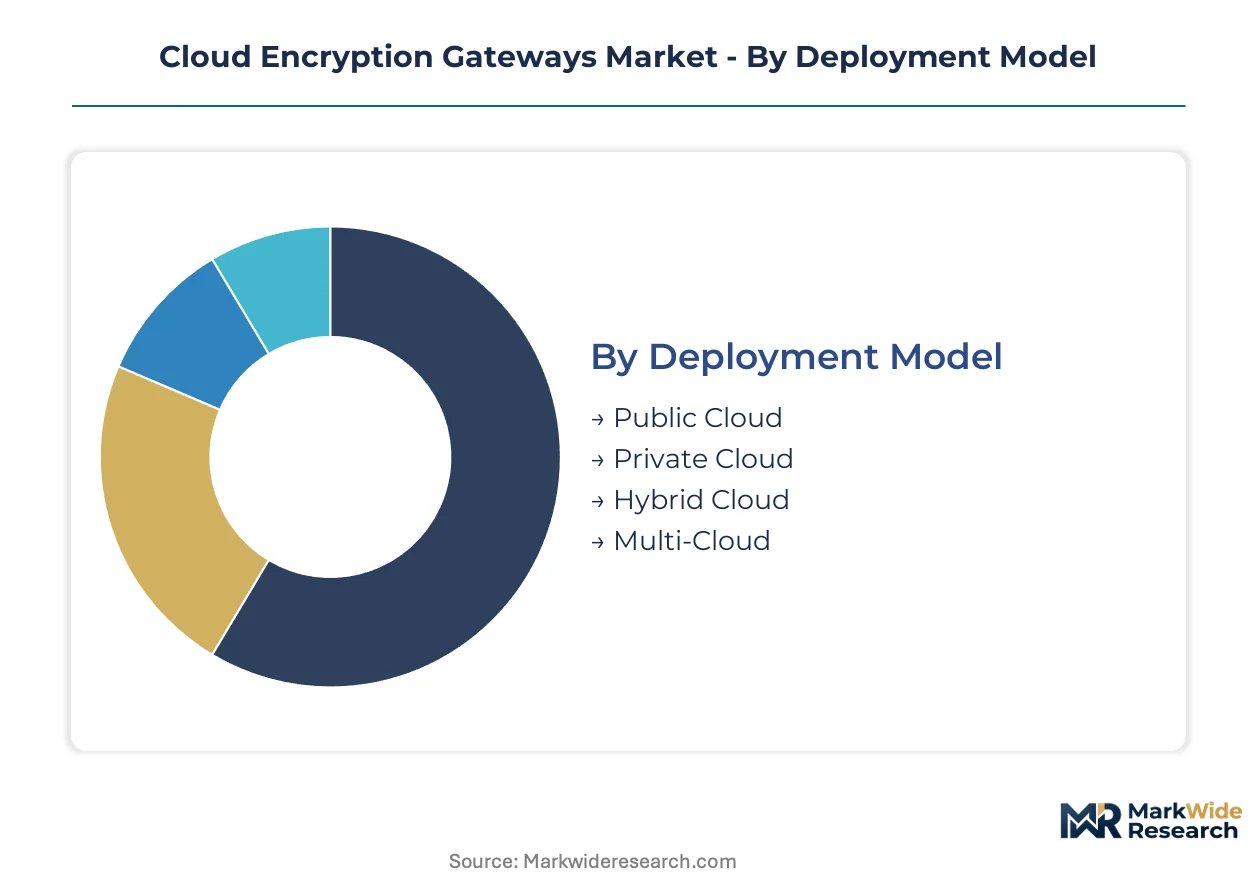
Encryption gateway architectures diverge sharply across deployment topologies and cryptographic workloads. Solution providers must align product roadmaps with specific compliance mandates and infrastructure configurations rather than pursuing universal platform strategies.
Deployment Model:
Use-case spectrum spans centralized public cloud encryption to sovereign private installations and distributed multi-cloud orchestration.
- Hybrid Cloud:Split-workload configurations dominate procurement from financial services and healthcare enterprises operating split infrastructure across on-premises data centers and AWS or Azure regions. United States federal contractors under FedRAMP mandates favor hybrid deployments that preserve on-premises key custody while extending encrypted tunnels to authorized cloud regions.
- Multi-Cloud:Organizations distributing workloads across three or more public providers require gateway fabrics that normalize encryption policy across disparate APIs. German automotive manufacturers and Japanese electronics conglomerates are consolidating multi-cloud encryption to satisfy METI and EU AI Act data sovereignty requirements.
- Public Cloud:Native gateway services integrated with hyperscaler marketplaces serve mid-market buyers with limited security engineering resources.
- Private Cloud:Dedicated hardware appliances in sovereign data centers address defense and intelligence community requirements for air-gapped key management.
Established volume favors hybrid configurations; emerging adoption favors multi-cloud orchestration layers.
Solution Type:
Cost tier stratification separates commodity data protection from premium post-quantum readiness and specialized tokenization services.
- Post-Quantum Encryption:Lattice-based CRYSTALS-Kyber implementations are reaching production firmware in hardware security modules from Thales and ID Quantique. NIST-mandated transition deadlines are compressing replacement cycles for fixed-function appliances in United States federal and German financial clearinghouse environments.
- Data Encryption:AES-256 traffic interception at network perimeters maintains the largest installed base among HIPAA-covered entities and PCI-DSS Level 1 merchants. United States hospital systems and retail payment processors treat data encryption as table stakes for cyber insurance eligibility.
- Key Management:Enterprise key lifecycle platforms with HSM-backed escrow are gaining share fastest among European banks navigating GDPR Article 32 accountability requirements.
- Tokenization:Format-preserving substitution for payment card and personal identifier fields serves retail and healthcare verticals with legacy application constraints.
Regulatory pressure is reshaping investment priority from data encryption toward post-quantum readiness.
End User:
Application intensity varies by data sensitivity and regulatory exposure across financial, healthcare, retail, and government verticals.
- BFSI:Trading systems and core banking platforms require sub-millisecond encryption throughput with hardware-backed key attestation. United States and Japanese financial regulators are mandating quantum-safe transition roadmaps that accelerate gateway refresh cycles.
- Government:Classified and controlled unclassified information environments demand Common Criteria-certified appliances with tamper-evident hardware. FedRAMP and NATO information assurance programs specify gateway architectures for cloud migration eligibility.
- Healthcare:HIPAA minimum necessary standard and state-level privacy laws are driving encryption proxy deployment for electronic health record exchanges.
- Retail:PCI-DSS point-to-point encryption requirements for card-present transactions sustain demand for gateway appliances at payment processing hubs.
Procurement concentration clusters in BFSI; compliance-driven expansion favors government verticals.
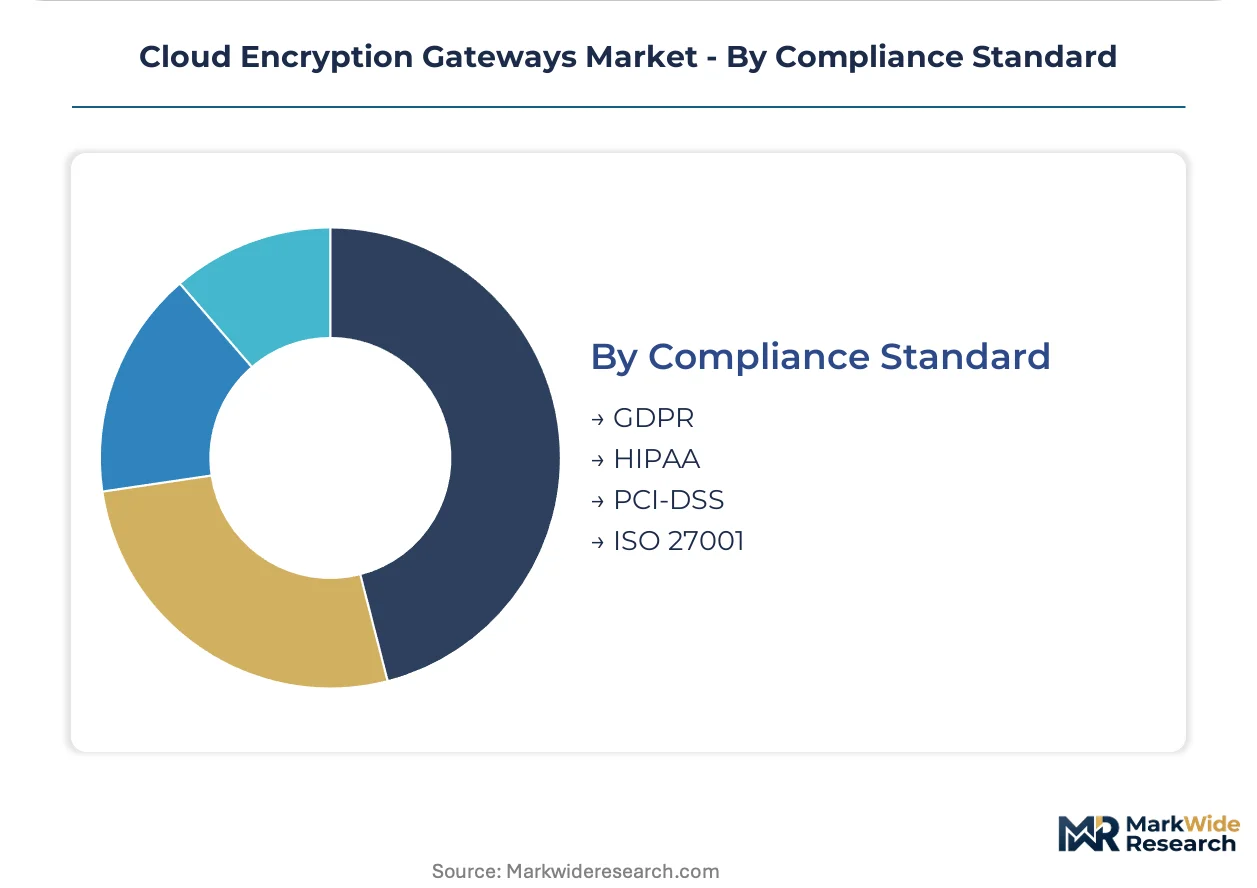
Compliance Standard:
Geographic enforcement intensity determines architectural requirements for cross-border data flows and sector-specific safeguards.
- GDPR:European Data Protection Board guidance on supplementary measures for international transfers mandates encryption gateways with sovereign key escrow for transatlantic cloud deployments. German and French data protection authorities are rejecting standard contractual clauses without demonstrable cryptographic separation.
- HIPAA:Office for Civil Rights settlement patterns emphasize encryption as a safe harbor for breach notification obligations, driving United States hospital system procurement.
- PCI-DSS:Council validation requirements for point-to-point encryption solutions constrain gateway vendor qualification to approved device listings.
- ISO 27001:Certification-seeking enterprises deploy gateways as auditable controls for Annex A cryptographic policy requirements.
Jurisdictional fragmentation favors GDPR-aligned architectures; sector-specific enforcement favors HIPAA and PCI-DSS specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable infrastructure underpins North American and European cloud data exchange, creating concentrated demand corridors for encryption gateway deployment. Submarine cable landing stations in Virginia Beach and Bude anchor transatlantic data flows that require sovereign cryptographic controls. Metro fiber rings in Frankfurt and Amsterdam serve as continental aggregation points for encrypted cloud traffic.
United States
FedRAMP mandates are accelerating federal contractor adoption of certified encryption gateways for cloud migrations. The SEC's cybersecurity disclosure rules are compelling publicly traded enterprises to demonstrate encryption controls for material data breaches. Northern Virginia's data center cluster hosts the densest concentration of gateway deployments, with AWS and Azure regions driving hybrid cloud encryption procurement.
Germany
BaFin's operational resilience requirements for financial institutions mandate quantum-safe encryption roadmaps by 2026. The EU AI Act's high-risk system classification is forcing automotive and industrial enterprises to cryptographically segregate training data flows. Frankfurt's financial district anchors demand from Deutsche Börse and Commerzbank for sub-millisecond encryption throughput.
Japan
METI's quantum-safe transition guidelines are compressing replacement cycles for legacy banking encryption appliances. The Financial Services Agency is requiring demonstrable key custody separation for cloud-hosted customer data. Tokyo's Marunouchi financial district and Osaka's trading floors are piloting lattice-based TLS implementations for derivatives clearing.
United Kingdom
The National Cyber Security Centre's cloud security guidance mandates encryption gateways for OFFICIAL-tier data processing. The Information Commissioner's Office is rejecting standard contractual clauses without supplementary cryptographic measures for US data transfers. London's Canary Wharf fintech cluster is deploying hybrid cloud encryption for open banking API traffic.
France
ANSSI's cloud security certification scheme requires sovereign key escrow for sensitive government data processing. The CNIL is interpreting GDPR Article 32 to mandate encryption gateways for health data exchanges with US cloud providers. Paris-Saclay's research cluster is piloting post-quantum encryption for academic cloud computing partnerships.
Cloud Encryption Gateways Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying cryptographic hardware and key management fabrics. The vendor landscape consolidates around three structural tiers: hyperscale cloud platforms bundling encryption into subscription services, network security vendors extending SASE portfolios, and dedicated hardware security module manufacturers. Strategic differentiation is concentrating on post-quantum readiness certification and managed key service bundling. Competitive moves emphasize M&A for cryptographic talent acquisition and strategic partnerships for multi-cloud policy orchestration.
Among platform integrators, Microsoft exemplifies the bundled-subscription archetype by embedding encryption gateways within Azure hybrid cloud offerings. Thales Group anchors the hardware security module tier through dedicated cryptographic processors that integrate with multi-cloud key management fabrics. Palo Alto Networks occupies a position within the network security extension archetype, representing vendors that subsume standalone encryption functions into broader SASE platform contracts.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Palo Alto Networks |
| Cisco Systems |
| Netskope |
| Thales Group |
| Fortinet |
| Check Point Software Technologies |
| Sophos |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwan Semiconductor Manufacturing Company for advanced cryptographic processor fabrication determines both tiered hardware pricing spreads and the geographic concentration of supply chain resilience investments. This chokepoint forces gateway vendors to absorb foundry premium pricing for post-quantum security modules while fragmenting final assembly across lower-cost jurisdictions.
Pricing Analysis
Volume-discount tiering structures separate enterprise-grade appliances with FIPS 140-3 Level 3 certification from mid-market software-defined gateways and entry-level cloud-native subscriptions. Price differentiation hinges on hardware security module integration depth and managed key service bundling intensity. Cost compression in the mid-market tier is intensifying because distributors are consolidating procurement volumes to extract concessionary terms from Thales and ID Quantique. Government and defense buyers demonstrate the lowest price sensitivity due to FedRAMP and Common Criteria mandates, while retail payment processors face acute margin pressure from PCI-DSS compliance overhead.
Supply Chain Analysis
Contract-manufacturing concentration rests with Foxconn and Jabil Electronics for hardware appliance final assembly, while specialized cryptographic processors draw from TSMC's advanced nodes and GlobalFoundries' mature processes. Raw material dependencies center on silicon wafers, rare-earth magnets for tamper-evident enclosures, and high-grade aluminum for electromagnetic shielding. Supply chain risk concentrates in single-source vulnerability for post-quantum algorithm firmware licensing from NIST-compliant certification bodies. Distribution runs through enterprise security distributors and managed service providers that bundle operational key lifecycle management with hardware deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud encryption gateways are approaching a platform-economics inflection where SASE consolidation and post-quantum interoperability will determine competitive survival. The ecosystem shift toward API-native key orchestration across AWS, Azure, and Google Cloud is collapsing standalone gateway margins.
For Market Incumbents: Pre-empt margin erosion by embedding encryption functions into broader zero-trust fabric subscriptions before Palo Alto Networks and Netskope capture mid-market SASE consolidation. Acquire post-quantum cryptographic engineering talent through targeted hires from NIST standardization working groups. Lock in federal contractor relationships with FedRAMP High certification acceleration to defend against emerging cloud-native challengers.
For New Entrants and Emerging Players: Japanese regional banking underpenetration offers the most accessible white-space target, as METI quantum-safe deadlines force appliance replacement cycles without incumbent loyalty lock-in. Target German automotive suppliers navigating EU AI Act training-data segregation requirements with lightweight encryption proxy solutions that integrate directly into MLOps pipelines. Pursue channel partnerships with European managed security service providers rather than direct enterprise sales to bypass Thales and Microsoft distribution blockades.
For Investors and Strategic Acquirers: Post-quantum algorithm specialists with NIST validation status and existing hardware security module vendor integration contracts represent the highest-conviction acquisition archetype. Long-term viability hinges on cryptographic agility—the capacity to swap algorithm implementations without appliance replacement as standards evolve. Watch for NIST transition deadline acceleration as the critical inflection signal that will compress replacement cycle timing and spike enterprise procurement urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Algorithm Certification | NIST validation unlocks federal and German financial procurement pipelines before mandate deadlines crystallize. |
| SASE Platform Integration | Embedding gateway functions into Palo Alto Networks and Netskope contracts captures mid-market consolidation demand. |
| Managed Key Service Bundling | Operational key lifecycle subscriptions penetrate hospital systems and regional banks lacking security engineering depth. |
| Multi-Cloud Policy Orchestration | API normalization across AWS, Azure, and Google Cloud addresses German automotive and Japanese electronics conglomerate requirements. |
| FedRAMP High Certification | United States federal contractor eligibility creates compliance-driven procurement moats against uncertified competitors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, hyperscaler capex disclosures, and NIST post-quantum standardization documentation to validate market sizing and competitive positioning assessments. Primary interviews engaged chief information security officers at financial services enterprises, federal procurement officers, hardware security module engineering directors, and managed security service provider channel managers. Secondary sources included FedRAMP authorization databases, EU AI Act implementation guidance, and customs records for cryptographic appliance trade flows. Bottom-up demand modeling from end-user deployment counts triangulates against top-down vendor revenue aggregation across the analysis window.
Forecast inputs include deployment model segmentation across hybrid, multi-cloud, public, and private configurations; solution type stratification from data encryption through post-quantum readiness tiers; and end-user vertical intensity from BFSI through government and healthcare. CAGRs derive from regression analysis of historical procurement velocity against regulatory mandate timelines and infrastructure refresh cycle patterns. Industry-specific forecast inputs encompass NIST post-quantum algorithm standardization velocity and METI quantum-safe transition guideline enforcement intensity.
Practitioners should monitor NIST transition deadline adjustments, TSMC foundry allocation shifts for cryptographic processors, and EU AI Act high-risk system classification expansions for early signals of forecast revision necessity. Quarterly review of FedRAMP authorization queues, BaFin operational resilience inspection schedules, and hospital system cyber insurance premium trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Philippines Cybersecurity Market
Cybersecurity
Cloud Security in Banking Market
Cybersecurity
Quantum Cryptography Market
Cybersecurity
Global Container and Kubernetes Security Market
Cybersecurity
South Africa Cybersecurity Market
Cybersecurity
Global Deep Packet Inspection (DPI) Market
Cybersecurity
Virtualization Security Tools Market
Cybersecurity
Retail Cybersecurity Market
Cybersecurity
Global Network Security Policy Management Market
Cybersecurity
Cloud Authentication Market
Cybersecurity
Cyber Security Consulting Market
Cybersecurity
Global Cyber Situational Awareness Market
Cybersecurity
Global Sensitive Data Discovery Market
Cybersecurity
Europe Web Application Firewall Market
Cybersecurity
Global Healthcare IoT Security Market
Cybersecurity
Spain Cybersecurity Market