
 Herceptin Biosimilar Market | 2026-2036
Herceptin Biosimilar Market Size, Share, and Industry Trends Forecast 2026-2036
Herceptin Biosimilar Market Foresight
EMA biosimilar interchangeability qualification is unwinding competitive access across European oncology channels. Celltrion Healthcare Co., Ltd. leverages vertically integrated biologics manufacturing from drug substance through finished injection. Samsung Bioepis anchors its position through sustained R&D intensity in trastuzumab biosimilar development. Amgen Inc. competes by extending its oncology portfolio breadth into HER2-targeted therapy alternatives.
Herceptin biosimilars are recombinant humanized monoclonal antibodies targeting HER2 receptors, manufactured through mammalian cell culture in bioreactors exceeding 10,000-liter scale, with glycosylation patterns critical for antibody-dependent cellular cytotoxicity function. These therapies serve primarily as first-line and adjuvant treatments for HER2-positive breast and gastric malignancies. Intravenous delivery mode dominates current revenue pools due to established hospital infusion infrastructure, while subcutaneous formulations represent the fastest-growing segment driven by patient convenience and reduced administration burden. Hospital end users capture the largest volume share through centralized procurement, though oncology clinics are gaining ground as site-of-care shifts accelerate.
FDA, EMA, and WHO prequalification standards collectively shape approval timelines, manufacturing inspections, and post-market pharmacovigilance requirements for trastuzumab biosimilars. These frameworks determine which manufacturers achieve commercial access in regulated markets versus emerging economies. Stakeholders must monitor evolving interchangeability designation pathways and reference product switching study requirements as regulatory divergence between FDA and EMA approaches intensifies.
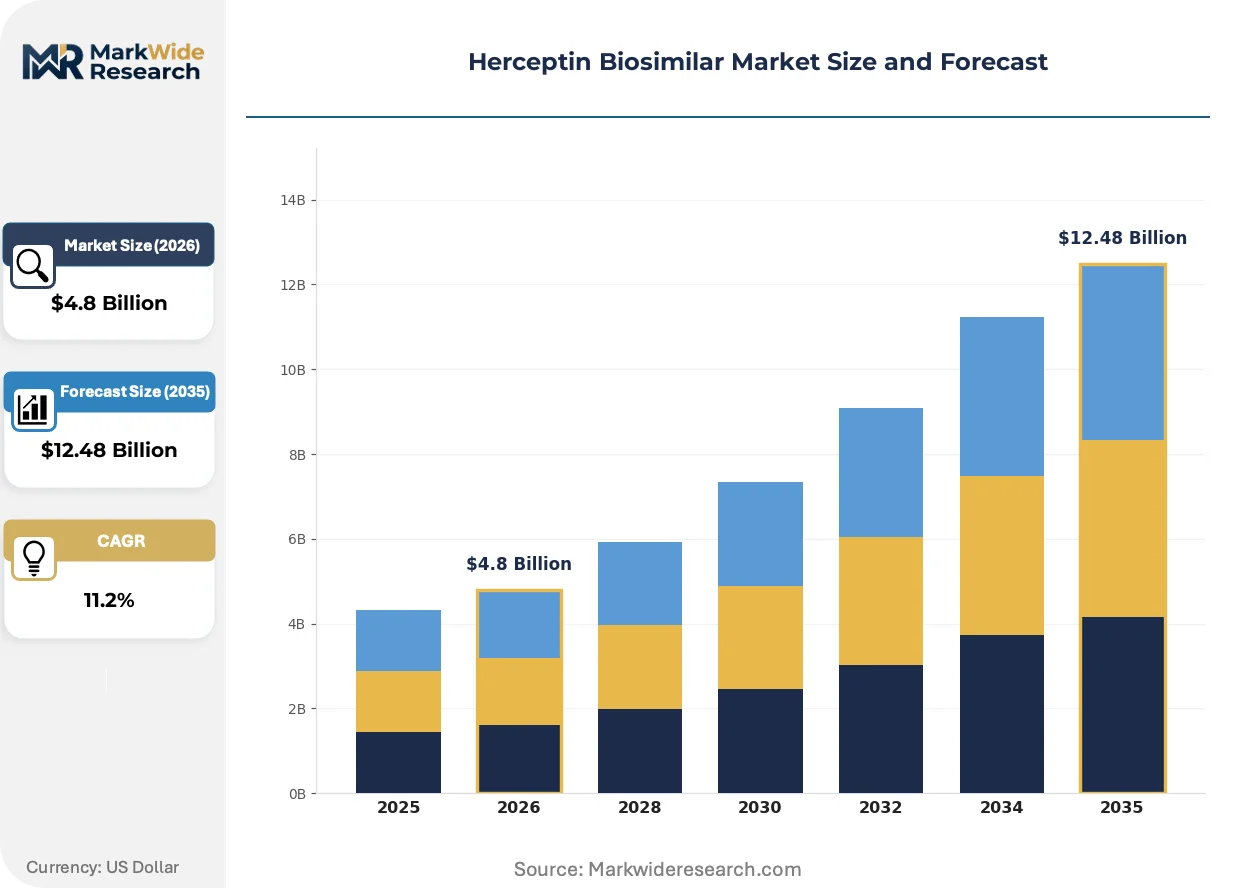
Market Dynamics
EMA interchangeability guidelines are restructuring competitive access across European oncology channels, while manufacturing scale concentration in India and South Korea reshapes supply-side leverage for intravenous and subcutaneous formulations.
Growth Catalysts
- EMA Biosimilar Interchangeability Framework:Maturing guidelines in Germany and France are unlocking automatic substitution at pharmacy level, accelerating patient access without prescriber consultation barriers.
- Subcutaneous Delivery Innovation:Patient-administered injection formats are reducing hospital infusion center burden and capturing preference among HER2-positive breast cancer patients in outpatient settings.
- WHO Prequalification Pathway:Expanded access programs in low- and middle-income countries are creating procurement volume through centralized purchasing mechanisms and tiered pricing structures.
Market Restraints
- Reference Product Lifecycle Extension:Originator patent thickets and secondary formulation patents in the United States are delaying market entry for some biosimilar developers by 18-36 months.
- Glycosylation Consistency Requirements:Mammalian cell culture variability creates batch-to-batch heterogeneity that complicates analytical similarity demonstrations to FDA and EMA reviewers.
- Cold Chain Infrastructure Gaps:Temperature-controlled distribution networks remain underdeveloped in sub-Saharan Africa and parts of Southeast Asia, limiting addressable patient populations.
Strategic Opportunities
- Oncology Clinic Site-of-Care Migration:Community-based infusion centers in the United States and Western Europe are capturing volume from hospital outpatient departments, creating channel diversification.
- Combination Therapy Positioning:Biosimilar trastuzumab paired with pertuzumab biosimilars in development pipelines offers bundled procurement opportunities for payers and health systems.
- Digital Therapeutic Integration:Remote patient monitoring platforms paired with subcutaneous administration are enabling home-based treatment models with adherence tracking capabilities.
Industry Challenges
- Analytical Methodology Talent Scarcity:Bioanalytical scientists capable of designing and validating biosimilarity studies for complex glycoproteins command premium compensation and limited availability.
- Immunogenicity Surveillance Infrastructure:Post-market pharmacovigilance systems required for anti-drug antibody monitoring remain underdeveloped in several emerging markets with expanding biosimilar uptake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herceptin Biosimilar Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drug Substance, Drug Product, Antibody, Injection End User: Hospitals, Clinics, Oncologists, Pharmacies Delivery Mode: Intravenous, Subcutaneous, Oral, Other Application: Breast Cancer, Gastric Cancer, Clinical Trials, Research |
| Companies Covered | Amgen Inc., Biocon, Celltrion Healthcare Co., Ltd., Samsung Bioepis, Pfizer Inc., Teva Pharmaceuticals, Mylan N.V., Shanghai Henlius Biotech, Inc., AryoGen Pharmed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herceptin Biosimilar Market Shifts & Advancements
Bioprocess intensification and continuous manufacturing are compressing cost structures while regulatory science advances enable streamlined development timelines for complex biologics.
Single-use bioreactor systems is supplanting stainless steel infrastructure in new facility designs, enabling rapid product changeover and reduced cross-contamination risk. Contract manufacturing organizations in South Korea and Singapore are adopting these platforms for multi-product biosimilar suites. This technology is supplanting traditional facility economics by cutting capital deployment timelines from five years to eighteen months for greenfield sites.
EMA's revised biosimilar guidelines now explicitly address extrapolation of indications and interchangeability study design, creating regulatory clarity that the FDA has not yet matched. European oncology clinics are responding by expanding automatic substitution protocols, while US health systems await FDA interchangeability designation pathways. The divergence is fragmenting commercial strategy between jurisdictions and forcing dual-track clinical development programs.
Hospital procurement consortia are consolidating purchasing power through multi-year sole-source agreements with preferred biosimilar suppliers. Group purchasing organizations in the United States are displacing open formulary competition with exclusive contracts tied to rebate structures and volume commitments. This concentration is most visible in integrated delivery networks spanning multiple states, where centralized pharmacy committees now control site-of-care decisions.
Herceptin Biosimilar Market Segmentation
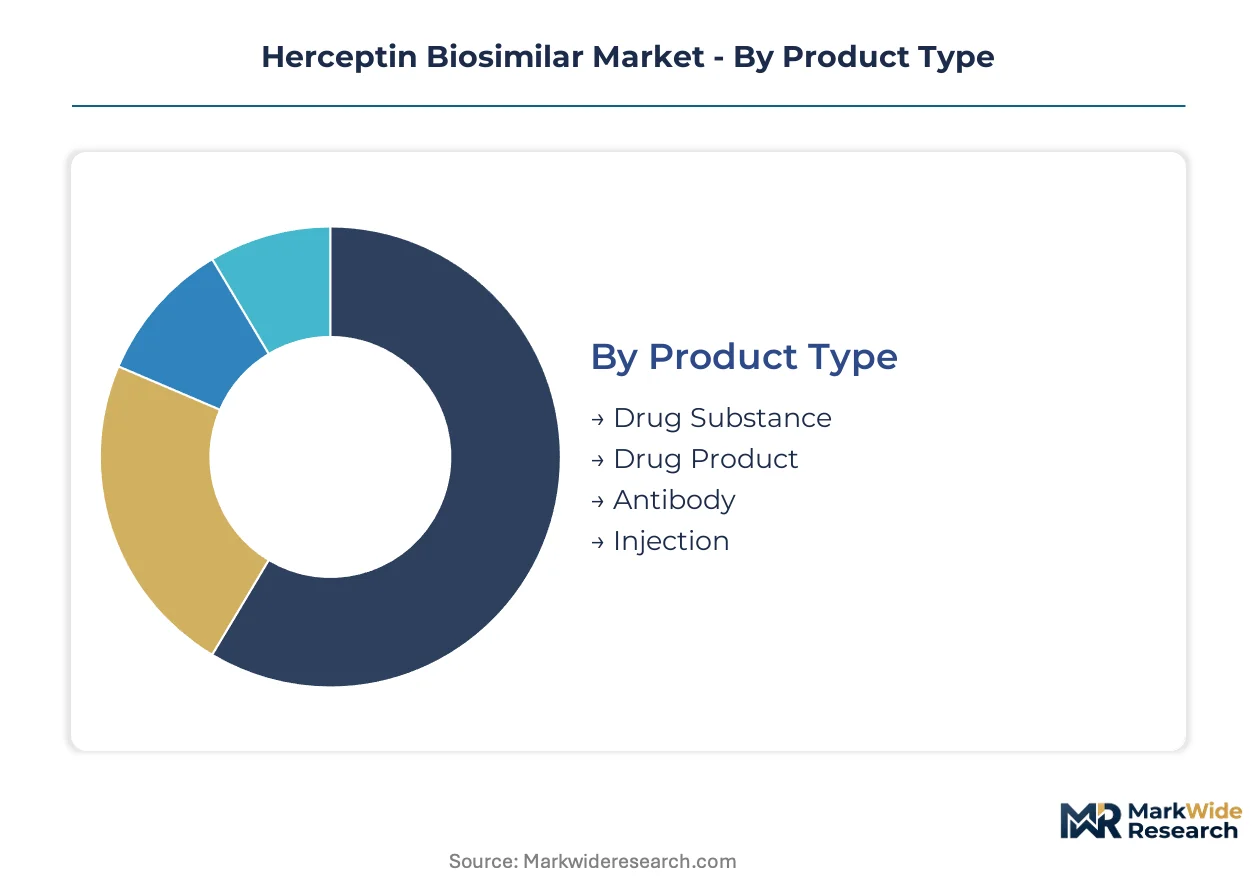
Segmentation in Herceptin biosimilars reveals where procurement power and margin capture diverge across manufacturing stages, clinical settings, and patient administration pathways. Understanding these fault lines enables targeted positioning for developers, contract manufacturers, and distribution partners competing across regulated and emerging markets.
Product Type:
Margin pools concentrate in finished drug product manufacturing where formulation expertise and aseptic processing create defensible positions against commodity drug substance suppliers.
- Drug Substance:Bulk recombinant trastuzumab produced via mammalian cell culture in bioreactors exceeding 10,000-liter scale. Indian and South Korean CDMOs anchor capacity here, though analytical similarity requirements and glycosylation consistency constraints limit qualified supplier pools.
- Drug Product:Final formulated sterile injectable requiring aseptic fill-finish capabilities and cold-chain validated packaging. European oncology clinics and US hospital systems concentrate demand here as procurement committees prioritize supply security over unit cost minimization.
- Antibody:Purified monoclonal antibody intermediate requiring protein A chromatography and viral clearance validation. Biocon and Celltrion Healthcare Co., Ltd. maintain captive production for vertical control over critical quality attributes.
- Injection:Ready-to-administer presentation in prefilled syringes or vials with patient-centric labeling. Subcutaneous auto-injector formats are climbing the fastest as site-of-care migration accelerates in Germany and France.
Drug product holds installed capacity. Injection is rotating up the share rankings.
End User:
Procurement authority is shifting toward consolidated purchasing entities as oncology care decentralizes from academic medical centers to community settings.
- Hospitals:Centralized infusion centers with established cold-chain infrastructure and pharmacy oversight. Group purchasing organizations in the United States are capturing volume through multi-year sole-source agreements with preferred biosimilar suppliers.
- Clinics:Community-based oncology practices with limited on-site pharmacy capabilities. Germany's EMA-guided automatic substitution protocols are unlocking access here without prescriber consultation barriers.
- Oncologists:Individual prescribers exercising formulary influence through integrated delivery network participation. Prescribing patterns concentrate in HER2-positive breast cancer first-line adjuvant settings where clinical familiarity with reference product dosing drives biosimilar acceptance.
- Pharmacies:Retail and specialty pharmacy channels handling subcutaneous take-home prescriptions. EMA interchangeability frameworks are expanding substitution authority here, though FDA designation pathways remain pending in the United States.
Hospitals retain volume leadership. Clinics are expanding share through site-of-care migration.
Delivery Mode:
Patient convenience preferences and reimbursement incentives are restructuring administration economics across infusion and injection formats.
- Intravenous:Hospital-administered infusion requiring 30-90 minute chair time with cardiac monitoring protocols. Established infrastructure in India and Brazil supports volume concentration, though capacity constraints in European outpatient settings are limiting expansion.
- Subcutaneous:Patient or caregiver-administered injection with reduced healthcare utilization and faster pharmacy turnaround. This format is expanding most quickly in Western Europe and the United States as home-based treatment models gain payer endorsement.
- Oral:Investigational small-molecule HER2 inhibitors in development pipelines, not yet commercialized for trastuzumab biosimilar equivalence. Research programs concentrate in academic-industry partnerships exploring oral bioavailability challenges for large protein therapeutics.
- Other:Experimental depot formulations and implantable delivery systems in preclinical stages. Clinical trial activity remains limited to academic research centers with specialized formulation capabilities.
Intravenous dominates current revenue pools. Subcutaneous is climbing the fastest as administration burden reduction drives preference.
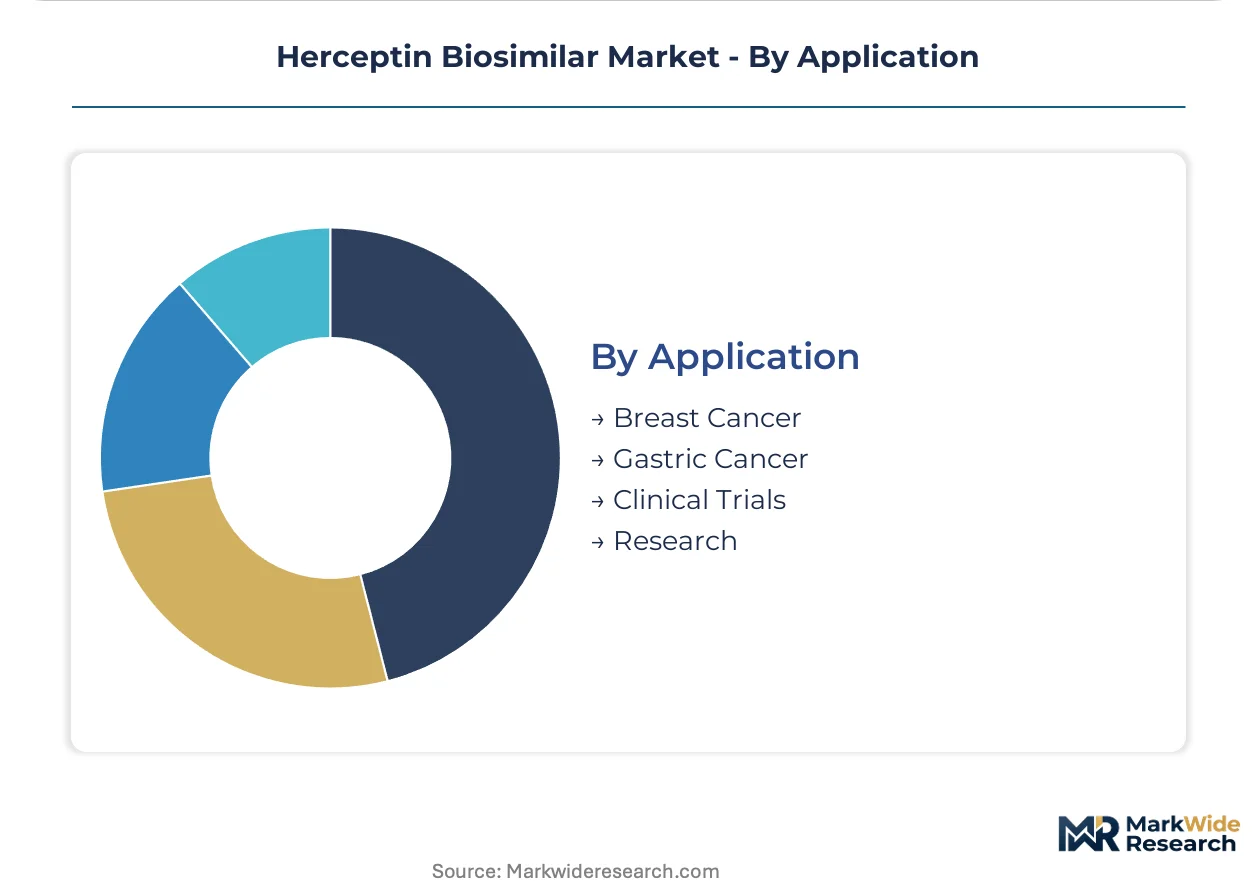
Application:
Clinical indication breadth and trial design requirements determine regulatory investment returns and market access timelines for biosimilar developers.
- Breast Cancer:HER2-positive adjuvant and metastatic settings representing the primary commercial indication. EMA extrapolation guidelines enable indication expansion from breast to gastric cancer without separate clinical trials, compressing development timelines for qualified applicants.
- Gastric Cancer:HER2-positive gastroesophageal junction and gastric adenocarcinoma applications. Demand concentrates in East Asian markets where gastric cancer incidence exceeds Western benchmarks, with Japan's PMDA and South Korea's MFDS shaping regional approval standards.
- Clinical Trials:Biosimilar switching studies and interchangeability trials required for EMA automatic substitution qualification. German and French oncology clinics are hosting investigator-initiated studies as national health technology assessment bodies mature evidentiary requirements.
- Research:Academic and preclinical investigations into biosimilar analytical similarity methodologies. WHO prequalification pathway development is creating reference standard demand for low- and middle-income country access programs.
Breast cancer holds established revenue concentration. Gastric cancer is rotating up the share rankings through Asia-Pacific incidence patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology procurement committees in Germany, India, South Korea, and the United States concentrate purchasing volume for trastuzumab biosimilars, while hospital consortia in France and the United Kingdom accelerate formulary diversification through automatic substitution protocols.
Germany
EMA interchangeability guidelines unlock pharmacy-level substitution without prescriber consultation, expanding access through community oncology clinics. Germany's national health technology assessment body shapes reimbursement parity between biosimilars and reference products. Manufacturing demand clusters around Bavaria and North Rhine-Westphalia, where hospital consortia negotiate multi-year supply agreements with preferred suppliers.
India
Domestic oncology burden and export-oriented manufacturing capacity drive dual-market participation from Indian producers. CDSCO accelerated approval pathways compress regulatory timelines for qualified biosimilar applicants. Hyderabad and Bangalore anchor biologics manufacturing clusters, with Biocon leveraging captive fermentation capacity to supply intravenous and subcutaneous formulations across emerging markets.
South Korea
MFDS biosimilar guidelines align with ICH standards, enabling simultaneous development for domestic and OECD market access. Government R&D tax incentives support continuous bioprocessing investments. The Songdo and Incheon free economic zones concentrate contract manufacturing capacity, with Samsung Bioepis anchoring trastuzumab biosimilar development through sustained investment intensity.
United States
FDA interchangeability designation pathways remain pending, delaying automatic substitution authority relative to European benchmarks. Group purchasing organizations consolidate procurement power through exclusive rebate-structured contracts. The Boston-Cambridge corridor and Research Triangle Park host clinical trial infrastructure for biosimilar switching studies required for future interchangeability qualification.
France
ANSM automatic substitution protocols expand biosimilar penetration in community pharmacy channels serving oncology patients. National health insurance reimbursement frameworks eliminate patient cost-sharing differentials between biosimilars and originators. The Paris-Saclay cluster concentrates pharmacovigilance expertise for post-market immunogenicity surveillance required under EMA guidelines.
Herceptin Biosimilar Market Competitive Landscape
Player mix skews toward vertically integrated biologics manufacturers with captive mammalian cell culture capacity and contract development organizations serving multi-product biosimilar portfolios. Market structure concentrates around three strategic archetypes: originator-affiliated developers leveraging reference product expertise, independent biotech specialists with fermentation scale advantages, and emerging market producers with cost-optimized manufacturing platforms. Competitive positioning depends on glycosylation consistency capabilities and cold-chain distribution reach. Dominant moves include backward integration into drug substance production and geographic expansion through WHO prequalification pathways.
Within the integrated manufacturing tier, Celltrion Healthcare Co., Ltd. and Samsung Bioepis exemplify Korean producers with bioreactor scale exceeding 10,000 liters and multi-regulatory filing strategies. Biocon represents the emerging market archetype with fermentation capacity anchored in Indian manufacturing zones and supply relationships spanning regulated and access markets. Amgen Inc. occupies a position bridging originator heritage with biosimilar portfolio diversification into HER2-targeted therapy alternatives.
| Leading Market Players |
|---|
| Amgen Inc. |
| Biocon |
| Celltrion Healthcare Co., Ltd. |
| Samsung Bioepis |
| Pfizer Inc. |
| Teva Pharmaceuticals |
| Mylan N.V. |
| Shanghai Henlius Biotech, Inc. |
| AryoGen Pharmed |
| Others |
Supply & Pricing Matrix
EMA interchangeability designation protocols gate both supplier qualification and price differentiation simultaneously, restricting automatic substitution authority to manufacturers meeting glycosylation consistency thresholds while compressing margin spreads between qualified and non-qualified tiers.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate hospital procurement agreements, with group purchasing organizations negotiating multi-year offtake tied to fermentation yield benchmarks. Price differentiation rests on FDA versus EMA regulatory tier and cold-chain validated packaging grade. Cost compression in intravenous formulations is intensifying because Indian and South Korean CDMOs are expanding 10,000-liter bioreactor capacity. Oncology clinics demonstrate highest price sensitivity due to limited pharmacy budgets, while integrated delivery networks prioritize supply security over unit cost.
Supply Chain Analysis
Inbound logistics costs from Port of Busan to European cold-chain distribution hubs have tightened container availability for temperature-controlled trastuzumab shipments, elevating freight as a share of landed cost. Manufacturing gravity centers on India, South Korea, and Germany, with Hyderabad and Songdo anchoring fermentation capacity. Supply chains draw from Chinese-sourced cell culture media, single-use bioreactor bags, and European protein A resin. Single-source vulnerability concentrates in viral clearance filtration membrane supply. Distribution runs through hospital consortia and specialty pharmacy channels with validated cold-chain packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent biosimilar manufacturers face substitution defense imperatives against emerging subcutaneous auto-injector formats and next-generation HER2-targeted antibody-drug conjugates that threaten to displace intravenous trastuzumab in first-line settings.
For Market Incumbents: Consolidate manufacturing scale through captive 10,000-liter bioreactor additions in South Korean free economic zones to defend against emerging market CDMO cost structures. Lock in multi-year sole-source agreements with German and French hospital consortia before EMA interchangeability guidelines fully mature and fragment procurement authority.
For New Entrants and Emerging Players: WHO prequalification fast-track pathways offer the most penetrable regulatory entry point for low- and middle-income country volume capture. Target sub-Saharan African markets with underdeveloped cold-chain infrastructure where reference product penetration remains limited. Pursue digital therapeutic integration partnerships with remote patient monitoring platforms to differentiate subcutaneous administration offerings.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous bioprocessing equipment installations, favoring asset-light contract manufacturing platforms over greenfield fermentation builds. Five-to-ten year viability hinges on glycosylation analytics capabilities and multi-regulatory filing track records. Watch for FDA interchangeability designation pathway finalization as the inflection signal triggering US automatic substitution volume migration.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Interchangeability Qualification | Unlocks pharmacy-level automatic substitution in Germany and France without prescriber consultation barriers. |
| Subcutaneous Auto-Injector Development | Captures site-of-care migration demand from hospital infusion centers to community oncology clinics. |
| Backward Integration into Drug Substance | Secures glycosylation consistency control and reduces dependency on qualified CDMO supplier pools. |
| WHO Prequalification Pathway Entry | Enables centralized procurement access in low- and middle-income countries with tiered pricing structures. |
| Continuous Bioprocessing Adoption | Compresses cost structures through single-use bioreactor platforms with reduced cross-contamination risk. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with formulary directors and GPO contracts managers alongside secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population modeling and top-down manufacturer capacity assessments were triangulated to anchor volume estimates.
Segmentation dimensions modeled include delivery mode, end-user channel, product type, and regional regulatory cluster across the projection horizon. CAGRs were derived from trend extrapolation of biosimilar adoption curves in comparable monoclonal antibody markets, calibrated against trastuzumab-specific factors including reference product lifecycle extension pressures and EMA interchangeability timeline assumptions. Forecast inputs incorporated bioreactor capacity expansion announcements and CDSCO accelerated approval pathway utilization rates.
Decision-makers should treat outputs as directional under assumptions of stable EMA-FDA regulatory divergence and continued originator patent thicket enforcement; material deviation would warrant model refresh. Specific risk factors include glycosylation batch failure rates, cold-chain infrastructure development delays in target markets, and immunogenicity surveillance system maturity gaps. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Immunology Biosimilars Market
Biosimilars
Fusion Protein and Biosimilars Market
Biosimilars
Retinal Biosimilars Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Etanercept Market
Biosimilars
Dasatinib Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Biosimilar Monoclonal Antibody Comparability Test Platforms Market
Biosimilars
Global Biosimilar Monoclonal Antibodies (Mabs) Market
Biosimilars
Pegfilgrastim Biosimilar Market
Biosimilars
Europe Biosimilars Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Global Biosimilars Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Global Sirolimus Market
Biosimilars
Insulin Biosimilars Market