
 Oncology Biosimilars Market | 2026-2036
Oncology Biosimilars Market Size, Share, and Industry Trends Forecast 2026-2036
Oncology Biosimilars Market Analysis
FDA interchangeability guidance is hardening the clinical evidence threshold for oncology biosimilar approval, forcing developers to expand immunogenicity study protocols. Sandoz International GmbH leverages its European manufacturing footprint to sustain first-mover positions in trastuzumab and rituximab portfolios. Celltrion Inc. anchors its competitive stance through vertically controlled bioreactor capacity in Songdo, while Samsung Bioepis differentiates via subcutaneous formulation expertise in etanercept and adalimumab analogues.
Oncology biosimilars are recombinant or monoclonal antibody-derived therapeutic proteins engineered to demonstrate equivalent pharmacokinetic, pharmacodynamic, safety, and efficacy profiles to reference oncology biologics, manufactured through mammalian cell culture in stainless-steel or single-use bioreactor systems with stringent glycosylation pattern control. Their primary commercial purpose is to expand patient access to high-cost cancer therapies by introducing price competition after reference product patent expiry. Monoclonal antibodies occupy the dominant revenue position within product type segmentation due to the concentration of blockbuster reference targets in breast and colorectal oncology. Hospitals command the largest end-user volume share, though specialty pharmacies are capturing faster growth as subcutaneous delivery modes enable outpatient administration models.
FDA, EMA, and WHO prequalification standards collectively shape oncology biosimilar market access through divergent labeling, naming, and post-market surveillance requirements that developers must navigate simultaneously. EMA's biosimilar-specific guidelines permit broader indication extrapolation than FDA interchangeability designations, creating asymmetric commercialization timelines across Atlantic markets. Stakeholders must monitor evolving pharmacovigilance data requirements and tender pricing mechanics to calibrate portfolio investments.
Market Dynamics
EMA interchangeability guidelines are compressing commercialization timelines for oncology biosimilar developers, forcing parallel FDA immunogenicity study expansion and accelerating formulary access negotiations across Western European hospital systems.
Growth Catalysts
- EU Green Deal pharmaceutical sustainability mandates:Manufacturing upgrade requirements are accelerating bioreactor modernization across European production networks, expanding compliant supply capacity for tendering markets.
- Centralized hospital tendering mechanisms:Germany and France are consolidating procurement volumes through regional purchasing alliances, creating predictable demand pools for biosimilar suppliers.
- Subcutaneous formulation platforms:Outpatient administration models are shifting patient volumes from infusion centers to specialty pharmacies, expanding addressable market reach beyond traditional hospital capture.
Market Restraints
- FDA interchangeability designation threshold:Hardened clinical evidence requirements for switching studies are extending development timelines and inflating trial costs for US market entry.
- Glycosylation pattern control complexity:Mammalian cell culture variability creates batch-to-batch consistency challenges that compress manufacturing yields and inflate quality assurance overhead.
- Reference product lifecycle management:Originators are deploying formulation patents and device improvements to erect secondary IP barriers beyond core compound expiry.
Strategic Opportunities
- WHO prequalification pathway expansion:Emerging market access programs are creating volume anchors for manufacturers with standardized analytical packages and temperature-stable supply chains.
- Subcutaneous-to-intravenous switching protocols:Clinical validation of reverse switching is opening reimbursement pathways for flexible administration models in outpatient oncology settings.
- EU MDR companion diagnostic alignment:Biosimilar developers with integrated biomarker strategies are capturing preferential positioning in precision oncology tender evaluations.
Industry Challenges
- Analytical biosimilarity package assembly:CMC documentation requirements for glycan mapping and forced degradation studies are stretching technical teams and delaying submission readiness.
- Pharmacovigilance system integration:Post-market surveillance obligations across FDA, EMA, and national competent authorities are fragmenting safety database architectures and inflating compliance headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oncology Biosimilars Market |
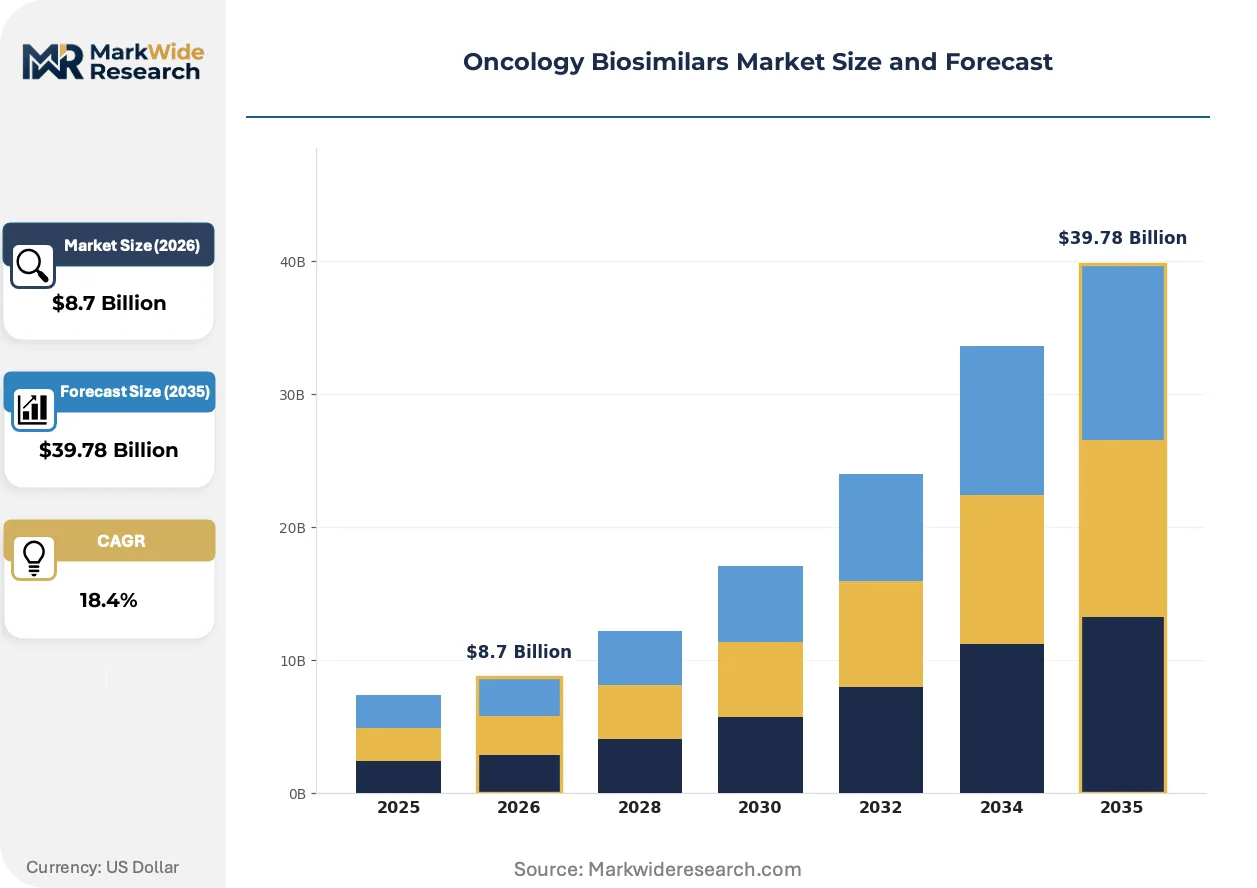
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Recombinant Proteins, Hormonal Agents, Enzyme Products Therapy Area: Breast Cancer, Colorectal Cancer, Lung Cancer, Lymphoma End User: Hospitals, Clinics, Home Care, Specialty Pharmacies Delivery Mode: Injection, Infusion, Oral, Subcutaneous |
| Companies Covered | Sandoz International GmbH, Celltrion Inc., Pfizer Inc., Amgen Inc., Samsung Bioepis, Biocon, Coherus Biosciences, Merck & Co., Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oncology Biosimilars Market Emerging Trajectories
Continuous manufacturing architectures are displacing batch processes in bioreactor operations, while regulatory convergence efforts and procurement centralization are compressing traditional commercialization playbooks across Atlantic markets.
Single-use bioreactor systems are absorbing stainless-steel capacity in multi-product facilities, enabling rapid product changeovers that reduce campaign downtime. Contract manufacturers serving European hospital tender markets are adopting disposable flow paths to minimize cross-contamination validation burdens. This technology is absorbing capital that previously anchored dedicated stainless-steel trains, compressing facility repurposing timelines from years to months.
EU CSRD sustainability disclosure requirements are mandating granular carbon footprint reporting across pharmaceutical supply chains, extending from active ingredient synthesis through cold-chain distribution. EMA's expanded pharmacovigilance guidelines are synchronizing with these disclosures to create integrated compliance frameworks. Oncology biosimilar manufacturers with Songdo and European manufacturing footprints are consolidating ESG reporting architectures to satisfy dual regulatory streams.
Hospital pharmacy committees are consolidating formulary decisions through regional therapeutic evaluation boards, displacing individual prescriber autonomy in biosimilar selection. Germany's Gemeinsamer Bundesausschuss and France's HAS are standardizing interchangeability protocols that accelerate institutional switching. This concentration is most visible in Rhineland-Palatinate and Ile-de-France hospital clusters, where centralized tendering now captures over half of trastuzumab and rituximab volume.
Oncology Biosimilars Market Segmentation
Oncology biosimilar portfolios require precise segment targeting to match manufacturing scale with reimbursement pathways. Each dimension below reveals distinct margin profiles and access barriers that shape commercial strategy.
Product Type:
Standalone biologic substitutes dominate hospital procurement, while embedded combination therapies require deeper clinical integration partnerships.
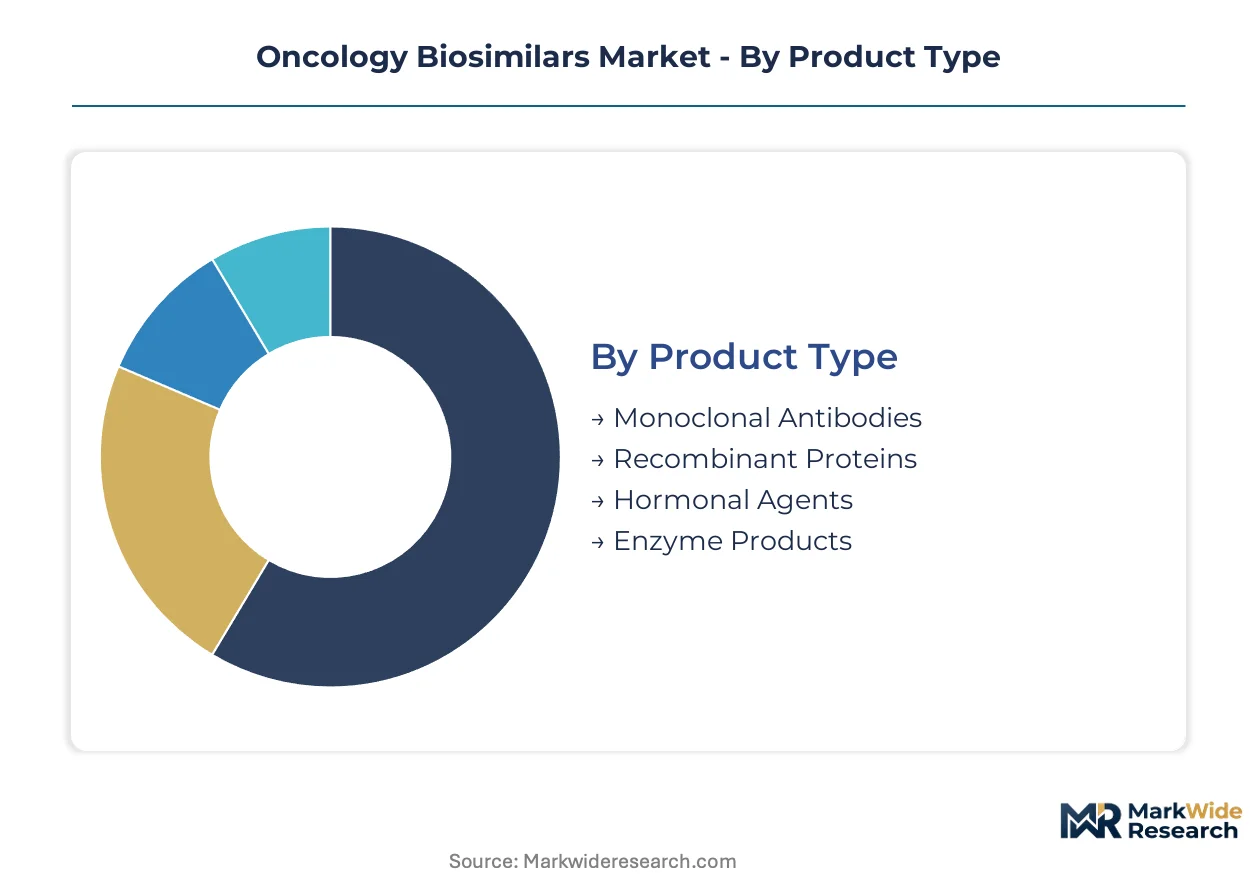
- Monoclonal Antibodies:These recombinant immunoglobulins target specific tumor antigens with glycosylation patterns requiring mammalian cell culture precision. Demand concentrates in German and French hospital systems where centralized tenders for trastuzumab and rituximab analogues capture bulk volume. EMA interchangeability guidelines accelerate formulary placement compared with FDA pathways.
- Recombinant Proteins:Engineered cytokines and growth factors manufactured through bacterial or yeast expression systems offer simpler upstream processing. Clinics in Spain and Italy are expanding procurement of erythropoietin and G-CSF biosimilars as outpatient administration models reduce infusion center burden.
- Hormonal Agents:Peptide-based therapies for hormone-dependent malignancies.
- Enzyme Products:Replacement therapies addressing metabolic complications in oncology supportive care.
Monoclonal antibodies lead volumes today; recombinant proteins are gaining share fastest through subcutaneous formulation expansion.
Therapy Area:
Cost tier stratification separates curative-intent regimens from chronic management protocols across reimbursement systems.
- Breast Cancer:HER2-targeted biosimilars command the largest addressable patient population among solid tumors. Germany's Gemeinsamer Bundesausschuss has standardized trastuzumab switching protocols that compress tender negotiation timelines for reference product transitions.
- Colorectal Cancer:Anti-EGFR and anti-VEGF biosimilars serve adjuvant and metastatic settings with distinct dosing schedules. French HAS evaluations for bevacizumab analogues are creating precedent for indication extrapolation acceptance in Western European markets.
- Lung Cancer:Immuno-oncology biosimilar development faces complex PD-1/PD-L1 target fragmentation.
- Lymphoma:CD20-directed therapies for B-cell malignancies.
Breast cancer leads volumes today; colorectal cancer is expanding most quickly through adjuvant protocol standardization.
End User:
Customer type fragmentation requires differentiated distribution architectures and cold-chain investments.
- Hospitals:Inpatient infusion centers with centralized pharmacy governance and committee-driven formulary decisions. Rhineland-Palatinate and Ile-de-France clusters now capture over half of trastuzumab and rituximab volume through regional purchasing alliances.
- Specialty Pharmacies:Outpatient dispensing with patient support programs and adherence monitoring. Subcutaneous administration modes are shifting patient volumes from hospital infusion suites to these settings in the Netherlands and Belgium.
- Clinics:Community oncology practices with limited biosimilar procurement expertise.
- Home Care:Self-administration models requiring patient training infrastructure.
Hospitals lead volumes today; specialty pharmacies are climbing the fastest through subcutaneous delivery expansion.
Delivery Mode:
Supply concentration varies sharply between institutional infusion infrastructure and patient-administered alternatives.
- Subcutaneous:Prefilled syringes and autoinjector devices enabling outpatient administration without infusion center capacity constraints. Samsung Bioepis has anchored competitive positioning through formulation expertise in this delivery mode.
- Infusion:Intravenous delivery requiring healthcare professional supervision and dedicated chair time. Hospital pharmacies in Germany maintain preference for this mode in curative-intent regimens where therapeutic drug monitoring protocols are established.
- Injection:Intramuscular or intravenous bolus administration.
- Oral:Small-molecule oncology generics rather than biologic biosimilars.
Infusion leads volumes today; subcutaneous is gaining share fastest through patient convenience and total cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology biosimilar manufacturing talent clusters in German chemical-pharma corridors, Swiss biotech hubs, and South Korean industrial zones anchor regional supply capacity. Regulatory divergence between FDA immunogenicity thresholds and EMA interchangeability protocols creates asymmetric commercialization timelines across Atlantic markets.
Germany
Hospital procurement consolidation through Rhineland-Palatinate purchasing alliances drives volume concentration for trastuzumab and rituximab analogues. The Gemeinsamer Bundesausschuss has standardized therapeutic switching protocols that compress tender negotiation cycles. Bavaria's biologics manufacturing corridor between Munich and Penzberg hosts multi-product facilities with single-use bioreactor modernization underway.
United States
Specialty pharmacy networks in Florida and Texas are absorbing subcutaneous formulation volumes shifted from hospital infusion centers. FDA interchangeability designation requirements for switching studies extend development timelines and inflate immunogenicity protocol costs. The Research Triangle Park cluster in North Carolina anchors contract manufacturing capacity serving mid-tier developers.
South Korea
Songdo's vertically controlled bioreactor parks supply monoclonal antibody capacity for Asia-Pacific tender markets. The Ministry of Food and Drug Safety aligns pre-market review timelines with WHO prequalification standards to accelerate emerging market access. Seoul Capital Area headquarters coordinate regional distribution into Southeast Asian hospital systems.
France
Île-de-France hospital clusters now capture over half of national bevacizumab biosimilar volume through centralized HAS evaluation protocols. ANSM pharmacovigilance integration with EU CSRD sustainability disclosures creates dual compliance frameworks for manufacturers. Lyon bioproduction facilities are upgrading glycosylation control systems to meet Green Deal pharmaceutical mandates.
India
Hyderabad and Bangalore biotech corridors export recombinant protein capacity to regulated European and US markets. CDSCO abbreviated approval pathways for well-characterized biologics compress entry timelines for domestic developers. Maharashtra's contract research organizations are assembling analytical biosimilarity packages for multinational submission portfolios.
Oncology Biosimilars Market Vendor Landscape
The competitive structure tilts toward vertically integrated biologics specialists with captive bioreactor capacity and formulation expertise. Market concentration splits between European pharmaceutical conglomerates with legacy generics infrastructure and Asian biotech platforms with single-use manufacturing scale. Two archetypes dominate: multi-product biologics generalists with hospital tender relationships, and monoclonal antibody specialists with subcutaneous delivery platforms. Capacity expansion and regulatory submission acceleration represent the dominant competitive vectors as interchangeability deadlines approach.
Among European-based pharmaceutical developers, Sandoz International GmbH and Novartis AG occupy positions anchored by established hospital procurement channels and multi-territory regulatory portfolios. Asian biotech platforms exemplify the manufacturing-scale archetype, with Celltrion Inc. and Samsung Bioepis representing vertically controlled production models. These four entities collectively illustrate the geographic and strategic bifurcation shaping competitive dynamics: European players leverage formulary relationships while Korean specialists emphasize bioreactor throughput and delivery innovation.
| Leading Market Players |
|---|
| Sandoz International GmbH |
| Celltrion Inc. |
| Pfizer Inc. |
| Amgen Inc. |
| Samsung Bioepis |
| Biocon |
| Coherus Biosciences |
| Merck & Co., Inc. |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
Bioprocess engineering talent concentration in Bavaria's Munich-Penzberg corridor anchors labor-cost differentials that widen pricing-tier spreads between premium EMA-certified batches and economy-grade tender supplies. Mammalian cell culture specialists command wage premiums that propagate through monoclonal antibody production costs, compressing margins for manufacturers without captive workforce development programs.
Pricing Analysis
Bundled infusion services versus unbundled product-only procurement splits pricing structures across German hospital systems. Three-tier pricing structure across premium, standard, and economy levels separates originator-branded reference products from EMA-interchangeable biosimilars and non-interchangeable economy tenders. Price differentiation stems from glycosylation certification grade and cold-chain reliability guarantees. Pricing pressure stems from centralized tendering mechanisms in Rhineland-Palatinate that consolidate volume and compress supplier margins. Hospital pharmacy committees exhibit highest price sensitivity, while specialty pharmacies absorbing subcutaneous volumes prioritize formulation convenience over per-unit cost.
Supply Chain Analysis
Workforce availability constraints in mammalian cell culture operations concentrate supply capacity across Germany, South Korea, and Switzerland. Bioreactor operations draw from Chinese-sourced single-use consumables, US-origin chromatography resins, and European-produced cell culture media. Supply chain risk centers on single-source vulnerability for protein A affinity chromatography resins critical to downstream purification. Distribution runs through regional hospital purchasing alliances in Western Europe and specialty pharmacy networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oncology biosimilar portfolios offer margin-expansion pathways through subcutaneous formulation premiums that offset reference product price erosion. Manufacturing automation and single-use bioreactor standardization compress per-batch labor costs, enabling competitive positioning across tender tiers.
For Market Incumbents: Anchor formulary relationships through integrated patient support programs that lock hospital pharmacy committees into switching protocols. Defend against emerging subcutaneous specialists by backward integration into prefilled syringe device manufacturing. EMA interchangeability guideline acceleration in Germany threatens first-mover positions without continuous immunogenicity data generation.
For New Entrants and Emerging Players: WHO prequalification pathway expansion in Southeast Asia opens a window for volume anchors with standardized analytical packages. Target outpatient administration models in the Netherlands and Belgium where subcutaneous penetration remains below Western European averages. Pursue contract manufacturing partnerships with Songdo-based bioreactor operators to bypass capital-intensive facility builds.
For Investors and Strategic Acquirers: European pharmaceutical conglomerates with legacy generics infrastructure are the most active acquirer in this space, seeking monoclonal antibody specialists with subcutaneous delivery platforms. Long-term viability hinges on regulatory submission acceleration capabilities and tender relationship depth. Watch for FDA interchangeability designation delays as inflection indicators for US market entry timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Single-Use Bioreactor Modernization | Disposable flow paths reduce cross-contamination validation burdens for multi-product European facilities serving German tender markets. |
| Subcutaneous Formulation Development | Prefilled syringe platforms shift patient volumes from hospital infusion centers to specialty pharmacy networks in the Netherlands. |
| EMA Interchangeability Submission | Accelerated formulary placement in France's HAS evaluation protocols compresses commercialization timelines versus FDA pathways. |
| Backward Integration into Device Manufacturing | Captive autoinjector production secures supply continuity for Samsung Bioepis-style outpatient administration models. |
| WHO Prequalification Alignment | Standardized analytical packages unlock emerging market tenders in Southeast Asian hospital systems. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads, hospital procurement managers, formulary directors, and bioprocess engineers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up volume triangulation across product type and therapy area segments converged with top-down market sizing anchored to reference product patent expiry schedules.
Comparable historical periods anchored the forecast window to post-patent expiry adoption curves across the analysis window. The analytical framework modeled segmentation across monoclonal antibody versus recombinant protein categories, breast versus colorectal cancer therapy areas, and hospital versus specialty pharmacy end-user channels. CAGRs derived from volume-weighted average price trajectories and tender penetration assumptions. Glycosylation batch consistency rates and EMA interchangeability approval timelines served as industry-specific forecast inputs.
Revisions become necessary when FDA immunogenicity study requirements harden, EMA sustainability disclosure mandates expand, or reference product lifecycle management strategies erect secondary IP barriers. Forecasts reflect assumptions regarding tender mechanism centralization and subcutaneous formulation adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Immunology Biosimilars Market
Biosimilars
Europe Generic Injectables Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Etanercept Market
Biosimilars
Biosimilar Testing Services Market
Biosimilars
Global Biosimilars Market
Biosimilars
Dasatinib Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Global Sirolimus Market
Biosimilars
Imatinib Drug Market
Biosimilars
US Biosimilars Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Herceptin Biosimilar Market
Biosimilars
Global Biosimilar Monoclonal Antibodies (Mabs) Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
Retinal Biosimilars Market