
 Carbon and Energy Software Market | 2026-2036
Carbon and Energy Software Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon and Energy Software Market Analysis
The pool of certified carbon accountants and energy data engineers is collapsing across developed economies, creating a bottleneck that software vendors must address through automation. SAP SE leverages its entrenched ERP footprint to embed emissions modules directly into procurement workflows. Microsoft Corporation anchors its position through Azure sustainability APIs that integrate with existing enterprise data lakes. Schneider Electric SE dominates industrial energy management with hardware-software bundles that lock in long-term platform contracts.
Carbon and energy software encompasses platforms that ingest utility meter data, fuel consumption records, and supply chain activity metrics to calculate greenhouse gas inventories and model decarbonization pathways, typically processing inputs against emission factors from databases such as DEFRA or EPA and outputting audit-ready reports for voluntary and mandatory disclosure. Emissions tracking leads product type adoption as regulators mandate granular Scope 1-3 disclosure, while cloud-based deployment grows fastest among mid-market entrants seeking lower implementation overhead. Corporates represent the deepest end-user margin pool due to complex multi-site energy procurement and investor-grade sustainability reporting requirements.
The EPA enforces mandatory greenhouse gas reporting for large stationary sources and fuel suppliers, compelling covered entities to adopt validated calculation engines, while the EU Green Deal's Corporate Sustainability Reporting Directive expands audit obligations across thousands of European firms. The SEC's climate disclosure rules, though contested, signal converging global standards that reshape product roadmaps toward attestation-ready data architectures. Stakeholders must monitor which jurisdictions next mandate third-party verification of software-derived emissions claims, as this determines platform certification requirements and competitive moats.
Market Dynamics
The convergence of mandatory climate disclosure rules and collapsing talent pools is forcing software vendors to automate carbon accounting workflows that previously required certified specialists, compressing implementation timelines from months to weeks.
Growth Catalysts
- EU Green Deal CSRD mandates:Thousands of European firms must submit audit-grade Scope 1-3 emissions data, creating immediate demand for validated calculation engines and disclosure-ready reporting modules.
- Scope 3 supply chain complexity:Multinational corporates face investor pressure to trace emissions through tier-2 and tier-3 suppliers, driving procurement of platforms that ingest supplier activity metrics at scale.
- Cloud deployment economics:Mid-market entrants previously priced out of on-premise implementations now access carbon accounting through subscription models with minimal IT overhead.
Market Restraints
- Certified carbon accountant scarcity:The pool of qualified professionals capable of validating software outputs is contracting across Germany, the United Kingdom, and the United States, creating verification bottlenecks.
- Emission factor database fragmentation:Inconsistent methodologies between DEFRA, EPA, and ISO carbon intensity datasets force vendors to maintain multiple calculation engines, raising development costs.
- Legacy ERP integration friction:Industrial facilities running decades-old energy management systems face prohibitive reconfiguration costs to enable automated data ingestion.
Strategic Opportunities
- India manufacturing compliance wave:The country's Bureau of Energy Efficiency is tightening industrial energy audit requirements, creating first-mover advantage for cloud-based platforms localized to Indian accounting standards.
- AI-powered anomaly detection:Machine learning models trained on utility interval data can flag meter misreadings and data gaps that currently escape rule-based validation, improving inventory accuracy.
- Hardware-software bundling:Vendors with captive sensor and smart meter production can offer integrated energy-carbon packages that lock in long-term platform contracts through equipment financing.
Industry Challenges
- Attestation-ready data architecture:Platforms must reconstruct audit trails for every emissions calculation to satisfy emerging third-party verification requirements, demanding expensive engineering retrofits.
- Cross-functional implementation coordination:Successful deployments require alignment between sustainability officers, procurement teams, and IT departments with conflicting priorities and timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon and Energy Software Market |
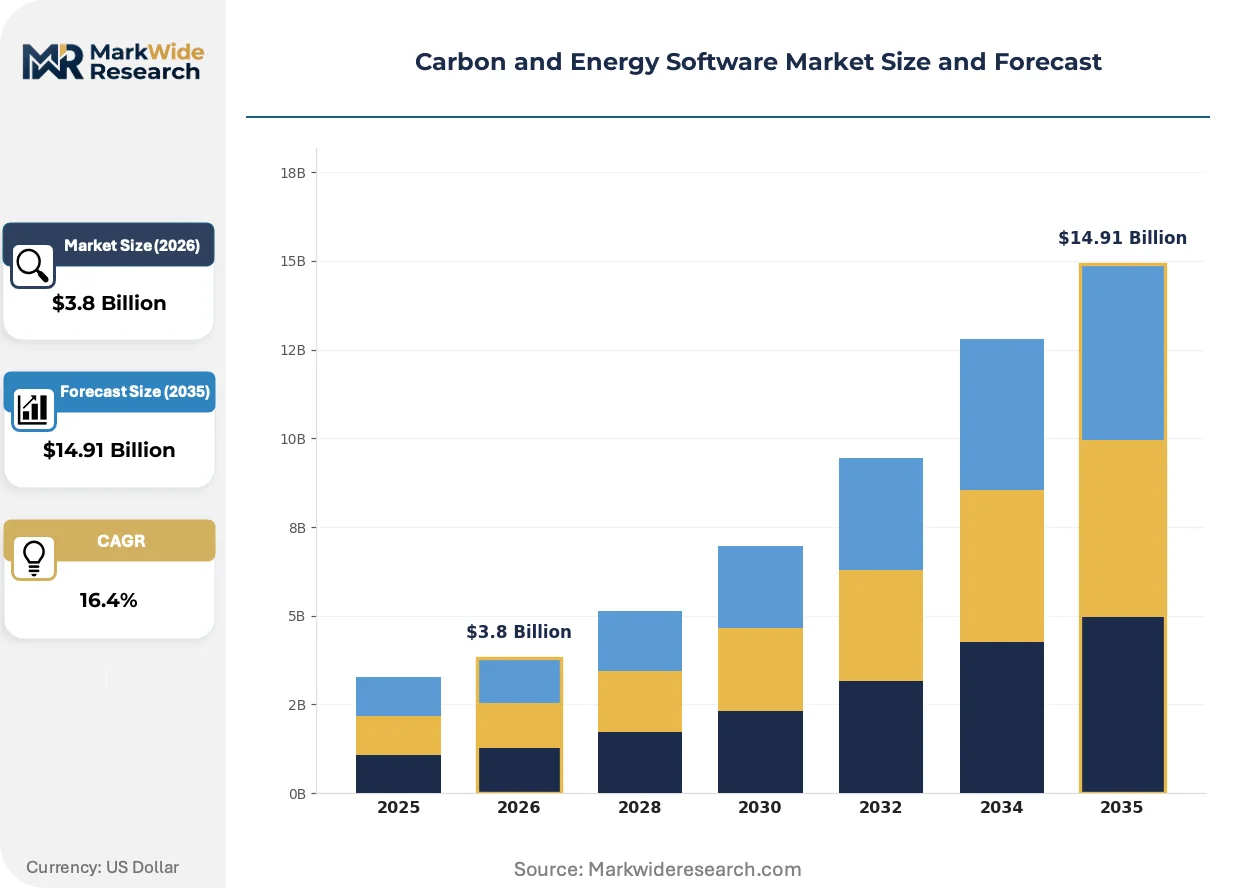
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Management, Emissions Tracking, Carbon Footprint Calculation, Renewable Energy Analysis Deployment: On-Premises, Cloud-Based, Hybrid, Software as a Service End User: Utilities, Corporates, Government Agencies, Non-Profit Organizations Application: Compliance Reporting, Performance Optimization, Data Analysis, Risk Assessment |
| Companies Covered | Persefoni AI Inc., Sweep SAS, Plan A Earth GmbH, Sphera Solutions Inc., Wolters Kluwer N.V., SAP SE, Microsoft Corporation, Schneider Electric SE, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon and Energy Software Market Emerging Trajectories
Carbon and energy software is pivoting from retrospective reporting tools toward predictive decarbonization planning systems, embedding optimization engines that model pathway scenarios against real-time energy price signals.
Automated emissions factor matching is bifurcating platform architectures into two tiers: lightweight tools for small emitters using standardized regional defaults, and enterprise-grade systems that ingest supplier-specific primary data for precision Scope 3 accounting. Fortune 500 sustainability teams are demanding the latter despite implementation complexity, compressing margins for vendors trapped in the former category.
The SEC's contested climate disclosure rules are reshaping product roadmaps regardless of final implementation, as software vendors anticipate converging standards by building attestation-ready data architectures that satisfy both voluntary TCFD frameworks and emerging mandatory regimes. Platforms serving publicly traded US corporates are prioritizing auditor-facing documentation features over user interface polish.
Buyers are consolidating vendor relationships around integrated energy-carbon suites rather than point solutions, displacing standalone carbon accounting specialists in favor of platforms that combine utility bill management, facility optimization, and emissions reporting in unified workflows. This preference shift is most visible among industrial conglomerates with multi-site operations across Texas, Ohio, and Pennsylvania seeking to reduce procurement overhead.
Carbon and Energy Software Market Segmentation
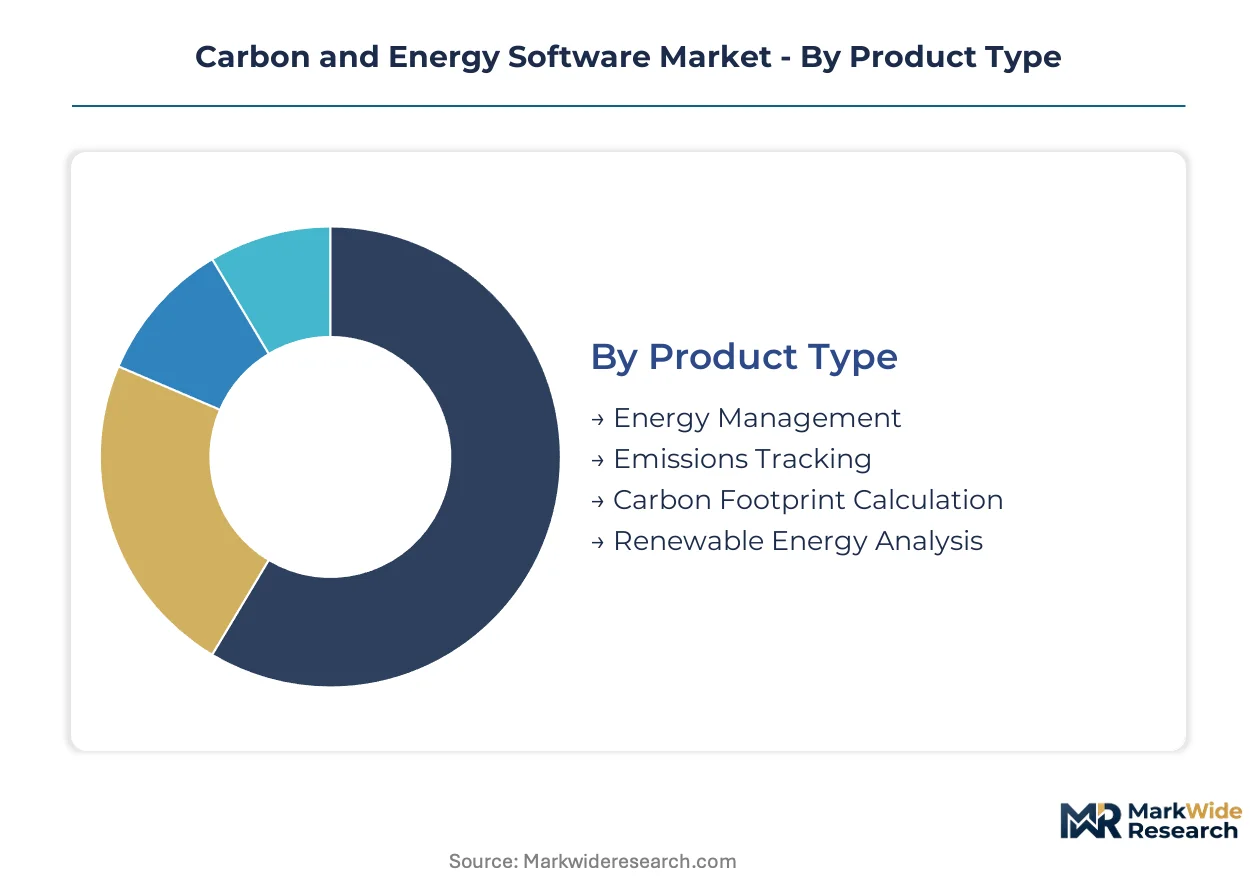
Carbon and energy software vendors configure product architectures around four intersecting dimensions that determine implementation complexity and pricing power. Deployment models and end-user profiles shape margin structures more dramatically than functional modules alone.
Product Type:
Domestic procurement concentrates in emissions tracking and energy management modules serving regulated industrial bases in Germany, the United States, and Japan. Export-led demand flows toward carbon footprint calculation tools purchased by multinational corporates with supply chain exposure across emerging manufacturing economies.
- Energy Management:Platforms ingest real-time utility interval data, building automation signals, and equipment telemetry to optimize load scheduling against time-of-use tariffs. Demand clusters among Texas and Ohio industrial conglomerates seeking to reduce peak demand charges and qualify for utility demand response incentives. Hardware-software bundles from captive sensor manufacturers lock in long-term platform contracts through equipment financing structures.
- Emissions Tracking:Systems calculate Scope 1-3 inventories by processing fuel consumption records, travel databases, and supplier activity metrics against emission factor libraries. European corporates under CSRD mandates drive procurement of audit-ready modules with third-party verification pathways. The EPA's mandatory reporting rules for large stationary sources compel parallel adoption across US oil refining and power generation facilities.
- Carbon Footprint Calculation:Lifecycle assessment engines model product-level emissions from raw material extraction through end-of-life disposal.
- Renewable Energy Analysis:Procurement optimization tools evaluate power purchase agreements, on-site generation economics, and grid interconnection feasibility.
Energy Management commands the established base. The steepest expansion runs through Emissions Tracking.
Deployment:
Cost tier stratification separates enterprise buyers with dedicated IT infrastructure from mid-market entrants seeking minimal implementation overhead. Premium deployments demand six-figure professional services engagements; economy tiers operate through self-service configuration wizards.
- On-Premises:Licensed software running on client-managed servers behind corporate firewalls, demanded by defense contractors and financial institutions with data sovereignty requirements. German automotive manufacturers and Japanese precision engineering firms maintain this preference despite higher total cost of ownership.
- Cloud-Based:Multi-tenant architectures with browser-based interfaces and API connectivity to enterprise data lakes. Mid-market corporates in the United Kingdom and Netherlands accelerate migration to reduce IT staffing burdens and accelerate implementation timelines from months to weeks.
- Hybrid:Sensitive calculation engines remain on-site while reporting modules sync to cloud dashboards for executive consumption.
- Software as a Service:Subscription pricing with usage-based tiers for meter point counts and supplier data volumes.
On-Premises retains the highest contract values. Cloud-Based is climbing the fastest as procurement shifts from IT-led to sustainability-team-led buying centers.
End User:
Customer type determines feature prioritization: utilities demand grid-scale analytics, corporates require investor-grade disclosure workflows, agencies need audit trails for enforcement actions.
- Utilities:Grid operators and retail energy providers deploy platforms to manage customer energy efficiency portfolios, comply with state-level renewable portfolio standards, and model distribution system decarbonization pathways. California investor-owned utilities and Texas municipal utilities represent concentrated procurement pools.
- Corporates:Multinational manufacturers and technology firms with complex multi-site energy procurement and Scope 3 supply chain accounting requirements. Fortune 500 sustainability teams in the United States and EU-27 member states drive demand for attestation-ready data architectures.
- Government Agencies:National environmental regulators and municipal sustainability offices tracking public building portfolios and procurement emissions.
- Non-Profit Organizations:Climate advocacy groups and industry associations conducting sector-wide benchmarking studies with limited software budgets.
Corporates generate the deepest margin pool. Government Agencies are expanding most quickly as stimulus-funded building retrofit programs mandate energy tracking.
Application:
Maturity stages separate retrospective reporting tools from predictive optimization engines, with pricing premiums attaching to forward-looking capabilities.
- Compliance Reporting:Audit-ready disclosure modules structured around EPA greenhouse gas reporting protocols, EU CSRD templates, and emerging SEC climate disclosure requirements. Demand concentrates among publicly traded US corporates and EU-registered firms with 2024-2025 filing deadlines.
- Performance Optimization:Real-time analytics engines identifying energy waste patterns and automated control sequences for building systems. Industrial facilities across Pennsylvania and Illinois deploy these tools to reduce per-unit production energy intensity.
- Data Analysis:Exploratory dashboards for sustainability teams investigating emission hotspots without predefined reporting obligations.
- Risk Assessment:Scenario modeling for carbon price exposure, physical climate risk to assets, and supply chain disruption from climate policy shifts.
Compliance Reporting commands the established base. Performance Optimization is gaining share fastest as energy price volatility drives operational urgency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of mandatory greenhouse gas reporting for large stationary sources anchors North American demand, while EU Green Deal CSRD mandates accelerate procurement across European industrial clusters. Software vendors prioritize attestation-ready architectures in jurisdictions with converging disclosure standards.
United States
Fortune 500 sustainability teams in Texas and Ohio drive procurement of emissions tracking modules for SEC climate disclosure readiness. EPA mandatory reporting rules compel oil refining and power generation facilities to adopt validated calculation engines. Industrial conglomerates across Pennsylvania seek unified energy-carbon suites to reduce multi-site procurement overhead.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg maintain on-premise deployment preferences despite higher total cost of ownership. EU Green Deal CSRD expands audit obligations across thousands of firms with 2024-2025 filing deadlines. Chemical clusters along the Rhine River accelerate cloud migration to compress implementation timelines from months to weeks.
United Kingdom
Mid-market corporates in London and the Midlands accelerate cloud-based adoption to reduce IT staffing burdens. DEFRA emission factor databases require vendors to maintain parallel calculation engines alongside EPA and ISO datasets. Financial institutions in the City of London demand data sovereignty features for Scope 3 supply chain accounting.
India
The Bureau of Energy Efficiency tightens industrial energy audit requirements, creating first-mover advantage for localized cloud platforms. Manufacturing hubs in Maharashtra and Gujarat face compliance deadlines for facility-level energy tracking. Software vendors embed Indian accounting standards into subscription models targeting mid-market entrants previously priced out of enterprise implementations.
Japan
Precision engineering firms in the Chubu region around Nagoya sustain preference for licensed software behind corporate firewalls. METI industrial policy encourages hardware-software bundling for long-term platform contracts through equipment financing. Technology firms in Tokyo-Osaka corridors pilot AI-powered anomaly detection trained on utility interval data.
Carbon and Energy Software Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with ERP-embedded modules commanding premium pricing against standalone carbon accounting specialists. The vendor base stratifies into three tiers: enterprise platforms with captive hardware production, cloud-native entrants with automated workflows, and legacy compliance tools facing displacement. Dominant competitive moves include strategic partnerships for emission factor database licensing and geographic expansion through regulatory tailwinds.
Within the ERP-embedded tier, SAP SE and Microsoft Corporation represent archetypes of platform incumbents leveraging existing enterprise data lake footprints. Schneider Electric SE exemplifies hardware-software bundling strategies that lock in long-term contracts through integrated energy-carbon packages. Among pure-play specialists, Persefoni AI Inc. and Sweep SAS occupy positions as cloud-native entrants targeting mid-market sustainability teams with reduced implementation overhead.
| Leading Market Players |
|---|
| Persefoni AI Inc. |
| Sweep SAS |
| Plan A Earth GmbH |
| Sphera Solutions Inc. |
| Wolters Kluwer N.V. |
| SAP SE |
| Microsoft Corporation |
| Schneider Electric SE |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
Cloud-native SaaS architectures displacing licensed on-premise deployments simultaneously redistribute supply geography toward India and Ireland hosting clusters while compressing pricing economics through subscription standardization. This substitution dynamic concentrates platform development talent in Bangalore and Dublin while forcing legacy vendors to absorb professional services margin erosion.
Pricing Analysis
North American enterprise contracts command 40-60% premiums over equivalent UK mid-market subscriptions due to CSRD attestation requirements and SEC disclosure readiness features. Pricing stratifies across premium attestation-ready tiers, standard compliance modules, and economy self-service configurations, with differentiation resting on auditor-facing documentation depth and API integration complexity. Cost compression in the standard tier intensifies as cloud-native entrants automate implementation workflows previously requiring six-figure professional services engagements. Mid-market sustainability teams in the Netherlands exhibit highest price sensitivity, while Fortune 500 energy procurement officers in Texas prioritize audit trail completeness over subscription cost.
Supply Chain Analysis
India and Ireland anchor cloud infrastructure provisioning for carbon accounting platforms, with Bangalore development centers producing calculation engine codebases and Dublin data centers hosting EU-regulated client workloads. The software supply chain draws from open-source emission factor libraries, proprietary DEFRA and EPA database licenses, and third-party utility data aggregation services. Single-source vulnerability concentrates in EPA emission factor database access, where API rate limits and licensing terms constrain vendor scaling. Distribution runs through direct enterprise sales teams for Fortune 500 accounts, supplemented by systems integrator partnerships serving mid-market manufacturing conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon and energy software functions as a service-attach play where recurring subscription revenue from emissions tracking modules expands faster than one-time energy management hardware sales, with SaaS gross margins reaching 75-85% versus 35-45% for bundled equipment.
For Market Incumbents: Shield installed base relationships through embedded ERP integration moats that lock procurement workflows into existing data lake architectures. Deepen backward integration into captive sensor manufacturing to offer integrated energy-carbon packages that raise switching costs. Prioritize CSRD attestation certification investments to defend against cloud-native entrants automating audit-ready reporting. For New Entrants and Emerging Players: Differentiate on AI-powered anomaly detection trained on utility interval data, a capability gap in legacy rule-based validation systems. Target India manufacturing compliance wave as the Bureau of Energy Efficiency tightens industrial audit requirements with localized cloud platforms. Pursue channel partnerships with Indian systems integrators rather than direct sales to compress customer acquisition costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed carbon accounting specialists lacking ERP integration depth or hardware bundling capabilities. Long-term viability across the analysis window hinges on attestation-ready data architecture investments satisfying converging EU and US disclosure standards. Monitor SEC rule finalization timing as inflection indicator for US corporate procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP-embedded emissions modules capture procurement workflow data from SAP and Microsoft data lakes. |
| Acquisition of Specialist Firm | AI anomaly detection startups fill capability gaps in legacy rule-based validation engines. |
| Geographic Expansion | India localization addresses Bureau of Energy Efficiency industrial audit compliance deadlines. |
| Strategic Partnership | Emission factor database licensing agreements with DEFRA and EPA secure calculation engine inputs. |
| Product Launch | Attestation-ready architectures satisfy CSRD third-party verification requirements ahead of filing deadlines. |
Methodological Framework
The analysis maps emissions tracking, energy management, and carbon footprint calculation sub-sectors, each validated through sustainability officers, IT procurement leads, and energy data engineers at industrial conglomerates and cloud-native software vendors. Primary interviews with utility demand response program managers and ERP integration specialists combined with secondary validation against EPA greenhouse gas reporting protocols, EU CSRD regulatory filings, and DEFRA emission factor database releases. Bottom-up segmentation sizing triangulates against top-down market aggregation across deployment models and end-user categories.
Consistency checks validated volume and value outputs against hyperscaler sustainability API disclosures and industrial energy management system procurement databases across the projection horizon. The analytical framework models deployment architecture, organization size tier, vertical industry, integration complexity depth, and regional regulatory cluster. CAGRs derive from segment-level growth rate synthesis incorporating cloud migration velocity and mandatory disclosure rule implementation timing. Forecast inputs include utility smart meter penetration curves and certified carbon accountant supply constraints.
Material uncertainties — SEC rule litigation outcomes, EU Green Deal enforcement variance, and emission factor database methodology revisions — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory convergence and talent pool automation substitution rates. Recalibration cycles align with material shifts in mandatory disclosure jurisdictions and third-party verification requirement adoptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Smart Grid Software Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
Africa Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Power System Analysis Software Market
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
Spain Big Data Analytics in Energy Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Digital Energy Platform Market