
 Solar Digitalization Platform Market | 2026-2036
Solar Digitalization Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Digitalization Platform Market Intelligence
Silicon carbide power electronics is repositioning inverter architectures across utility-scale solar farms, trimming switching losses and enabling tighter integration with digital twin platforms. Tigo Energy leverages module-level power electronics to sustain granular monitoring revenue streams. RatedPower anchors cloud-based PV design automation for utility developers across Southern Europe. SenseHawk competes on drone-enabled site digitization for construction-phase asset documentation.
A solar digitalization platform comprises software, hardware, and service layers that ingest telemetry from inverters, weather stations, and SCADA systems to optimize energy yield, predict equipment failures, and automate compliance reporting. These systems typically process time-series data at sub-minute intervals while maintaining IEC 61850 communication protocols for substation interoperability. Cloud-based deployment now leads the market as utilities prioritize centralized fleet visibility over on-premises infrastructure. AI-driven analytics represents the fastest-expanding technology segment as machine learning models displace rule-based fault detection in predictive maintenance workflows.
FERC Order 2222 in the United States enables aggregated distributed solar resources to participate in wholesale electricity markets, directly expanding addressable demand for grid-edge digitalization platforms. The EU AI Act imposes risk-classification requirements on automated energy dispatch algorithms, compelling platform vendors to embed explainability modules. Stakeholders must weigh interoperability investments against the fragmentation of national grid codes as electrification targets harden across jurisdictions.
Market Dynamics
Silicon carbide power electronics is compressing inverter switching losses while tightening integration with cloud-based digital twin architectures, forcing platform vendors to rebuild telemetry pipelines around sub-minute data granularity.
Growth Catalysts
- FERC Order 2222:Aggregated distributed solar resources now access wholesale electricity markets in the United States, expanding addressable demand for grid-edge digitalization platforms.
- EU F-Gas Regulation:Real-time emissions-linked performance monitoring is becoming mandatory for photovoltaic installations across member states, accelerating retrofit cycles.
- Cloud-based asset management:Utility-scale solar operators in Germany, Spain, and Italy are replacing on-premises SCADA with centralized fleet visibility tools.
Market Restraints
- IEC 61850 interoperability costs:Substation protocol compliance requires expensive hardware retrofits for legacy inverter fleets.
- Fragmented national grid codes:Platform vendors face duplicated certification burdens across Germany, Italy, and Spain.
- Edge computing hardware:On-premise deployment remains capital-intensive for smaller distributed solar operators.
Strategic Opportunities
- Drone-enabled site digitization:Construction-phase asset documentation using aerial photogrammetry is penetrating Southern European utility-scale projects.
- EU AI Act explainability mandates:Automated energy dispatch algorithms require embedded interpretability modules, creating service revenue for compliance vendors.
- Predictive maintenance AI:Machine learning fault detection is displacing rule-based systems in aging solar fleet retrofits.
Industry Challenges
- SCADA integration complexity:Legacy substation communication architectures resist seamless cloud migration.
- Data science talent scarcity:Machine learning model deployment for yield optimization requires scarce time-series analytics expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Digitalization Platform Market |
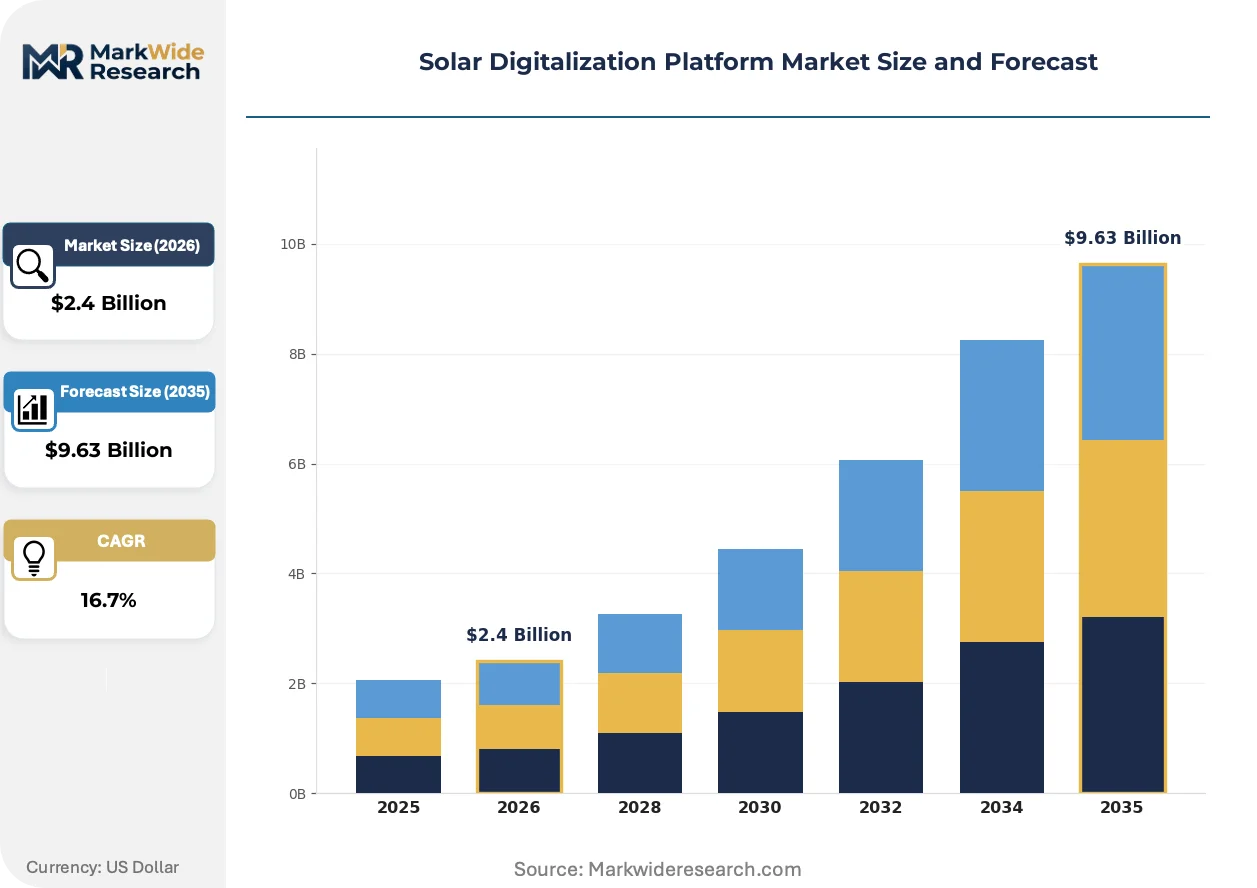
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $9.63 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Utilities, OEMs, Government, Enterprises Technology: IoT, AI, Blockchain, Machine Learning |
| Companies Covered | EnergySage, Enode, SenseHawk, SmartHelio, Solstice, Tigo Energy, RatedPower, Enpal, Scanifly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Digitalization Platform Market Strategic Shifts & Innovations
Digital twin architectures are absorbing module-level power electronics data streams, compressing the gap between physical asset performance and virtual simulation fidelity across utility-scale installations.
Digital twin platforms are unifying inverter telemetry, weather station inputs, and drone-captured construction documentation into single simulation environments. Utility developers in Spain and Italy are deploying these systems during project commissioning to validate as-built configurations against design models. This unification is collapsing the feedback loop between construction-phase documentation and operational yield optimization.
The EU AI Act risk-classification framework is imposing explainability requirements on automated energy dispatch algorithms. Platform vendors must now embed interpretability modules for high-risk AI systems used in grid balancing. Photovoltaic fleet operators in Germany face the steepest compliance timeline as their aggregated resources participate in frequency regulation markets.
Utility procurement departments are bundling digitalization platform contracts with long-term operations and maintenance agreements. This shifts vendor selection criteria from software licensing fees toward guaranteed availability metrics and predictive maintenance outcomes. Spanish utility-scale developers are pioneering this bundled contracting model for new solar park construction.
Solar Digitalization Platform Market Segmentation
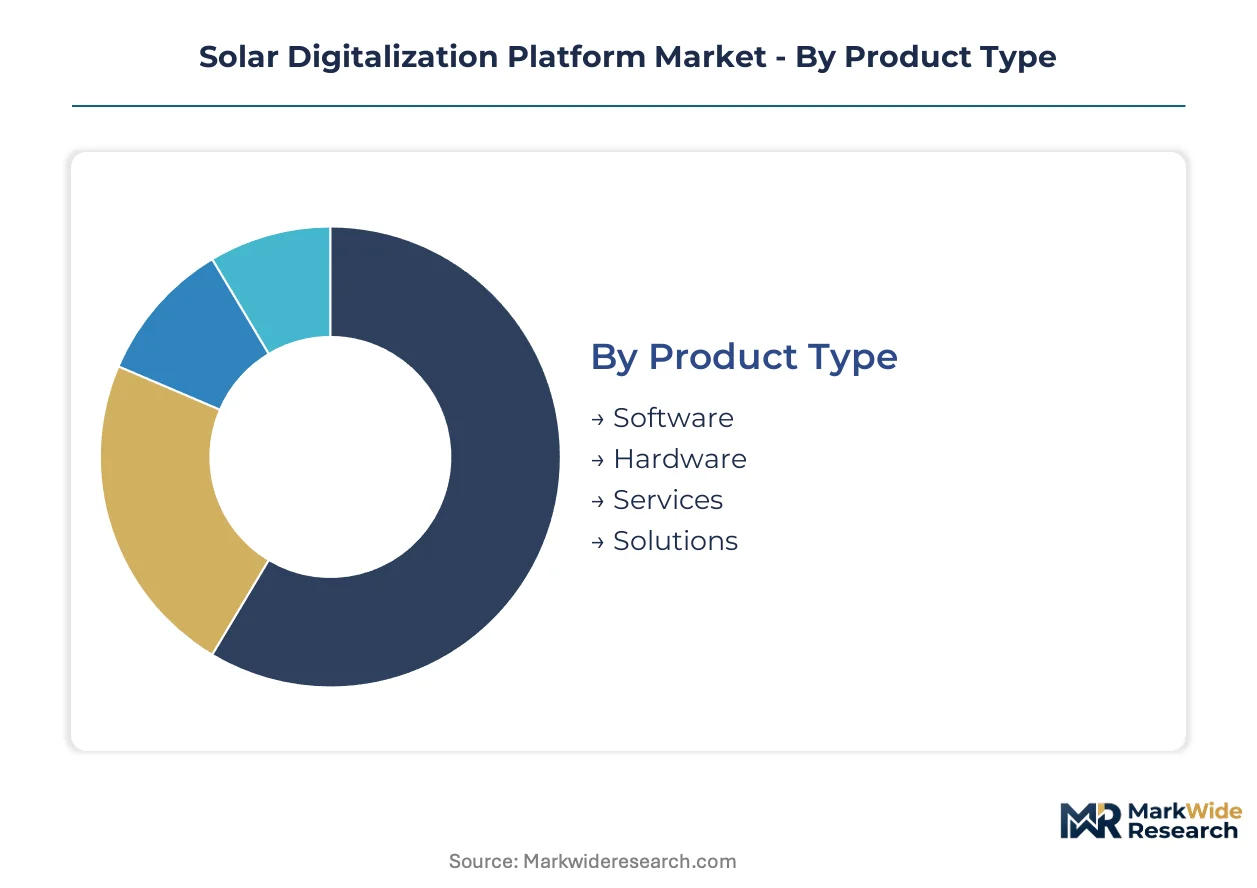
Platform architecture varies sharply by deployment mode and buyer sophistication. Procurement patterns cluster around cloud migration timelines and regulatory compliance mandates across utility-scale installations.
Product Type:
Standardization dominates software layers while hardware retains project-specific engineering requirements.
- Software:Cloud-native asset management applications ingest SCADA telemetry at sub-minute intervals. German and Spanish utilities prioritize these tools for centralized fleet visibility under EU F-Gas monitoring mandates.
- Hardware:Edge computing devices and protocol gateways bridge legacy inverter fleets to cloud platforms. IEC 61850 compliance requirements concentrate demand among retrofitting operators in Italy.
- Services:Implementation consulting and integration support for SCADA migration projects.
- Solutions:Bundled software-hardware-service packages with guaranteed availability SLAs.
Most installed capacity flows through Software. Expansion is steepest in Solutions.
Deployment:
Cost tier structures separate capital-intensive on-premise builds from operational-expense cloud models.
- On-Premises:Legacy SCADA architectures requiring dedicated server infrastructure and IT staffing. Smaller distributed operators in Southern Europe face prohibitive capital barriers.
- Cloud-Based:Centralized data lakes with API-driven analytics accessible across multi-site portfolios. Utility-scale developers in Germany and Spain lead adoption for predictive maintenance automation.
- Hybrid:Edge preprocessing with cloud aggregation for latency-sensitive control applications.
- Mobile:Field technician applications for construction-phase documentation and remote diagnostics.
Cloud-Based deployments carry the majority of new procurement. Hybrid architectures are climbing the fastest as frequency regulation markets demand millisecond response times.
End User:
Application maturity separates regulated utilities from speculative enterprise adopters.
- Utilities:Grid operators and independent power producers managing multi-gigawatt portfolios. FERC Order 2222 compliance in the United States and EU AI Act risk classification in Germany drive platform investments.
- OEMs:Inverter and module manufacturers embedding digitalization capabilities into factory warranties.
- Government:Public procurement for national solar monitoring infrastructure and emissions verification.
- Enterprises:Commercial and industrial off-takers with behind-the-meter installations.
Utilities command the largest contract values. Government procurement is expanding most quickly under Green Deal retrofit programs.
Technology:
Supply concentration in AI talent pools shapes competitive differentiation.
- IoT:Sensor networks for module-level monitoring and weather station integration. Spanish utility-scale projects deploy dense IoT meshes during construction-phase commissioning.
- AI:Automated energy dispatch and yield forecasting algorithms. Explainability mandates under the EU AI Act impose compliance costs on German frequency regulation participants.
- Blockchain:Immutable generation certificates and peer-to-peer energy trading settlement.
- Machine Learning:Time-series models for predictive maintenance and fault detection.
IoT sensor infrastructure underpins most operational deployments. AI analytics is gaining share fastest as rule-based systems retire from aging fleet retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor concentrates the densest deployment of predictive maintenance platforms for aging photovoltaic fleets. Utility-scale operators across Bavaria and North Rhine-Westphalia retrofit legacy inverters with cloud-based telemetry systems under tightening EU F-Gas Regulation mandates. Spanish solar parks in Extremadura and Andalusia pioneer drone-enabled construction documentation bundled with long-term operations contracts.
United States
Texas and California utility-scale developers drive demand for grid-edge digitalization platforms following FERC Order 2222 market access rules. The Federal Energy Regulatory Commission's aggregation standards compel independent power producers to deploy sub-minute telemetry for wholesale electricity participation. Arizona and Nevada solar clusters integrate silicon carbide inverter architectures with digital twin validation during commissioning.
Germany
Frequency regulation market participation forces German utilities to embed EU AI Act explainability modules in automated dispatch algorithms. The Federal Network Agency enforces real-time emissions monitoring under F-Gas Regulation retrofit timelines. Industrial solar operators in Saxony-Anhalt deploy hybrid edge-cloud architectures to meet millisecond response requirements for grid balancing services.
Spain
Andalusian and Extremadura solar parks bundle digitalization platform procurement with twenty-year operations agreements. The national grid operator's technical specifications require IEC 61850 protocol compliance for new utility-scale connections. Drone-enabled site digitization vendors concentrate construction-phase documentation contracts in the Guadiana Valley photovoltaic cluster.
Italy
Southern Italian operators in Puglia and Sicily face steep IEC 61850 hardware retrofit costs for legacy inverter fleets. The national energy regulator accelerates smart monitoring mandates for agricultural photovoltaic installations under EU Green Deal rural electrification programs. Industrial zones around Naples retrofit aging solar assets with predictive maintenance AI to reduce insurance premiums.
India
Gujarat and Rajasthan solar parks deploy machine learning fault detection for dust-related yield degradation. The Central Electricity Authority mandates centralized monitoring infrastructure for all utility-scale installations above designated capacity thresholds. Domestic platform vendors in Bangalore and Hyderabad compete on cost-optimized cloud deployment for distributed commercial rooftops.
Solar Digitalization Platform Market Key Industry Players
Strategic partnerships dominate the current landscape as platform vendors bundle software licensing with hardware procurement and long-term service agreements. The vendor base organizes into three tiers: established inverter manufacturers extending into digital services, pure-play software vendors with cloud-native architectures, and specialized drone documentation providers. Two archetypes command premium positioning: vertically integrated energy majors with captive solar portfolios, and independent software vendors with AI-driven predictive maintenance specialization. M&A activity and portfolio diversification represent the dominant competitive moves, with vendors acquiring complementary sensor hardware and machine learning talent pools.
Within the pure-play software tier, Tigo Energy and RatedPower exemplify divergent strategic positioning. SenseHawk anchors the aerial documentation specialist segment. These three companies occupy distinct competitive spaces: module-level power electronics integration, cloud-based design automation, and construction-phase site digitization respectively. Their geographic footprints reflect regional regulatory clustering, with European headquarters proximity to EU AI Act and F-Gas Regulation compliance demand centers.
| Leading Market Players |
|---|
| EnergySage |
| Enode |
| SenseHawk |
| SmartHelio |
| Solstice |
| Tigo Energy |
| RatedPower |
| Enpal |
| Scanifly |
| Others |
Cost & Logistics Intelligence
Silicon carbide substrate costs cascade through inverter hardware tiers before settling into software subscription pricing for utility-scale fleet operators. German and Spanish procurement departments negotiate bundled availability SLAs that compress margins on edge computing gateways while elevating premiums for AI-driven predictive maintenance modules.
Pricing Analysis
Input-cost pass-through from silicon carbide power electronics and IEC 61850 protocol gateways shapes SaaS-tiered subscription structures across deployment scales. Price differentiation rests on certification grade for EU AI Act explainability modules and geographic delivery cost for Southern European retrofit projects. Cost compression in hardware tiers intensifies as Chinese edge computing vendors enter distributed solar markets. Smaller agricultural photovoltaic operators in Italy exhibit highest price sensitivity, while German frequency regulation participants accept premium pricing for millisecond-response hybrid architectures.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based silicon carbide foundries serving European inverter manufacturers. Component sourcing draws from Germany for SCADA protocol gateways, China for edge computing hardware, and the United States for cloud infrastructure. Supply chain risk centers on tariff exposure for semiconductor substrates under evolving transatlantic trade frameworks. Distribution runs through EPC contractor bundling agreements that tie platform procurement to long-term O&M contracts in Spanish and Italian utility-scale developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
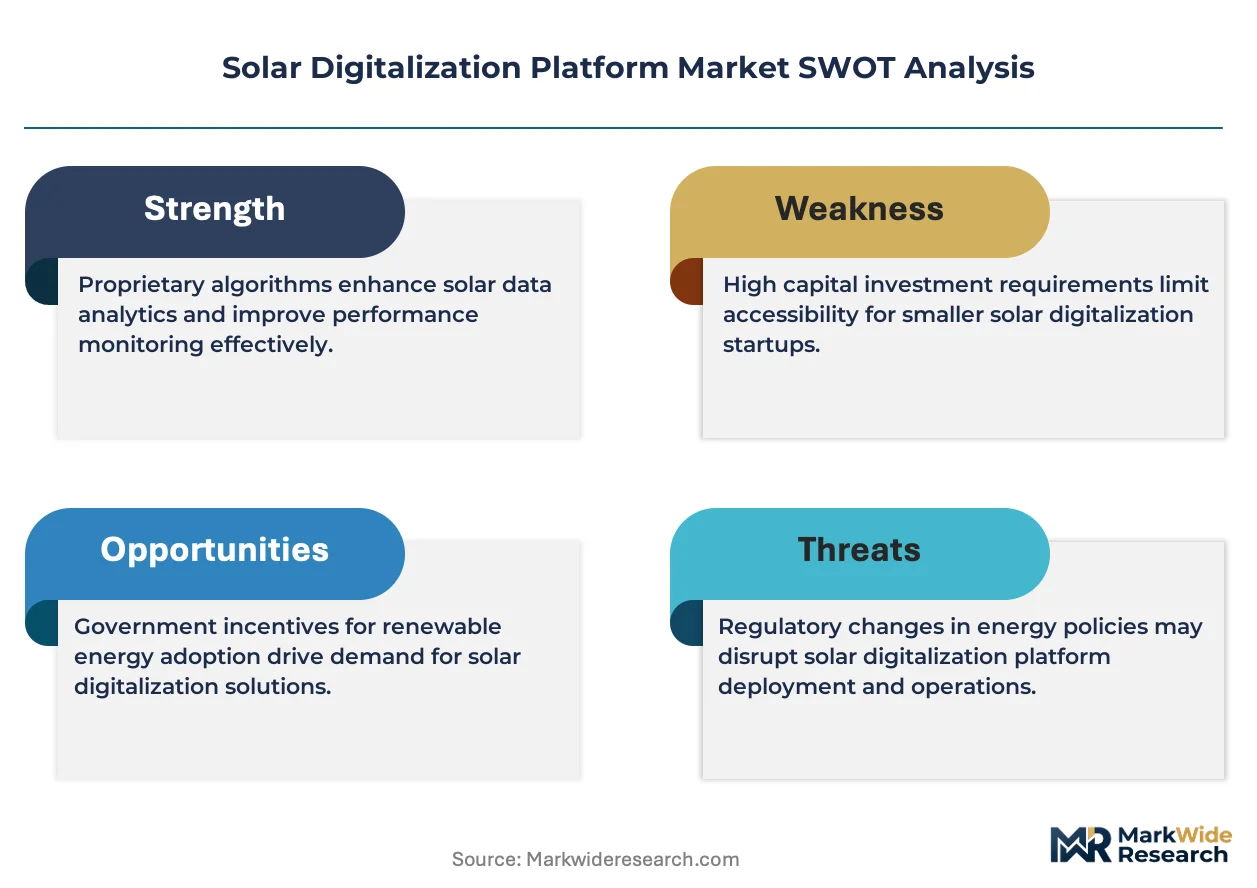
The solar digitalization platform market functions as a regulatory compounder where EU F-Gas retrofit mandates and AI Act risk classification create durable demand visibility for compliance-embedded vendors.
For Market Incumbents: To counter pure-play AI vendors displacing rule-based fault detection, established platform providers should deepen backward integration into module-level power electronics hardware and anchor cloud-native architectures with guaranteed availability SLAs for German frequency regulation markets. For New Entrants and Emerging Players: API-first integration layers represent the most penetrable entry vector for construction-phase drone documentation vendors seeking expansion into operational predictive maintenance. Target agricultural photovoltaic installations in Southern Italy where IEC 61850 retrofit complexity creates service revenue opportunities for compliance-specialist entrants. For Investors and Strategic Acquirers: Consolidation pressure builds where AI explainability talent pools concentrate in Berlin and Barcelona. Long-term viability favors vendors with captive sensor hardware supply and embedded regulatory compliance modules. Watch FERC Order 2222 aggregation thresholds as the signal indicating wholesale market participation inflection for grid-edge platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| AI Explainability Module Development | EU AI Act risk classification mandates embed interpretability into German frequency regulation algorithms. |
| Drone-Enabled Site Digitization | Andalusian solar parks bundle aerial photogrammetry with twenty-year O&M contracting structures. |
| Silicon Carbide Inverter Integration | Sub-minute telemetry pipelines tighten coupling between power electronics and digital twin architectures. |
| Predictive Maintenance AI Acquisition | Machine learning talent scarcity in time-series analytics drives specialist firm valuations in Bangalore. |
| Hybrid Edge-Cloud Architecture Deployment | Millisecond response requirements for grid balancing services accelerate Saxony-Anhalt utility adoption. |
Research Approach
Coverage spans Germany, Spain, Italy, the United States, and India, with primary inputs from each market cluster. The research combines structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators alongside secondary validation through FERC filings, IEA renewable energy reports, EU regulatory databases, and project development tracking systems. Bottom-up capacity installation estimates triangulate against top-down platform spending surveys.
Granularity-level modeling disaggregates revenue across deployment mode, end-user sophistication tier, and technology stack complexity throughout the projection horizon. Segmentation dimensions include platform architecture, regulatory compliance intensity, and regional grid code fragmentation. CAGRs derive from fitted growth curves calibrated to historical adoption patterns in cloud migration and AI deployment. Forecast inputs incorporate silicon carbide inverter penetration timelines and EU F-Gas retrofit compliance schedules.
The model assumes a particular technology adoption path; alternative pathways for AI-driven predictive maintenance would alter the outlook if explainability mandates soften or edge computing costs collapse faster than projected. Forecasts reflect assumptions about regulatory enforcement consistency and utility procurement cycle timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Energy As a Service (Eaas) Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Big Data Analytics in Energy Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
US Big Data Analytics in Energy Market
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
Smart Grid Software Market
Energy Analytics and Software
Global Wind Turbine Condition Monitoring System Market
Energy Analytics and Software
Italy Big Data Analytics in Energy Market
Energy Analytics and Software
Power System Analysis Software Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
Energy and Utilities Analytics Market
Energy Analytics and Software
Carbon and Energy Software Market