
 US Big Data Analytics in Energy Market | 2026-2036
US Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
US Big Data Analytics in Energy Market Insights
Utility procurement channels for analytics software are reshaping competitive dynamics across the sector. Microsoft Corporation leverages its Azure cloud infrastructure to capture long-term enterprise contracts with major power generators. Palantir Technologies Inc. sustains its position through specialized government and critical infrastructure relationships that demand high-security data environments. IBM Corporation anchors its competitiveness in hybrid deployment architectures that appeal to legacy-heavy utility IT departments.
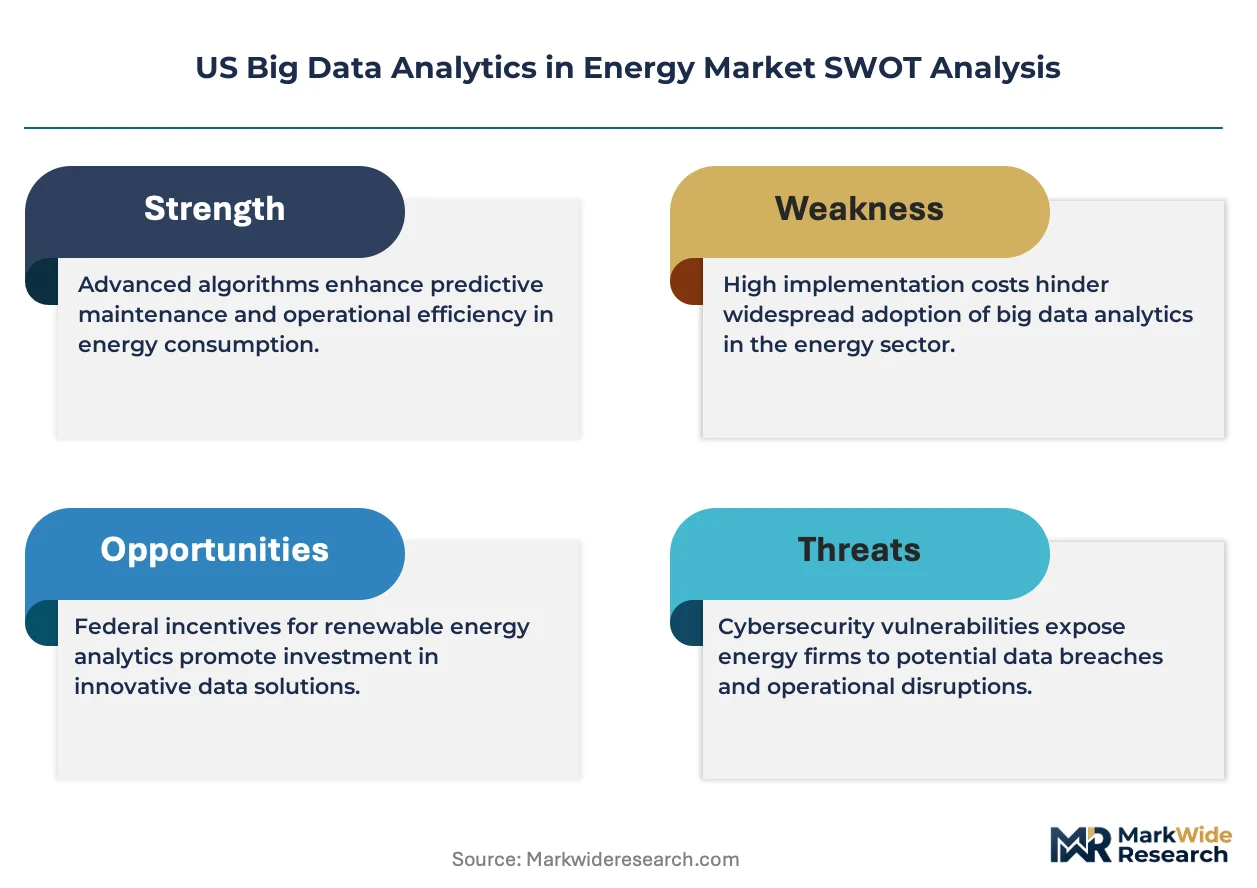
US Big Data Analytics in Energy encompasses the collection, processing, and algorithmic analysis of massive heterogeneous datasets generated across generation, transmission, distribution, and consumption nodes, typically involving petabyte-scale time-series sensor feeds, geospatial telemetry, and market pricing signals processed through machine learning pipelines to enable real-time operational decisions. The primary commercial purpose centers on reducing capital intensity, improving asset utilization rates, and mitigating supply-demand imbalance risks in increasingly decentralized power systems. Predictive Analytics commands the deepest margin pools as utilities prioritize outage prevention and renewable intermittency management over retrospective reporting. Cloud-Based deployment is expanding fastest as cybersecurity frameworks mature and capital expenditure constraints favor operational expenditure models. Grid Management applications attract concentrated investment where aging infrastructure intersects with distributed solar and battery storage proliferation.
FERC Order 2222 and state-level public utility commission mandates are accelerating aggregator participation in wholesale markets, forcing analytics platforms to support bidirectional data flows and complex settlement calculations. The Inflation Reduction Act's production tax credits and domestic content bonuses create compliance reporting burdens that only sophisticated data infrastructure can satisfy. EPA greenhouse gas performance standards for existing power plants further tighten emissions monitoring requirements. Stakeholders must evaluate whether their analytics stacks can scale to sub-second grid balancing intervals while maintaining audit trails for evolving federal incentive programs.
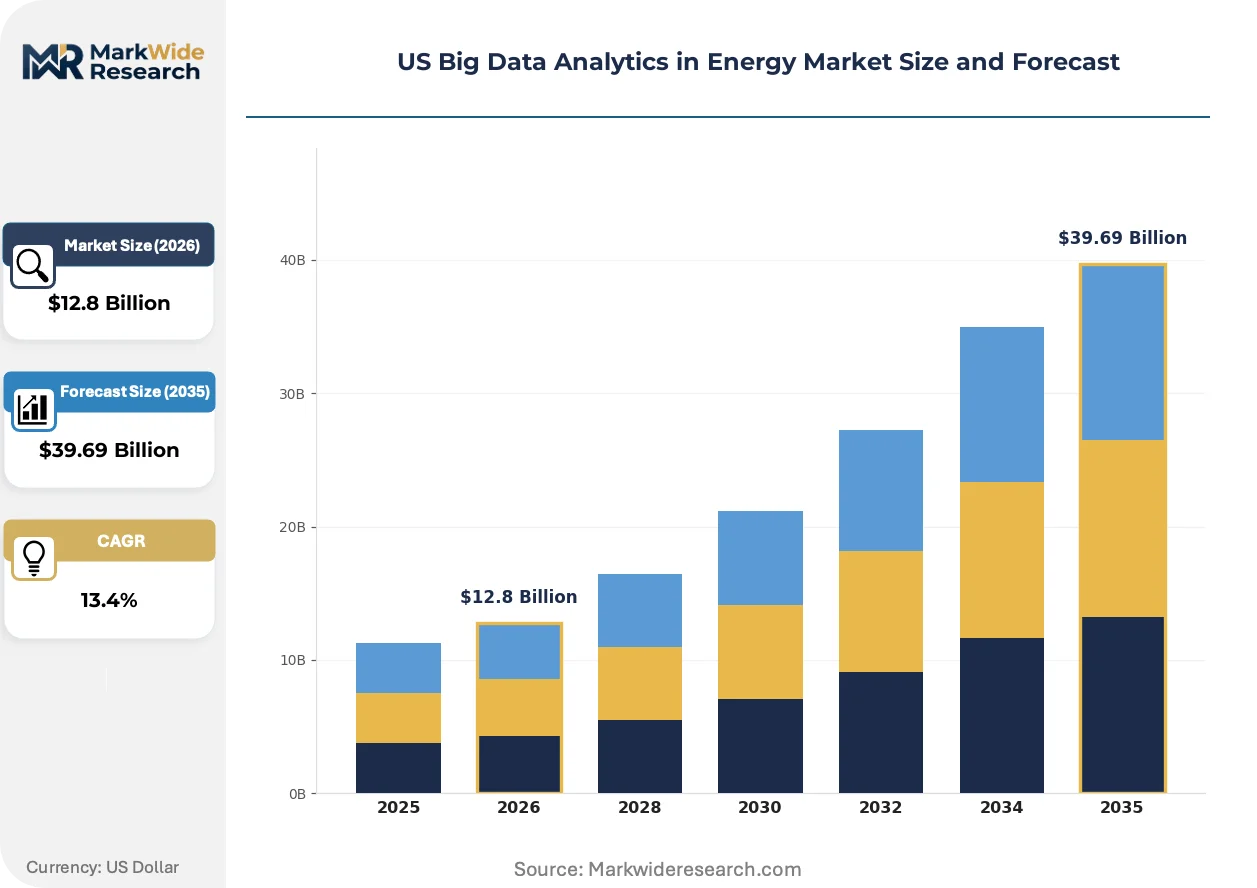
Market Dynamics
Grid operators face mounting pressure to balance renewable intermittency against baseload retirement, forcing analytics platforms to compress forecasting intervals from hourly to sub-second resolutions. This structural imperative is reshaping procurement criteria across investor-owned utilities and independent system operators.
Growth Catalysts
- FERC Order 2222:Aggregator participation mandates in wholesale markets require bidirectional data infrastructure and complex settlement engines.
- Texas ERCOT market design:The country's largest deregulated power market generates exceptional demand for predictive load forecasting and congestion management tools.
- Inflation Reduction Act compliance:Production tax credit domestic content bonuses create data-intensive reporting obligations that only advanced platforms satisfy.
Market Restraints
- Cloud migration costs:Capital expenditure constraints at municipal utilities delay transitions from on-premise server farms to operational expenditure models.
- Cybersecurity talent scarcity:Specialized data security professionals command premiums that strain mid-tier utility IT budgets.
- Legacy SCADA incompatibility:Decades-old supervisory control systems resist API-based integration with modern machine learning pipelines.
Strategic Opportunities
- Behind-the-meter DER aggregation:Residential battery and rooftop solar fleets remain underserved by forecasting platforms optimized for utility-scale assets.
- EPA GHG performance standards:Emissions monitoring mandates for existing power plants create compliance software demand.
- Edge computing convergence:Latency-sensitive grid applications favor distributed processing architectures over centralized cloud deployments.
Industry Challenges
- Data science workforce gaps:Power systems engineering expertise rarely overlaps with machine learning operations competency.
- Multi-vendor integration complexity:Analytics stacks must harmonize sensor feeds from disparate OEM equipment without standard protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Big Data Analytics in Energy Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $39.69 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Management, Visualization Tools, Predictive Analytics, Reporting Solutions End User: Utilities, Renewable Energy Providers, Oil & Gas Companies, Energy Traders Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing Application: Demand Forecasting, Asset Management, Operational Efficiency, Grid Management |
| Companies Covered | IBM Corporation, SAP SE, Microsoft Corporation, Teradata Corporation, Palantir Technologies Inc., Accenture PLC, Dell Technologies Inc., Oracle Corporation, C3.ai, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Big Data Analytics in Energy Market Trends and Innovations
Digital twin architectures are compressing development cycles for grid modernization programs. These virtual replicas enable operators to stress-test renewable integration scenarios before capital deployment.
Physics-informed neural networks combine first-principles power flow equations with data-driven pattern recognition. Grid operators in Texas and California are piloting these hybrid models for inverter-dominated distribution networks. The approach is rendering obsolete purely statistical forecasting methods that fail to capture electromagnetic transient behaviors.
EPA greenhouse gas performance standards for existing power plants mandate continuous emissions monitoring systems with quarterly reporting. Coal and gas fleet operators must retrofit analytics infrastructure to satisfy verification protocols. The regulation most affects Midwest and Southeast generators with aging baseload assets.
Subscription-based software licensing is displacing perpetual enterprise agreements across municipal utilities. Smaller cooperatives prefer operational expenditure models that align costs with rate recovery cycles. This shift concentrates most visibly in rural electric cooperative territories across the Great Plains and Mountain West states.
US Big Data Analytics in Energy Market Segmentation
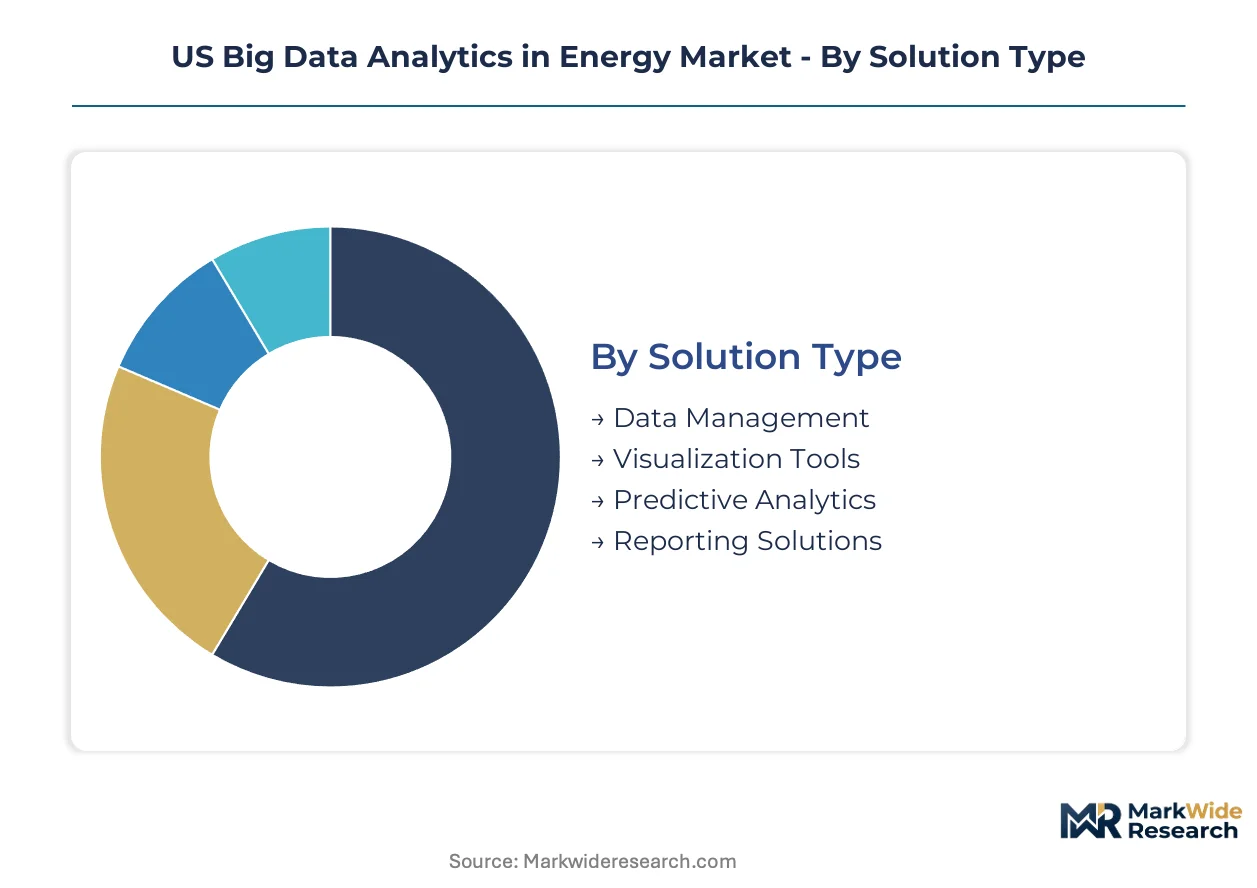
Analytics procurement patterns across US energy infrastructure vary sharply by operational maturity and data sovereignty requirements. Solution architecture, deployment constraints, and end-user sophistication create distinct margin profiles that vendors must navigate.
Solution Type:
After-sales service intensity diverges dramatically across solution categories, with predictive platforms demanding continuous model retraining and data pipeline maintenance.
- Predictive Analytics:Machine learning pipelines process petabyte-scale time-series sensor feeds to forecast equipment failures and renewable intermittency. Texas ERCOT operators and California ISOs deploy these platforms for sub-second grid balancing decisions where outage prevention justifies premium service contracts.
- Data Management:Ingestion, storage, and governance layers handle heterogeneous telemetry from SCADA, AMI, and market pricing feeds. Midwest municipal utilities prioritize these foundations before layering advanced analytics, creating implementation bottlenecks.
- Visualization Tools:Dashboard and BI interfaces translate complex grid data into operator-facing insights.
- Reporting Solutions:Compliance documentation engines satisfy FERC, EPA, and state public utility commission audit requirements.
By volume, Data Management leads. By growth pace, Predictive Analytics is expanding most quickly.
End User:
Customer technical sophistication spans legacy-heavy municipal cooperatives to algorithmic trading desks, reshaping vendor sales cycles and implementation support ratios.
- Utilities:Investor-owned and public power entities deploy enterprise-scale platforms across generation, transmission, and distribution operations. Southern California Edison and Consolidated Edison anchor demand for grid modernization analytics where aging infrastructure intersects with DER proliferation.
- Renewable Energy Providers:Wind and solar asset operators optimize fleet performance and forecast production volatility. Texas and Great Plains developers drive adoption as production tax credit compliance intensifies data requirements.
- Oil & Gas Companies:Upstream and midstream operators apply analytics to reservoir modeling and pipeline integrity.
- Energy Traders:Quantitative firms leverage real-time market signals for position optimization.
By installed base, Utilities dominate. By expansion trajectory, Renewable Energy Providers are gaining share fastest.
Deployment Model:
Capital expenditure constraints at smaller cooperatives favor subscription economics, while cybersecurity maturity determines cloud migration timelines.
- Cloud-Based:Scalable infrastructure eliminates on-premise hardware refresh cycles and accelerates machine learning deployment. Municipal utilities in the Mountain West and Great Plains prefer operational expenditure models aligned with rate recovery cycles.
- Hybrid:Split architectures keep sensitive operational data on-premise while bursting compute-intensive workloads to cloud. Legacy-heavy IT departments in the Southeast and Midwest anchor demand where SCADA integration complexity resists full migration.
- On-Premises:Air-gapped installations serve critical infrastructure with stringent security mandates.
- Edge Computing:Distributed processing reduces latency for real-time grid control applications.
By current deployment share, Hybrid leads. By momentum, Cloud-Based shows the steepest adoption curve.
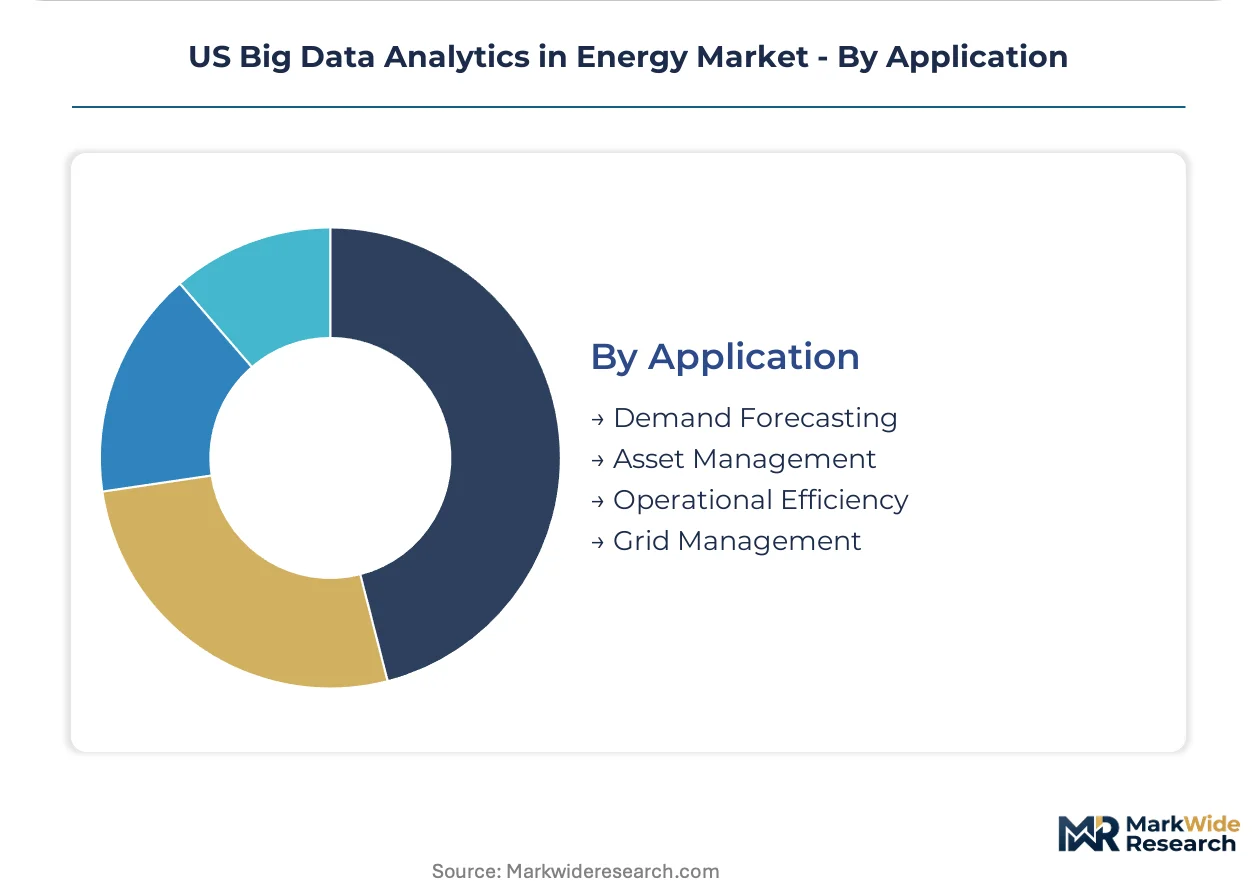
Application:
Use case prioritization reflects regional infrastructure stress points, with renewable-heavy markets emphasizing forecasting while aging-grid regions concentrate on asset integrity.
- Grid Management:Real-time monitoring and control platforms balance distributed solar, battery storage, and EV loads against transmission constraints. California and Hawaii utilities drive investment where inverter-dominated networks require advanced power flow analytics.
- Asset Management:Predictive maintenance engines optimize capital deployment across generation and T&D infrastructure. Rust Belt and Southeast generators with aging coal and gas fleets prioritize these tools as EPA emissions monitoring tightens.
- Demand Forecasting:Load prediction models anticipate consumption patterns for resource adequacy planning.
- Operational Efficiency:Process optimization analytics reduce fuel consumption and maintenance costs.
By spending concentration, Grid Management leads. By urgency of regulatory drivers, Asset Management is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Texas and California while procurement budgets lag across municipal utilities in the Great Plains and Mountain West. This asymmetry drives divergent deployment timelines for cloud-based analytics platforms.
Texas
ERCOT's deregulated market structure generates exceptional demand for predictive load forecasting and real-time congestion management tools. FERC Order 2222 mandates bidirectional data infrastructure for distributed energy resource aggregators. Houston and Austin anchor development clusters where independent system operators deploy sub-second grid balancing analytics.
California
Inverter-dominated distribution networks in Southern California Edison territory require advanced power flow analytics for distributed solar and battery storage integration. The California Public Utilities Commission enforces aggressive decarbonization mandates that intensify data reporting obligations. The San Francisco Bay Area hosts concentrated vendor development activity for grid modernization software.
New York Metro
Consolidated Edison's aging infrastructure intersects with offshore wind interconnection planning, driving investment in asset integrity analytics. The state's Climate Leadership and Community Protection Act imposes emissions monitoring requirements that only sophisticated data platforms satisfy. The New York City metropolitan area concentrates demand forecasting investment for electrification load growth.
Pacific Northwest
Hydropower-dominated utilities in Washington and Oregon prioritize operational efficiency analytics to optimize reservoir dispatch against variable renewable output. Bonneville Power Administration transmission planning mandates complex settlement calculations for distributed resource participation. Seattle and Portland anchor cooperative utility procurement clusters favoring subscription-based software licensing.
Southeast
Aging coal and gas fleets across Florida, Georgia, and the Carolinas face EPA greenhouse gas performance standards requiring continuous emissions monitoring retrofits. State public utility commissions in the region lag on distributed resource interconnection rules, delaying advanced analytics adoption. Atlanta and Charlotte concentrate investor-owned utility headquarters driving centralized procurement decisions.
US Big Data Analytics in Energy Market Competitive Landscape
Cloud hyperscalers and specialized infrastructure software providers split the market along deployment architecture preferences. The vendor base concentrates around three strategic archetypes: hyperscale cloud platforms with energy sector verticalization, critical infrastructure specialists with government security clearances, and legacy IT incumbents with hybrid deployment expertise. Competitive moves center on long-term enterprise contract capture and cybersecurity framework certification rather than price-based rivalry.
Within the hyperscale tier, Microsoft Corporation exemplifies cloud-native platform positioning through Azure infrastructure, while IBM Corporation anchors hybrid deployment architectures appealing to legacy-heavy utility IT departments. Palantir Technologies Inc. occupies the critical infrastructure specialist position, serving high-security data environments through government and utility relationships. These three companies represent distinct competitive vectors based on deployment model preference rather than direct feature competition.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Microsoft Corporation |
| Teradata Corporation |
| Palantir Technologies Inc. |
| Accenture PLC |
| Dell Technologies Inc. |
| Oracle Corporation |
| C3.ai, Inc. |
| Others |
Pricing and Supply Chain Analysis
Cloud hyperscaler concentration in Washington State and Northern Virginia data center clusters feeds directly into margin capture at the enterprise software tier, where Azure and AWS infrastructure costs determine downstream SaaS pricing floors for utility analytics platforms.
Pricing Analysis
Configured-to-order predictive analytics deployments command 40-60% premiums over standardized visualization modules. Subscription-based SaaS tiers dominate, with price differentiation driven by cybersecurity certification levels (FedRAMP High vs Moderate) and after-sales model retraining intensity. Cost compression in municipal utility segments intensifies as capital expenditure constraints favor operational expenditure models. Renewable energy providers exhibit lowest price sensitivity due to production tax credit compliance requirements.
Supply Chain Analysis
Foundry capacity for GPU and specialized AI accelerators concentrates in Taiwan and South Korea, with assembly and systems integration anchored in China and Mexico. Raw material dependencies span advanced silicon wafers, high-bandwidth memory modules, and rare earth magnet components for edge computing hardware. Single-source vulnerability in advanced node semiconductor fabrication creates supply chain risk. Distribution runs through direct enterprise sales teams and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated investor-owned utilities as municipal cooperative fragmentation slows procurement centralization.
For Market Incumbents: Build switching-cost moats through deep SCADA integration and FERC 2222 compliance certification. Incumbents should anchor hybrid deployment architectures to capture legacy utility IT departments while accelerating edge computing partnerships to defend against cloud-native entrants. Cybersecurity framework certification investment represents the critical defensive lever. For New Entrants and Emerging Players: Mid-market rural electric cooperatives in the Mountain West represent the most penetrable entry point for subscription-native platforms. Behind-the-meter DER aggregation for residential battery fleets offers second white-space opportunity. Go-to-market should emphasize operational expenditure alignment with rate recovery cycles. For Investors and Strategic Acquirers: Capital is best deployed toward specialized critical infrastructure software providers with existing government security clearances and utility relationships. Long-term viability hinges on sub-second grid balancing capability and EPA emissions monitoring compliance integration. Watch for FERC Order 2222 implementation acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Azure or AWS embedding captures long-term enterprise utility contracts with hyperscaler marketplace distribution. |
| Acquisition of Specialist Firm | Physics-informed neural network startups accelerate inverter-dominated distribution network analytics capability. |
| Strategic Partnership | SCADA OEM alliances resolve legacy system API integration bottlenecks for hybrid deployments. |
| Geographic Expansion | Texas ERCOT market presence secures sub-second forecasting contracts in the country's largest deregulated power market. |
| Product Launch | Edge computing analytics suites target latency-sensitive grid control applications outside centralized cloud infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across utility planning officers, IPP project developers, EPC contractors, grid operators, and fuel supply specialists. Secondary validation drew from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Calibration against historical deployment trajectories anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, grid type, and regulatory framework complexity. CAGRs were derived from trend extrapolation and technology diffusion curves. Forecast inputs incorporated renewable penetration rates and EPA emissions monitoring mandate timelines.
Practitioners should monitor FERC Order 2222 implementation pace and EPA GHG performance standard enforcement intensity for early signals of demand inflection. Forecasts reflect assumptions around cloud cybersecurity framework maturation and SCADA modernization funding availability. Quarterly review of utility capital expenditure disclosures and renewable interconnection queue data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Predictive Maintenance in the Energy Market
Energy Analytics and Software
Italy Big Data Analytics in Energy Market
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
Global Wind Turbine Condition Monitoring System Market
Energy Analytics and Software
AI in Energy Market
Energy Analytics and Software
Smart Grid Software Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
Spain Big Data Analytics in Energy Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
India Big Data Analytics in Energy Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Power Monitoring and Control Software Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market