
 AI in Energy Market | 2026-2036
AI in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Energy Market Analysis
ISO/IEC 27001 certification for energy sector AI systems is rotating as a decisive gate for vendor qualification in European and North American procurement cycles. Siemens AG leverages its digital grid software portfolio to anchor large-scale utility deployments across Germany and Scandinavia. Schneider Electric SE competes through its EcoStruxure platform, which sustains deep integration with building energy management systems. C3.ai differentiates by specializing in enterprise-scale predictive analytics for oil and gas majors seeking operational uptime improvements.
AI in Energy encompasses machine learning algorithms, neural network architectures, and real-time data analytics pipelines deployed to optimize generation scheduling, predict equipment failures, and automate demand-side load balancing. These systems process time-series sensor data from turbines, transformers, and smart meters to reduce downtime and curtail carbon-intensive peaking plant dispatch. Predictive Analytics commands the largest share of application spending as utilities prioritize asset health monitoring over exploratory AI pilots. Machine Learning dominates technology adoption, though Neural Networks are gaining share in renewable forecasting where pattern recognition exceeds rule-based performance. Optimization Services capture premium pricing relative to Monitoring Services because vendors assume outcome-linked performance risk.
The EU AI Act classifies grid-management algorithms as high-risk systems, mandating conformity assessments that extend sales cycles and favor established vendors with compliance infrastructure. In the United States, FERC Order 2222 enables distributed energy resource aggregation, creating jurisdictional overlap with state public utility commissions that stakeholders must navigate. The EPA's evolving greenhouse gas reporting requirements for power generators are embedding AI-derived emissions tracking into standard compliance workflows. Stakeholders should monitor how divergent transatlantic liability frameworks for autonomous grid decisions reshape vendor contracting terms and insurance structures.
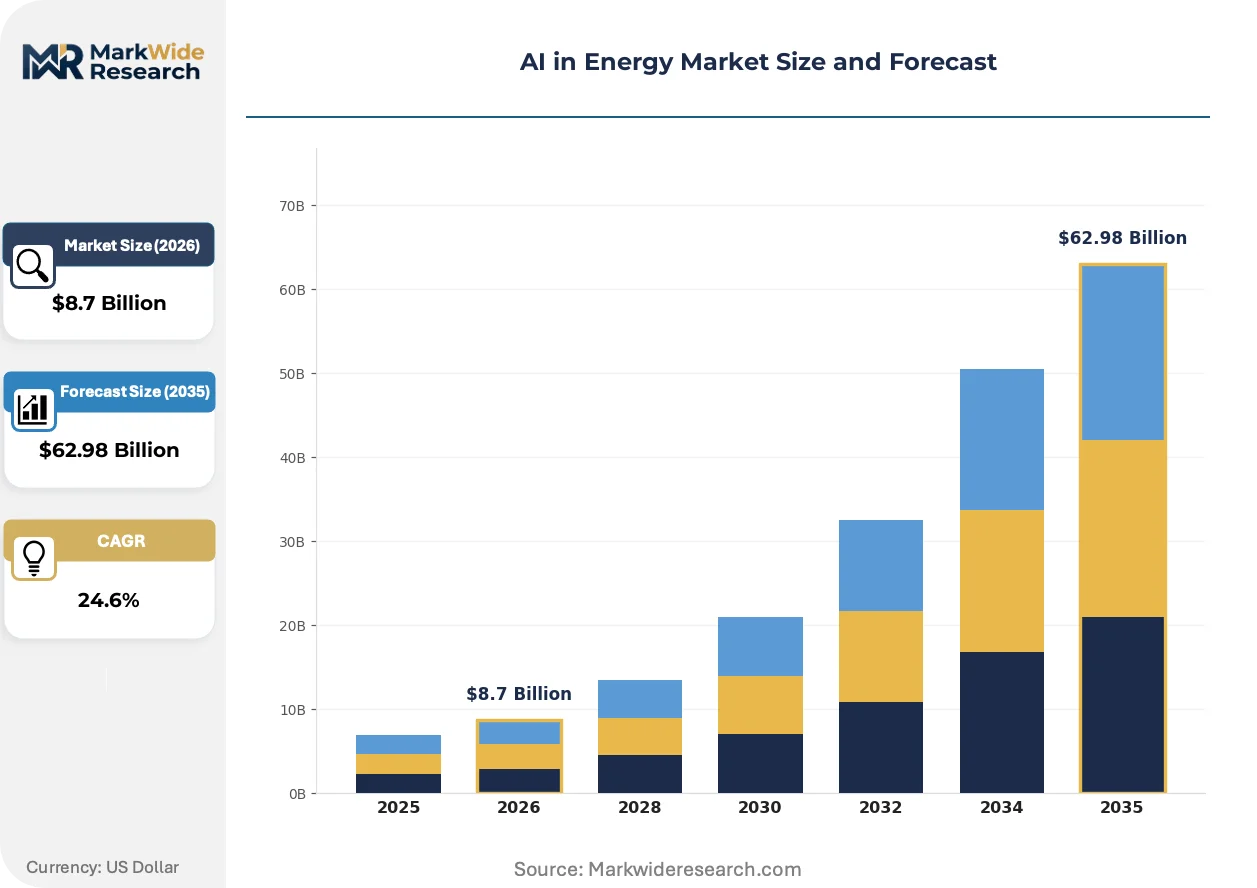
Market Dynamics
The EU AI Act's high-risk classification for grid-management algorithms is compressing vendor qualification timelines and tilting procurement toward established compliance infrastructure holders. This regulatory pressure is reshaping competitive entry barriers across European and North American utility markets.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation rules in the United States are opening procurement channels for algorithmic load-balancing platforms. Independent system operators in Texas and California are expanding pilot programs.
- Neural network architectures:Pattern recognition capabilities for renewable forecasting are displacing rule-based models in German wind and solar forecasting services. Industrial clusters in Bavaria are anchoring deployment.
- EPA greenhouse gas reporting:Evolving emissions tracking requirements for power generators are embedding AI-derived monitoring into standard compliance workflows. Compliance-driven demand concentrates in coal-to-gas transition states.
Market Restraints
- ISO/IEC 27001 certification costs:Cybersecurity compliance for energy sector AI systems is extending sales cycles by 8-14 months for unqualified vendors. Certification infrastructure concentrates in established software houses.
- Sensor hardware concentration:Time-series data pipelines depend on turbine and transformer sensor networks dominated by German and Japanese industrial automation suppliers. Geographic concentration creates input bottlenecks.
- EU AI Act conformity assessments:High-risk system documentation requirements are favoring vendors with existing regulatory affairs teams. New entrants face structural documentation gaps.
Strategic Opportunities
- Scandinavian grid modernization:Norway and Sweden are accelerating procurement of predictive maintenance platforms for hydroelectric and offshore wind assets. State-owned utilities are issuing multi-year framework agreements.
- Building energy management convergence:Integration between AI load forecasting and smart building systems is creating white space for platform vendors. Schneider Electric's EcoStruxure architecture demonstrates the integration pathway.
- US Inflation Reduction Act:Clean energy tax credits are expanding capital availability for AI-enabled emissions reduction projects. Project developers are bundling algorithmic optimization into financing structures.
Industry Challenges
- Power systems engineering talent scarcity:Grid-domain expertise combined with machine learning implementation skills is concentrating in German technical universities and US national laboratories. Vendor hiring timelines are extending.
- Legacy SCADA integration complexity:Real-time data pipelines must interface with decades-old control systems. Retrofit costs are absorbing 30-40% of implementation budgets for brownfield deployments.
- Algorithmic liability frameworks:Divergent transatlantic standards for autonomous grid decisions are complicating insurance structuring. Underwriters in London and New York are developing divergent risk models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Energy Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Predictive Analytics, Energy Management, Demand Response, Fault Detection Technology: Machine Learning, Neural Networks, Data Analytics, Natural Language Processing Service Type: Consulting Services, Optimization Services, Maintenance Services, Monitoring Services End User: Utilities, Energy Producers, Industrial Facilities, Commercial Buildings |
| Companies Covered | Siemens AG, Schneider Electric SE, GE Vernova, ABB, C3.ai, Atos SE, Enel Group, Iberdrola, Uplight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Energy Market Emerging Trajectories
Machine learning inference at the grid edge is displacing centralized cloud processing for latency-critical applications. This architectural shift is redistributing computational loads and reshaping vendor hardware partnerships.
Transformer-based neural architectures for time-series forecasting are decomposing the dominance of recurrent neural networks in renewable generation prediction. German transmission system operators are adopting these models for 15-minute intraday trading. The technology is compressing forecast error rates and enabling tighter dispatch schedules.
The EU F-Gas Regulation is tightening compliance requirements for cooling systems in data centers hosting AI training workloads. Grid operators are renegotiating power purchase agreements to account for thermal load shifts. German utilities are prioritizing liquid cooling and free-air cooling architectures in new facility designs.
Utility procurement departments are consolidating vendor relationships around outcome-linked performance contracts. Traditional time-and-materials consulting arrangements are losing share to risk-sharing models where vendors assume uptime guarantees. This shift is most visible in North American independent power producer markets.
AI in Energy Market Segmentation
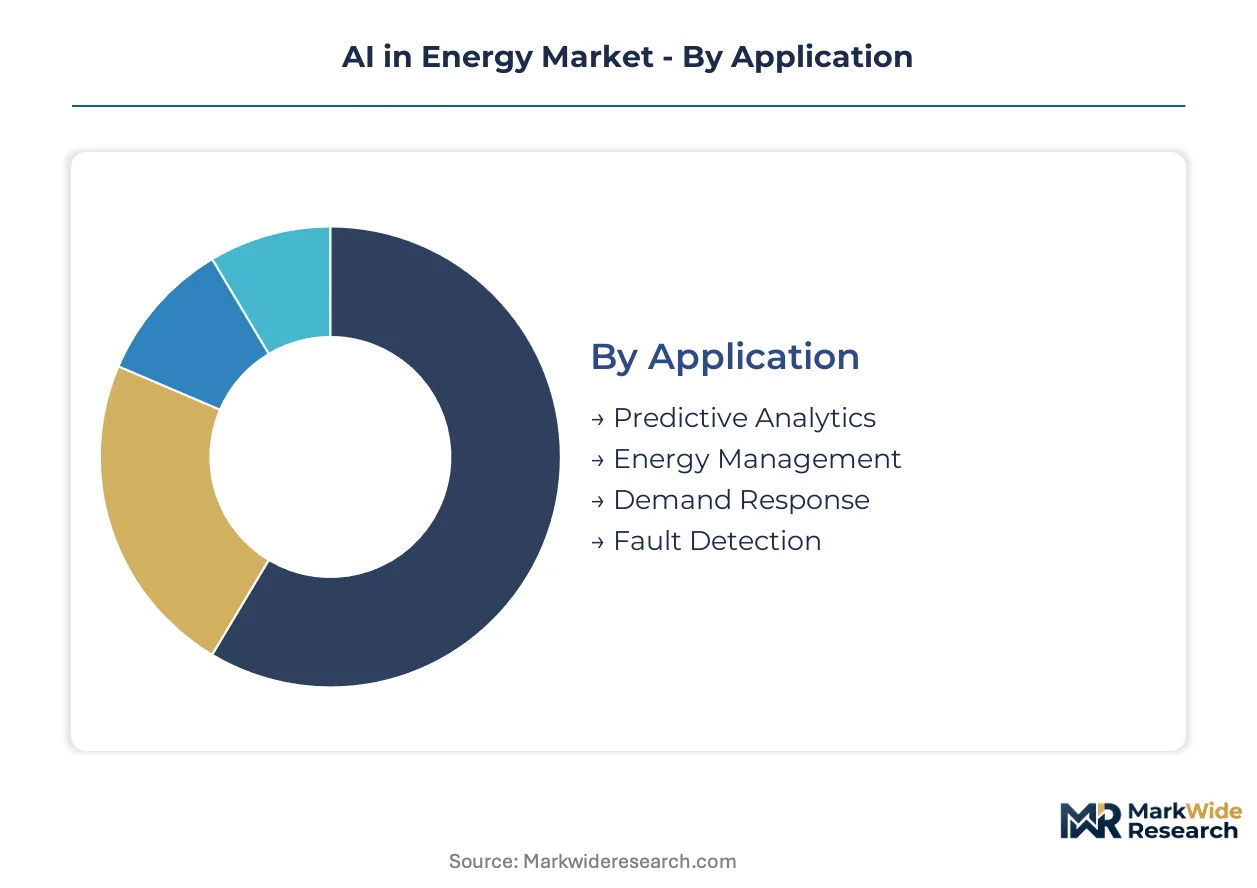
Segmentation in AI for energy reveals how vendor specialization aligns with divergent buyer risk appetites and regulatory exposure. Procurement patterns differ sharply between utilities seeking compliance-grade systems and industrial operators prioritizing rapid deployment.
Application:
Predictive Analytics faces the strongest substitution pressure as rule-based condition monitoring vendors retrofit legacy platforms with lightweight statistical modules.
- Predictive Analytics:Algorithms process vibration, thermal, and electrical signature data from rotating machinery to forecast failure windows. German transmission system operators and Texas independent power producers anchor procurement, driven by FERC Order 2222 aggregation incentives and EU AI Act high-risk system documentation requirements.
- Energy Management:Real-time optimization engines balance generation dispatch against carbon pricing signals and grid constraints. Demand concentrates in Scandinavian state-owned utilities modernizing hydroelectric fleets, constrained by ISO/IEC 27001 certification mandates for vendor qualification.
- Demand Response:Automated load curtailment systems interface with smart meter infrastructure and building management protocols.
- Fault Detection:Anomaly identification in distribution networks using waveform analysis and topological state estimation.
Predictive Analytics retains volume leadership; Fault Detection holds the steepest expansion curve.
Technology:
Cost tier differentiation separates enterprise-grade neural network deployments from lightweight machine learning implementations.
- Machine Learning:Supervised and unsupervised algorithms dominate brownfield SCADA integration projects where interpretability requirements constrain model complexity. Deployment concentrates in US coal-to-gas transition states embedding EPA emissions tracking into compliance workflows.
- Neural Networks:Deep learning architectures excel at pattern recognition in renewable forecasting where temporal dependencies exceed rule-based capacity. German wind and solar forecasting services in Bavarian industrial clusters anchor adoption, displacing recurrent neural networks with transformer-based time-series models.
- Data Analytics:Descriptive and diagnostic pipelines processing historical operational datasets for strategic planning.
- Natural Language Processing:Document extraction and regulatory text analysis for compliance automation and contract management.
Machine Learning retains volume leadership; Neural Networks holds the steepest expansion curve.
Service Type:
Customer type segmentation distinguishes risk-averse utilities favoring outcome-linked contracts from industrial buyers accepting time-and-materials arrangements.
- Optimization Services:Vendors assume performance risk through uptime guarantees and efficiency improvement commitments, commanding premium pricing. North American independent power producers consolidate procurement around these structures, displacing traditional consulting arrangements.
- Consulting Services:Advisory engagements for AI strategy, vendor selection, and regulatory readiness. Demand concentrates among European utilities navigating EU AI Act conformity assessment timelines and documentation gaps.
- Maintenance Services:Ongoing model retraining, drift monitoring, and algorithmic performance auditing.
- Monitoring Services:Continuous surveillance of asset health indicators with alert generation and diagnostic support.
Optimization Services retains volume leadership; Maintenance Services holds the steepest expansion curve.
End User:
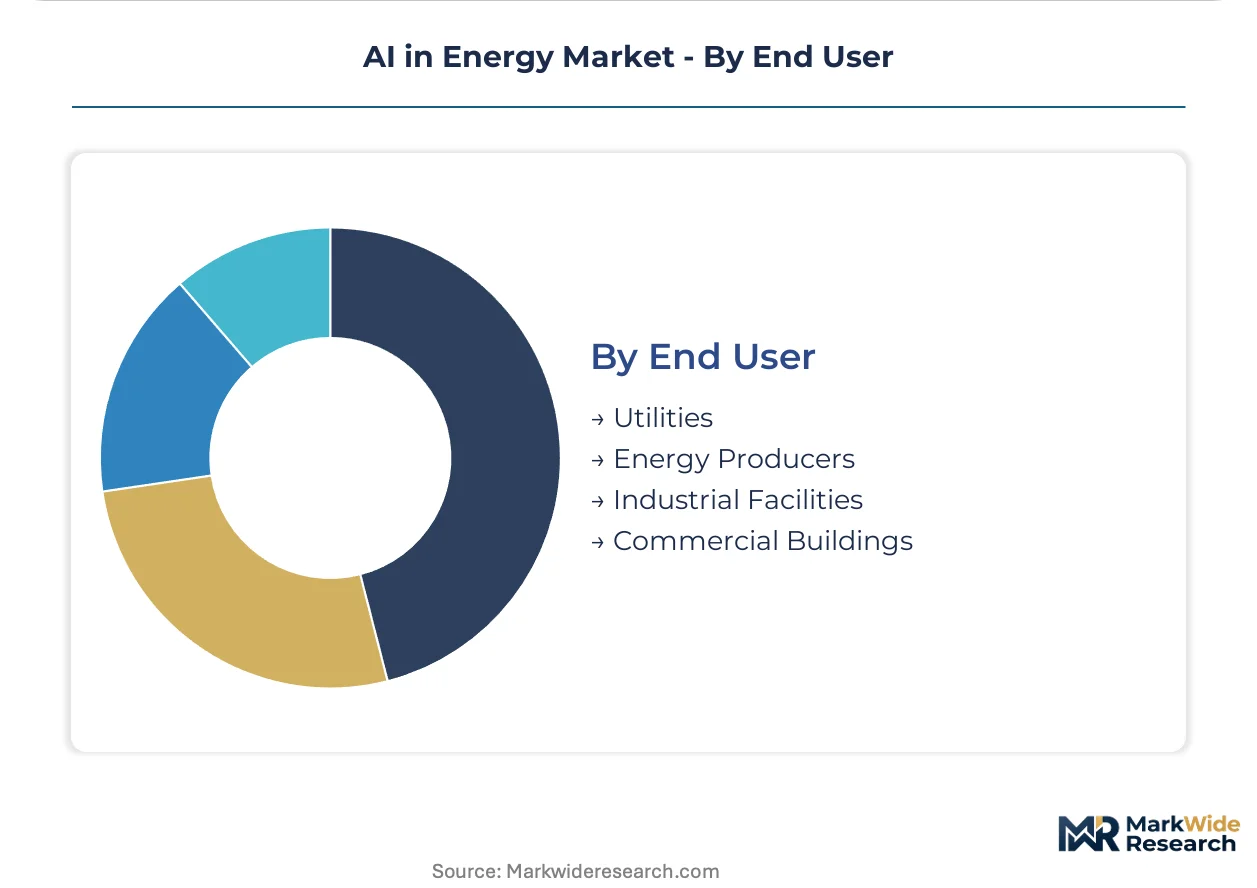
Geographic concentration patterns vary by end user category, with utilities clustering compliance-driven demand in Germany and industrial facilities dispersing across US manufacturing belts.
- Utilities:Grid operators and distribution companies procuring high-availability systems for generation scheduling and network management. German and Scandinavian state-owned entities anchor demand, constrained by EU F-Gas Regulation cooling requirements for AI training infrastructure.
- Industrial Facilities:Manufacturing and process industries optimizing on-site generation and load flexibility. Deployment concentrates in US states with IRA clean energy tax credit availability, bundling algorithmic optimization into project financing structures.
- Energy Producers:Independent power producers and renewable developers forecasting output and managing merchant price exposure.
- Commercial Buildings:Smart building operators integrating AI load forecasting with HVAC and lighting control systems.
Utilities retains volume leadership; Commercial Buildings holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement departments in Germany, the United States, and Scandinavia are driving the bulk of algorithmic grid management investment. State-owned operators favor multi-year framework agreements with established compliance infrastructure holders. Independent power producers in deregulated markets prioritize outcome-linked performance contracts over time-and-materials arrangements.
United States
Texas and California independent system operators are expanding pilot programs for distributed energy resource aggregation under FERC Order 2222. The EPA's evolving greenhouse gas reporting requirements are embedding AI-derived emissions tracking into standard compliance workflows for coal-to-gas transition states. Project developers in these states are bundling algorithmic optimization into Inflation Reduction Act financing structures.
Germany
Bavarian industrial clusters are anchoring deployment of transformer-based neural architectures for 15-minute intraday renewable forecasting. The EU AI Act's high-risk system classification mandates conformity assessments that extend sales cycles and favor established vendors with regulatory affairs teams. Siemens AG leverages its digital grid software portfolio to anchor large-scale utility deployments across Germany and Scandinavia.
Norway
State-owned utilities are issuing multi-year framework agreements for predictive maintenance platforms targeting hydroelectric and offshore wind assets. The EU F-Gas Regulation is tightening compliance requirements for cooling systems in data centers hosting AI training workloads. Norwegian grid operators are renegotiating power purchase agreements to account for thermal load shifts in new facility designs.
Sweden
Grid modernization procurement is accelerating for hydroelectric fleet optimization and offshore wind integration. ISO/IEC 27001 certification serves as a decisive gate for vendor qualification in Scandinavian utility procurement cycles. Stockholm-based transmission system operators are adopting machine learning inference at the grid edge for latency-critical applications.
United Kingdom
Distribution network operators are procuring fault detection systems using waveform analysis and topological state estimation. The UK regulator's emphasis on network resilience is driving demand for anomaly identification platforms. London-headquartered utilities are consolidating vendor relationships around outcome-linked performance contracts with uptime guarantees.
AI in Energy Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with embedded digital divisions and enterprise software specialists targeting vertical use cases. Market structure tilts toward established compliance infrastructure holders as regulatory documentation requirements raise entry barriers. Two strategic archetypes dominate: legacy automation vendors retrofitting hardware-centric portfolios with algorithmic layers, and cloud-native analytics platforms selling predictive modules to asset-intensive operators. Competitive moves concentrate on strategic partnerships bridging SCADA legacy systems with modern data pipelines, and portfolio diversification into adjacent building energy management convergence.
Within the industrial conglomerate tier, Siemens AG and Schneider Electric SE exemplify the automation-to-software transition archetype. C3.ai occupies a position among enterprise-scale predictive analytics specialists serving oil and gas majors. These three anchors demonstrate how vendor qualification timelines under EU AI Act and North American cybersecurity mandates are compressing procurement toward entities with pre-existing certification infrastructure and regulatory affairs capabilities.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric SE |
| GE Vernova |
| ABB |
| C3.ai |
| Atos SE |
| Enel Group |
| Iberdrola |
| Uplight |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Japanese sensor fabrication facilities shapes both input availability and price floors for AI-enabled grid management systems. Scale economies in transformer and turbine sensor networks concentrate supply-side leverage among industrial automation incumbents, compressing margin room for downstream algorithm vendors.
Pricing Analysis
Cost-plus contracts with steel and semiconductor indexation dominate procurement for predictive maintenance platforms. Three-tier pricing structure across premium, standard, and economy levels separates ISO/IEC 27001-certified vendors from uncertified competitors and bare-software licensors. Cost compression in the economy tier is intensifying because unqualified vendors absorb extended sales cycles for cybersecurity compliance. Independent power producers exhibit highest price sensitivity, while German state-owned utilities prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of GPU and FPGA hardware precedes major utility procurement cycles, contrasting with just-in-time software licensing patterns. Sensor hardware concentrates in Germany, Japan, and the United States, drawing from precision manufacturing clusters in Bavaria and Nagoya. Rare earth dependencies for magnetics in turbine monitoring equipment and silicon wafer supplies for edge-computing chips create single-source vulnerability. Distribution runs through systems integrators with SCADA retrofit expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs formidable defensive moats for established vendors, as EU AI Act documentation requirements and North American cybersecurity mandates extend qualification timelines beyond new entrant capital runways.
For Market Incumbents: Secure ISO/IEC 27001 certification expansion into predictive maintenance modules before unqualified competitors close documentation gaps. Anchor multi-year framework agreements with Scandinavian state-owned utilities to lock out cloud-native challengers lacking hydroelectric domain expertise. Vertical integration into sensor hardware partnerships mitigates input bottlenecks from German and Japanese automation suppliers.
For New Entrants and Emerging Players: ISO/IEC 27001 fast-track through accredited third-party assessors opens procurement channels previously blocked by 8-14 month compliance timelines. Target building energy management convergence as the most penetrable white space, where Schneider Electric's platform architecture leaves integration gaps for specialized load-forecasting modules. Lead with outcome-linked performance contracts rather than time-and-materials consulting to differentiate from incumbent professional services.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise-scale predictive analytics specialists serving oil and gas majors with operational uptime mandates. Long-term viability across the projection horizon rests on regulatory affairs infrastructure depth rather than algorithmic performance alone. Monitor FERC Order 2222 implementation velocity in Texas and California as the inflection signal for distributed energy resource aggregation platform demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing | Transformer-based neural architectures for 15-minute intraday forecasting compress dispatch error rates for German transmission operators. |
| Strategic Partnership | SCADA integration alliances bridge decades-old control systems with modern data pipelines, absorbing 30-40% of brownfield implementation budgets. |
| Platform Integration | EcoStruxure-class building energy management convergence creates white space for AI load-forecasting vendors targeting HVAC optimization. |
| Acquisition of Specialist Firm | Grid-domain expertise combined with machine learning implementation skills concentrates in German technical universities and US national laboratories. |
| Green Certification Program | EU F-Gas Regulation compliance for liquid cooling architectures renegotiates power purchase agreements for AI training facility thermal loads. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EIA generation statistics, IEA grid modernization reports, FERC interconnection queue data, and EU AI Act implementation guidance. Utility planning officers, independent power producer project developers, EPC contractors, and grid operators provided operational perspective on procurement timelines and vendor qualification criteria. Bottom-up project pipeline aggregation triangulates against top-down market sizing from regulatory filing analysis.
Segmentation dimensions modeled include application type, technology architecture, service delivery model, and end-user category across the projection horizon. CAGRs derive from weighted capacity expansion schedules, regulatory compliance timeline assumptions, and technology substitution elasticity estimates. Neural network adoption curves incorporate pattern recognition performance benchmarks against rule-based renewable forecasting baselines.
Decision-makers should treat outputs as directional under sustained IRA tax credit availability and EU AI Act enforcement intensity; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
GCC Well Testing Services Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
China Big Data Analytics in Energy Market
Energy Analytics and Software
Solar Digitalization Platform Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Spain Big Data Analytics in Energy Market
Energy Analytics and Software
France Big Data Analytics in Energy Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
Predictive Maintenance in the Energy Market