
 Europe Electric Motors for Electric Vehicle Market | 2026-2036
Europe Electric Motors for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Motors for Electric Vehicle Market Foresight
Asset-light leasing models for EV powertrain components are reshaping competitive dynamics among motor suppliers. Siemens AG leverages its industrial electrification heritage to sustain R&D intensity in synchronous motor architectures. Robert Bosch GmbH anchors its position through backward integration into power electronics and thermal management systems. Continental AG competes by specializing in asynchronous motor designs for cost-sensitive commercial vehicle applications.
Electric motors for electric vehicles are electromechanical devices that convert electrical energy into mechanical torque through electromagnetic induction, typically operating at power densities exceeding 3 kW per kilogram for automotive traction applications. Their primary commercial purpose is to deliver propulsion force while enabling regenerative braking energy recovery. Permanent magnet synchronous motors currently lead the technology segment due to superior efficiency at high rotational speeds, while switched reluctance architectures are gaining traction as manufacturers seek to reduce rare-earth dependency. Passenger vehicles dominate end-user demand, though heavy-duty applications represent the fastest-growing margin pool as fleet electrification mandates tighten across European member states.
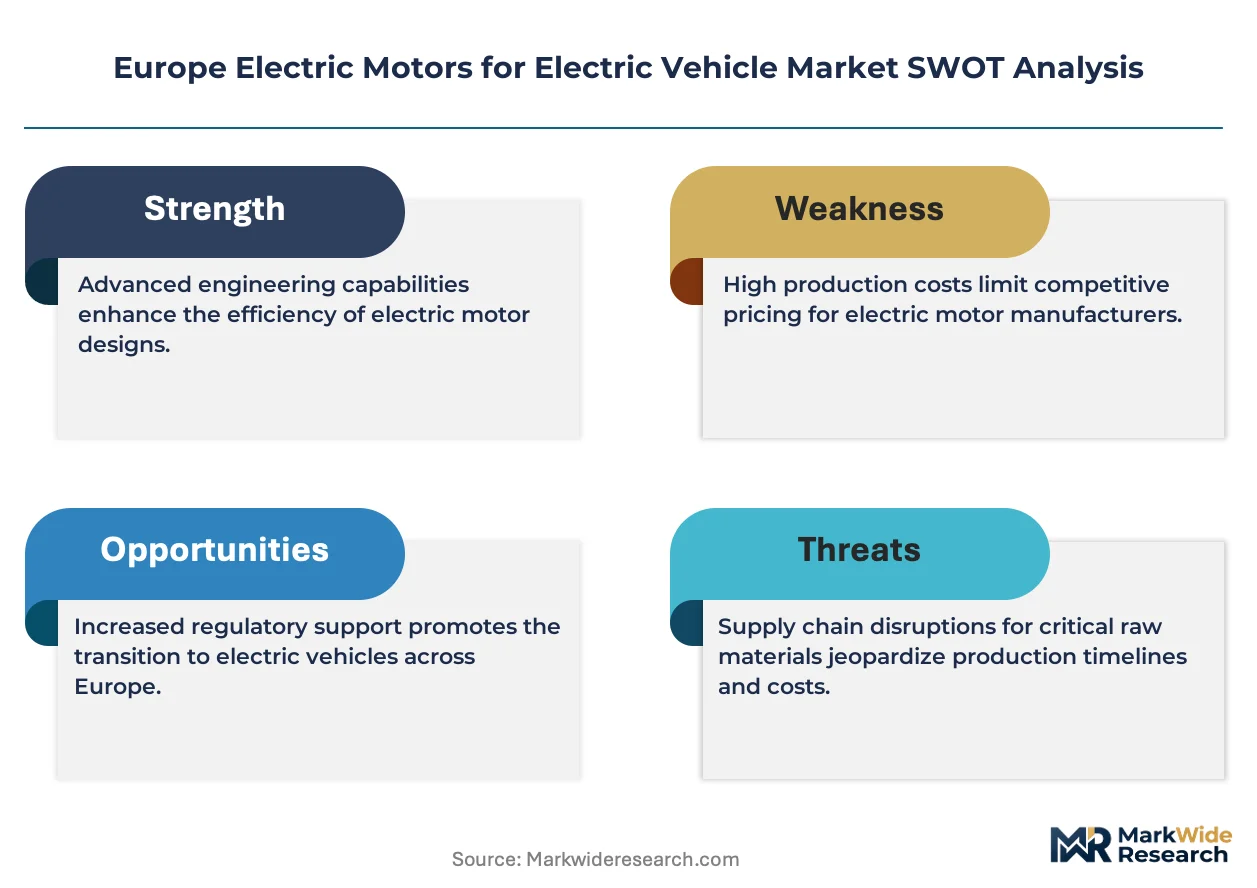
The EU Green Deal, F-Gas Regulation, and REACH framework collectively mandate stricter lifecycle emissions accounting and restricted substance protocols for motor materials, directly influencing supplier qualification criteria and import sourcing strategies. EMA guidelines on automotive component safety and CE marking requirements for electromagnetic compatibility further shape product certification pathways. Stakeholders must monitor evolving critical raw material legislation and battery-motor system integration standards to anticipate procurement restructuring and qualification timeline shifts.
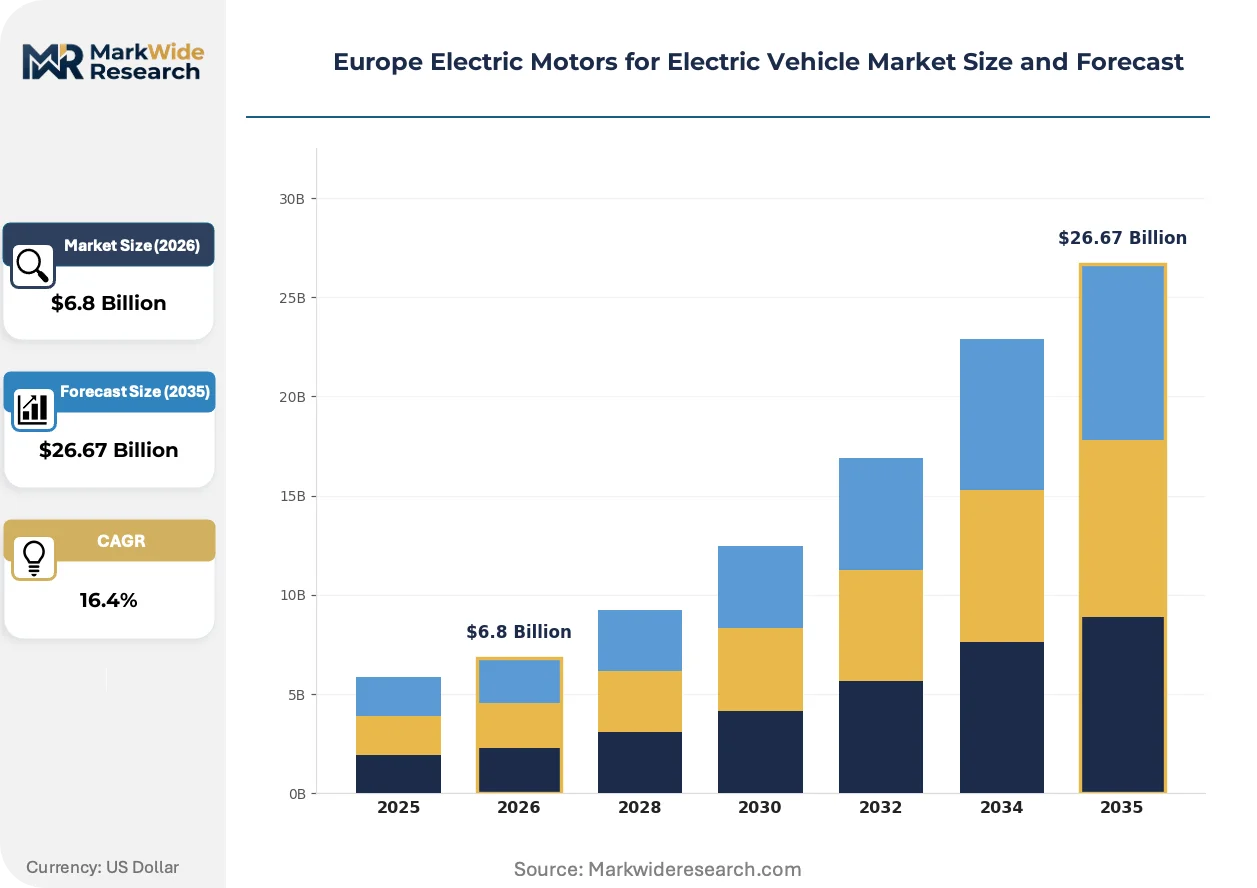
Market Dynamics
Permanent magnet synchronous motor architectures face mounting pressure from the EU Green Deal's rare-earth sourcing disclosure mandates, forcing European automakers to requalify supplier bases and accelerate alternative motor topology development.
Growth Catalysts
- EU F-Gas Regulation:Stringent fluorinated gas phase-out timelines are accelerating demand for liquid-cooled motor designs that eliminate refrigerant-dependent thermal management systems in premium passenger vehicle platforms.
- Heavy-duty fleet electrification:Commercial vehicle operators across Germany, France, and Italy face tightening municipal zero-emission zone mandates that require high-torque motor configurations for last-mile logistics.
- Switched reluctance topology maturation:Advances in silicon carbide inverter pairing are resolving torque ripple limitations that previously constrained adoption in high-speed automotive traction applications.
Market Restraints
- Neodymium-dysprosium price volatility:Rare-earth oxide concentrate costs fluctuate with Chinese export quota announcements, compressing margins for permanent magnet motor suppliers locked into long-term automotive supply agreements.
- Magnet supply concentration:Separation and refining capacity for heavy rare earths concentrates in Southeast Asian processing hubs creates single-point-of-failure exposure for European motor manufacturers.
- Asynchronous efficiency ceiling:Induction motor power density limitations at sustained high-speed operation restrict applicability in performance-oriented passenger vehicle segments demanding extended autobahn capability.
Strategic Opportunities
- Poland and Czech Republic manufacturing:Greenfield motor production facilities in Central European automotive clusters offer proximity to Volkswagen Group and Stellantis assembly plants with favorable logistics cost structures.
- Axial-flux topology commercialization:Torque-dense pancake motor architectures enable packaging advantages for electric axle integration in compact urban delivery vehicles and light commercial platforms.
- CSRD-aligned lifecycle accounting:Corporate Sustainability Reporting Directive scope 3 emissions disclosure requirements create first-mover advantage for motor suppliers with verified carbon footprint transparency across raw material extraction and manufacturing.
Industry Challenges
- Power electronics-motor integration:Co-design of silicon carbide inverters with high-speed motor electromagnetic characteristics demands cross-functional engineering teams scarce in traditional tier-one automotive suppliers.
- REACH substance compliance:Evolving restricted substance candidate list updates for insulation materials and bearing lubricants trigger costly requalification cycles that delay platform launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Motors for Electric Vehicle Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC Motors, AC Motors, Stepper Motors, Induction Motors Technology: Permanent Magnet, Switched Reluctance, Synchronous, Asynchronous End User: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Heavy-duty Vehicles Application: Light-duty Applications, Heavy-duty Applications, Hybrid Electric Vehicles, Pure Electric Vehicles |
| Companies Covered | Robert Bosch GmbH, Siemens AG, Valeo SA, ZF Friedrichshafen AG, Nidec Corporation, Continental AG, BorgWarner Inc., Magna International, DENSO Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Motors for Electric Vehicle Market Shifts & Advancements
European motor suppliers are pivoting from efficiency optimization toward rare-earth independence and system-level thermal integration. Three convergent developments are restructuring competitive positioning and procurement criteria.
Switched reluctance motors paired with silicon carbide power electronics are rendering obsolete conventional induction motor architectures in cost-sensitive commercial vehicle applications. Tier-one suppliers serving European van and truck manufacturers are qualifying these topologies for 800-volt platforms. The shift compresses motor bill-of-material costs while meeting payload-critical torque density requirements.
REACH framework amendments targeting per- and polyfluoroalkyl substances in motor winding insulation are forcing reformulation of high-temperature enamel coatings. European motor manufacturers must validate alternative dielectric materials by 2027 to maintain CE marking eligibility. Passenger vehicle platforms with extended warranty obligations face the steepest requalification burden.
Leasing structures for powertrain subsystems are displacing traditional component purchase models among fleet operators. Commercial vehicle buyers in Germany and France increasingly contract motor-inverter-thermal units as service subscriptions tied to uptime guarantees. This reconfigures supplier cash flow profiles and residual value risk allocation across the value chain.
Europe Electric Motors for Electric Vehicle Market Segmentation
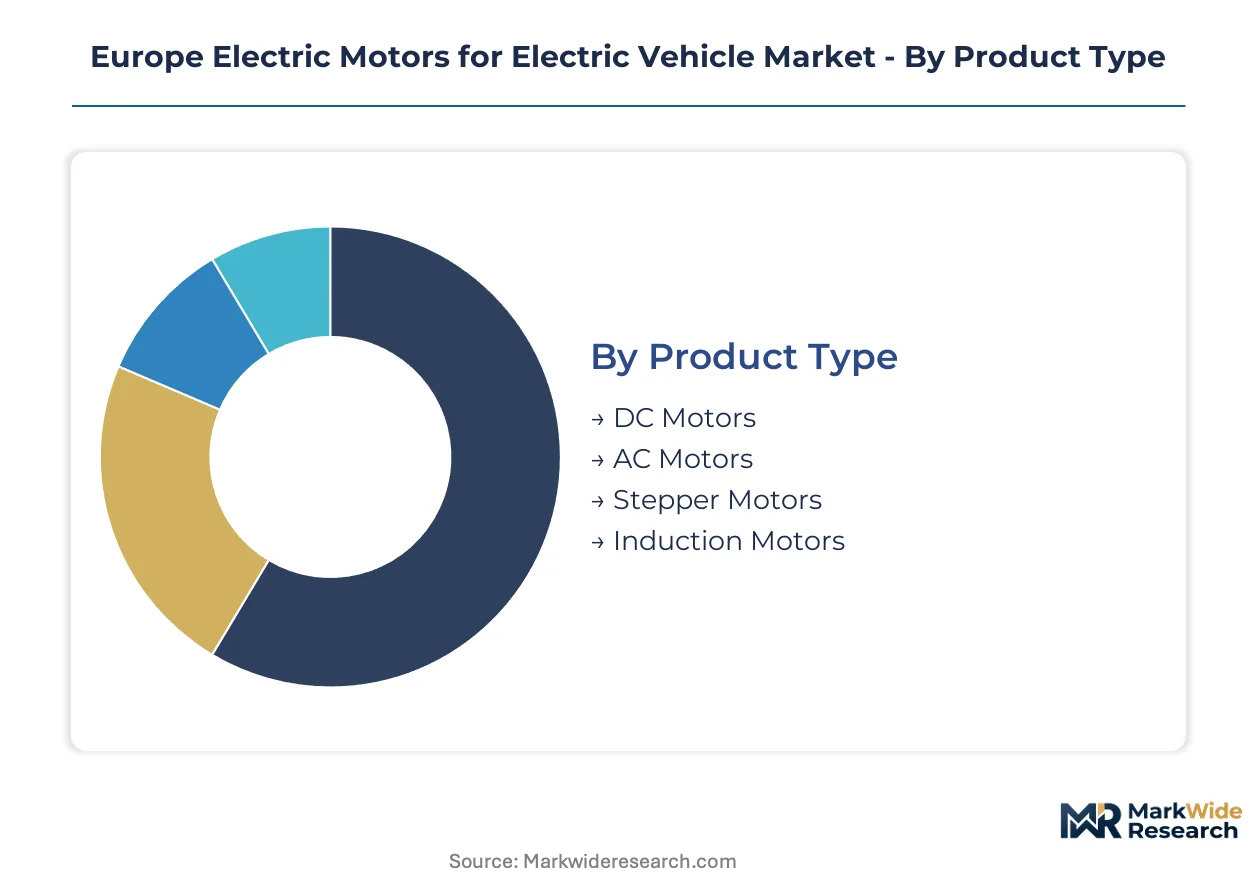
Segmentation in the Europe electric motors for electric vehicle market reveals distinct procurement cycles and technical qualification timelines. Motor topology selection directly determines supplier requalification frequency and platform development investment intensity across German, French, and Italian automotive clusters.
Product Type:
AC motors turn over fastest on specification refresh cycles, while DC architectures face extended validation periods due to legacy platform commitments.
- AC Motors:Polyphase alternating current architectures dominate high-voltage traction applications through variable frequency drive compatibility. German premium passenger vehicle manufacturers concentrate procurement here, driven by autobahn-capable sustained speed requirements and regenerative braking efficiency mandates.
- Induction Motors:Cage-rotor asynchronous designs eliminate permanent magnet supply chain exposure entirely. French commercial vehicle operators specify these for urban delivery fleets where torque density demands remain moderate and total cost of ownership prioritizes material cost stability over peak efficiency.
- DC Motors:Brushed and brushless direct current configurations persist in auxiliary systems and low-voltage applications.
- Stepper Motors:Incremental positioning motors serve precision control subsystems in thermal management and active aerodynamic actuators.
AC motors anchor the volume base while induction motor configurations gain share at the steepest rate.
Technology:
Cost tiers separate rare-earth-dependent architectures from magnet-free alternatives, with silicon carbide inverter pairing costs determining total system economics.
- Permanent Magnet:Neodymium-iron-boron rotor designs achieve power densities exceeding 4 kW per kilogram through concentrated magnetic flux. Italian sports car manufacturers and German luxury platforms specify these for launch torque and high-speed efficiency, though EU Green Deal sourcing disclosure mandates are extending supplier qualification timelines.
- Switched Reluctance:Doubly-salient rotor-stator geometries eliminate all rare-earth content while tolerating extreme thermal environments. Stellantis and Renault Group procurement teams are qualifying these for 800-volt commercial vehicle platforms, attracted by bill-of-material cost compression and supply security.
- Synchronous:Field-excited rotor designs balance efficiency with material flexibility through externally powered electromagnets.
- Asynchronous:Induction principles with copper or aluminum rotor cages remain cost-optimized for price-sensitive high-volume applications.
Permanent magnet architectures retain the revenue concentration while switched reluctance topologies are expanding most quickly across new platform introductions.
End User:
Application maturity varies sharply, with passenger vehicle segments demanding highest integration density and heavy-duty sectors tolerating larger form factors.
- Passenger Vehicles:Compact axial-flux and radial-flux motors integrate into electric axle modules with sub-100 millimeter axial length constraints. Volkswagen Group and BMW AG specifications drive demand here, with multi-speed gearbox pairing requirements complicating electromagnetic design optimization.
- Heavy-duty Vehicles:High-torque low-speed configurations for refuse collection and construction equipment operate at continuous duty cycles exceeding passenger vehicle thermal envelopes. Municipal zero-emission mandates in Berlin, Paris, and Milan are accelerating fleet conversion procurement.
- Commercial Vehicles:Van and light truck applications prioritize payload preservation through motor mass minimization.
- Two-wheelers:Hub-mounted and mid-drive configurations serve scooter and motorcycle electrification across Southern European urban mobility schemes.
Passenger vehicles anchor the volume base while heavy-duty vehicles gain share at the steepest rate.
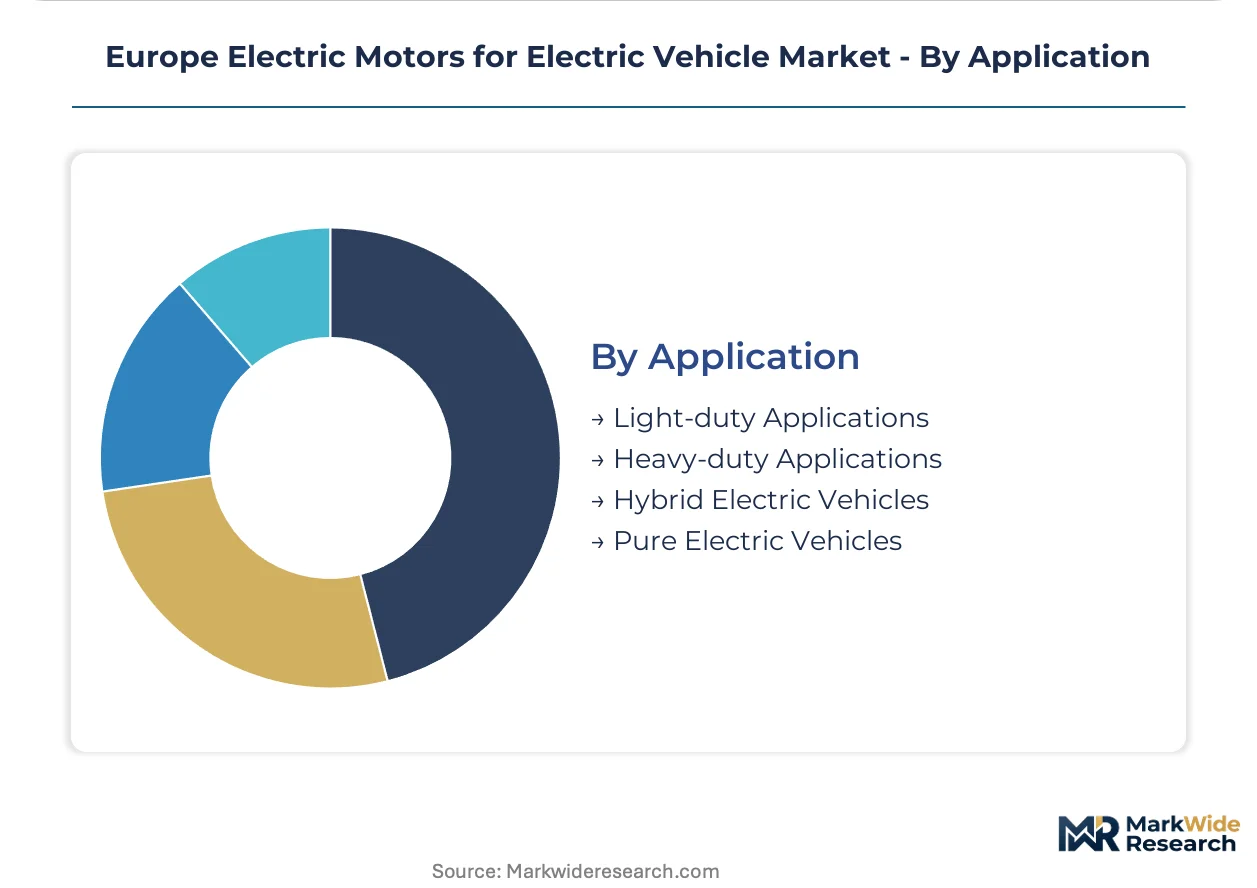
Application:
Supply concentration clusters around pure electric platforms, with hybrid applications fragmenting across multiple motor configurations per vehicle.
- Pure Electric Vehicles:Dedicated battery-electric architectures optimize motor sizing for single-source propulsion without combustion engine packaging compromises. Tesla Berlin-Brandenburg and Hyundai Motor Group Czech Republic production facilities source high-volume motor contracts here, with 800-volt system voltage migration driving insulation system upgrades.
- Heavy-duty Applications:Continuous gradeability and trailer-towing torque requirements demand liquid-cooled thermal management and reinforced bearing systems. Scandinavian electric truck manufacturers and Rhine-Ruhr logistics operators specify these for alpine corridor freight routes.
- Light-duty Applications:Urban delivery and commuter vehicles prioritize efficiency over peak power capability.
- Hybrid Electric Vehicles:Dual-motor configurations with power-split or parallel architectures require complex control integration.
Pure electric vehicle applications anchor the volume base while heavy-duty applications gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive clusters while French commercial vehicle operators extract procurement leverage through volume aggregation. This asymmetry shapes supplier qualification timelines and platform development investment intensity across European motor markets.
Germany
Volkswagen Group and BMW AG specifications drive demand for autobahn-capable synchronous motor architectures with multi-speed gearbox integration. KBA vehicle type approval mandates and EU Green Deal rare-earth sourcing disclosure rules extend supplier qualification cycles for permanent magnet designs. The Stuttgart and Munich production corridors anchor high-volume motor procurement for premium passenger vehicle platforms.
France
Renault Group and Stellantis procurement teams qualify switched reluctance topologies for commercial vehicle applications where bill-of-material cost compression outweighs peak efficiency targets. ANSM-aligned supply chain transparency requirements and REACH substance compliance protocols trigger reformulation of high-temperature winding insulation materials. The Paris-Saclay automotive cluster hosts power electronics-motor co-design engineering centers serving van and light truck electrification programs.
Italy
Ferrari and Lamborghini specifications sustain demand for high power-density permanent magnet motors exceeding 4 kW per kilogram for launch torque applications. EMA guidelines on automotive component safety and CE marking requirements for electromagnetic compatibility shape product certification pathways for Tier-1 suppliers. The Emilia-Romagna motor valley concentration around Modena and Bologna maintains specialized winding and rotor assembly capabilities for performance-oriented platforms.
Poland
Greenfield motor production facilities serving Volkswagen Group and Stellantis assembly plants leverage proximity logistics cost advantages and EU structural fund access for capacity expansion. F-Gas Regulation phase-out timelines accelerate demand for liquid-cooled thermal management systems in locally assembled commercial vehicles. The Lower Silesia and Greater Poland voivodeships concentrate new manufacturing investments from German and French Tier-1 suppliers.
Czech Republic
Hyundai Motor Group production facilities in Nošovice source high-volume motor contracts for dedicated battery-electric architectures migrating to 800-volt system voltages. REACH framework amendments targeting per- and polyfluoroalkyl substances in insulation materials force requalification of alternative dielectric coatings by 2027. The Moravian-Silesian automotive cluster integrates motor assembly with inverter and battery pack production for export-oriented vehicle platforms.
Europe Electric Motors for Electric Vehicle Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on electromagnetic design and thermal management subsystems. The vendor base structures around three tiers: diversified industrial conglomerates with captive automotive divisions, pure-play motor manufacturers with scale advantages in winding automation, and specialized engineering houses focused on topology innovation. Consolidation pressure concentrates among mid-cap suppliers lacking silicon carbide inverter pairing capabilities or axial-flux commercialization pipelines. Dominant competitive moves include backward integration into power electronics and geographic expansion into Central European automotive clusters.
Within the diversified industrial tier, Robert Bosch GmbH and Siemens AG exemplify platform integrators with cross-sector electrification heritage anchoring their positions. Continental AG occupies a specialist position in asynchronous motor architectures for cost-sensitive commercial applications. These three German-headquartered entities represent contrasting strategic postures: conglomerate breadth against focused topology specialization, with each archetype serving distinct procurement criteria across passenger and heavy-duty vehicle segments.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Siemens AG |
| Valeo SA |
| ZF Friedrichshafen AG |
| Nidec Corporation |
| Continental AG |
| BorgWarner Inc. |
| Magna International |
| DENSO Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese rare-earth oxide separation facilities is compressing magnet feedstock premiums and forcing European motor suppliers to renegotiate long-term offtake terms or absorb margin erosion on permanent magnet architectures.
Pricing Analysis
The customization-premium spread between configured-to-order synchronous motors and standard induction designs runs wide across European procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates rare-earth-dependent permanent magnet systems from switched reluctance alternatives and basic asynchronous configurations. Cost compression in the economy tier is intensifying because Stellantis and Renault Group procurement teams are consolidating volume around magnet-free topologies. Fleet operators in France and Germany exhibit the highest price sensitivity, while Italian sports car manufacturers tolerate substantial premiums for launch-torque-optimized designs.
Supply Chain Analysis
Upstream feedstock concentration in Chinese rare-earth mining and Southeast Asian oxide separation facilities exposes European motor manufacturers to quota-announcement volatility. Neodymium-iron-boron magnet production draws from Chinese separation capacity, Malaysian processing hubs, and Japanese alloy fabrication. Single-source vulnerability concentrates in heavy rare-earth separation where dysprosium and terbium supply hinges on Myanmar and Chinese feedstock. Distribution runs through German and French Tier-1 suppliers with captive winding facilities in Poland and the Czech Republic.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain-as-a-service subscription models are expanding faster than hardware unit sales across German and French commercial vehicle fleets, creating attach-rate expansion for thermal management and predictive maintenance overlays.
For Market Incumbents: Insulate permanent magnet motor margins by accelerating backward integration into rare-earth magnet recycling and qualifying secondary supply from Australian and Canadian feedstock projects. Siemens AG and Robert Bosch GmbH must defend against switched reluctance substitution by embedding silicon carbide inverter co-design capabilities that asynchronous competitors cannot replicate.
For New Entrants and Emerging Players: Mid-market commercial van operators in Poland and the Czech Republic represent the most penetrable entry point for axial-flux topology specialists lacking incumbent scale. Czech-based engineering houses can leverage proximity to Hyundai Motor Group Nošovice production for 800-volt platform qualification. A motor-inverter-thermal bundle sold through fleet management aggregators bypasses entrenched OEM supply agreements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among powertrain subsystem lessors with uptime-guarantee contracts tied to municipal zero-emission mandates. Acquisition targets with CSRD-aligned lifecycle accounting and verified scope 3 carbon transparency command premium multiples. Watch for EU Green Deal rare-earth disclosure enforcement tightening as the inflection signal for magnet-recycling technology valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Co-Design | Enables switched reluctance motor adoption in 800-volt platforms for Stellantis and Renault. |
| Rare-Earth Magnet Recycling Capacity | Reduces Chinese feedstock dependency under EU Green Deal sourcing disclosure mandates. |
| Axial-Flux Topology Commercialization | Delivers packaging advantages for compact urban delivery vehicles in Polish and Czech markets. |
| Powertrain-as-a-Service Subscription | Captures recurring revenue from German and French fleet operators seeking uptime guarantees. |
| REACH-Compliant Insulation Reformulation | Maintains CE marking eligibility as PFAS restrictions tighten on high-temperature winding coatings. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket service heads, and power electronics integration specialists. Secondary validation drew from KBA vehicle type approval databases, ECHA REACH substance filings, EU structural fund disbursement records, and IHS Markit vehicle production data. Bottom-up motor shipment estimates triangulated against top-down EV penetration forecasts across the analysis window.
Calibration against historical permanent magnet price series and silicon carbide inverter adoption curves anchored the analytical framework. Segmentation dimensions modeled include motor topology, vehicle class, propulsion architecture, and regional production cluster. CAGRs were derived from fitted growth curves applied to technology-specific adoption phases. Rare-earth oxide price volatility assumptions and F-Gas Regulation phase-out timelines served as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in euro-denominated raw material costs, Chinese export quota announcements, or EU Green Deal enforcement intensity would shift the trajectory. Cross-checking against EEA EV registration benchmarks and OEM production plan disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
UAE Electric Motor Market
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Global Hub Motors Market
Electric Motor
Electric Motors for IC Engine Vehicle Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Electric Drives Market
Electric Motor
EV Traction Motor Market
Electric Motor
Electric Motorcycle Market
Electric Motor
Automotive Heater Fan Motor Market
Electric Motor
Separately Excited Motor Market
Electric Motor
Torque Motor Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Global in-Wheel Motors Market
Electric Motor
Large Synchronous Motor Market
Electric Motor
Electric Vehicle Motor Shaft Market