
 Global Electric Motors for Electric Vehicle Market | 2026-2036
Global Electric Motors for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Motors for Electric Vehicle Market Analysis
Software-defined motor calibration is broadening what automakers purchase beyond hardware alone. Robert Bosch GmbH leverages its integrated powertrain software stack to capture recurring service value. Nidec Corporation anchors high-volume permanent magnet motor production for Asian OEM supply chains. Continental AG differentiates through thermal management integration that extends motor operating envelopes.
Electric motors for electric vehicles are electromechanical devices converting electrical energy into mechanical torque through electromagnetic induction, typically achieving peak efficiencies above 95% in permanent magnet synchronous configurations. These motors propel battery-electric and hybrid vehicles without direct fossil fuel combustion. Permanent magnet motors command the dominant share of passenger car applications due to superior power density and efficiency thresholds. Brushless DC architectures are gaining share in two-wheeler and light commercial segments where cost sensitivity and simplified control electronics matter most. Integrated powertrain technology concentrates margin pools by combining motor, inverter, and gearbox into single thermal and mechanical packages.
The US EPA tailpipe standards and NHTSA fuel economy mandates compel OEMs to source higher-efficiency motor systems. China's MIIT enforces GB standards for motor energy consumption that filter market access for foreign suppliers. The EU Green Deal and REACH regulations on rare earth sourcing are forcing supply chain restructuring for permanent magnet materials. Stakeholders must monitor how rare earth recycling mandates and alternative magnet chemistries reshape cost structures and supplier qualifications.
Market Dynamics
Permanent magnet supply concentration and rare earth processing bottlenecks are forcing motor manufacturers to redesign rotor architectures and qualify alternative magnetic materials. This structural pressure cascades through procurement timelines, thermal management specifications, and supplier qualification protocols across passenger and commercial vehicle programs.
Growth Catalysts
- China's MIIT GB efficiency mandates:Domestic OEMs must source motors meeting stricter energy consumption thresholds, filtering supplier pools toward high-performance permanent magnet synchronous designs.
- Commercial vehicle electrification:Heavy-duty battery-electric trucks and buses require high-torque motors with sustained thermal endurance, expanding addressable motor volumes beyond passenger cars.
- Hairpin winding technology:This conductor geometry improves slot fill factors and copper utilization, enabling power density gains that satisfy downsizing requirements without sacrificing output.
Market Restraints
- Rare earth oxide price volatility:Neodymium and dysprosium feedstock costs swing with Chinese export quotas, compressing margins for permanent magnet rotor producers.
- Single-source magnet processing:Separation and refining capacity concentrates in China's Jiangxi and Inner Mongolia corridors, creating geopolitical exposure for Western motor manufacturers.
- Induction motor efficiency ceiling:Without rare earth permanent magnets, asynchronous designs hit thermal and power density limits that disqualify them from premium passenger EV platforms.
Strategic Opportunities
- India's PLI scheme for auto components:Localized motor and powertrain manufacturing incentives attract suppliers seeking tariff-advantaged access to emerging domestic EV demand.
- Ferrite-assisted synchronous reluctance motors:Combining ferrite magnets with optimized rotor geometries offers a rare-earth-reduced pathway for cost-sensitive vehicle segments.
- Direct-to-fleet powertrain procurement:Logistics operators with captive charging infrastructure now source integrated motor-inverter-axle units outside traditional OEM channels.
Industry Challenges
- Electromagnetic compatibility certification:Motor-inverter systems must pass stringent CISPR and OEM-specific EMC validation cycles that extend development timelines.
- High-voltage winding insulation expertise:The shift to 800V architectures demands specialized impregnation and partial discharge testing capabilities that remain scarce in contract manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Motors for Electric Vehicle Market |
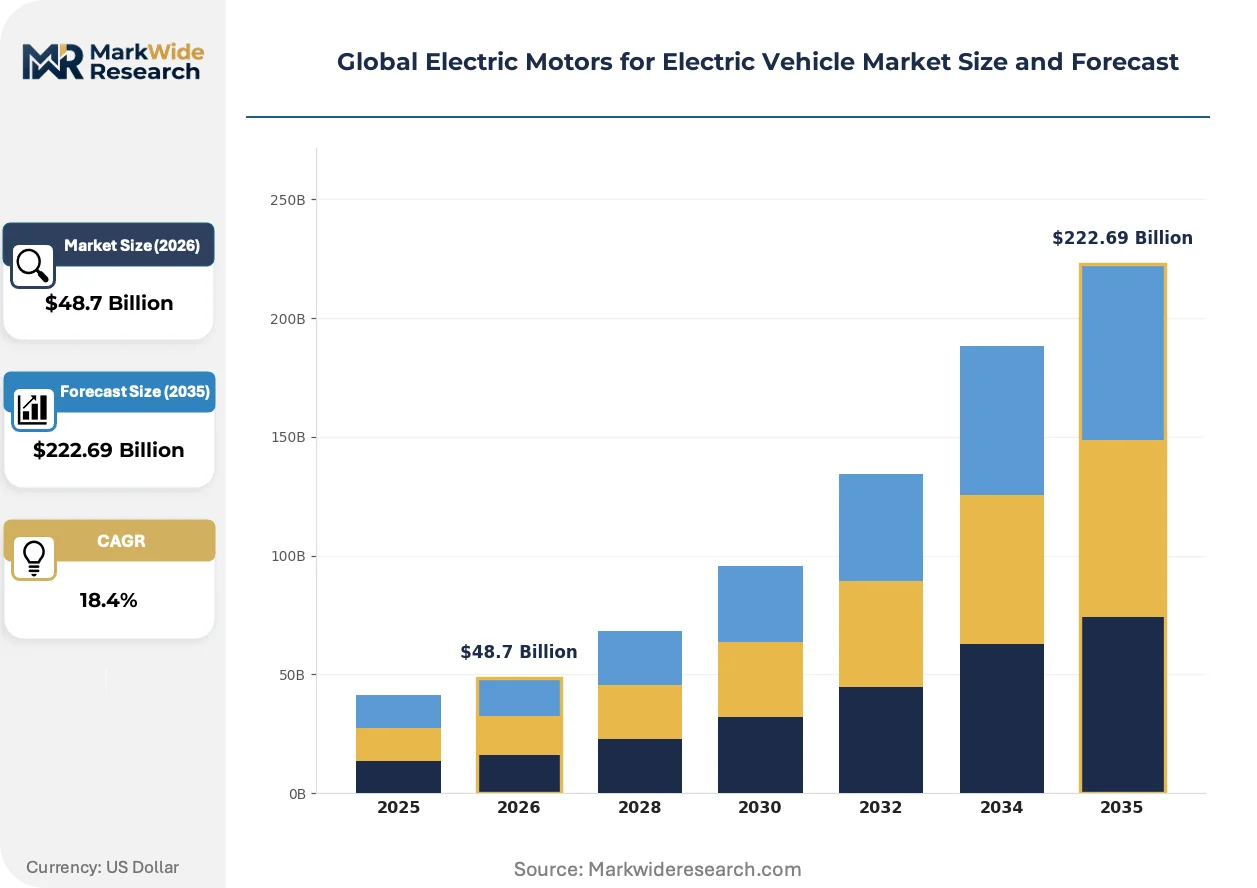
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $222.69 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: AC Induction, Brushless DC, Switched Reluctance, Permanent Magnet Power Rating: Small (up to 50 kW), Medium (51-150 kW), Large (151-300 kW), Extra Large (above 300 kW) Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Buses Technology: Direct Drive, Geared Motors, Dual Motor, Integrated Powertrain |
| Companies Covered | Robert Bosch GmbH, Nidec Corporation, ABB Ltd., ZF Friedrichshafen AG, Mitsubishi Electric Corporation, Brose Fahrzeugteile SE & Co. KG, Continental AG, Johnson Electric Group, BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Motors for Electric Vehicle Market Emerging Trajectories
Silicon carbide power electronics and advanced thermal interface materials are compressing the boundary between motor and inverter engineering. These converging capabilities enable new integrated powertrain architectures that reduce mass, part count, and assembly complexity.
Hairpin stator winding is decentralizing motor manufacturing geography by enabling automated coil insertion that reduces labor cost differentials between high-wage and emerging production locations. European and North American suppliers are adopting this process to reshore stator assembly previously concentrated in Asian wound-motor facilities. The technology permits smaller batch sizes and faster retooling, supporting regionalized supply strategies that align with IRA and EU Green Deal content requirements.
The EU's F-Gas Regulation and REACH restrictions on per- and polyfluoroalkyl substances are compelling motor manufacturers to eliminate fluorinated cooling fluids and PFAS-containing bearing greases from sealed powertrain units. Suppliers must reformulate thermal management fluids and lubricants while maintaining dielectric strength and operating temperature ranges. This regulatory pressure most acutely affects integrated e-axle producers serving German and French OEM platforms, where compliance deadlines precede other markets by 18-24 months.
Fleet operators and mobility-as-a-service providers are unbundling powertrain procurement from vehicle purchases, negotiating direct motor-inverter service agreements based on utilization metrics rather than upfront hardware costs. This consumption-based model disrupts traditional OEM captive supply structures and opens channels for independent motor specialists. The shift is most visible in European urban bus electrification and North American last-mile delivery van deployments, where total-cost-of-ownership transparency favors modular, replaceable powertrain subsystems.
Global Electric Motors for Electric Vehicle Market Segmentation
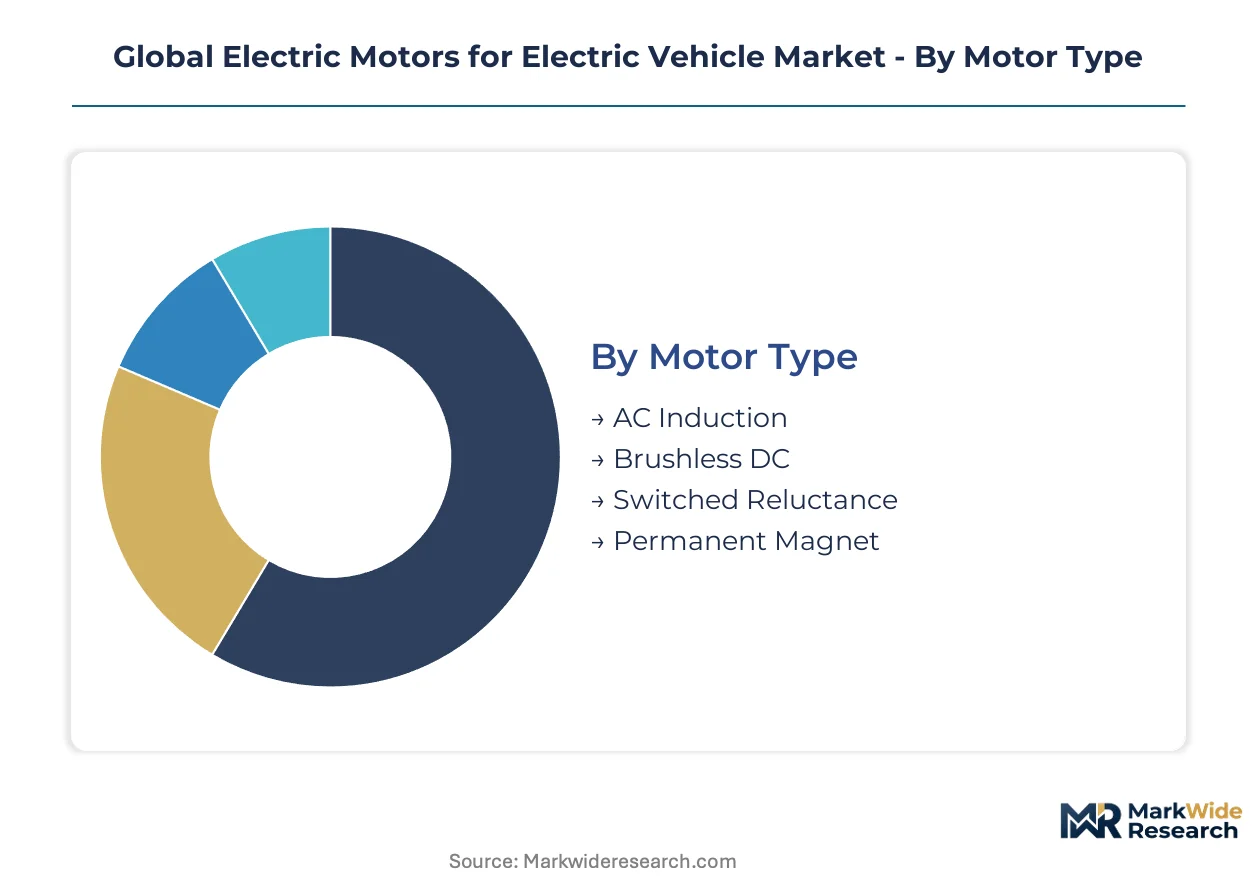
Motor segmentation determines procurement architecture for OEMs. Power density requirements, thermal envelopes, and integration depth vary sharply across vehicle classes and operating profiles.
Motor Type:
Standardization dominates high-volume platforms while custom rotor geometries serve niche thermal or cost constraints.
- Permanent Magnet:Neodymium-iron-boron rotors deliver peak efficiencies above 95% with superior power density. China's MIIT GB standards and German OEM platforms in Stuttgart concentrate demand here, though rare earth supply concentration forces alternative magnet qualification timelines.
- Brushless DC:Simplified electronic commutation reduces controller complexity for cost-sensitive two-wheeler and light commercial applications. Indian PLI scheme incentives and Southeast Asian motorcycle electrification are accelerating volume ramp.
- AC Induction:Copper rotor bars eliminate magnet supply risk entirely. Tesla's early platform adoption established volume precedent, though efficiency ceilings limit expansion into premium passenger segments.
- Switched Reluctance:Salient pole rotors without windings or magnets withstand extreme thermal cycling. Mining and construction vehicle electrification in Australia and Canada exploits this ruggedness.
Most installed capacity flows through Permanent Magnet. Expansion is steepest in Brushless DC.
Power Rating:
Cost tier segmentation tracks vehicle class and battery pack sizing, with thermal management spend scaling non-linearly above 150 kW.
- Medium (51-150 kW):Dominates compact and mid-size passenger car platforms where single-motor front-wheel-drive architectures prevail. European C-segment electrification and China's domestic OEM volume programs anchor demand here.
- Large (151-300 kW):Dual-motor all-wheel-drive premium platforms and single-motor commercial vans require sustained thermal endurance. German luxury OEMs and North American delivery fleet operators are standardizing on this bracket.
- Small (up to 50 kW):Two-wheeler and urban micro-mobility applications prioritize weight reduction over peak output. Indian electric scooter manufacturers and Vietnamese motorcycle converters dominate procurement.
- Extra Large (above 300 kW):Heavy-duty battery-electric trucks and articulated buses demand liquid-cooled stator assemblies with hairpin windings. Mining haul trucks in Western Australia and European long-haul corridors are piloting these systems.
Volume concentrates in Medium ratings. Value expansion runs fastest through Extra Large.
Vehicle Type:
Application-driven specification divergence separates passenger car efficiency optimization from commercial vehicle durability engineering.
- Passenger Cars:Permanent magnet synchronous motors with integrated inverters dominate platform designs. German automotive manufacturing corridors around Stuttgart and Munich, plus China's Yangtze River Delta OEM clusters, set global specification benchmarks.
- Commercial Vehicles:High-torque requirements and sustained gradeability demand reinforced bearing systems and enhanced cooling. California's Advanced Clean Trucks regulation and EU CO2 standards for heavy-duty vehicles are forcing motor upsizing.
- Motorcycles:Hub-mounted brushless DC architectures eliminate chain or belt drivetrains. Southeast Asian conversion programs and Indian electric two-wheeler subsidies are expanding addressable volumes.
- Buses:Low-floor packaging constraints favor axial-flux or pancake motor geometries with direct wheel mounting. European urban fleet electrification and China's municipal procurement mandates drive specification convergence.
Passenger Cars absorb the greatest motor unit volumes. Commercial Vehicles are climbing the fastest on value per unit.
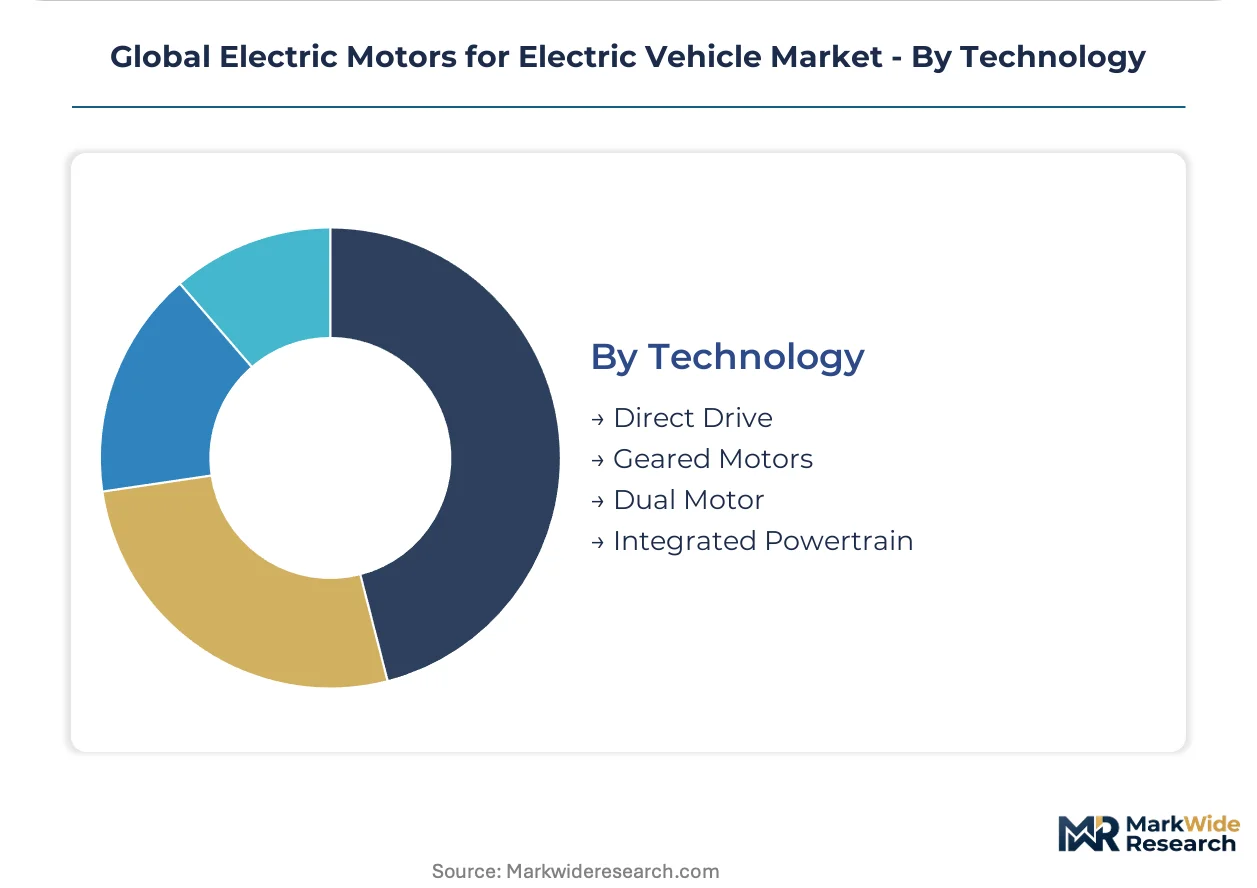
Technology:
Integration depth determines supplier margin capture, with modular architectures enabling third-party service competition.
- Integrated Powertrain:Combined motor-inverter-gearbox units reduce assembly complexity and thermal interface count. Robert Bosch GmbH and Continental AG compete here through software-defined calibration stacks.
- Direct Drive:Elimination of reduction gears cuts mechanical losses and maintenance points. Urban bus and delivery van applications in European low-emission zones favor this simplicity.
- Geared Motors:Single-speed or multi-speed reduction stages optimize motor operating points across vehicle speed ranges. Cost-sensitive platforms in India and Brazil retain this proven architecture.
- Dual Motor:Torque vectoring and redundancy for premium all-wheel-drive platforms. German luxury OEMs and North American electric truck startups specify these for performance differentiation.
Integrated Powertrain captures the highest share of new program awards. Direct Drive is expanding most quickly in fleet conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates permanent magnet motor engineering for premium passenger platforms, while China's MIIT efficiency mandates filter supplier access through stricter GB standards that domestic OEMs must satisfy.
China
Yangtze River Delta OEM clusters anchor high-volume permanent magnet synchronous motor procurement for domestic EV platforms. MIIT enforces GB standards for motor energy consumption that filter market access for foreign suppliers. Jiangxi and Inner Mongolia corridors concentrate rare earth separation and refining capacity, creating processing bottlenecks that cascade through rotor procurement timelines.
Germany
Stuttgart and Munich manufacturing corridors set global specification benchmarks for integrated powertrain systems serving luxury OEM platforms. EU Green Deal and REACH regulations on rare earth sourcing force supply chain restructuring for permanent magnet materials. Continental AG and Robert Bosch GmbH compete through software-defined calibration stacks that capture recurring service value.
United States
California's Advanced Clean Trucks regulation and NHTSA fuel economy mandates compel OEMs to source higher-efficiency motor systems for heavy-duty electrification. EPA tailpipe standards tighten compliance thresholds across passenger and commercial vehicle segments. Michigan and Ohio manufacturing bases host inverter-motor integration facilities serving North American OEM programs.
India
Domestic OEM volume programs and electric scooter manufacturers drive brushless DC motor demand in the 51-150 kW and sub-50 kW brackets. PLI scheme for auto components attracts localized motor and powertrain manufacturing seeking tariff-advantaged market access. Tamil Nadu and Gujarat production corridors expand stator winding capacity for Southeast Asian motorcycle electrification export programs.
Japan
Automotive Tier 1 suppliers anchor high-reliability motor-inverter integration for hybrid and battery-electric platforms. METI industrial policy supports rare earth recycling technology development to reduce magnet supply concentration risk. Nagoya and Tokyo metropolitan manufacturing bases concentrate hairpin winding automation expertise serving Asian OEM supply chains.
Global Electric Motors for Electric Vehicle Market Vendor Landscape
Top-tier vendors anchor integrated powertrain engineering, while mid-tier specialists compete on motor subcomponent cost and regional manufacturing proximity. The vendor base stratifies across three tiers: diversified automotive Tier 1 conglomerates with software stacks, dedicated motor manufacturers with magnet supply chain control, and emerging Asian fabricators exploiting hairpin winding automation. Consolidation pressure runs through strategic partnerships for silicon carbide inverter integration and captive rare earth processing investments.
Within the diversified Tier 1 tier, Robert Bosch GmbH and Continental AG exemplify integrated powertrain competition combining motor, inverter, and thermal management engineering. Nidec Corporation occupies a position among dedicated motor specialists with permanent magnet production scale. These three entities represent distinct competitive archetypes: software-defined calibration capture, high-volume magnet motor manufacturing, and thermal envelope extension through system integration.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Nidec Corporation |
| ABB Ltd. |
| ZF Friedrichshafen AG |
| Mitsubishi Electric Corporation |
| Brose Fahrzeugteile SE & Co. KG |
| Continental AG |
| Johnson Electric Group |
| BorgWarner Inc. |
| Others |
Supply Flow & Price Mechanics
Captive rare earth processing in China's Jiangxi and Inner Mongolia corridors anchors permanent magnet rotor pricing power, with Western motor manufacturers absorbing cost volatility through long-term offtake contracts or alternative magnet qualification programs. This upstream concentration forces tiered sourcing strategies that separate premium OEM platforms willing to pay magnet security premiums from cost-sensitive segments pursuing ferrite-assisted designs.
Pricing Analysis
Capacity additions in Tamil Nadu and Gujarat are reshaping price floors for brushless DC motors serving Indian and Southeast Asian two-wheeler electrification. Three-tier pricing structure across premium permanent magnet, standard ferrite-assisted, and economy induction configurations tracks certification grade and thermal envelope specifications. Cost compression in the sub-150 kW bracket is intensifying because hairpin winding automation reduces labor cost differentials between high-wage and emerging production locations. Fleet operators with captive charging infrastructure exhibit lowest price sensitivity, while Indian electric scooter manufacturers face acute procurement pressure.
Supply Chain Analysis
Hairpin winding automation expertise concentrates in Japan's Nagoya and Tokyo metropolitan manufacturing bases, with secondary capacity building in Germany's Stuttgart corridor and Michigan's inverter-motor integration facilities. Motor manufacturing draws from neodymium-iron-boron magnet feedstock, silicon carbide power semiconductors, and specialized high-voltage winding insulation materials. Single-source magnet processing in Chinese rare earth corridors creates geopolitical exposure for rotor procurement timelines. Distribution runs through Tier 1 integrated powertrain suppliers to OEM platform engineering teams, with direct-to-fleet channels emerging in European urban bus electrification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's MIIT efficiency mandates filtering supplier access and India's PLI scheme incentives attracting tariff-advantaged manufacturing investment.
For Market Incumbents: Anchor software-defined calibration stacks to capture recurring service value as fleet operators unbundle powertrain procurement from vehicle purchases. Deepen backward integration into rare earth recycling technology to reduce magnet supply concentration exposure. Prioritize thermal management integration investments that extend motor operating envelopes beyond competitor reach.
For New Entrants and Emerging Players: Logistics operators with captive charging infrastructure represent the most penetrable buyer archetype outside traditional OEM captive supply structures. Target direct-to-fleet motor-inverter service agreements based on utilization metrics rather than upfront hardware costs. Pursue ferrite-assisted synchronous reluctance motor qualification for cost-sensitive commercial vehicle segments where rare earth price volatility disqualifies permanent magnet designs.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier motor specialists with hairpin winding automation and regional manufacturing proximity because OEMs are reshoring stator assembly previously concentrated in Asian wound-motor facilities. Acquisition candidates should demonstrate silicon carbide inverter integration partnerships or captive rare earth processing investments. Monitor EU F-Gas Regulation and REACH compliance deadlines as inflection indicators for thermal management fluid and lubricant reformulation capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Hairpin Winding Automation Deployment | Enables reshoring of stator assembly from Asian facilities to meet IRA and EU Green Deal content requirements. |
| Rare Earth Recycling Technology Investment | Reduces magnet supply concentration risk as China's export quotas compress permanent magnet rotor margins. |
| Silicon Carbide Inverter Integration | Compresses thermal boundaries between motor and power electronics for next-generation integrated powertrain architectures. |
| Direct-to-Fleet Service Agreement Launch | Captures utilization-based revenue streams as logistics operators unbundle powertrain procurement from vehicle purchases. |
| Ferrite-Assisted Motor Qualification | Opens cost-sensitive commercial vehicle segments where rare earth price volatility constrains permanent magnet adoption. |
Methodological Framework
Coverage spans China's Yangtze River Delta OEM clusters, Germany's Stuttgart and Munich manufacturing corridors, India's Tamil Nadu and Gujarat production bases, and North American Midwest inverter-motor integration facilities, with primary inputs from each. Motor procurement directors at Tier 1 suppliers, OEM platform engineers, rare earth processing specialists, and fleet electrification managers contributed through structured interviews. Secondary validation drew from MIIT GB standard filings, EPA tailpipe compliance databases, EU REACH substance restriction updates, and vehicle production registration data. Bottom-up segment sizing triangulated against top-down OEM platform electrification roadmaps.
Rate-of-change decomposition separated volume expansion from content-per-vehicle increases across the projection horizon. Segmentation dimensions modeled include motor type, power rating bracket, vehicle class, and integration depth. CAGRs derived from fitted growth curves applied to OEM platform launch timelines and regulatory compliance deadlines. Industry-specific forecast inputs encompassed commercial vehicle electrification mandates and hairpin winding adoption rates in regional manufacturing bases.
Inputs from regulatory filing databases and OEM procurement disclosures were available through the study window; gaps in direct fleet operator utilization data introduce uncertainty bands around service-based revenue projections. Forecasts reflect assumptions regarding rare earth supply continuity and silicon carbide power semiconductor scaling. Practitioners should monitor EU F-Gas Regulation enforcement timelines and China's dual carbon goal implementation pace for early signals of thermal management fluid reformulation urgency and magnet supply restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
APAC Electric Drives Market
Electric Motor
Electric Vehicle (EV) Traction Motor Market
Electric Motor
Torque Motor Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Global Automotive Starter Motor Market
Electric Motor
Electric Motor Sales Market
Electric Motor
Automotive Heater Fan Motor Market
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
China E-Bike (Pedelec Bikes) Hub Motor Market
Electric Motor
Separately Excited Motor Market
Electric Motor
Kayak Trolling Motor Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Vibrator Motor Market
Electric Motor
Electric Vehicle Motor Micro Controller Market
Electric Motor
Implant Motors Market
Electric Motor
Large Synchronous Motor Market