
 Europe Electric Motor Market | 2026-2036
Europe Electric Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Motor Market Analysis
German industrial motor production is decoupling from legacy asynchronous designs as tier-one suppliers retool for electrification. Siemens AG leverages its Nuremberg R&D campus to anchor permanent magnet motor development for traction applications. Robert Bosch GmbH sustains competitive position through backward integration into power electronics and rotor manufacturing. ABB Group dominates medium-voltage industrial motor supply across Nordic process industries.
An electric motor converts electrical energy into mechanical torque through electromagnetic interaction between stator windings and a rotor, with continuous power ratings spanning fractional horsepower to multi-megawatt outputs for heavy industrial loads. AC Motors retain volume leadership across European HVAC Systems and compressor applications where grid-connected operation predominates. Brushless technology captures disproportionate investment as servo-grade precision requirements expand in German packaging machinery and Swiss CNC equipment. The Transportation End User segment generates premium margin pools as rail propulsion and marine electrification specifications tighten.
The EU Ecodesign Directive and F-Gas Regulation jointly reshape product standards by mandating IE4 efficiency minimums and restricting cooling system refrigerants that interact with motor-integrated heat pumps. EMA and national notified bodies coordinate conformity assessment for medical device motors under MDR Annex I performance requirements. Stakeholders must monitor how the EU AI Act classifies autonomous motor control systems before committing to embedded sensor architectures.
Market Dynamics
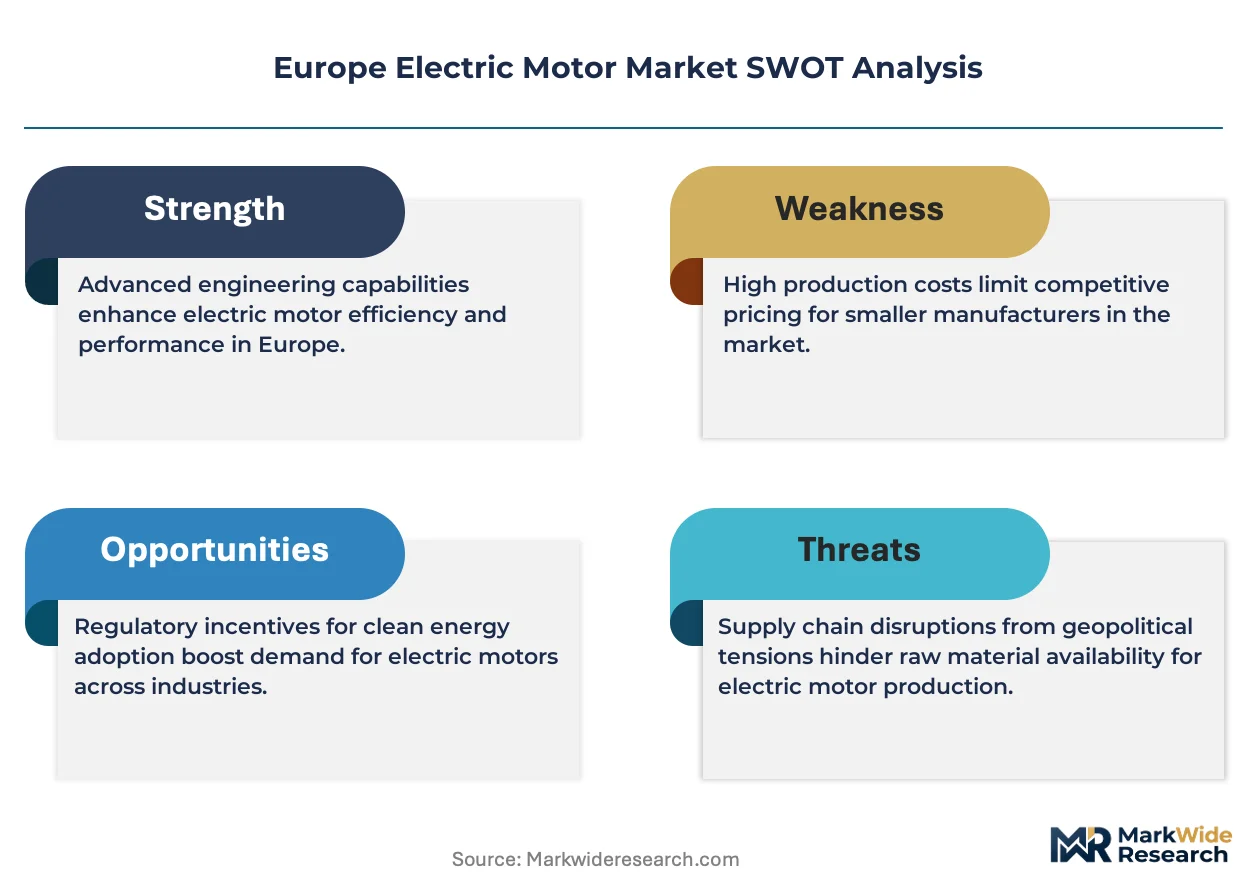
The EU Ecodesign Directive's IE4 efficiency mandates are forcing synchronous motor replacement cycles across European process industries while simultaneously elevating rare-earth magnet supply security to strategic priority status.
Growth Catalysts
- IE4 Minimum Efficiency Mandates:The EU Ecodesign Directive's tightened standards for industrial motors are compelling facility-wide upgrades across German chemical processing and Nordic pulp-and-paper operations.
- Rail Electrification Specifications:Tightening propulsion standards for high-speed and urban rail networks are expanding multi-megawatt traction motor procurement volumes in France, Italy, and Spain.
- Permanent Magnet Rotor Adoption:Brushless synchronous designs are capturing share in precision servo applications across Swiss CNC equipment and German packaging machinery sectors.
Market Restraints
- Rare-Earth Concentration Risk:Neodymium and dysprosium processing concentrates outside European borders, creating supply vulnerability for high-efficiency permanent magnet motors.
- Copper Price Volatility:Stator winding material costs fluctuate with commodity cycles, compressing margins for standardized asynchronous motor producers serving price-sensitive HVAC channels.
- Technical Limitation in High-Temperature Environments:Permanent magnet demagnetization thresholds constrain motor deployment in steel mill rolling mills and cement kiln applications where legacy wound-rotor designs persist.
Strategic Opportunities
- Poland Industrial Motor Demand:Manufacturing reshoring and automotive supplier clustering around Wrocław and Poznań are creating underpenetrated demand for medium-voltage drive systems.
- Marine Electrification Specifications:Baltic Sea and Mediterranean port authorities are tightening emissions standards for harbor craft and short-sea shipping, expanding kilowatt-class propulsion motor procurement.
- Power Electronics Convergence:Integration of wide-bandgap semiconductors with motor control architectures is enabling higher switching frequencies that reduce filter size and thermal management overhead.
Industry Challenges
- Magnet Rewinding Skill Shortage:European technical training pipelines are failing to produce sufficient technicians proficient in rare-earth magnet handling and rotor re-magnetization procedures.
- CE-MDR Dual Certification Timelines:Medical device motor suppliers face extended conformity assessment periods as EMA and national notified bodies coordinate Annex I performance validations.
- Legacy Drive Retrofit Complexity:Replacing asynchronous motors with synchronous designs in established manufacturing lines requires coordinated inverter, cable, and control system upgrades that disrupt production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Motor Market |
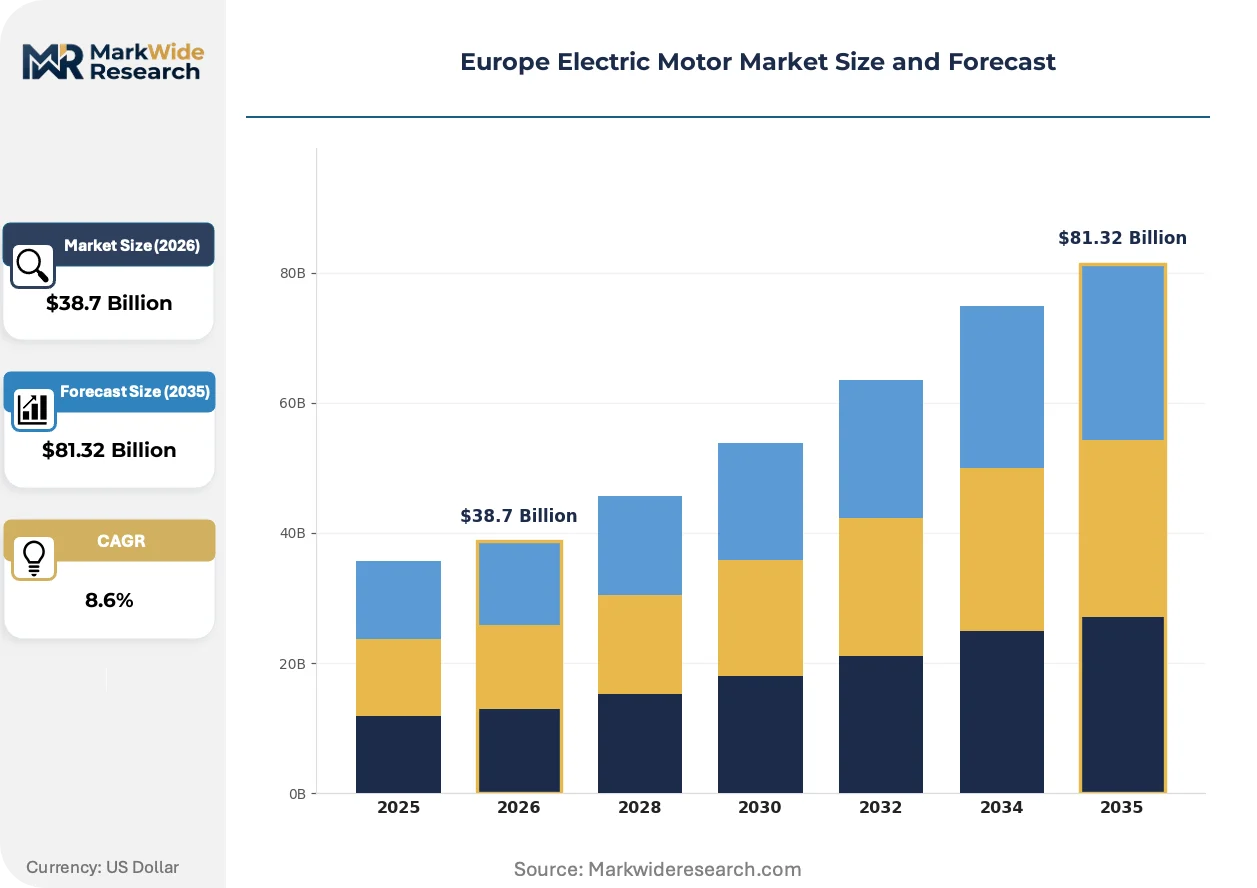
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Servo Motors, Stepper Motors Application: Automotive, Industrial Machinery, HVAC Systems, Home Appliances End User: Manufacturing, Transportation, Residential, Commercial Technology: Brushless, Synchronous, Asynchronous, Switched Reluctance |
| Companies Covered | ZF Friedrichshafen AG, SEW EURODRIVE, Siemens AG, Maxon Motor AG, Nidec Corporation, Robert Bosch GmbH, Valeo SA, AISIN, ABB Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Motor Market Emerging Trajectories
Permanent magnet motor architectures are unifying with silicon carbide power electronics to reshape efficiency benchmarks across European industrial automation and transportation electrification segments.
Silicon carbide MOSFET-based inverters are unifying with interior permanent magnet motors to eliminate DC-link capacitors and enable higher power density in compact traction packages. German automotive suppliers are accelerating adoption for 800-volt EV platforms. This convergence is compressing the physical envelope for integrated drive units while elevating thermal management requirements.
The EU AI Act's risk classification framework for autonomous motor control systems is forcing embedded sensor architecture redesigns before full-scale deployment. Medical device and collaborative robotics manufacturers face heightened conformity obligations for real-time condition monitoring algorithms. Nordic process industry OEMs are delaying smart motor launches pending clarified notified body guidance on Annex III high-risk system categories.
Asset-as-a-service contracting is displacing outright motor purchases in energy-intensive process industries. Chemical and paper producers in the Netherlands and Belgium now specify performance-based availability guarantees rather than capital equipment procurement. This shift compresses supplier cash conversion cycles while elevating predictive maintenance capability requirements for motor OEMs serving Benelux manufacturing clusters.
Europe Electric Motor Market Segmentation
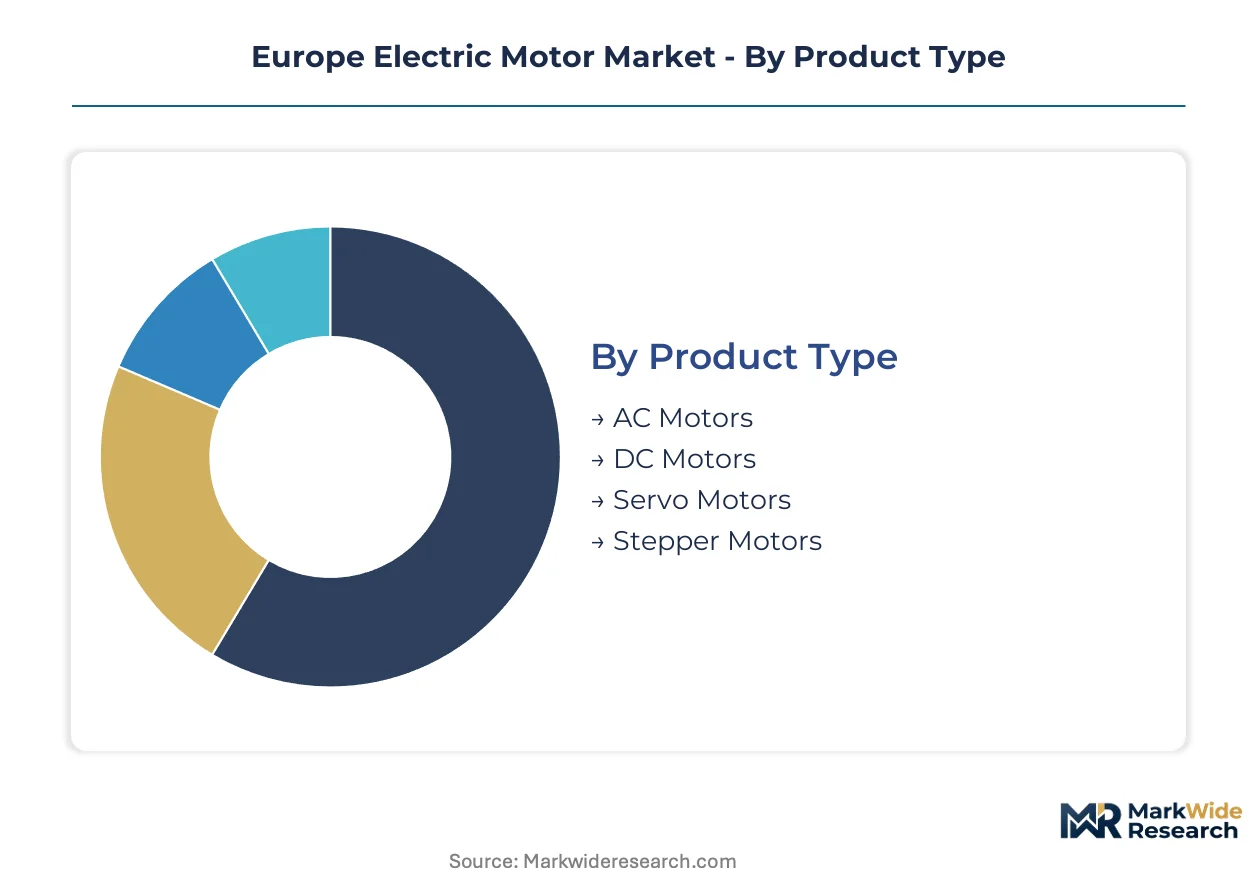
Electric motor procurement across Europe diverges sharply by power density requirements, duty cycle intensity, and regulatory exposure. Buyers prioritize efficiency certifications in German industrial corridors while Mediterranean markets emphasize first-cost economics for shorter payback periods.
Product Type:
Cost tier separates buyers seeking standardized commodity units from those demanding precision motion control with integrated feedback systems.
- AC Motors:Induction-based designs dominate grid-connected industrial infrastructure with continuous-duty ratings. Demand concentrates in Nordic pulp-and-paper mills upgrading to IE4 efficiency tiers under Ecodesign Directive pressure.
- DC Motors:Brushed and brushless configurations serve battery-powered mobility and off-grid automation. Swiss medical device manufacturers specify compact DC units for portable diagnostic equipment requiring precise speed regulation.
- Servo Motors:Closed-loop positioning systems with encoder feedback enable sub-millimeter accuracy in robotic workcells.
- Stepper Motors:Open-loop incremental positioning suits low-cost automation in packaging machinery across Poland's emerging manufacturing belt.
AC Motors lead volumes today; Servo Motors are gaining share fastest.
Application:
Application selection tracks capital intensity cycles and energy cost exposure across European manufacturing clusters.
- Automotive:Traction motors and auxiliary drive systems span 800-volt EV platforms to 48-volt mild-hybrid architectures. German OEMs in Bavaria and Baden-Württemberg dominate procurement volumes for integrated electric axle assemblies.
- Industrial Machinery:Conveyor drives, pump motors, and compressor units constitute the installed base replacement opportunity. Benelux chemical processors face compressed upgrade timelines as Ecodesign Directive enforcement tightens.
- HVAC Systems:Fan and blower motors in commercial buildings face refrigerant-linked efficiency pressures from F-Gas Regulation compliance.
- Home Appliances:Washing machine and refrigerator compressors drive fractional-horsepower demand in Eastern European manufacturing zones.
Industrial Machinery anchors current revenue; Automotive applications show the steepest expansion trajectory.
End User:
Customer type determines contract structure, with asset-as-a-service penetration varying by sector maturity and energy intensity.
- Manufacturing:Process industries and discrete automation constitute the core replacement market. German automotive suppliers around Stuttgart specify high-duty-cycle motors with predictive maintenance integration.
- Transportation:Rail propulsion and marine electrification command premium specifications. French TGV network expansions and Italian high-speed corridors drive multi-megawatt traction motor procurement.
- Residential:Heat pump and appliance motors face efficiency mandates through EU energy labeling frameworks.
- Commercial:Building automation and retail refrigeration systems prioritize acoustic performance alongside energy metrics.
Manufacturing retains volume leadership; Transportation end-use is expanding most quickly.
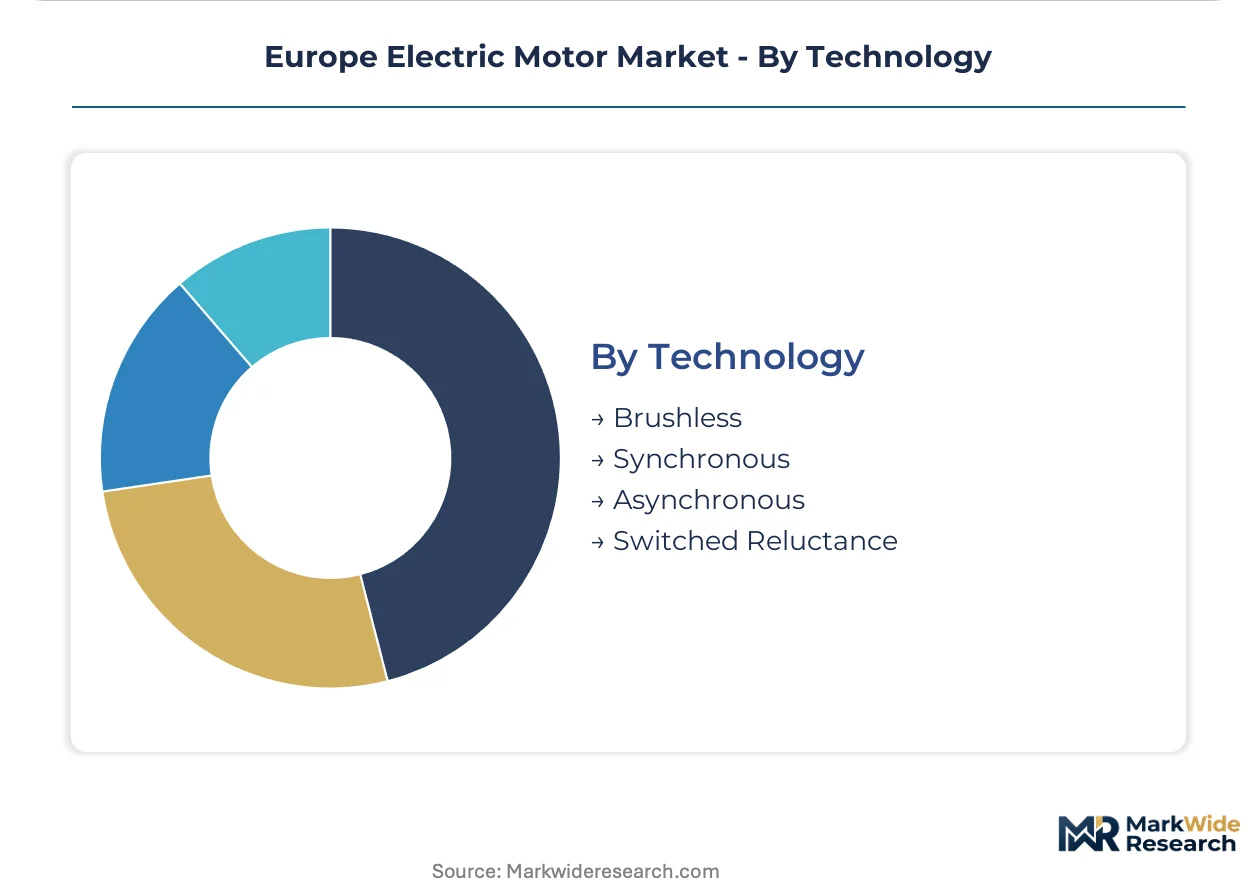
Technology:
Technology adoption splits between legacy asynchronous reliability and synchronous efficiency gains requiring magnet supply security.
- Brushless:Electronic commutation eliminates wear components while enabling precise torque control. German packaging machinery OEMs specify brushless servo systems for high-speed indexing applications.
- Synchronous:Permanent magnet and wound-field designs achieve highest efficiency ratings. Rare-earth magnet concentration outside Europe creates supply vulnerability for IE4-compliant industrial retrofits.
- Asynchronous:Squirrel-cage induction motors retain cost advantage in price-sensitive HVAC and pump applications.
- Switched Reluctance:Magnet-free topology suits high-temperature environments where demagnetization risks exclude permanent magnet alternatives.
Asynchronous technology dominates installed base; Synchronous designs are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within Europe tracks divergent enforcement timelines for the EU Ecodesign Directive, with manufacturers relocating assembly to jurisdictions offering transitional compliance grace periods or localized subsidy regimes for efficiency retrofits.
Germany
Automotive OEM procurement for 800-volt EV traction motors dominates demand volumes across Bavaria and Baden-Württemberg. The KBA enforces type-approval standards for powertrain electrification that exceed baseline EU requirements. Stuttgart's supplier corridor concentrates brushless motor R&D investment from tier-one drivetrain specialists.
France
TGV network expansion and urban rail electrification drive multi-megawatt traction motor procurement through SNCF and RATP procurement channels. ANSM coordination with EU notified bodies streamlines medical device motor certifications under MDR Annex I. The Île-de-France industrial belt hosts specialized winding facilities serving aerospace actuator applications.
Italy
High-speed rail corridor development between Milan and Naples expands synchronous motor orders for Hitachi Rail and Alstom propulsion systems. CE marking enforcement through national notified bodies tightens for industrial motors exported to German manufacturing customers. Emilia-Romagna's packaging machinery cluster specifies precision servo systems for food processing automation.
Poland
Automotive supplier clustering around Wrocław and Poznań generates underpenetrated demand for medium-voltage industrial drive systems serving battery component manufacturing. EU cohesion fund disbursements support factory efficiency upgrades that accelerate IE4 motor replacement cycles. The Silesian industrial zone retains wound-rotor motor demand for steel mill applications where permanent magnet temperature limits exclude synchronous designs.
Netherlands
Asset-as-a-service contracting for motor fleets displaces capital procurement among Rotterdam-Belgium chemical processing corridors. The Dutch Emissions Authority enforces F-Gas Regulation compliance for motor-integrated heat pumps in greenhouse horticulture. Eindhoven's high-tech systems sector sources compact brushless units for semiconductor wafer handling equipment.
Europe Electric Motor Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue magnet-free topologies and wide-bandgap integration to circumvent rare-earth supply vulnerabilities. The vendor base stratifies across three tiers: diversified industrial conglomerates with captive power electronics divisions, specialized motor OEMs serving defined application verticals, and Asian component suppliers penetrating through cost-optimized standard product lines. Dominant competitive moves include backward integration into permanent magnet recycling and strategic partnerships with silicon carbide foundries for inverter co-development.
Among Germany-based industrial groups, Siemens AG and Robert Bosch GmbH exemplify the integrated-systems archetype through in-house power electronics and rotor manufacturing capabilities. ABB Group anchors the Nordic process industry supply position. SEW EURODRIVE occupies a specialist role in decentralized drive technology. These entities represent contrasting strategic postures: conglomerate breadth versus application-focused depth versus regional market anchoring.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| SEW EURODRIVE |
| Siemens AG |
| Maxon Motor AG |
| Nidec Corporation |
| Robert Bosch GmbH |
| Valeo SA |
| AISIN |
| ABB Group |
| Others |
Supply Flow & Price Mechanics
Silicon carbide MOSFET integration with interior permanent magnet architectures is compressing inverter-motor package costs while simultaneously concentrating procurement leverage among German automotive OEMs with 800-volt platform scale. This technology shift elevates rare-earth magnet security to a pricing determinant alongside copper winding volatility.
Pricing Analysis
Distributor margins on standard asynchronous motors compress as direct OEM contracts for integrated traction systems capture volume discounts unavailable through channel intermediaries. Three-tier pricing structure across premium servo-grade, standard industrial IE4, and economy HVAC tiers separates buyers by certification burden and thermal management specification. Price differentiation hinges on CE-MDR dual certification timelines for medical device applications versus commodity induction units. Pricing pressure stems from copper commodity cycles and magnet supply uncertainty, with Eastern European appliance manufacturers exhibiting highest sensitivity and Swiss precision equipment buyers least responsive to first-cost variation.
Supply Chain Analysis
Workforce availability constraints in Czech and Romanian winding facilities are forcing production retention in German and Italian manufacturing corridors despite labor cost premiums. Magnet processing concentrates in China and Myanmar, while copper cathode supply draws from Chile and Zambia. Stator lamination dependency on electrical steel from Japan and South Korea creates tariff exposure through EU trade remedy proceedings. Distribution runs through tier-one automotive supplier clusters in Bavaria and Baden-Württemberg for traction applications, with industrial aftermarket channels serving fragmented Benelux process industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive operates as a regulatory compounder, with IE4 efficiency mandates forcing synchronous motor replacement cycles that accelerate demand for rare-earth-secure supply chains.
For Market Incumbents: Cement magnet recycling capabilities and silicon carbide foundry partnerships before rare-earth supply disruptions erode margin sustainability. Siemens AG and Robert Bosch GmbH demonstrate the defensive value of backward integration into power electronics and rotor manufacturing. Threat concentration sits with Chinese magnet processors leveraging cost-positioned standard motor exports into Eastern European manufacturing zones. For New Entrants and Emerging Players: Switched reluctance topology expertise offers a technology-first wedge into steel mill and cement kiln applications where permanent magnet demagnetization thresholds exclude synchronous designs. Poland's automotive supplier clustering around Wrocław presents the most penetrable geography for medium-voltage drive system entry. A performance-guarantee contracting model aligns with Benelux chemical processor preferences for asset-as-a-service procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among magnet-free motor specialists with high-temperature application portfolios and established relationships with Nordic process industry OEMs. Long-term viability centers on rare-earth supply security rather than commodity copper exposure. The signal to watch is EU critical raw materials legislation implementation pace as inflection indicator for permanent magnet motor cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Recycling Facility Investment | Secures rare-earth supply independence for IE4 motor production under EU Critical Raw Materials Act pressure. |
| Silicon Carbide Foundry Partnership | Enables 800-volt traction motor-inverter integration for German automotive OEM procurement specifications. |
| Switched Reluctance R&D Expansion | Addresses steel mill and cement kiln applications where synchronous motor temperature limits create exclusion. |
| Asset-as-a-Service Platform Launch | Aligns with Benelux chemical processor contracting preferences and compresses competitor cash conversion cycles. |
| Poland Manufacturing Footprint Establishment | Captures automotive supplier clustering demand around Wrocław and Poznań with EU cohesion fund tailwinds. |
Methodological Framework
Multiple input streams — OEM procurement director interviews, tier-one supplier technical consultations, and regulatory affairs exchanges with EMA and national notified bodies — were reconciled against trade data, SEC filings from listed motor manufacturers, and EU Ecodesign Directive implementation tracking. Secondary validation drew from customs records, production databases, and F-Gas Regulation enforcement disclosures. Bottom-up segment sizing and top-down macroeconomic anchoring were cross-checked for consistency.
Data-stream reconciliation across product type, application vertical, technology topology, and end-user intensity dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit evolution through the forecast period. Rare-earth magnet price indices and copper commodity cycles informed cost-side modeling, while EU regulatory enforcement timelines drove replacement cycle assumptions.
The model holds under stable EU Ecodesign Directive implementation and continued automotive electrification investment; deviation in critical raw materials trade policy or magnet supply disruption would shift synchronous motor penetration trajectories. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
North America Electric Motor Market
Electric Motor
Air Motor Market
Electric Motor
Automotive Power Steering Motor Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Global Motor Management Market
Electric Motor
High Speed Motor Market
Electric Motor
Europe Electric Motors for Electric Vehicle Market
Electric Motor
Automotive in-Wheel Motors Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
GCC Electric Motor Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
Intelligent Motor Controller Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Europe Electric Commercial Vehicle Battery Pack Market