
 Car Charger Market | 2026-2036
Car Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Car Charger Market Analysis
Silicon carbide is rebalancing power conversion economics in car charger designs by cutting thermal losses and shrinking inverter footprints. Tesla leverages its captive semiconductor sourcing to sustain cost advantages across its Supercharger network. ABB anchors industrial-grade reliability standards for DC fast charging hardware deployed at highway corridors and fleet depots.
A car charger is an electrical device that converts grid alternating current into direct current suitable for battery storage, typically operating at power levels from 1.4 kW in residential Level 1 units to 350 kW in commercial DC fast chargers with liquid-cooled cable assemblies. Its primary commercial purpose is to replenish electric vehicle battery capacity within time windows that match user dwell patterns. DC Fast Charger configurations command the dominant share of capital deployment as highway infrastructure and fleet operators prioritize throughput over unit economics. Wireless Charger installations represent the fastest-growing technology category despite higher per-port costs, driven by autonomous vehicle readiness and premium residential applications.
The US EPA tailpipe regulations and NHTSA fuel economy standards directly expand addressable demand by accelerating fleet turnover to electric platforms. EUs F-Gas Regulation and CE marking requirements shape cooling system design and refrigerant selection for thermal-managed charging hardware sold in member states. Stakeholders must monitor evolving interoperability mandates from ISO and IEC working groups that will determine connector compatibility and payment system access across national charging networks.
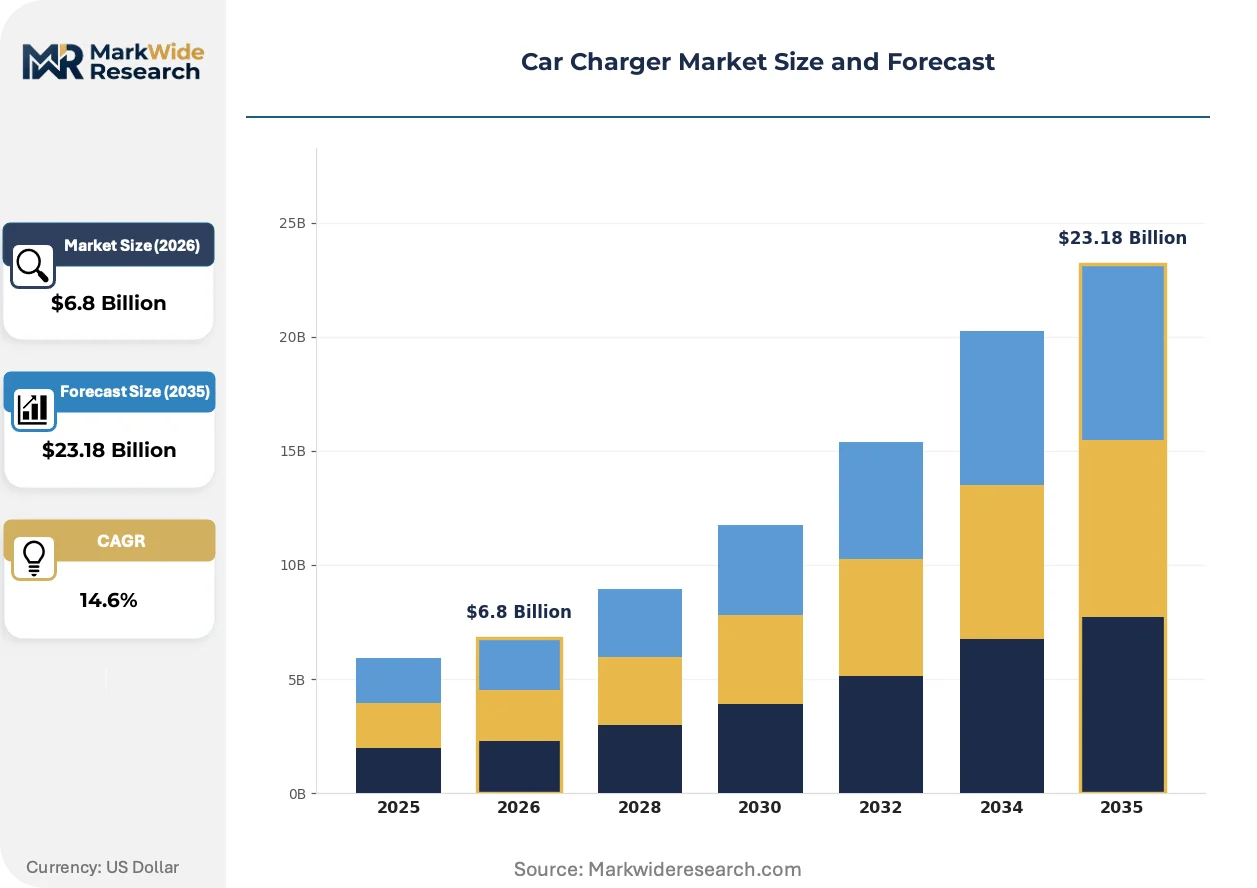
Market Dynamics
Silicon carbide power electronics and liquid-cooled cable architectures are compressing thermal management costs while enabling 350 kW throughput, fundamentally altering capital deployment economics for highway corridor infrastructure.
Growth Catalysts
- US EPA commercial vehicle emissions thresholds:Fleet operators across California, Texas, and Illinois are accelerating electrification timelines to preempt compliance deadlines, concentrating procurement orders for high-power DC hardware.
- Autonomous vehicle readiness protocols:Robotaxi developers in Arizona and Nevada require wireless inductive charging pads for hands-free energy replenishment during passenger turnover cycles.
- China's urban network densification:Municipal governments in Shanghai, Shenzhen, and Beijing mandate charging station ratios per 100 EVs, locking in deployment quotas for domestic suppliers.
Market Restraints
- Copper and rare earth magnet cost volatility:Liquid-cooled cable assemblies and permanent magnet motors face input price swings that compress hardware margins before long-term service contracts mature.
- Korean semiconductor foundry concentration:Silicon carbide wafer supply chains cluster among three fabrication facilities, creating single-source vulnerability for 800V architecture rollouts.
- EU F-Gas refrigerant phase-down:Thermal management systems using conventional coolants face redesign cycles and certification delays before CE marking approval.
Strategic Opportunities
- India's commercial fleet electrification:State transport utilities in Maharashtra, Karnataka, and Tamil Nadu issue tenders for depot-based fast charging without incumbent supplier lock-in.
- Vehicle-to-grid bidirectional standards:ISO 15118-20 protocol adoption enables residential chargers to sell stored capacity back to utilities, creating new revenue streams for hardware owners.
- Retail parking integration:Grocery and big-box chains in Florida and Georgia deploy Level 2 ports as dwell-time amenities, converting parking assets into captive energy retail.
Industry Challenges
- High-voltage electrical technician scarcity:Installation and maintenance of 480V three-phase infrastructure outpaces certified workforce supply in secondary US metro markets.
- Multi-protocol software stack complexity:Chargers must integrate OCPP, ISO 15118, and proprietary OEM APIs simultaneously, extending firmware validation timelines.
- Grid interconnection queue delays:Utility upgrade approvals for 1MW+ fleet depots stretch 18-24 months in constrained transmission zones, deferring revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Charger Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Charger, Level 2 Charger, DC Fast Charger, Wireless Charger Technology: Electric, Hybrid, Solar, Bi-directional End User: Residential, Commercial, Fleet, Public Charging Stations Installation Type: Pole-mounted, Wall-mounted, Portable, Built-in |
| Companies Covered | Tesla, ChargePoint, ABB, EVBox, Eaton, Wallbox, Delta Electronics, EVgo, Star Charge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Charger Market Emerging Trajectories
Power semiconductor architectures and autonomous vehicle infrastructure requirements are compressing charger form factors while expanding functional scope beyond simple energy transfer.
Silicon carbide MOSFETs replace silicon IGBTs in power conversion stages, cutting switching losses by two-thirds at 800V operating levels. Highway corridor operators and luxury automotive OEMs are adopting these devices for 350 kW+ installations. This semiconductor transition is converging with liquid-cooled cable designs to eliminate forced-air thermal management, shrinking enclosure volumes by forty percent and enabling sidewalk-integrated urban deployments.
The EU F-Gas Regulation mandates refrigerant phase-down schedules for cooling systems above 100 kW thermal load, forcing hardware redesigns toward CO2-based heat pumps. Industrial charger manufacturers serving German and French highway networks must recertify thermal architectures before 2027 deployment windows. Fleet depot operators in the Netherlands and Belgium are prioritizing hardware with pre-certified F-Gas-compliant cooling to avoid procurement delays.
Buyers now specify outcome-based availability contracts rather than capital equipment purchases, transferring uptime risk to charger manufacturers and network operators. Municipal procurement offices and corporate fleet managers in California and New York are leading this shift, replacing traditional CAPEX models with per-kWh service fees. This contracting evolution is most visible in school bus electrification programs, where districts lack technical staff to maintain high-voltage infrastructure internally.
Car Charger Market Segmentation
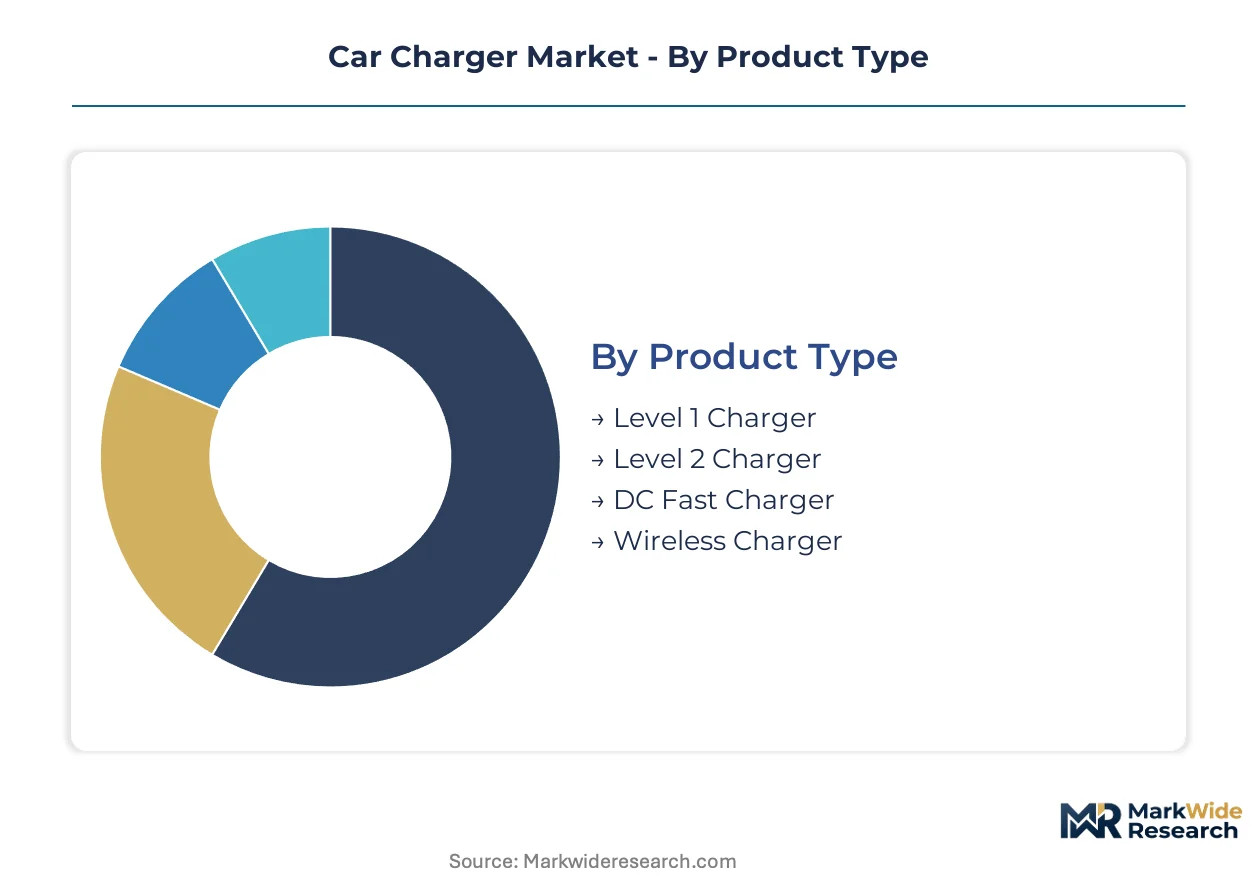
Car charger segmentation reveals how capital deployment, technical specifications, and installation constraints fragment procurement decisions across residential, commercial, and fleet applications. Understanding these divisions clarifies why hardware economics diverge sharply between overnight home charging and high-throughput highway infrastructure.
Product Type:
Capital intensity varies dramatically across power levels, with DC fast charging hardware requiring 50-100x the upfront investment of residential units.
- DC Fast Charger:Liquid-cooled cable assemblies and silicon carbide power electronics enable 350 kW throughput for highway corridor and fleet depot deployment. Fleet operators in California, Texas, and Illinois concentrate procurement here to meet EPA commercial vehicle compliance deadlines.
- Wireless Charger:Inductive pad systems eliminate connector wear and enable autonomous vehicle hands-free replenishment during passenger turnover cycles. Robotaxi developers in Arizona and Nevada are driving pilot installations despite 3-4x per-port cost premiums over conductive alternatives.
- Level 2 Charger:240V residential and workplace units balance installation simplicity with 6-8 hour full-charge cycles for daily commuting patterns.
- Level 1 Charger:Standard 120V outlet adapters deliver trickle charging for overnight residential use with minimal hardware cost.
DC Fast Charger hardware absorbs the bulk of installed capacity; Wireless Charger installations are expanding most quickly.
Technology:
Power conversion architectures determine thermal management requirements, semiconductor selection, and grid interconnection complexity.
- Electric:Grid-tied AC-to-DC conversion dominates volume, with silicon carbide MOSFETs displacing silicon IGBTs in new 800V architecture designs to cut switching losses by two-thirds.
- Bi-directional:ISO 15118-20 protocol enables vehicle-to-grid energy resale, creating hardware differentiation for residential chargers in deregulated electricity markets.
- Hybrid:Dual-source systems combine grid connection with on-site generation buffering for remote or backup-critical installations.
- Solar:DC-coupled photovoltaic integration bypasses grid conversion losses for off-grid and net-zero building applications.
Electric technology commands the dominant installed base; Bi-directional capability is gaining share fastest as utilities pilot distributed storage programs.
End User:
Customer type dictates pricing tolerance, service level requirements, and contract structure preferences.
- Fleet:Depot-based charging for buses, delivery vans, and heavy trucks requires 1MW+ grid connections and outcome-based availability contracts. State transport utilities in Maharashtra, Karnataka, and Tamil Nadu issue tenders without incumbent supplier lock-in.
- Public Charging Stations:Highway corridor and urban network operators prioritize 24/7 uptime and multi-protocol software stacks integrating OCPP, ISO 15118, and proprietary OEM APIs.
- Commercial:Retail parking integration at grocery and big-box chains converts dwell-time into captive energy retail across Florida and Georgia.
- Residential:Single-family and multi-unit dwelling installations focus on overnight charging convenience and bidirectional grid services.
Fleet applications absorb the dominant share of high-power hardware investment; Public Charging Stations are scaling fastest as municipal governments mandate network densification ratios.
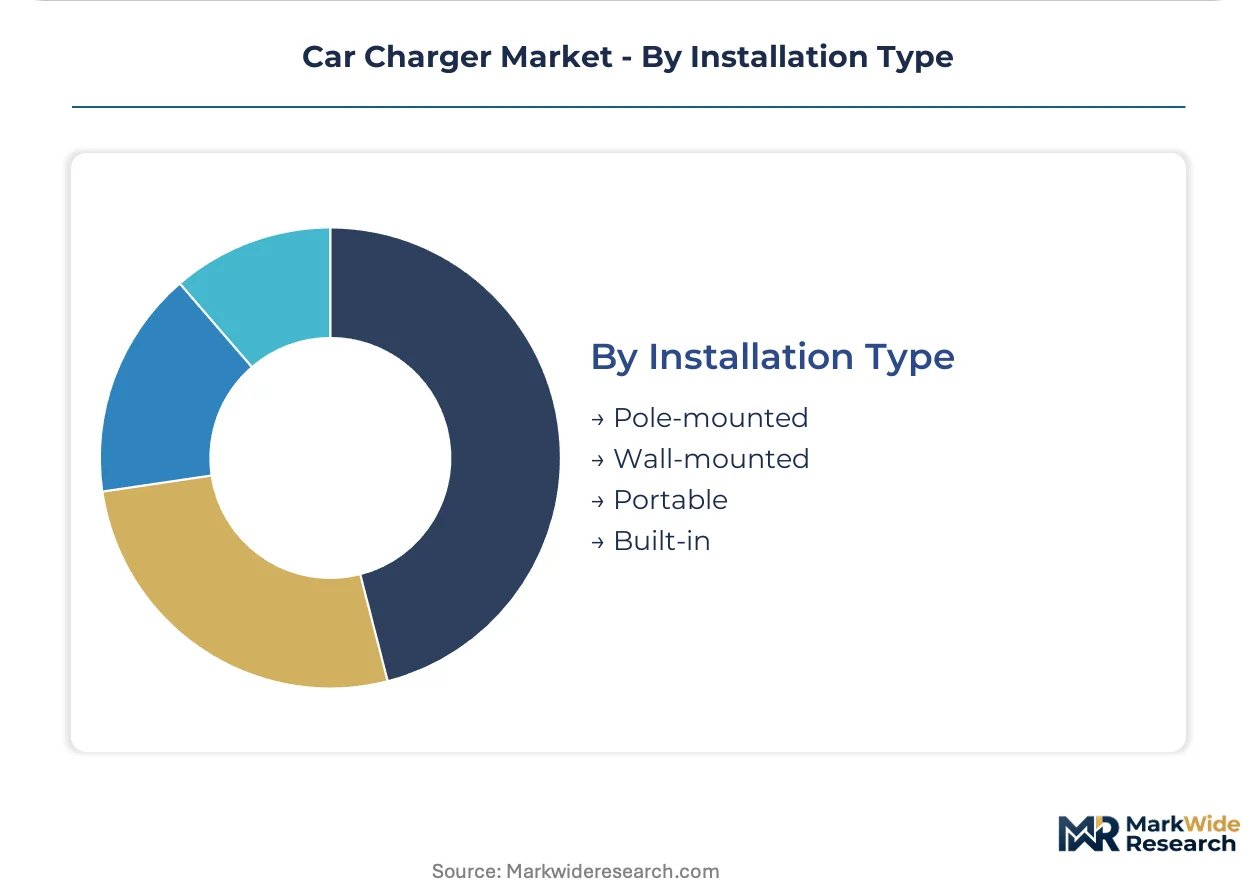
Installation Type:
Mounting configuration determines site preparation costs, electrical permitting complexity, and relocation flexibility.
- Wall-mounted:Bracket-fixed units dominate residential garages and commercial parking structures with existing 240V infrastructure.
- Pole-mounted:Curb-side deployment enables sidewalk-integrated urban charging without garage access requirements.
- Built-in:OEM-integrated vehicle charging systems eliminate external hardware but lock owners into manufacturer service networks.
- Portable:Mobile 120V/240V units provide emergency backup and travel flexibility with reduced power output.
Wall-mounted hardware retains the largest installed footprint; Pole-mounted systems are climbing fastest as cities prioritize curbside accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates over half of global EV charging hardware deployment, driven by municipal mandates for urban network density. Fleet electrification in the United States and depot infrastructure buildout across India are accelerating procurement timelines. European highway corridor operators face simultaneous pressure from F-Gas refrigerant rules and ISO interoperability mandates.
China
Shanghai, Shenzhen, and Beijing enforce charging station ratios per 100 EVs that lock in deployment quotas for domestic suppliers. MIIT's GB standards for connector compatibility and grid interconnection shape hardware certification requirements. Star Charge anchors high-density urban networks in the Yangtze River Delta while provincial state-grid subsidiaries expand coverage into western provinces.
United States
Fleet operators in California, Texas, and Illinois concentrate procurement orders for 350 kW DC hardware to meet EPA commercial vehicle emissions thresholds. NHTSA fuel economy standards and IRA tax credits accelerate turnover timelines for depot-based charging. Tesla's Supercharger network spans highway corridors with proprietary connector architectures that now face federal interoperability mandates.
Germany
Autobahn corridor operators prioritize industrial-grade reliability standards for DC fast charging hardware serving long-haul freight electrification. EU F-Gas Regulation phase-down schedules force thermal management redesigns toward CO2-based heat pumps before 2027 deployment windows. ABB anchors charging infrastructure across Bavaria and Baden-Württemberg with hardware certified for CE marking and KBA vehicle-type approval alignment.
India
State transport utilities in Maharashtra, Karnataka, and Tamil Nadu issue tenders for depot-based fast charging without incumbent supplier lock-in. CEA grid codes and BIS electrical safety standards govern 1MW+ fleet depot interconnections. Bangalore and Chennai industrial clusters host emerging domestic assembly operations for power conversion modules and liquid-cooled cable assemblies.
Netherlands
Fleet depot operators in Rotterdam and Amsterdam prioritize F-Gas-compliant cooling systems to preempt procurement delays under EU refrigerant phase-down mandates. CE marking requirements and ISO 15118-20 protocol adoption enable bidirectional vehicle-to-grid pilot programs. EVBox exemplifies local hardware specialization with charging infrastructure deployed across Randstad urban networks and North Sea port corridors.
Car Charger Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive automotive OEM networks and independent hardware providers competing for highway corridor and fleet depot deployment. The vendor base concentrates among three strategic tiers: integrated energy companies with captive semiconductor sourcing, industrial electrical specialists with certified thermal management expertise, and regional network operators with municipal procurement relationships. Competitive moves center on silicon carbide supply chain security and outcome-based service contracting that transfers uptime risk from fleet operators to equipment providers.
Within the integrated energy tier, Tesla exemplifies captive semiconductor sourcing and proprietary connector architectures that sustain cost advantages across Supercharger networks. Among industrial electrical specialists, ABB occupies a position representing industrial-grade reliability standards for DC fast charging hardware. Star Charge anchors the regional network operator archetype with deployment concentration in Chinese municipal mandates. These three patterns—captive supply chains, certified industrial reliability, and quota-locked domestic deployment—represent the dominant competitive positions shaping procurement decisions across highway, fleet, and urban charging applications.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| EVBox |
| Eaton |
| Wallbox |
| Delta Electronics |
| EVgo |
| Star Charge |
| Others |
Supply Flow & Price Mechanics
Certified high-voltage electrical technician scarcity in secondary US metro markets widens labor-cost differentials between premium 350 kW DC installations and economy-grade Level 2 residential units. This workforce concentration compresses margins on complex highway corridor deployments while sustaining pricing power for standardized home charging hardware.
Pricing Analysis
Volume concentration in residential Level 2 units sustains thinner margins than project-based DC fast charging deployments where outcome-based availability contracts transfer uptime risk to manufacturers. Price differentiation hinges on silicon carbide certification tier and liquid-cooled cable assembly grade, with fleet operators in California and Texas showing lowest sensitivity due to EPA compliance deadlines. Cost compression in mid-power commercial segments intensifies as retail parking integrators in Florida and Georgia prioritize dwell-time amenity economics over performance specifications.
Supply Chain Analysis
Ocean freight cost volatility from Korean semiconductor foundries to North American assembly plants elevates landed costs for 800V architecture power modules. Silicon carbide wafer supply draws from facilities in South Korea, Japan, and the United States, with rare earth magnet and copper cable assemblies sourcing from Chinese and Chilean extraction operations. Single-source vulnerability in wafer fabrication creates procurement risk for tier-one hardware manufacturers. Distribution runs through certified electrical distributors and direct OEM channel partnerships to fleet operators and municipal procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car charger market sits in a semiconductor-transition phase where silicon carbide MOSFETs displace legacy silicon IGBTs, compressing thermal management costs and reshaping competitive economics across power conversion tiers.
For Market Incumbents: Deploy captive semiconductor sourcing to secure wafer allocation from Korean and Japanese foundries before 800V architecture demand accelerates. Consolidate service network density in California, Texas, and Illinois to capture fleet electrification procurement tied to EPA commercial vehicle thresholds. Deepen backward integration into liquid-cooled cable assembly production to defend margins against copper price volatility. For New Entrants and Emerging Players: Bidirectional vehicle-to-grid certification gaps in deregulated electricity markets offer technology-first entry points for residential hardware specialists. Target India's state transport utilities in Maharashtra and Tamil Nadu where tender processes lack incumbent supplier lock-in. Pursue outcome-based service contracting models that transfer uptime risk from school bus electrification programs to equipment providers. For Investors and Strategic Acquirers: Re-rating potential sits with industrial electrical specialists possessing pre-certified F-Gas-compliant thermal management given EU refrigerant phase-down deadlines. Long-term viability over the next decade favors vendors with silicon carbide supply chain security and municipal procurement relationships in Chinese urban network densification programs. Monitor ISO 15118-20 protocol adoption rates as the signal for bidirectional charging infrastructure inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Security | Captive wafer sourcing from Korean foundries sustains cost advantages in 350 kW highway deployments. |
| F-Gas Compliance Certification | CO2-based heat pump thermal systems unlock German and French highway corridor procurement before regulatory deadlines. |
| Outcome-Based Service Contracting | Per-kWh availability models transfer uptime risk from California fleet operators to equipment manufacturers. |
| Bidirectional Protocol Integration | ISO 15118-20 compatibility enables residential vehicle-to-grid revenue streams in deregulated US electricity markets. |
| Municipal Quota Lock-In | Domestic supplier relationships with Shanghai and Beijing authorities secure deployment mandates under MIIT GB standards. |
Methodological Framework
Independent corroboration across fleet procurement officers, high-voltage electrical contractors, and silicon carbide semiconductor specialists underwrites the qualitative findings in this study. Primary interviews with utility interconnection planners, OEM platform engineers, and municipal transportation authorities combined with secondary validation from EPA regulatory filings, NHTSA fuel economy databases, and MIIT GB standard documentation. Bottom-up installation forecasts and top-down infrastructure investment triangulation anchored market sizing across power level, technology, and end-use segments.
Comparable historical deployment patterns from early highway corridor buildouts informed the projection horizon for fleet depot and urban network densification scenarios. The analytical framework modeled charger segmentation by power level, semiconductor architecture, cooling system type, and regional regulatory cluster, with CAGRs derived from utility interconnection queue data and municipal procurement timelines. Forecast inputs incorporated silicon carbide adoption curves and F-Gas refrigerant phase-down schedules affecting thermal management hardware certification cycles.
Several conditions sit outside the modeled scope, including unannounced EPA emissions threshold revisions, Korean foundry expansion timelines, and autonomous vehicle readiness protocol standardization. Forecasts reflect assumptions about grid interconnection approval durations and copper price stability that stakeholder due diligence should verify against specific operating contexts. Stakeholders should weight assumptions against their own procurement timelines and regional workforce availability constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Smart E-Drive Market
Electric Motor
EV Traction Motor Control Unit Market
Electric Motor
Torque Motor Market
Electric Motor
UK Solar E-Bike Market
Electric Motor
North America Electric Motor Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Electric Motor Sales Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Electric Motorcycle Market
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
Traction Motor Core Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Large Synchronous Motor Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Europe Electric Motor Market