
 Motorcycle Lead Acid Battery Market | 2026-2036
Motorcycle Lead Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Lead Acid Battery Market Outlook
ISO 9001 quality management certification is collapsing as a baseline qualifier for OEM supply contracts, forcing smaller foundries toward aftermarket channels. GS Yuasa Corporation leverages its Japanese manufacturing heritage to dominate premium AGM supply for high-displacement motorcycles. Exide Industries Ltd. anchors its position through backward integration into lead smelting and extensive Indian distribution. Clarios sustains technology leadership through advanced grid alloys that extend cycle life in stop-start applications.
A motorcycle lead acid battery is an electrochemical storage device employing lead dioxide positive plates, sponge lead negative plates, and sulfuric acid electrolyte, typically rated between 12V and 14Ah for standard motorcycle applications, designed to deliver high cold-cranking amperage for internal combustion engine starting and stable voltage for lighting systems. AGM product types command premium positioning due to spill-proof construction and vibration resistance demanded by sport and adventure motorcycle segments. Aftermarket providers represent the fastest-growing end-user channel as digital platforms displace traditional brick-and-mortar battery retail. Conventional flooded batteries retain volume dominance in price-sensitive scooter markets across South Asia and Latin America, though margin pools have shifted toward gel and maintenance-free installation categories.
India's BIS mandates and China's GB standards collectively govern product safety, lead content limits, and recycling chain accountability across the two largest production bases. EPA regulations in the United States enforce closed-loop recycling and cradle-to-cradle lead stewardship that elevates compliance costs for non-integrated manufacturers. ECHA's REACH framework in Europe restricts hazardous substance thresholds, effectively filtering import eligibility for Asian producers. Stakeholders must monitor how lithium-ion substitution timelines in electric two-wheelers reshape lead acid replacement demand and inventory planning across dual supply chains.
Market Dynamics
Lead smelter consolidation across China and India is compressing raw material access for non-integrated battery assemblers, forcing margin erosion and channel migration toward captive recycling networks.
Growth Catalysts
- Stop-start motorcycle proliferation:Dual-battery architectures for micro-hybrid powertrains in European and Japanese models are expanding AGM specification rates.
- BIS certification tightening:India's Bureau of Indian Standards mandates for lead purity and cycle-life testing are filtering substandard imports and elevating replacement quality thresholds.
- Ride-hailing fleet density:Indonesian and Vietnamese urban mobility platforms are compressing replacement cycles through high-utilization scheduling, accelerating aftermarket throughput.
Market Restraints
- Lead price volatility:LME lead contract fluctuations directly transmit to cell-level manufacturing costs, squeezing margin for toll-assemblers without smelter ownership.
- Lithium-ion substitution trajectory:Electric two-wheeler platforms in China and Europe are displacing starter battery demand in new vehicle categories.
- REACH compliance burden:ECHA substance restrictions elevate testing and documentation costs for Asian exporters serving European aftermarket channels.
Strategic Opportunities
- Digital aftermarket platforms:E-commerce battery retail in Southeast Asian urban corridors is disintermediating traditional distributor networks and capturing margin compression.
- Closed-loop recycling mandates:EPA cradle-to-cradle stewardship requirements in the United States favor integrated producers with captive smelter capacity.
- Gel battery penetration:Deep-cycle applications in adventure touring motorcycles present premium positioning above conventional flooded units.
Industry Challenges
- Grid alloy formulation expertise:Advanced calcium-tin additive chemistry for extended cycle life requires metallurgical capabilities scarce outside integrated R&D facilities.
- Dual supply chain complexity:Inventory planners must simultaneously service lead acid replacement demand and lithium-ion new-vehicle platforms without cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Lead Acid Battery Market |
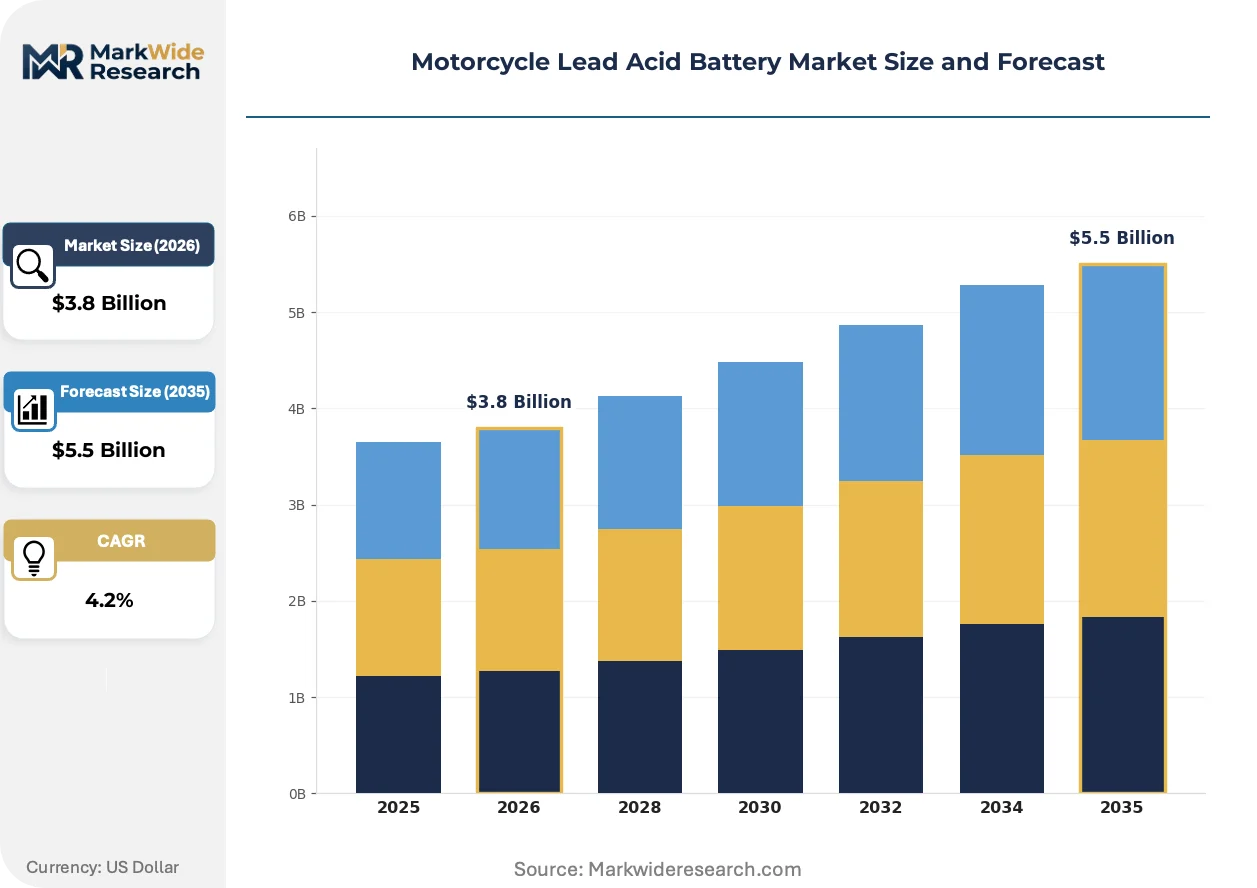
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, AGM, Gel, Lithium Application: Motorcycles, Scooters, ATVs, Electric Bikes End User: OEMs, Aftermarket Providers, Retailers, Online Stores Installation: Direct Replacement, Maintenance-Free, Seasonal Use, Custom Fit |
| Companies Covered | GS Yuasa Corporation, Exide Industries Ltd., Clarios, Amara Raja Batteries Ltd., Camel Group Co., Ltd., Leoch International Technology, Hitachi Chemical Energy Technology, OKAYA Power Pvt Ltd., Yuasa Battery, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Lead Acid Battery Market Strategic Shifts
Electrification timelines are bifurcating the motorcycle powertrain landscape, forcing lead acid producers to defend replacement-cycle revenue while lithium-ion captures new-vehicle specification.
Absorbed Glass Mat construction is miniaturizing cell packaging for high-displacement sport motorcycles, enabling frame-integrated battery placement previously impossible with flooded designs. Japanese and Italian premium manufacturers are specifying AGM for vibration-intensive adventure categories. This architecture is miniaturizing installation footprints and compressing traditional battery tray dimensions across new model development.
EPA closed-loop recycling enforcement is tightening lead stewardship documentation for United States aftermarket distribution, elevating compliance costs for non-integrated importers. The regulation forces cradle-to-grave tracking through smelter verification. Independent distributors are consolidating toward supplier networks with certified recycling partnerships.
Fleet procurement centralization among Indonesian and Vietnamese ride-hailing operators is displacing individual rider replacement behavior with contracted volume agreements. Platform procurement teams negotiate direct manufacturer relationships, bypassing traditional retail channels. This concentration is most visible in Jakarta and Ho Chi Minh City service corridors where vehicle utilization rates exceed 200 kilometers daily.
Motorcycle Lead Acid Battery Market Segmentation
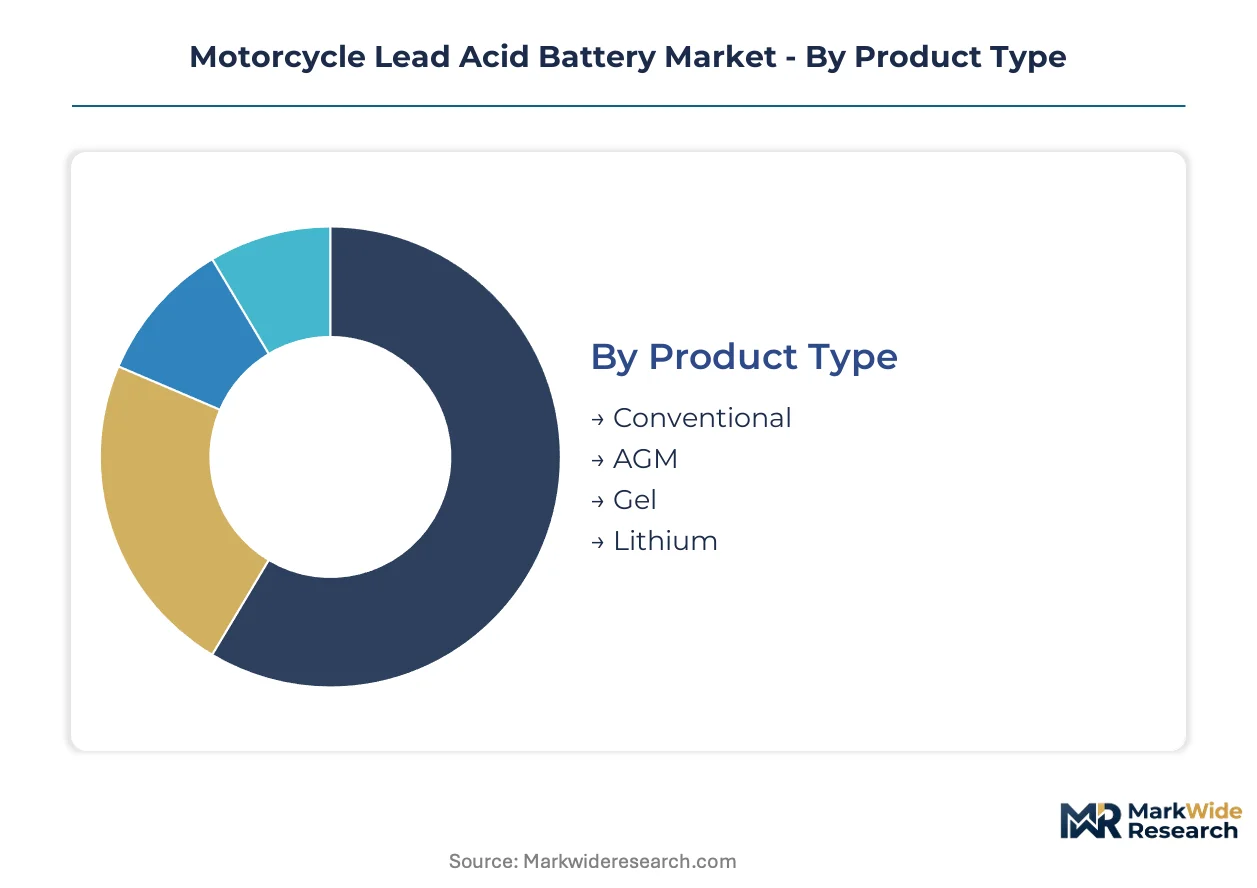
Motorcycle lead acid battery segmentation reflects divergent supply chain architectures across product technologies and channel structures. Product type and application dimensions reveal distinct geographic concentration patterns that shape procurement strategies for integrated versus non-integrated manufacturers.
Product Type:
Conventional flooded batteries dominate domestic production bases in India and Indonesia, while AGM and gel variants flow through export-oriented manufacturing corridors serving premium motorcycle assembly in Japan and Italy.
- Conventional:Flooded lead acid construction with removable cell caps for electrolyte maintenance. Demand concentrates in India's scooter service corridors and Indonesian ride-hailing fleets where unit economics prioritize acquisition cost over cycle life. BIS certification tightening is elevating quality thresholds for domestic suppliers.
- AGM:Absorbed Glass Mat construction immobilizes electrolyte in fiberglass separators, enabling spill-proof operation and frame-integrated mounting. Japanese and Italian premium manufacturers specify AGM for adventure touring categories where vibration resistance commands specification priority. Stop-start motorcycle proliferation in European markets is accelerating dual-battery architecture adoption.
- Gel:Silica-thickened electrolyte provides deep-cycle durability for touring motorcycles with auxiliary electrical loads. German and Austrian alpine touring segments specify gel for cold-weather reliability.
- Lithium:Lithium iron phosphate chemistry displaces lead acid in high-performance electric two-wheeler platforms, though lead acid retains cost advantage in internal combustion starter applications.
Conventional flooded batteries command the established base across South Asian price-sensitive markets. The steepest expansion runs through AGM specification for premium displacement categories and micro-hybrid powertrains.
Application:
Volume distribution across application segments correlates with vehicle utilization intensity and replacement cycle compression, with fleet-operated categories driving aftermarket throughput.
- Motorcycles:Internal combustion engines from 125cc to 1000cc displacement require high cold-cranking amperage for starting reliability. Indonesian and Vietnamese urban mobility platforms compress replacement cycles through intensive daily utilization exceeding 200 kilometers.
- Scooters:Automatic transmission vehicles dominate Indian and Southeast Asian urban commuting. Conventional flooded batteries retain volume dominance due to price sensitivity, though margin pools are shifting toward maintenance-free installation categories.
- ATVs:All-terrain vehicles in North American recreational and agricultural applications demand vibration-resistant construction. Seasonal use patterns create distinct replacement seasonality versus year-round motorcycle operation.
- Electric Bikes:Two-wheeled electric platforms in China and Europe are bifurcating the powertrain landscape, with lithium-ion capturing new-vehicle specification while lead acid defends replacement-cycle revenue in legacy internal combustion fleets.
Scooters anchor volume concentration across South Asian domestic markets. Motorcycles generate the premium margin expansion through fleet procurement centralization and stop-start technology adoption.
End User:
Channel structure divergence between OEM specification and aftermarket replacement creates distinct customer relationship requirements, with digital platforms disrupting traditional distributor economics.
- OEMs:Original equipment manufacturers in Japan, Italy, and India specify battery chemistry during vehicle development, with AGM penetration rising for premium displacement categories. ISO 9001 certification has collapsed as a baseline qualifier, forcing smaller foundries toward aftermarket channels.
- Aftermarket Providers:Independent service networks and battery specialists represent the fastest-growing channel as digital platforms displace traditional brick-and-mortar retail. Southeast Asian urban corridors are consolidating toward direct manufacturer relationships.
- Retailers:Traditional distributor networks in India and Indonesia maintain geographic coverage advantages in secondary cities, though margin compression is accelerating consolidation.
- Online Stores:E-commerce battery retail is disintermediating distributor networks in Jakarta, Ho Chi Minh City, and Bangkok service corridors, capturing margin compression through platform procurement centralization.
Aftermarket providers are gaining share fastest through digital platform expansion. OEM specification remains the margin defense priority for integrated manufacturers with captive smelter capacity.
Installation:
Installation category segmentation reflects technician labor economics and rider self-service capability, with maintenance-free positioning commanding premium pricing.
- Direct Replacement:Like-for-like battery swaps in existing tray configurations dominate independent service channel volume. Indian and Indonesian roadside mechanics execute the majority of direct replacements within 15-minute service windows.
- Maintenance-Free:Sealed construction eliminates electrolyte checking, appealing to urban riders without technical inclination or tool access. This category captures premium positioning above conventional flooded units in Southeast Asian aftermarket channels.
- Seasonal Use:Battery tender compatibility and cold-weather starting reliability for North American and European recreational vehicles with intermittent operation patterns.
- Custom Fit:Frame-integrated and non-standard tray configurations for adventure touring and custom motorcycle builds requiring dimensional adaptation.
Direct replacement anchors volume throughput across established service networks. Maintenance-free installation is climbing the fastest as urban rider demographics shift toward convenience-oriented service preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and ride-hailing platforms concentrate replacement demand in Southeast Asian urban corridors, while OEM specification gravitates toward Japanese and Italian premium motorcycle assembly. India's regulatory tightening filters supplier qualification, and North American aftermarket channels face elevated recycling compliance.
Indonesia
Jakarta's ride-hailing fleet density exceeds 200 kilometers daily utilization, compressing battery replacement cycles for Gojek and Grab-operated motorcycles. The country's Ministry of Industry enforces SNI certification for automotive battery safety and lead content limits. Surabaya and Bandung service corridors are consolidating procurement toward direct manufacturer relationships, bypassing traditional distributor networks.
India
Scooter-dominated urban commuting across Mumbai, Delhi, and Bangalore sustains conventional flooded battery volume, though margin pools shift toward maintenance-free categories. BIS mandates for lead purity and cycle-life testing are filtering substandard imports and reshaping supplier qualification. Tamil Nadu and Gujarat manufacturing clusters anchor domestic production for Exide Industries and Amara Raja supply.
Vietnam
Ho Chi Minh City and Hanoi mobility platforms replicate Indonesian fleet centralization, with contracted volume agreements displacing individual rider replacement behavior. The country's national technical standards regulator enforces battery safety protocols aligned with ASEAN harmonization frameworks. Northern industrial zones around Hai Phong concentrate toll-assembly operations for regional export.
Japan
Stop-start motorcycle proliferation in European and domestic markets drives AGM specification for dual-battery micro-hybrid architectures. METI oversees JIS standards for vibration resistance and cycle-life performance in premium displacement categories. Japanese manufacturing heritage anchors GS Yuasa's supply position for adventure touring segments requiring spill-proof construction.
United States
ATV and recreational motorcycle seasonal use patterns create distinct replacement seasonality versus year-round fleet operation. EPA closed-loop recycling enforcement mandates cradle-to-grave lead stewardship documentation, elevating compliance costs for non-integrated importers. Independent distributors consolidate toward supplier networks with certified smelter partnerships across Midwest and Southeast service territories.
Motorcycle Lead Acid Battery Market Competitive Environment
Player mix skews toward integrated manufacturers with captive lead smelting capacity and toll-assemblers dependent on external raw material access. Japanese and Indian producers anchor the premium AGM and conventional flooded tiers respectively. Three archetypes dominate: vertically integrated majors controlling recycling networks, regional specialists serving captive geographies, and toll-assemblers facing margin compression from lead price volatility. Competitive moves center on backward integration into smelting capacity and digital platform partnerships for aftermarket channel disintermediation.
Among Japanese producers, GS Yuasa Corporation exemplifies heritage-based positioning in premium AGM supply. Indian integrated manufacturers Exide Industries Ltd. and Amara Raja Batteries Ltd. occupy positions anchored by domestic distribution density and regulatory compliance capability. These three represent the structural divide between export-oriented premium specification and volume-driven emerging market replacement cycles.
| Leading Market Players |
|---|
| GS Yuasa Corporation |
| Exide Industries Ltd. |
| Clarios |
| Amara Raja Batteries Ltd. |
| Camel Group Co., Ltd. |
| Leoch International Technology |
| Hitachi Chemical Energy Technology |
| OKAYA Power Pvt Ltd. |
| Yuasa Battery, Inc. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Indian and Chinese lead smelters creates asymmetric pricing power, compressing cell-level margins for toll-assemblers while integrated manufacturers capture cost floors through captive recycling networks. This scale concentration shapes both procurement hierarchies and price resistance thresholds across Southeast Asian aftermarket channels.
Pricing Analysis
Cost-plus contracts with LME lead indexation dominate raw material pass-through structures, though finished battery pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. AGM variants command positioning above conventional flooded units due to BIS compliance costs and spill-proof construction premiums. Price erosion runs through non-integrated toll-assemblers facing lead price volatility without smelter ownership. Ride-hailing fleet operators exhibit lowest price sensitivity due to replacement cycle reliability premiums, while individual scooter riders in South Asian secondary cities drive volume at cost-optimized tiers.
Supply Chain Analysis
Inventory lead times stretch 6-8 weeks for non-integrated assemblers sourcing lead from external smelters, compressing working capital efficiency versus vertically integrated competitors. Manufacturing gravity centers on India, China, and Indonesia, with raw material feeds drawing from domestic lead smelting and imported concentrate. Supply chain risk concentrates in single-source vulnerability for advanced calcium-tin grid alloys requiring metallurgical capabilities scarce outside integrated R&D facilities. Distribution runs through traditional distributor networks in Indian and Indonesian secondary cities, though digital platforms are disintermediating these channels in Jakarta, Ho Chi Minh City, and Bangkok urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates white-space opportunities as electrification bifurcation splits procurement teams between lead acid replacement cycles and lithium-ion new-vehicle platforms, generating niche specialization potential for agile suppliers.
For Market Incumbents: Consolidate smelter capacity through backward integration into lead recycling to defend margin compression from LME volatility. Lock in direct procurement relationships with Indonesian and Vietnamese ride-hailing platforms before fleet centralization completes. Prioritize BIS and SNI certification maintenance as regulatory tightening filters supplier qualification.
For New Entrants and Emerging Players: Anchor in maintenance-free installation categories where urban rider demographics shift toward convenience-oriented service preferences. Target gel battery penetration for German and Austrian alpine touring segments where deep-cycle durability commands specification priority. Pursue digital platform partnerships for aftermarket channel disintermediation in Southeast Asian urban corridors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated manufacturers with captive smelter capacity and certified recycling partnerships serving EPA-regulated North American aftermarket channels. Long-term viability hinges on dual-supply-chain capability without cross-contamination between lead acid and lithium-ion inventory streams. Monitor lithium-ion substitution velocity in Chinese electric two-wheeler platforms as the critical inflection signal for lead acid replacement demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Smelting | Captive recycling capacity insulates margins from LME volatility and satisfies EPA cradle-to-grave stewardship mandates. |
| Digital Platform Partnership | E-commerce battery retail disintermediates traditional distributor networks and captures margin compression in Jakarta and Ho Chi Minh City. |
| AGM Specification Expansion | Stop-start motorcycle proliferation in European and Japanese markets drives dual-battery architecture adoption. |
| BIS Certification Investment | Lead purity and cycle-life testing compliance filters substandard imports and elevates replacement quality thresholds in India. |
| Fleet Procurement Centralization | Direct manufacturer relationships with Gojek and Grab operators bypass traditional retail channels and compress replacement cycles. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with battery manufacturing executives, aftermarket distribution managers, ride-hailing fleet procurement officers, and lead smelter operations directors; and secondary validation through BIS certification registries, SNI automotive battery safety filings, EPA closed-loop recycling enforcement records, and ASEAN trade flow databases. Bottom-up cell-level production estimates triangulated against top-down replacement cycle modeling across vehicle utilization intensity tiers.
Across the analysis window, forecasts incorporated product type segmentation by construction technology, application segmentation by vehicle displacement and utilization pattern, end-user channel structure, and installation category by service complexity. CAGRs derived from replacement cycle compression rates in fleet-operated categories and stop-start technology penetration curves in premium displacement segments. Lead price volatility bands and lithium-ion substitution trajectory scenarios framed sensitivity analysis.
Material uncertainties — lithium-ion cost parity acceleration, regulatory tightening velocity in India and Indonesia, and ride-hailing platform consolidation patterns — sit outside the modeled envelope. Forecasts reflect documented assumptions about fleet utilization rates and stop-start specification adoption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Motors for IC Engine Vehicle Market
Electric Motor
Automotive Induction Motors Market
Electric Motor
Air Motor Market
Electric Motor
Motorcycle Battery Market
Electric Motor
Intelligent Motor Control Center Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
Electric AC Motors Market
Electric Motor
Automotive Power Steering Motor Market
Electric Motor
Global EV Motor Controller Market
Electric Motor
EV Traction Motor Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Global Two Wheeler Hub Motor Market
Electric Motor
Traction Motor Core Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Global Automotive Starter Motor Market