
 Europe Automated Guided Vehicle (AGV) Market | 2026-2036
Europe Automated Guided Vehicle (AGV) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automated Guided Vehicle (AGV) Market Foresight
CE marking under the EU Machinery Directive is collapsing the field of qualified AGV suppliers across Europe. Toyota Material Handling Europe AB leverages its established dealer network to dominate aftermarket service coverage. Swisslog Holding AG specializes in integrating AGV fleets with warehouse management software for pharmaceutical distribution centers. KION Group AG anchors its position through captive production of lithium-ion battery packs for extended fleet uptime.
An automated guided vehicle is a mobile robot that follows markers or wires in the floor, or uses vision, magnets, or lasers for navigation, typically operating at speeds up to 2 meters per second with payload capacities ranging from 500 kilograms to over 50 tons for heavy industrial applications. These systems execute material transport, picking, and staging tasks without human drivers, reducing labor costs and collision incidents in high-throughput facilities. Unit load vehicles lead the product type category due to their versatility in moving standardized totes and cartons across automotive and electronics assembly lines. Lidar technology is displacing magnetic tape guidance in new installations as warehouses demand flexible route reconfiguration without floor infrastructure changes.
The EU Machinery Directive, CE marking requirements, and national workplace safety regulations enforced by Germany's KBA and France's labor inspectorate shape AGV design standards, mandating protective fields, emergency stop systems, and human-robot collaboration protocols. REACH compliance for battery chemistries and the EU Green Deal's decarbonization targets are pushing manufacturers toward energy recovery systems and recyclable powertrain components. Buyers must evaluate vendor certification depth against upcoming EU AI Act provisions that will classify autonomous navigation algorithms as high-risk systems requiring conformity assessments.
Market Dynamics
Lidar-based navigation is supplanting magnetic tape guidance across European warehousing, forcing incumbent suppliers to re-certify fleets under evolving CE marking protocols while buyers demand route flexibility without floor infrastructure investments.
Growth Catalysts
- EU Machinery Directive compliance mandates:Warehouse operators in Germany face enforced deadlines for protective field systems and emergency stop protocols, accelerating fleet replacement cycles.
- Lithium-ion battery chemistry advances:Extended operational uptime between charges enables three-shift deployment in pharmaceutical distribution centers previously limited to two-shift coverage.
- E-commerce fulfillment network densification:Automated warehousing deployments across the Netherlands and Belgium are absorbing unit load vehicles for same-day delivery staging.
Market Restraints
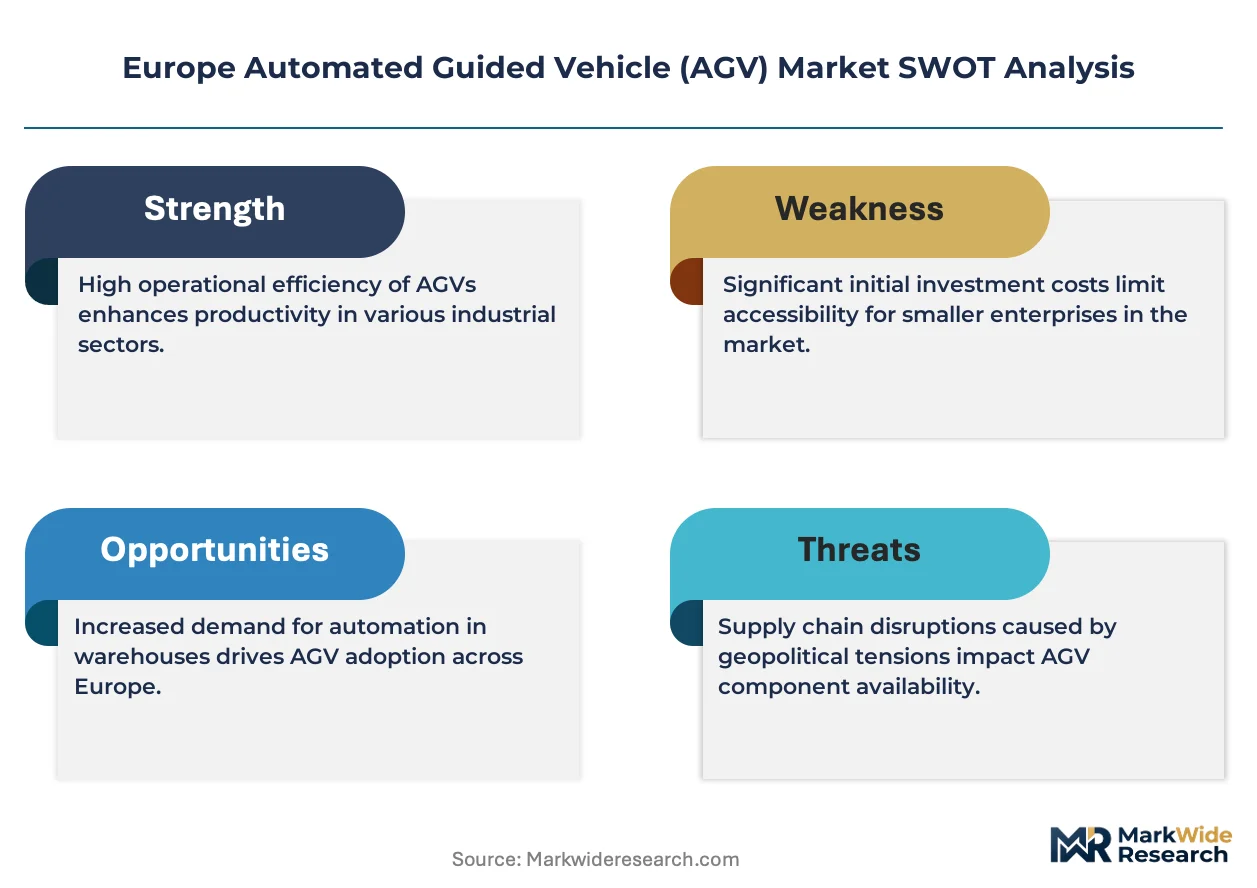
- CE marking certification timelines:Conformity assessment bottlenecks at notified bodies extend product launch windows by eight to fourteen months for navigation algorithm updates.
- Battery raw material concentration:Lithium and cobalt supply chains anchored in non-European processing facilities expose fleet operators to price volatility and forced labor scrutiny.
- Qualified systems integrator scarcity:The field of engineers capable of WMS-AGV synchronization for multi-vendor environments remains concentrated in Southern Germany and Northern Italy.
Strategic Opportunities
- Polish and Romanian manufacturing clusters:Greenfield automotive assembly plants in these markets remain underpenetrated by automated intralogistics relative to Western European benchmarks.
- EU AI Act high-risk system classification:Autonomous navigation algorithms face impending conformity assessments, creating first-mover advantage for vendors with pre-certified algorithmic transparency documentation.
- Swiss pharmaceutical cold chain integration:Temperature-controlled AGV fleets for vaccine distribution represent an emerging application with distinct certification requirements from standard warehousing.
Industry Challenges
- Multi-vendor fleet orchestration:Warehouse operators struggle to synchronize navigation protocols across equipment from different suppliers within shared aisle networks.
- Functional safety engineer recruitment:The pool of professionals qualified to validate PL-d and PL-e safety systems under ISO 13849 remains shallow relative to deployment demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automated Guided Vehicle (AGV) Market |
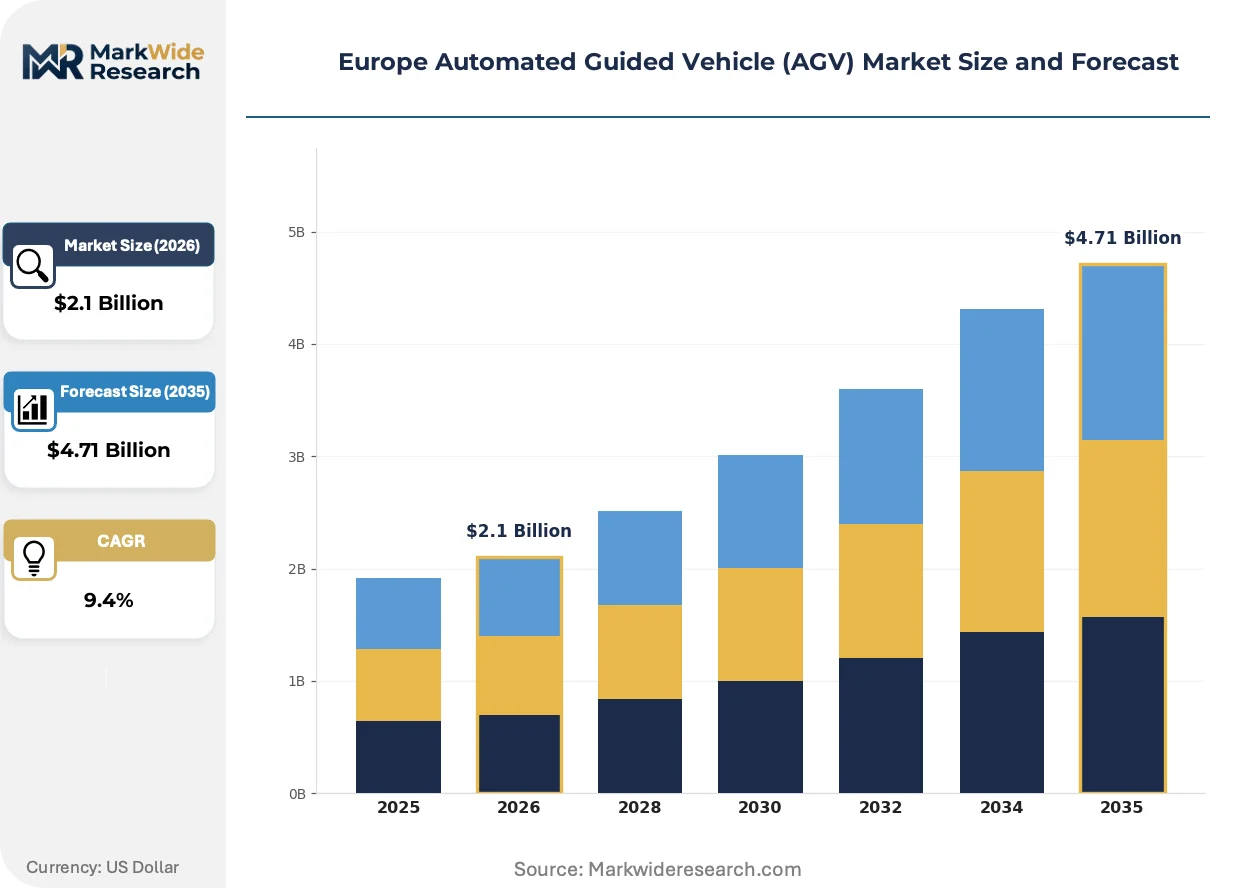
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unit Load, Tow, Pallet, Hybrid Technology: Lidar, Magnetic, Vision Guidance, Laser Navigation End User: Manufacturing, Retail, Logistics, Food & Beverage Deployment: Indoor, Outdoor, Automated Warehousing, Hospital |
| Companies Covered | Toyota Material Handling Europe AB, Swisslog Holding AG, KION Group AG, Linde Material Handling GmbH, SSI SCHAEFER, KUKA AG, Jungheinrich AG, STILL GmbH, Daifuku Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automated Guided Vehicle (AGV) Market Shifts & Advancements
Navigation autonomy, energy density improvements, and procurement model restructuring are converging to redefine competitive advantage in European material handling. These shifts favor vendors with verticalized software stacks and certified service networks.
Lidar sensors paired with SLAM algorithms enable dynamic path planning without floor-mounted reflectors or magnetic strips. Automotive assembly plants in Slovakia and Hungary are adopting these systems for body-in-white transport sequences. The technology is supplanting legacy wire-guided installations that required production line shutdowns for route modifications.
The EU AI Act will classify autonomous navigation systems as high-risk applications requiring conformity assessments and algorithmic transparency documentation. Pharmaceutical distribution centers face the steepest compliance burden given their validated environment requirements. German warehouse operators are pre-emptively demanding vendor roadmaps for technical documentation ahead of enforcement deadlines.
Leasing structures with bundled maintenance and software updates are displacing traditional equipment purchase models among mid-cap logistics providers. Third-party logistics operators in the Netherlands pioneered this shift to preserve balance sheet flexibility. French e-commerce fulfillment networks are now replicating this pattern as they scale automated handling capacity.
Europe Automated Guided Vehicle (AGV) Market Segmentation
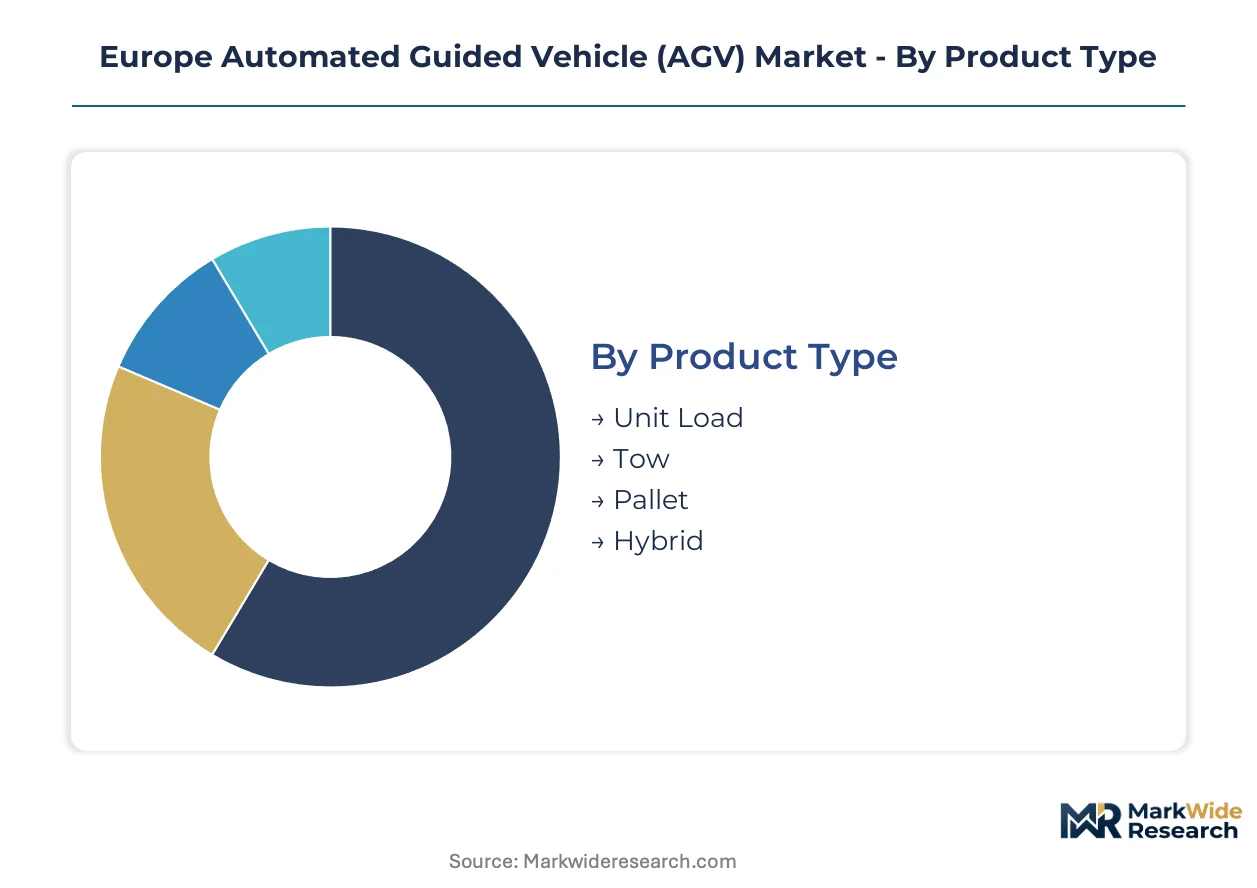
AGV procurement patterns diverge sharply across European markets based on payload requirements, navigation infrastructure, and regulatory environment. Channel strategies for fleet deployment must align with specific segment characteristics to capture replacement cycles and greenfield automation investments.
Product Type:
Channel mix varies by product complexity, with unit load and pallet vehicles flowing through material handling dealers while tow vehicles and hybrid platforms increasingly route through systems integrators for customized fleet orchestration.
- Unit Load:These vehicles transport standardized totes, cartons, and containers using roller or chain conveyor decks integrated with warehouse automation systems. German automotive assembly plants and Dutch e-commerce fulfillment centers are absorbing the highest volumes as they replace legacy conveyor infrastructure with flexible routing capabilities. CE marking requirements for protective field systems extend procurement timelines but reinforce preference for established European suppliers with certified service networks.
- Pallet:Fork-based or clamp mechanisms handle Euro pallets and industrial skids at heights up to twelve meters, serving pharmaceutical distribution centers in Switzerland and cold storage facilities across Belgium. Lithium-ion powertrains are displacing lead-acid batteries in this segment due to opportunity charging requirements in multi-shift operations.
- Tow:Tugger vehicles pull carts or trailers in train configurations for milk-run material delivery sequences.
- Hybrid:Modular platforms switch between unit load and pallet handling modes through attachment changes.
By volume, unit load leads. By growth pace, hybrid configurations are expanding most quickly as warehouses seek fleet standardization across diverse material flows.
Technology:
Cost tiers separate navigation approaches, with magnetic guidance occupying the economy position and lidar-based systems commanding premium pricing for route flexibility.
- Lidar:Laser scanning paired with SLAM algorithms enables dynamic path planning without floor-mounted infrastructure. Slovakian and Hungarian automotive plants are adopting these systems for body-in-white transport, eliminating production shutdowns previously required for route modifications. The EU AI Act's impending high-risk system classification is accelerating vendor investment in algorithmic transparency documentation ahead of enforcement deadlines.
- Laser Navigation:Reflector-based triangulation provides precise positioning for high-bay storage applications in Belgian and German distribution centers.
- Magnetic:Tape or wire guidance remains deployed in legacy installations with fixed routes and predictable throughput requirements.
- Vision Guidance:Camera-based systems recognize environmental features for navigation in semi-structured outdoor environments.
By installed base, magnetic systems dominate. By replacement velocity, lidar is gaining share fastest as warehouse operators prioritize infrastructure-free reconfiguration.
End User:
Customer type determines procurement authority, with manufacturing controlling capital budgets directly while retail and logistics increasingly rely on third-party fleet operators and leasing structures.
- Manufacturing:Automotive, electronics, and industrial assembly operations deploy AGVs for just-in-time component delivery and work-in-progress transport. German OEMs are expanding captive engineering teams to manage multi-vendor fleet integration, while Polish and Romanian greenfield plants remain underpenetrated relative to Western European automation benchmarks.
- Logistics:Third-party operators and dedicated contract distribution networks prioritize asset flexibility and uptime guarantees.
- Retail:E-commerce fulfillment and store replenishment operations concentrate demand in the Netherlands and France.
- Food & Beverage:Temperature-controlled transport and hygienic design requirements apply to dairy, beverage, and packaged goods handling.
By fleet size, manufacturing leads. By deployment pace, logistics operators are climbing the fastest as e-commerce densification accelerates across Benelux and Northern France.
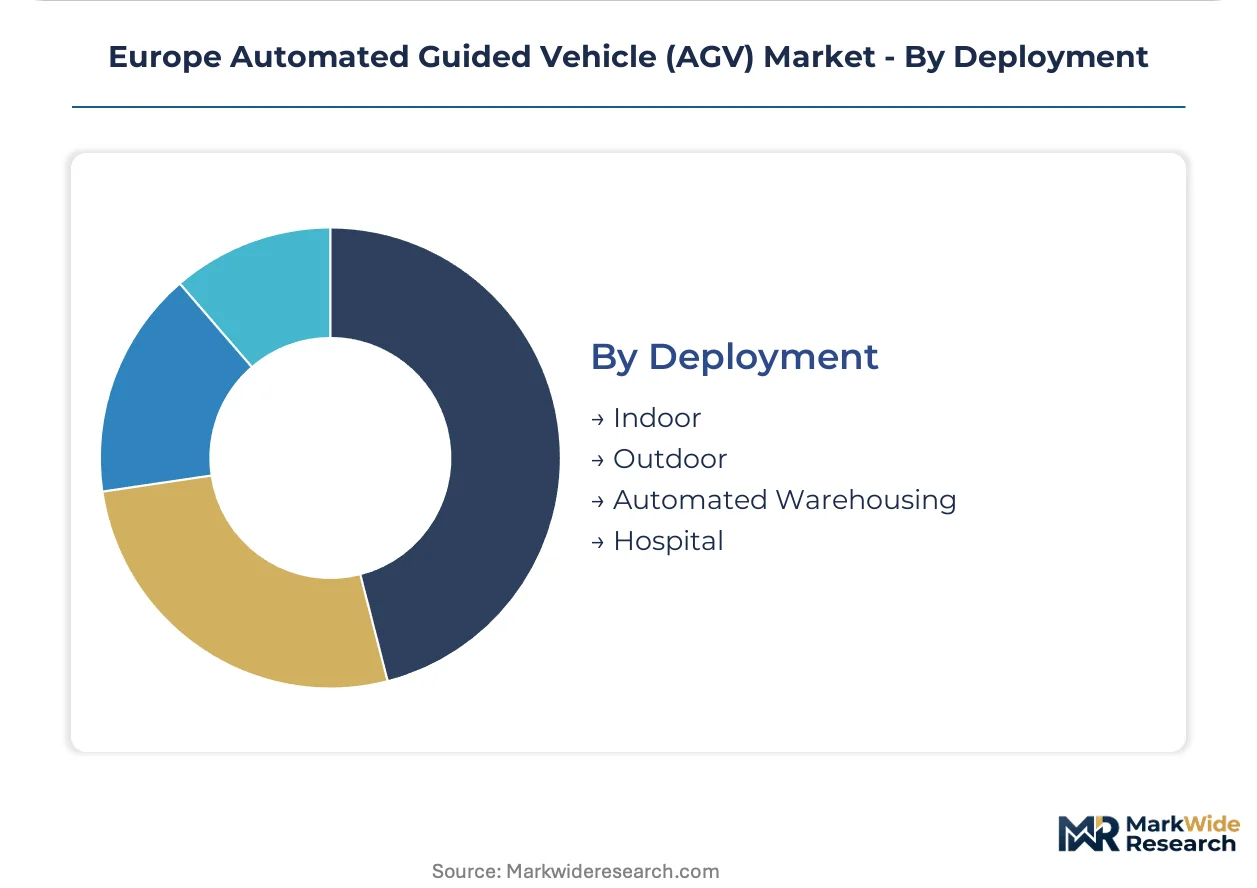
Deployment:
Maturity curves separate deployment environments, with indoor warehousing representing established applications and hospital settings requiring emerging certification pathways.
- Automated Warehousing:High-bay storage, goods-to-person picking, and sortation staging systems define the core revenue base for European AGV suppliers. Dutch and Belgian distribution centers are absorbing unit load vehicles for same-day delivery networks, while German pharmaceutical warehouses demand validated navigation systems with audit trail documentation.
- Indoor:Manufacturing and assembly plant applications span cleanroom, paint shop, and general assembly environments.
- Outdoor:Yard logistics and inter-facility transport face weatherproofing and mixed-traffic safety challenges.
- Hospital:Sterile supply, linen, and meal delivery applications require infection control protocols and elevator integration.
By revenue concentration, automated warehousing leads. By emerging application growth, hospital deployments show the steepest expansion trajectory as healthcare systems address labor availability constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure underwrites the Netherlands' central role in European intralogistics automation, channeling AGV demand through the Rhine-Scheldt delta into German and Belgian distribution networks.
Germany
Automotive OEMs in Stuttgart and Wolfsburg are expanding captive AGV engineering teams to manage multi-vendor fleet integration for just-in-time component delivery. KBA enforcement of protective field systems under the EU Machinery Directive accelerates replacement cycles in legacy warehouses. The Ruhr Valley logistics corridor concentrates demand for unit load vehicles serving e-commerce fulfillment networks.
Netherlands
Third-party logistics operators around Rotterdam and Venlo pioneered leasing structures with bundled maintenance, preserving balance sheet flexibility for automated warehousing scale-outs. REACH compliance for battery chemistries shapes procurement specifications at pharmaceutical distribution centers. The Randstad megalopolis anchors same-day delivery staging infrastructure absorbing lidar-guided vehicle fleets.
Belgium
Pharmaceutical cold storage facilities in Antwerp deploy validated navigation systems with audit trail documentation for vaccine distribution networks. The EU Green Deal's decarbonization targets push operators toward energy recovery systems in high-bay warehouses. Flanders' dense motorway network enables rapid fulfillment radius expansion from automated distribution hubs.
Switzerland
Swissmedic validation requirements for pharmaceutical distribution create distinct certification pathways for temperature-controlled AGV fleets serving Basel and Geneva life sciences clusters. The country's Alpine rail tunnels channel cross-border logistics automation investment toward precision handling systems. Zurich's financial sector supports equipment leasing structures for mid-cap logistics providers.
Poland
Greenfield automotive assembly plants in Lower Silesia and the Poznań region remain underpenetrated by automated intralogistics relative to Western European automation benchmarks. EU structural funds accelerate warehouse automation adoption near the German border. The Łódź logistics hub attracts e-commerce fulfillment investment requiring flexible route reconfiguration capabilities.
Europe Automated Guided Vehicle (AGV) Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and service network coverage, producing a tiered structure where scale advantages in lithium-ion battery production separate top-tier vendors from mid-cap challengers. Consolidation pressures concentrate around CE marking expertise and WMS integration capabilities. Three archetypes dominate: full-stack material handling conglomerates with captive battery production, warehouse automation specialists with verticalized software stacks, and regional systems integrators serving national manufacturing clusters. Competitive moves center on pre-certification of autonomous navigation algorithms ahead of EU AI Act enforcement and geographic expansion into underpenetrated Central European automotive corridors.
Within the full-stack conglomerate tier, Toyota Material Handling Europe AB and KION Group AG exemplify scale-driven positioning through established dealer networks and captive powertrain component production. Swisslog Holding AG represents the warehouse automation specialist archetype, integrating AGV fleets with management software for validated pharmaceutical environments. Among Japanese multinationals with European assembly presence, Daifuku Co., Ltd. occupies a position serving high-throughput distribution networks.
| Leading Market Players |
|---|
| Toyota Material Handling Europe AB |
| Swisslog Holding AG |
| KION Group AG |
| Linde Material Handling GmbH |
| SSI SCHAEFER |
| KUKA AG |
| Jungheinrich AG |
| STILL GmbH |
| Daifuku Co., Ltd. |
| Others |
Supply & Pricing Matrix
Lithium-ion battery chemistry substitution for lead-acid powertrains is simultaneously shifting supply geography toward East Asian cathode processing centers and compressing pricing economics for mid-tier AGV configurations as European buyers absorb volatile raw material pass-through costs.
Pricing Analysis
Volume-discount tiering structures separate enterprise fleet operators securing multi-year service bundles from mid-cap logistics providers purchasing equipment through leasing structures. Three-tier pricing stratifies across premium lidar-guided systems with embedded AI transparency documentation, standard laser-navigation platforms for high-bay warehousing, and economy magnetic-tape configurations serving legacy route requirements. Price differentiation hinges on CE marking certification depth and lithium-ion battery energy density specifications. Cost compression in the standard tier is intensifying because notified body bottlenecks extend conformity assessment timelines and inflate compliance overhead.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for lidar sensors and servo motor controllers sourced from Chinese and South Korean manufacturing clusters. Lithium carbonate and cobalt hydroxide feedstocks draw from Chilean mining operations and Indonesian processing facilities, creating single-source vulnerability for cathode active materials. Distribution runs through Rotterdam port infrastructure into Rhine-Scheldt delta warehousing corridors serving German and Benelux fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a defensive-moat story anchored in regulatory entrenchment: CE marking expertise and EU AI Act pre-certification create switching costs that lock warehouse operators into established vendor relationships.
For Market Incumbents: Secure algorithmic transparency documentation ahead of EU AI Act enforcement deadlines to entrench pharmaceutical distribution relationships. Deepen backward integration into lithium-ion battery pack assembly to insulate margins from cathode material price volatility. Expand captive service networks in Polish and Romanian manufacturing corridors before challenger systems integrators establish footholds. For New Entrants and Emerging Players: CE marking fast-track partnerships with Southern German notified bodies offer the most penetrable entry vector for mid-cap logistics providers seeking alternatives to incumbent dealer networks. Target Polish automotive greenfield plants with lidar-based navigation systems priced below Western European benchmarks. Position through equipment-as-a-service models that bundle maintenance and software updates to bypass capital budget gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward warehouse automation specialists with verticalized software stacks and pre-certified autonomous navigation algorithms. Long-term viability over a multi-year horizon rests on vendors capturing recurring revenue streams from fleet orchestration software rather than hardware margins alone. Watch for inflection when EU AI Act enforcement triggers consolidation among non-compliant mid-tier suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | Algorithmic transparency documentation creates first-mover lock-in with pharmaceutical distributors facing validated environment requirements. |
| Lithium-Ion Battery Integration | In-house powertrain production insulates margins from cobalt and lithium price volatility while enabling three-shift deployment guarantees. |
| Leasing Structure Expansion | Equipment-as-a-service models preserve balance sheet flexibility for mid-cap logistics providers scaling automated handling capacity. |
| Central European Geographic Expansion | Greenfield automotive assembly plants in Poland and Romania remain underpenetrated relative to Western European automation benchmarks. |
| WMS-AGV Synchronization Investment | Verticalized software stacks capture recurring revenue from fleet orchestration while reducing multi-vendor integration friction. |
Research Methodology
Initial hypotheses were tested against primary input from warehouse operations directors, AGV fleet managers, systems integration engineers, and pharmaceutical distribution compliance officers and refined through secondary validation against EU Machinery Directive guidance documents, CE marking technical files, notified body assessment records, and customs trade data for lithium-ion battery imports. Bottom-up unit economics for fleet deployment scenarios were triangulated against top-down market sizing from material handling dealer channel surveys.
Variance decomposition across the projection horizon isolates volume drivers by product type, navigation technology tier, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis of legacy magnetic-tape installations and greenfield automation penetration rates in Central European manufacturing corridors. Forecast inputs incorporate lithium-ion battery energy density improvement curves and EU AI Act implementation timelines for high-risk system classification.
Underlying assumptions cover stable REACH compliance frameworks for battery chemistries and sustained e-commerce fulfillment network densification across Benelux and Northern France, with deviation risk concentrated in notified body capacity constraints extending CE marking timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotic Tool Changer Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Lab Robotics Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
China Cloud Robotics Market
Robotics and Automation
Smart Worker Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Global Exoskeleton Market
Robotics and Automation
Global Wafer Handling Robots Market
Robotics and Automation
Self-Driving Delivery Robot Market
Robotics and Automation
Europe Service Robotics Market
Robotics and Automation
Drone Package Delivery Market
Robotics and Automation
Global Construction Robot Market
Robotics and Automation
Underwater Exploration Robots Market
Robotics and Automation
Construction Robotics Market