
 Global Auto Dealer Software Market | 2026-2036
Global Auto Dealer Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Auto Dealer Software Market Foresight
North American software vendors is pivoting toward integrated dealership operating systems that merge inventory, finance, and customer data layers. CDK Global leverages its established dealer management system footprint to sustain recurring revenue across franchise networks. Cox Automotive anchors its competitive position through end-to-end retail solutions spanning listing, financing, and logistics. Reynolds and Reynolds differentiates through specialized document compliance and registration workflow tools.
Auto dealer software encompasses integrated information systems that manage vehicle inventory pipelines, customer relationship databases, financial transaction ledgers, and regulatory compliance documentation across automotive retail operations. These platforms typically employ real-time data synchronization protocols, API-based third-party integrations, and role-based access architectures to coordinate sales, service, and back-office functions. Cloud-based deployment models lead adoption as franchise dealership groups prioritize remote accessibility and reduced infrastructure overhead. Customer Relationship Management modules represent a concentrated margin pool where data monetization and predictive analytics capabilities command premium positioning. On-premise legacy installations persist among smaller independent retailers constrained by migration costs and localized data sovereignty preferences.
The US Federal Trade Commission's Gramm-Leach-Bliley Safeguards Rule and state-level dealer licensing boards shape software requirements around consumer financial data protection and audit trail standards. Europe's GDPR and the EU AI Act impose algorithmic transparency and consent management obligations on automated credit decisioning and customer profiling tools. China's SAMR and MIIT cybersecurity standards mandate domestic data localization for dealer platforms serving state-affiliated automotive groups. Stakeholders must monitor how fragmented regulatory timelines across Washington, Brussels, and Beijing will fragment product roadmaps and certification costs.
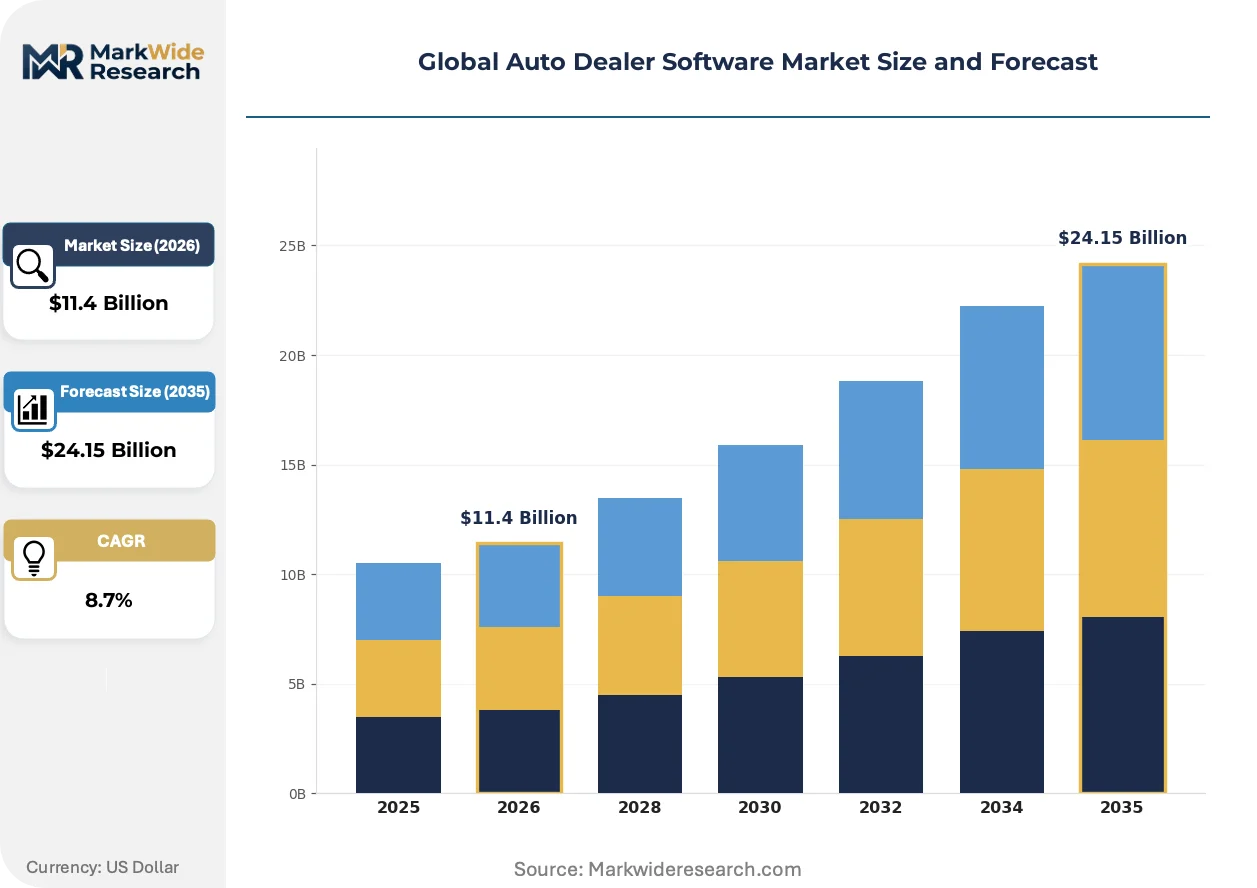
Market Dynamics
Cloud migration mandates from Brussels and Beijing are forcing dealer management system vendors to rebuild architectures for data localization, API transparency, and algorithmic audit trails across three continents simultaneously.
Growth Catalysts
- EU AI Act algorithmic transparency rules:Automated credit decisioning tools now require explainable AI layers, pushing dealers toward certified SaaS platforms with built-in consent management and bias detection.
- Used vehicle reconditioning automation:Predictive analytics modules that forecast refurbishment costs and time-to-lot are commanding premium positioning in franchise networks.
- China's state-affiliated dealer consolidation:Domestic automotive groups are mandating unified software stacks across acquired independents, creating concentrated procurement pools in Shanghai and Guangzhou.
Market Restraints
- Legacy on-premise technical debt:Smaller independent retailers in rural United States markets face migration costs exceeding $150,000 per rooftop, freezing replacement cycles.
- Input cost volatility in semiconductor components:Dealer management system hardware refresh cycles depend on stable GPU and memory pricing, which remains exposed to Taiwan Strait supply disruptions.
- GDPR certification fragmentation:Divergent national implementations across Germany, France, and Italy force vendors to maintain multiple compliance variants, inflating R&D overhead.
Strategic Opportunities
- India's PLI scheme for automotive software:Domestic production incentives are attracting dealer platform vendors to establish development centers in Pune and Chennai for cost-competitive export manufacturing.
- Subscription-based F&I product integration:Embedded insurance and warranty modules that activate at point-of-sale are opening recurring revenue streams beyond traditional license fees.
- Vehicle-to-grid data monetization:Electric vehicle charging pattern analytics from dealer service bays are creating secondary data products for utility demand-response programs.
Industry Challenges
- API standardization delays:The lack of unified data exchange protocols between OEM telematics feeds and dealer CRM systems forces expensive custom integration projects.
- Cybersecurity skill scarcity:Dealer IT departments lack personnel trained in NIST framework implementation, leaving SaaS vendors responsible for breach liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Auto Dealer Software Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Inventory Management, Customer Relationship Management, Sales Analytics, Finance & Accounting, Compliance Tracking, Service Scheduling Deployment Model: Cloud-Based, On-Premise, Hybrid, Software as a Service, Mobile Application, Web Application Customer Type: Franchise Dealerships, Independent Retailers, Online Marketplaces, Vehicle Wholesalers, Fleet Management Companies, Leasing Agencies End User Role: Sales Managers, Service Technicians, Finance Officers, Marketing Teams, Inventory Coordinators, Customer Support Representatives |
| Companies Covered | Cox Automotive, CDK Global, Reynolds and Reynolds, RouteOne, Dominion Enterprises, DealerSocket, Internet Brands, Dealertrack, ELEAD1ONE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Auto Dealer Software Market Shifts & Advancements
Artificial intelligence is penetrating dealer operations through predictive inventory pricing, automated customer scoring, and generative marketing content, compressing decision cycles from days to minutes.
Large language models are rewriting how franchise dealers generate vehicle descriptions, respond to inbound inquiries, and draft personalized follow-up communications. Tier-one automotive groups in the United States and Germany are deploying these tools across hundreds of rooftops within eighteen-month rollout windows. The technology is rewriting job descriptions in business development centers, reducing headcount per rooftop while raising lead conversion rates.
China's SAMR cybersecurity standards now mandate domestic data localization for all dealer platforms serving state-affiliated automotive groups. Vendors must establish mainland China cloud infrastructure or forfeit access to the world's largest vehicle market. European and North American software firms are responding through joint ventures with domestic technology partners rather than direct market entry.
Franchise dealer procurement committees are consolidating vendor relationships from point solutions toward integrated operating systems spanning inventory, finance, and service. Independent software vendors selling single modules face exclusion from RFP shortlists at multi-rooftop groups. This concentration is most visible in the United States, where the fifty largest dealer groups control software specification for thousands of affiliated locations.
Global Auto Dealer Software Market Segmentation
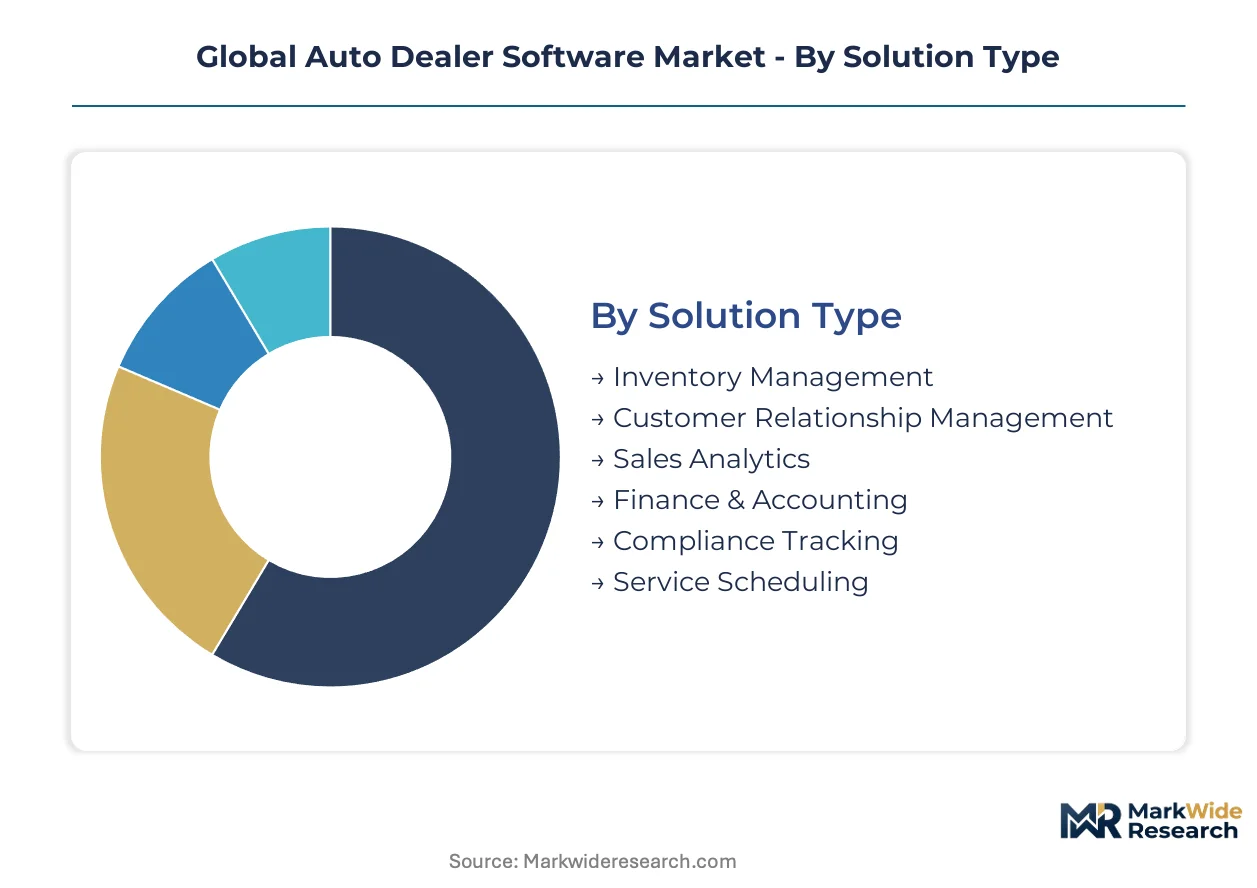
Auto dealer software purchasing decisions hinge on regulatory compliance burdens, integration complexity, and the scale of multi-rooftop operations. Buyers evaluate solutions against their existing technical debt and the specific workflows of their sales, service, and finance departments.
Solution Type:
Dealership procurement committees prioritize modules that consolidate data silos and reduce manual reconciliation across departments.
- Inventory Management:Real-time vehicle tracking systems synchronize lot counts with OEM allocation feeds and third-party listing platforms. Demand concentrates among franchise groups in the United States and Germany where just-in-time stocking and velocity-based pricing require granular visibility.
- Customer Relationship Management:Unified databases capture prospect interactions, purchase history, and service records across touchpoints. United States-based dealer groups are driving adoption here as predictive lead scoring and automated follow-up sequences compress sales cycles.
- Sales Analytics:Dashboard tools visualize conversion funnels, salesperson performance, and gross margin attribution.
- Finance & Accounting:Ledger systems integrate with lender networks and captive finance arms to automate contract submission and funding reconciliation.
- Compliance Tracking:Audit trail modules document consumer consent, credit decisioning rationale, and document retention per FTC Safeguards Rule and GDPR requirements.
- Service Scheduling:Bay allocation and technician dispatch tools optimize capacity utilization at fixed-ops departments.
Volume sits with Inventory Management; growth tilts toward Customer Relationship Management.
Deployment Model:
Total cost of ownership and data sovereignty requirements split buyer preferences across architecture types.
- Cloud-Based:Multi-tenant architectures deliver remote accessibility and automatic updates without on-site server maintenance. European dealers facing EU AI Act mandates are migrating fastest as certified SaaS platforms satisfy algorithmic transparency and consent management obligations.
- On-Premise:Localized server installations retain full data control and customization flexibility. Independent retailers in rural United States markets persist here due to unreliable broadband infrastructure and migration cost constraints exceeding available capital.
- Hybrid:Split configurations keep sensitive financial data local while pushing customer-facing tools to cloud infrastructure.
- Software as a Service:Subscription licensing shifts capital expenditure to operating budgets and bundles vendor-managed security patching.
- Mobile Application:Native iOS and Android tools enable floor sales staff and service advisors to access customer records and inventory from anywhere on the lot.
- Web Application:Browser-based interfaces eliminate installation friction and support bring-your-own-device policies at smaller operations.
Revenue concentrates in Cloud-Based deployments; expansion is steepest in Software as a Service offerings.
Customer Type:
Organizational scale and OEM affiliation determine integration depth and module sophistication requirements.
- Franchise Dealerships:Authorized new vehicle retailers require DMS platforms that handshake with manufacturer order banks, warranty systems, and incentive programs. China's state-affiliated automotive groups are mandating unified software stacks across acquired independents, creating procurement concentration in Shanghai and Guangzhou.
- Independent Retailers:Used vehicle specialists and unaffiliated new car sellers prioritize affordability and rapid implementation over deep OEM integration. Smaller rooftops in the United States face technical debt barriers exceeding available migration budgets.
- Online Marketplaces:Digital-first vehicle retailers need API-heavy platforms that ingest listings from multiple sources and automate pricing algorithms.
- Vehicle Wholesalers:Auction and remarketing operators track vehicle condition grades, transport logistics, and buyer payment verification.
- Fleet Management Companies:Commercial vehicle lessors monitor utilization rates, maintenance schedules, and driver compliance across distributed assets.
- Leasing Agencies:Long-term rental and subscription providers manage recurring billing, mileage tracking, and end-of-term remarketing workflows.
Dealership count favors Franchise Dealerships; wallet share is climbing fastest among Online Marketplaces.
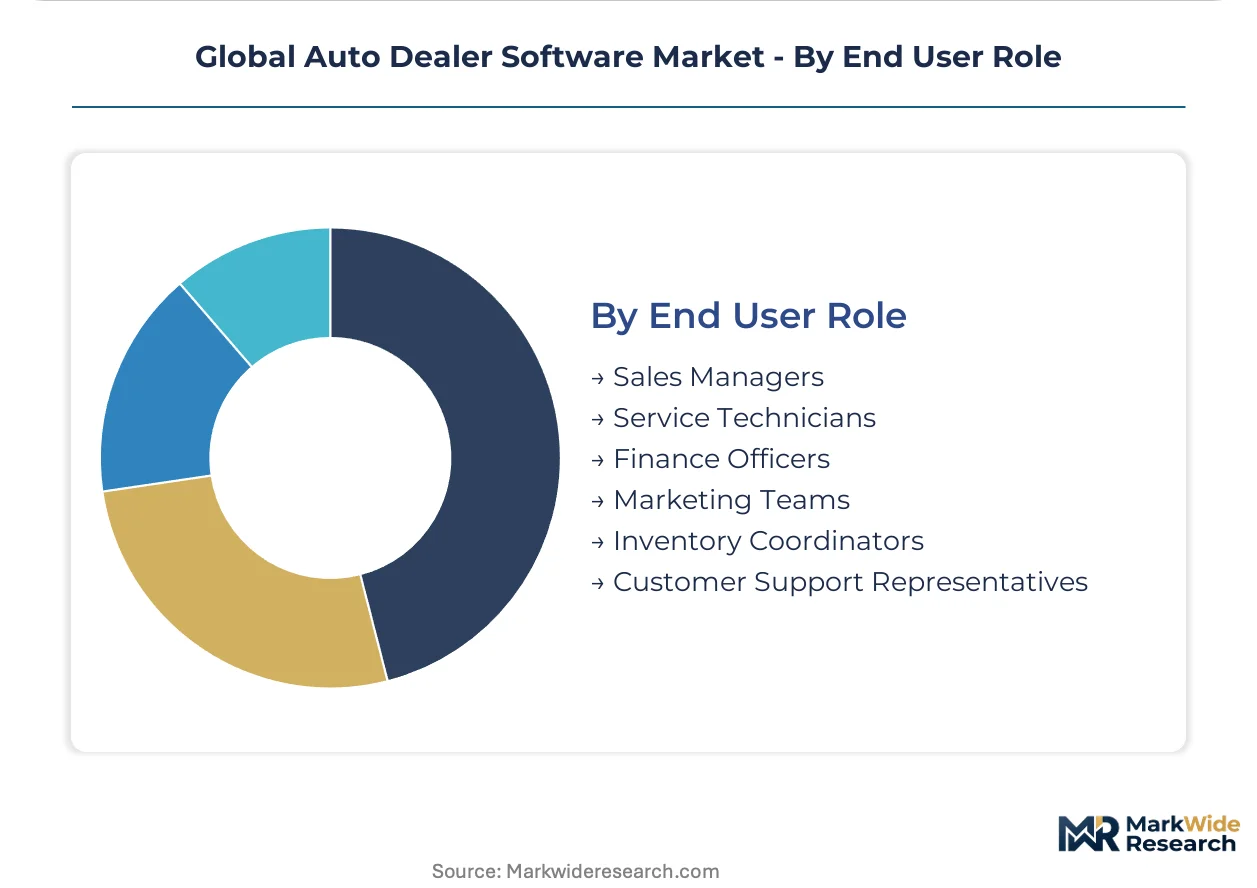
End User Role:
Workflow-specific feature requirements fragment purchasing influence across departmental stakeholders.
- Sales Managers:Pipeline visibility tools track lead sources, appointment show rates, and closing ratios by salesperson. United States franchise groups are deploying these dashboards across hundreds of rooftops to standardize performance benchmarking.
- Service Technicians:Digital inspection tools capture photo documentation, parts ordering, and labor time tracking at the bay level.
- Finance Officers:Contract generation, lender submission, and regulatory disclosure modules dominate this user segment's requirements.
- Marketing Teams:Campaign management, inventory merchandising, and reputation monitoring tools coordinate digital advertising spend.
- Inventory Coordinators:Acquisition pricing, reconditioning workflow, and lot placement optimization occupy daily workflows.
- Customer Support Representatives:Case management, callback scheduling, and satisfaction survey tools structure post-sale engagement.
License volume centers on Sales Managers; feature velocity is highest for Service Technicians.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley venture capital and Seattle cloud infrastructure anchor software development for automotive retail platforms across three continents.
United States
Franchise dealership groups in Texas and Florida are consolidating vendor relationships toward integrated operating systems. The FTC's Gramm-Leach-Bliley Safeguards Rule mandates audit trail capabilities for consumer financial data protection. Greater Atlanta hosts Cox Automotive's headquarters, where end-to-end retail solutions coordinate listing, financing, and logistics across thousands of rooftops.
Germany
Authorized Mercedes-Benz and BMW retailers require DMS platforms with native OEM order bank integration. The EU AI Act imposes algorithmic transparency obligations on automated credit decisioning tools. Stuttgart and Munich clusters concentrate development centers where vendors build explainable AI layers for consent management and bias detection.
China
State-affiliated automotive groups in Shanghai and Guangzhou mandate unified software stacks across acquired independents. SAMR and MIIT cybersecurity standards require domestic data localization for dealer platforms. The Yangtze River Delta hosts joint ventures between European vendors and domestic technology partners seeking market access without direct entry.
India
Domestic production incentives under the PLI scheme attract dealer platform vendors to establish development centers. The country's central bank and automotive regulators shape software requirements around financial data localization. Pune and Chennai clusters specialize in cost-competitive export manufacturing for SaaS modules serving Southeast Asian markets.
United Kingdom
London-based dealer groups prioritize cloud migration to satisfy GDPR certification requirements and reduce infrastructure overhead. The Financial Conduct Authority oversees consumer credit activities embedded in dealer finance modules. The Southeast England corridor concentrates fintech partnerships that enable subscription-based F&I product integration at point-of-sale.
Global Auto Dealer Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded insurance and vehicle-to-grid data monetization adjacent spaces. The vendor base stratifies across three tiers: legacy DMS incumbents with franchise network penetration, cloud-native challengers targeting independent retailers, and OEM-captive technology arms serving affiliated groups. Dominant competitive moves include M&A consolidation of point-solution vendors into integrated platforms and strategic partnerships with telematics providers for real-time inventory feeds.
Within the legacy incumbent tier, CDK Global, Cox Automotive, and Reynolds and Reynolds represent the established footprint across North American franchise networks. CDK Global exemplifies the recurring revenue model sustained through dealer management system relationships. Cox Automotive anchors competitive positioning through vertical integration spanning listing aggregation to logistics coordination. Reynolds and Reynolds occupies a specialized position in document compliance and registration workflow tools.
| Leading Market Players |
|---|
| Cox Automotive |
| CDK Global |
| Reynolds and Reynolds |
| RouteOne |
| Dominion Enterprises |
| DealerSocket |
| Internet Brands |
| Dealertrack |
| ELEAD1ONE |
| Others |
Supply & Pricing Matrix
EU AI Act compliance certification gates both qualified supply and premium-tier pricing access for dealer management system vendors, forcing European dealers toward certified SaaS platforms while excluding uncertified competitors from high-margin procurement pools. This regulatory filter concentrates pricing power among vendors with established mainland China cloud infrastructure or European development centers, fragmenting procurement options across compliance tiers.
Pricing Analysis
Warranty and service-bundling arrangements separate premium-tier dealer software contracts from unbundled standard offerings, with franchise dealership groups in the United States and Germany paying subscription premiums for embedded compliance modules and 24/7 technical support. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and integration depth, with cloud-native SaaS deployments commanding recurring revenue multiples above on-premise perpetual licenses. Pricing pressure stems from India's PLI scheme attracting cost-competitive development centers in Pune and Chennai, compressing margins on export-oriented modules. Independent retailers in rural United States markets exhibit highest price sensitivity due to migration cost constraints exceeding available capital, while China's state-affiliated automotive groups show lowest sensitivity given mandated procurement timelines.
Supply Chain Analysis
Freight cost volatility from Taiwan Strait disruptions propagates through semiconductor component sourcing for dealer management system hardware refresh cycles, elevating total cost of ownership calculations for on-premise server installations. Supply concentrates in the United States for legacy DMS incumbents, Germany for OEM-captive technology arms serving Mercedes-Benz and BMW retailers, and China for domestic platforms mandated by SAMR data localization requirements. GPU and memory chip dependencies draw from Taiwan and South Korea fabrication facilities, while cloud infrastructure rests on hyperscaler data centers in Virginia, Frankfurt, and Shanghai. Single-source vulnerability in advanced semiconductor nodes threatens hardware delivery timelines. Distribution runs through direct enterprise sales teams for franchise networks and value-added resellers for independent retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud infrastructure capacity scarcity in mainland China props pricing for vendors with established SAMR-compliant data centers, constraining supply expansion for European and North American firms seeking market access without joint venture structures.
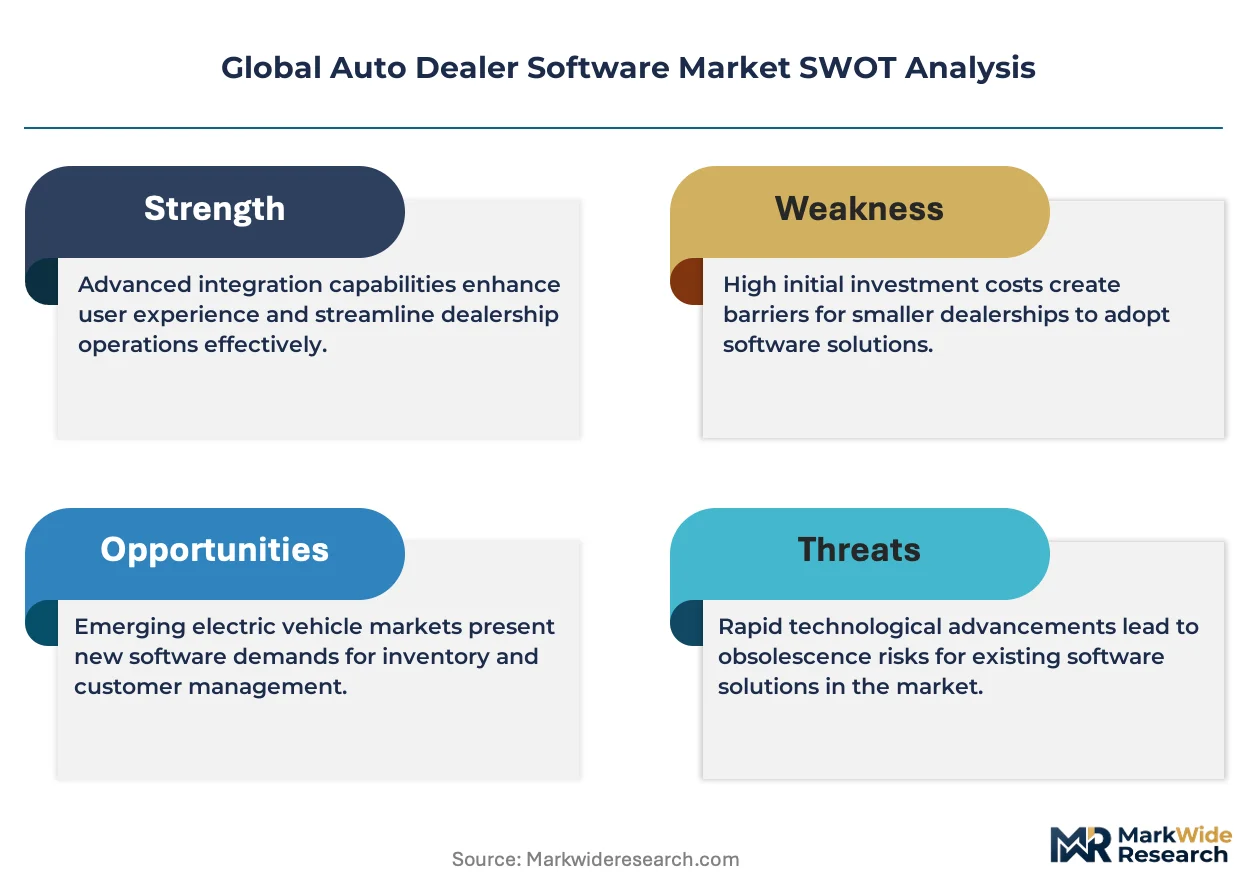
For Market Incumbents: Acquire specialized compliance workflow vendors to consolidate document management and GDPR audit trail capabilities into unified platforms. CDK Global and Cox Automotive should deepen backward integration into telematics data feeds, securing real-time inventory synchronization against emerging API standardization challengers. Certification investment in EU AI Act explainable AI layers defends recurring revenue streams from cloud-native entrants targeting independent retailers with lightweight CRM modules. For New Entrants and Emerging Players: Capture white-space in India's domestic dealer market before PLI scheme incentives attract established vendors to Pune and Chennai development centers. Target used vehicle reconditioning automation modules where predictive analytics capabilities command premium positioning with minimal incumbent penetration. Deploy mobile-first SaaS architectures for independent retailers in rural United States markets, bypassing migration cost barriers through browser-based deployment rather than on-premise replacement cycles. For Investors and Strategic Acquirers: Joint venture announcements between European vendors and Chinese technology partners are the leading indicator that SAMR compliance pathways have cleared regulatory review, signaling viable market entry structures. Long-term viability favors vendors with multi-continental cloud footprints spanning Virginia, Frankfurt, and Shanghai data center regions. Acquisition target archetype: specialized F&I product integration platforms enabling embedded insurance modules at point-of-sale. Watch for FTC Gramm-Leach-Bliley Safeguards Rule enforcement actions as inflection signal for compliance-tracking module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying inventory, finance, and CRM layers reduces manual reconciliation across franchise rooftop networks. |
| Acquisition of Specialist Firm | Compliance workflow vendors add GDPR and FTC Safeguards Rule audit trail capabilities to core DMS offerings. |
| Strategic Partnership | Joint ventures with Chinese technology partners satisfy SAMR data localization without direct mainland entry. |
| Geographic Expansion | Development centers in Pune and Chennai exploit PLI scheme incentives for cost-competitive SaaS manufacturing. |
| Product Launch | Explainable AI layers for automated credit decisioning address EU AI Act algorithmic transparency mandates. |
Research Methodology
Multi-period observation of dealer technology procurement cycles, cloud migration timelines, and regulatory compliance certification rates anchored the trend analysis, supplemented by interviews with dealership operations directors, DMS vendor product managers, automotive OEM platform engineers, and FTC regulatory affairs specialists. Primary fieldwork combined with secondary validation from SEC 10-K filings of listed dealer software vendors, IHS Markit vehicle registration databases, EU AI Act implementation guidance documents, and SAMR cybersecurity standard releases. Bottom-up dealer count modeling and top-down software spend estimates triangulated market sizing across deployment models.
Input-output matrices mapped cloud infrastructure capacity, compliance certification timelines, and franchise rooftop expansion plans to SaaS revenue projections across the analysis window. Segmentation dimensions modeled include deployment architecture, customer type, solution module, and regional regulatory cluster. CAGRs derived from slope-log regression against technology budget growth rates reported by the fifty largest United States dealer groups. Industry-specific forecast inputs incorporated GPU pricing volatility indices and EU AI Act enforcement phase transitions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan Strait supply disruptions, divergent GDPR national implementations across Germany, France, and Italy, and China's state-affiliated dealer consolidation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Embedded Operating Systems Market
Software & Services
France Digital Marketing Software Market
Software & Services
Meditation Software Market
Software & Services
Salesforce Services Market
Software & Services
Background Removal Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Sports League Management Software Market
Software & Services
Global Backup Restore Software Market
Software & Services
OCR Scanning Software Market
Software & Services
Europe Database Management Software Market
Software & Services
Strategy Management Software Market
Software & Services
BIM Objects Software Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
Digital Illustration App Market
Software & Services
Multivariate Testing Software Market