
 Programming Language Market | 2026-2036
Programming Language Market Size, Share, and Industry Trends Forecast 2026-2036
Programming Language Market Analytics
The capital-intensity divergence between deep compiler infrastructure and lightweight runtime tooling is bifurcating competitive strategy across the Programming Language Market. Microsoft sustains dominance through integrated development environments and cloud-native language services anchored to Azure. Google differentiates via Go and Dart investments that occupy strategic positions in container orchestration and cross-platform mobile stacks. JetBrains competes through specialized IDE products that extend Kotlin's footprint beyond Android into server-side and data engineering workflows.
A programming language constitutes a formal system of notation for writing computer programs, comprising syntax rules, semantic definitions, and either a compiler that translates source code into machine instructions or an interpreter that executes statements sequentially. Its primary commercial purpose is enabling software construction across operating systems, hardware architectures, and network topologies with predictable performance and security properties. Compiled languages retain structural importance in systems programming where deterministic execution and hardware proximity protect margin pools, while interpreted and scripting categories capture expanding share in data science and rapid application prototyping. The object-oriented paradigm leads in enterprise codebases, yet functional programming gains traction in distributed systems and concurrent processing workloads.
The European Union AI Act and GDPR impose algorithmic transparency and data handling requirements that reshape language selection toward statically typed, formally verifiable options. ISO and IEC standards for language specification and safety-critical software certification further constrain market access for unvalidated implementations. The Python Software Foundation and Rust Foundation navigate these compliance currents by advancing governance models that embed security review into language evolution. Stakeholders must monitor how regulatory pressure on AI explainability and data sovereignty redistributes preference across paradigm and type categories.
Market Dynamics
Memory-safety mandates from the EU AI Act and GDPR compliance pressures are forcing enterprises to re-architect codebases, creating immediate demand pull for Rust and formally verified languages while compressing legacy C/C++ maintenance cycles.
Growth Catalysts
- EU AI Act algorithmic transparency requirements:Organizations must demonstrate explainable decision paths in machine learning systems, driving adoption of statically typed languages with robust type inference and audit trails.
- Cloud-native development cluster expansion:Container orchestration platforms in the United States, Germany, and India require languages optimized for microservices concurrency and cold-start latency.
- Machine learning pipeline standardization:Python's ecosystem dominance in data engineering workflows creates vendor lock-in effects that expand enterprise licensing and support contract values.
Market Restraints
- Compiler toolchain consolidation:LLVM's near-monopoly in optimization infrastructure creates single-point-of-failure risk for languages dependent on its intermediate representation.
- Talent scarcity in formal verification:Rust and Ada require specialized expertise in ownership semantics and proof-carrying code, limiting deployment velocity outside defense and fintech verticals.
- Legacy codebase entrenchment:Decades of COBOL and Fortran in financial and government systems impose switching costs that delay greenfield language adoption.
Strategic Opportunities
- Edge computing firmware gaps:Rust's zero-cost abstractions and deterministic memory management position it to capture embedded systems previously dominated by C in automotive and industrial IoT applications.
- India's PLI scheme for electronics manufacturing:Domestic semiconductor fabrication incentives create demand for hardware-description languages and silicon-proven verification tools.
- WebAssembly runtime maturation:Cross-platform bytecode execution enables language-agnostic deployment across browser, server, and edge environments without recompilation.
Industry Challenges
- Supply chain attestation for open-source dependencies:SBOM generation and vulnerability scanning impose documentation burdens on package maintainers that slow release cadences.
- ISO 26262 functional safety certification:Automotive software qualification requires exhaustive tool validation that extends compiler qualification timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programming Language Market |
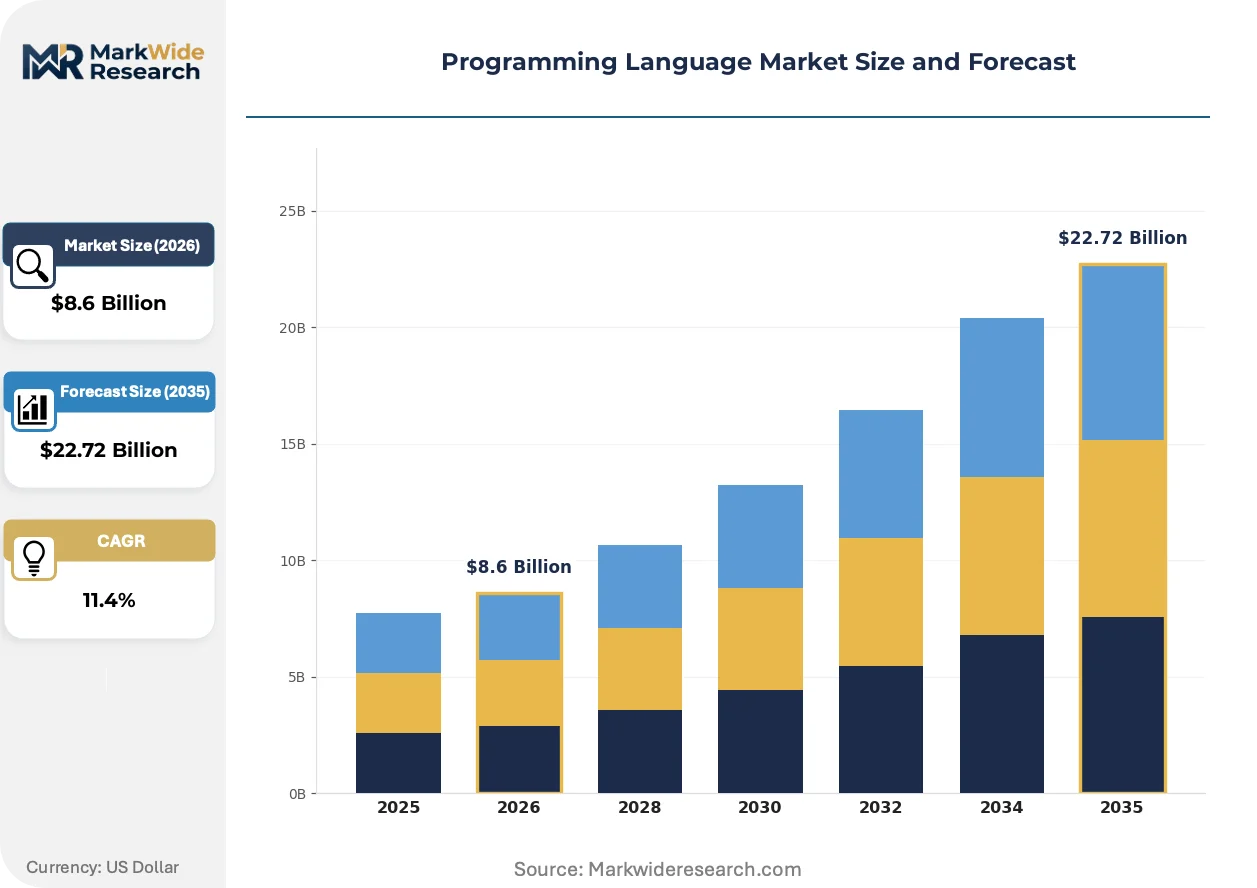
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $22.72 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Compiled, Interpreted, Scripting, Markup Application: Web Development, Data Science, Game Development, Mobile Applications End User: Small Businesses, Enterprises, Educational Institutions, Freelancers Paradigm: Object-Oriented, Functional, Procedural, Logic |
| Companies Covered | JetBrains, Mozilla Foundation, Microsoft, Meta Platforms, Apple, Google, The Python Software Foundation, Rust Foundation, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programming Language Market Evolving Landscape
Compiler infrastructure is fragmenting between heavyweight optimizing toolchains for systems programming and lightweight just-in-time runtimes for rapid deployment, reshaping how language vendors monetize distribution and support.
WebAssembly is miniaturizing deployment artifacts across cloud and edge environments. Platform engineering teams at SaaS providers are standardizing on WASM modules for portable function execution. This technology is miniaturizing the traditional operating system abstraction layer into sandboxed runtime instances that boot in milliseconds.
The EU AI Act's risk-based classification system for algorithmic decision-making imposes documentation and testing burdens on high-risk applications. Language ecosystems must embed audit logging and model provenance directly into standard libraries. Financial services firms in Germany and the Netherlands are prioritizing Coq and Isabelle for formal specification of critical transaction logic.
Developer experience tooling has become the primary procurement differentiator over raw language performance. Platform engineering budgets are consolidating around integrated language servers, automated refactoring, and AI-assisted code generation. This shift is most visible in United States enterprise accounts where JetBrains and Microsoft compete for multi-year IDE subscription contracts tied to Azure and AWS commitments.
Programming Language Market Segmentation
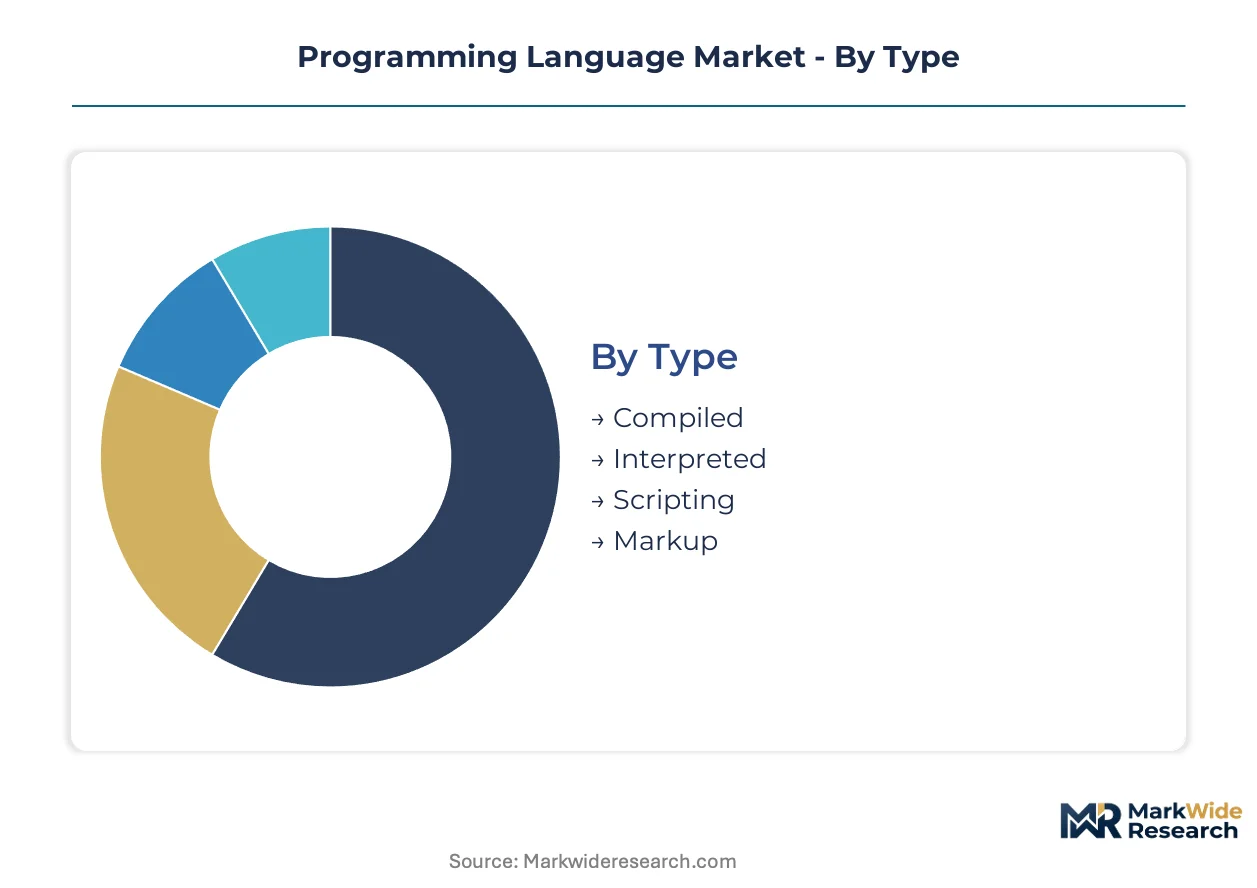
Language selection in enterprise procurement now hinges on paradigm alignment with workload patterns and compliance architecture. Segmentation reveals where vendor lock-in concentrates and where switching costs erode.
Type:
Margin pools cluster in compiled languages where deterministic execution commands premium support contracts and safety-critical certification pathways.
- Compiled:Source code transforms entirely into machine instructions before runtime, delivering predictable latency and hardware proximity. Aerospace and automotive manufacturers in Germany prioritize these languages for ISO 26262 functional safety compliance where memory layout must be statically verifiable.
- Interpreted:Execution occurs line-by-line through a runtime engine, enabling rapid iteration cycles. Data science teams in United States financial services favor this category for exploratory modeling where compilation overhead would obstruct hypothesis testing velocity.
- Scripting:Lightweight automation syntax for system orchestration and DevOps pipelines.
- Markup:Document structure notation with presentational semantics rather than computational logic.
Compiled languages hold installed capacity. Interpreted languages are rotating up the share rankings.
Application:
Volume concentration tracks cloud-native development cluster expansion across United States, Germany, and India.
- Web Development:Server-side and client-side programming for browser-rendered applications. Indian SaaS startups drive demand here, leveraging container orchestration platforms that reward languages with minimal cold-start latency.
- Data Science:Statistical computing, machine learning pipelines, and visualization workflows. Python's ecosystem dominance creates vendor lock-in effects that expand enterprise licensing values across German automotive predictive maintenance programs.
- Game Development:Real-time rendering engines and physics simulation requiring deterministic frame pacing.
- Mobile Applications:Cross-platform deployment targeting iOS and Android runtime environments.
Web Development anchors current deployment volume. Data Science is climbing the fastest.
End User:
Procurement authority splinters between centralized IT governance and decentralized developer self-service.
- Enterprises:Large organizations with formal procurement processes and multi-year support contracts. These buyers prioritize memory-safe languages that satisfy EU AI Act algorithmic transparency mandates and reduce liability exposure.
- Small Businesses:Resource-constrained operations selecting languages based on talent availability and hosting cost minimization. Freelancer marketplaces in India supply these users with pre-built solutions in high-verbosity scripting languages.
- Educational Institutions:Curriculum-driven adoption shaping future workforce skill distributions.
- Freelancers:Independent contractors optimizing for project velocity and client interoperability.
Enterprises control the premium support revenue pool. Small Businesses are gaining share fastest.
Paradigm:
Structural alignment with concurrency models determines suitability for distributed systems architecture.
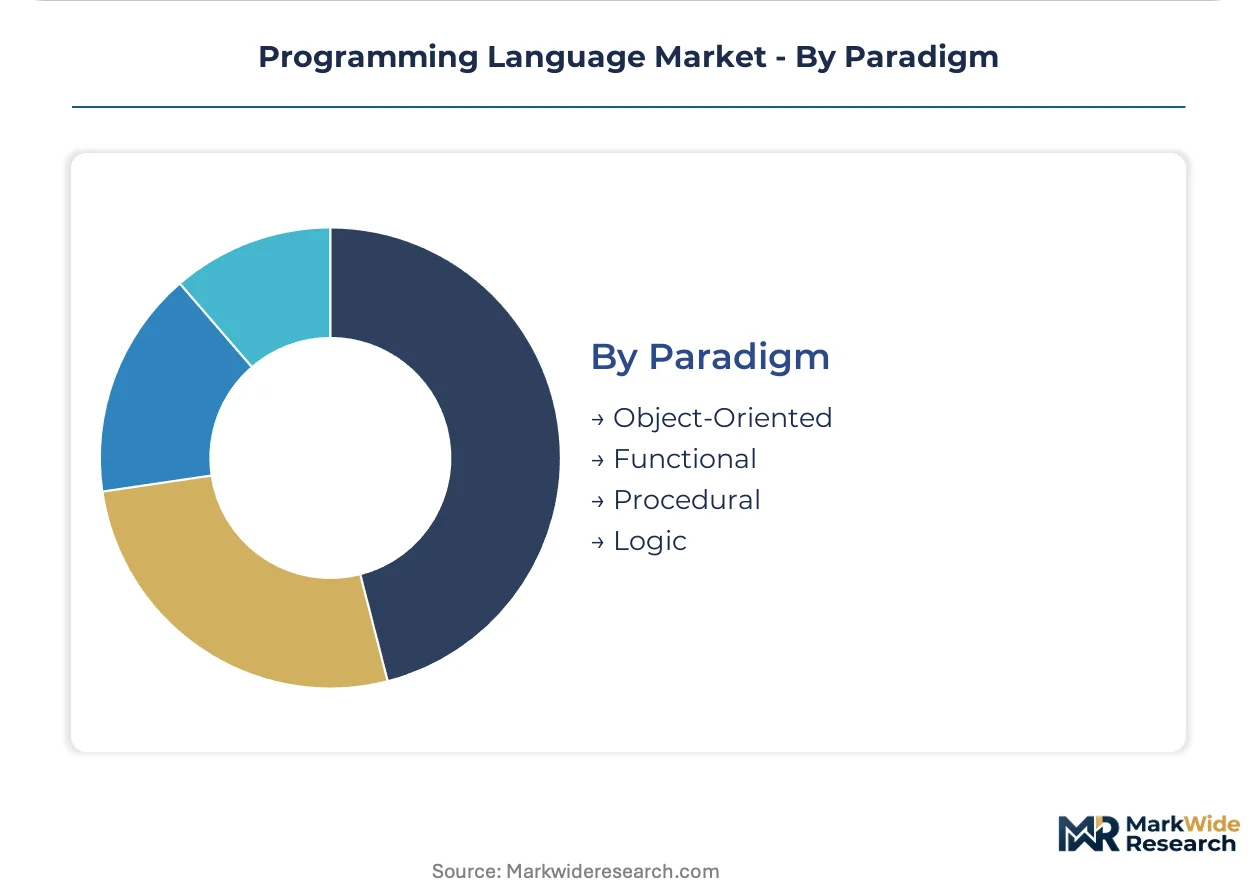
- Object-Oriented:Encapsulation and inheritance patterns dominate legacy enterprise codebases. United States financial institutions maintain substantial investments here, though refactoring costs mount as these systems interface with functional microservices.
- Functional:Immutable data structures and first-class functions enable parallel execution without shared-state contention. German industrial IoT deployments increasingly specify this paradigm for stream processing workloads.
- Procedural:Sequential instruction blocks with minimal abstraction overhead for embedded constraints.
- Logic:Declarative rule engines for constraint satisfaction and automated theorem proving.
Object-Oriented languages retain the largest installed base. Functional programming is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States enterprises prioritize developer experience tooling and cloud-native runtimes. German manufacturers emphasize memory-safety certification for automotive and industrial systems. Indian software services firms optimize for rapid deployment velocity at scale.
United States
Enterprise cloud-native development clusters in Seattle, San Francisco, and Austin drive demand for container-optimized languages with minimal cold-start latency. FCC and FAA regulations on software-defined systems influence procurement toward formally auditable codebases. Microsoft's Redmond headquarters anchors integrated development environment subscriptions tied to Azure commitments.
Germany
Automotive predictive maintenance programs and industrial IoT deployments require ISO 26262-compliant compiled languages with deterministic memory layout. EU AI Act algorithmic transparency mandates push financial services in Frankfurt toward statically typed options with embedded audit trails. Munich and Stuttgart host concentrated Rust adoption for safety-critical embedded systems.
India
PLI scheme incentives for electronics manufacturing create demand for hardware-description languages and silicon verification tools across Bengaluru and Hyderabad. Domestic SaaS startups leverage container orchestration platforms that reward languages optimized for microservices concurrency. Mumbai financial services firms expand Python-based data engineering workflows.
United Kingdom
London fintech clusters prioritize functional programming paradigms for distributed transaction processing and regulatory reporting automation. Financial Conduct Authority guidelines on operational resilience shape language selection toward formally verifiable options. Cambridge and Oxford research institutions influence academic-to-industry pipeline for specialized compiler expertise.
Japan
METI industrial digitization programs accelerate adoption of memory-safe languages for robotics and factory automation systems. Tokyo and Osaka manufacturing conglomerates evaluate Rust for embedded firmware replacement in legacy equipment. Automotive suppliers in Aichi Prefecture navigate ISO 26262 certification timelines for next-generation vehicle software.
Programming Language Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Programming Language Market. Microsoft and Google occupy the upper tier through cloud platform integration and runtime infrastructure control. Mozilla Foundation and Rust Foundation exemplify the specialist tier with foundation-governed open-source models. Competitive moves concentrate on strategic partnerships with hyperscale cloud providers and IDE subscription bundling with enterprise support contracts.
Within the integrated platform tier, Microsoft and Google anchor competitive positioning through development environment and cloud service integration. JetBrains occupies a specialist position with IDE-centric monetization extending Kotlin's footprint beyond mobile into server-side workflows. These three entities exemplify divergent strategies: platform lock-in versus tooling excellence versus language-specific ecosystem cultivation.
| Leading Market Players |
|---|
| JetBrains |
| Mozilla Foundation |
| Microsoft |
| Meta Platforms |
| Apple |
| The Python Software Foundation |
| Rust Foundation |
| Oracle |
| Others |
Value Network & Pricing Analysis
Rust's displacement of C/C++ in safety-critical embedded systems simultaneously concentrates compiler toolchain procurement in Germany and the United States while compressing legacy language support premiums. This substitution dynamic redistributes margin pools toward memory-safe certification tiers and fragments pricing power across foundation-governed open-source distributions and commercial IDE bundling.
Pricing Analysis
Long-term enterprise support contracts dominate commercial procurement, with multi-year IDE subscriptions tethered to cloud platform commitments commanding premium positioning. Pricing stratifies across certified safety-critical tiers, volume-based site licensing, and freemium open-source foundations with paid support overlays. Cost compression in legacy C/C++ maintenance contracts is intensifying as EU AI Act compliance deadlines accelerate migration timelines. Small businesses exhibit highest price sensitivity, optimizing for freelancer marketplace availability and zero-license-cost runtime options, while German automotive OEMs accept substantial premiums for ISO 26262-qualified toolchains.
Supply Chain Analysis
Inventory cycles for compiler qualification and safety certification extend lead times by 18-24 months in automotive verticals. Supply concentrates in the United States for cloud-native runtime infrastructure, Germany for safety-critical embedded toolchains, and India for rapid-deployment scripting ecosystems. Raw material dependencies center on LLVM intermediate representation libraries, formal verification proof engines, and hardware-description language synthesis tools. Single-source vulnerability in LLVM's optimization monopoly creates systemic risk for languages without alternative backend strategies. Distribution runs through hyperscaler marketplaces, direct enterprise licensing, and open-source package repositories with commercial support overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs in developer tooling ecosystems and regulatory entrenchment in safety-critical certification pathways protect incumbent positions. Network effects in language-specific package repositories compound these barriers.
For Market Incumbents: Consolidate control over compiler toolchain distribution through hyperscaler marketplace integration and embedded safety certification partnerships. Deepen vertical integration into formal verification services to capture ISO 26262 qualification timelines that lock out unvalidated competitors. Mozilla Foundation's stewardship model demonstrates how foundation governance can neutralize enterprise liability concerns while preserving ecosystem openness against commercial IDE bundling threats. For New Entrants and Emerging Players: EU AI Act algorithmic transparency fast-tracks offer the most penetrable entry vector for statically typed languages with embedded audit capabilities. Target Indian SaaS startups and German industrial IoT mid-market segments where legacy entrenchment remains shallow and compliance-driven procurement creates greenfield opportunity. Lead with WebAssembly runtime portability as the primary go-to-market angle, enabling language-agnostic deployment across browser, server, and edge environments without recompilation friction. For Investors and Strategic Acquirers: The market sits at a compliance-acceleration phase that favors specialist compiler infrastructure and safety-critical certification capabilities over general-purpose language proliferation. Long-term viability hinges on regulatory trajectory durability across the EU AI Act implementation window and subsequent jurisdictional harmonization. Acquisition target archetype: vertically integrated tooling vendors with captive formal verification expertise and established automotive or fintech customer concentration. Monitor NHTSA and KBA safety software guidance evolution as the critical inflection signal for memory-safety mandate geographic expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Compiler Toolchain Integration | Hyperscaler marketplace placement captures enterprise procurement workflows tied to Azure and AWS commitments. |
| Safety Certification Investment | ISO 26262 qualification timelines create 18-24 month competitive moats in German automotive supply chains. |
| WebAssembly Runtime Maturation | Cross-platform bytecode execution enables language-agnostic deployment without recompilation overhead. |
| Formal Verification Service Expansion | Coq and Isabelle expertise commands premium positioning in Frankfurt financial services compliance architecture. |
| Foundation Governance Strengthening | Rust Foundation's security review embedding demonstrates liability-neutral commercialization for enterprise adoption. |
Research Methodology
Operator-level perspectives from compiler infrastructure engineers, platform engineering leads at SaaS providers, automotive software qualification officers, and open-source foundation governance directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation across SEC filings from hyperscaler cloud providers, LLVM project documentation, EU AI Act regulatory impact assessments, and ISO 26262 certification body disclosures. Bottom-up language adoption modeling triangulated against top-down enterprise IT spend allocations across the analysis window.
Sensitivity analysis tested forecast robustness across regulatory implementation timing scenarios and talent supply elasticity assumptions. Segmentation dimensions modeled include language type, deployment paradigm, end-user organization scale, vertical compliance intensity, and regional cloud-native cluster maturity. CAGRs derived from installed base rotation rates and greenfield project language selection patterns, with specific inputs from machine learning pipeline standardization velocity and embedded systems safety-migration timelines.
Decision-makers should treat outputs as directional under sustained EU AI Act enforcement and stable hyperscaler capex commitment assumptions; material deviation in regulatory harmonization or cloud platform consolidation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Online Assessment Software Market
Software & Services
Taxi Booking Software Market
Software & Services
Global Architecture Software Market
Software & Services
Global Open Source Services Market
Software & Services
Global Inspection Management Software Market
Software & Services
Global Performance Appraisal Software Market
Software & Services
Mobile Tracking Software Market
Software & Services
UK Applicant Tracking System Market
Software & Services
Global Diagram Software Market
Software & Services
Video Communications Software Market
Software & Services
Software Consulting Market
Software & Services
Automotive Operating Systems Market
Software & Services
Payroll - HR Solutions and Services Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
BFSI Software Market
Software & Services
Global Human Capital Management Software Market