
 Surgical Drapes Market | 2026-2036
Surgical Drapes Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Drapes Market Intelligence
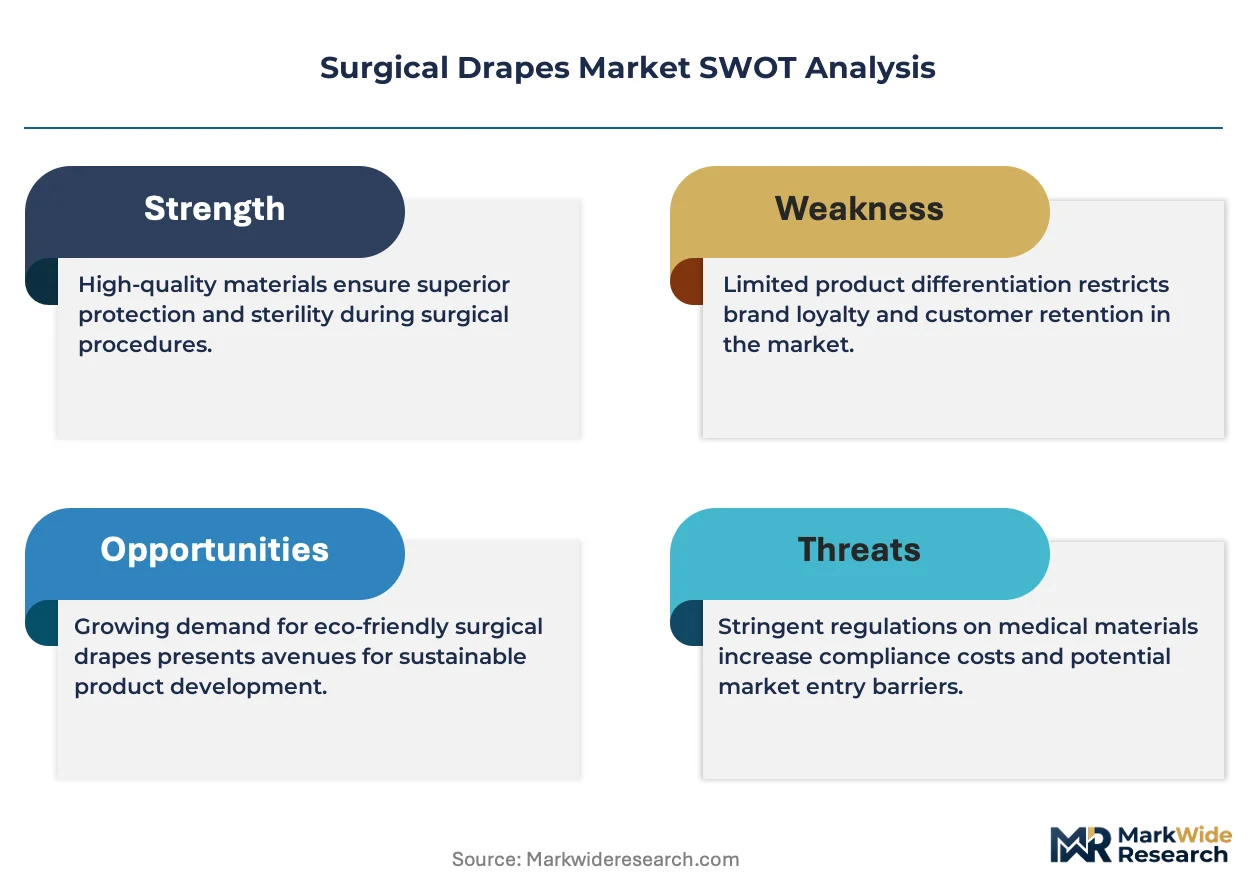
ASTM F2101-level bacterial filtration efficiency is redrawing competitive positioning in surgical drapes. Cardinal Health leverages captive nonwoven manufacturing to sustain cost leadership across high-volume disposable lines. Mölnlycke Health Care anchors premium positioning through proprietary breathable film laminates for cardiothoracic applications. 3M differentiates via adhesive incise drape technology that integrates antimicrobial layers directly into the sterile field.
Surgical drapes are sterile barrier fabrics engineered to block microbial transmission during operative procedures, typically constructed from spunbond-meltblown-spunbond polypropylene achieving hydrostatic head resistance exceeding 50 cm. Their primary purpose is maintaining aseptic conditions by isolating the surgical site from environmental contaminants and patient flora. Disposable drapes now dominate procurement budgets due to elimination of laundering validation costs, while reusable cotton-polyester blends retain share in orthopedic suites where drape heaviness reduces field displacement. Microporous film segments command margin premiums in cardiothoracic applications where simultaneous moisture vapor transmission and viral barrier performance are mandatory.
FDA quality system regulation and ASTM F2100 standards govern barrier classification and biocompatibility testing for surgical drapes marketed in the United States. The EPA additionally oversees antimicrobial additive claims incorporated into incise drape adhesives. These frameworks elevate compliance costs for new entrants while rewarding manufacturers with established 510(k) clearance pathways and documented sterilization validation. Stakeholders must monitor evolving FDA guidance on pyrogenicity testing as single-use sterile drapes displace legacy reusable systems in outpatient settings.
Market Dynamics
Hospital consolidation in the United States is compressing supplier counts and forcing drape manufacturers to validate barrier performance across standardized surgical pack specifications rather than individual product lines.
Growth Catalysts
- FDA Quality System Regulation:Updated validation requirements for barrier performance are accelerating replacement of legacy reusable systems with disposable sterile drapes in ambulatory surgical centers.
- Spunbond-meltblown-spunbond polypropylene:Advances in nonwoven lamination technology are enabling simultaneous hydrostatic resistance and moisture vapor transmission for cardiothoracic applications.
- United States hospital procurement:Consolidation of health system purchasing is concentrating demand volume and rewarding manufacturers with established 510(k) clearance pathways.
Market Restraints
- Polypropylene resin volatility:Feedstock cost swings compress margin predictability for high-volume disposable drape manufacturers dependent on petrochemical supply chains.
- Reusable cotton-polyester blends:Orthopedic suites retain preference for heavier drapes that resist field displacement, creating substitution pressure in procedural segments.
- EPA antimicrobial claim oversight:Registration requirements for incise drape adhesives with integrated antimicrobial layers extend product development timelines and elevate compliance expenditure.
Strategic Opportunities
- India ambulatory surgery expansion:CDSCO regulatory harmonization with ISO 13485 standards is opening pathways for barrier fabric manufacturers to serve price-sensitive outpatient facilities.
- Breathable film-cotton hybrid laminates:Convergence of single-use convenience with textile-like drape stability addresses unmet demand in orthopedic and neurosurgical settings.
- Direct-to-hospital distribution platforms:E-procurement portals are disintermediating traditional medical-surgical distributors and enabling margin capture by specialized drape manufacturers.
Industry Challenges
- Pyrogenicity testing validation:Evolving FDA guidance on endotoxin limits for single-use sterile drapes requires retooling of quality assurance protocols and extended certification timelines.
- Barrier performance standardization:Misalignment between ASTM F2100 and EN 13795 classifications complicates product portfolio rationalization for manufacturers serving multiple regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Drapes Market |
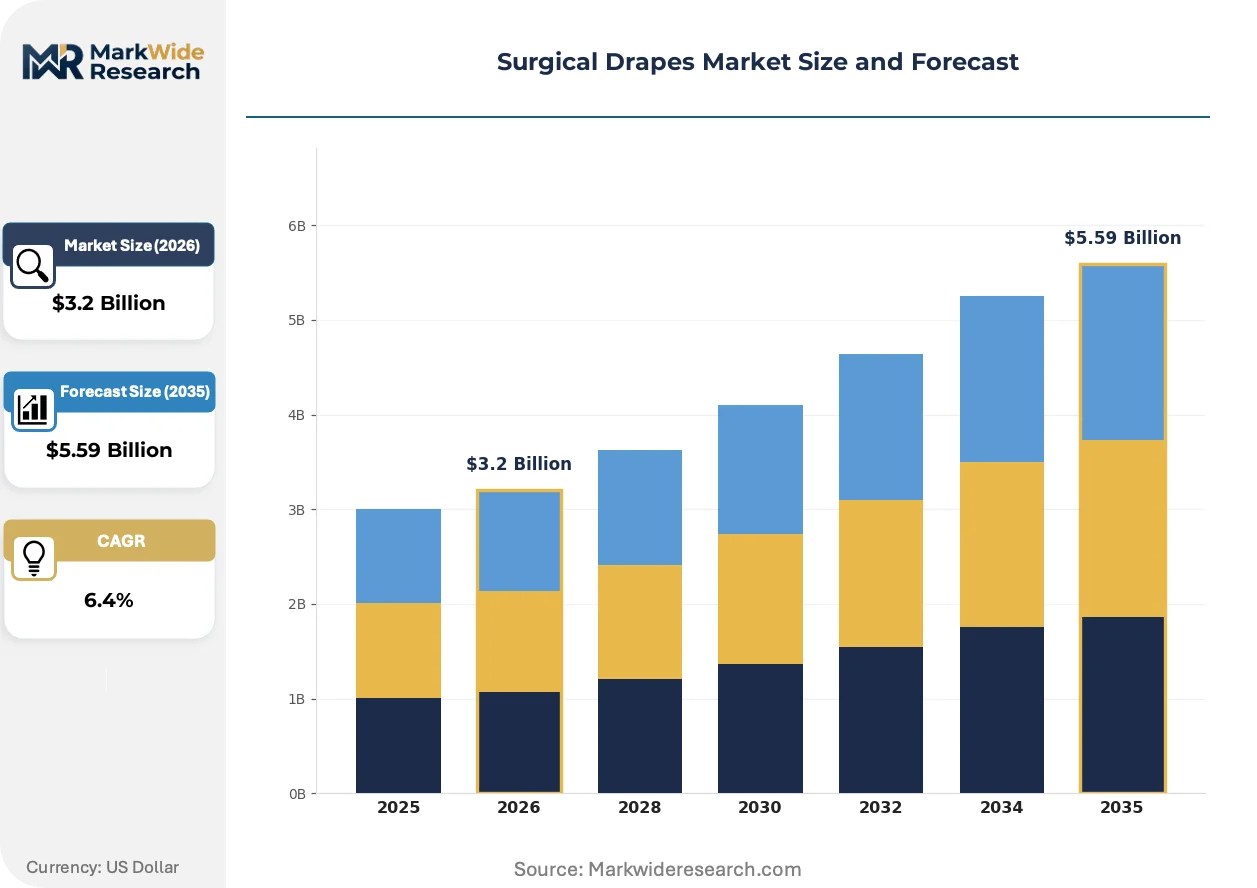
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Drapes, Disposable Drapes, Sterile Drapes, Non-Sterile Drapes Material: Polypropylene, Polyester, Cotton, Microporous Film Application: General Surgery, Orthopedic Surgery, Cardiothoracic Surgery, Gynecological Surgery End User: Hospitals, Surgical Centers, Clinics, Research Institutions |
| Companies Covered | Cardinal Health, Medline Industries, 3M, Mölnlycke Health Care, Steris, Paul Hartmann AG, Owens & Minor, Standard Textile, Priontex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Drapes Market Strategic Shifts & Innovations
Barrier fabric technology is bifurcating between commodity spunbond lines and engineered microporous laminates, with regulatory pressure on infection control protocols accelerating material specification divergence across procedural categories.
Antimicrobial-integrated incise drape adhesives are fragmenting the sterile field preparation segment. Cardiothoracic surgical teams are adopting these films at accelerated pace to reduce surgical site contamination. The technology is fragmenting competitive positioning between adhesive specialists and traditional textile barrier manufacturers.
EU MDR technical documentation requirements are elevating biocompatibility testing burdens for surgical drapes marketed in Europe. Manufacturers must now submit clinical evaluation reports and post-market surveillance data that exceed legacy Medical Device Directive standards. Smaller European drape suppliers are responding by withdrawing from Class I sterile barrier categories rather than absorbing compliance costs.
Health system value analysis committees are consolidating supplier relationships and unbundling after-sales technical support from product pricing. Integrated delivery networks in the United States are replacing fragmented purchasing across individual facilities with centralized contracts spanning multiple surgical specialties. This behavioral shift is most visible in the southeastern United States where hospital merger activity has concentrated buying power among three dominant health systems.
Surgical Drapes Market Segmentation
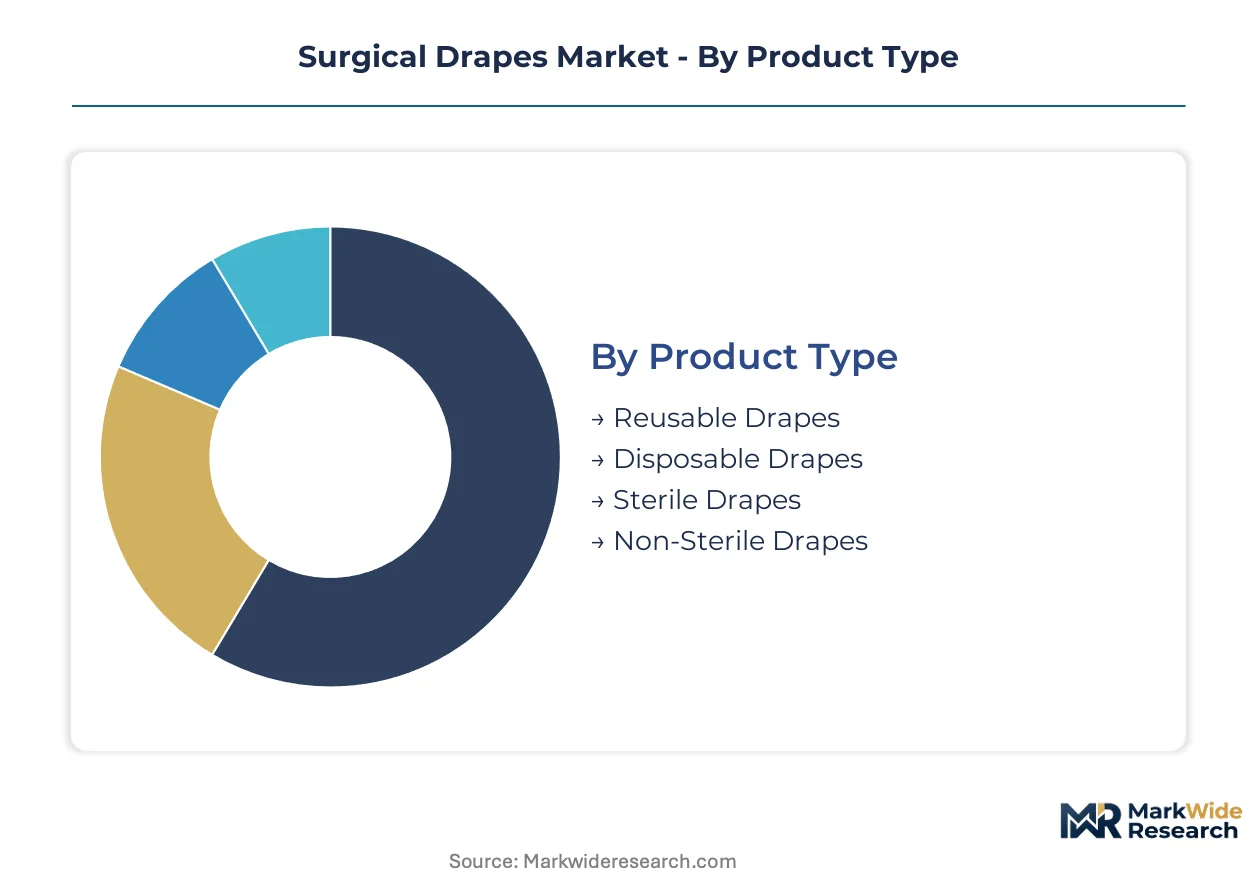
Surgical drapes segmentation reflects divergent supply chain logics across infection control protocols, material science capabilities, and procedural specialization. Manufacturers configure product portfolios around sterilization validation costs, barrier performance tiers, and health system procurement consolidation patterns.
Product Type:
Disposable drapes dominate domestic hospital procurement in the United States, while reusable systems retain export concentration toward cost-sensitive Asian and Latin American markets.
- Reusable Drapes:Woven cotton-polyester blends withstand industrial laundering cycles exceeding 100 uses. Orthopedic suites in Germany and Japan specify heavier 180-200 gsm constructions that resist field displacement during joint replacement procedures. Laundering validation costs and water/energy expenditure constrain expansion.
- Disposable Drapes:Spunbond-meltblown-spunbond polypropylene achieves hydrostatic head resistance above 50 cm with single-use sterility assurance. United States ambulatory surgical centers are converting procurement entirely to disposable formats as FDA quality system regulations tighten validation requirements for reusable systems.
- Sterile Drapes:Pre-sterilized barrier fabrics packaged for immediate operative field deployment. Central sterile supply departments in consolidated US health systems standardize on sterile formats to eliminate in-house sterilization capacity.
- Non-Sterile Drapes:Unsterilized barrier fabrics requiring terminal sterilization at point of use. Research institutions and veterinary surgical facilities in India and Brazil absorb the sterilization burden to capture lower unit pricing.
Disposable drapes hold the largest share; momentum sits with sterile pre-packaged formats.
Material:
Material selection stratifies by margin tier, with commodity polypropylene serving high-volume applications and engineered laminates commanding premium positioning in cardiothoracic segments.
- Polypropylene:Spunbond and meltblown nonwoven structures provide cost-efficient bacterial filtration. Hospital procurement in the United States concentrates demand for 40-60 gsm standard-weight polypropylene across general surgery applications.
- Polyester:Woven and nonwoven polyester offers dimensional stability and chemical resistance. Reusable drape manufacturers in Italy and Turkey specify polyester-rich blends for industrial laundering durability.
- Cotton:Natural fiber construction provides textile-like drape stability and patient comfort. Orthopedic and neurosurgical teams in France and Spain retain cotton-polyester hybrids for procedures requiring heavy field anchoring.
- Microporous Film:Expanded polytetrafluoroethylene or polyethylene laminates achieve simultaneous viral barrier and moisture vapor transmission. Cardiothoracic surgical centers in the United States and Germany specify breathable film constructions for lengthy procedures where perspiration management is critical.
Polypropylene dominates volume; microporous film is climbing the fastest.
Application:
Application segmentation tracks procedural complexity tiers, with general surgery representing installed base maintenance and cardiothoracic applications driving specification upgrades.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair procedures utilize standard barrier protection. Community hospitals across the United States, India, and Brazil constitute the core demand base for commodity drape specifications.
- Orthopedic Surgery:Joint replacement and spinal procedures require heavy drape stability and extended sterile field duration. Academic medical centers in the United States and Germany specify reinforced laminates with adhesive incise films for hip and knee arthroplasty.
- Cardiothoracic Surgery:Open-heart and thoracic procedures demand the highest barrier performance tier with breathable film technology. Tertiary care centers in the United States, Germany, and Japan concentrate procurement of premium microporous laminates.
- Gynecological Surgery:Cesarean section and hysterectomy procedures utilize specialized fenestrated drapes with fluid collection pouches. Maternity hospitals in Brazil, Mexico, and India drive volume for obstetric-specific drape configurations.
General surgery holds the largest share; cardiothoracic is gaining share fastest.
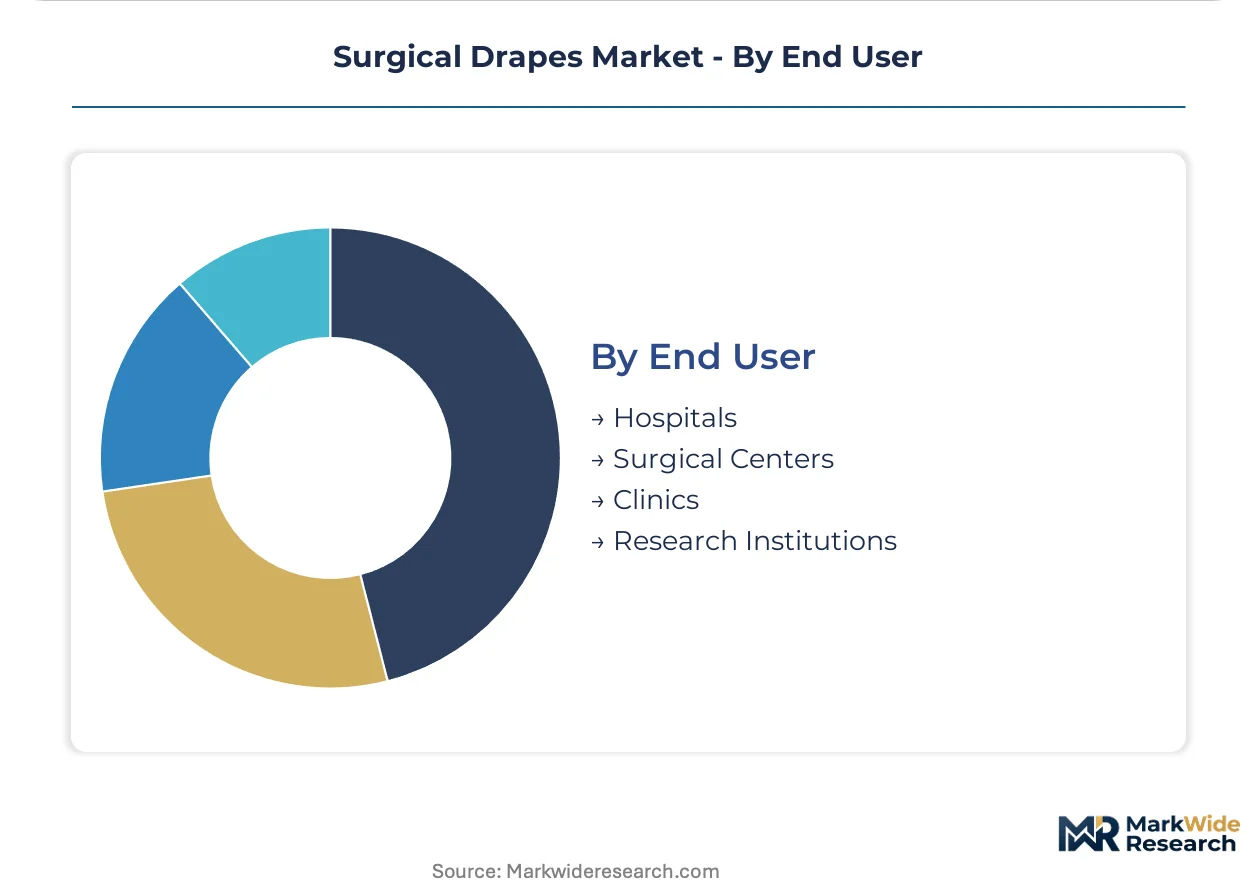
End User:
End user concentration reflects healthcare infrastructure hierarchy, with hospitals anchoring premium specification demand and surgical centers driving disposable format conversion.
- Hospitals:Integrated delivery networks in the United States consolidate procurement across surgical specialties. Tertiary facilities specify tiered drape portfolios spanning commodity general surgery to premium cardiothoracic laminates.
- Surgical Centers:Ambulatory facilities in the United States, United Kingdom, and Australia are eliminating reusable systems entirely. Single-use sterile drapes align with streamlined infection control protocols and reduced capital equipment requirements.
- Clinics:Minor procedure facilities in India, Southeast Asia, and Latin America balance cost constraints with basic barrier requirements. Non-sterile drape formats predominate with on-site sterilization or antiseptic field preparation.
- Research Institutions:Veterinary and experimental surgical facilities utilize non-standard drape configurations. Academic medical centers in the United States and Europe specify specialized sizes and fenestration patterns for translational research applications.
Hospitals hold the largest share; surgical centers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrier fabric manufacturing clusters in Ohio and North Carolina supply integrated delivery networks across the southeastern United States. Hospital consolidation in Georgia and Florida concentrates procurement volume among three dominant health systems.
United States
Ambulatory surgical centers in Texas and Florida are eliminating reusable systems entirely. FDA quality system regulations tighten validation requirements for barrier performance. Cardinal Health maintains captive nonwoven manufacturing in Ohio to serve consolidated health system contracts.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia specify premium microporous laminates for cardiothoracic applications. EU MDR technical documentation requirements elevate biocompatibility testing burdens for sterile barrier categories. Mölnlycke Health Care anchors manufacturing in the Gothenburg corridor to supply German tertiary facilities.
India
Outpatient surgical facilities in Maharashtra and Karnataka absorb sterilization burdens to capture lower unit pricing on non-sterile formats. CDSCO regulatory harmonization with ISO 13485 standards opens pathways for barrier fabric manufacturers. Mumbai-based distributors serve price-sensitive clinics across western India.
Japan
Orthopedic suites in Osaka and Tokyo retain preference for heavier 180-200 gsm cotton-polyester constructions. PMDA oversight aligns with international barrier performance standards for imported disposable formats. Nagoya medical device clusters source specialized fenestrated drapes for domestic manufacturers.
Brazil
Maternity hospitals in São Paulo and Rio de Janeiro drive volume for obstetric-specific drape configurations with fluid collection pouches. ANVISA registration requirements extend product development timelines for imported barrier fabrics. Local converters in Minas Gerais assemble surgical packs for southeastern health networks.
Surgical Drapes Market Key Industry Players
Concentration sits with diversified health care conglomerates possessing captive nonwoven manufacturing and established 510(k) clearance pathways. Mid-scale regional fabricators compete on price-sensitive formats for Asian and Latin American markets. Strategic archetypes include integrated conglomerates with backward polymer control, specialized barrier film engineers, and regional laundering-service operators. Competitive moves center on health system contract consolidation and sterile-format portfolio expansion.
Among North American integrated suppliers, Cardinal Health and Medline Industries exemplify scale-driven archetypes with distribution infrastructure spanning consolidated hospital networks. 3M occupies a position among adhesive technology specialists leveraging antimicrobial incise film differentiation. These three anchors represent the dominant competitive vectors: manufacturing scale, regulatory clearance depth, and materials science specialization.
| Leading Market Players |
|---|
| Cardinal Health |
| Medline Industries |
| 3M |
| Mölnlycke Health Care |
| Steris |
| Paul Hartmann AG |
| Owens & Minor |
| Standard Textile |
| Priontex |
| Others |
Cost & Logistics Intelligence
Multi-year health system contracts lock in both polypropylene supply access and price visibility for drape manufacturers serving consolidated US networks. These arrangements transfer feedstock volatility risk from converters to resin suppliers while anchoring procurement budgets against spot market swings.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across the surgical drapes landscape. Three-tier pricing structure across premium microporous laminates, standard SMS polypropylene, and economy non-sterile formats separates cardiothoracic applications from general surgery and veterinary procedures. Price differentiation hinges on barrier performance certification and sterilization validation depth, with academic medical centers least sensitive and outpatient clinics in India and Brazil most responsive to unit cost. Cost compression in standard-weight polypropylene is intensifying because hospital consolidation forces volume discounts across standardized surgical pack specifications.
Supply Chain Analysis
Inventory buffers stretch 60-90 days for spunbond-meltblown-spunbond polypropylene as manufacturers balance just-in-time health system delivery against resin price volatility. Supply concentrates in the United States, Germany, and China, with Ohio and North Carolina hosting captive nonwoven production for integrated delivery networks. Raw material flows draw from petrochemical feedstocks, medical-grade polypropylene resin, and adhesive antimicrobial additives. Single-source vulnerability runs through concentrated resin suppliers in the Gulf Coast petrochemical corridor. Distribution runs through specialized medical-surgical distributors and direct e-procurement portals disintermediating traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from reusable cotton-polyester blends in orthopedic suites where drape stability outweighs convenience. Defense requires locking in barrier performance advantages while neutralizing cost gaps in retained-use segments.
For Market Incumbents: Shield market position by deepening backward integration into polypropylene resin conversion and accelerating sterile-format portfolio expansion. Cardinal Health's captive Ohio manufacturing exemplifies the defensive moat against commodity import pressure. Prioritize 510(k) pathway maintenance as regulatory validation costs rise under updated FDA quality system requirements.
For New Entrants and Emerging Players: Lead with breathable film-cotton hybrid laminates targeting orthopedic and neurosurgical white space where neither pure disposable nor legacy reusable formats fully satisfy demand. India's CDSCO-harmonized outpatient facilities offer the most penetrable geography for price-sensitive sterile drape conversion. Pursue direct-to-hospital e-procurement distribution to bypass entrenched medical-surgical distributor relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale regional fabricators possessing established sterilization validation infrastructure but lacking health system contract scale. Long-term viability hinges on consolidation capture as EU MDR compliance costs force smaller European suppliers from Class I sterile barrier categories. Watch pyrogenicity testing guidance evolution as the inflection signal for quality assurance retooling investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| 510(k) Clearance Pathway Investment | FDA validation depth determines hospital contract eligibility and pricing tier access. |
| Captive Nonwoven Manufacturing Scale-Up | Backward polymer control insulates margin against resin volatility and import competition. |
| Sterile Format Portfolio Expansion | Pre-sterilized packaging eliminates in-house hospital sterilization capacity requirements. |
| Direct-to-Hospital E-Procurement Platform | Digital distribution disintermediates traditional medical-surgical distributors and captures margin. |
| Breathable Film Laminate R&D | Microporous technology commands premium positioning in cardiothoracic barrier applications. |
Research Approach
Operator-level perspectives from hospital purchasing committee directors, GPO contracts managers, biomedical engineers, and central sterile supply coordinators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, hospital procurement databases, GPO contract disclosures, and customs trade records for polypropylene resin flows. Bottom-up unit demand modeling triangulated against top-down health system expenditure analysis.
Sensitivity analysis tested barrier performance tier adoption rates and resin price elasticity across the projection horizon. Segmentation dimensions modeled include product type, material composition, application complexity, and end-user facility tier. CAGRs derived from procedural volume trajectories, infection control protocol evolution, and health system consolidation patterns. Forecast inputs incorporated ambulatory surgery expansion rates and regulatory harmonization timelines for emerging markets.
Underlying assumptions cover FDA quality system regulation stability and polypropylene supply chain continuity, with deviation risk concentrated in pyrogenicity testing guidance evolution and EU MDR technical documentation burden expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Antimicrobial Textiles Market
Medical and Hygiene Textiles
Feminine Wipes Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
Arm Pouches Market
Medical and Hygiene Textiles
North America Sanitary Napkin Market
Medical and Hygiene Textiles
Sanitary Napkins Machine Market
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Global Diabetic Socks Market
Medical and Hygiene Textiles
Europe Adult Diaper Market
Medical and Hygiene Textiles
Period Patch Market
Medical and Hygiene Textiles
Tissue Towel Market
Medical and Hygiene Textiles
Antimicrobial Polyamide Textiles Market
Medical and Hygiene Textiles
Breast Pads Market
Medical and Hygiene Textiles
Period Panties Market