
 Methacrylic Acid Market | 2026-2036
Methacrylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Methacrylic Acid Market Intelligence
Asian petrochemical producers is restructuring methacrylic acid capacity allocation toward higher-purity grades serving electronics and medical applications. LG Chem leverages its integrated C4 feedstock position to sustain cost-competitive output across Northeast Asian markets. Dow anchors North American supply through its Gulf Coast manufacturing complex, while BASF SE competes via specialized high-purity grades targeting European pharmaceutical and optical polymer customers.
Methacrylic acid, an alpha-beta unsaturated carboxylic acid with the formula CH2=C(CH3)COOH, polymerizes readily to form polymethacrylates prized for optical clarity, weather resistance, and dimensional stability. Industrial production proceeds primarily via acetone cyanohydrin-based or C4 oxidation routes yielding grades differentiated by purity thresholds from technical grade through electronic-grade specifications. The paints and coatings end-use segment occupies the largest volume share as architectural and automotive waterborne formulations displace solvent-borne alternatives. High-purity product grades command disproportionate margin contribution despite smaller tonnage as semiconductor lithography and medical device applications impose stringent metal-ion and moisture specifications.
EPA regulations under the Toxic Substances Control Act govern methacrylic acid handling thresholds and emission controls in United States manufacturing facilities, while REACH registration requirements in Europe mandate comprehensive toxicity dossiers affecting import and production volumes. China's MEE enforces increasingly stringent volatile organic compound discharge standards at petrochemical complexes producing methacrylic acid and derivatives. Stakeholders must monitor regulatory divergence between jurisdictions where purity certification regimes and carbon-intensity disclosures are becoming decisive factors in supplier selection and long-term contract negotiations.
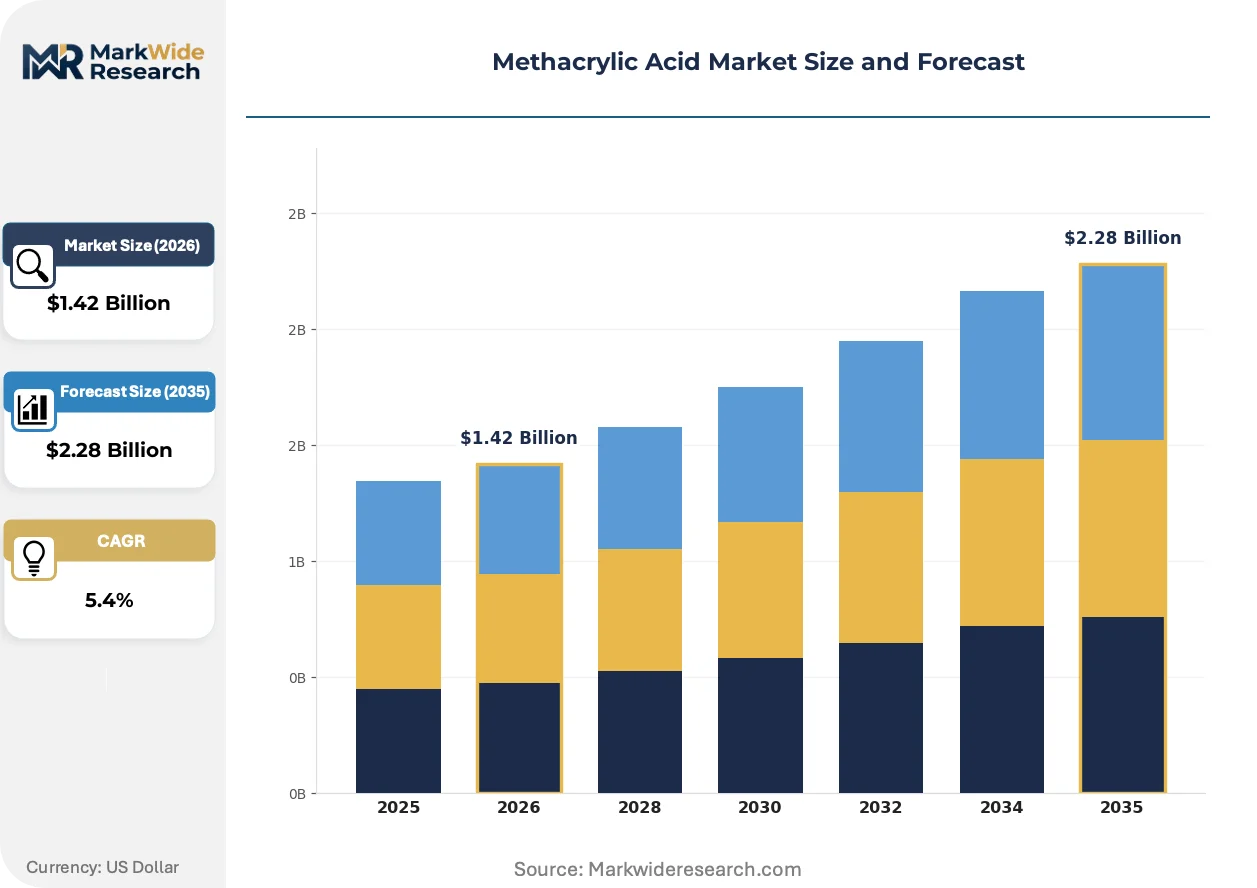
Market Dynamics
Waterborne coating formulations are displacing solvent-borne systems across architectural and automotive end-uses, pulling methacrylic acid demand toward higher-purity emulsion grades while tightening metal-ion specifications from semiconductor lithography customers.
Growth Catalysts
- REACH purity mandates:European ECHA registration requirements for toxicity dossiers are filtering technical-grade suppliers and concentrating qualified production among integrated petrochemical complexes capable of electronic-grade certification.
- Semiconductor lithography expansion:Advanced packaging nodes below 7nm require methacrylic acid-derived photoresists with sub-ppb metal contamination thresholds, creating specification premiums that reward purification technology investment.
- C4 feedstock integration:Northeast Asian crackers with captive isobutylene supply are achieving cost positions that sustain margin through acetone cyanohydrin route volatility.
Market Restraints
- Acetone cyanohydrin input volatility:Hydrogen cyanide supply constraints and acetone price swings transmit directly to non-integrated methacrylic acid producers lacking C4 oxidation alternatives.
- Capacity concentration in China:Domestic Chinese producers control disproportionate technical-grade volume, exposing import-dependent regions to freight cost surges and tariff friction.
- Substitution by bio-based acrylics:Fermentation-derived 3-hydroxypropionic acid pathways are achieving purity thresholds that challenge methacrylic acid in select coating applications.
Strategic Opportunities
- India specialty chemicals investment:PLI scheme incentives for electronic chemicals manufacturing are attracting methacrylic acid purification joint ventures to serve domestic semiconductor fabrication capacity expansion.
- Medical device polymer demand:Orthopedic cement and dental applications require USP-grade methacrylic acid with biocompatibility certification that commands 3-4x technical-grade pricing.
- Carbon intensity disclosure requirements:EU CSRD mandates for Scope 3 emissions reporting are creating preference for European-produced methacrylic acid with verified low-carbon process credentials.
Industry Challenges
- Electronic-grade certification timelines:Semiconductor customer qualification protocols require 18-24 month stability data and metal-ion testing that delays revenue realization for new purification investments.
- Legacy coating formulation expertise gaps:Waterborne emulsion chemistry demands polymer science capabilities distinct from solvent-borne acrylic experience, constraining technical service capacity at regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methacrylic Acid Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Low Purity, Technical Grade, Specialty Grades End Use Industry: Paints & Coatings, Adhesives, Plastics, Textiles Distribution Channel: Direct Sales, Distributors, Online Sales, Wholesalers Application: Emulsions, Resins, Films, Thermoplastics |
| Companies Covered | Formosa Korea, LG Chem, Dow, Nippon Shokubai, MITSUBISHI GAS CHEMICAL COMPANY, INC, BASF SE, KURARAY CO., LTD, PTT Asahi Chemical, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methacrylic Acid Market Strategic Shifts & Innovations
Process intensification and digital quality control systems are compressing batch-to-batch variation in high-purity methacrylic acid production while regulatory disclosure requirements reshape supplier-customer data exchange protocols.
Continuous flow oxidation reactors are integrating real-time spectroscopic monitoring to maintain tight control over unsaturated acid purity profiles. Semiconductor photoresist manufacturers in Taiwan and South Korea are adopting these supply streams at accelerated qualification pace. The technology is integrating process analytical technology that reduces off-specification batches and enables just-in-time inventory models for lithography chemical supply chains.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon replacement in foam blowing agents, indirectly pressuring methacrylic acid derivatives used in insulation polymer formulations. German chemical complexes are retrofitting C4 oxidation trains to capture and recycle byproduct streams that previously vented fluorinated compounds. Coating formulators in Benelux markets are most affected, with reformulation timelines compressed to meet 2027 GWP thresholds.
Specification-driven procurement is consolidating methacrylic acid purchasing among coating manufacturers with dedicated analytical laboratories capable of certificate-of-analysis verification. Regional distributors without in-house testing infrastructure are losing position to direct mill relationships. The shift is most visible in German automotive OEM supply chains, where Tier-1 suppliers now mandate supplier site audits and batch traceability systems.
Methacrylic Acid Market Segmentation
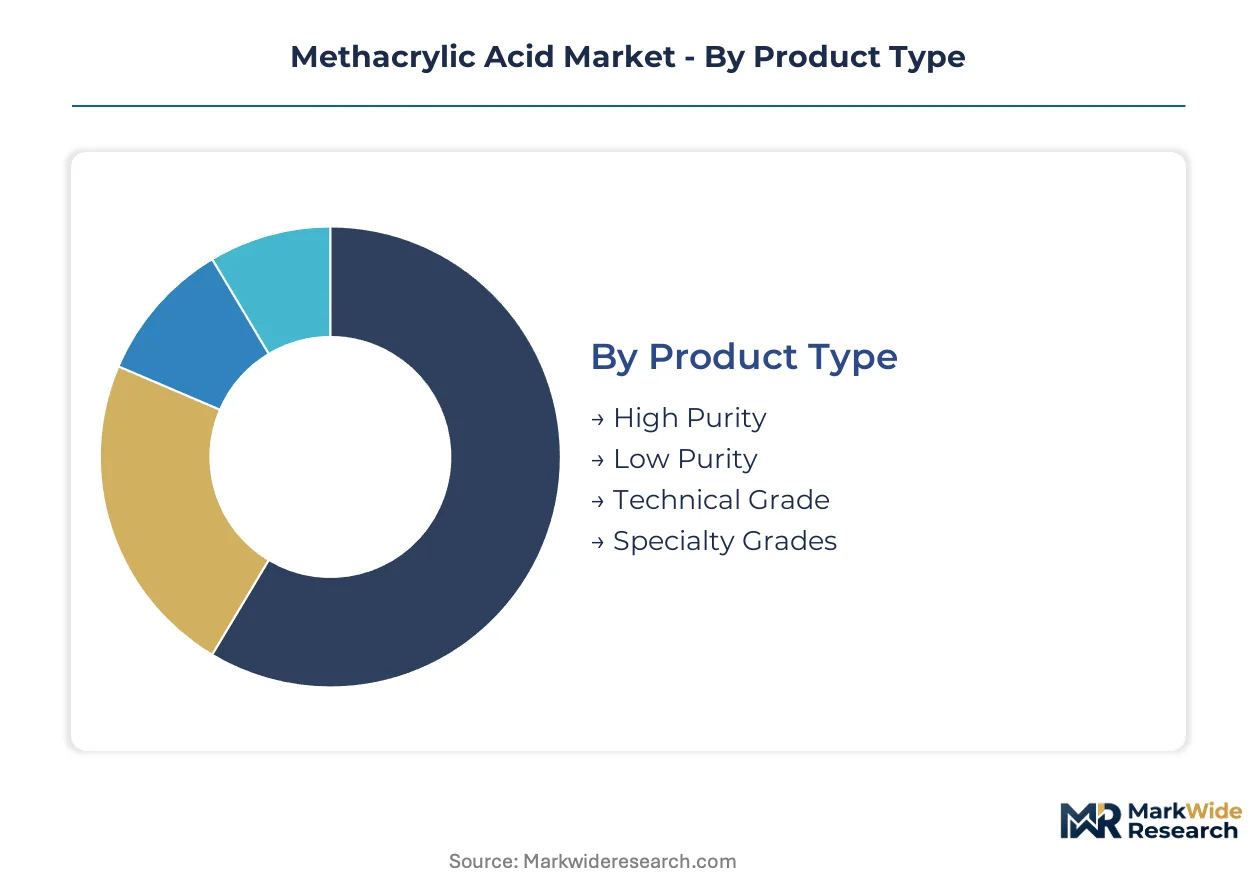
Methacrylic acid demand fragments sharply across purity tiers and end-use specifications. Semiconductor lithography and medical device manufacturers impose metal-ion thresholds that technical-grade suppliers cannot meet, while coating formulators prioritize cost-efficient emulsion grades.
Product Type:
Buyers in this category differentiate primarily by contamination tolerance and certification burden.
- High Purity:Electronic-grade material with sub-ppb metal-ion specifications serves semiconductor photoresist and lithography chemical manufacturers. Taiwan and South Korea fabs demand 18-24 month qualification protocols that lock in supplier relationships. REACH registration dossiers and ECHA toxicity data requirements filter out non-integrated producers lacking purification infrastructure.
- Specialty Grades:USP-grade methacrylic acid for orthopedic cement and dental applications carries biocompatibility certification commanding substantial premiums over technical material. German pharmaceutical polymer compounders and Japanese medical device manufacturers dominate procurement.
- Technical Grade:Standard industrial purity for general-purpose polymethacrylate production.
- Low Purity:Cost-optimized material for bulk adhesive and construction applications with relaxed specification requirements.
Technical grade leads volumes today; high purity is gaining share fastest.
End Use Industry:
Application maturity determines margin structure and contract duration across these verticals.
- Paints & Coatings:Waterborne architectural and automotive formulations displace solvent-borne systems, pulling demand toward emulsion-grade methacrylic acid. EPA VOC discharge standards and China's MEE regulations tighten emission thresholds at manufacturing facilities. German automotive OEM supply chains now mandate supplier site audits and batch traceability systems.
- Plastics:Optical clarity and weather resistance specifications in polymethacrylate sheet and molding compounds serve signage, lighting, and automotive glazing. Japanese LED diffuser panel manufacturers and German lighting component producers anchor demand.
- Adhesives:Pressure-sensitive and structural bonding applications leverage methacrylic acid copolymers for tack and durability.
- Textiles:Sizing agents and fiber modification chemicals represent a smaller volume outlet with price-sensitive procurement.
Paints and coatings anchors volume concentration; plastics climbs the fastest on optical polymer expansion.
Distribution Channel:
Channel selection reflects buyer technical capability and inventory management preferences.
- Direct Sales:Integrated petrochemical producers like LG Chem and Dow supply high-volume coating manufacturers and semiconductor chemical formulators through mill-direct relationships. Specification-driven procurement with certificate-of-analysis verification requirements favors this channel for electronic and medical grades.
- Distributors:Regional chemical distributors serve mid-tier coating formulators and adhesive compounders lacking in-house analytical laboratories. German automotive supply chains increasingly bypass this tier for Tier-1 supplier direct relationships.
- Online Sales:Digital platforms capture small-laboratory and research-scale procurement with credit-card transactions and rapid fulfillment.
- Wholesalers:Bulk material aggregators serve construction adhesive and general industrial accounts with standardized technical grades.
Direct sales dominates value capture; distributor share compresses as qualification requirements intensify.
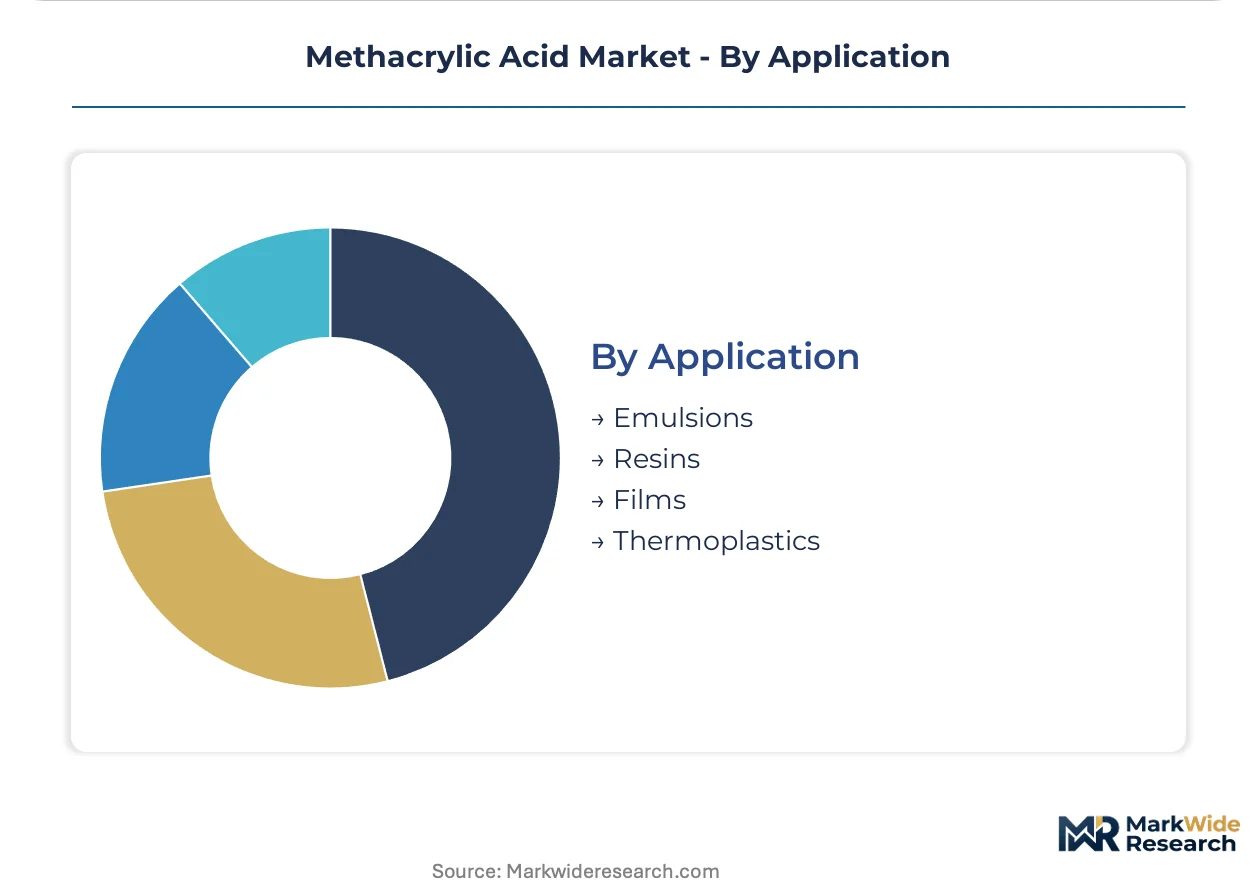
Application:
Formulation chemistry determines purity requirements and supplier switching costs.
- Emulsions:Waterborne acrylic emulsions for architectural and automotive coatings require carefully controlled particle size distribution and surfactant compatibility. BASF SE and Dow compete via specialized high-purity emulsion grades targeting European and North American coating manufacturers. Legacy solvent-borne formulation expertise gaps constrain technical service capacity at regional distributors.
- Resins:Solution and solid acrylic resins for industrial coatings and printing inks leverage methacrylic acid for adhesion and weatherability.
- Thermoplastics:Extruded and injection-molded polymethacrylate components demand thermal stability and optical clarity.
- Films:Cast and oriented polymethacrylate films serve protective and optical applications with thickness and haze specifications.
Emulsions holds the largest volume position; thermoplastics shows steepest expansion trajectory on medical and optical demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting methacrylic acid investment toward jurisdictions with clearer certification pathways and lower cost-of-compliance for high-purity production. Producers are relocating purification capacity to exploit gaps between REACH dossier requirements and emerging market disclosure standards.
China
Domestic producers dominate technical-grade volume serving waterborne coating formulators across the Yangtze River Delta. MEE volatile organic compound discharge standards are tightening emission thresholds at petrochemical complexes in Ningbo and Shanghai. Capacity expansion concentrates in Shandong Province where integrated C4 oxidation trains achieve feedstock cost advantages.
Germany
Specialized high-purity grades for pharmaceutical and optical polymer customers anchor European demand concentration. REACH registration dossiers and ECHA toxicity data requirements filter non-integrated suppliers lacking electronic-grade certification infrastructure. The Ludwigshafen chemical cluster hosts purification investments targeting semiconductor lithography qualification protocols.
United States
Gulf Coast manufacturing complexes supply coating manufacturers and semiconductor chemical formulators through mill-direct relationships. EPA regulations under the Toxic Substances Control Act govern handling thresholds and emission controls at Texas and Louisiana facilities. Dow anchors North American supply from its integrated petrochemical operations.
South Korea
Advanced packaging nodes below 7nm drive demand for photoresists with sub-ppb metal contamination thresholds. LG Chem leverages integrated C4 feedstock positions to sustain cost-competitive output across Northeast Asian markets. Seoul Capital Area fabs are accelerating qualification pace for continuous flow oxidation reactor supply streams.
Japan
LED diffuser panel manufacturers and medical device compounders anchor optical polymer and USP-grade procurement. METI industrial standards shape purity certification requirements for orthopedic cement and dental applications. The Osaka-Kobe chemical corridor concentrates specialty grade production serving domestic pharmaceutical polymer customers.
Methacrylic Acid Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-purity specialization and regional joint ventures. The vendor base concentrates among integrated petrochemical complexes with captive feedstock positions and purification infrastructure. Three archetypes dominate: C4-integrated Asian producers, European specialty-grade specialists, and Gulf Coast scale operators. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines lock in supplier relationships.
Within the integrated petrochemical tier, LG Chem, Dow, and BASF SE exemplify divergent geographic and grade strategies. LG Chem anchors Northeast Asian supply through feedstock integration. Dow occupies the North American scale position. BASF SE represents the European specialty-grade archetype targeting pharmaceutical and optical certification requirements.
| Leading Market Players |
|---|
| Formosa Korea |
| LG Chem |
| Dow |
| Nippon Shokubai |
| MITSUBISHI GAS CHEMICAL COMPANY, INC |
| BASF SE |
| KURARAY CO., LTD |
| PTT Asahi Chemical |
| Evonik Industries |
| Others |
Cost & Logistics Intelligence
Integrated petrochemical conglomerates with sovereign wealth backing anchor capacity investment decisions across Northeast Asia, linking feedstock security to pricing discipline that technical-grade importers cannot replicate. Their captive C4 oxidation economics transmit directly to contract structures, compressing margin for acetone cyanohydrin-dependent competitors.
Pricing Analysis
Distributor margin compression is accelerating as specification-driven procurement shifts volume toward direct mill relationships with certificate-of-analysis verification. Pricing stratifies across electronic-grade, USP-certified, and technical tiers, with metal-ion thresholds and biocompatibility dossiers commanding substantial premiums. Cost compression in technical grades is intensifying because Chinese domestic capacity expansion outpaces coating demand growth. Mid-tier adhesive compounders exhibit highest price sensitivity; semiconductor photoresist manufacturers show least.
Supply Chain Analysis
Specialized polymer chemist and process engineer availability constraints in Ludwigshafen and Gulf Coast corridors are delaying purification train commissioning timelines. Manufacturing concentrates in China, Germany, and the United States, with South Korean and Japanese facilities serving lithography and medical grades. Feedstock draws from isobutylene, acetone, and hydrogen cyanide streams. Single-source vulnerability runs through acetone cyanohydrin route producers lacking C4 alternatives. Distribution runs through direct sales for high-purity grades; regional distributors retain technical-grade construction adhesive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH dossier completeness and ECHA toxicity data quality determine supplier survival, with semiconductor lithography metal-ion thresholds representing the most demanding demand catalyst.
For Market Incumbents:Cement electronic-grade certification moats through 18-24 month stability data investments that lock in Taiwan and South Korea fab relationships. Deepen backward integration into C4 feedstock where cracker proximity sustains cost positions against acetone cyanohydrin volatility. Prioritize purification infrastructure over technical-grade volume as biobased acrylic substitution threats emerge in coating applications.
For New Entrants and Emerging Players:Indian specialty chemical buyers under PLI scheme incentives present the most penetrable white-space target, with domestic semiconductor fabrication capacity expansion creating demand for electronic-grade purification joint ventures. Medical device polymer compounders in Japan and Germany offer secondary entry points through USP-grade biocompatibility certification. Lead with analytical laboratory partnerships that bypass distributor technical service gaps.
For Investors and Strategic Acquirers:Valuations sit cheapest among regional distributors without in-house testing infrastructure, as qualification requirements compress their share of coating manufacturer procurement. Five-to-ten year viability hinges on carbon intensity disclosure capabilities under EU CSRD mandates. Watch for acetone cyanohydrin route margin collapse as C4-integrated producers expand as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Shandong Province C4 oxidation trains exploit feedstock cost advantages against acetone cyanohydrin volatility. |
| Backward Integration | Captive isobutylene supply from Northeast Asian crackers locks in margin through hydrogen cyanide price swings. |
| Long-term Supply Agreement | Direct mill relationships with German automotive OEMs bypass distributor infrastructure gaps. |
| Joint Venture | India electronic chemicals partnerships leverage PLI incentives to serve domestic semiconductor fabrication demand. |
| Green Manufacturing Transition | EU CSRD Scope 3 disclosure compliance creates preference for verified low-carbon process credentials. |
Research Approach
Multiple input streams — plant manager interviews, procurement lead discussions with downstream coating manufacturers, technical R&D director consultations, and distribution channel partner assessments — were reconciled against customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings. Bottom-up grade-tier volume builds and top-down end-use industry demand estimates were cross-validated through the analysis window.
Historical capacity utilization patterns were cross-referenced against panel input from petrochemical strategists to anchor projection assumptions. The modeling framework segmented by purity tier, end-use industry concentration, and regional production hub configuration. CAGRs were derived from demand elasticity coefficients applied to semiconductor lithography node expansion and waterborne coating displacement rates.
Inputs from ECHA registration databases and MEE discharge standard filings were available through the study window; gaps in proprietary fab qualification protocols introduce uncertainty bands around high-purity market share estimates. Forecasts reflect documented assumptions regarding acetone cyanohydrin route viability and biobased acrylic substitution timelines. Material deviation in REACH dossier acceptance rates or EPA TSCA enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Cyclopentanone Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
Aminophenol Market
Organic Chemicals
Terephthalic Aldehyde Market
Organic Chemicals
Acetylacetone Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Alanine Market
Organic Chemicals
Chloroethylene Market
Organic Chemicals
Cyclohexanone Market