
 Global Tert-Butanol Market | 2026-2036
Global Tert-Butanol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tert-Butanol Market Foresight
Bulk tanker delivery is consolidating as the dominant packaging configuration for large-volume solvent and chemical intermediate buyers across Asia-Pacific and North American supply chains. Kuraray Co., Ltd leverages its integrated isobutylene feedstock position to anchor captive tert-butanol production for specialty polymer derivatives. LyondellBasell Industries Holdings B.V. competes through Gulf Coast propylene oxide/tert-butanol co-product scale, while Evonik Industries AG differentiates via pharmaceutical-grade purification capabilities serving European API manufacturers.
Tert-butanol, or 2-methyl-2-propanol, is a tertiary alcohol with a melting point of 25.7°C and a boiling point of 82.4°C, manufactured primarily through acid-catalyzed hydration of isobutylene or as a co-product in propylene oxide production via the Halcon process. Its industrial purpose centers on serving as a protic solvent, crystallization medium, and precursor to methyl tert-butyl ether and tert-butylamine derivatives. Industrial grade product dominates volume throughput for paints and coatings solvent applications, while pharmaceutical grade commands premium positioning in active pharmaceutical ingredient crystallization where residual impurity thresholds fall below 0.1 percent. Chemical intermediate applications for fuel additive and plasticizer precursors represent the fastest-expanding demand pool as refiners seek octane enhancement alternatives amid aromatic blending constraints.
EPA fuel additive registrations under 40 CFR Part 79 and REACH Annex XVII restrictions on volatile organic compound content in consumer products shape formulation choices and purity requirements across North American and European demand centers. China's GB standards administered by SAMR set national specifications for industrial-grade material used in domestic agrochemical and adhesive manufacturing. Stakeholders must monitor regulatory divergence between OECD-aligned hazard classification systems and emerging chemical management frameworks in major producing jurisdictions to anticipate compliance-driven grade migration and reformulation timelines.
Market Dynamics
Agrochemical formulators are expanding procurement of tert-butanol as a solvent and chemical intermediate for pesticide synthesis, tightening purity specifications across fuel additive and personal care applications under REACH and EPA frameworks.
Growth Catalysts
- REACH compliance mandates:European manufacturers must upgrade to pharmaceutical-grade material, accelerating grade migration timelines for personal care and fuel additive applications.
- Isobutylene feedstock abundance:Petrochemical cluster expansion around Zibo and Nanjing in China is lowering delivered costs for regional derivative producers.
- Octane enhancement alternatives:Refiners seek methyl tert-butyl ether precursors amid aromatic blending constraints, expanding chemical intermediate demand.
Market Restraints
- Propylene oxide co-production dependency:Gulf Coast supply chains tie tert-butanol output to propylene oxide demand cycles, creating volume volatility.
- Isobutylene price pass-through:Hydration route producers face margin compression when olefin feedstock costs spike.
- Volatile organic compound restrictions:REACH Annex XVII and EPA 40 CFR Part 79 are limiting solvent-grade applications in consumer-facing formulations.
Strategic Opportunities
- Indian agrochemical manufacturing:CDSCO registration pathways for pesticide intermediates remain underpenetrated relative to formulation scale-up.
- Pharmaceutical-grade crystallization:Active pharmaceutical ingredient manufacturers in Switzerland and Germany seek sub-0.1 percent impurity thresholds.
- Bulk tanker distribution:Direct-to-derivative-producer logistics are compressing packaging costs for large-volume buyers across Asia-Pacific supply chains.
Industry Challenges
- Multi-jurisdiction certification timelines:SAMR GB standards, REACH dossiers, and EPA fuel additive registrations require parallel compliance tracks.
- Halcon process retrofit capital:Co-product producers face significant expenditure to isolate pharmaceutical-grade streams from existing propylene oxide trains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tert-Butanol Market |
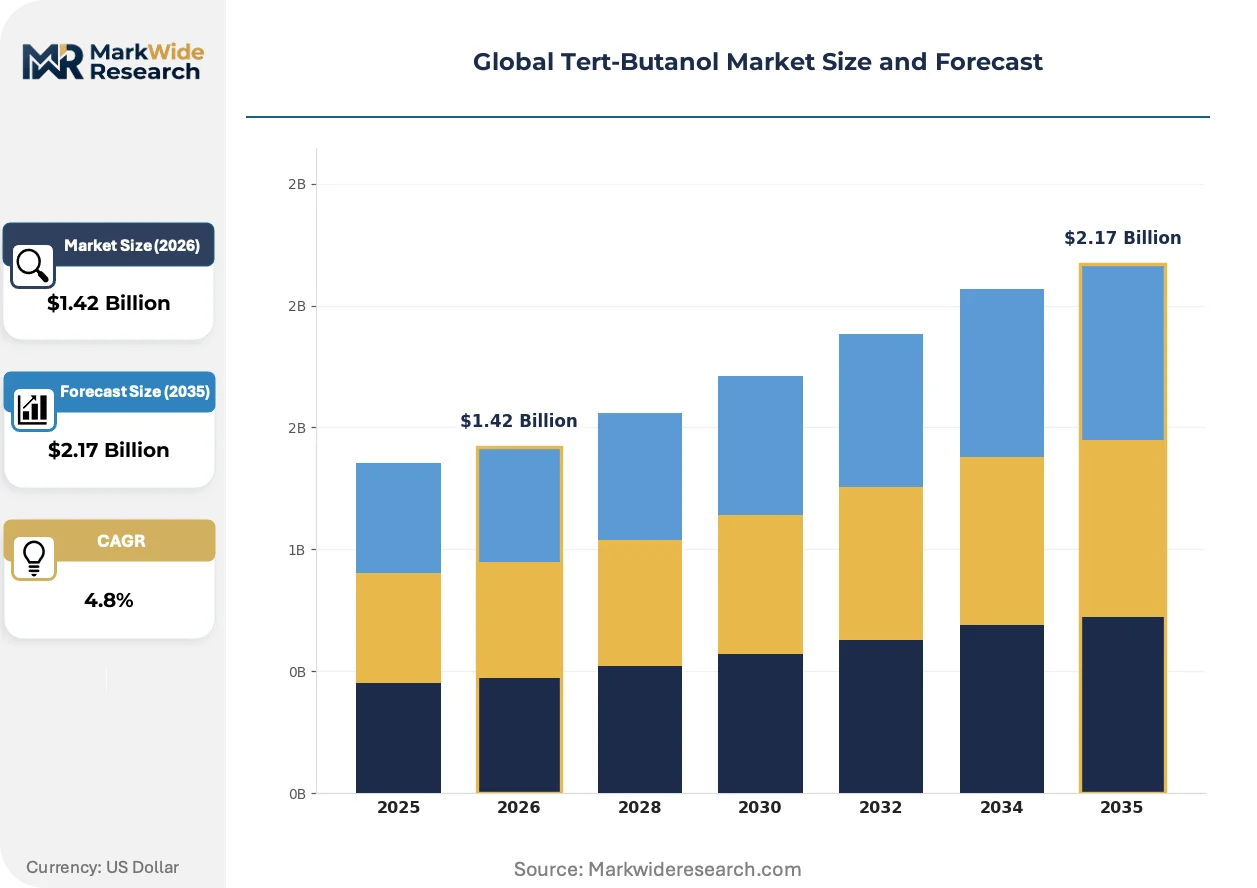
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Cosmetic Grade, Laboratory Grade Application: Solvent, Fuel Additive, Chemical Intermediate, Extraction Agent, Plasticizer Packaging Type: Drums, Bulk Tankers, Intermediate Bulk Containers, Bottles End Use Industry: Paints & Coatings, Agrochemicals, Personal Care, Oilfield Chemicals, Adhesives |
| Companies Covered | Kuraray Co., Ltd, Indorama Ventures, LyondellBasell Industries Holdings B.V., Maruzen Petrochemical, Sinopec Corp., Evonik Industries AG, LOTTE Chemical Corporation, Zibo Qixiang Petrochemical Industry Group Co., Ltd., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tert-Butanol Market Shifts & Advancements
Membrane separation and advanced distillation architectures are reshaping purification economics, enabling producers to capture pharmaceutical-grade premiums without greenfield investment.
Hybrid pervaporation-distillation systems are electrifying tert-butanol recovery from aqueous waste streams. Specialty chemical manufacturers in Japan and South Korea are retrofitting existing solvent recovery units with these membranes. The technology is electrifying margin structures for mid-scale producers previously locked out of pharmaceutical-grade supply.
EPA 40 CFR Part 79 is tightening fuel additive registration requirements, forcing reformulators to document complete supply chain purity. Refiners are responding by specifying certified pharmaceutical-grade material for octane blending. North American fuel additive producers now face compressed timelines to upgrade sourcing specifications.
Direct procurement from integrated petrochemical complexes is displacing distributor-mediated supply for agrochemical formulators. Large-volume buyers in China are negotiating annual offtake agreements with Zibo and Nanjing cluster producers. This pattern is most visible in pesticide synthesis operations where delivered cost transparency outweighs inventory flexibility.
Global Tert-Butanol Market Segmentation
Certification requirements fragment tert-butanol procurement across radically different compliance burdens. Product grade determines which regulatory dossiers buyers must maintain, while application chemistry dictates purity thresholds that reshape supplier qualification timelines.
Product Type:
EPA fuel additive registrations under 40 CFR Part 79, REACH Annex XVII dossiers, and FDA pharmaceutical master files each map to distinct grade specifications with non-overlapping compliance tracks.
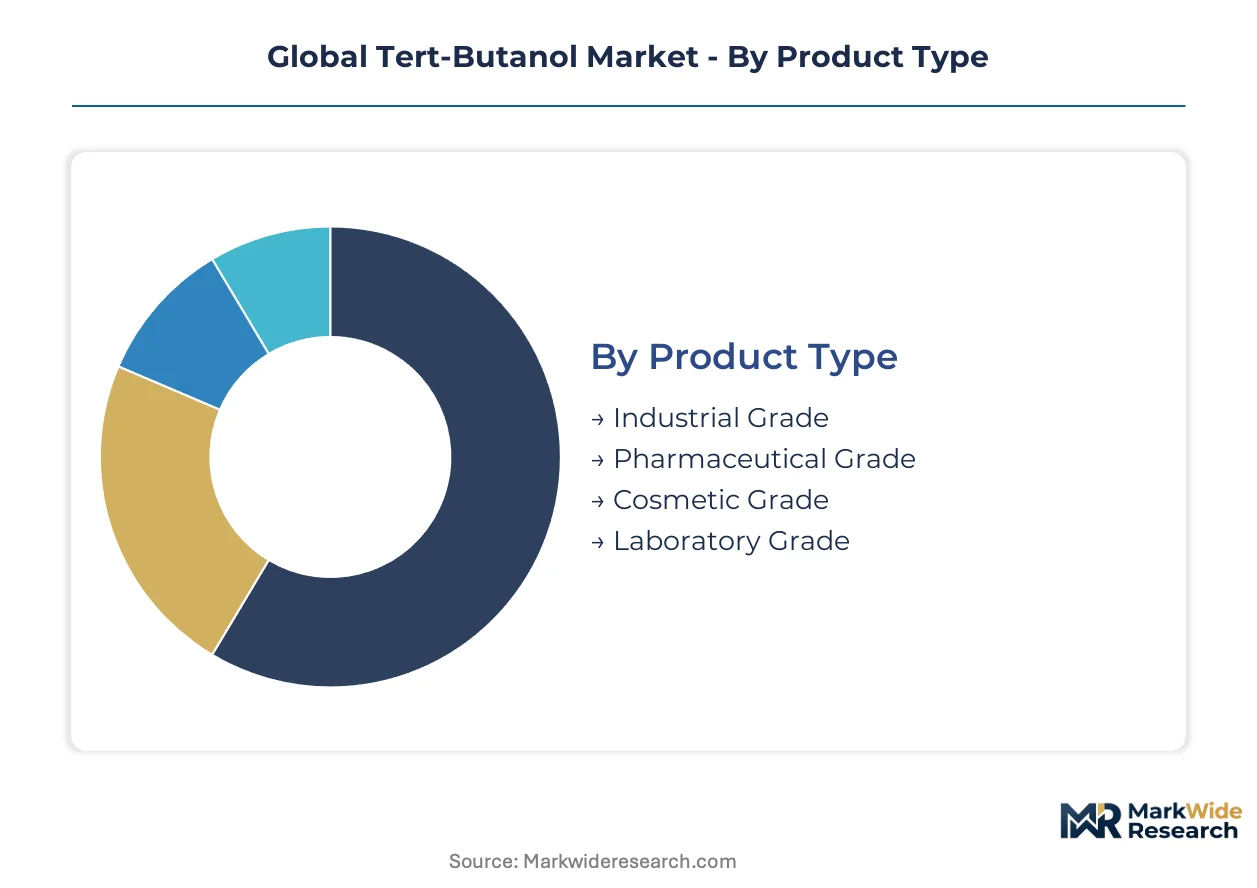
- Industrial Grade:Material with 99.0-99.5% purity serves paints and coatings solvent applications where residual water and light hydrocarbons remain acceptable. Agrochemical formulators in China dominate procurement volumes, leveraging Zibo cluster proximity to compress delivered costs for pesticide synthesis operations.
- Pharmaceutical Grade:Sub-0.1% impurity thresholds with full traceability documentation support API crystallization protocols. Swissmedic and EMA inspections drive specification tightening, forcing European manufacturers to isolate dedicated production trains from industrial-grade commingling.
- Cosmetic Grade:REACH-compliant material with restricted peroxide content addresses personal care solvent demand under EU Cosmetics Regulation 1223/2009.
- Laboratory Grade:ACS or reagent specifications serve analytical chemistry and research applications with batch-level certificates of analysis.
Leading the category by volume: Industrial Grade. Expanding most quickly: Pharmaceutical Grade.
Application:
Margin structures diverge sharply between commoditized solvent offtake and specialty chemical intermediate premiums.
- Solvent:Protic dissolution properties enable crystallization media and reaction diluents across pharmaceutical and agrochemical manufacturing. REACH Annex XVII VOC restrictions are compressing European demand, redirecting volume toward Asian formulation centers with less stringent emission frameworks.
- Chemical Intermediate:Methyl tert-butyl ether and tert-butylamine precursors anchor refinery octane enhancement strategies. US refiners facing aromatic blending constraints are accelerating procurement of MTBE-grade material, though California Air Resources Board prohibitions fragment state-level addressable demand.
- Fuel Additive:Direct octane blending applications require EPA 40 CFR Part 79 registration with full supply chain purity documentation.
- Extraction Agent:Selective solubility properties serve natural product and pharmaceutical extraction protocols.
- Plasticizer:Tert-butyl ester derivatives modify polymer flexibility in adhesive and coating formulations.
Dominating current offtake: Solvent. Steepest expansion trajectory: Chemical Intermediate.
Packaging Type:
Logistics configuration directly determines unit economics for derivative producers at varying scale tiers.
- Bulk Tankers:Dedicated rail and road tanker deliveries consolidate procurement for large-volume solvent and intermediate buyers. Nanjing petrochemical cluster producers are negotiating annual offtake agreements with agrochemical formulators, displacing distributor-mediated supply.
- Intermediate Bulk Containers:1000-liter totes bridge mid-scale procurement with reduced handling versus drum alternatives.
- Drums:Standard 200-liter steel packaging serves fragmented coatings and adhesive manufacturers without tanker unloading infrastructure.
- Bottles:Laboratory and pilot-scale quantities with amber glass or fluoropolymer lining for light-sensitive applications.
Capturing greatest volume share: Bulk Tankers. Gaining adoption fastest: Intermediate Bulk Containers.
End Use Industry:
Regulatory exposure varies dramatically between consumer-facing personal care applications and industrial chemical synthesis.
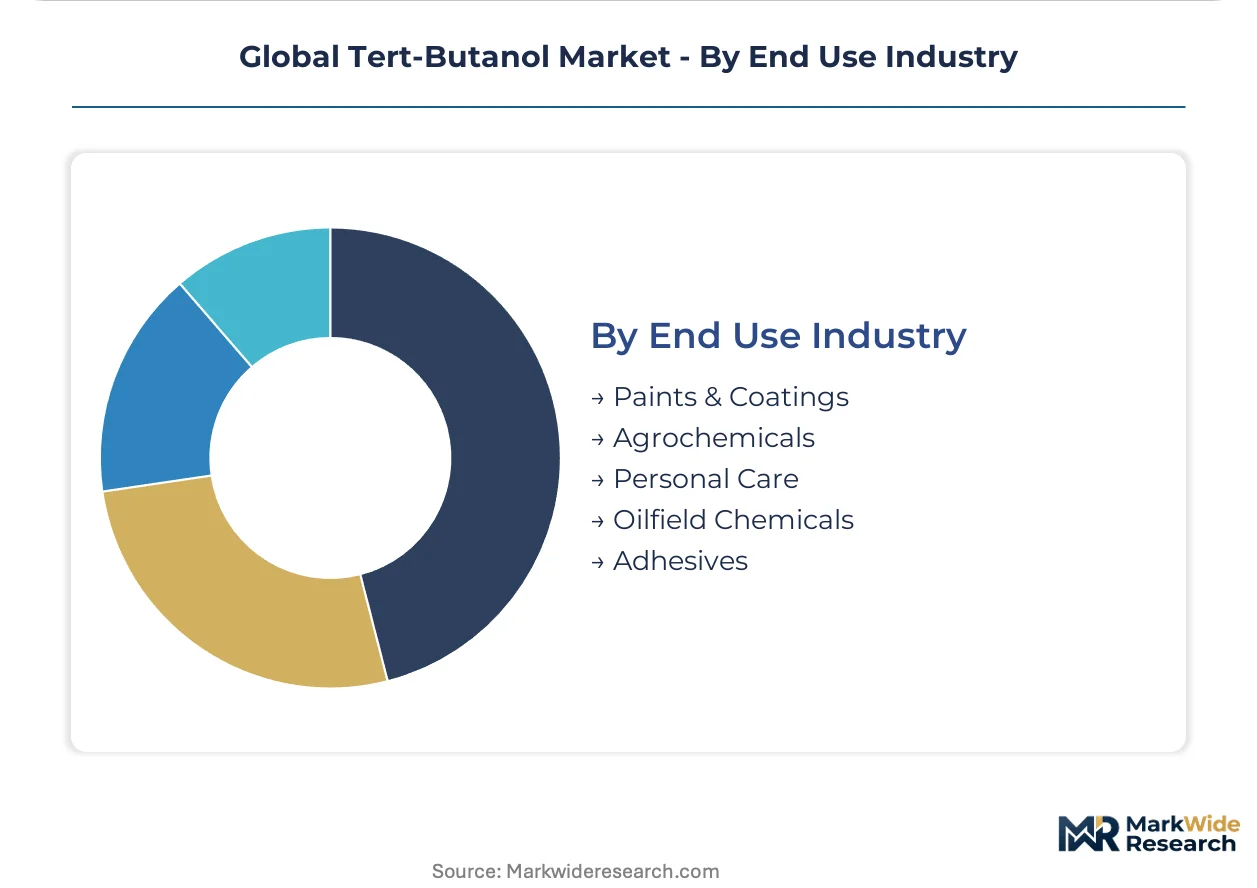
- Agrochemicals:Pesticide intermediate and formulation solvent demand concentrates in China and India. CDSCO registration pathways for pesticide synthesis intermediates remain underpenetrated relative to Indian formulation manufacturing scale-up.
- Paints & Coatings:Industrial-grade solvent consumption tracks construction and automotive refinish cycles. South Korean and Japanese manufacturers are retrofitting solvent recovery units with hybrid pervaporation systems to electrify margin structures.
- Personal Care:Cosmetic-grade specifications under EU Cosmetics Regulation drive pharmaceutical-grade migration for fragrance and extraction applications.
- Oilfield Chemicals:Specialty solvent demand follows unconventional drilling intensity in Permian and Vaca Muerta basins.
- Adhesives:Tert-butyl acrylate and methacrylate precursors support pressure-sensitive and structural adhesive polymerization.
Commanding largest volume: Paints & Coatings. Climbing fastest: Agrochemicals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Shandong and Jiangsu provinces concentrate tert-butanol production capacity through feedstock-integrated petrochemical complexes. These zones attract derivative manufacturers seeking delivered cost advantages for agrochemical and solvent applications.
China
Agrochemical formulators in Zibo and Nanjing drive industrial-grade offtake for pesticide synthesis operations. SAMR-administered GB standards govern purity specifications for domestic manufacturing. The Yangtze River Delta petrochemical corridor anchors co-product supply chains serving methyl tert-butyl ether precursor demand.
United States
Refiners facing aromatic blending constraints accelerate procurement of chemical intermediates for octane enhancement strategies. EPA 40 CFR Part 79 fuel additive registrations require complete supply chain purity documentation. Gulf Coast propylene oxide co-production facilities tie tert-butanol output to regional olefin demand cycles.
Germany
Pharmaceutical-grade material commands premium positioning among active pharmaceutical ingredient crystallization operations. EMA inspections and REACH Annex XVII dossiers force dedicated production train isolation from industrial-grade commingling. The Rhine-Ruhr chemical cluster supports specialty solvent distribution across European formulation centers.
India
CDSCO registration pathways for pesticide intermediates remain underpenetrated relative to formulation manufacturing scale-up. Central government production-linked incentive schemes encourage domestic agrochemical intermediate capacity. Gujarat and Maharashtra industrial corridors attract bulk tanker deliveries from Middle Eastern supply sources.
Japan
Specialty chemical manufacturers retrofit solvent recovery units with hybrid pervaporation-distillation systems for aqueous waste stream processing. METI industrial efficiency standards accelerate electrification of margin structures for mid-scale producers. The Keiyo petrochemical complex maintains integrated isobutylene feedstock positions for captive derivative production.
Global Tert-Butanol Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tert-butanol supply tiers. The market structure fragments between integrated petrochemical majors, regional hydration-route producers, and pharmaceutical-grade purification specialists. Three archetypes dominate: feedstock-integrated conglomerates leveraging olefin positions, co-product specialists tied to propylene oxide economics, and high-purity refiners serving regulated pharmaceutical applications. Capacity expansion and grade-migration partnerships constitute the dominant competitive moves as regulatory divergence accelerates.
Among Japanese chemical conglomerates, Kuraray Co., Ltd represents the feedstock-integrated archetype through its isobutylene position. LyondellBasell Industries Holdings B.V. exemplifies Gulf Coast co-production scale, while Evonik Industries AG occupies the pharmaceutical-grade purification tier serving European API manufacturers. These three anchors illustrate how geographic and strategic positioning stratify competitive access across regulatory jurisdictions.
| Leading Market Players |
|---|
| Kuraray Co., Ltd |
| Indorama Ventures |
| LyondellBasell Industries Holdings B.V. |
| Maruzen Petrochemical |
| Sinopec Corp. |
| Evonik Industries AG |
| LOTTE Chemical Corporation |
| Zibo Qixiang Petrochemical Industry Group Co., Ltd. |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Captive isobutylene integration anchors pricing power for hydration-route producers in China's Shandong province, compressing delivered costs for Zibo cluster buyers while Gulf Coast co-product suppliers face margin volatility tied to propylene oxide demand cycles.
Pricing Analysis
Short lead-time premiums dominate spot procurement for pharmaceutical-grade material, while annual offtake contracts secure volume discounts for industrial-grade solvent buyers. Three-tier pricing structure across pharmaceutical, industrial, and cosmetic certification levels differentiates by purity threshold and documentation burden. Cost compression in industrial-grade runs through isobutylene feedstock pass-through mechanisms. Agrochemical formulators in India exhibit highest price sensitivity due to CDSCO registration cost burdens, whereas Swiss API manufacturers accept premium positioning for sub-0.1% impurity guarantees.
Supply Chain Analysis
REACH dossier and EPA fuel additive registration requirements gate supplier qualification timelines, fragmenting procurement across non-overlapping compliance tracks. Production concentrates in China, the United States, and Germany, with feedstock draws from regional olefin crackers and refinery streams. Supply chains rest on isobutylene hydration catalysts, propylene oxide co-production trains, and pharmaceutical-grade distillation membranes. Single-source vulnerability persists for European pharmaceutical-grade buyers dependent on Rhine-Ruhr specialty refiners. Distribution runs through bulk tanker direct delivery for large-volume derivative producers, displacing distributor-mediated channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where feedstock control over isobutylene positions determines long-term margin sustainability against co-product volatility.
For Market Incumbents: Hedge propylene oxide co-production exposure by securing dedicated isobutylene hydration capacity in China's Yangtze River Delta. Invest in membrane separation retrofitting to isolate pharmaceutical-grade streams from existing industrial trains. Defensive positioning requires preemptive REACH Annex XVII compliance upgrades before EMA inspection cycles tighten.
For New Entrants and Emerging Players: Mid-scale agrochemical formulators in Gujarat and Maharashtra represent underserved buyers seeking CDSCO-registered intermediate supply with transparent bulk tanker logistics. White-space concentration appears in Indian pesticide synthesis operations lacking domestic tert-butylamine precursor capacity. Entry strategy should anchor on annual offtake agreements with direct refinery feedstock sourcing.
For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical-grade purification specialists with EMA-inspected production trains and existing FDA master files. Long-term viability hinges on regulatory divergence between OECD-aligned hazard classification and emerging chemical management frameworks. Watch for SAMR GB standard harmonization signals as inflection indicators for Chinese supply chain reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isobutylene Feedstock | Kuraray's captive olefin position secures margin insulation against spot price volatility. |
| Pharmaceutical-Grade Purification Retrofit | Membrane separation upgrades enable Evonik to capture API crystallization premiums without greenfield capex. |
| Long-Term Supply Agreement with Zibo Cluster | Direct procurement contracts compress packaging costs for Nanjing agrochemical derivative producers. |
| Joint Venture for Indian CDSCO Registration | Partnerships with Gujarat formulators accelerate pesticide intermediate market penetration. |
| Green Manufacturing Transition | Hybrid pervaporation-distillation electrification aligns with METI efficiency standards for Keiyo complex operators. |
Research Methodology
Document review covered SEC 10-K filings, REACH dossier databases, and SAMR GB standard registries, complemented by interviews with plant managers at hydration-route facilities, procurement leads at downstream agrochemical OEMs, and technical R&D directors overseeing membrane separation pilot programs. Secondary validation drew from customs trade data, ACC and Cefic industry reports, and EPA fuel additive registration filings. Bottom-up volume modeling triangulated against top-down petrochemical derivative demand estimates.
Segment-level outputs across the analysis window reflect grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived from elasticity-adjusted demand projections incorporating isobutylene feedstock cost trajectories and regulatory compliance timeline assumptions. Forecast inputs included refinery octane blending constraint intensities and aromatic substitution rates for MTBE precursor demand.
Revisions become necessary when REACH Annex XVII amendments, EPA 40 CFR Part 79 rulemaking, or SAMR standard updates materialize with accelerated implementation timelines. Forecasts reflect documented assumptions regarding petrochemical cluster expansion schedules and pharmaceutical inspection cycle frequencies. A model refresh is warranted upon material change in isobutylene hydration capacity commissioning or propylene oxide co-production economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
5-Isopropyl-M-Xylene Market
Solvents
Mineral Turpentine Market
Solvents
Oxygenated Solvents Market
Solvents
3-Butylene Glycol Market
Solvents
Phenylacetonitrile Market
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market
Solvents
Diethanolamine (DEA) Market
Solvents
Decanol Market
Solvents
Global Furfural Solvent Market
Solvents
Coating Solvents Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Mono Propylene Glycol Market
Solvents
Dimethyl Formamide Market
Solvents
Chloromethane Market
Solvents
Hydrosol Market
Solvents
Allyl Cyanide Market