
 Tetraethyl Benzene Market | 2026-2036
Tetraethyl Benzene Market Size, Share, and Industry Trends Forecast 2026-2036
Tetraethyl Benzene Market Analysis
A shortage of skilled process chemists familiar with Friedel-Crafts alkylation optimization is redrawing competitive boundaries among tetraethyl benzene manufacturers. BASF SE leverages its integrated Ludwigshafen complex to sustain captive production of ethylated aromatics with tight specification control. Evonik Industries AG anchors its position through specialized high-purity grades serving pharmaceutical contract manufacturing organizations. Sagechem Limited competes on flexible batch scales for research-grade material demanded by academic and early-stage discovery laboratories.
Tetraethyl benzene is a symmetrically substituted alkylbenzene with four ethyl groups attached to a central benzene ring, typically produced through catalytic alkylation of ethylbenzene or direct ethylation of benzene using acid catalysts at elevated temperature and pressure; it functions primarily as a specialty solvent and chemical intermediate in organic synthesis and materials science. Industrial grade material dominates volume throughput due to broad uptake in petrochemical process streams and bulk chemical manufacturing, while pharmaceutical grade commands premium positioning driven by stringent impurity thresholds required for active pharmaceutical ingredient synthesis. The additive application segment shows structural momentum as formulators seek low-toxicity aromatic extenders for polymer modification and lubricant base stocks.
EPA oversight under the Toxic Substances Control Act shapes manufacturing compliance burdens for US-based producers, while REACH registration requirements in Europe mandate extensive toxicological dossiers that filter out smaller importers. China's SAMR enforces GB standards for chemical purity and labeling that directly affect market access for foreign suppliers. Buyers and producers must monitor regulatory divergence between jurisdictions to avoid supply disruptions and qualification gaps.
Market Dynamics
Specialty chemical manufacturers are consolidating procurement around high-purity tetraethyl benzene intermediates as pharmaceutical synthesis protocols tighten impurity thresholds and supplier qualification windows narrow.
Growth Catalysts
- Pharmaceutical synthesis protocols:Active pharmaceutical ingredient manufacturers are expanding orders for pharmaceutical-grade material to meet FDA and EMA purity dossier requirements. Contract manufacturing organizations now specify sub-ppm impurity ceilings in master service agreements.
- China's petrochemical expansion:Domestic alkylated aromatic capacity additions under government-backed advanced materials programs are accelerating local consumption of tetraethyl benzene process intermediates. State-supported research institutes are qualifying new feedstock pathways.
- REACH registration completion:Full toxicological dossier acceptance by ECHA has filtered out marginal importers and concentrated volume among registered suppliers. This regulatory clarity enables long-term supply contracts with European formulators.
Market Restraints
- Ethylene feedstock volatility:Crack spread fluctuations at integrated petrochemical complexes transmit directly to tetraethyl benzene production economics. Producers lack pricing power to pass through sustained ethylene cost spikes.
- Friedel-Crafts catalyst supply concentration:Specialized acid catalyst manufacturing clusters in Germany and the United States create single-source vulnerability for batch-scale producers. Qualifying alternative catalyst suppliers requires 18-24 month validation cycles.
- Substitution by isopropylated aromatics:Lubricant formulators are piloting diisopropylbenzene and triisopropylbenzene extenders in polymer modification applications. These alternatives offer comparable solvency with lower viscosity indices.
Strategic Opportunities
- India's specialty chemical import substitution:PLI scheme incentives for pharmaceutical intermediates are attracting investment in domestic tetraethyl benzene purification capacity. CDSCO fast-track approvals for registered suppliers create first-mover advantage.
- Green chemistry catalyst convergence:Solid acid zeolite systems combined with continuous flow reactor architectures promise yield improvements and waste reduction. Early adopters in academic-industrial partnerships are securing patent positions.
- Direct-to-laboratory distribution channels:Research-grade material procurement is migrating from traditional chemical distributors to specialized e-commerce platforms serving discovery laboratories. These channels reduce minimum order quantities and accelerate delivery timelines.
Industry Challenges
- Friedel-Crafts process optimization expertise:The shortage of skilled process chemists capable of tuning alkylation selectivity and suppressing polyethylbenzene byproduct formation constrains capacity expansion. Technical training programs at German and Swiss universities are not producing sufficient graduates.
- Pharmaceutical-grade certification timelines:EMA and FDA active pharmaceutical ingredient starting material qualifications require 24-36 month documentation and audit cycles. Smaller producers lack regulatory affairs bandwidth to pursue parallel submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetraethyl Benzene Market |
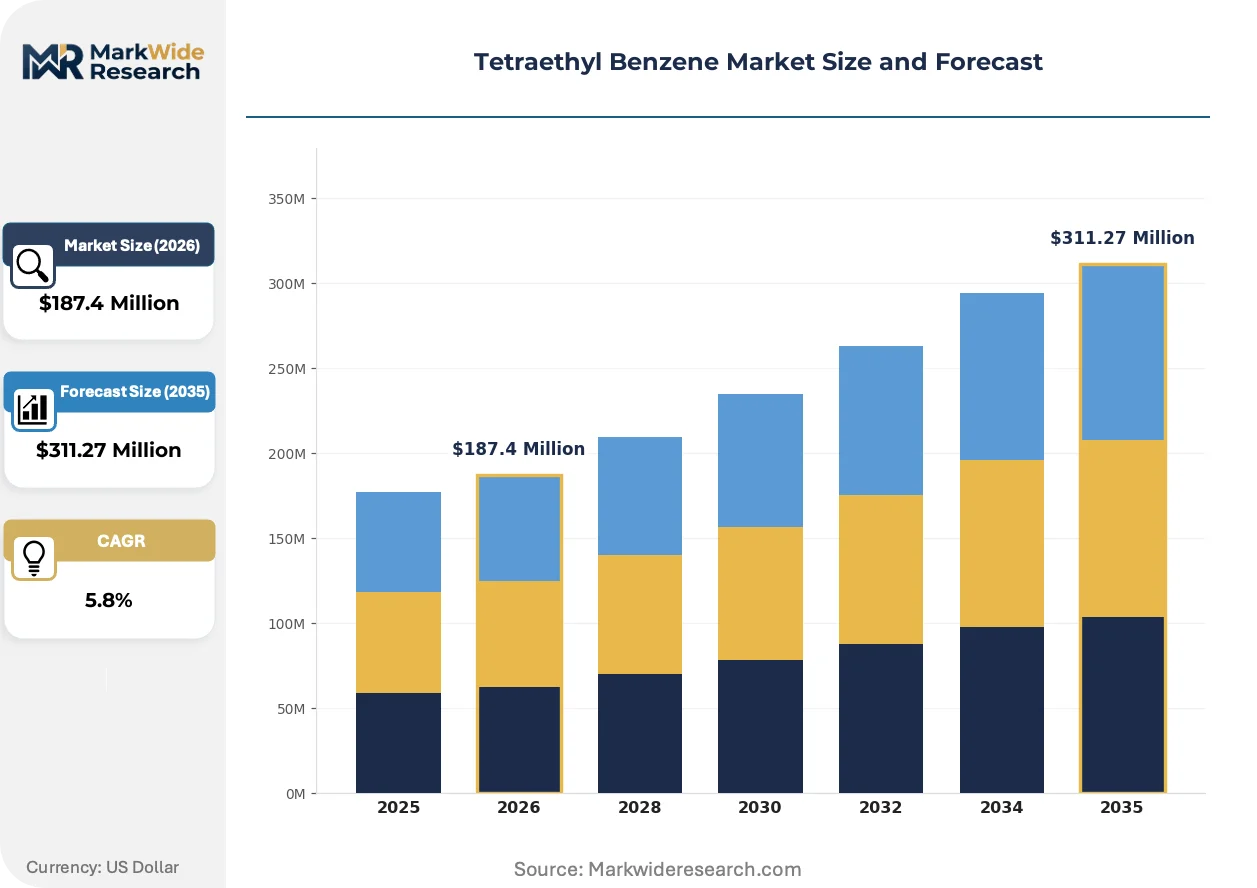
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Commercial Grade, Pharmaceutical Grade, Research Grade Application: Solvent, Intermediate, Chemical Synthesizer, Additive End User: Pharmaceuticals, Petrochemicals, Agriculture, Plastics Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail |
| Companies Covered | BASF SE, Evonik Industries AG, Sagechem Limited, BOCSCI Inc., LEAPChem Co., Ltd., Angene International, Antimex Chemical Limited, Henan Tianfu Chemical Co., Ltd., ChemSampCo, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetraethyl Benzene Market Emerging Trajectories
Process intensification and regulatory data harmonization are compressing traditional manufacturing and qualification timelines for tetraethyl benzene suppliers serving pharmaceutical and materials science end-uses.
Continuous flow alkylation reactor technology is fragmenting the conventional batch production paradigm for tetraethyl benzene. Pharmaceutical contract manufacturers are piloting these systems at kilogram-per-hour scales to demonstrate impurity profile consistency. The technology is fragmenting capital deployment patterns by enabling distributed production nodes closer to formulation sites rather than centralized commodity-scale plants.
REACH Annex XV dossier updates and evolving EPA TSCA Section 5 notification requirements are forcing toxicological data regeneration for legacy alkylation catalyst residues. Industrial-grade producers face six-figure compliance costs to maintain European market access. Specialty chemical distributors are responding by consolidating supplier panels to registered-only sources with existing dossier coverage.
Research-grade buyers are compressing supplier switching cycles from annual contracts to quarterly spot purchases with certificate-of-analysis verification. Academic laboratories and early-stage biotechnology firms are displacing traditional distributor relationships with direct manufacturer engagement through specialized procurement platforms. This pattern is most visible in the Boston and San Francisco corridor clusters where discovery chemistry outsourcing concentrates.
Tetraethyl Benzene Market Segmentation
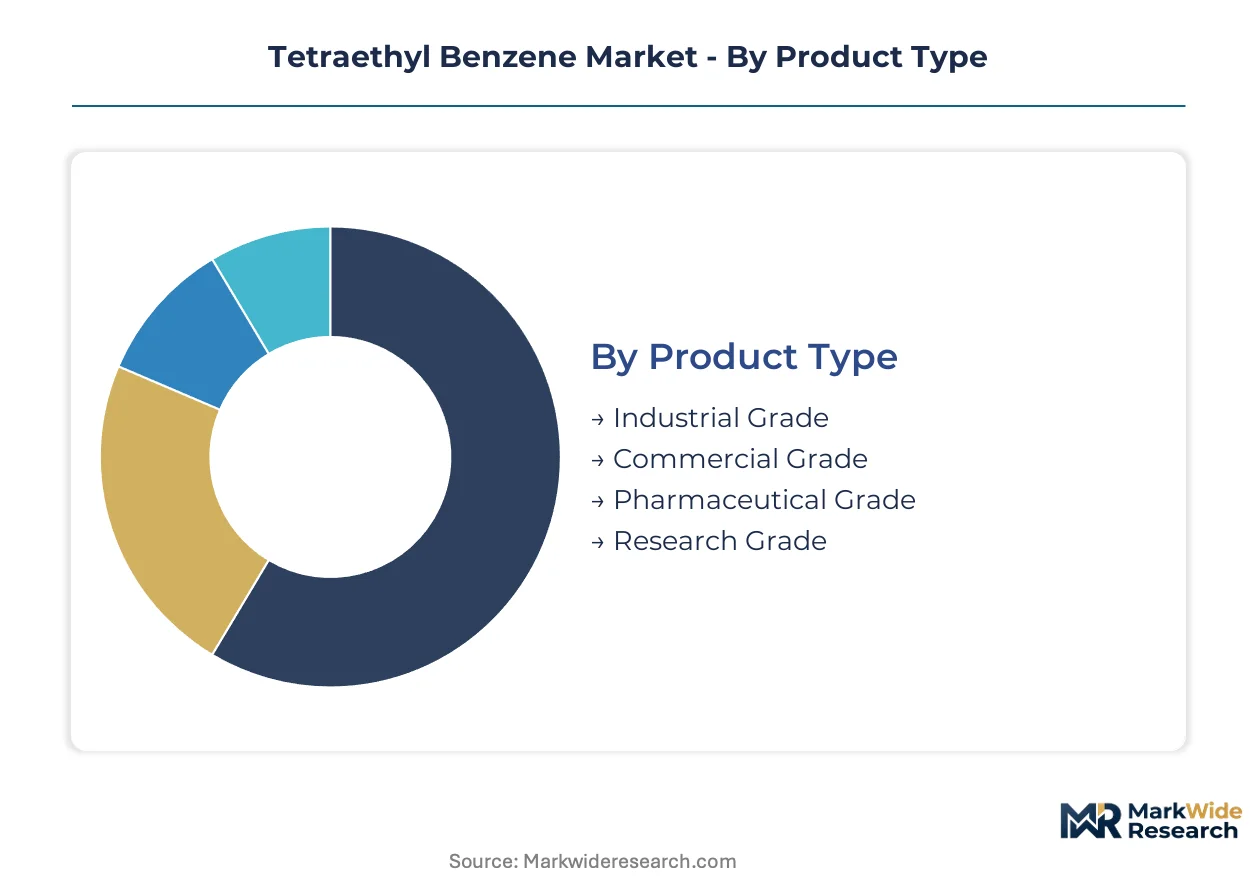
Tetraethyl benzene procurement patterns diverge sharply across purity tiers and end-use specifications. Regulatory thresholds from FDA, ECHA, and China's SAMR fragment demand into distinct qualification corridors that reshape supplier selection criteria.
Product Type:
REACH registration dossiers and FDA starting material qualifications create rigid purity boundaries that determine market access eligibility across grades.
- Industrial Grade:Material with 95-98% purity serves bulk petrochemical process streams and lubricant blending operations. Volume concentrates in China's Shandong and Jiangsu province refineries where domestic ethylbenzene capacity expansion feeds captive alkylation units. State-backed advanced materials programs accelerate local consumption of this feedstock tier.
- Pharmaceutical Grade:Sub-ppm impurity specifications meet FDA and EMA active pharmaceutical ingredient starting material requirements. Contract manufacturing organizations in Basel and Boston corridors specify this grade in master service agreements with 24-36 month qualification timelines. CDSCO fast-track approvals in India are attracting investment in dedicated purification capacity.
- Commercial Grade:Mid-tier purity material bridges industrial and specialty applications with moderate specification control.
- Research Grade:Small-batch production serves academic laboratories and early-stage discovery operations with flexible certificate-of-analysis protocols.
Established volume favors Industrial Grade; emerging adoption favors Pharmaceutical Grade.
Application:
Process intensification in continuous flow reactor systems is redrawing functional boundaries between solvent and intermediate uses.
- Solvent:High-boiling aromatic properties enable use in polymer modification and extraction processes. Demand clusters in German lubricant formulators seeking low-toxicity aromatic extenders. Substitution pressure from isopropylated aromatics constrains expansion in viscosity-sensitive applications.
- Intermediate:Friedel-Crafts alkylation feedstock for downstream ethylated aromatic synthesis commands premium positioning. Pharmaceutical contract manufacturers in Switzerland and Massachusetts pilot kilogram-per-hour continuous flow systems to demonstrate impurity profile consistency for regulatory dossiers.
- Chemical Synthesizer:Reagent-grade material supports organic synthesis protocols in materials science research.
- Additive:Polymer modification applications in plastics compounding seek aromatic extender functionality with reduced viscosity indices.
Current procurement weight rests with Solvent applications; steepest expansion trajectory appears in Intermediate uses.
End User:
Customer technical capability and regulatory bandwidth determine grade selection and supplier relationship intensity.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturers drive pharmaceutical-grade demand through FDA and EMA purity dossier requirements. ECHA REACH Annex XV updates force toxicological data regeneration that filters supplier panels to registered-only sources.
- Petrochemicals:Integrated refineries in China and Germany consume industrial-grade material for process stream optimization. Ethylene feedstock volatility at cracking complexes transmits directly to production economics without pricing power recovery.
- Agriculture:Agrochemical formulators utilize commercial-grade material for intermediate synthesis with moderate purity thresholds.
- Plastics:Polymer compounders specify additive-grade material for lubricant base stock and aromatic extender applications.
Margin concentration favors Pharmaceuticals; volume scale favors Petrochemicals.
Distribution Channel:
Minimum order quantity compression and delivery acceleration are fragmenting traditional distributor relationships.
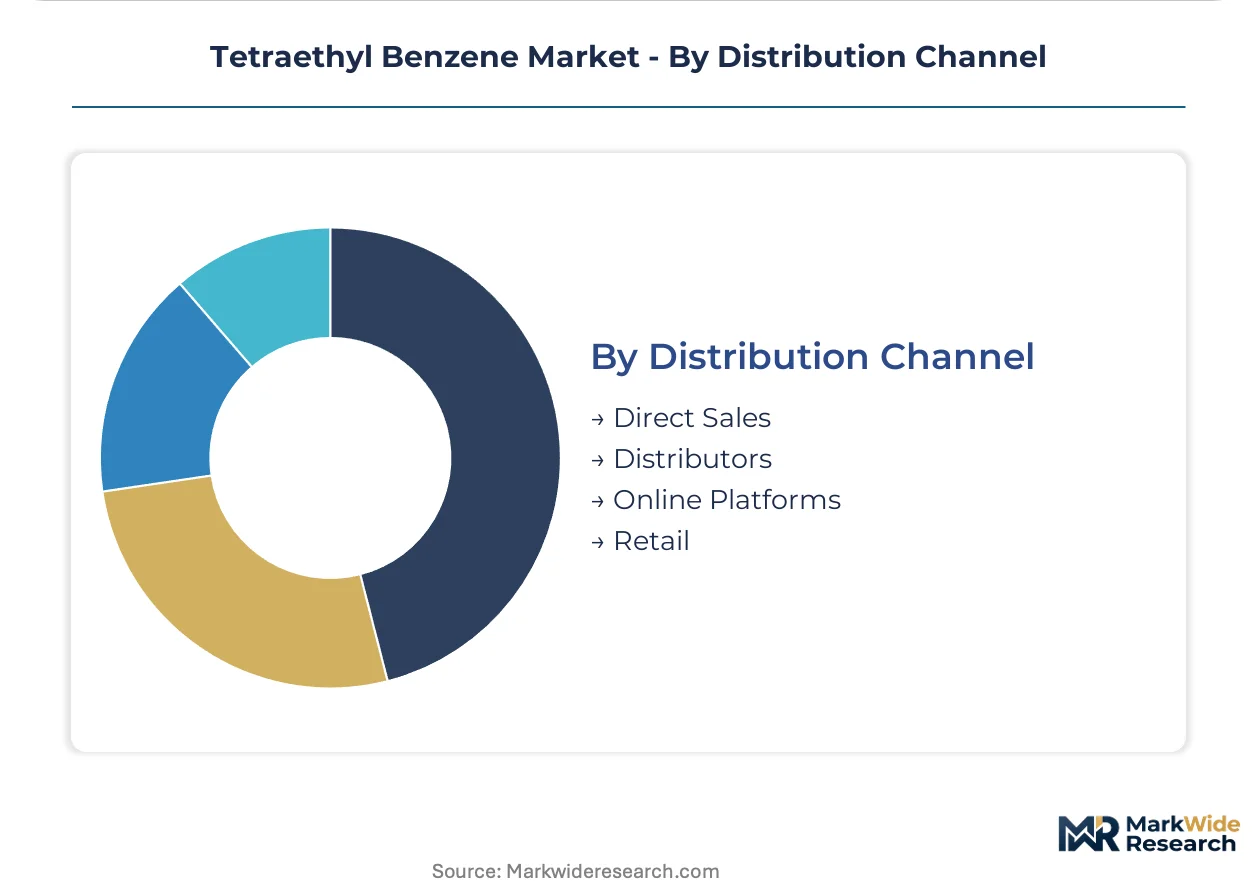
- Direct Sales:Manufacturer engagement bypasses traditional distributors for pharmaceutical-grade and research-grade material. Academic laboratories in Boston and San Francisco corridors migrate to specialized procurement platforms with quarterly spot purchasing and certificate-of-analysis verification.
- Distributors:Consolidated chemical distributors maintain industrial-grade volume throughput with annual contract structures. REACH registration filtering drives panel consolidation toward registered suppliers with existing dossier coverage.
- Online Platforms:E-commerce channels reduce minimum order quantities for discovery laboratories and early-stage biotechnology firms.
- Retail:Small-volume packaging serves academic and research institutions with immediate fulfillment requirements.
Relationship stability favors Distributors; channel innovation favors Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR enforces GB standards that determine market access for foreign tetraethyl benzene suppliers. China anchors regional demand through state-backed advanced materials programs and domestic petrochemical expansion. The regulatory landscape fragments across EPA TSCA enforcement in the United States, REACH dossier requirements in Europe, and CDSCO fast-track pathways in India.
China
Domestic alkylated aromatic capacity expansion under government-backed advanced materials programs accelerates local consumption. SAMR enforces GB standards for chemical purity and labeling that directly affect import eligibility. Shandong and Jiangsu province refineries operate captive alkylation units feeding state-supported research institutes.
United States
Pharmaceutical contract manufacturers in the Boston corridor specify sub-ppm impurity ceilings for active pharmaceutical ingredient synthesis. EPA oversight under the Toxic Substances Control Act shapes manufacturing compliance burdens for domestic producers. Massachusetts and California clusters pilot continuous flow reactor systems at kilogram-per-hour scales.
Germany
Lubricant formulators seek low-toxicity aromatic extenders for polymer modification applications. REACH registration requirements mandate extensive toxicological dossiers that filter out smaller importers. The Ludwigshafen chemical complex sustains captive production of ethylated aromatics with integrated specification control.
India
PLI scheme incentives for pharmaceutical intermediates attract investment in domestic purification capacity. CDSCO fast-track approvals for registered suppliers create first-mover advantage in active pharmaceutical ingredient starting material qualifications. Maharashtra and Gujarat chemical corridors expand dedicated tetraethyl benzene production infrastructure.
Switzerland
Pharmaceutical-grade demand concentrates among Basel-based contract manufacturing organizations with stringent master service agreements. Swissmedic maintains alignment with EMA purity dossier requirements for starting material qualifications. The Basel corridor anchors European pharmaceutical synthesis protocol development.
Tetraethyl Benzene Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in tetraethyl benzene supply. The upper tier comprises multinational chemical conglomerates with captive aromatic alkylation capacity and regulatory affairs bandwidth for parallel FDA and EMA submissions. The specialist tier fragments across regional batch-scale producers, research-grade suppliers, and pharmaceutical-focused purification operations. Competitive moves concentrate on backward integration into ethylbenzene feedstock security and technology licensing for continuous flow reactor architectures.
Within the integrated leader tier, BASF SE and Evonik Industries AG exemplify divergent strategic positioning. BASF anchors its position through the Ludwigshafen complex with captive production and tight specification control across industrial and pharmaceutical grades. Evonik occupies a specialized position serving pharmaceutical contract manufacturing organizations with high-purity grades. Among research-grade specialists, Sagechem Limited represents the flexible batch-scale archetype demanded by academic and early-stage discovery laboratories.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Sagechem Limited |
| BOCSCI Inc. |
| LEAPChem Co., Ltd. |
| Angene International |
| Antimex Chemical Limited |
| Henan Tianfu Chemical Co., Ltd. |
| ChemSampCo, LLC |
| Others |
Supply Flow & Price Mechanics
Captive ethylbenzene conversion economics at integrated Ludwigshafen and Shandong-Jiangsu complexes establish minimum efficient scale thresholds that filter out sub-scale batch producers and compress price floors for import-dependent buyers. Pharmaceutical-grade certification costs and REACH dossier maintenance create fixed-cost barriers that stratify supply tiers and sustain premium capture for registered suppliers serving FDA and EMA qualification pathways.
Pricing Analysis
China-to-Europe price spreads for pharmaceutical-grade material reflect freight differentials and CDSCO fast-track qualification premiums that Indian purification operations command. Three-tier pricing structure across pharmaceutical, industrial, and research grades tracks certification burden and batch-scale flexibility, with FDA starting material qualifications driving the widest spreads. Cost compression in industrial-grade runs through ethylene feedstock volatility at cracking complexes that producers cannot pass through contractually. Research-grade buyers in Boston and San Francisco corridors exhibit lowest price sensitivity due to discovery-timeline urgency and small-volume procurement patterns.
Supply Chain Analysis
Strategic stockpiling of Friedel-Crafts acid catalysts dominates inventory strategy given 18-24 month supplier validation cycles and manufacturing concentration in Germany and the United States. Supply concentrates in China, Germany, and India, with Shandong-Jiangsu captive units, Ludwigshafen integrated complexes, and Maharashtra-Gujarat PLI-backed capacity anchoring regional flows. Raw material dependencies draw from ethylbenzene alkylation feedstock, zeolite catalyst systems, and high-purity solvent purification media. Single-source catalyst vulnerability constitutes the primary structural risk. Distribution runs through direct manufacturer engagement for pharmaceutical and research grades, with consolidated distributors maintaining industrial-grade annual contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of Friedel-Crafts process optimization expertise constrains capacity expansion and creates acquisition premiums for technical teams capable of suppressing polyethylbenzene byproduct formation in continuous flow architectures.
For Market Incumbents: Compound regulatory affairs bandwidth through parallel FDA and EMA submission capabilities that smaller competitors cannot replicate, while securing captive ethylbenzene supply through backward integration into cracking complex offtake agreements. Isopropylated aromatic substitution threats in lubricant applications demand accelerated green chemistry catalyst patenting to defend intermediate-grade positioning. For New Entrants and Emerging Players: CDSCO fast-track approval pathways for pharmaceutical-grade purification represent the most penetrable regulatory corridor, enabling qualification ahead of European REACH dossier completion timelines. Direct-to-laboratory e-commerce channels serving Boston and San Francisco discovery clusters offer immediate revenue traction without distributor panel consolidation barriers. Target research-grade spot purchasing migration with flexible certificate-of-analysis protocols and quarterly contract structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors batch-to-continuous conversion specialists with demonstrated impurity profile consistency at kilogram-per-hour scales. Long-term viability hinges on green chemistry catalyst licensing positions and pharmaceutical-grade certification pipeline depth. The signal to watch is ECHA Annex XV dossier update timing that forces toxicological data regeneration and filters supplier panels to registered-only sources.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylbenzene Feedstock | Ludwigshafen and Shandong-Jiangsu complexes demonstrate cost control through captive cracking unit offtake. |
| Continuous Flow Reactor Technology Licensing | Kilogram-per-hour scale demonstrations at Basel and Massachusetts sites enable distributed production node deployment. |
| Green Chemistry Catalyst Patent Positioning | Solid acid zeolite systems combined with flow architectures promise yield improvements and waste reduction. |
| CDSCO Fast-Track Qualification Pursuit | PLI scheme incentives in Maharashtra-Gujarat corridors attract investment ahead of European dossier completion. |
| Direct-to-Laboratory Distribution Buildout | Specialized procurement platforms serving Boston and San Francisco clusters compress minimum order quantities and accelerate delivery. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical contract manufacturing procurement leads, petrochemical plant managers at integrated alkylation units, specialty chemical distribution channel partners, and academic laboratory procurement coordinators. Secondary validation drew from ECHA REACH registration databases, FDA starting material qualification filings, CDSCO fast-track approval records, customs and trade flow data, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up volume estimates across grade tiers and applications were triangulated against top-down petrochemical capacity utilization and pharmaceutical intermediate demand projections.
Across the analysis window, the forecasting framework modeled segmentation dimensions including purity grade tier, end-use application intensity, and regional regulatory cluster alignment. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines. Key inputs included ethylene crack spread volatility assumptions, Friedel-Crafts catalyst supply concentration indices, and substitution elasticity estimates for isopropylated aromatic extenders in lubricant formulations.
Decision-makers should treat outputs as directional under base assumptions of sustained pharmaceutical synthesis protocol tightening and China petrochemical capacity expansion; material deviation would warrant model refresh. Specific risk factors include REACH Annex XV dossier update timing, EPA TSCA Section 5 notification requirement evolution, and catalyst supply disruption events. Revision becomes warranted when ethylene feedstock volatility or substitution penetration crosses thresholds that alter producer margin sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Hydrogen Cyanamide Market
Solvents
Ethane Market
Solvents
Allyl Cyanide Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
2,2-Dimethylbutyryl Chloride Market
Solvents
High Purity Solvents Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
Japan Acetonitrile Market
Solvents
Butyl Acetate (BAC) Market
Solvents
Coating Solvents Market
Solvents
GCC Acetonitrile Market
Solvents
Global Tert-Butanol Market
Solvents
Dimethyl Ether (DME) Market
Solvents
Ethoxydiglycol Market
Solvents
Methyl Isopropyl Ketone Market
Solvents
Decanol Market